
 Global Fine Art Insurance Market | 2026-2036
Global Fine Art Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fine Art Insurance Market Foresight
The EU Green Deal is restructuring fine art insurance demand across Europe as institutional buyers mandate carbon-accounted transit and climate-resilient storage. AXA Art leverages its specialist underwriting infrastructure to dominate high-value painting coverage in continental Europe. Chubb anchors North American private collector portfolios through tailored all-risks policies with agreed-value settlements. Lloyd's of London sustains its historic position in international transit and war-risk coverage for traveling exhibitions.
Fine art insurance is a specialized property and casualty coverage form that indemnifies physical loss or damage to collectible objects based on appraised fair market value or agreed value, with policies typically incorporating conservation-grade restoration clauses, mysterious disappearance riders, and pairs-and-sets provisions. Its primary commercial purpose is to align capital protection with liquidity events such as auction consignment, estate transfer, or museum loan circulation. Coverage type segments reveal structural divergence: all-risks policies command premium positioning among museums requiring comprehensive protection, while named perils products compete on price for lower-value residential collections. Policyholder type dynamics show auction houses generating the fastest-growing submission volume as consignment values escalate and seller-mandated coverage becomes standard practice.
US state insurance commissioners enforce surplus lines regulations that shape how non-admitted carriers access high-value art risks, while the UK's Prudential Regulation Authority and Lloyd's Franchise Board set capital adequacy standards for syndicate underwriters. The EU's Insurance Distribution Directive governs broker remuneration transparency and policyholder disclosure across continental markets. Stakeholders must monitor evolving climate litigation precedents that could reclassify flood and wildfire exposure from excluded perils to standard coverage expectations.
Market Dynamics
Blockchain-based provenance verification is converging with digital condition monitoring to compress underwriting cycles and eliminate information asymmetry between insurers and high-value collectors. These technologies force carriers to rebuild risk assessment protocols around real-time data streams rather than static appraisals.
Growth Catalysts
- EU Green Deal carbon-accounted transit mandates:Institutional buyers across Germany, France, and Italy now require climate-resilient storage and emissions-tracked logistics, expanding coverage demand for specialized transit policies.
- Ultra-high-net-worth collector portfolio expansion:Private wealth concentration in the United States and United Kingdom drives demand for all-risks policies with agreed-value settlements and mysterious disappearance riders.
- Auction house consignment standardization:Seller-mandated coverage clauses in major auction venues generate submission volume growth as consignment values escalate and institutional sellers require proof of insurance.
Market Restraints
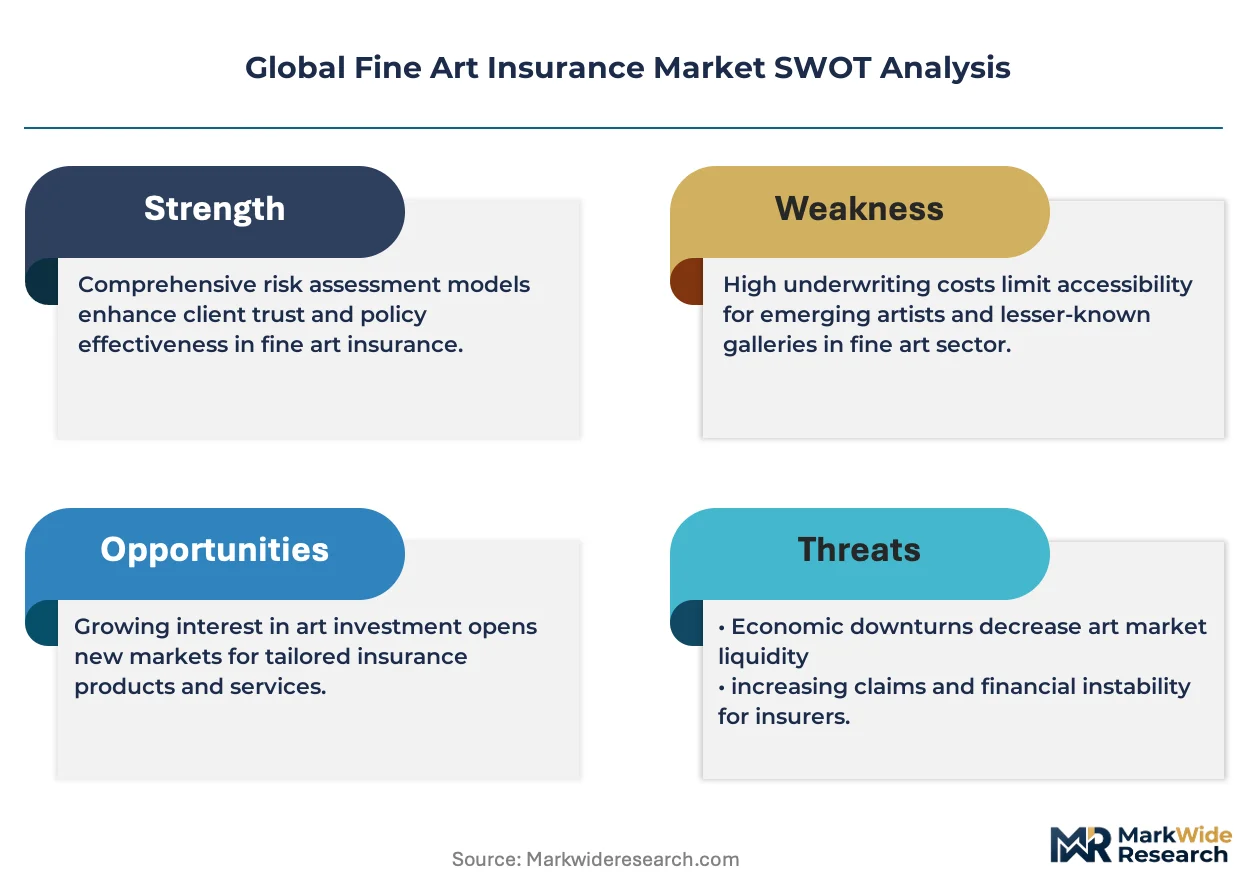
- Climate litigation exposure reclassification:US state courts and EU precedents threaten to shift flood and wildfire damage from excluded perils to standard coverage expectations, compressing carrier margins.
- Specialized conservator supply concentration:Restoration expertise clusters in London, New York, and Zurich, creating bottleneck risks when major damage events require simultaneous conservation-grade intervention across multiple claims.
- Surplus lines access friction:US state insurance commissioners enforce non-admitted carrier restrictions that limit how international syndicates access high-value American risks without admitted status.
Strategic Opportunities
- India emerging collector market underpenetration:Mumbai and Delhi wealth creation outpaces specialist insurance penetration, creating first-mover advantage for tailored private collector products.
- Parametric climate coverage innovation:Temperature and humidity threshold triggers offer settlement speed advantages over traditional loss-adjustment processes for transit and storage risks.
- Fractional ownership platform integration:Blockchain-enabled art securitization creates demand for novel policies covering dispersed ownership structures and automated valuation adjustments.
Industry Challenges
- Conservation-grade restoration capacity scarcity:Qualified conservators capable of executing insurer-mandated restoration clauses remain concentrated in legacy European and North American training pipelines.
- Provenance verification standardization delays:Absence of interoperable blockchain protocols across auction houses, museums, and private databases forces carriers to maintain redundant due diligence processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fine Art Insurance Market |
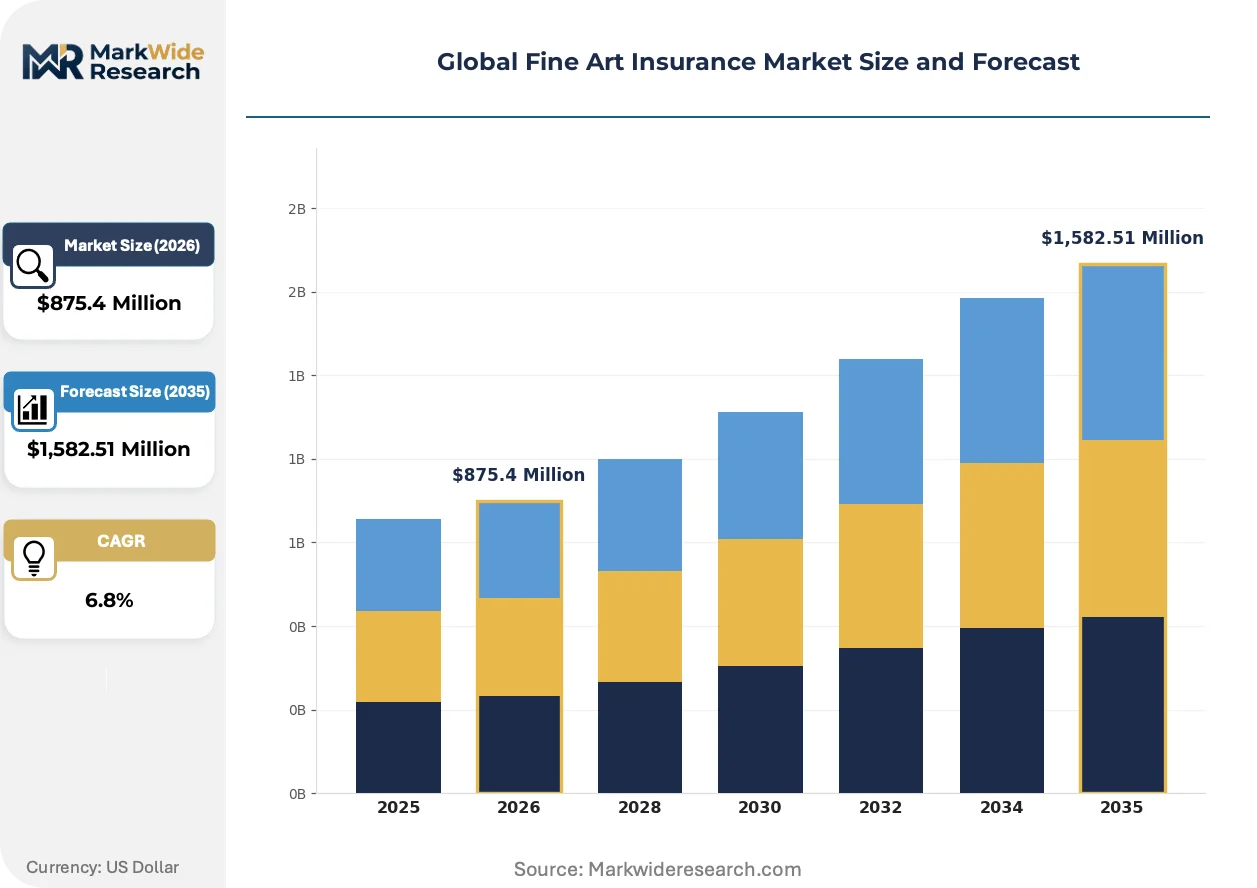
| Market Size in 2026 | $875.4 Million |
| Market Size in 2035 | $1,582.51 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: All Risks, Named Perils, Valuation Guarantee, Worldwide, Theft Protection Policyholder Type: Private Collectors, Museums, Art Galleries, Auction Houses, Dealers Art Category: Paintings, Sculptures, Photographs, Manuscripts, Antiques Distribution Channel: Brokers, Direct Insurers, Online Platforms, Specialty Agents, Bancassurance |
| Companies Covered | Allianz, AIG, Chubb, Marsh, Zurich, AXA Art, Lloyd's of London, MetLife, Hiscox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fine Art Insurance Market Shifts & Advancements
Sensor-based environmental monitoring and distributed ledger technologies are compressing the information gap between risk origination and underwriting assessment. Carriers now face pressure to integrate real-time data into pricing models previously built on annual appraisals.
Internet-of-Things microclimate sensors embedded in transit crates and storage facilities transmit continuous temperature, humidity, and shock data to underwriting platforms. Major museums and logistics providers in Switzerland and the United States deploy these networks to preempt condition degradation before claims materialize. This telemetry infrastructure is converging with automated valuation engines to enable dynamic premium adjustments based on actual exposure rather than static risk classifications.
The EU Green Deal's carbon-accounted transit requirements are restructuring European fine art logistics as institutional buyers mandate emissions disclosure for loan exhibitions and acquisitions. German and French museum consortiums now exclude carriers unable to document supply chain carbon intensity from preferred vendor panels. This regulatory pressure forces underwriters to integrate climate accounting into policy pricing and partner with certified green logistics providers.
Collector procurement preferences are fragmenting across generational lines as established buyers maintain broker-mediated relationships while emerging wealth segments favor direct digital platforms with instant quote generation. Asian private banks in Singapore and Hong Kong embed insurance procurement into art-secured lending workflows, displacing standalone policy shopping. This channel convergence concentrates distribution power with financial institutions capable of bundling coverage with wealth management services.
Global Fine Art Insurance Market Segmentation
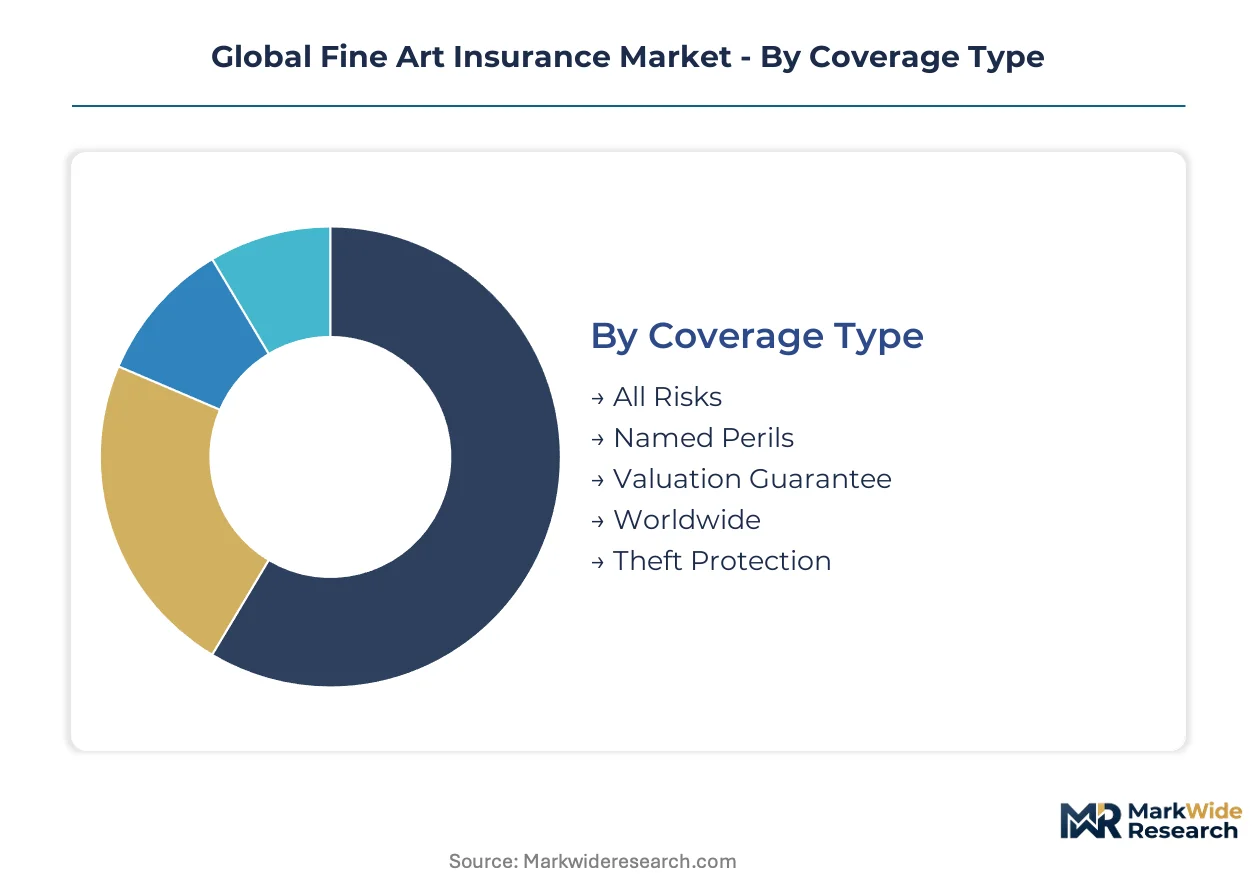
Fine art insurance segments reflect divergent risk appetites, valuation methodologies, and distribution preferences across collector ecosystems. Coverage structures and policyholder profiles determine pricing elasticity, claims complexity, and carrier specialization requirements.
Coverage Type:
Private collectors and institutional buyers separate sharply based on tolerance for premium expenditure versus peril specificity.
- All Risks:Comprehensive protection against physical loss or damage from any cause not explicitly excluded, with agreed-value settlements and mysterious disappearance riders standard. Museum deaccessioning policies and climate-related transit hazards in the United States drive concentrated demand for this tier.
- Named Perils:Coverage limited to specified risks such as fire, theft, or flood, competing on price for lower-value residential collections and emerging collector segments. Cost-conscious buyers in Germany and France favor this structure for secondary market acquisitions.
- Valuation Guarantee:Locks appraisal values for policy duration, eliminating disputes during claims settlement. Appeals to auction house consignors requiring proof of coverage with fixed value documentation.
- Worldwide:Extends territorial scope across transit and exhibition circuits without location-specific endorsements. Traveling exhibition organizers and international private banks mandate this for cross-border loan portfolios.
- Theft Protection:Specialized coverage addressing mysterious disappearance and burglary with enhanced security protocol requirements. Ultra-high-net-worth collectors in London and New York deploy this for high-theft-risk categories like portable antiquities.
All Risks leads volumes today; Named Perils is gaining share fastest among first-time collectors.
Policyholder Type:
Volume concentration varies dramatically by transaction frequency, average policy size, and broker involvement depth.
- Private Collectors:Individual wealth holders purchasing tailored all-risks policies with agreed-value structures and conservation-grade restoration clauses. Wealth concentration in the United States and United Kingdom sustains premium positioning for this segment.
- Museums:Institutional buyers mandating carbon-accounted transit and climate-resilient storage under EU Green Deal procurement rules. German and French museum consortiums now exclude carriers lacking emissions documentation from vendor panels.
- Art Galleries:Commercial operators requiring inventory coverage with fluctuating value endorsements and exhibition extension provisions. Inventory turnover velocity in New York and London creates dynamic premium adjustment requirements.
- Auction Houses:Generate submission volume growth as seller-mandated coverage clauses become standard practice. Consignment value escalation at major venues drives demand for instant proof-of-insurance documentation.
- Dealers:Specialist traders needing stock-throughput coverage spanning acquisition, restoration, and resale phases. Swiss and Belgian dealers leverage this for art fair circuits and private treaty sales.
Private Collectors dominate premium value; Auction Houses are expanding most quickly.
Art Category:
Physical vulnerability, valuation methodology, and restoration complexity differentiate risk profiles across object types.
- Paintings:Dominant premium category with established condition grading protocols and liquid secondary markets. AXA Art's specialist underwriting infrastructure targets high-value canvas and panel coverage across continental Europe.
- Sculptures:Three-dimensional works requiring transit-specific coverage for installation, deinstallation, and environmental exposure. Bronze and stone conservation expertise clusters in London and New York.
- Photographs:Light-sensitive works demanding microclimate-controlled storage with humidity threshold triggers. Parametric coverage innovation targets this category for settlement speed advantages.
- Manuscripts:Unique documentary artifacts combining material fragility with irreplaceable content value. Specialized academic and institutional libraries in Italy and Spain drive niche demand.
- Antiques:Age-qualified objects with provenance verification challenges and restoration material authenticity requirements. Blockchain-based provenance tracking is compressing underwriting cycles for this segment.
Paintings commands the largest premium pool; Photographs shows steepest expansion trajectory.
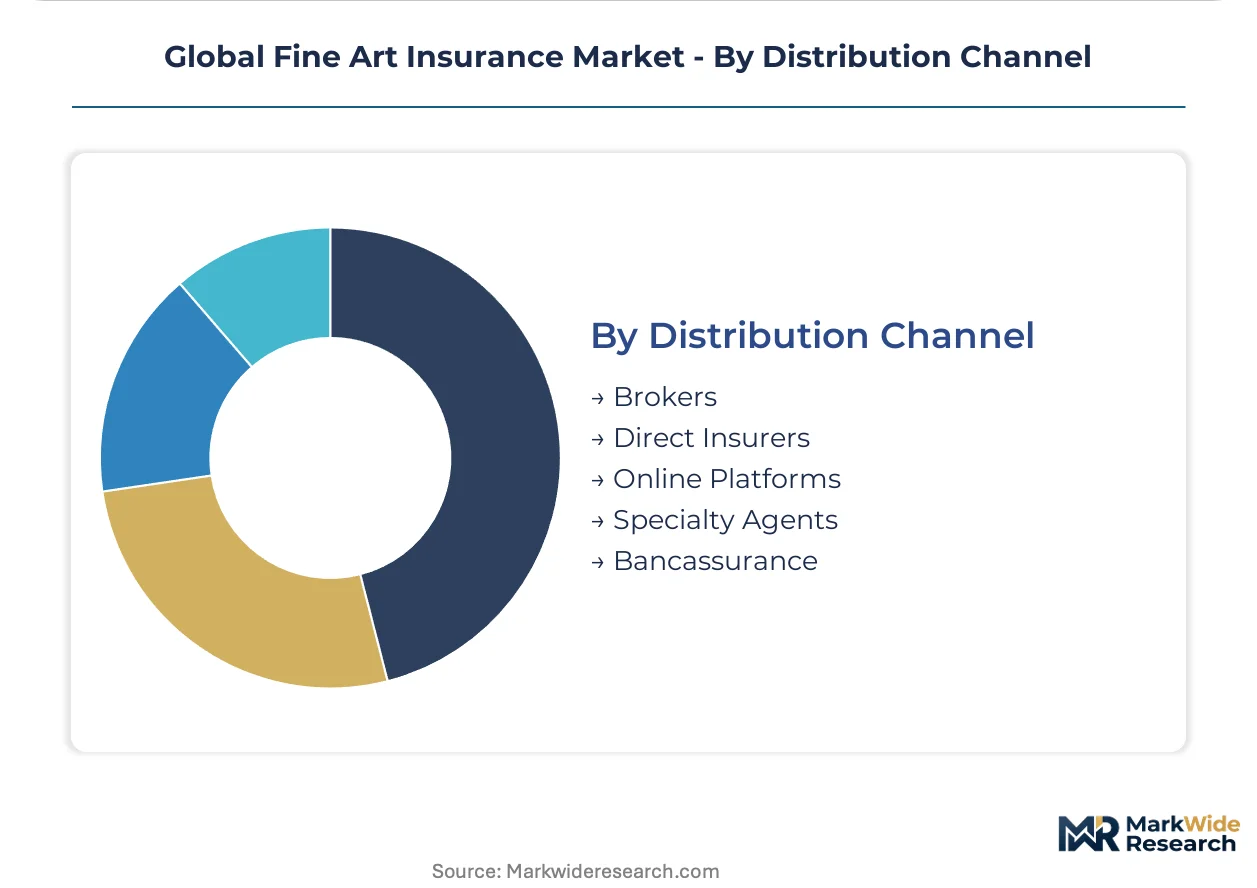
Distribution Channel:
Collector demographics and transaction context determine channel preference fragmentation.
- Brokers:Established intermediaries managing complex museum and ultra-high-net-worth portfolios with multi-carrier placement. Lloyd's of London syndicate access runs through this channel for international transit risks.
- Direct Insurers:Carrier-proprietary sales forces targeting standardized private collector products with simplified underwriting. Chubb anchors North American portfolios through this model.
- Online Platforms:Instant quote generation and digital policy issuance attracting emerging wealth segments. Singapore and Hong Kong private banks embed this capability into art-secured lending workflows.
- Specialty Agents:Niche intermediaries with conservator networks and appraisal relationships. Concentrated in Zurich, London, and New York for high-value placement.
- Bancassurance:Financial institution distribution bundling coverage with wealth management and lending products. Asian private banks concentrate distribution power through this channel convergence.
Brokers retain the largest placement volume; Online Platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fine art insurance originated in London's shipping underwriters of the eighteenth century, then migrated to continental Europe and North America as private wealth concentration shifted. Today the industry clusters in jurisdictions with deep collector infrastructure, specialized legal frameworks for cultural property, and proximity to major auction venues.
United States
Ultra-high-net-worth collectors in New York and Los Angeles drive demand for all-risks policies with agreed-value settlements. State insurance commissioners enforce surplus lines regulations that shape how non-admitted carriers access high-value risks. Museum deaccessioning policies and climate-related transit hazards in the American Southeast generate complex policy endorsements.
United Kingdom
Lloyd's of London sustains its historic dominance in international transit and war-risk coverage for traveling exhibitions. The Prudential Regulation Authority and Lloyd's Franchise Board set capital adequacy standards for syndicate underwriters. Conservation-grade restoration expertise clusters in London, creating capacity bottlenecks during major damage events.
Germany
Museum consortiums in Berlin and Munich now mandate carbon-accounted transit under EU Green Deal procurement rules. The Insurance Distribution Directive governs broker remuneration transparency across continental operations. German institutional buyers exclude carriers lacking emissions documentation from preferred vendor panels.
France
Paris-based auction houses generate submission volume growth as seller-mandated coverage clauses become standard practice. The EU Green Deal's climate-resilient storage requirements reshape policy specifications for national museum networks. Specialist underwriters concentrate in the Île-de-France region serving high-value painting portfolios.
Switzerland
Geneva and Zurich host dense networks of specialty agents with conservator relationships and appraisal expertise. Freeport storage facilities in the cantons drive demand for mysterious disappearance riders and enhanced security protocol endorsements. Swiss dealers leverage stock-throughput coverage for art fair circuits and private treaty sales.
Global Fine Art Insurance Market Competitive Landscape
Capital-heavy insurers with admitted status and balance-sheet capacity compete with asset-light syndicates and specialist MGA platforms that access risk through delegated authority. The market structures around three tiers: global multi-line carriers with fine art divisions, Lloyd's syndicates and specialist underwriters with niche expertise, and regional players with local regulatory access. Consolidation pressure concentrates among mid-tier specialists seeking scale to absorb climate litigation exposure. Portfolio diversification into parametric products and fractional ownership coverage represents the dominant competitive move.
Within the specialist underwriting tier, AXA Art and Chubb exemplify divergent geographic positioning strategies. AXA Art leverages its continental European infrastructure to dominate high-value painting coverage across Germany, France, and Italy. Chubb anchors North American private collector portfolios through tailored all-risks policies with agreed-value settlements. Lloyd's of London occupies a distinctive position in international transit and war-risk coverage, sustaining its historic role through syndicate capacity for traveling exhibitions.
| Leading Market Players |
|---|
| Allianz |
| AIG |
| Chubb |
| Marsh |
| Zurich |
| AXA Art |
| Lloyd's of London |
| MetLife |
| Hiscox |
| Others |
Supply & Pricing Matrix
Blockchain-enabled provenance verification and sensor-based condition monitoring are compressing underwriting cycles while concentrating technology procurement power with carriers capable of integrating real-time data streams into pricing models. This dual shift elevates capital requirements for digital infrastructure while squeezing margins for carriers dependent on static annual appraisals.
Pricing Analysis
Agreed-value settlement structures with mysterious disappearance riders dominate premium positioning among ultra-high-net-worth collectors, while named-perils products compete on price for emerging residential collections. Price differentiation rests on restoration clause quality and transit carbon-accounting certification under EU Green Deal mandates. Cost compression in the standard tier is intensifying because auction house consignment standardization forces rapid quote generation with reduced underwriting margin. Emerging collectors in Asia-Pacific markets exhibit highest price sensitivity; museum risk managers show lowest sensitivity due to procurement bundling with wealth management services.
Supply Chain Analysis
Single-source vulnerability sits with conservation-grade restoration expertise concentrated in London, New York, and Zurich, creating simultaneous-claim capacity bottlenecks during major damage events. Underwriting capacity draws from Lloyd's of London syndicates, continental European specialist carriers, and North American admitted insurers with balance-sheet scale. Supply chain risk centers on tariff exposure for climate-resilient storage materials and specialized transit crate manufacturing. Distribution runs through broker-mediated placement for museum and high-net-worth portfolios, with direct digital platforms and bancassurance channels displacing standalone procurement among emerging wealth segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Fine Art Insurance Market functions as a stable compounder anchored by irreversible wealth concentration in tangible asset categories and regulatory mandates for climate-accounted cultural property logistics.
For Market Incumbents: Lock in restoration capacity through exclusive conservator network partnerships in London, New York, and Zurich to preempt simultaneous-claim bottlenecks. Deepen vertical integration into sensor-based condition monitoring infrastructure to capture telemetry data advantages over asset-light competitors. Climate litigation exposure reclassification in US state courts and EU precedents threatens margin compression; priority lever sits with parametric product development for settlement speed differentiation. For New Entrants and Emerging Players: EU Green Deal carbon-accounted transit mandates in Germany and France open a window for specialized logistics-coverage bundling with certified green providers. Target Mumbai and Delhi collector markets where wealth creation outpaces specialist insurance penetration. White-space opportunity concentrates in fractional ownership platform integration with automated valuation adjustment capabilities. Go-to-market angle should embed insurance procurement into private banking art-secured lending workflows rather than standalone policy distribution. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier specialist MGAs with delegated authority access but lacking balance-sheet scale to absorb climate litigation exposure. Long-term viability over a multi-year horizon hinges on portfolio diversification into parametric products and blockchain-enabled provenance verification services. Acquisition target archetype: regional players with local regulatory access and conservator relationships in underpenetrated Asian markets. Signal to watch: carbon-accounted transit mandate expansion beyond EU Green Deal jurisdictions into UK and Swiss procurement standards.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Climate Coverage Launch | Temperature and humidity threshold triggers accelerate settlement speed for transit and storage claims beyond traditional loss-adjustment. |
| Blockchain Provenance Integration | Distributed ledger verification compresses underwriting cycles and eliminates information asymmetry between carriers and high-value collectors. |
| Conservator Network Exclusive Partnership | Restoration capacity concentration in London, New York, and Zurich creates bottleneck risk requiring preemptive capacity lock-in. |
| Bancassurance Channel Convergence | Singapore and Hong Kong private banks embed insurance procurement into art-secured lending workflows, displacing standalone distribution. |
| Carbon-Accounted Transit Certification | German and French museum consortiums exclude carriers lacking emissions documentation from preferred vendor panels under EU Green Deal rules. |
Research Methodology
Direct dialogue with underwriting executives at Lloyd's syndicates and specialist carriers, fine art brokers with museum and private collector portfolios, conservation-grade restoration specialists, and private banking wealth managers with art-secured lending programs grounded the qualitative foundation. Secondary validation drew from Lloyd's Franchise Board capital adequacy disclosures, EU Insurance Distribution Directive implementation reports, US state insurance commissioner surplus lines filings, and museum procurement documentation under EU Green Deal mandates. Bottom-up policy submission volume analysis and top-down premium pool estimation were triangulated against carrier balance-sheet capacity disclosures.
Segmentation outputs across coverage type, policyholder category, art category, and distribution channel were modeled across the projection horizon with dynamic premium adjustment assumptions reflecting sensor-based telemetry adoption curves. CAGRs were derived from rolling three-year policy inception trend analysis and wealth concentration elasticity estimates. Forecast inputs incorporated climate litigation exposure reclassification probability assessments and blockchain provenance verification penetration scenarios.
Revisions become necessary when EU Green Deal mandate expansion accelerates beyond institutional procurement into private collector requirements, or when US state courts establish precedents reclassifying flood and wildfire exposure from excluded perils to standard coverage. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
China Group Health Insurance Market
Insurance
Australia Parametric Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
Russia Property and Casualty Insurance Market
Insurance
Aerial Imaging in Insurance Service Market
Insurance
Medical Claims Processing Services Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
US Extended Warranty Market
Insurance
Property Insurance Market
Insurance
Global Boats and Yacht Insurance Market
Insurance
Germany Car Insurance Market
Insurance
Asia-Pacific Travel Insurance Market
Insurance
Asia-Pacific EV Insurance Market
Insurance
Digital Monetary Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
Middle East and Africa Travel Insurance Market