
 Title Insurance Market | 2026-2036
Title Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Title Insurance Market Analysis
Single-source reliance on captive title agents is rebalancing toward multi-source broker networks as underwriters seek channel diversification. Fidelity National Title Insurance Co. dominates direct operations through its integrated agency platform. First American Title Insurance Co. leverages proprietary property data analytics to differentiate risk assessment capabilities. Stewart Title Guaranty Co. anchors its position in residential refinancing corridors with specialized closing services.
Title insurance is an indemnity product that protects property purchasers and mortgage lenders against financial loss from defects in real estate title records, including undiscovered liens, encumbrances, or errors in public land registries. Policies are underwritten after exhaustive examination of chain-of-title documents, tax records, and court filings to verify legal ownership and flag competing claims. Coverage insurance commands the largest premium pool among product type segments, while title search services capture expanding margins as automation reduces per-file labor costs. The broker distribution channel leads transaction volume nationally, though direct sales relationships with mortgage originators yield higher retention rates per account.
The Consumer Financial Protection Bureau enforces Truth-in-Lending and RESPA disclosure rules that govern title insurance cost presentation at closing. State insurance departments regulate rate filings, reserve requirements, and agent licensing standards that vary across jurisdictions. The American Land Title Association maintains best-practice protocols for title plant operations and cyber security standards. Stakeholders must monitor state-level rate modernization proceedings and federal digital mortgage integration timelines to anticipate margin compression or channel disruption.
Market Dynamics
Digital title search automation is compressing underwriting timelines while blockchain-based property records are decentralizing custody of land registry data away from county recorders. These twin forces are redistributing value from manual examination labor toward algorithmic risk scoring and distributed ledger infrastructure.
Growth Catalysts
- Residential Refinancing Acceleration:Mortgage lenders are expanding title coverage purchases as interest rate cycles trigger loan restructuring volumes. This end-use segment now commands the fastest-growing buyer category in premium generation.
- Blockchain Land Registries:Distributed ledger pilots in county recording offices are reducing title defect rates by creating immutable chain-of-title documentation. The technology is eliminating gaps in historical record transfers.
- CFPB Disclosure Mandates:The Consumer Financial Protection Bureau's Truth-in-Lending and RESPA enforcement is standardizing cost presentation at closing. This regulatory clarity is reducing buyer friction and accelerating transaction velocity.
Market Restraints
- Title Plant Concentration:Historical property data repositories remain concentrated among legacy operators in key metropolitan corridors. This supply concentration creates barriers for new entrants seeking comprehensive backward coverage.
- State Rate Filing Friction:Insurance departments in multiple jurisdictions maintain manual rate approval processes that delay pricing responsiveness. This regulatory friction compresses margin flexibility during competitive cycles.
- Manual Examination Labor:Complex commercial transactions still require attorney-level title review that automation cannot replicate. This technical limitation caps scalability in high-value policy segments.
Strategic Opportunities
- Underpenetrated Commercial Closings:Multi-state commercial transactions in secondary metros lack standardized title products. This geography offers white space for specialized coverage instruments.
- API-First Distribution:Direct integration with mortgage origination platforms is displacing traditional broker channels. This distribution innovation captures higher retention rates per account.
- ALTA Cyber Security Protocols:The American Land Title Association's best-practice standards are creating certification-driven demand for compliant vendors. This regulatory tailwind favors infrastructure investments in data protection.
Industry Challenges
- Title Examiner Talent Scarcity:Skilled professionals capable of interpreting century-old deed language and tax lien hierarchies are aging out of the workforce. This skill gap threatens quality control in complex files.
- Legacy System Integration:Core policy administration platforms built on decades-old architectures resist API connectivity with modern data analytics stacks. This integration complexity delays automation roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Title Insurance Market |
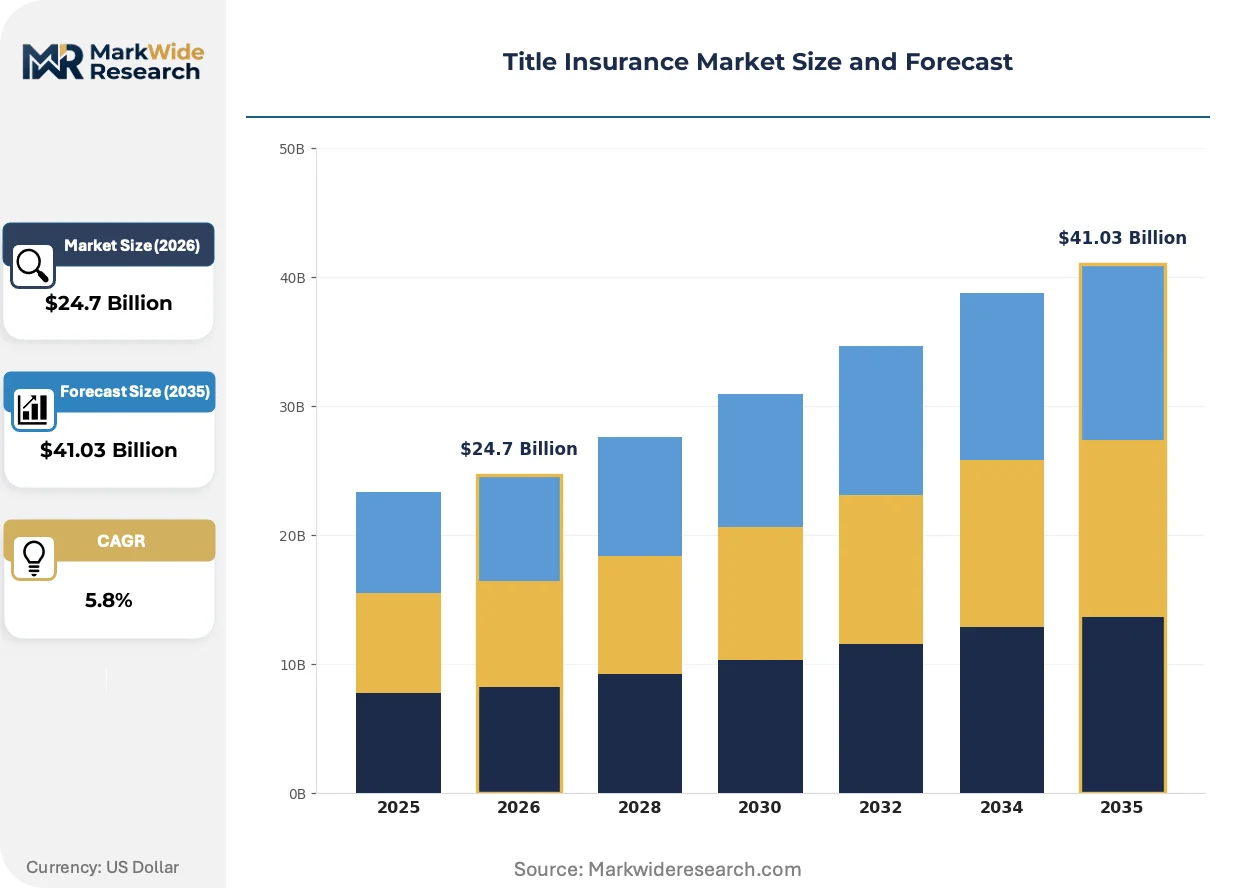
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $41.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
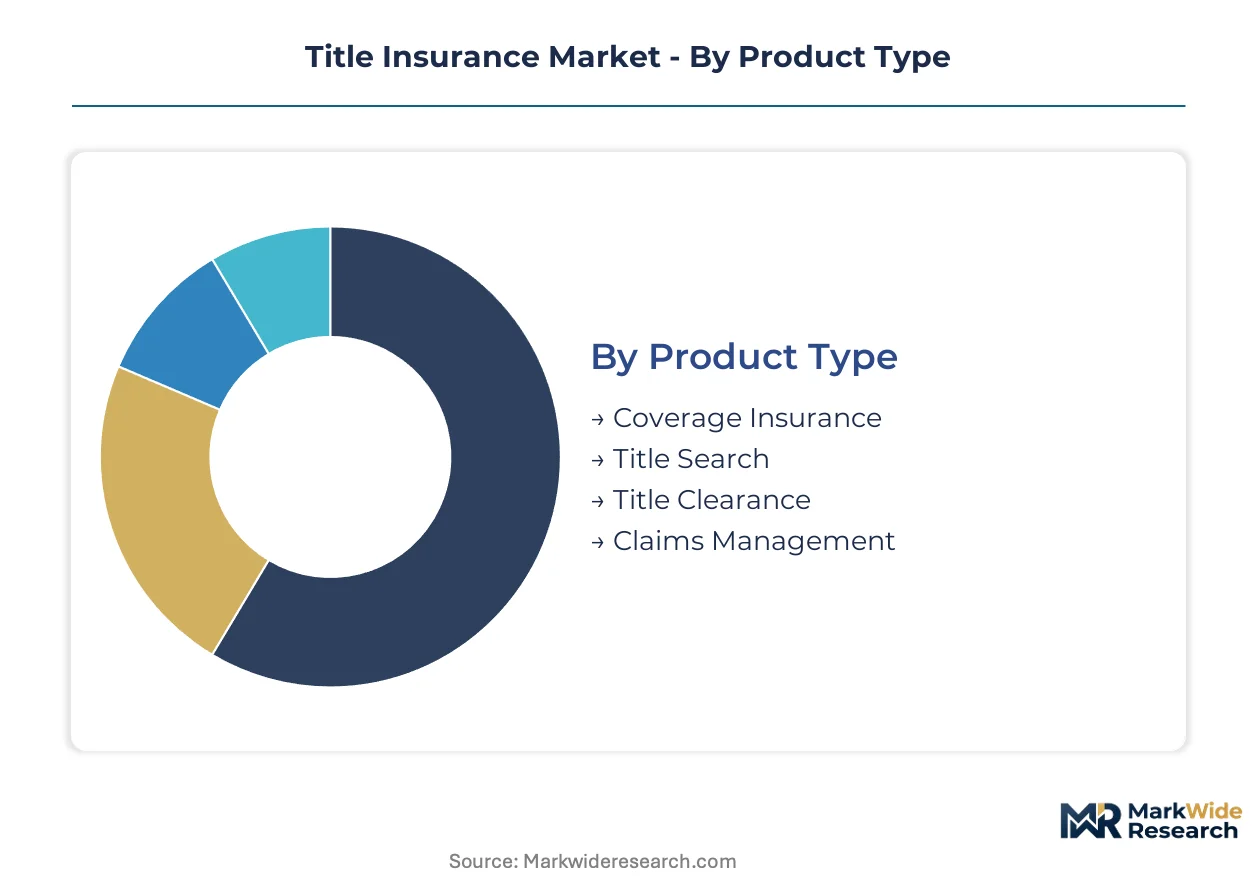
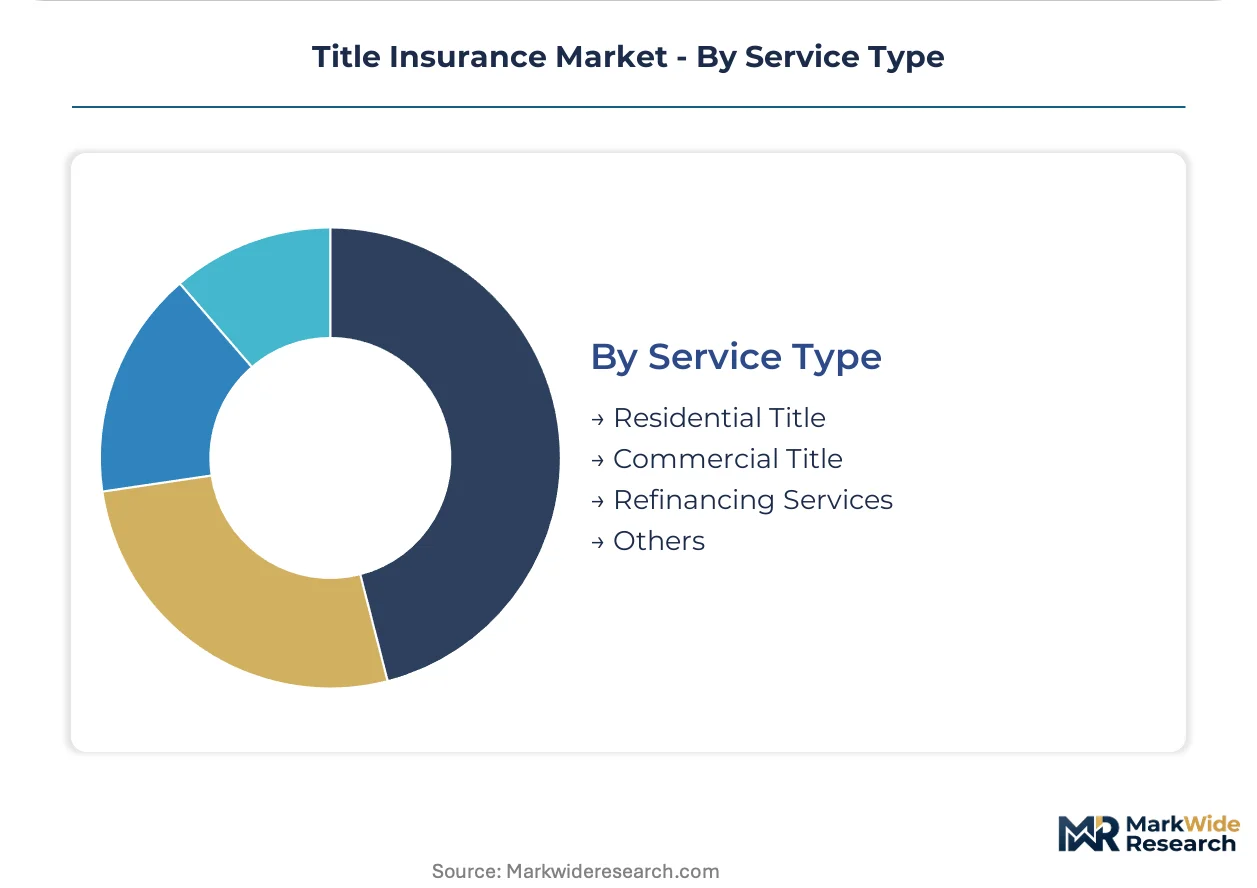
| Segmentation | Product Type: Coverage Insurance, Title Search, Title Clearance, Claims Management Distribution Channel: Direct Sales, Brokers, Online Platforms, Affiliates Customer Type: Homebuyers, Lenders, Investors, Real Estate Firms Service Type: Residential Title, Commercial Title, Refinancing Services, Others |
| Companies Covered | Chicago Title Insurance Co., Westcor Land Title Insurance Co., First American Title Insurance Co., Title Resources Guaranty Co., Commonwealth Land Title Insurance Co., Fidelity National Title Insurance Co., Stewart Title Guaranty Co., WFG National Title Insurance Co., Old Republic National Title Insurance Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Title Insurance Market Emerging Trajectories
Title insurance workflows are undergoing fundamental restructuring as distributed ledger technology, regulatory digitization mandates, and buyer channel preferences converge. These forces are compressing traditional value chains and redistributing margin capture.
Blockchain-based property record systems are decentralizing custody of land registry data away from county recorder offices. Mortgage originators with direct API connections to distributed ledgers are adopting verification protocols that bypass traditional title plant queries. This technology is decentralizing risk assessment authority toward algorithmic consensus mechanisms and compressing the role of centralized title abstractors.
The Consumer Financial Protection Bureau's digital mortgage integration timeline is accelerating electronic closing adoption. Lenders must reconfigure disclosure workflows to embed title cost data within integrated loan estimate platforms. Residential refinancing corridors are responding by consolidating vendor relationships around end-to-end digital closing providers.
Mortgage originators are consolidating vendor panels around direct underwriter relationships that bypass independent title agents. Broker-dependent transaction volume is fragmenting as large lenders negotiate captive pricing agreements with national underwriters. This channel consolidation is most visible in high-volume refinance markets where per-loan margin compression favors scale-based procurement terms.
Title Insurance Market Segmentation
Segmentation in title insurance reveals how risk transfer mechanisms, distribution economics, and customer sophistication stratify across transaction types. Product design, channel selection, and service bundling decisions cascade differently for residential refinancings versus complex commercial portfolios.
Product Type:
Standalone indemnity products dominate premium generation, while embedded search and clearance services increasingly merge into automated underwriting workflows.
- Coverage Insurance:Core indemnity contracts protect against financial loss from undiscovered title defects, liens, or competing ownership claims. Residential lenders in high-refinance corridors drive placement volume as mandatory coverage requirements persist across state jurisdictions. Rate filings and reserve requirements vary significantly by state insurance department, compressing margin flexibility in competitive cycles.
- Title Search:Exhaustive examination of chain-of-title documents, tax records, and court filings verifies legal ownership prior to policy issuance. Digital automation is reducing per-file labor costs and compressing underwriting timelines in standardized residential transactions. Algorithmic risk scoring redistributes value from manual examination toward technology infrastructure.
- Title Clearance:Remediation services resolve identified defects through lien releases, boundary adjustments, or probate proceedings. These services capture expanding margins as complexity increases in multi-generational property transfers.
- Claims Management:Post-closing defense and settlement administration activates when title defects materialize after policy issuance. Legal defense reserves and settlement protocols vary by underwriter risk appetite and historical loss experience.
Volume placements concentrate in Coverage Insurance; the faster expansion belongs to Title Search as automation penetrates standard residential files.
Distribution Channel:
Channel economics stratify sharply between direct underwriter relationships and intermediary-dependent transaction flows, with retention rates diverging accordingly.
- Direct Sales:Underwriter-owned agency platforms and captive sales forces serve national mortgage originators with standardized pricing agreements. Large lenders in high-volume refinance markets negotiate scale-based procurement terms that compress per-loan margins but secure volume commitments.
- Brokers:Independent title agents aggregate local market expertise and maintain relationships with regional lenders and real estate attorneys. Broker-dependent transaction volume is fragmenting as mortgage originators consolidate vendor panels around direct underwriter relationships.
- Online Platforms:Digital marketplaces and API-integrated origination systems embed title services within end-to-end closing workflows. Consumer Financial Protection Bureau digital mortgage mandates accelerate electronic closing adoption through these channels.
- Affiliates:Controlled business arrangements link title services to real estate brokerages, mortgage lenders, or builders through referral networks. RESPA Section 8 compliance requirements govern permissible compensation structures in these arrangements.
Broker channels retain the deepest geographic penetration; API-integrated platforms are climbing the fastest as mortgage technology stacks modernize.
Customer Type:
Customer sophistication and transaction frequency create distinct service requirements across residential consumers and institutional counterparties.
- Homebuyers:Individual purchasers acquire owner's policies to protect equity investments against title defects, with premium costs typically bundled into closing disclosures. First-time buyers in competitive housing markets prioritize speed and cost transparency over comprehensive coverage customization.
- Lenders:Mortgage originators purchase lender's policies as mandatory collateral protection, with coverage amounts tracking outstanding loan balances. This segment commands premium volume leadership as refinancing accelerations trigger repeat purchases across interest rate cycles.
- Investors:Portfolio acquirers and institutional owners require specialized coverage for multi-property holdings, 1031 exchanges, and complex entity structures. Commercial investors in secondary metros face standardization gaps that create white space for specialized products.
- Real Estate Firms:Developers, property managers, and commercial brokers procure bulk title services for acquisition, disposition, and leasing activities. Entity-level relationships span multiple transaction types and jurisdictions.
Lender placements dominate transaction velocity; investor-facing products show the steepest expansion trajectory as institutional capital concentrates in rental housing.
Service Type:
Service bundling and specialization intensity diverge between high-frequency residential workflows and bespoke commercial engagements.
- Residential Title:Standardized policy forms and automated search protocols serve single-family home purchases and refinancings. Digital closing providers are consolidating vendor relationships in high-volume corridors.
- Commercial Title:Customized coverage for multi-state transactions, environmental lien exposure, and complex entity structures requires attorney-level examination. Multi-state commercial transactions in secondary metros lack standardized products.
- Refinancing Services:Accelerated title updates and policy reissues serve mortgage restructuring volumes triggered by interest rate movements. This application segment is gaining share fastest as rate cycles drive transaction velocity.
- Others:Niche services including construction loan title monitoring, leasehold coverage, and timeshare documentation serve specialized property types. These offerings capture premium margins through technical specialization.
Residential services anchor volume scale; refinancing-focused offerings are expanding most quickly as interest rate sensitivity drives cyclical demand spikes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
County courthouse records and municipal land registries anchor title insurance operations in jurisdictions with mature property documentation systems. Premium generation concentrates where mortgage lending volumes intersect with regulatory mandates for lender coverage.
United States
Residential refinancing waves and mandatory lender coverage requirements drive premium volume across state insurance departments. The Consumer Financial Protection Bureau enforces Truth-in-Lending and RESPA disclosure rules that standardize cost presentation at closing. Texas, Florida, and California metropolitan corridors concentrate title plant infrastructure and underwriter direct operations.
Canada
Commercial real estate transactions in Toronto and Vancouver generate demand for attorney-level title examination. Provincial insurance regulators oversee rate filings and agent licensing standards that vary across Ontario, British Columbia, and Alberta. The Greater Toronto Area anchors national transaction velocity for both residential purchases and institutional portfolio acquisitions.
United Kingdom
Conveyancing solicitor networks and lender panel requirements shape title indemnity product distribution. The Financial Conduct Authority governs insurance conduct standards while HM Land Registry digitization initiatives reduce title defect rates. London and Southeast England concentrate high-value commercial transactions requiring bespoke coverage instruments.
Germany
Notary-mediated property transfers and Grundbuch land registry accuracy limit traditional title insurance penetration. BaFin insurance supervision applies to emerging title indemnity products serving cross-border commercial investors. Frankfurt and Munich financial centers generate demand for specialized coverage on multi-entity real estate structures.
Australia
Torrens title system registration reduces but does not eliminate demand for title insurance on unregistered interests and boundary disputes. ASIC and state-based insurance regulators oversee product distribution and disclosure requirements. Sydney and Melbourne metropolitan markets concentrate premium generation through residential purchase and refinance activity.
Title Insurance Market Vendor Landscape
Channel consolidation dominates the current landscape as mortgage originators narrow vendor panels around direct underwriter relationships. The market structure concentrates among national underwriters with integrated agency platforms and proprietary title plant infrastructure. Three archetypes prevail: scale-driven direct operators, technology-integrated data analytics specialists, and regional broker-dependent networks. M&A activity and API-first distribution partnerships represent the dominant competitive vectors reshaping market share allocation.
Within the integrated direct operations tier, Fidelity National Title Insurance Co., First American Title Insurance Co., and Stewart Title Guaranty Co. exemplify divergent strategic positioning. Fidelity National occupies a position anchored in captive agency platform density. First American represents the data analytics archetype through proprietary property information assets. Stewart Title sits within specialized closing services concentration in high-velocity refinance corridors.
| Leading Market Players |
|---|
| Chicago Title Insurance Co. |
| Westcor Land Title Insurance Co. |
| First American Title Insurance Co. |
| Title Resources Guaranty Co. |
| Commonwealth Land Title Insurance Co. |
| Fidelity National Title Insurance Co. |
| Stewart Title Guaranty Co. |
| WFG National Title Insurance Co. |
| Old Republic National Title Insurance Co. |
| Others |
Supply Flow & Price Mechanics
Policy-issuance tier divergence between direct underwriter platforms and independent broker networks manifests in divergent pricing architectures and supply chain configurations across the title insurance market. Premium compression in high-volume refinance corridors feeds back into captive agency infrastructure investments, while broker-dependent channels absorb margin erosion through reduced examiner headcount.
Pricing Analysis
Warranty bundling separates lender's policies with integrated title search from unbundled owner-policy offerings that externalize examination costs. The market operates on a per-transaction fee structure with rate filings varying by state insurance department jurisdiction. Price differentiation rests on volume scale and direct lender relationship depth, with national mortgage originators commanding scale-based procurement terms. Cost compression in standardized residential files is intensifying because algorithmic risk scoring displaces manual examination labor. Refinance-focused lenders exhibit highest price sensitivity; commercial portfolio investors show lowest sensitivity due to bespoke coverage requirements.
Supply Chain Analysis
Examiner workforce availability constraints in Texas, Florida, and California metropolitan corridors anchor title plant infrastructure concentration. Raw material dependencies include historical deed repositories, tax lien databases, and court filing systems maintained at county recorder offices. Supply chain risk centers on single-source vulnerability where legacy title plants control comprehensive backward coverage in key markets. Distribution runs through direct underwriter agency platforms, independent broker networks, and API-integrated mortgage origination systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Title insurance market consolidation is accelerating as mortgage originators narrow vendor panels, forcing capital-constrained regional brokers toward acquisition or exit.
For Market Incumbents: To counter channel displacement by API-first distribution platforms, Fidelity National and First American should deepen captive agency density in high-velocity refinance corridors. Backward integration into proprietary title plant infrastructure in Texas and Florida secures data asset control. Certification investment in ALTA cyber security protocols creates compliance-driven switching costs for lender clients. For New Entrants and Emerging Players: Begin with underpenetrated commercial closing segments in secondary metros where standardized multi-state products remain unavailable. White space exists in construction loan title monitoring and 1031 exchange coverage for institutional investors. A go-to-market angle through direct API integration with regional mortgage origination platforms bypasses broker channel fragmentation. For Investors and Strategic Acquirers: Re-rating potential sits with technology-integrated title data specialists given blockchain land registry pilots accelerating across county recording offices. Long-term viability favors platforms with proprietary property information assets and algorithmic underwriting capabilities. The signal to watch is state-level rate modernization proceedings that could compress margins for non-integrated operators.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Distribution Integration | Direct mortgage origination platform connectivity captures higher retention rates per lender account. |
| Blockchain Land Registry Partnership | County recorder pilot participation decentralizes custody and reduces title defect rates. |
| ALTA Cyber Security Certification | Compliance-driven demand from lenders favors certified infrastructure vendors. |
| Refinance Corridor Agency Expansion | High-velocity market presence secures volume commitments from national mortgage originators. |
| Commercial Title Product Standardization | Multi-state coverage instruments address white space in secondary metro transactions. |
Methodological Framework
Document review covered state insurance department rate filings, American Land Title Association operational protocols, and Consumer Financial Protection Bureau disclosure mandates, complemented by interviews with underwriter product executives, mortgage lender procurement officers, title agency operators, and county recorder administrators. Secondary validation drew from regulatory filings, title plant operational disclosures, and mortgage origination platform technical documentation. Bottom-up transaction volume estimates triangulated against top-down premium generation benchmarks.
Cross-referencing historical rate filing patterns with panel input from underwriter pricing committees shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, customer archetype, and service bundling configuration. CAGRs derived from premium volume trajectories intersecting with interest rate cycle assumptions and refinancing velocity projections. Industry-specific forecast inputs incorporated state-level regulatory modernization timelines and digital mortgage adoption curves.
Underlying measurement precision varies by segment; residential refinancing services carry tighter precision than commercial title offerings due to standardized policy forms. Forecasts reflect assumptions around interest rate sensitivity, regulatory digitization mandates, and examiner workforce availability. Material deviation in blockchain land registry adoption rates or state rate filing friction warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Art Insurance Market
Insurance
Estonia Property and Casualty Insurance Market
Insurance
India Life and Non-Life Insurance Market
Insurance
Insurance Aggregators Market
Insurance
Africa Insurance Market
Insurance
Saudi Arabia Travel Insurance Market
Insurance
Financial Protection Market
Insurance
Russia Property and Casualty Insurance Market
Insurance
Employee Benefit Broker Market
Insurance
Logistics Insurance Market
Insurance
Insurance Third Party Administrators Market
Insurance
India Travel Insurance Market
Insurance
Credit Insurance Market
Insurance
Online Insurance Market
Insurance
Agriculture Insurance Market
Insurance
Asia-Pacific Mobile Phone Insurance Market