
 India Property & Casualty Insurance Market | 2026-2036
India Property & Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
India Property & Casualty Insurance Market Insights
Data analytics infrastructure is realigning underwriting economics across the India Property & Casualty Insurance landscape. ICICI Lombard General Insurance leverages predictive modeling to refine risk selection in motor and commercial portfolios. Bajaj Allianz General Insurance sustains rural penetration through bancassurance partnerships and agent networks. New India Assurance Co. Ltd. anchors the public sector segment with dominant positions in government-mandated crop and property covers.
Property and casualty insurance encompasses contracts that indemnify policyholders against financial loss from damage to physical assets, liability exposures, or specified perils, with terms governed by actuarial risk pools, premium adequacy ratios, and claims reserve requirements. Auto insurance and commercial insurance represent the largest premium pools, with commercial lines capturing disproportionate margin contribution from industrial and infrastructure risks. SME penetration across home insurance and travel insurance remains structurally underdeveloped relative to corporates, creating expansion vectors for online platforms and broker-led distribution.
IRDAI governs solvency margins, product filing approvals, and distribution norms, while BIS standards influence fire safety engineering linked to property coverage pricing. RBI's oversight of bancassurance channels shapes how insurers access retail and SME deposit bases. Stakeholders must weigh capital allocation between traditional agent networks and direct digital acquisition as regulatory sandboxes expand permissible product experimentation.
Market Dynamics
IRDAI's regulatory sandbox framework is compressing product development cycles and enabling digital-first distribution models that bypass traditional agent hierarchies. This structural shift is redrawing competitive economics across motor, commercial, and personal lines.
Growth Catalysts
- SME Commercial Adoption:Small and medium enterprises across Maharashtra and Gujarat are expanding asset coverage as industrial investment accelerates. IRDAI's sandbox approvals allow insurers to trial parametric products for business interruption risks.
- Telematics Penetration:Usage-based motor insurance is gaining traction through smartphone-enabled data capture. Younger policyholders in urban centers favor pay-as-you-drive models over traditional annual premiums.
- Crop Insurance Mandates:Government-mandated agricultural coverage under the Pradhan Mantri Fasal Bima Yojana sustains premium inflows. Rural penetration expands through banking correspondent networks.
Market Restraints
- Reinsurance Cost Volatility:Catastrophe coverage pricing fluctuates with monsoon severity and flood loss accumulation. Indian insurers remain dependent on offshore reinsurance capacity for property catastrophe layers.
- Legacy IT Infrastructure:Core policy administration systems at established carriers constrain real-time data integration. Modernization timelines stretch across multiple budget cycles.
- Claims Litigation Friction:Motor third-party disputes clog consumer forums and civil courts. Disputed liability assessments delay settlement finalization and inflate loss adjustment expenses.
Strategic Opportunities
- Tier-Two City Expansion:Surat, Pune, and Coimbatore present underpenetrated commercial lines potential. Industrial clusters in these centers lack specialized risk transfer solutions for supply chain disruptions.
- Cyber Liability Emergence:Digital transaction growth among Indian SMEs creates demand for first-party cyber coverage. IRDAI's 2023 sandbox guidelines permit standalone cyber product filings.
- API-Enabled Distribution:Embedded insurance partnerships with fintech lenders and e-commerce platforms open direct acquisition channels. Policy issuance integrates at point-of-sale across travel, gadget, and mobility transactions.
Industry Challenges
- Actuarial Talent Scarcity:Qualified pricing professionals with predictive modeling expertise command premium compensation. Insurers compete with banking and consulting sectors for quantitative risk analysts.
- Fraud Detection Integration:Image-based motor claims verification requires computer vision deployment across legacy claims workflows. False documentation persists in medical reimbursement and property damage filings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Property & Casualty Insurance Market |
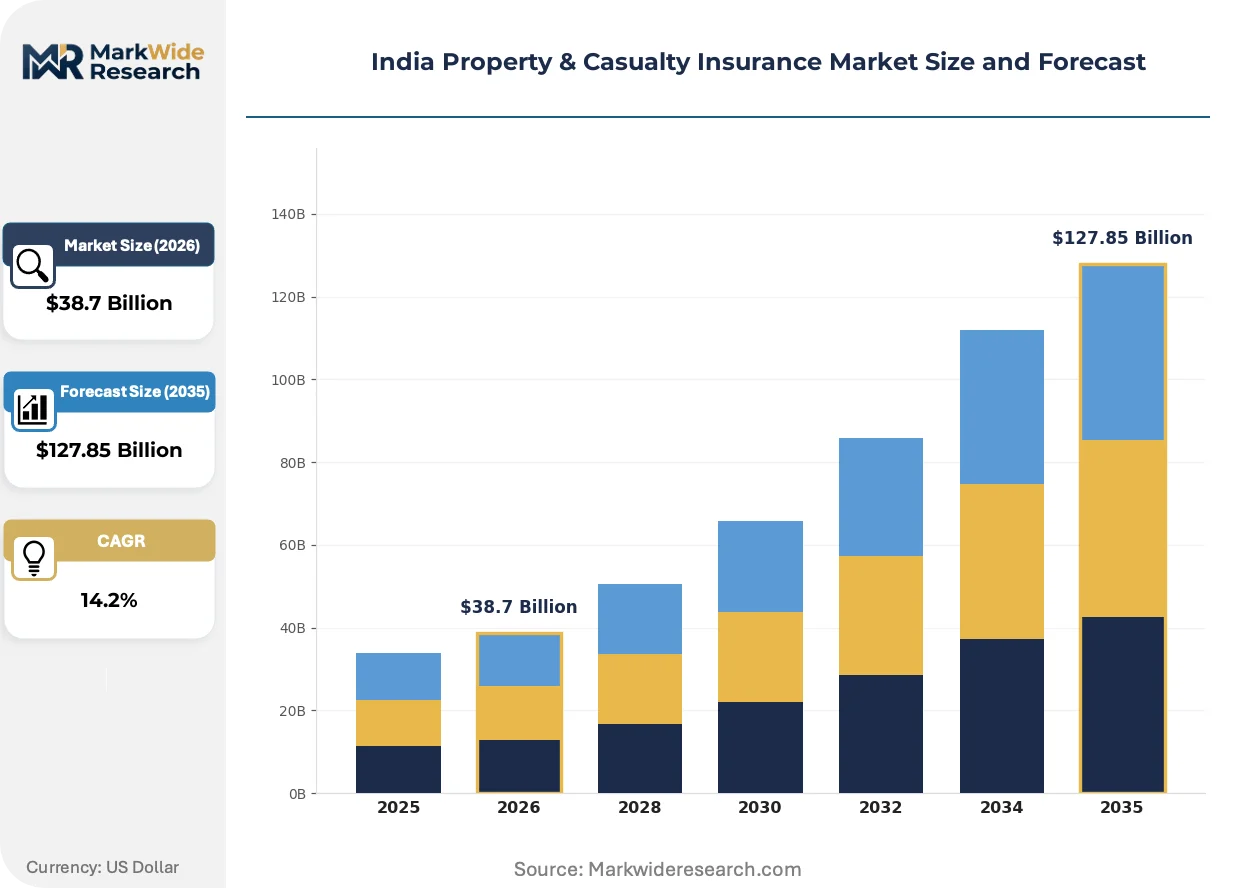
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Insurance, Auto Insurance, Travel Insurance, Commercial Insurance End User: Individuals, SMEs, Corporates, Government Entities Coverage Type: Comprehensive, Third-Party, Liability, Fire Distribution Channel: Direct Sales, Agents, Brokers, Online Platforms |
| Companies Covered | New India Assurance Co. Ltd., ICICI Lombard General Insurance, Bajaj Allianz General Insurance, HDFC ERGO General Insurance, United India Insurance, Tata AIG General Insurance, National Insurance Co. Ltd., Oriental Insurance Co. Ltd., Cholamandalam MS General Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Property & Casualty Insurance Market Trends and Innovations
Digital infrastructure is compressing distribution layers and enabling algorithmic risk selection that was previously uneconomical at scale. Incumbent carriers and insurtech entrants are racing to deploy data assets across underwriting and claims functions.
Telematics platforms are consolidating risk assessment precision in motor portfolios. Fleet operators and ride-hailing aggregators mandate connected vehicle data sharing for coverage eligibility. This technology is consolidating premium pricing power among insurers with superior data ingestion architecture.
IRDAI's Bima Sugam initiative mandates interoperable data standards across the insurance ecosystem. The framework compels carriers to expose policy and claims records through standardized APIs. Smaller regional insurers face compliance cost pressure while digital-native competitors accelerate market entry.
Corporate risk managers are unbundling traditional packaged coverage into component purchases through broker-led reverse auctions. Large manufacturing and infrastructure buyers segment property, liability, and business interruption into separate placements. This procurement evolution concentrates negotiating leverage with specialist brokers in Mumbai and Delhi commercial lines markets.
India Property & Casualty Insurance Market Segmentation
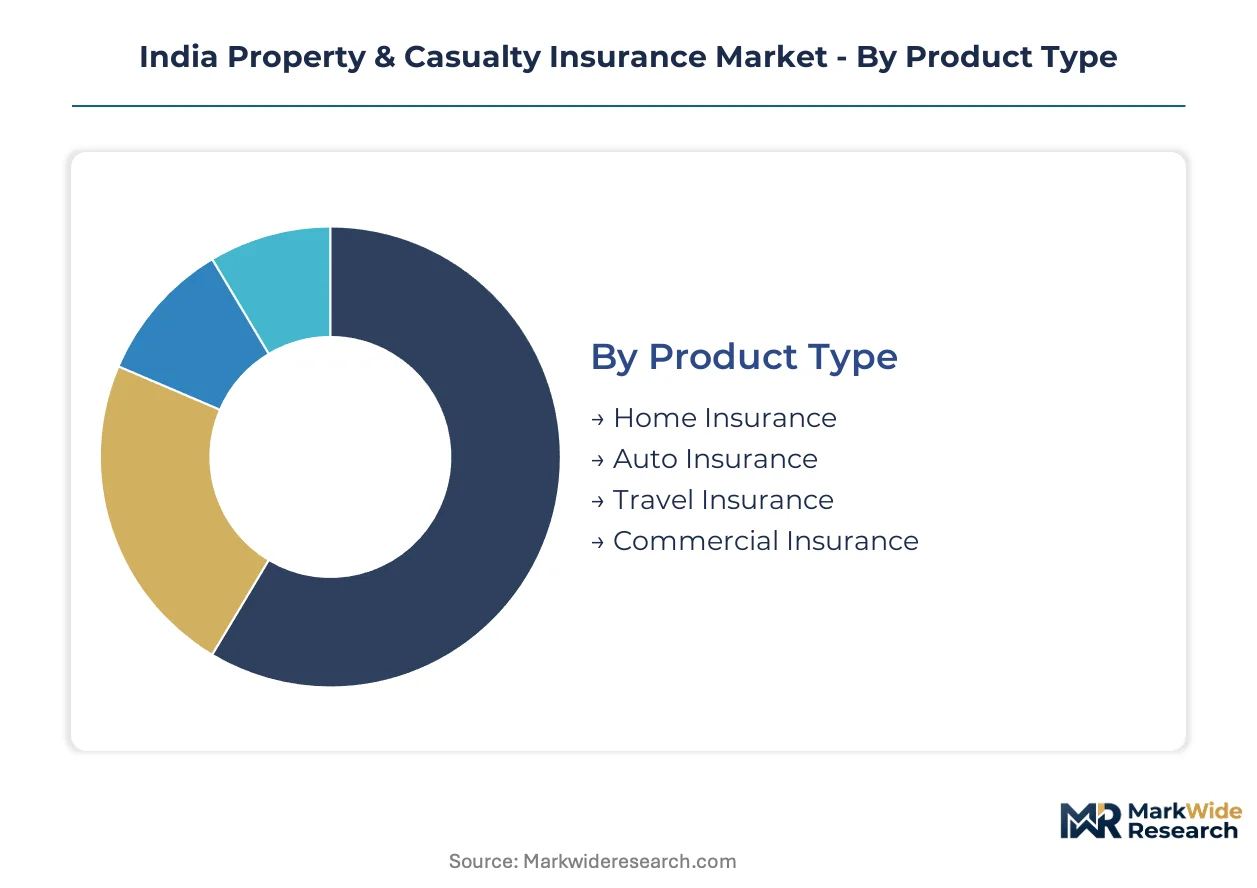
Segmentation reveals how premium pools fragment across risk categories and buyer economics in India's property and casualty landscape. IRDAI's regulatory sandbox permits product-level experimentation that reshapes how carriers allocate capital between personal lines and commercial exposures.
Product Type:
Technical specifications governing risk transfer mechanisms differentiate premium adequacy and loss ratio profiles across product lines.
- Auto Insurance:Motor coverage combines own-damage protection with mandatory third-party liability under the Motor Vehicles Act. Maharashtra and Gujarat generate concentrated premium flows from commercial fleet operators and private vehicle owners navigating dense urban corridors. Telematics integration is compressing pricing cycles for usage-based models.
- Commercial Insurance:Industrial asset and liability coverage spans property, marine, and engineering risks with customized policy wordings. Manufacturing clusters in Pune and Surat drive demand for business interruption and supply chain protection. IRDAI sandbox approvals enable parametric triggers for contingent business loss.
- Home Insurance:Dwelling and contents coverage remains structurally underpenetrated among urban households despite rising property values.
- Travel Insurance:Short-term medical and trip cancellation products attach to international air bookings through airline partnerships.
Mature deployment sits with Auto Insurance. Newer deployment is concentrated in Commercial Insurance.
End User:
Buyer sophistication and procurement authority determine coverage complexity and distribution economics across the customer base.
- Corporates:Large manufacturing and infrastructure enterprises negotiate tailored placements through Mumbai and Delhi broker networks. Risk managers unbundle packaged coverage into component purchases via reverse auctions. Fire and liability limits scale with asset valuations and contractual indemnity requirements.
- SMEs:Small and medium enterprises in tier-two industrial centers lack specialized risk transfer solutions for supply chain disruptions. Bancassurance partnerships and agent networks penetrate this segment with standardized product templates. Premium affordability constraints limit coverage breadth relative to corporates.
- Individuals:Retail buyers access motor and home coverage through direct digital channels and agent intermediaries.
- Government Entities:Public sector undertakings and municipal corporations place large infrastructure and property risks through tender-based processes.
Established underwriting expertise concentrates with Corporates. Steepest expansion trajectory is emerging in SMEs.
Coverage Type:
Indemnity structure and peril scope define claims settlement protocols and reinsurance dependency across coverage categories.
- Comprehensive:All-risk policies covering multiple perils under single contract terms command premium multiples over named-peril alternatives. Commercial property buyers in Gujarat's chemical belt favor comprehensive protection against operational interruption. Pricing reflects catastrophe exposure accumulation and offshore reinsurance costs.
- Third-Party:Mandatory motor liability coverage generates high-frequency, low-severity claims pools with litigation friction in consumer forums. Disputed liability assessments inflate loss adjustment expenses and delay settlement finalization.
- Liability:Professional and product liability coverage protects against legal defense costs and damage awards.
- Fire:Named-peril property coverage adheres to BIS safety engineering standards in premium calculation.
Traditional dominance rests with Fire coverage. Accelerating uptake is visible in Comprehensive.
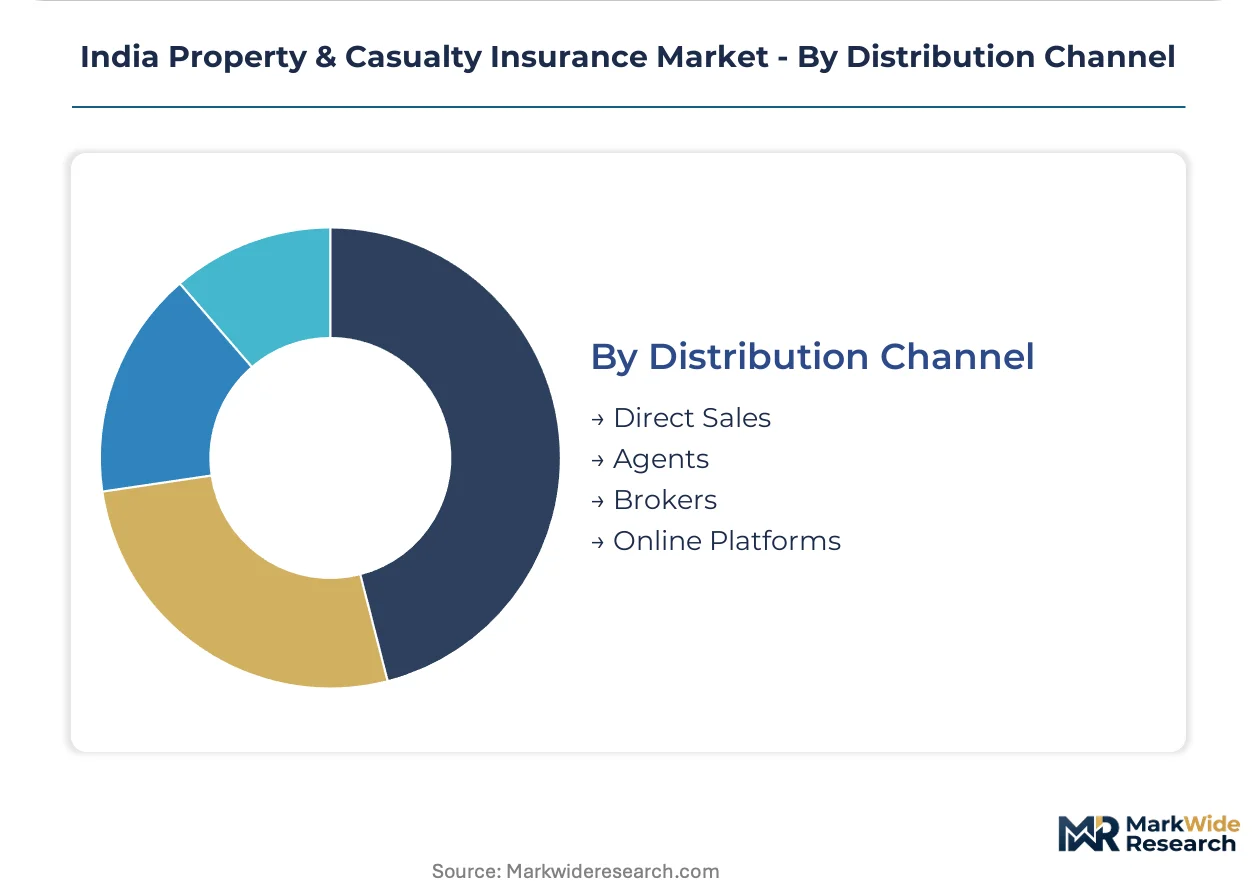
Distribution Channel:
Channel economics and customer acquisition costs vary sharply between physical intermediation and digital direct models.
- Online Platforms:API-enabled issuance integrates at point-of-sale across travel, gadget, and mobility transactions. Fintech lenders and e-commerce partnerships open direct acquisition channels without agent commission loads. Younger policyholders in urban centers favor smartphone-enabled purchase journeys.
- Agents:Individual and corporate agent networks sustain rural penetration and complex commercial placements requiring relationship-based servicing. Commission structures and training investments constrain unit economics relative to digital channels.
- Brokers:Specialist intermediaries concentrate negotiating leverage for large corporate placements in Mumbai commercial lines markets.
- Direct Sales:Insurer-employed sales forces target group policies and affinity segments through employer-sponsored programs.
Volume concentration remains with Agents. Fastest channel expansion is occurring in Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for property and casualty coverage concentrates in Maharashtra and Gujarat, where industrial asset bases and infrastructure investments drive premium growth. Tier-two cities across Karnataka and Tamil Nadu present underpenetrated commercial lines potential. Regulatory sandboxes in select states accelerate digital-first product experimentation.
Maharashtra
Commercial fleet operators and private vehicle owners in Mumbai and Pune generate concentrated motor premium flows. IRDAI's regulatory sandbox framework permits insurers to trial parametric products for business interruption risks in this state. Manufacturing clusters in Pune drive demand for supply chain protection and customized policy wordings.
Gujarat
Chemical belt operations in Vadodara and Surat favor comprehensive property protection against operational interruption. BIS fire safety engineering standards influence premium calculation for named-peril coverage in this industrial corridor. Surat's textile and diamond processing hubs lack specialized risk transfer solutions for contingent business loss.
Karnataka
Technology sector expansion in Bengaluru creates demand for cyber liability coverage among digital-native enterprises. IRDAI's 2023 sandbox guidelines permit standalone cyber product filings in this state. The city's fintech ecosystem drives API-enabled distribution partnerships for embedded insurance at point-of-sale.
Tamil Nadu
Automotive and electronics manufacturing in Chennai and Coimbatore sustains engineering and marine risk coverage placement. RBI oversight of bancassurance channels shapes how insurers access retail deposit bases in this region. Coimbatore's industrial clusters present expansion vectors for SME commercial adoption.
Delhi-NCR
Corporate risk managers in the national capital region unbundle packaged coverage into component purchases through broker-led reverse auctions. Large infrastructure buyers segment property and liability into separate placements. Specialist brokers concentrate negotiating leverage for commercial lines in this market.
India Property & Casualty Insurance Market Competitive Landscape
Strategic partnerships dominate the current landscape as carriers balance traditional agent networks against direct digital acquisition. The market structures around three tiers: public sector incumbents with government-mandated portfolios, private sector conglomerate affiliates with bancassurance scale, and regional specialists with niche commercial expertise. Competitive moves center on API-enabled distribution integration and telematics platform deployment for usage-based motor pricing.
Within the public sector tier, New India Assurance Co. Ltd. and United India Insurance exemplify carriers anchored in government-mandated crop and property coverage. ICICI Lombard General Insurance and Bajaj Allianz General Insurance represent private sector archetypes with predictive modeling capabilities and rural penetration through agent networks. HDFC ERGO General Insurance occupies a position among digital-first competitors leveraging bancassurance partnerships for retail acquisition.
| Leading Market Players |
|---|
| New India Assurance Co. Ltd. |
| ICICI Lombard General Insurance |
| Bajaj Allianz General Insurance |
| HDFC ERGO General Insurance |
| United India Insurance |
| Tata AIG General Insurance |
| National Insurance Co. Ltd. |
| Oriental Insurance Co. Ltd. |
| Cholamandalam MS General Insurance |
| Others |
Pricing and Supply Chain Analysis
Corporate risk managers in Mumbai and Delhi commercial lines markets command pricing leverage through broker-led reverse auctions that unbundle packaged coverage into component purchases. This procurement concentration rewards carriers with superior data ingestion architecture and compresses margins for standardized product templates distributed through agent hierarchies.
Pricing Analysis
Volume concentrates in mandatory motor third-party liability with thin margins, while commercial property and cyber liability lines retain pricing power through customization depth. Premium differentiation hinges on catastrophe exposure accumulation and predictive modeling capabilities, with IRDAI's sandbox framework enabling parametric triggers that command rate multiples over traditional indemnity structures. Pricing pressure stems from reinsurance cost volatility tied to monsoon severity, particularly for property catastrophe layers. SMEs exhibit highest price sensitivity due to premium affordability constraints, whereas large manufacturing enterprises prioritize coverage breadth over rate minimization.
Supply Chain Analysis
BIS fire safety engineering standards and IRDAI solvency margin requirements reshape domestic sourcing for risk assessment infrastructure and claims verification technology. Core technology inputs draw from the United States, United Kingdom, and Singapore for predictive modeling platforms and telematics architecture. Raw material dependencies center on cloud computing capacity, computer vision software, and smartphone-enabled data capture hardware. Single-source vulnerability concentrates in offshore reinsurance capacity for catastrophe layers, with Indian insurers tethered to London and Bermuda markets for peak risk transfer. Distribution runs through bancassurance partnerships, embedded API integrations with fintech platforms, and traditional agent networks with diverging commission economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race as carriers pursue captive control over data ingestion architecture to compress pricing cycles and bypass reinsurance dependency for mid-layer risks.
For Market Incumbents: Extend predictive modeling capabilities into SME commercial lines through API-enabled distribution partnerships that bypass agent commission loads. Consolidate telematics platform ownership to defend against insurtech entrants capturing usage-based motor pricing power. Invest in computer vision deployment across legacy claims workflows to offset litigation friction inflating loss adjustment expenses. For New Entrants and Emerging Players: Smartphone-enabled data capture offers a technology-first wedge into tier-two city commercial lines where Surat, Pune, and Coimbatore industrial clusters lack specialized supply chain disruption coverage. Target SME parametric products for business interruption risks in Maharashtra and Gujarat manufacturing belts. Pursue embedded insurance partnerships with fintech lenders at point-of-sale to acquire customers without legacy agent network investments. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with niche commercial expertise in Karnataka cyber liability and Tamil Nadu engineering risks during reinsurance cost volatility windows. Long-term viability centers on carriers with demonstrated sandbox product approval velocity and interoperable data architecture under Bima Sugam mandates. Monitor IRDAI sandbox approval volume as inflection indicator for digital-native competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Usage-based motor pricing captures younger urban policyholders through smartphone-enabled data capture. |
| Parametric Product Development | IRDAI sandbox approvals enable business interruption triggers that bypass traditional claims adjustment friction. |
| API-Enabled Distribution Partnership | Embedded insurance at fintech point-of-sale opens direct acquisition channels without agent commission loads. |
| Cyber Liability Portfolio Buildout | Standalone product filings under 2023 sandbox guidelines address SME digital transaction protection gaps. |
| Core System Modernization | Real-time data integration replaces legacy policy administration constraining telematics deployment velocity. |
Research Methodology
IRDAI regulatory filings, BIS standards documentation, and RBI bancassurance channel reports formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with underwriting heads, actuarial pricing leads, broker network managers, and claims operations directors at carriers across public and private tiers validated segment-level assumptions. Triangulation across bottom-up premium pool estimates and top-down macroeconomic indicators anchored volume and value outputs.
Bottom-up modeling disaggregated premium flows across auto, commercial, home, and travel product lines, then cross-referenced against end-user procurement authority and distribution channel economics. Segmentation dimensions included coverage type indemnity structure, geographic regulatory cluster, and buyer sophistication tier. CAGRs were derived from fitted growth curves incorporating SME commercial adoption rates, telematics penetration trajectories, and crop insurance mandate expansion across the projection horizon.
Several conditions sit outside the modeled scope, including catastrophic monsoon loss years exceeding reinsurance attachment points, IRDAI sandbox approval delays constraining product launch velocity, and litigation backlog resolution timelines affecting motor third-party reserve adequacy. Forecasts reflect documented assumptions regarding regulatory framework continuity and capital market access for offshore reinsurance placement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Indonesia Private Health Insurance Market
Insurance
Global Home Insurance Market
Insurance
Intellectual Property Liability Insurance Market
Insurance
North America Car Insurance Aggregators Market
Insurance
Asia-Pacific Group Health Insurance Market
Insurance
Global AI in Auto-Insurance Market
Insurance
France Liability Insurance Market
Insurance
Financial Protection Market
Insurance
Cargo Insurance Market
Insurance
Term Insurance Market
Insurance
USA Travelers Insurance Market
Insurance
Property and Casualty Insurance Market
Insurance
Europe Online Insurance Market
Insurance
Digital Insurance Market
Insurance
Asia-Pacific Electronic Gadgets Insurance Market
Insurance
United Kingdom Car Insurance Market