
 Global User and Entity Behavior Analytics Market | 2026-2036
Global User and Entity Behavior Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global User and Entity Behavior Analytics Market Foresight
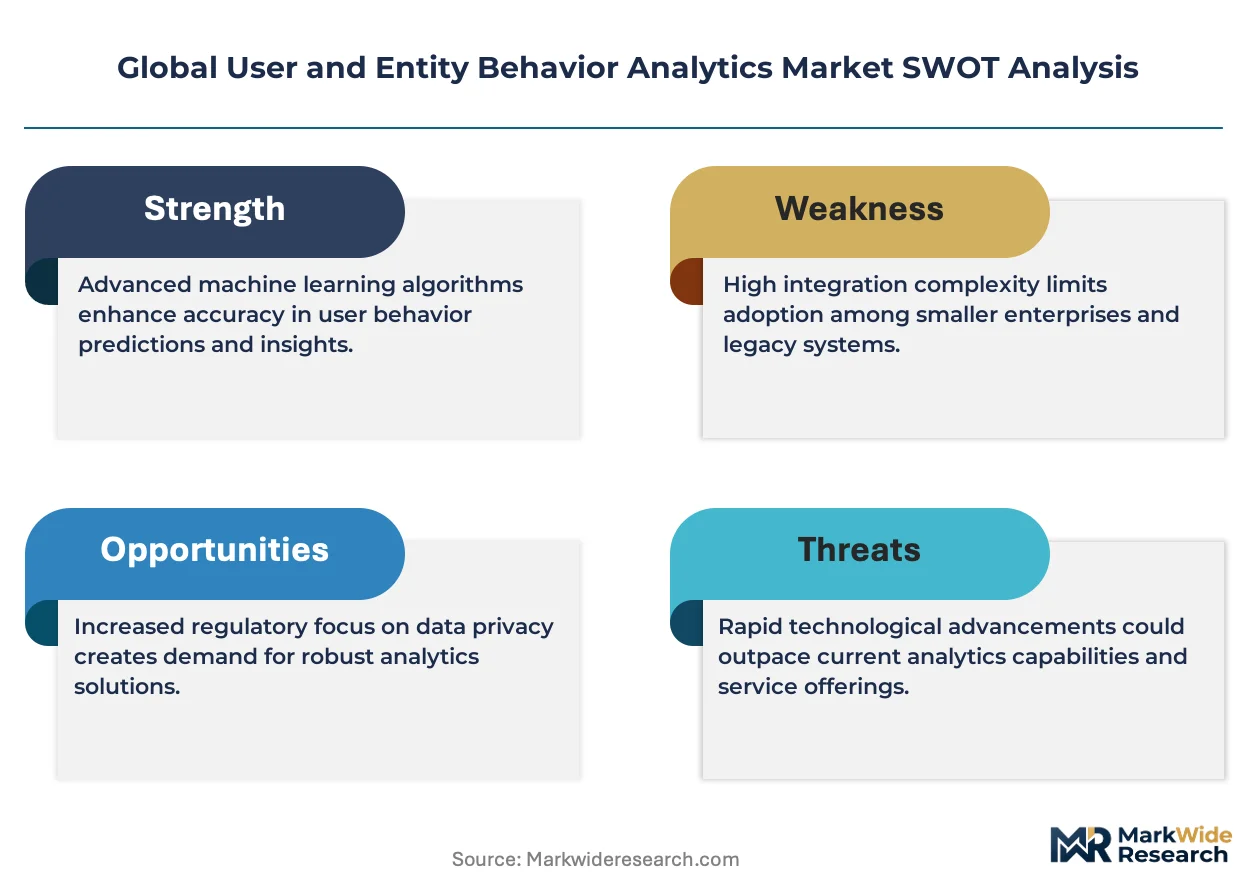
North American cybersecurity vendors is consolidating around cloud-native behavioral analytics architectures. Microsoft Corporation leverages its Azure ecosystem to anchor enterprise deployments across hybrid environments. Palo Alto Networks competes through deep integration of UEBA with next-generation firewalls and SOAR workflows. Splunk specializes in log-centric anomaly detection that dominates security operations center budgets.
User and Entity Behavior Analytics encompasses machine learning systems that baseline normal activity patterns for users, devices, and applications, then flag deviations indicating compromise or misuse through statistical scoring and risk prioritization algorithms. The technology serves commercial and government organizations by reducing mean time to detect insider threats and credential-based attacks. Cloud-Based deployment models lead adoption as financial services and telecom operators abandon capital-intensive on-premises infrastructure. Insider Threat Detection solutions command premium pricing due to regulatory pressure from banking supervisors and data protection authorities. Behavioral Analytics Platforms extend into fraud prevention use cases as e-commerce firms face synthetic identity proliferation.
FDA oversight of medical device cybersecurity, EU GDPR breach notification requirements, and SEC disclosure rules for material cyber incidents collectively mandate auditable behavioral monitoring across regulated enterprises. The EU AI Act adds algorithmic transparency requirements that shape vendor product roadmaps and customer procurement specifications. Stakeholders must evaluate how emerging quantum-resistant authentication standards will recalibrate baseline behavioral models before implementation timelines compress.
Market Dynamics
Cloud migration mandates from financial services regulators are compressing deployment timelines for behavioral analytics platforms, forcing vendors to abandon on-premises architectures entirely. The EU AI Act's algorithmic transparency requirements are recalibrating product roadmaps before compliance deadlines mature.
Growth Catalysts
- GDPR Breach Notification Mandates:European data protection authorities require auditable user activity logs, accelerating procurement of UEBA platforms with native compliance reporting across Germany, France, and the Netherlands.
- Medical Device Cybersecurity Oversight:FDA premarket guidance for connected healthcare equipment mandates continuous behavioral monitoring, opening dedicated vertical solutions for hospital networks and device manufacturers.
- Telecom Operator Cloud Migration:Tier-1 carriers in India and Brazil are abandoning capital-intensive SIEM infrastructure for SaaS-native behavioral analytics, reducing mean time to detect credential compromise.
Market Restraints
- Specialized ML Talent Scarcity:Shortage of data scientists capable of tuning anomaly detection models for low-signal insider threat environments limits vendor scaling velocity.
- Legacy SIEM Sunk Costs:Enterprises with multi-year Splunk or IBM QRadar contracts face contractual friction and integration complexity when evaluating standalone UEBA replacements.
- Quantum-Resistant Authentication Uncertainty:NIST post-quantum cryptographic standards remain in draft status, freezing baseline behavioral model investments until final specifications stabilize.
Strategic Opportunities
- Synthetic Identity Fraud Detection:E-commerce platforms in Southeast Asia are deploying behavioral biometrics convergence with UEBA to combat account takeover at digital checkout points.
- SEC Cyber Disclosure Rules:Material incident reporting requirements for US public companies create audit-trail mandates that behavioral analytics platforms can address through immutable logging architectures.
- Edge Computing Architectures:Manufacturing facilities in Japan and South Korea are processing behavioral telemetry locally to reduce cloud egress costs while maintaining sub-second anomaly detection.
Industry Challenges
- Cross-Domain Data Normalization:Security teams struggle to reconcile identity signals from Active Directory, cloud IAM, and operational technology networks into unified risk scoring frameworks.
- False Positive Tuning:Machine learning models require six to twelve months of environment-specific calibration before achieving actionable alert precision, delaying security operations center trust.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global User and Entity Behavior Analytics Market |
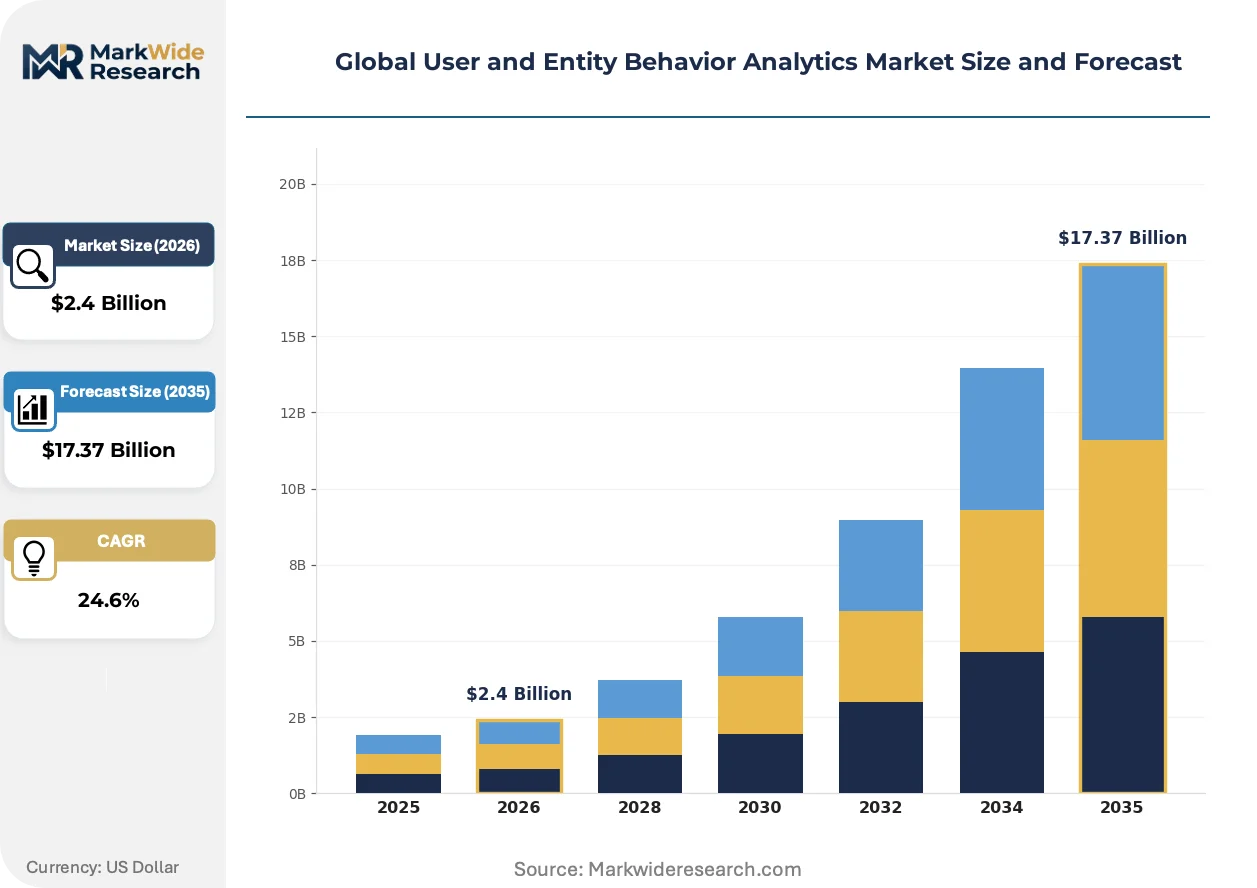
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $17.37 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Behavioral Analytics Platform, Fraud Detection Software, Threat Intelligence System, Insider Threat Detection, Anomaly Detection Tools Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services Use Case: Security Monitoring, Risk Management, Compliance Assurance, Fraud Prevention, Access Management End User: Financial Services, Telecom Operators, Government Agencies, E-Commerce Firms |
| Companies Covered | Microsoft Corporation, Check Point Software Technologies Ltd., Varonis Systems, Inc., Palo Alto Networks, Inc., IBM Corporation, Fortinet, Inc., Rapid7, Inc., Cisco Systems, Inc., Splunk, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global User and Entity Behavior Analytics Market Shifts & Advancements
Behavioral analytics architectures are fragmenting between cloud-native streaming platforms and edge-deployed inference engines, with vendor positioning hardening around latency requirements and data residency constraints.
Federated learning for privacy-preserving anomaly detection is rewriting how multinational banks share threat intelligence without centralizing sensitive transaction data. Deutsche Bank and HSBC pilot implementations demonstrate cross-institutional model training that preserves jurisdictional data sovereignty. This architecture compresses time-to-value for behavioral baselining across dispersed geographic operations.
The EU AI Act's risk classification framework for biometric identification systems is forcing vendors to document training data provenance and decision logic for high-risk deployments. Financial services procurement specifications now require algorithmic impact assessments before contract execution. German banking supervisors have issued interpretive guidance linking UEBA vendor selection to documented fairness metrics.
Security operations centers are unbundling detection engineering from managed security service provider relationships, building in-house behavioral analytics capabilities through open-source toolchains. This pattern concentrates in US technology and fintech verticals where talent density supports specialized hiring. Channel relationships with value-added resellers face margin compression as direct vendor engagement grows preferred.
Global User and Entity Behavior Analytics Market Segmentation
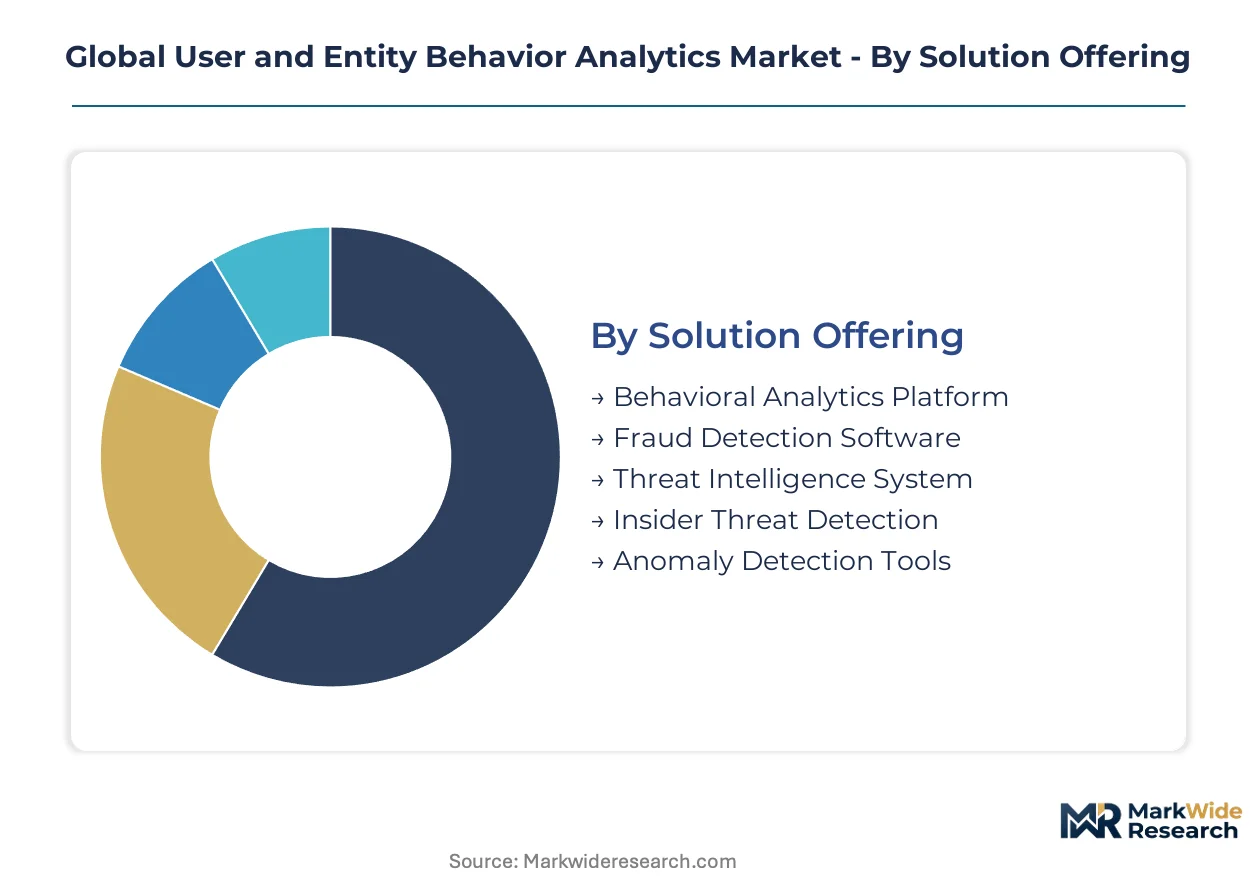
UEBA procurement patterns diverge sharply across deployment architectures and regulatory exposure levels. Organizations prioritize solution configurations that compress mean time to detection while satisfying jurisdiction-specific audit mandates.
Solution Offering:
Replacement cycles accelerate as financial institutions retire rule-based SIEM correlation engines in favor of machine learning-native platforms.
- Behavioral Analytics Platform:Unified systems ingest identity telemetry from Active Directory, cloud IAM, and SaaS applications to establish dynamic baselines. Demand concentrates among US healthcare networks modernizing security operations centers under FDA medical device cybersecurity guidance.
- Insider Threat Detection:Specialized modules apply statistical scoring to privilege escalation patterns and data exfiltration behaviors. German banking supervisors mandate these capabilities under interpretive guidance linking vendor selection to documented fairness metrics.
- Fraud Detection Software:Convergence with behavioral biometrics addresses synthetic identity proliferation at digital checkout points.
- Threat Intelligence System:Federated learning architectures enable cross-institutional model training without centralizing sensitive transaction data.
- Anomaly Detection Tools:Point solutions target manufacturing facilities in Japan processing telemetry locally to reduce cloud egress costs.
Behavioral Analytics Platform sits at the top of the volume ranking, with Insider Threat Detection climbing the fastest.
Deployment Model:
Cost tier differentiation separates capital-intensive infrastructure from operational expenditure models favored by capital-constrained operators.
- Cloud-Based:SaaS-native architectures eliminate hardware procurement cycles and compress deployment timelines from months to weeks. Tier-1 carriers in India and Brazil abandon on-premises SIEM infrastructure to reduce credential compromise detection latency.
- Hybrid:Configurations preserve sensitive data on-premises while leveraging cloud analytics for non-critical workloads. Financial services firms in Switzerland deploy this architecture to satisfy FINMA data residency requirements without sacrificing compute elasticity.
- On-Premises:Remains entrenched in defense and intelligence sectors with classified network mandates.
- Managed Services:Outsourced detection engineering appeals to mid-market enterprises lacking specialized ML talent.
Cloud-Based commands the largest installed base, though Hybrid is gaining share fastest among regulated multinationals.
Use Case:
Application maturity varies with regulatory enforcement intensity and incident disclosure requirements.
- Security Monitoring:Core function dominating security operations center budgets through real-time alert generation and risk prioritization workflows. US public companies deploy these capabilities to satisfy SEC material cyber incident disclosure rules with immutable audit trails.
- Compliance Assurance:Native reporting modules map behavioral telemetry to GDPR breach notification requirements and EU AI Act algorithmic transparency mandates. Procurement accelerates across France, Germany, and the Netherlands following data protection authority enforcement actions.
- Fraud Prevention:E-commerce platforms in Southeast Asia integrate behavioral biometrics at digital checkout points.
- Risk Management:Enterprise-wide risk scoring frameworks consolidate identity signals across Active Directory, cloud IAM, and operational technology networks.
- Access Management:Continuous authentication replaces periodic password validation in zero-trust architectures.
Security Monitoring retains the highest deployment penetration, while Compliance Assurance shows the steepest expansion trajectory.
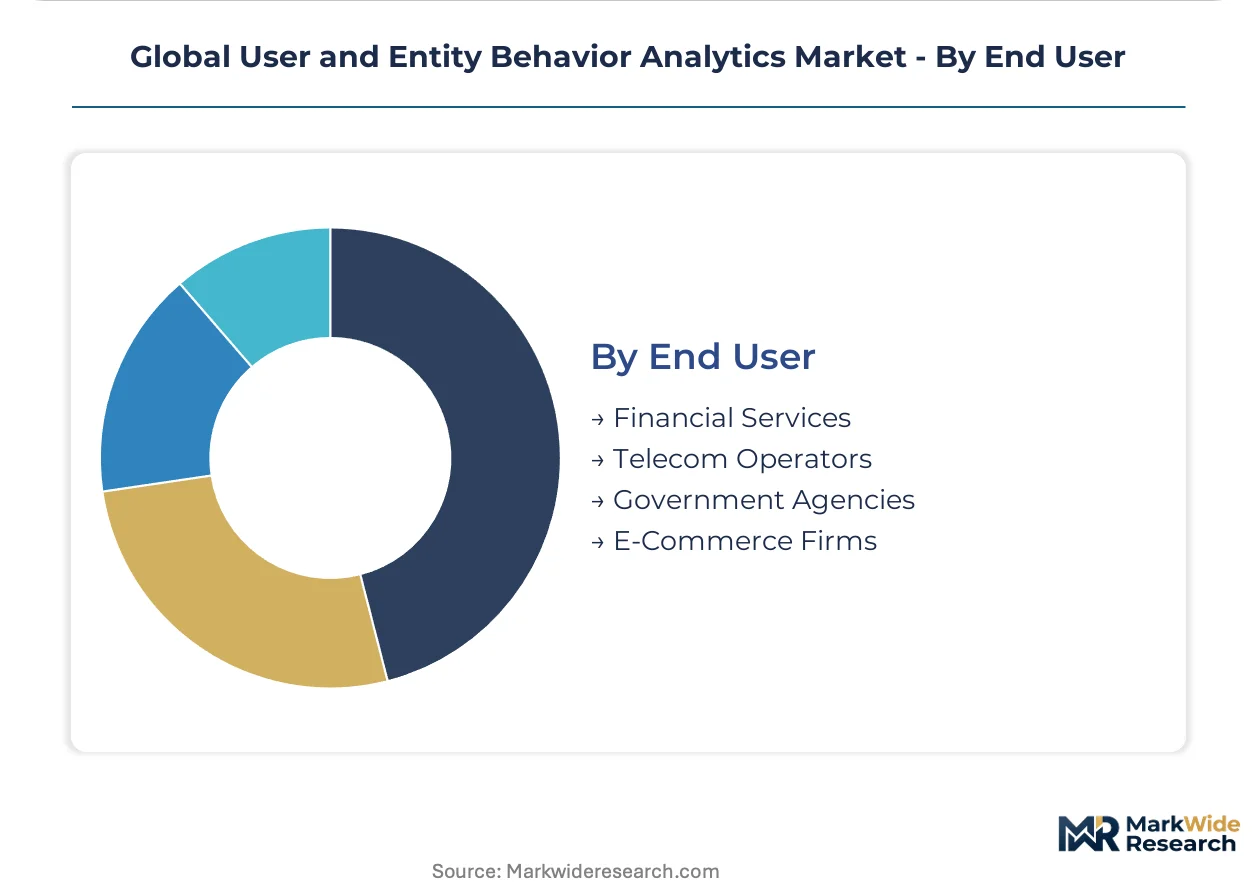
End User:
Customer type determines pricing tolerance and solution complexity requirements.
- Financial Services:Banks and insurers command premium pricing for insider threat detection due to supervisory pressure from banking regulators. Deutsche Bank and HSBC pilot federated learning implementations demonstrating cross-institutional model training.
- Government Agencies:Defense and civilian entities mandate on-premises deployments with classified network accreditation. Procurement specifications emphasize quantum-resistant authentication compatibility.
- Telecom Operators:Tier-1 carriers in Brazil abandon capital-intensive infrastructure for SaaS-native behavioral analytics.
- E-Commerce Firms:Southeast Asian platforms deploy behavioral biometrics convergence to combat account takeover.
Financial Services generates the highest revenue concentration, with Government Agencies expanding most quickly following classified network modernization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outpaces Germany in enterprise security spending intensity, while India accelerates faster than Brazil in cloud-native behavioral analytics adoption. Regulatory enforcement divergence across these jurisdictions creates distinct procurement patterns for UEBA platforms.
United States
Financial services modernization and SEC cyber disclosure mandates drive enterprise demand. The SEC requires immutable audit trails for material incident reporting, pushing US public companies toward behavioral analytics with native compliance architectures. Security operations centers in New York and San Francisco concentrate vendor engagement as direct procurement replaces managed service provider channels.
Germany
Banking supervisory pressure and EU AI Act algorithmic transparency requirements reshape vendor selection criteria. Germany's federal financial regulator links UEBA procurement to documented fairness metrics for high-risk biometric deployments. Frankfurt's financial district hosts concentrated pilot programs for federated learning implementations across multinational banks.
India
Telecom operator cloud migration and RBI cybersecurity guidelines compress deployment timelines for SaaS-native platforms. Tier-1 carriers abandon capital-intensive SIEM infrastructure to reduce credential compromise detection latency. Mumbai and Bangalore clusters concentrate value-added reseller relationships for mid-market enterprise penetration.
Japan
Manufacturing facility edge computing adoption and METI data sovereignty guidance localize behavioral telemetry processing. Japanese industrial conglomerates deploy sub-second anomaly detection to reduce cloud egress costs while maintaining operational technology network isolation. Nagoya and Osaka industrial corridors anchor edge-deployed inference engine installations.
Switzerland
FINMA data residency requirements and private banking secrecy protocols sustain hybrid deployment architectures. Swiss financial institutions preserve sensitive transaction data on-premises while leveraging cloud analytics for non-critical workloads. Zurich and Geneva private banking clusters drive premium pricing tolerance for insider threat detection modules.
Global User and Entity Behavior Analytics Market Competitive Landscape
United States vendors anchor the cloud-native tier; Israeli security specialists hold differentiated positions in threat prevention integration. The vendor base organizes around three strategic archetypes: platform consolidators extending ecosystem dominance, standalone UEBA pure-plays defending technical differentiation, and network security incumbents embedding behavioral analytics into broader infrastructure stacks. Dominant competitive moves include strategic partnerships with cloud hyperscalers and portfolio diversification into adjacent fraud prevention segments.
Within the platform consolidator tier, Microsoft Corporation and Palo Alto Networks occupy positions that exemplify ecosystem-anchored distribution. Microsoft leverages its Azure infrastructure to compress enterprise deployment friction across hybrid environments. Palo Alto Networks represents the network security incumbent archetype, embedding behavioral analytics within next-generation firewall and SOAR workflow integration. Splunk sits within the log-centric anomaly detection specialization that has historically dominated security operations center budget allocations.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Check Point Software Technologies Ltd. |
| Varonis Systems, Inc. |
| Palo Alto Networks, Inc. |
| IBM Corporation |
| Fortinet, Inc. |
| Rapid7, Inc. |
| Cisco Systems, Inc. |
| Splunk, Inc. |
| Others |
Supply & Pricing Matrix
EU AI Act algorithmic transparency mandates gate both qualified supply and premium-tier pricing access, as vendors must document training data provenance and decision logic before German banking supervisors permit procurement of high-risk biometric deployments.
Pricing Analysis
Capacity additions in India are reshaping price floors for SaaS-native behavioral analytics platforms. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by GDPR compliance certification depth and native SOAR workflow integration. Cost compression in the standard tier is intensifying because Tier-1 carriers in Brazil demand rapid deployment without customization. Mid-market enterprises lacking specialized ML talent exhibit highest price sensitivity; financial services firms facing supervisory pressure show lowest.
Supply Chain Analysis
Dual-sourcing requirements from US public companies mandate multi-supplier qualification for immutable logging architectures. Component supply concentrates in the United States, Germany, and India, with inference engine hardware drawing from Taiwan semiconductor fabs and cloud hyperscaler infrastructure. Supply chain risk centers on single-source vulnerability for federated learning model training infrastructure. Distribution runs through direct vendor engagement and value-added reseller channels, with channel relationships facing margin compression as security operations centers build in-house capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with regulatory enforcement intensity from banking supervisors and data protection authorities driving steady procurement expansion across financial services and healthcare verticals.
For Market Incumbents: Deploy federated learning partnerships as the primary lever to defend against standalone UEBA pure-plays and open-source toolchains eroding managed security service provider relationships. Deepen backward integration into cloud hyperscaler infrastructure to compress deployment friction across hybrid environments. Invest in algorithmic impact assessment documentation to satisfy EU AI Act procurement specifications before compliance deadlines mature. For New Entrants and Emerging Players: Cloud-native channel routes through mid-market security operations centers in India and Brazil offer the most penetrable entry points, as Tier-1 carriers abandon capital-intensive SIEM infrastructure for SaaS-native alternatives. Target manufacturing facilities in Japan deploying edge computing architectures for sub-second anomaly detection with localized processing. Pursue OEM integration partnerships with next-generation firewall vendors to bypass direct procurement friction. For Investors and Strategic Acquirers: Roll-up economics work for platform consolidators because behavioral analytics architectures are fragmenting between cloud-native streaming and edge-deployed inference engines, creating acquisition targets with technical differentiation. Five-to-ten-year viability hinges on quantum-resistant authentication compatibility and federated learning capability depth. Watch NIST post-quantum cryptographic standard finalization as the signal indicating baseline behavioral model investment resumption.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Partnership | Deutsche Bank and HSBC pilots demonstrate cross-institutional model training preserving data sovereignty. |
| Edge Computing Deployment | Japanese manufacturing facilities in Nagoya and Osaka corridors localize telemetry processing to reduce cloud egress costs. |
| Algorithmic Transparency Certification | German banking supervisors link UEBA vendor selection to documented fairness metrics for high-risk deployments. |
| SOAR Workflow Integration | Palo Alto Networks embeds behavioral analytics within next-generation firewall infrastructure to compress detection latency. |
| Immutable Logging Architecture | SEC material cyber incident disclosure rules push US public companies toward native compliance reporting capabilities. |
Research Methodology
Direct dialogue with chief information security officers, security operations center directors, banking regulatory affairs leads, and healthcare biomedical engineers grounded qualitative findings, combined with secondary validation from SEC cybersecurity disclosure filings, EU AI Act interpretive guidance documents, FDA medical device cybersecurity premarket submissions, and hospital procurement databases. Bottom-up and top-down triangulation reconciled vendor-reported deployment metrics with enterprise IT budget allocations.
Bottom-up modeling aggregated segment-level adoption curves across deployment architectures, solution offerings, and end-user verticals, while top-down analysis calibrated aggregate market expansion against regulatory enforcement timelines and cloud migration mandates. CAGRs derived from environment-specific calibration periods for machine learning models and procurement cycle compression observed across financial services modernization programs. Inputs included SIEM replacement velocity, federated learning pilot expansion rates, and edge computing infrastructure capex disclosures.
The model assumes a particular technology adoption path; alternative pathways for quantum-resistant authentication standardization would alter the outlook if NIST specifications diverge from current draft frameworks. Deviation in EU AI Act enforcement intensity or banking supervisory guidance interpretation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Capacity Management Analytics Market
Analytics
Germany Geospatial Analytics Market
Analytics
Edge Analytics Market
Analytics
Global Network Analytics Market
Analytics
Global Saas-Based Business Analytics Market
Analytics
Global Business Intelligence (BI) Software Market
Analytics
Location Analytics Market
Analytics
Spain Geospatial Imagery Analytics Market
Analytics
Global in-Store Analytics Market
Analytics
Embedded Analytics Market
Analytics
Mobile Apps and Web Analytics Market
Analytics
Global Analytics Market
Analytics
Global Clickstream Analytics Market
Analytics
Data Analytics Outsourcing Market
Analytics
Lead Intelligence Software Market
Analytics
Multichannel Analytics Market