
 Analytics of Things (Aot) Market | 2026-2036
Analytics of Things (Aot) Market Size, Share, and Industry Trends Forecast 2026-2036
Analytics of Things (Aot) Market Analysis
A capability gap in edge-computing infrastructure between hyperscale cloud operators and legacy enterprise software vendors is redrawing competitive boundaries in the Analytics of Things ecosystem. Microsoft leverages its Azure IoT platform to sustain hybrid deployment dominance across industrial end users. IBM Corporation anchors its position through specialized predictive maintenance solutions that integrate with existing operational technology stacks. Amazon Web Services, Inc. competes on serverless analytics architectures that reduce latency for real-time telemetry processing.
Analytics of Things refers to the application of advanced analytical techniques—statistical modeling, machine learning inference, and complex event processing—to data streams generated by connected sensors, actuators, and embedded systems, typically requiring sub-second processing latencies for operational decision-making. The technology serves industrial and commercial purposes by transforming raw device telemetry into actionable intelligence for automated control, anomaly detection, and resource optimization. Cloud-based deployment leads in revenue contribution due to elasticity requirements for variable data volumes, though edge computing represents the fastest-expanding segment as manufacturers seek to minimize bandwidth costs and satisfy data sovereignty constraints. Among end-user verticals, manufacturing occupies the deepest margin pools because production-line analytics command premium pricing tied to measurable downtime reduction.
The U.S. Food and Drug Administration regulates connected healthcare analytics through cybersecurity guidance for medical devices, while the European Union's GDPR and AI Act impose strict constraints on automated decision-making using personal data from smart home and healthcare IoT deployments. China's Ministry of Industry and Information Technology enforces GB standards for industrial IoT data interfaces, shaping product certification requirements for vendors accessing its manufacturing sector. Stakeholders must monitor evolving cross-border data localization mandates and determine whether distributed edge architectures or regional cloud instances offer the more defensible compliance posture.
Market Dynamics
Edge computing architectures are compressing data processing latencies below 100 milliseconds for industrial control systems, forcing vendors to rebuild analytics stacks around distributed inference rather than centralized cloud pipelines.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making restrictions on personal data from healthcare IoT devices are accelerating investment in privacy-preserving edge analytics architectures across German and French hospital networks.
- Predictive maintenance in discrete manufacturing:Japanese automotive OEMs are deploying vibration-sensor analytics to compress unplanned downtime intervals, creating pull-through demand for real-time anomaly detection software.
- 5G private network rollouts:Ultra-reliable low-latency connectivity in US Gulf Coast petrochemical complexes is enabling closed-loop process control that was previously infeasible over Wi-Fi or public cellular.
Market Restraints
- GPU and AI accelerator supply concentration:Taiwan-based foundry capacity constraints for edge inference chips are extending lead times for industrial gateway manufacturers beyond 26 weeks.
- Interoperability protocol fragmentation:Competing industrial data standards between OPC UA, MQTT Sparkplug, and proprietary vendor formats are inflating integration costs for multi-vendor sensor deployments.
- Cybersecurity certification complexity:IEC 62443 compliance timelines for safety-critical infrastructure are stretching 14-18 months, delaying revenue recognition for vendors targeting energy and water utilities.
Strategic Opportunities
- India's smart city infrastructure buildout:Municipal corporations in Bangalore and Hyderabad are tendering for integrated traffic-waste-energy analytics platforms with 15-year operations contracts.
- Digital twin convergence with physics simulation:Combined CFD and machine learning models for semiconductor fabrication are opening premium pricing tiers for vendors with multi-physics software heritage.
- US Inflation Reduction Act clean energy incentives:Domestic content requirements for solar and battery manufacturing are driving demand for production-line traceability analytics with carbon-footprint verification.
Industry Challenges
- Embedded systems machine learning engineering scarcity:The talent pool for optimizing neural networks on sub-watt microcontroller platforms remains shallow, constraining product roadmaps for battery-powered sensor vendors.
- Legacy SCADA migration complexity:Brownfield industrial sites running 1990s-era control systems require costly protocol bridging hardware before analytics layers can extract actionable telemetry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Analytics of Things (Aot) Market |
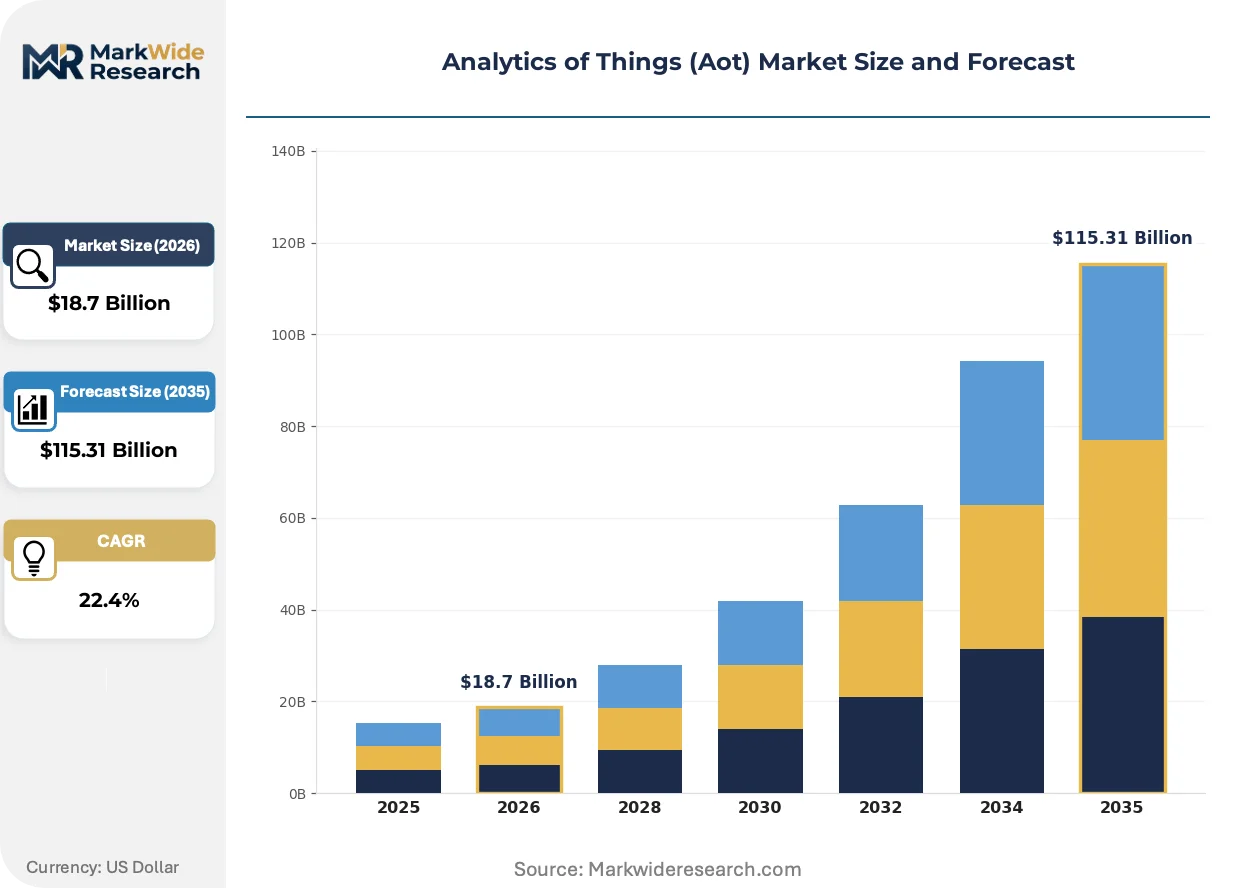
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Healthcare, Manufacturing, Smart Homes, Automotive Solution: Real-Time Analytics, Data Visualization, Predictive Maintenance, IoT Analytics Application: Supply Chain Management, Asset Tracking, Energy Management, Environmental Monitoring |
| Companies Covered | IBM Corporation, Microsoft, Amazon Web Services, Inc., Cisco Systems, Inc., SAP SE, Oracle, Salesforce, Inc., Hewlett Packard Enterprise Development LP, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analytics of Things (Aot) Market Emerging Trajectories
TinyML inference engines are migrating onto microcontroller-class devices, compressing the cost floor for intelligent sensing and enabling analytics deployment in locations previously excluded by power or connectivity constraints.
Neuromorphic silicon from BrainChip and Intel is miniaturizing spiking neural network accelerators into postage-stamp form factors. Discrete manufacturers in Bavaria are piloting these chips for sub-millisecond defect detection on high-speed packaging lines. The technology is miniaturizing the physical footprint of edge intelligence, collapsing the distinction between sensor node and analytics compute unit.
The EU AI Act's risk-based classification system is mandating human oversight interfaces for high-risk industrial automation decisions. German machinery builders are retrofitting explainability dashboards into existing predictive maintenance suites. Food and beverage processors with automated quality-sorting systems face the steepest compliance burdens and are engaging specialized systems integrators for audit trail documentation.
Asset-as-a-service contracting is displacing perpetual software licenses in mid-market manufacturing. Machine tool OEMs in Japan are bundling analytics-driven uptime guarantees with equipment leases, transferring operational risk from plant managers to vendor balance sheets. The shift is most advanced among automotive tier-one suppliers in Aichi Prefecture seeking to reduce capital intensity during model-cycle transitions.
Analytics of Things (Aot) Market Segmentation
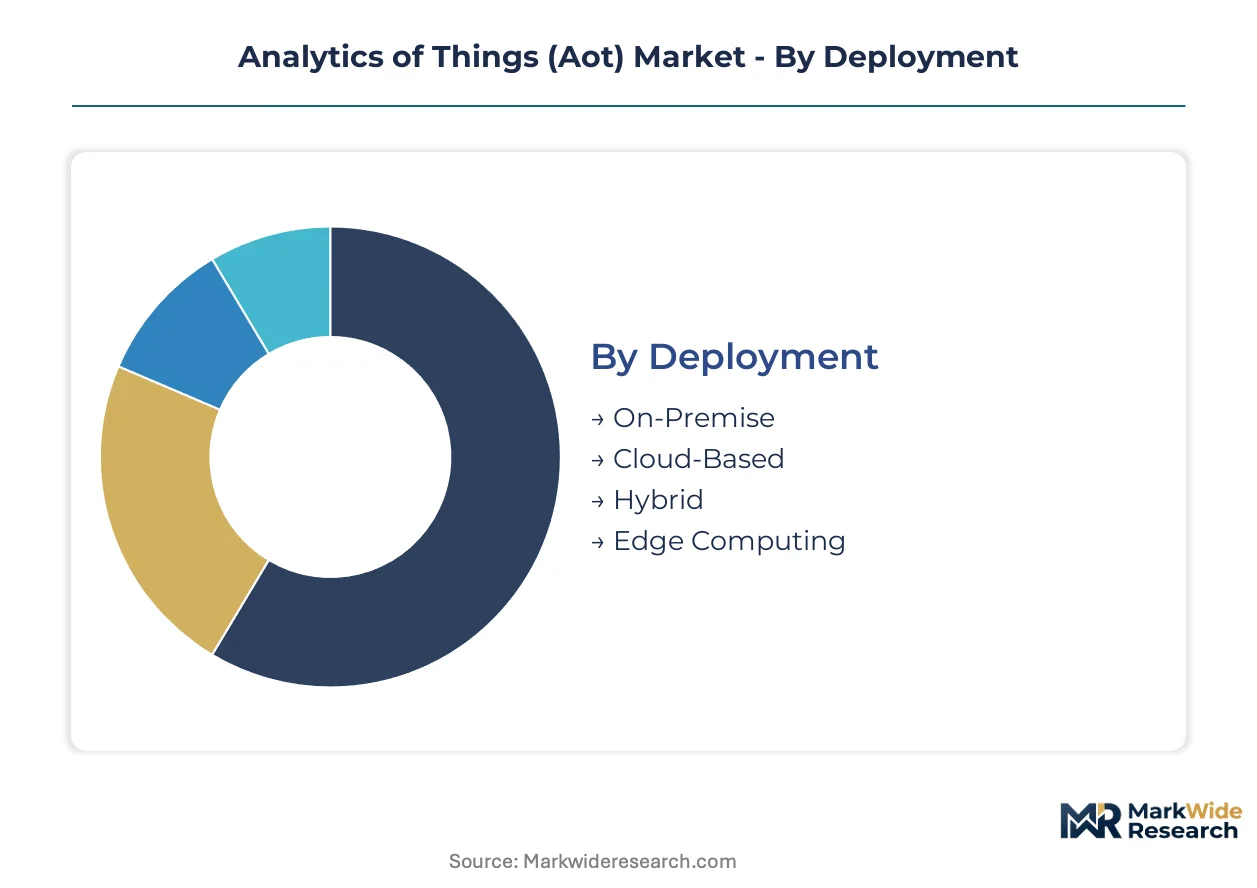
Segmentation in the Analytics of Things market reveals how regulatory pressure, latency requirements, and data sovereignty concerns reshape deployment choices across industries. Understanding these divides exposes where pricing power concentrates and which technology architectures command premium positioning.
Deployment:
GDPR's cross-border transfer restrictions and the EU AI Act's human oversight mandates are fragmenting deployment strategies, with compliance costs now driving architecture selection as much as technical performance.
- Cloud-Based:Elastic compute pools handle variable telemetry volumes from distributed sensor fleets, with German automotive suppliers dominating consumption for centralized model training. The FDA's cybersecurity guidance for connected medical devices imposes validation overhead that slows healthcare cloud migration relative to industrial adopters.
- Edge Computing:Sub-100 millisecond inference on factory-floor gateways satisfies data residency requirements without round-trip latency to distant regions. Bavarian packaging lines and US Gulf Coast petrochemical complexes are expanding deployments fastest where 5G private networks enable closed-loop control.
- Hybrid:Split architectures run sensitive preprocessing locally while feeding anonymized aggregates to cloud analytics layers, balancing compliance with computational depth.
- On-Premise:Air-gapped installations persist in defense and critical infrastructure where IEC 62443 certification timelines stretch procurement cycles.
Established volume favors cloud-based deployment; emerging adoption favors edge computing.
End User:
Margin pools diverge sharply based on measurable downtime costs and regulatory compliance burdens, with production-line analytics commanding premium pricing against consumer-facing deployments.
- Manufacturing:Vibration-sensor predictive maintenance on Japanese automotive assembly lines delivers quantified unplanned downtime reduction, justifying subscription premiums tied to uptime guarantees. The sector absorbs the steepest analytics spending per connected device.
- Healthcare:Remote patient monitoring networks in French and German hospital systems face EU AI Act automated decision-making restrictions, accelerating investment in explainable edge architectures with human-in-the-loop interfaces.
- Automotive:Connected vehicle telemetry streams drive fleet optimization and over-the-air diagnostic pipelines.
- Smart Homes:Privacy-preserving local inference on voice and motion sensors addresses GDPR personal data constraints while limiting cloud subscription attach rates.
Manufacturing captures the deepest margins; healthcare shows the steepest compliance-driven architecture shift.
Solution:
Solution bundling reflects customer maturity, with integrated platforms displacing point tools as industrial buyers consolidate vendor relationships.
- Predictive Maintenance:Physics-informed machine learning models on semiconductor fabrication equipment combine thermal and vibration signatures to forecast bearing failures before yield degradation, opening premium pricing tiers for vendors with multi-physics software heritage.
- Real-Time Analytics:Complex event processing on high-speed production lines enables sub-second anomaly response, with Japanese automotive tier-one suppliers in Aichi Prefecture driving demand for millisecond-latency pipelines.
- IoT Analytics:Unified ingestion and visualization layers reduce integration overhead for brownfield deployments with heterogeneous sensor protocols.
- Data Visualization:Explainability dashboards address EU AI Act audit trail requirements for high-risk automated sorting decisions in food and beverage processing.
Standalone visualization tools face commoditization; integrated predictive maintenance platforms expand fastest.
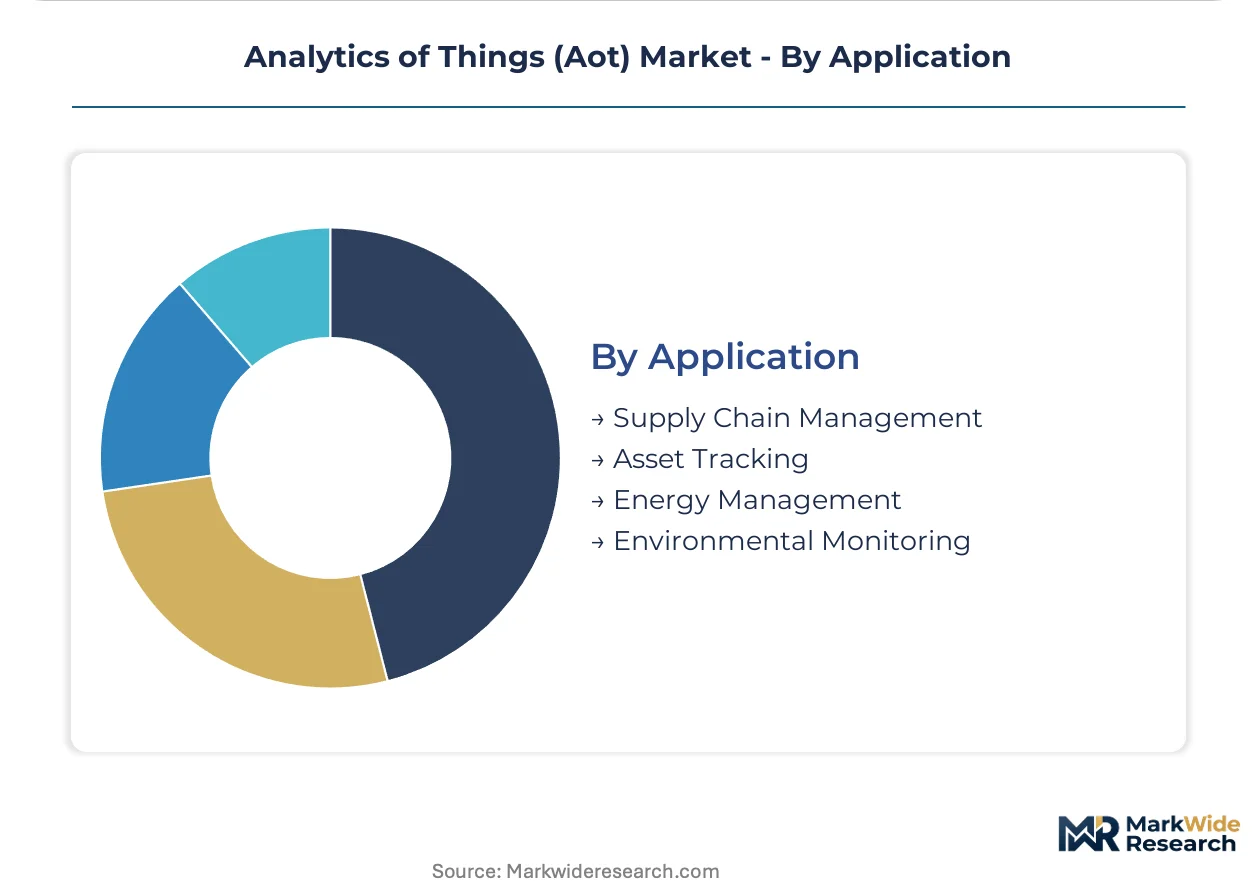
Application:
Application prioritization tracks capital intensity and energy cost exposure, with carbon-foottrace verification emerging as a new spending trigger.
- Supply Chain Management:Production-line traceability analytics with embedded carbon accounting satisfy US Inflation Reduction Act domestic content requirements for solar and battery manufacturing, with vendors capturing multi-year operations contracts.
- Energy Management:Real-time load balancing across industrial microgrids reduces peak demand charges, with German chemical complexes deploying edge-based optimization to minimize grid interaction under volatile electricity pricing.
- Asset Tracking:Indoor positioning and condition monitoring for high-value tooling reduces search time and misplacement losses.
- Environmental Monitoring:Emissions sensing networks face China's MIIT GB standard certification requirements for industrial data interfaces, shaping product roadmaps for vendors accessing its manufacturing sector.
Asset tracking represents mature adoption; supply chain analytics climbs the fastest on regulatory compliance tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan and Germany absorb premium pricing for predictive maintenance suites, while Indian municipal tenders emphasize 15-year operational cost minimization over upfront software investment.
United States
Gulf Coast petrochemical complexes deploy 5G private networks for closed-loop process control, with ultra-reliable low-latency connectivity enabling real-time telemetry processing previously infeasible over Wi-Fi. The FDA's cybersecurity guidance for connected medical devices imposes validation overhead that slows healthcare cloud migration relative to industrial adopters. Houston-area energy infrastructure operators are expanding edge-based analytics deployments to satisfy FERC grid reliability mandates.
Germany
Automotive suppliers in Stuttgart and Munich dominate consumption of centralized cloud analytics for model training, while Bavarian packaging lines pilot neuromorphic silicon for sub-millisecond defect detection. The EU AI Act's risk-based classification system mandates human oversight interfaces for high-risk industrial automation decisions, forcing machinery builders in Baden-Württemberg to retrofit explainability dashboards. German hospital networks are accelerating investment in privacy-preserving edge architectures to comply with GDPR cross-border transfer restrictions.
Japan
Automotive OEMs in Aichi Prefecture deploy vibration-sensor analytics to compress unplanned downtime intervals, with tier-one suppliers driving demand for millisecond-latency real-time pipelines. METI's industrial digitalization programs provide subsidy frameworks for smart factory retrofits. Nagoya-area machine tool OEMs are bundling analytics-driven uptime guarantees with equipment leases, transferring operational risk from plant managers to vendor balance sheets.
China
Semiconductor fabrication facilities in the Yangtze River Delta combine thermal and vibration signatures through physics-informed machine learning models to forecast bearing failures before yield degradation. The Ministry of Industry and Information Technology enforces GB standards for industrial IoT data interfaces, shaping product certification requirements for vendors accessing the manufacturing sector. Shenzhen-based electronics assemblers are expanding environmental monitoring networks to satisfy dual carbon goals emission tracking requirements.
India
Municipal corporations in Bangalore and Hyderabad tender for integrated traffic-waste-energy analytics platforms with 15-year operations contracts, prioritizing total cost of ownership over capital expenditure. The PLI scheme for electronics manufacturing is attracting industrial IoT vendors to establish local edge computing infrastructure. Tamil Nadu's automotive component clusters are piloting predictive maintenance deployments to align with OEM supply chain digitization requirements.
Analytics of Things (Aot) Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with hyperscale cloud operators leveraging platform breadth against vertical software vendors with deep operational technology integration. The competitive terrain separates into three strategic archetypes: infrastructure-anchored platforms, specialized predictive maintenance suites, and serverless analytics architectures. Dominant competitive moves include hybrid deployment bundling and edge-to-cloud pipeline consolidation.
Within the infrastructure-anchored tier, Microsoft and Amazon Web Services occupy positions defined by cloud-native platform scale, while IBM Corporation exemplifies the specialized predictive maintenance archetype through operational technology stack integration. These three entities represent the primary competitive anchors, with Cisco Systems and SAP SE sitting within adjacent networking and enterprise software domains respectively.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft |
| Amazon Web Services, Inc. |
| Cisco Systems, Inc. |
| SAP SE |
| Oracle |
| Salesforce, Inc. |
| Hewlett Packard Enterprise Development LP |
| Others |
Supply Flow & Price Mechanics
IEC 62443 certification timelines for safety-critical infrastructure gate both vendor qualification and price tiering simultaneously, compressing margins for uncertified entrants while enabling premium positioning for compliant suppliers in energy and water utility segments. Buyers absorb extended procurement cycles as the cost of supply security, with certified vendors capturing multi-year service contracts that amortize compliance investment across operational lifespans.
Pricing Analysis
After-sales service revenue from extended maintenance contracts and predictive maintenance subscriptions drives lifetime value for industrial analytics vendors. Three-tier pricing structure across premium, standard, and economy levels separates IEC 62443-certified deployments from uncertified gateway hardware and open-source analytics stacks. Price differentiation rests on certification grade and vertical integration depth, with fully integrated platform vendors commanding service premiums. Cost compression in edge inference hardware is intensifying because Taiwan-based foundry capacity constraints extend component lead times. Mid-market manufacturers show highest price sensitivity, while German automotive OEMs absorb premium pricing for uptime-guaranteed predictive maintenance bundles.
Supply Chain Analysis
Container availability fluctuations on Asia-North America trade lanes elevate inbound logistics costs for edge gateway manufacturers sourcing neuromorphic silicon and AI accelerators. Component supply concentrates in Taiwan, South Korea, and China, with discrete inference chips and industrial-grade sensors drawing from concentrated foundry capacity. Raw material dependencies span silicon wafers, rare earth elements for magnetics, and copper for connectivity infrastructure. Single-source vulnerability around Taiwan-based semiconductor fabrication presents structural risk. Distribution runs through specialized industrial automation distributors and direct OEM procurement channels, with cloud hyperscalers increasingly bypassing traditional channels for enterprise direct sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Analytics of Things market sits in early-cycle expansion, with EU AI Act compliance mandates accelerating replacement demand across European hospital networks and manufacturing facilities that previously deferred analytics investment.
For Market Incumbents: Consolidate hybrid deployment capabilities through edge-to-cloud pipeline unification, defending against serverless analytics entrants by embedding predictive maintenance modules deeper into existing operational technology stacks. Vertical integration into neuromorphic silicon supply channels reduces exposure to Taiwan foundry capacity constraints. Certification investment in IEC 62443 and EU AI Act compliance creates switching costs that protect installed base revenue. For New Entrants and Emerging Players: Lead with privacy-preserving edge architectures targeting German and French healthcare networks facing GDPR cross-border transfer restrictions and automated decision-making oversight mandates. India's smart city infrastructure buildout presents the most penetrable geography, with 15-year operations contracts favoring vendors accepting deferred revenue models. A go-to-market angle bundling carbon-footprint verification analytics with supply chain traceability addresses US Inflation Reduction Act domestic content requirements. For Investors and Strategic Acquirers: The EU AI Act's risk-based classification system reshapes the acquisition landscape, elevating vendors with explainable AI interfaces and audit trail documentation capabilities. Long-term viability centers on platforms spanning both industrial and healthcare verticals with compliant edge architectures. Acquisition target archetype: specialized predictive maintenance vendors with physics-informed machine learning heritage and embedded systems optimization expertise. The signal to watch is 5G private network deployment velocity in US Gulf Coast industrial corridors as proxy for closed-loop control analytics demand.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-to-Cloud Pipeline Integration | Unifies telemetry ingestion across Azure IoT and AWS Greengrass deployments for German automotive suppliers. |
| Neuromorphic Silicon Partnership | Secures sub-millisecond inference capacity for Bavarian packaging line defect detection pilots. |
| IEC 62443 Certification Acceleration | Opens utility procurement channels with 14-18 month compliance timelines for safety-critical infrastructure. |
| Asset-as-a-Service Contracting | Transfers operational risk to vendor balance sheets for Aichi Prefecture automotive tier-one suppliers. |
| Physics Simulation Convergence | Combines CFD and machine learning for semiconductor fabrication yield optimization in Yangtze River Delta. |
Methodological Framework
Operator-level perspectives from plant engineers, maintenance directors, IoT platform architects, and hospital biomedical informatics leads anchored the qualitative base. Primary interviews with industrial automation procurement teams and healthcare technology officers combined with secondary validation from SEC filings of hyperscale cloud operators, FDA cybersecurity guidance documents, EU AI Act regulatory texts, and METI industrial digitalization program disclosures. Bottom-up telemetry volume estimates and top-down market sizing triangulated across deployment model, end-user vertical, solution type, and application area.
Sensitivity analysis around foundry capacity constraints and 5G private network deployment schedules informed the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user industry, solution bundling, and application priority, with regional regulatory clusters treated as distinct adoption environments. CAGRs derived from installed base expansion rates and replacement cycle compression in regulated verticals. Forecast inputs incorporated edge inference cost curves and compliance-driven procurement acceleration patterns.
The analysis sits within stated boundaries; outcomes outside sustained EU AI Act enforcement intensity and stable Taiwan semiconductor supply would require recalibration. Forecasts reflect documented assumptions around industrial digitalization subsidy continuity and cross-border data localization trajectory. Specific risk factors include geopolitical disruption to AI accelerator supply chains and accelerated standardization around OPC UA or MQTT Sparkplug protocols that could reshape integration economics. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Voice Analytics Market
Analytics
Global Marketing Attribution Software Market
Analytics
Global Graph Analytics Market
Analytics
Operational Intelligence Market
Analytics
Marketing Mix Optimization Market
Analytics
Sweden ICT Market
Analytics
Digital Analytics Solutions Market
Analytics
Enterprise Drone Analytics Software Market
Analytics
Manufacturing Analytics Market
Analytics
Dark Analytics Market
Analytics
North America Location Analytics Market
Analytics
Content Analytics Software Market
Analytics
Complex Event Processing Market
Analytics
Europe HR Analytics Market
Analytics
Asia-Pacific Mobile Analytics Market
Analytics
North America HR Analytics Market