
 Big Data Analytics Market | 2026-2036
Big Data Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data Analytics Market Analysis
Healthcare as an end-use vertical is decoupling from traditional retail and manufacturing in analytics spend intensity. Microsoft Corporation leverages its Azure cloud fabric to anchor enterprise healthcare deployments across North American hospital systems. Amazon Web Services competes through specialized health data lake architectures that sustain long-term storage economics for genomic research. IBM Corporation differentiates via Watson Health integration layers that dominate clinical decision-support workflows in academic medical centers.
Big data analytics encompasses the algorithmic processing of multi-terabyte structured and unstructured datasets using distributed computing frameworks such as Apache Spark and Hadoop, with latency thresholds often below 100 milliseconds for real-time streams. Its primary commercial purpose is extracting predictive signals from operational noise to automate decision pipelines across revenue, risk, and resource allocation functions. Cloud deployment now leads infrastructure preference as enterprises abandon capital-intensive on-premises clusters, while predictive analytics commands the fastest expansion within solution categories due to its direct linkage to revenue optimization. Real-time analytics concentrates margin pools in financial services and telecommunications where sub-second latency determines competitive outcomes.
The FDA enforces algorithmic transparency requirements for clinical analytics tools, while HIPAA governs patient data de-identification standards that shape product architecture in health-focused deployments. The EU AI Act imposes risk-tiered conformity assessments on automated decision systems, restricting market access for non-compliant predictive models in European jurisdictions. Stakeholders must monitor evolving cross-border data localization mandates that threaten cloud-native delivery models and force architectural fragmentation across regulatory domains.
Market Dynamics
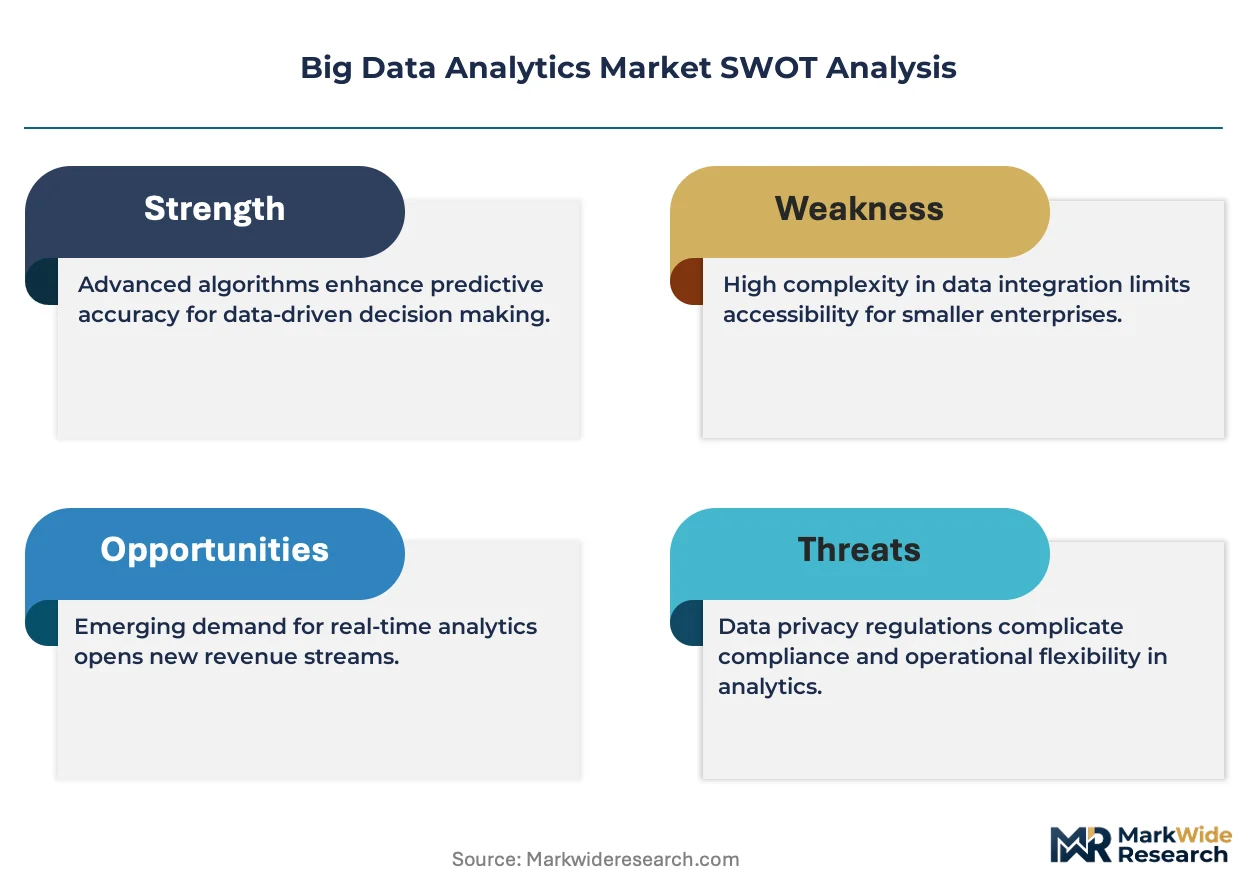
Cloud migration mandates under HIPAA and the EU AI Act are compressing deployment timelines while fragmenting architectural choices across jurisdictional boundaries. Healthcare providers now face dual pressure to modernize infrastructure and demonstrate algorithmic transparency simultaneously.
Growth Catalysts
- EU AI Act Conformity Assessments:Risk-tiered evaluation requirements for automated clinical decision systems are accelerating procurement of compliant analytics platforms across European hospital networks.
- Apache Spark Distributed Processing:Sub-100 millisecond latency thresholds for real-time patient monitoring streams are expanding addressable use cases in critical care and surgical robotics.
- Federal Agency Concentration:United States hospital networks and federal health agencies in the Northeast and California are consolidating vendor relationships around cloud-native deployments.
Market Restraints
- Cross-Border Data Localization:Emerging mandates in multiple jurisdictions threaten cloud-native delivery models and force redundant infrastructure investment.
- Genomic Storage Economics:Long-term archival requirements for petabyte-scale genomic datasets impose sustained cost pressure on research institution budgets.
- Algorithmic Transparency Requirements:FDA enforcement of explainability standards for clinical analytics tools extends development cycles and elevates compliance overhead.
Strategic Opportunities
- HIPAA Data Governance Modernization:De-identification standard updates are creating replacement demand for legacy patient data management architectures.
- Real-Time Financial Services Integration:Sub-second latency requirements in revenue cycle management are opening adjacent market entry for telecom-grade analytics vendors.
- Telemedicine Platform Convergence:Remote patient monitoring systems are fusing with predictive analytics engines to enable preemptive intervention workflows.
Industry Challenges
- Distributed Systems Expertise Scarcity:Shortage of engineers proficient in Hadoop and Spark optimization is constraining deployment velocity for enterprise health systems.
- Legacy Electronic Health Record Integration:Proprietary data formats in incumbent hospital information systems impose middleware costs and latency penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Data Analytics Market |
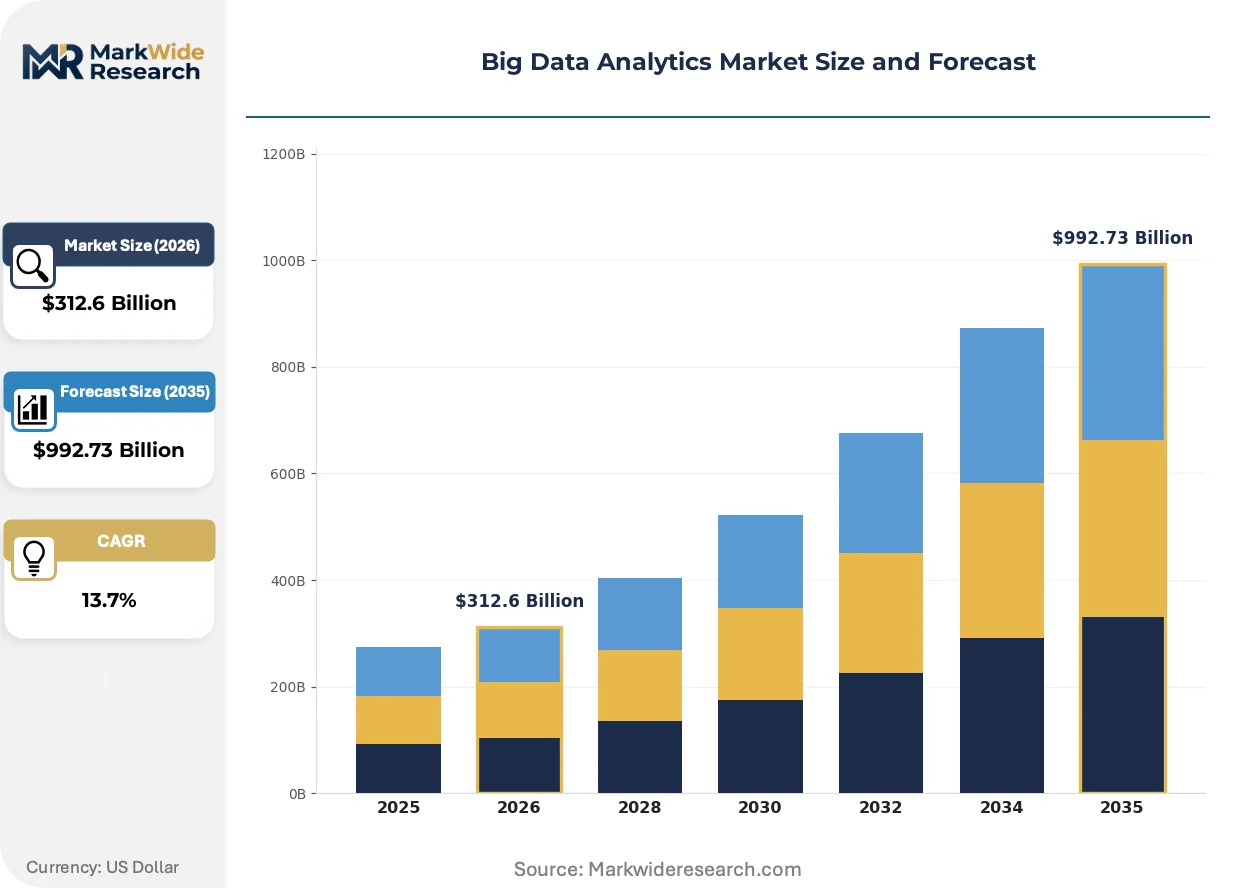
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $992.73 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Managed Services End User: Retail, Healthcare, Finance, Manufacturing Solution: Data Mining, Data Visualization, Predictive Analytics, Real-Time Analytics Application: Fraud Detection, Market Forecasting, Customer Insights, Operational Efficiency |
| Companies Covered | Microsoft Corporation, Amazon Web Services, IBM Corporation, Google LLC, Oracle Corporation, SAP SE, Salesforce, Snowflake Inc., Tableau Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data Analytics Market Emerging Trajectories
Real-time stream processing architectures are displacing batch-oriented workflows across revenue-critical healthcare operations. This shift is compressing decision latency from hours to milliseconds while elevating infrastructure requirements.
Federated learning architectures are electrifying multi-institutional research collaborations by enabling model training across siloed patient datasets without centralizing sensitive records. Academic medical centers in Germany and the Netherlands are piloting these frameworks for rare disease research. The approach is compressing data governance overhead while preserving HIPAA and GDPR compliance boundaries.
The EU AI Act's risk classification system is forcing predictive model vendors to rearchitect product roadmaps around conformity assessment documentation. High-risk clinical decision-support tools now require third-party auditing before market access. European health technology procurement teams are prioritizing vendors with established notified body relationships.
Subscription-based consumption models are displacing perpetual license structures in enterprise analytics procurement. Hospital network CIOs are demanding usage-aligned pricing to match variable patient volume cycles. This pattern is most visible in United States integrated delivery networks consolidating vendor relationships under master service agreements.
Big Data Analytics Market Segmentation
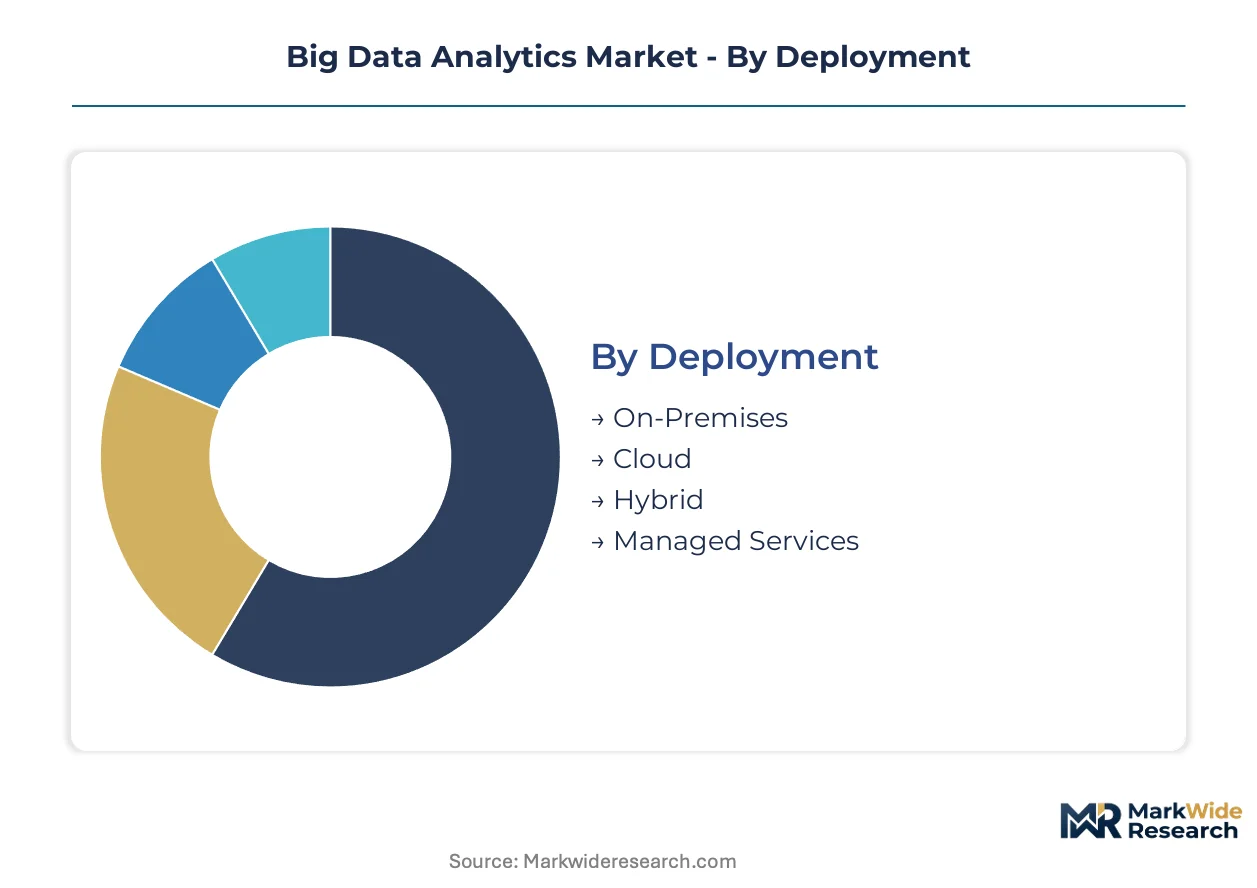
Big data analytics procurement patterns diverge sharply across deployment models, end-user verticals, and solution architectures. Understanding these fault lines reveals where capital commitments concentrate and which technology stacks command premium pricing.
Deployment:
Cloud deployments absorb the heaviest upfront infrastructure investment as enterprises abandon owned data centers for elastic compute contracts.
- Cloud:Elastic compute and storage provisioning eliminates capital expenditure on physical hardware. United States hospital networks in California and the Northeast are consolidating vendor relationships around Azure and AWS architectures to satisfy HIPAA data governance mandates.
- Hybrid:Split workloads between on-premises clusters and public cloud instances for sensitive versus general data processing. Financial services firms in New York maintain trading algorithms on-premises while pushing customer analytics to cloud instances.
- On-Premises:Dedicated hardware installations retain relevance for classified federal workloads and genomic research requiring air-gapped security.
- Managed Services:Third-party operational responsibility for infrastructure maintenance and optimization, appealing to mid-market healthcare providers lacking distributed systems expertise.
Most installed capacity flows through Cloud deployments. Expansion is steepest in Hybrid configurations as regulated industries seek jurisdictional flexibility.
End User:
Healthcare providers now outspend retail and manufacturing on a per-organization basis as patient outcome optimization drives analytics intensity.
- Healthcare:Clinical decision-support workflows and real-time patient monitoring dominate procurement priorities. Academic medical centers deploy Watson Health integration layers for diagnostic assistance while federal agencies mandate algorithmic transparency under FDA enforcement.
- Finance:Sub-second latency requirements for fraud detection and algorithmic trading sustain premium pricing for stream-processing architectures. Revenue cycle management platforms are opening adjacent demand for telecom-grade analytics vendors.
- Retail:Customer segmentation and demand forecasting applications, though maturing, face margin compression from commoditized cloud tooling.
- Manufacturing:Predictive maintenance and supply chain optimization lag in adoption velocity due to legacy operational technology integration costs.
Healthcare captures the largest share of new enterprise commitments. Finance maintains the highest per-seat expenditure levels.
Solution:
Predictive analytics commands the steepest price premiums due to direct revenue linkage, while data visualization approaches commoditization.
- Predictive Analytics:Machine learning models forecasting patient deterioration, equipment failure, or credit default. EU AI Act conformity assessments are accelerating procurement of compliant platforms across European hospital networks.
- Real-Time Analytics:Sub-100 millisecond stream processing for critical care monitoring and financial transaction surveillance. Apache Spark distributed processing is expanding addressable use cases in surgical robotics.
- Data Mining:Pattern extraction from unstructured clinical notes, sensor telemetry, and genomic sequences.
- Data Visualization:Dashboard and reporting layers facing pricing pressure from open-source alternatives and native cloud tooling.
Predictive analytics absorbs the majority of solution-level R&D investment. Real-time analytics is climbing the fastest as latency thresholds tighten.
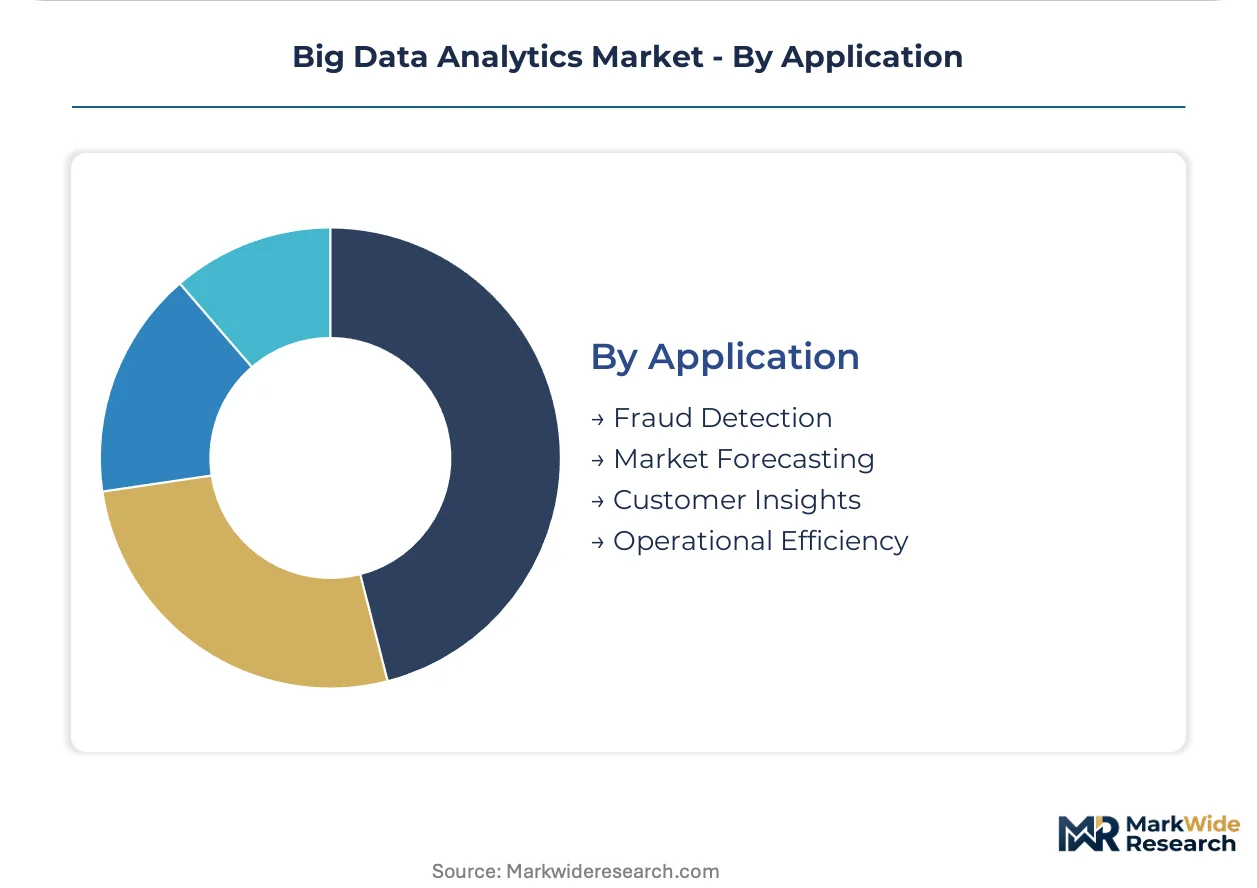
Application:
Fraud detection justifies the highest infrastructure spend per transaction volume due to regulatory scrutiny and financial exposure.
- Fraud Detection:Real-time pattern recognition across payment networks and insurance claims. Cross-border data localization mandates are forcing redundant infrastructure investment for multinational deployments.
- Customer Insights:Behavioral segmentation and lifetime value modeling, increasingly commoditized by platform-native tooling.
- Market Forecasting:Demand prediction and pricing optimization for retail and manufacturing supply chains.
- Operational Efficiency:Resource allocation and process automation, typically the entry point for analytics adoption in cost-constrained environments.
Fraud detection concentrates margin pools in financial services. Customer insights is gaining share fastest as telemedicine platforms fuse remote monitoring with preemptive intervention workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital networks across the United States are consolidating vendor relationships around cloud-native deployments. Federal agencies in the Northeast and California are driving procurement concentration. The EU AI Act is fragmenting architectural choices across European jurisdictions.
United States
Hospital networks in California and the Northeast are absorbing the heaviest analytics infrastructure investment. HIPAA data governance mandates are compressing deployment timelines for cloud migration projects. Federal health agencies in Washington D.C. and Bethesda are mandating algorithmic transparency standards under FDA enforcement.
Germany
Academic medical centers in Berlin and Heidelberg are piloting federated learning frameworks for rare disease research. The EU AI Act's risk-tiered conformity assessments are accelerating procurement of compliant predictive platforms. EMA documentation requirements are forcing vendors to rearchitect product roadmaps around third-party auditing.
United Kingdom
NHS trusts in London and Manchester are expanding real-time patient monitoring deployments. GDPR compliance boundaries are shaping de-identification architectures for genomic data lakes. Oxford and Cambridge research clusters are driving demand for sub-100 millisecond latency stream processing.
India
Telemedicine platforms in Bangalore and Hyderabad are fusing remote monitoring with predictive intervention engines. CDSCO is tightening algorithmic transparency requirements for clinical decision-support tools. Hospital networks in Maharashtra and Delhi-NCR are consolidating around subscription-based consumption models.
Japan
Metropolitan hospital systems in Tokyo and Osaka are deploying clinical decision-support workflows. METI guidelines on automated decision systems are elevating compliance documentation burdens. Pharmaceutical research consortia in Kansai are investing in petabyte-scale genomic storage architectures.
Big Data Analytics Market Vendor Landscape
Strategic partnerships dominate the current landscape as hyperscale cloud providers anchor enterprise healthcare deployments. The vendor base stratifies across three tiers: infrastructure platforms, specialized health data architectures, and clinical workflow integration layers. Technology licensing agreements and geographic expansion represent the primary competitive vectors as players seek jurisdictional coverage under divergent regulatory regimes.
Among North American hyperscalers, Microsoft Corporation exemplifies the infrastructure-platform archetype through Azure cloud fabric deployments. Amazon Web Services occupies a comparable position with health data lake architectures. IBM Corporation represents the clinical workflow specialist tier through Watson Health integration layers. These three entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services |
| IBM Corporation |
| Google LLC |
| Oracle Corporation |
| SAP SE |
| Salesforce |
| Snowflake Inc. |
| Tableau Software |
| Others |
Supply Flow & Price Mechanics
Horizontal integration into managed services partnerships anchors supply positioning and pricing power for mid-market healthcare providers lacking distributed systems expertise. Cloud hyperscalers leverage this structural dependency to enforce usage-aligned subscription tiers that match variable patient volume cycles across United States hospital networks.
Pricing Analysis
Input-cost pass-through from elastic compute provisioning compresses margins for pure-play analytics vendors competing against hyperscale bundled offerings. Three-tier pricing structure across premium, standard, and economy levels separates compliant EU AI Act deployments from basic visualization tools. Price differentiation hinges on certification level—FDA-cleared clinical decision-support modules command substantial premiums over uncertified operational dashboards. Pricing pressure stems from open-source Apache Spark and Hadoop alternatives commoditizing core processing layers. Mid-market healthcare providers exhibit highest price sensitivity, while academic medical centers prioritize algorithmic transparency over cost.
Supply Chain Analysis
Freight and data transfer costs concentrate in cross-border genomic dataset movements between research institutions in Germany, the United Kingdom, and Japan. Supply draws from specialized semiconductor fabrication in Taiwan for GPU acceleration hardware, lithium cell production in South Korea for edge device power systems, and rare earth processing in China for magnetic storage components. Single-source vulnerability pervades EU AI Act conformity assessment documentation, where notified body relationships lock vendors into exclusive third-party auditing channels. Distribution runs through direct enterprise sales teams for hospital network consolidation, supplemented by channel partners serving regional integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications now dominate procurement as HIPAA data governance modernization forces replacement of legacy patient data management architectures. This late-cycle quality story rewards vendors with established compliance documentation and penalizes commodity tool providers.
For Market Incumbents: Anticipate margin compression from federated learning architectures that enable multi-institutional research without centralized data lakes. Defensive consolidation around Watson Health integration layers and Azure cloud fabric deployments protects installed base relationships. Prioritize backward integration into genomic storage hardware to capture long-term archival economics from research institution budgets. For New Entrants and Emerging Players: Mid-tier hospital networks in India's Maharashtra and Delhi-NCR regions represent underserved buyer archetype with subscription-based consumption preference but limited distributed systems expertise. White-space targets include real-time financial services integration for revenue cycle management and telemedicine platform convergence with predictive intervention engines. Go-to-market through managed services partnerships bypasses internal engineering scarcity constraints. For Investors and Strategic Acquirers: Roll-up economics work for clinical workflow integration specialists because EU AI Act conformity assessment requirements fragment vendor relationships across European jurisdictions. Long-term viability centers on platform consolidation plays spanning five-to-ten year regulatory harmonization windows. Target acquisition archetype: federated learning framework providers with established academic medical center pilots. Signal to watch: CDSCO algorithmic transparency enforcement tightening in India as proxy for emerging market regulatory convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure and AWS health data lake architectures satisfy HIPAA mandates for Northeast hospital networks. |
| Regulatory Certification Pathway | FDA algorithmic transparency documentation accelerates procurement for clinical decision-support workflows. |
| Strategic Partnership | Federated learning collaborations between German academic centers compress data governance overhead. |
| Acquisition of Specialist Firm | Watson Health integration layers dominate diagnostic assistance in academic medical centers. |
| Geographic Expansion | Subscription models in United States integrated delivery networks match variable patient volume cycles. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged hospital CIOs, biomedical engineers, GPO contracts managers, and cloud platform integration specialists across United States, German, and Indian health systems. Secondary validation drew from FDA 510(k) filings, EMA conformity assessment databases, hospital procurement contract disclosures, and hyperscaler healthcare vertical revenue segmentations. Bottom-up deployment counts and top-down infrastructure spend estimates were reconciled through iterative triangulation.
Segment-weighting approaches distributed value across cloud, hybrid, and on-premises deployment models, with healthcare, finance, and retail verticals receiving distinct elasticity coefficients. End-user concentration in United States hospital networks and federal agencies, solution-type mix between predictive and real-time analytics, and application intensity in fraud detection versus customer insights shaped projection trajectories. CAGRs were derived from logistic adoption curves fitted to historical cloud migration patterns and regulatory enforcement timelines.
Underlying measurement precision varies by segment; cloud deployment values carry tighter precision than emerging hybrid configurations due to disclosed hyperscaler revenue reporting. Forecasts reflect documented assumptions about EU AI Act enforcement consistency and HIPAA data governance modernization velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
India Geospatial Analytics Market
Analytics
APAC Location Analytics Market
Analytics
Global Development Analytics Tools Market
Analytics
Content Analytics Market
Analytics
Global Big Data Analytics in Telecom Market
Analytics
Lead Intelligence Software Market
Analytics
Global Saas-Based Business Analytics Market
Analytics
Europe Operational Intelligence Market
Analytics
India Contact Center Analytics Market
Analytics
Global Graph Analytics Market
Analytics
Prescriptive Analytics Market
Analytics
Multichannel Analytics Market
Analytics
Product Analytics Market
Analytics
Assortment Analytics Market
Analytics
Europe Emotion Analytics Market
Analytics
Geospatial Imagery Analytics Market