
 Asia Pacific Speech Analytics Market | 2026-2036
Asia Pacific Speech Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Speech Analytics Market Outlook
India's call center corridor is narrowing the gap between legacy voice infrastructure and AI-ready platforms. NICE leverages its installed base across Mumbai and Bangalore to sustain enterprise loyalty. Uniphore anchors its growth on Indic-language NLP capabilities that dominate regional deployments. Microsoft Corporation competes through Azure cloud integrations that extend speech pipelines into existing enterprise stacks.
Speech analytics encompasses the computational extraction of meaning, emotion, and intent from audio signals through automatic speech recognition, natural language processing, and acoustic modeling, operating typically at 8–16 kHz sampling rates with real-time latency thresholds under 300 milliseconds for live agent guidance. Its primary commercial purpose centers on transforming unstructured voice interactions into structured intelligence for compliance verification, sales optimization, and customer experience measurement. Cloud-based deployment leads segment economics by reducing capital barriers for mid-market buyers across Southeast Asia, while voice biometrics commands premium pricing due to fraud-prevention mandates in financial services. Real-time analytics represents the fastest-growing solution category as APAC banks and insurers demand instantaneous intervention during live customer conversations.
India's TRAI recording retention rules, Australia's APRA customer data handling standards, and Japan's Act on Protection of Personal Information collectively shape product architecture by mandating encryption, consent logging, and data sovereignty controls that vendors must embed natively. China's Personal Information Protection Law further fragments cloud deployment strategies by restricting cross-border voice data flows. Stakeholders must weigh localization investments against platform scalability when selecting speech analytics infrastructure for multi-country APAC operations.
Market Dynamics
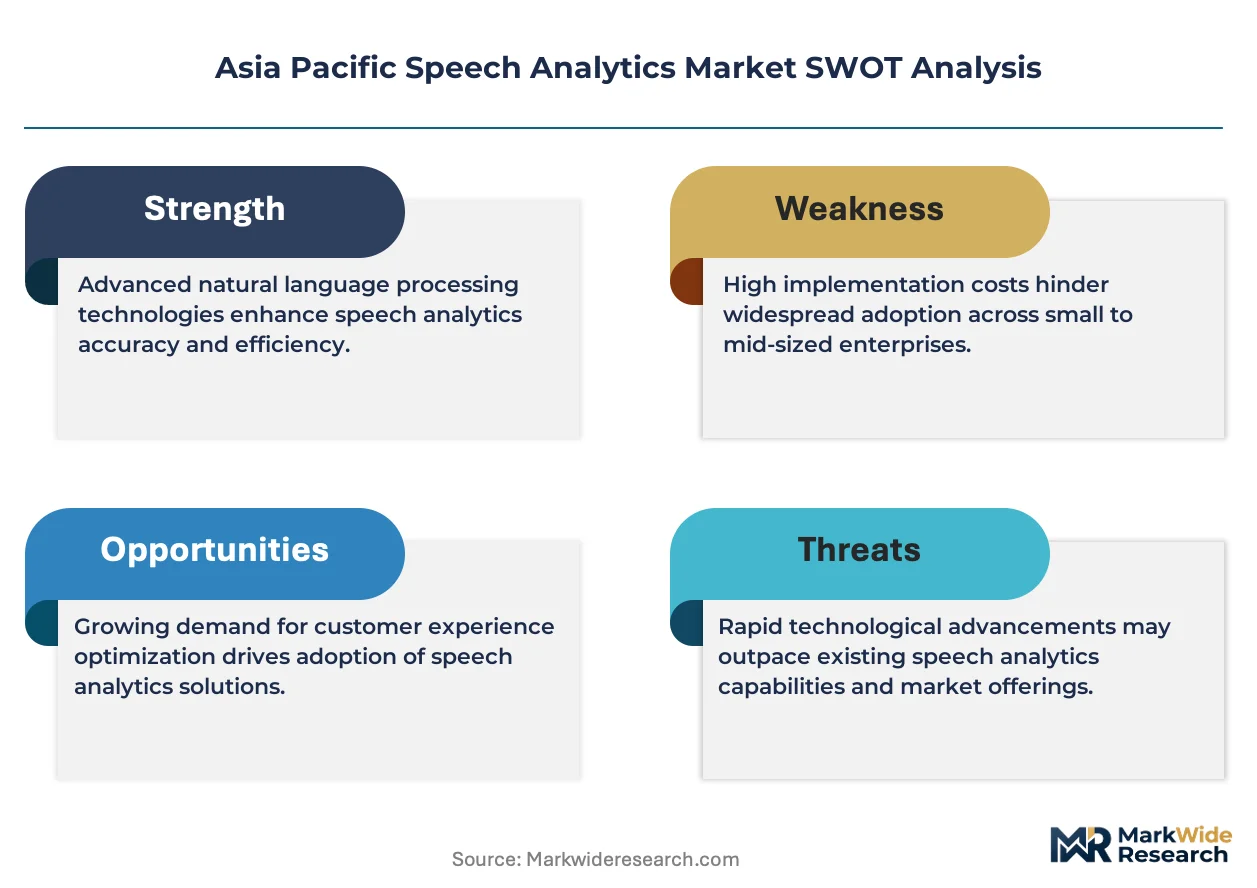
India's TRAI voice recording mandates and Australia's APRA customer data standards are forcing vendors to embed encryption and data sovereignty controls natively, reshaping product architecture across the Asia Pacific Speech Analytics Market.
Growth Catalysts
- Contact Center Automation:India's BPO corridor demands real-time quality assurance tools as enterprises replace manual call sampling with AI-driven monitoring at scale.
- APRA Prudential Standards:Australia's financial compliance sector requires verbatim conversation capture and retention, driving premium deployments in banking and insurance.
- Indic-Language NLP Maturation:Speech recognition engines trained on Hindi, Tamil, and Telugu variants unlock addressable market expansion beyond English-centric installations.
Market Restraints
- Data Localization Costs:China's Personal Information Protection Law restricts cross-border voice flows, forcing redundant in-country infrastructure investments that compress margins.
- GPU Supply Concentration:Training and inference workloads depend on NVIDIA hardware concentrated through Taiwan Semiconductor Manufacturing, creating input cost volatility and allocation risk.
- Accent Variability Limitations:Acoustic models trained on standard Mandarin or Australian English degrade materially with Singlish, Hinglish, and regional dialect variants, requiring costly retraining cycles.
Strategic Opportunities
- Philippines BPO Expansion:The country's contact center workforce exceeds India's in voice-agent headcount, yet speech analytics penetration remains sub-scale, presenting greenfield deployment potential.
- Real-Time Agent Guidance Convergence:Streaming analytics pipelines fused with CRM data streams enable next-best-action recommendations during live conversations, commanding 40-60% pricing premiums over post-call analysis.
- Japan's METI AI Guidelines:The ministry's human-centric AI framework creates procurement preference for explainable emotion-detection models in financial services and healthcare.
Industry Challenges
- Phonetic Transcription Talent Scarcity:Linguists capable of annotating tonal languages like Thai and Vietnamese for model training command compensation premiums that inflate R&D overhead.
- Legacy PBX Integration Friction:On-premise telephony infrastructure across Southeast Asian banks and insurers lacks API-native architectures, extending implementation timelines and requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Speech Analytics Market |
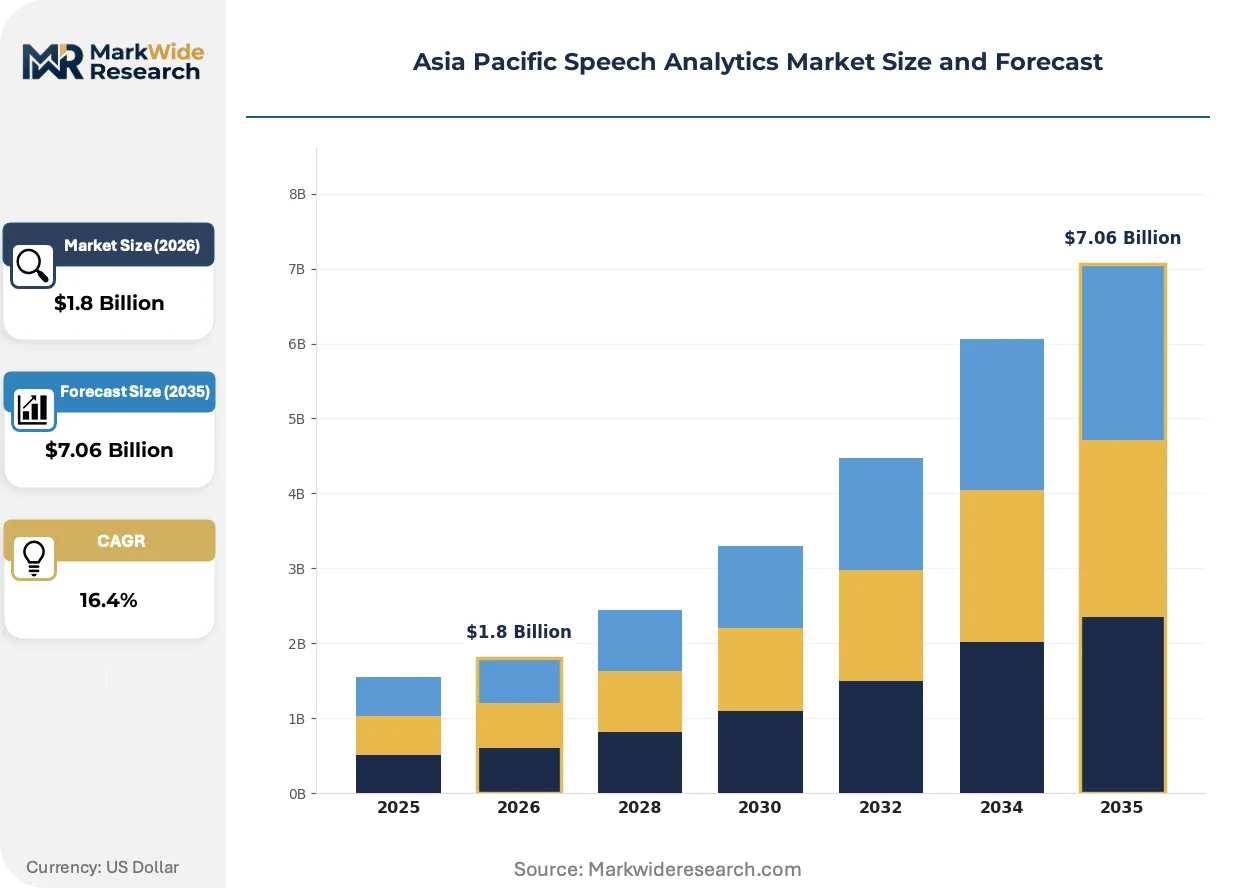
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premises, Cloud-Based, Hybrid, Open Source End User: Healthcare, Retail, Telecommunications, Financial Services Deployment: Public Cloud, Private Cloud, Multi-Cloud, Edge Computing Solution: Real-Time Analytics, Call Center Analytics, Voice Biometrics, Sentiment Analysis |
| Companies Covered | CallMiner, IBM Corporation, NICE, Baidu, Microsoft Corporation, Verint Systems, Avaya, Uniphore, Genesys, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Speech Analytics Market Strategic Shifts
Streaming inference architectures and multimodal fusion are compressing the latency window between spoken utterance and actionable intelligence, redefining competitive differentiation in live customer engagement scenarios.
Transformer-based speech encoders are digitizing acoustic feature extraction by replacing recurrent neural networks with self-attention mechanisms that capture long-range phonetic dependencies. Australian banks and Singaporean insurers are adopting these architectures for sub-200-millisecond emotion classification. This compression of inference latency is digitizing the boundary between post-call analytics and real-time intervention, forcing vendors to rearchitect cloud-edge deployment topologies.
Japan's Act on Protection of Personal Information amendments mandate explicit consent logging for voice biometric enrollment and emotion inference, effective across financial and healthcare sectors. Vendors must now embed audit trails demonstrating purpose limitation and data minimization at the architecture layer. Japanese enterprises are responding by procuring on-premise or sovereign-cloud deployments that satisfy METI guidance on anonymization thresholds.
Buyer procurement patterns are migrating from perpetual license models toward consumption-based pricing indexed to analyzed call minutes. Southeast Asian mid-market enterprises, previously priced out of enterprise-tier platforms, are accessing speech analytics through metered API access. This shift is most visible in Indonesia's digital banking sector, where neobanks scale analytics spend in lockstep with customer acquisition velocity rather than committing upfront capital.
Asia Pacific Speech Analytics Market Segmentation
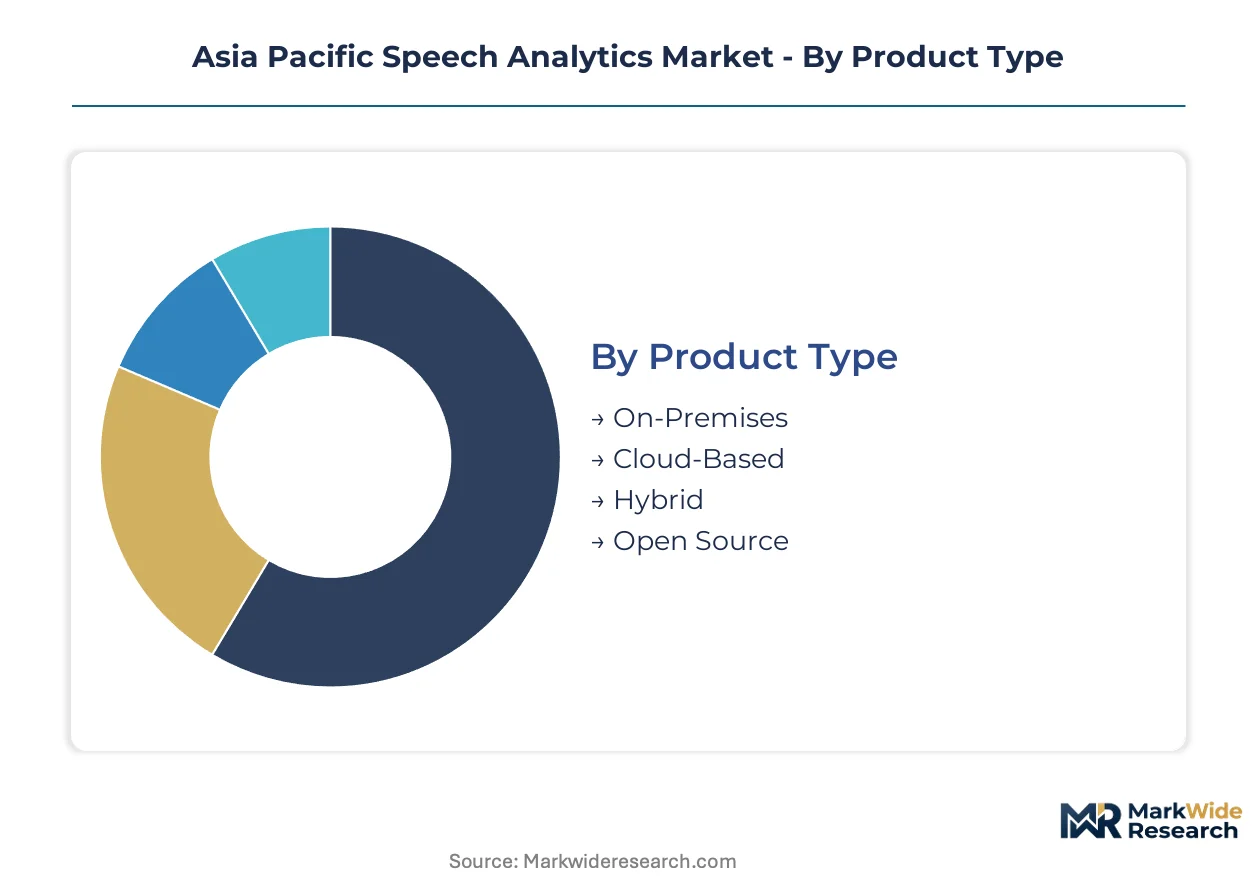
Speech analytics vendors architect product portfolios around deployment latency requirements and data sovereignty constraints. Segment selection determines whether buyers prioritize real-time inference speed, regulatory compliance architecture, or total cost of ownership across APAC's fragmented cloud infrastructure.
Product Type:
Cloud-based deployments turn over fastest as buyers migrate from capital-intensive installations to operational expenditure models; on-premises solutions retain longest replacement cycles due to embedded integration complexity.
- On-Premises:Hardware-resident deployments running dedicated GPU clusters for acoustic model inference. India's TRAI voice retention mandates and China's Personal Information Protection Law drive sovereign infrastructure demand across banking and telecom verticals.
- Cloud-Based:Fully managed SaaS architectures with auto-scaling inference pipelines. Southeast Asian neobanks and Australian insurers favor this model for metered pricing aligned to call volume volatility.
- Hybrid:Split architectures processing sensitive biometric enrollment on-premise while routing anonymized analytics to public cloud. Japanese financial institutions deploy this configuration to satisfy METI consent-logging requirements.
- Open Source:Self-maintained toolkits built on Mozilla DeepSpeech or Kaldi frameworks. Research consortia and university hospitals in South Korea leverage these for custom dialect model development.
On-Premises dominates installed base. Cloud-Based is where expansion concentrates.
End User:
Financial Services commands premium pricing tiers; Retail operates on compressed margins with volume-scaled deployments.
- Healthcare:Clinical conversation capture for diagnostic documentation and patient sentiment monitoring. Australian private hospital networks and Japanese telemedicine platforms deploy these systems to automate encounter coding.
- Retail:Post-call analytics for customer satisfaction scoring and agent coaching. Philippine e-commerce customer service operations represent the largest addressable volume for this segment.
- Telecommunications:Network quality monitoring and churn prediction through voice interaction analysis. Indian telecom operators under TRAI compliance pressure represent the most concentrated demand cluster.
- Financial Services:Real-time fraud detection and regulatory conversation archiving. Singaporean banks and Australian insurers under APRA standards drive the steepest expansion trajectory for voice biometrics integration.
Telecommunications holds the deepest legacy deployment footprint. Financial Services captures the fastest share gain.
Deployment:
Edge Computing contracts carry shortest sales cycles; Multi-Cloud engagements require longest procurement timelines due to vendor coordination complexity.
- Public Cloud:Shared-tenant infrastructure with regional availability zones. Indonesian digital banks and Vietnamese fintechs access speech APIs through hyperscaler marketplaces to bypass infrastructure buildout.
- Private Cloud:Single-tenant environments with dedicated compute isolation. Australian APRA-regulated institutions mandate this architecture for customer data handling compliance.
- Multi-Cloud:Orchestrated workloads across AWS, Azure, and Alibaba Cloud to mitigate concentration risk. Pan-Asian insurers with operations spanning Australia, Singapore, and Hong Kong deploy this topology.
- Edge Computing:On-device inference for sub-100-millisecond latency in live agent guidance. Japanese automotive contact centers and South Korean logistics operators pilot these configurations for real-time intervention.
Public Cloud dominates installed base. Edge Computing is where expansion concentrates.
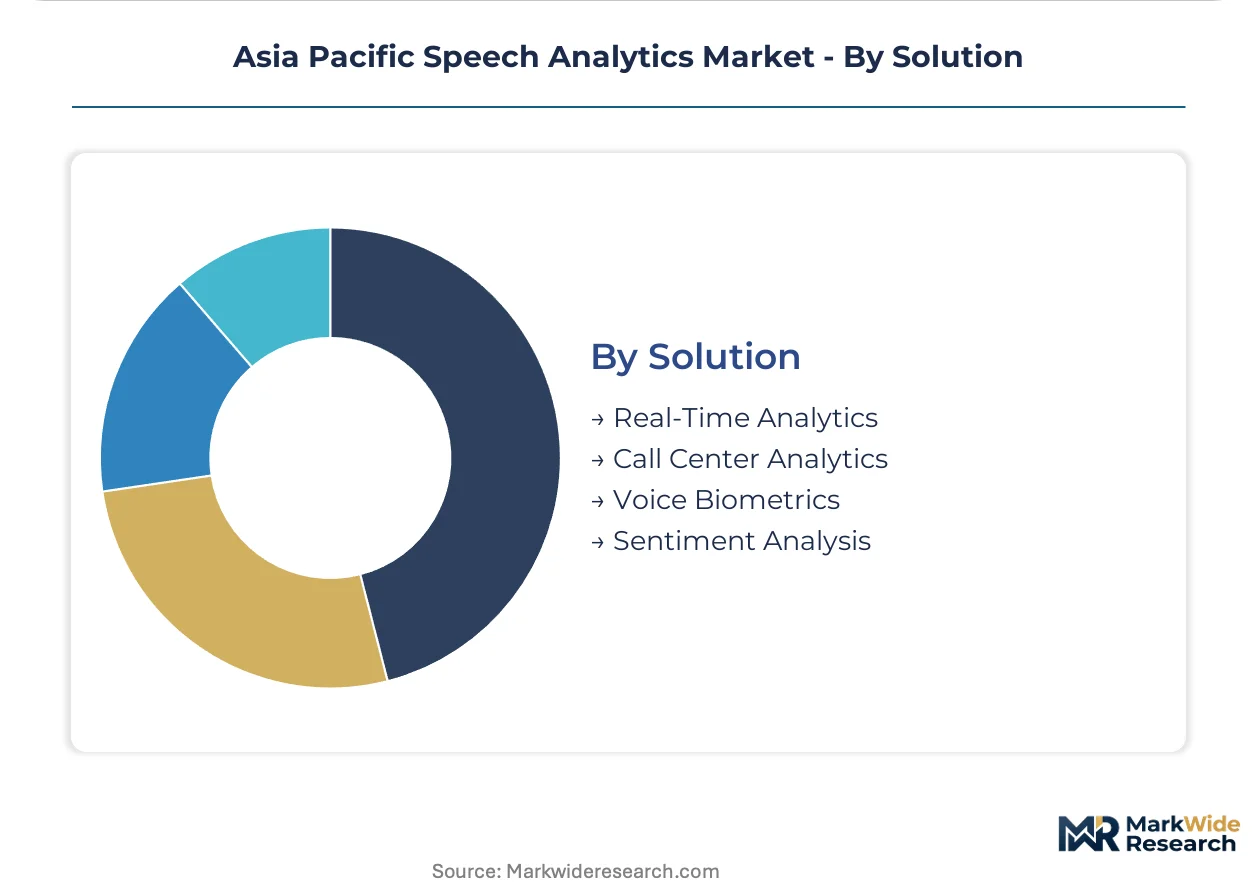
Solution:
Real-Time Analytics refreshes fastest as transformer architectures compress inference windows; Call Center Analytics maintains longest contract durations.
- Real-Time Analytics:Streaming pipelines delivering next-best-action prompts during live conversations. APAC banks and insurers command sub-200-millisecond emotion classification to intercept escalation triggers.
- Call Center Analytics:Post-interaction quality assurance and trend reporting. India's BPO corridor replaces manual sampling with automated scoring across Hindi, Tamil, and Telugu language variants.
- Voice Biometrics:Speaker identification and fraud prevention through acoustic fingerprinting. Singaporean digital banks and Australian neobanks embed these checks in account recovery workflows.
- Sentiment Analysis:Emotional valence extraction from prosodic features and lexical content. Japanese healthcare providers under Act on Protection of Personal Information amendments procure explainable models with audit-trail documentation.
Call Center Analytics dominates installed base. Real-Time Analytics is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys speech analytics primarily for contact center quality automation, while Australia concentrates investment in real-time financial compliance systems, and Japan prioritizes explainable emotion detection for healthcare consent management.
India
TRAI voice recording mandates and BPO corridor expansion drive enterprise adoption across Mumbai and Bangalore. The country's national telecom regulator requires encrypted retention standards that reshape product architecture for banking and telecom verticals. NICE leverages its installed base across these clusters to sustain enterprise loyalty through Indic-language NLP capabilities.
Australia
APRA prudential standards mandate verbatim conversation capture across banking and insurance sectors. The country's financial regulator enforces customer data handling protocols that command premium deployments. Sydney and Melbourne financial centers pilot sub-200-millisecond emotion classification systems for live intervention during customer conversations.
Japan
METI human-centric AI guidelines create procurement preference for explainable emotion-detection models in financial services and healthcare. The Act on Protection of Personal Information mandates explicit consent logging for voice biometric enrollment. Tokyo-based enterprises deploy sovereign-cloud configurations to satisfy anonymization thresholds.
China
The Personal Information Protection Law restricts cross-border voice data flows, forcing redundant in-country infrastructure investments. MIIT standards shape local cloud deployment strategies for acoustic model training. Shanghai and Beijing clusters concentrate development of Mandarin-centric recognition engines with embedded data sovereignty controls.
Singapore
Digital banking licenses and fraud-prevention mandates accelerate voice biometrics integration in account recovery workflows. The Monetary Authority of Singapore's technology risk management guidelines influence procurement patterns for real-time analytics. Financial institutions across the city-state deploy streaming pipelines for next-best-action recommendations during live conversations.
Asia Pacific Speech Analytics Market Competitive Environment
Capability concentration sits with specialized NLP vendors; scale advantage sits with hyperscaler cloud platforms. The market structures around three tiers: established contact center software incumbents, cloud-native speech API providers, and regional language specialists. Competitive moves center on vertical integration into sovereign data infrastructure and strategic partnerships with telecom operators for network-embedded deployment.
Among US-based technology conglomerates, IBM Corporation and Microsoft Corporation occupy positions anchoring enterprise cloud integration strategies. NICE represents the incumbent tier leveraging installed base relationships across India's BPO corridor. Uniphore exemplifies the regional specialist archetype through Indic-language capabilities that dominate deployments across Hindi, Tamil, and Telugu variants.
| Leading Market Players |
|---|
| CallMiner |
| IBM Corporation |
| NICE |
| Baidu |
| Microsoft Corporation |
| Verint Systems |
| Avaya |
| Uniphore |
| Genesys |
| Others |
Value Chain & Pricing Dynamics
GPU cluster undercapacity across Taiwan and South Korea is compressing vendor margins while amplifying pricing power for hyperscaler cloud providers that control reserved compute allocations, reshaping how speech analytics vendors structure customer contracts and supplier relationships across the Asia Pacific region.
Pricing Analysis
Long-term committed use contracts dominate enterprise procurement, with annual subscription tiers indexed to analyzed call-minute volumes replacing perpetual licenses. Pricing stratifies across premium real-time inference, standard post-call analytics, and economy-tier batch processing levels. Cost compression in the economy tier is intensifying as Indonesian neobanks and Vietnamese fintechs demand metered API access without minimum commitments. Mid-market buyers in Southeast Asia exhibit highest price sensitivity, while Australian APRA-regulated institutions accept premium pricing for sovereign-cloud deployments with embedded encryption.
Supply Chain Analysis
Extended payment terms from 30 to 90 days are becoming standard as NVIDIA GPU allocations tighten through Taiwan Semiconductor Manufacturing and Samsung Foundry. Hardware concentration rests on Taiwan, South Korea, and USA for advanced inference accelerators, while acoustic model training draws from labeled datasets sourced through Indian BPO operators and Australian financial institutions. Single-source vulnerability in NVIDIA's H100 and A100 supply creates allocation risk for real-time analytics vendors. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams with embedded solution engineering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific Speech Analytics Market is entering a cyclical recovery phase as contact center automation budgets rebound from post-pandemic retrenchment, with India's TRAI compliance deadlines and Australia's APRA enforcement waves creating synchronized procurement cycles.
For Market Incumbents: Entrench installed base relationships across Mumbai and Bangalore by embedding Indic-language NLP capabilities deeper into existing quality assurance workflows. Defend against cloud-native API providers by certifying sovereign-cloud configurations for China's Personal Information Protection Law and Japan's Act on Protection of Personal Information. Prioritize backward integration into GPU reservation pools to secure inference capacity allocation.
For New Entrants and Emerging Players: Philippine e-commerce customer service operations and Indonesian digital banking voice-agent workforces represent the most penetrable entry points for greenfield speech analytics deployment. Target real-time agent guidance convergence with CRM data streaming as the highest-value solution category. Pursue channel partnerships with telecom operators for network-embedded deployment rather than direct enterprise sales.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across real-time inference infrastructure as GPU procurement costs concentrate margin pressure. Five-to-ten year viability favors vendors with hybrid deployment architectures satisfying multi-country data sovereignty requirements. Acquisition target archetypes include regional language specialists with proprietary acoustic models for tonal languages. Watch NVIDIA allocation announcements as the critical inflection signal for vendor capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Indic-Language NLP Investment | Hindi, Tamil, and Telugu model training unlocks India's BPO corridor expansion beyond English-centric installations. |
| Sovereign-Cloud Certification | Embedded data sovereignty controls satisfy TRAI, APRA, and China's Personal Information Protection Law mandates. |
| Real-Time Inference Architecture | Sub-200-millisecond emotion classification commands premium pricing from Singaporean banks and Australian insurers. |
| Voice Biometrics Integration | Acoustic fingerprinting embedded in account recovery workflows addresses MAS fraud-prevention guidelines. |
| Hyperscaler Marketplace Distribution | AWS, Azure, and Alibaba Cloud listings bypass direct sales cycles for Southeast Asian mid-market buyers. |
Study Parameters
The analysis maps cloud-based deployments, on-premises sovereign infrastructure, hybrid architectures, and open-source toolkits, each validated through contact center operations directors, compliance officers at APRA-regulated institutions, NLP engineering leads, and procurement managers at Indonesian neobanks. Primary interviews with these stakeholders combined with secondary validation from TRAI regulatory filings, APRA prudential standards documentation, METI AI guideline publications, and hyperscaler capex disclosures. Bottom-up call-volume modeling and top-down market sizing triangulate segment outputs.
Assumptions around GPU supply availability, TRAI enforcement timelines, and APRA audit intensity were held fixed across baseline scenarios while varying Indic-language NLP adoption curves and Philippine BPO penetration rates in sensitivity cases. The projection horizon spans deployment models, end-user verticals, solution categories, and regional adoption patterns. CAGRs derive from fitted growth curves against historical contact center automation spend. Forecast inputs include labeled training data availability and acoustic model inference cost trajectories.
Macroeconomic conditions sit as an overlay; deviation in regional cloud infrastructure investment, cross-border data flow restrictions, or GPU supply allocation would shift the trajectory. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Europe Network and Location Analytics Market
Analytics
Speech and Voice Analytics Market
Analytics
Europe Supply Chain Analytics Market
Analytics
Canada Geospatial Imagery Analytics Market
Analytics
Spain Geospatial Analytics Market
Analytics
Geospatial Imagery Analytics Market
Analytics
Cloud-Based Business Analytics Software Market
Analytics
Data Mining Tools Market
Analytics
UAE Geospatial Analytics Market
Analytics
Content Analytics Software Market
Analytics
Global Saas-Based Business Analytics Market
Analytics
Contact Center Intelligence Market
Analytics
Big Data Analytics in Retail Market
Analytics
Text Analytics Market
Analytics
Europe Mobile Analytics Market
Analytics
Regression Analysis Tool Market