
 Big Data in Automotive Market | 2026-2036
Big Data in Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data in Automotive Market Insights
Fragmentation across fleet operators and mobility service providers is repositioning procurement power toward buyers with multi-thousand vehicle footprints. IBM leverages its Watson IoT platform to anchor enterprise-scale deployments across connected vehicle ecosystems. Microsoft competes through Azure's edge-computing layer, which sustains low-latency telemetry pipelines for autonomous driving workloads. Amazon Web Services dominates cloud storage architectures, controlling the underlying infrastructure that most automotive data lakes occupy.
Big Data in Automotive encompasses the capture, aggregation, and algorithmic processing of high-velocity sensor streams, telematics feeds, and customer interaction logs generated by vehicles and their surrounding infrastructure, typically operating across distributed cloud-edge architectures with sub-second latency requirements for safety-critical functions. The primary purpose is to enable predictive maintenance scheduling, real-time traffic optimization, and personalized in-cabin experiences while feeding training data back into machine learning models for autonomous systems. Predictive Maintenance leads product type margins due to its direct linkage with OEM warranty cost reduction, while Fleet Management represents the fastest-growing application segment as logistics operators monetize route efficiency gains. Machine Learning commands technology investment focus because neural network training on driving behavior datasets creates differentiation barriers that pure analytics tools cannot replicate.
NHTSA mandates event data recorder accessibility, while the EPA requires emissions telemetry verification, and California's CARB layers additional connected-vehicle reporting obligations that collectively shape OEM data architecture investments. The EU AI Act and GDPR impose algorithmic transparency and consent-management burdens on cross-border data flows, forcing automakers to regionalize their cloud deployments. Stakeholders must monitor whether emerging software liability frameworks will shift accountability from component suppliers to the platform owners curating vehicle data marketplaces.
Market Dynamics
Fleet operators with multi-thousand vehicle footprints are consolidating procurement power, forcing predictive analytics vendors to restructure pricing around per-vehicle economics rather than enterprise licenses. This buyer concentration is compressing margins for mid-tier platform providers while rewarding hyperscale cloud architectures.
Growth Catalysts
- NHTSA Crash-Data Mandates:Federal accessibility requirements for event data recorders compel OEMs to deploy real-time telemetry infrastructure across entire vehicle lines, creating baseline demand for edge-computing hardware.
- EPA Emissions Verification:Continuous monitoring rules require onboard diagnostics to stream verification data to centralized repositories, expanding data lake capacity requirements for powertrain engineering teams.
- German OEM Cloud-Native Integration:BMW, Mercedes-Benz, and Volkswagen are embedding analytics stacks directly into vehicle architectures, establishing technical templates that tier-two suppliers must replicate to maintain component eligibility.
Market Restraints
- GDPR Algorithmic Transparency Burdens:The EU AI Act forces automakers to document decision pathways for safety-critical machine learning models, inflating compliance costs for cross-border data flows.
- Silicon Concentration in Taiwan:Advanced driver-assistance system chips depend on concentrated foundry capacity, exposing predictive maintenance platform rollouts to single-point supply disruptions.
- Edge-to-Cloud Latency Floors:Autonomous driving workloads require sub-10-millisecond response times that 5G networks cannot yet guarantee outside dense urban corridors, limiting deployment geographies.
Strategic Opportunities
- India Fleet Digitization Gap:Commercial vehicle operators in Maharashtra and Gujarat states lack telematics penetration, creating first-mover advantages for cloud providers establishing localized data centers.
- Carbon Credit Monetization:California's CARB connected-vehicle reporting obligations enable logistics operators to convert route efficiency data into tradeable offset certificates.
- Digital Twin Convergence:Physics simulation engines fused with live sensor streams allow OEMs to validate powertrain calibrations without physical prototype fleets, compressing development cycles.
Industry Challenges
- Automotive ML Engineer Scarcity:Neural network training for driving behavior datasets requires specialists who command premiums exceeding standard software engineering compensation bands.
- Legacy CAN Bus Integration:Pre-2020 vehicle architectures lack standardized APIs, forcing retrofit hardware deployments that fragment data formats and complicate fleet-wide analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Data in Automotive Market |
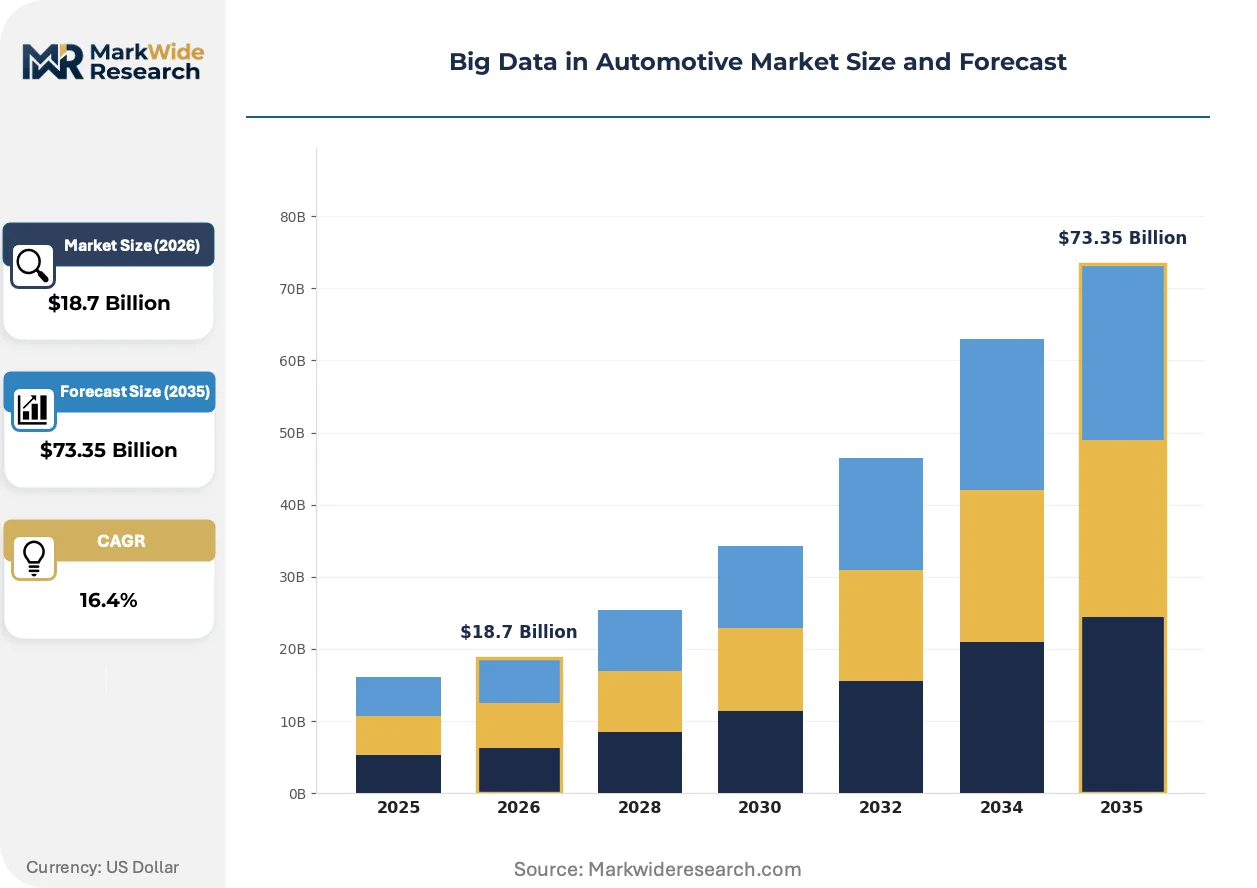
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telematics, Advanced Driver Assistance Systems, Predictive Maintenance, Fleet Management Application: Vehicle Performance Monitoring, Traffic Management, Customer Behavior Analysis, Safety Enhancement End User: OEMs, Aftermarket Providers, Fleet Operators, Insurance Companies Technology: Cloud Computing, Machine Learning, Data Analytics, IoT Solutions |
| Companies Covered | IBM, Microsoft, SAP SE, Amazon Web Services, SAS Institute, Sibros Technologies, Otonomo, Aptiv PLC, N-iX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data in Automotive Market Trends and Innovations
Automotive data architectures are pivoting from retrospective batch processing toward streaming inference at the vehicle edge, with regulatory mandates accelerating the technical transition. This shift is redefining competitive advantage around latency performance rather than storage economics.
Edge-native inference engines are overtaking centralized cloud training for real-time anomaly detection in battery thermal management systems. Tier-one suppliers are embedding these accelerators into battery management units to meet warranty cost reduction targets. The technology is overtaking traditional telematics gateways by eliminating round-trip latency that degrades predictive maintenance accuracy.
The EU AI Act's risk classification framework imposes documentation burdens on autonomous emergency braking algorithms that exceed prior self-certification norms. German regulators at KBA are interpreting these rules to require third-party audit trails for neural network updates. OEMs are responding by regionalizing model training infrastructure to isolate European driving data from other geographies.
Outcome-based service contracts are displacing per-vehicle software licenses among logistics operators with thousand-plus fleets. These agreements tie analytics platform fees to documented fuel savings and maintenance cost reductions. The model is most visible in the Rhine-Ruhr corridor, where freight operators bundle data subscriptions with vehicle procurement decisions.
Big Data in Automotive Market Segmentation
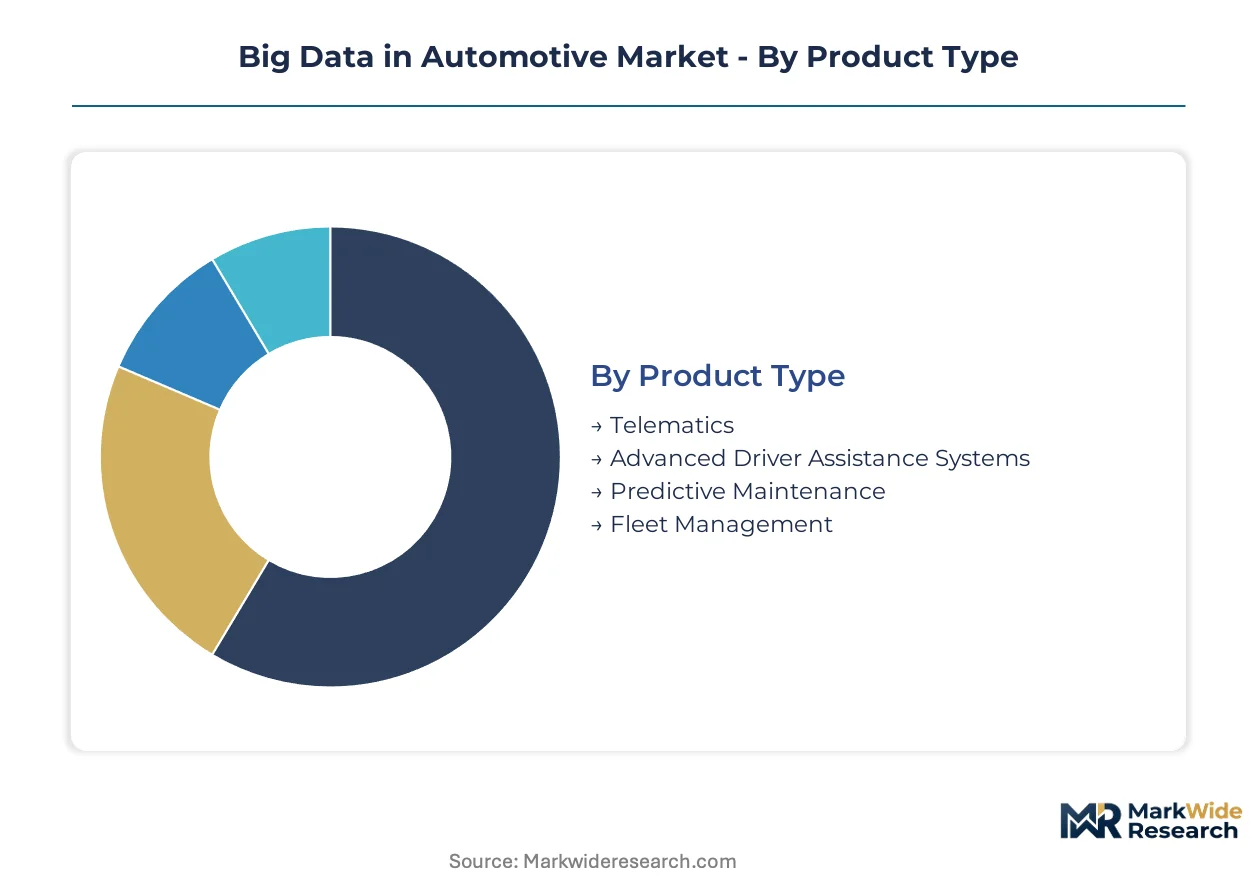
Segmentation in automotive big data reflects divergent buyer economics. OEMs prioritize warranty cost reduction while fleet operators monetize route efficiency, creating distinct procurement patterns across product categories.
Product Type:
Cost tier determines vendor selection, with premium predictive platforms commanding enterprise budgets and telematics solutions competing on per-vehicle pricing.
- Predictive Maintenance:Neural networks analyze sensor streams from powertrain components to forecast failures before warranty claims materialize. Demand concentrates among German OEMs—BMW, Mercedes-Benz, and Volkswagen—where thermal management analytics reduce battery replacement costs. Margin compression in mid-tier platforms rewards hyperscale cloud architectures.
- Fleet Management:Real-time route optimization engines process GPS, fuel consumption, and driver behavior data to minimize logistics costs. Logistics operators in the Rhine-Ruhr corridor bundle these subscriptions with vehicle procurement decisions, expanding most quickly among thousand-plus vehicle footprints.
- Telematics:Onboard diagnostic streaming satisfies NHTSA event data recorder mandates and EPA emissions verification requirements.
- Advanced Driver Assistance Systems:Edge-native inference engines process camera and lidar feeds for real-time hazard detection with sub-10-millisecond latency requirements.
Volume sits with Telematics; growth tilts toward Fleet Management.
Application:
Application selection tracks regulatory pressure intensity, with safety-critical functions drawing investment ahead of customer experience optimization.
- Safety Enhancement:Autonomous emergency braking algorithms require documented decision pathways under EU AI Act risk classifications. German regulators at KBA mandate third-party audit trails for neural network updates, forcing OEMs to regionalize European driving data.
- Traffic Management:Municipal infrastructure integration enables predictive congestion routing through vehicle-to-everything communication protocols. Deployment concentrates in dense urban corridors where 5G latency floors permit real-time coordination.
- Vehicle Performance Monitoring:Powertrain calibration validation through physics simulation engines compresses prototype fleet requirements.
- Customer Behavior Analysis:In-cabin interaction logs feed personalized infotainment recommendations while raising GDPR consent-management burdens.
Deployment maturity favors Safety Enhancement; steepest expansion trajectory belongs to Traffic Management.
End User:
Customer type dictates contract structure, with outcome-based agreements displacing per-vehicle licenses among concentrated buyers.
- Fleet Operators:Multi-thousand vehicle footprints consolidate procurement power, forcing analytics vendors to restructure pricing around documented fuel savings. Maharashtra and Gujarat commercial vehicle operators present first-mover opportunities for localized data center establishment.
- OEMs:Cloud-native analytics stack integration into vehicle architectures establishes technical templates that tier-two suppliers must replicate.
- Insurance Companies:Driving behavior datasets enable usage-based premium pricing with telematics verification.
- Aftermarket Providers:Retrofit hardware deployments address pre-2020 CAN bus architectures lacking standardized APIs.
Revenue concentration rests with OEMs; margin expansion favors Fleet Operators.
Technology:
Technology investment prioritizes differentiation barriers that pure analytics tools cannot replicate.
- Machine Learning:Neural network training on driving behavior datasets creates competitive moats through proprietary model architectures. Scarce automotive ML engineers command compensation premiums exceeding standard software engineering bands.
- Cloud Computing:Distributed architectures isolate European data flows under GDPR cross-border restrictions while sustaining centralized model development.
- IoT Solutions:Edge-to-cloud telemetry pipelines require sub-second latency guarantees for battery thermal management anomaly detection.
- Data Analytics:Batch processing platforms face displacement by streaming inference engines for real-time decision requirements.
Investment intensity clusters on Machine Learning; infrastructure scale belongs to Cloud Computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's hyperscale cloud campuses anchor North American data lake capacity for connected vehicle fleets. German automotive engineering clusters concentrate predictive analytics talent. Taiwanese semiconductor foundries supply the edge-computing silicon that enables real-time telemetry processing.
United States
Fleet operators with thousand-plus vehicle footprints consolidate procurement power across the Midwest logistics corridor. NHTSA event data recorder mandates and EPA emissions verification rules compel OEMs to deploy real-time telemetry infrastructure. Detroit's engineering ecosystem integrates cloud-native analytics stacks into next-generation powertrain architectures.
Germany
BMW, Mercedes-Benz, and Volkswagen embed analytics engines directly into vehicle electrical architectures. KBA regulators enforce third-party audit trails for neural network updates under EU AI Act risk classifications. Stuttgart and Munich host concentrated development centers for autonomous driving machine learning pipelines.
China
Domestic EV manufacturers scale edge-computing deployments for battery thermal management across the Yangtze River Delta. MIIT connected-vehicle data security regulations mandate localized cloud storage for telematics streams. Shenzhen's hardware ecosystem produces cost-optimized telematics gateways for commercial fleet retrofit programs.
India
Commercial vehicle operators in Maharashtra and Gujarat states present first-mover opportunities for localized data center establishment. The country's national automotive regulator advances telematics penetration mandates for heavy-duty fleet safety compliance. Bangalore's software engineering clusters supply automotive ML specialists to global OEM development programs.
Japan
Premium OEMs integrate predictive maintenance platforms into hybrid powertrain warranty programs. METI data governance guidelines shape cross-border cloud architecture decisions for multinational automakers. Nagoya's automotive supplier corridor concentrates edge-native inference engine development for battery management systems.
Big Data in Automotive Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized edge-computing niches. The vendor base stratifies across hyperscale cloud platforms, enterprise software incumbents, and automotive-native technology specialists. Three archetypes dominate: infrastructure-as-a-service providers controlling underlying data lake capacity, industrial software vendors with embedded OEM relationships, and fleet-focused analytics pure-plays. Competitive moves concentrate on strategic partnerships with tier-one suppliers and geographic expansion into underpenetrated commercial vehicle markets.
Within the hyperscale infrastructure tier, Amazon Web Services and Microsoft exemplify cloud-native platform dominance. IBM occupies a position bridging enterprise software heritage with automotive-specific IoT deployments. Among automotive-native specialists, Sibros Technologies and Otonomo represent the connected vehicle data marketplace archetype, while Aptiv PLC anchors the tier-one supplier integration vector. These named entities illustrate how competitive positioning fragments across data infrastructure, software layers, and vehicle-embedded systems rather than consolidating around unified platforms.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| SAP SE |
| Amazon Web Services |
| SAS Institute |
| Sibros Technologies |
| Otonomo |
| Aptiv PLC |
| N-iX |
| Others |
Pricing and Supply Chain Analysis
Fleet operators with multi-thousand vehicle footprints are consolidating procurement power and forcing predictive analytics vendors toward per-vehicle economics rather than enterprise licensing. This buyer concentration is compressing margins for mid-tier platform providers while rewarding hyperscale cloud architectures that can absorb volume-driven pricing pressure.
Pricing Analysis
Volume concentrates in telematics solutions competing on per-vehicle pricing, while margin accrues to predictive maintenance platforms commanding enterprise budgets at German OEMs. Three-tier pricing structure across premium, standard, and economy levels differentiates by data processing latency and model customization depth. Cost compression in mid-tier platforms is intensifying because fleet procurement teams benchmark cloud-native alternatives against legacy on-premise deployments. Logistics operators with thousand-plus footprints exhibit highest price sensitivity, whereas BMW, Mercedes-Benz, and Volkswagen procurement functions prioritize warranty cost reduction over unit pricing.
Supply Chain Analysis
Advanced driver-assistance system chip supply rests on Taiwanese foundry capacity, South Korean memory producers, and Japanese sensor specialists. Edge-computing hardware draws from silicon wafers, automotive-grade packaging substrates, and thermal management components. Single-source vulnerability in Taiwanese foundry concentration exposes predictive maintenance platform rollouts to geopolitical disruption. Distribution runs through tier-one supplier integration into vehicle electrical architectures, with direct OEM relationships displacing aftermarket channels for new vehicle programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive big data is becoming a vertical-integration race, with platform owners pursuing captive control over edge-computing silicon and cloud infrastructure to defend margin positions against hyperscale entrants.
For Market Incumbents: Deepen embedded software partnerships with BMW, Mercedes-Benz, and Volkswagen to lock in architecture standards before tier-two suppliers replicate cloud-native stacks. Acquire specialized automotive ML engineering teams to offset talent scarcity premiums. Defend against Microsoft Azure and Amazon Web Services by controlling vehicle-side data generation points through battery management unit integration. For New Entrants and Emerging Players: Tier-one battery suppliers represent the most accessible channel for edge-native inference engine deployment, as thermal management analytics create immediate warranty cost reduction value. Target Maharashtra and Gujarat commercial vehicle operators where telematics penetration remains below regulatory mandates. Pursue outcome-based service contracts tied to documented fuel savings rather than per-vehicle software licenses. For Investors and Strategic Acquirers: Distressed-cycle entries favor automotive-native data marketplace specialists with established OEM data-sharing agreements and regionalized GDPR-compliant infrastructure. Five-to-ten year viability hinges on platform owners capturing recurring revenue from autonomous driving training data pipelines. Watch for NHTSA software liability framework shifts that would reallocate accountability from component suppliers to data platform curators.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Inference Engine Deployment | Tier-one suppliers embedding accelerators into battery management units eliminate round-trip latency degrading predictive maintenance accuracy. |
| Regionalized Model Training Infrastructure | OEMs isolate European driving data under KBA third-party audit trail requirements mandated by EU AI Act risk classifications. |
| Outcome-Based Service Contract Expansion | Rhine-Ruhr freight operators bundle analytics subscriptions with vehicle procurement decisions, displacing per-vehicle software licenses. |
| Localized Data Center Establishment | Cloud providers capturing Maharashtra and Gujarat commercial vehicle operators gain first-mover advantage ahead of national telematics mandates. |
| Digital Twin Physics Simulation Convergence | OEMs validate powertrain calibrations without physical prototype fleets, compressing development cycles through live sensor stream fusion. |
Research Methodology
Document review covered SEC filings from hyperscale cloud providers, EPA emissions telemetry rulemaking records, and EU AI Act implementation guidance, complemented by interviews with OEM platform engineers, tier-one supplier procurement leads, fleet operations directors, and automotive ML engineering specialists. Secondary validation drew from NHTSA crash-data reporting mandates, KBA regulatory interpretations, vehicle production databases, and IHS Markit registration data. Bottom-up segment sizing and top-down macroeconomic cross-checks established triangulation boundaries.
Historical revenue trajectories were cross-referenced against panel input from industry participants to construct projection frameworks across the analysis window. Segmentation modeling incorporated product type, application, end user, and technology dimensions alongside vehicle class and propulsion architecture variables. CAGRs were derived from fitted growth curves applied to disclosed hyperscaler automotive vertical revenues and OEM R&D expenditure patterns. Forecast inputs included fleet digitization penetration rates, edge-computing hardware cost curves, and regulatory compliance timeline assumptions.
Several conditions sit outside the modeled scope, including potential Taiwan semiconductor supply disruptions, unilateral software liability framework revisions, and 5G network latency improvements outside dense urban corridors. Forecasts reflect documented assumptions about regulatory enforcement intensity and OEM cloud migration timelines. A small set of named triggers warrants ongoing watch: NHTSA event data recorder accessibility rule expansion, EU AI Act third-party audit cost inflation, and German OEM architecture standardization decisions affecting tier-two supplier eligibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Cloud-Based Predictive Analytics Platform Market
Analytics
Workforce Analytics Market
Analytics
Data Mining Tools Market
Analytics
Practice Analytics Market
Analytics
Investigative Analytics Market
Analytics
Europe Data Monetization Market
Analytics
Business Analytics Market
Analytics
Behavior Analytics Market
Analytics
Global Network Analytics Market
Analytics
Geospatial Imagery Analytics Market
Analytics
Geospatial Analytics Market
Analytics
Global High Performance Data Analytics (HPDA) Market
Analytics
Service Analytics Market
Analytics
Self Service Analytics Market
Analytics
Global Data Prep Market
Analytics
Business Intelligence (BI) Market