
 Europe Emotion Analytics Market | 2026-2036
Europe Emotion Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Emotion Analytics Market Insights
Enterprise buyers in customer experience management are rotating toward real-time emotion detection platforms, displacing traditional survey-based sentiment tools. Realeyes leverages computer vision pipelines to anchor its position in video-based attention measurement. Tobii sustains technology leadership through eye-tracking integration with facial coding systems. SAP AG competes by embedding emotion analytics into its enterprise cloud suite, extending reach to existing ERP clients.
Emotion analytics encompasses software systems that classify, quantify, and interpret human affective states through biometric signals, linguistic patterns, and behavioral markers, typically processing facial micro-expressions, vocal prosody, or textual sentiment at latencies under 300 milliseconds for real-time feedback loops. The technology serves commercial purposes spanning advertising optimization, clinical mental health screening, and adaptive learning environments. Machine learning architectures dominate deployment pipelines due to their capacity for continuous model retraining on proprietary affect datasets. Natural language processing occupies the fastest-expanding margin pool as enterprises prioritize text-based channels including chatbots and social listening. Cloud deployment leads in adoption velocity among mid-market buyers seeking API-first integration, while on-premises configurations retain preference in healthcare and defense contexts where GDPR Article 9 special-category data restrictions apply.
The EU AI Act imposes conformity assessment obligations on high-risk biometric identification systems, directly constraining facial recognition deployments in public spaces and employment settings. EMA guidelines and national health regulators in France, Germany, and Italy shape clinical validation requirements for emotion analytics deployed in therapeutic or diagnostic capacities. GDPR enforcement by CNIL, ICO, and other national data protection authorities creates jurisdictional variation in lawful processing grounds for affective data. Stakeholders must monitor the evolving interplay between the AI Act's risk classification framework and sector-specific health data regulations to determine viable go-to-market pathways.
Market Dynamics
The EU AI Act's risk classification framework for biometric systems is compressing deployment timelines and forcing vendors to rearchitect facial coding pipelines before 2025 enforcement deadlines. Enterprise buyers now demand pre-certified emotion analytics modules that embed conformity assessments upstream, shifting procurement criteria toward compliance-ready platforms rather than experimental pilots.
Growth Catalysts
- GDPR Article 9 special-category processing:Healthcare providers in Germany and France are securing lawful grounds for affective data processing in clinical mental health applications, opening regulated deployment pathways for diagnostic emotion analytics.
- Real-time customer experience platforms:Retail banking and telecommunications sectors across the United Kingdom are replacing post-interaction surveys with live emotion detection during video consultations.
- Cloud API-first architectures:Mid-market enterprises in the Netherlands and Spain are accelerating adoption through subscription-based emotion analytics services that bypass capital-intensive infrastructure builds.
Market Restraints
- GPU and specialized inference hardware costs:Edge deployment of computer vision models for real-time facial micro-expression analysis requires NVIDIA Jetson or equivalent chipsets, creating input cost volatility for on-premises configurations.
- Biometric data processor concentration:Cloud infrastructure for affective computing concentrates among three hyperscale providers, creating supply concentration risk for European buyers seeking data residency guarantees.
- Cross-border regulatory friction:Divergent national interpretations of GDPR lawful processing grounds between CNIL in France and ICO in the United Kingdom create compliance complexity for multi-country deployments.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Finland exhibit low emotion analytics penetration in public sector customer service despite high digital maturity, presenting first-mover advantages for localized platform vendors.
- Convergence of voice biometrics and prosodic analysis:Contact center operators are integrating speech emotion recognition with speaker identification, creating unified authentication and sentiment monitoring stacks.
- EU Green Deal procurement incentives:Public sector tenders in Italy and Poland are beginning to weight vendor ESG disclosures, favoring emotion analytics providers with documented sustainable AI development practices.
Industry Challenges
- Affective computing talent scarcity:Machine learning engineers with specialized expertise in multimodal emotion fusion remain concentrated in London, Berlin, and Paris, constraining R&D scaling for vendors outside these clusters.
- Legacy ERP integration complexity:Enterprise buyers require emotion analytics APIs to interface with SAP S/4HANA and Oracle Cloud HCM instances, demanding vendor investment in pre-built connectors and certification programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Emotion Analytics Market |
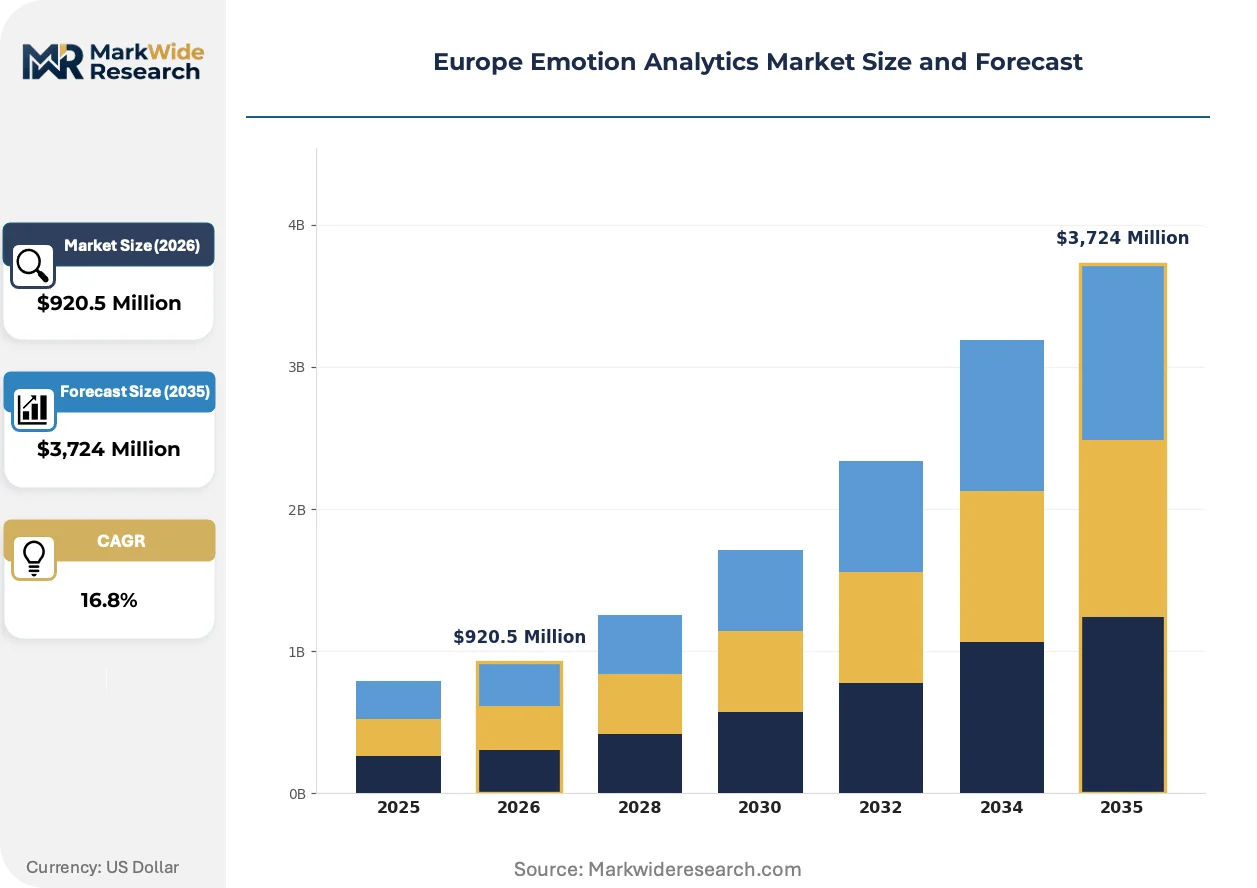
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $3,724 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Facial Recognition, Speech Recognition End User: Retail, Healthcare, Entertainment, Education Deployment: Cloud, On-Premises, Hybrid, Embedded Application: Market Research, Customer Experience Management, Advertising, Behavioral Analytics |
| Companies Covered | Realeyes, TextRazor Ltd., Adoreboard, Tobii, Sentiance, Aylien, SAP AG, iMotions A/S, nViso SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Emotion Analytics Market Trends and Innovations
Computer vision pipelines for facial emotion recognition are fragmenting into specialized architectures optimized for either high-accuracy laboratory conditions or noisy real-world deployment environments. This technical divergence is reshaping vendor R&D priorities and buyer evaluation frameworks across European enterprise segments.
Multimodal emotion fusion technology is bifurcating into two distinct product categories: research-grade systems combining facial coding, eye-tracking, and physiological sensors for clinical validation; and lightweight inference engines processing single-modality inputs for scalable customer experience deployments. Pharmaceutical sponsors in Switzerland and Germany are adopting the former for therapeutic efficacy studies, while British retail banks are deploying the latter for real-time agent coaching. The structural consequence is compressing price points for basic facial coding while expanding margin pools for validated multimodal platforms.
The EU AI Act's conformity assessment obligations for high-risk biometric systems are forcing vendors to redesign training data governance and model documentation practices before 2025 enforcement. Industrial consequence includes mandatory human oversight interfaces and algorithmic impact assessments for employment-facing emotion analytics. French and German HR technology providers are most affected, responding by establishing ethics review boards and external audit partnerships to secure CE marking pathways.
Enterprise procurement of emotion analytics is consolidating around outcome-based performance contracts rather than per-seat licensing models. British telecommunications operators and Italian insurance underwriters are piloting agreements tying vendor payments to measurable improvements in customer satisfaction scores or agent productivity metrics. This shift is most visible in the United Kingdom, where Ofcom's consumer duty requirements are amplifying pressure for demonstrable customer experience outcomes.
Europe Emotion Analytics Market Segmentation
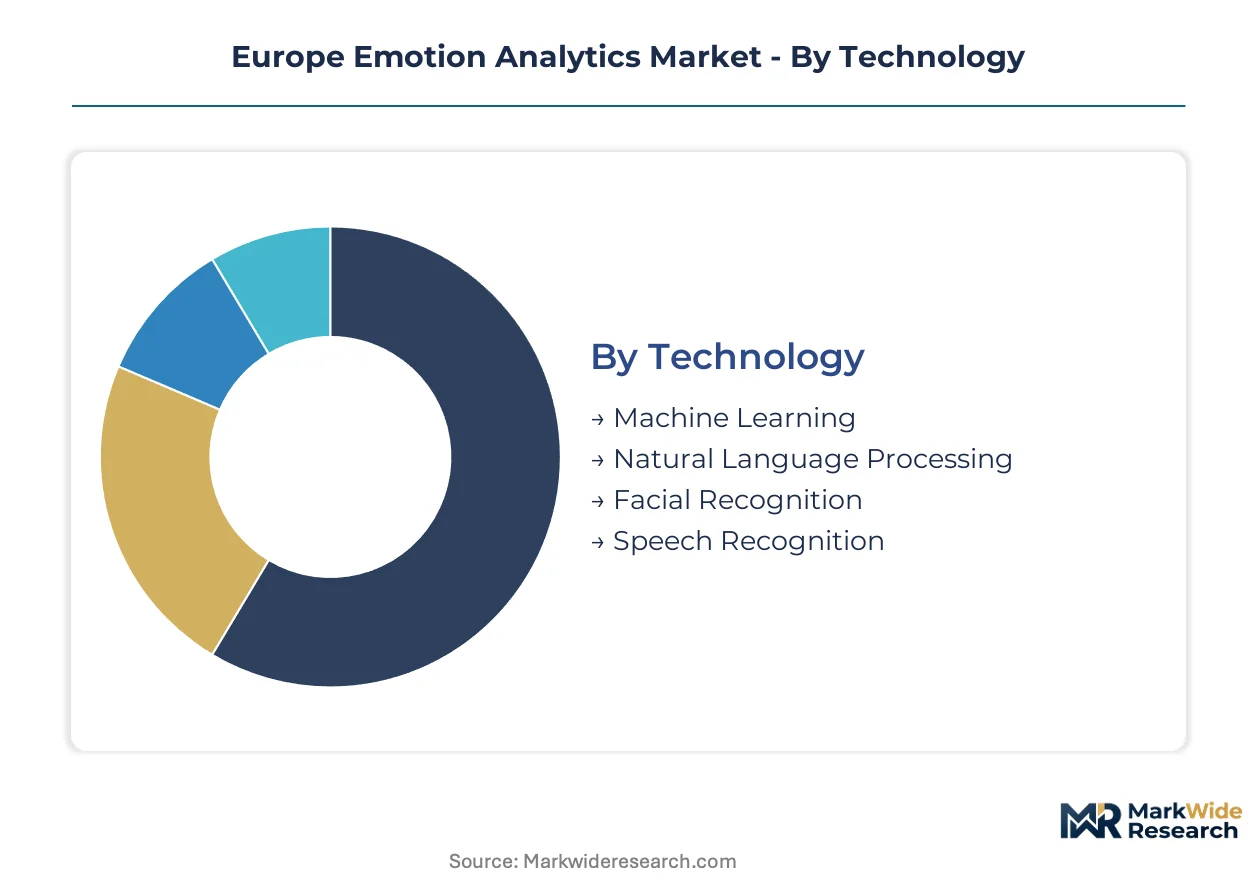
Segmentation in the Europe Emotion Analytics Market reveals how compliance architecture and deployment economics reshape vendor priorities. Buyers across Germany, France, and the United Kingdom are selecting technology stacks based on GDPR Article 9 processing requirements and real-time latency demands rather than feature breadth alone.
Technology:
Margin pools concentrate in multimodal fusion architectures that combine computer vision with linguistic analysis, commanding premium pricing from enterprise buyers seeking validated accuracy.
- Machine Learning:Deep learning architectures process proprietary affect datasets for continuous model retraining, with German automotive and pharmaceutical sponsors driving demand for laboratory-grade validation pipelines.
- Natural Language Processing:Text-based sentiment engines analyze chatbot transcripts and social listening feeds at sub-300-millisecond latency, expanding fastest among British retail banks and telecommunications operators replacing post-interaction surveys.
- Facial Recognition:Micro-expression classification systems face EU AI Act conformity assessment obligations for high-risk biometric deployments.
- Speech Recognition:Prosodic analysis modules extract emotional valence from vocal pitch and rhythm variations.
Machine Learning holds installed capacity. Natural Language Processing is rotating up the share rankings.
End User:
Healthcare providers in France and Germany are securing lawful grounds for affective data processing ahead of other verticals, creating regulated deployment pathways that justify higher platform investments.
- Healthcare:Clinical mental health screening and therapeutic efficacy studies require multimodal platforms combining facial coding with physiological sensors, with Swiss pharmaceutical sponsors and German university hospitals leading procurement.
- Retail:Real-time customer experience platforms in British department stores and Dutch e-commerce operations deploy lightweight inference engines for agent coaching and sentiment monitoring.
- Entertainment:Content optimization tools measure audience attention and emotional engagement during test screenings.
- Education:Adaptive learning environments adjust instructional pacing based on student frustration or confusion signals.
Healthcare commands the steepest expansion trajectory. Retail maintains volume leadership across the region.
Deployment:
Cloud configurations dominate adoption velocity among mid-market buyers, while on-premises and embedded systems retain preference where data residency guarantees outweigh cost considerations.
- Cloud:API-first subscription services enable rapid integration without capital-intensive infrastructure, accelerating fastest among Spanish and Dutch enterprises seeking scalable emotion analytics.
- On-Premises:Localized processing satisfies GDPR Article 9 special-category restrictions and EMA clinical validation requirements, with German healthcare providers and French defense contractors requiring full data sovereignty.
- Hybrid:Split architectures process sensitive biometric data locally while transmitting anonymized insights to cloud analytics layers.
- Embedded:Edge-optimized models run on NVIDIA Jetson chipsets for real-time inference without network dependency.
On-Premises holds installed capacity. Cloud is rotating up the share rankings.
Application:
Customer Experience Management concentrates enterprise spending as British telecommunications operators and Italian insurance underwriters pilot outcome-based performance contracts tied to measurable satisfaction improvements.
- Customer Experience Management:Live emotion detection during video consultations replaces traditional survey tools, with United Kingdom retail banking and telecommunications sectors leading displacement of post-interaction feedback systems.
- Market Research:Attention measurement and emotional response tracking optimize advertising creative and product positioning decisions.
- Advertising:Creative testing platforms score emotional resonance before campaign deployment.
- Behavioral Analytics:Pattern recognition identifies at-risk customers or employees through affective state monitoring.
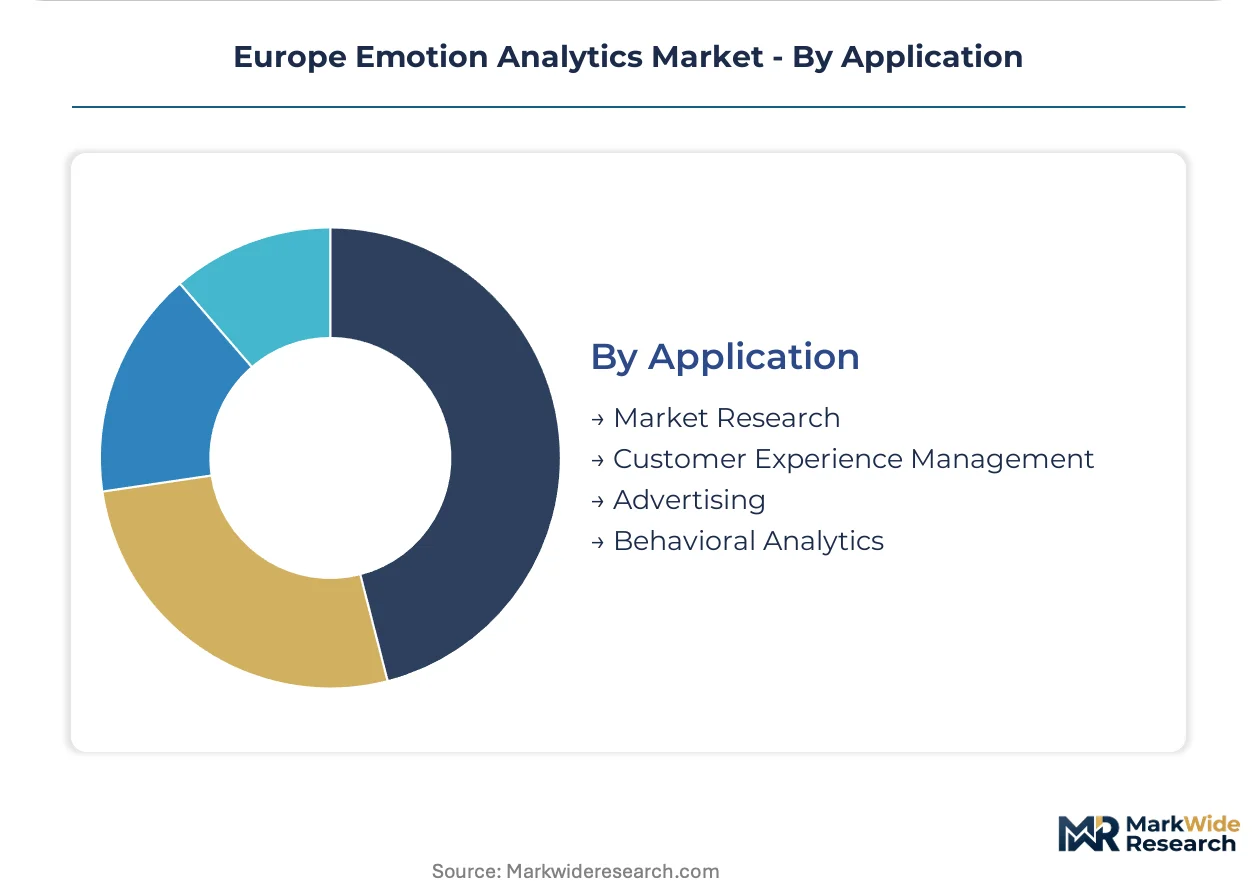
Customer Experience Management holds installed capacity. Market Research is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German emotion analytics vendors export multimodal platforms to Swiss pharmaceutical sponsors and British retail banking clients, establishing a north-south trade corridor across the continent.
Germany
Automotive OEMs in Stuttgart and Munich deploy facial coding systems for driver monitoring research, while Charité Berlin and Heidelberg University Hospital secure GDPR Article 9 lawful processing grounds for clinical mental health applications. The KBA and BfArM shape validation requirements for biometric systems in therapeutic settings. Bavaria's Munich-Franconia corridor concentrates R&D talent for laboratory-grade emotion fusion platforms.
United Kingdom
Retail banking and telecommunications operators in London and Manchester displace post-interaction surveys with live emotion detection during video consultations. The ICO enforces divergent lawful processing interpretations compared to continental regulators, creating compliance friction for multi-country deployments. The London-Reading tech corridor anchors demand for cloud API-first architectures among mid-market enterprises.
France
CNIL's strict biometric data enforcement pushes healthcare providers toward on-premises configurations for affective computing in Paris and Lyon hospital systems. ANSM guidelines shape clinical validation pathways for emotion analytics in therapeutic contexts. The Paris-Saclay research cluster concentrates computer vision talent for multimodal fusion development.
Switzerland
Pharmaceutical sponsors in Basel and Geneva adopt research-grade emotion platforms for therapeutic efficacy studies, leveraging Swissmedic's structured clinical validation framework. Roche and Novartis suppliers drive demand for validated multimodal systems combining facial coding with physiological sensors. The Basel-Zurich corridor anchors premium procurement for laboratory-grade deployments.
Netherlands
Amsterdam and Rotterdam-based enterprises accelerate adoption through subscription-based emotion analytics services, bypassing capital-intensive infrastructure builds. The Dutch Data Protection Authority enforces GDPR Article 9 restrictions with moderate stringency relative to CNIL. The Randstad metropolitan cluster concentrates mid-market demand for scalable customer experience platforms.
Europe Emotion Analytics Market Competitive Landscape
Player mix skews toward specialized computer vision vendors and enterprise software incumbents with embedded analytics capabilities. The vendor base separates into three functional tiers: pure-play biometric specialists, ERP-integrated platform providers, and research-grade multimodal system developers. Consolidation pressure is accelerating as enterprise buyers demand pre-certified modules with embedded conformity assessments. Strategic moves center on ethics review board establishment for CE marking pathways and API-first architecture development for mid-market penetration.
Within the pure-play biometric tier, Realeyes and Tobii occupy positions as video-based attention measurement and eye-tracking integration specialists respectively. SAP AG anchors the enterprise software vector by embedding emotion analytics into cloud suite offerings for existing ERP clients. Sentiance and iMotions A/S exemplify the research-grade multimodal segment, serving pharmaceutical sponsors and university hospitals requiring validated clinical pipelines. These three archetypes—computer vision specialists, enterprise platform incumbents, and research-system developers—collectively shape procurement criteria across European buyer segments.
| Leading Market Players |
|---|
| Realeyes |
| TextRazor Ltd. |
| Adoreboard |
| Tobii |
| Sentiance |
| Aylien |
| SAP AG |
| iMotions A/S |
| nViso SA |
| Others |
Pricing and Supply Chain Analysis
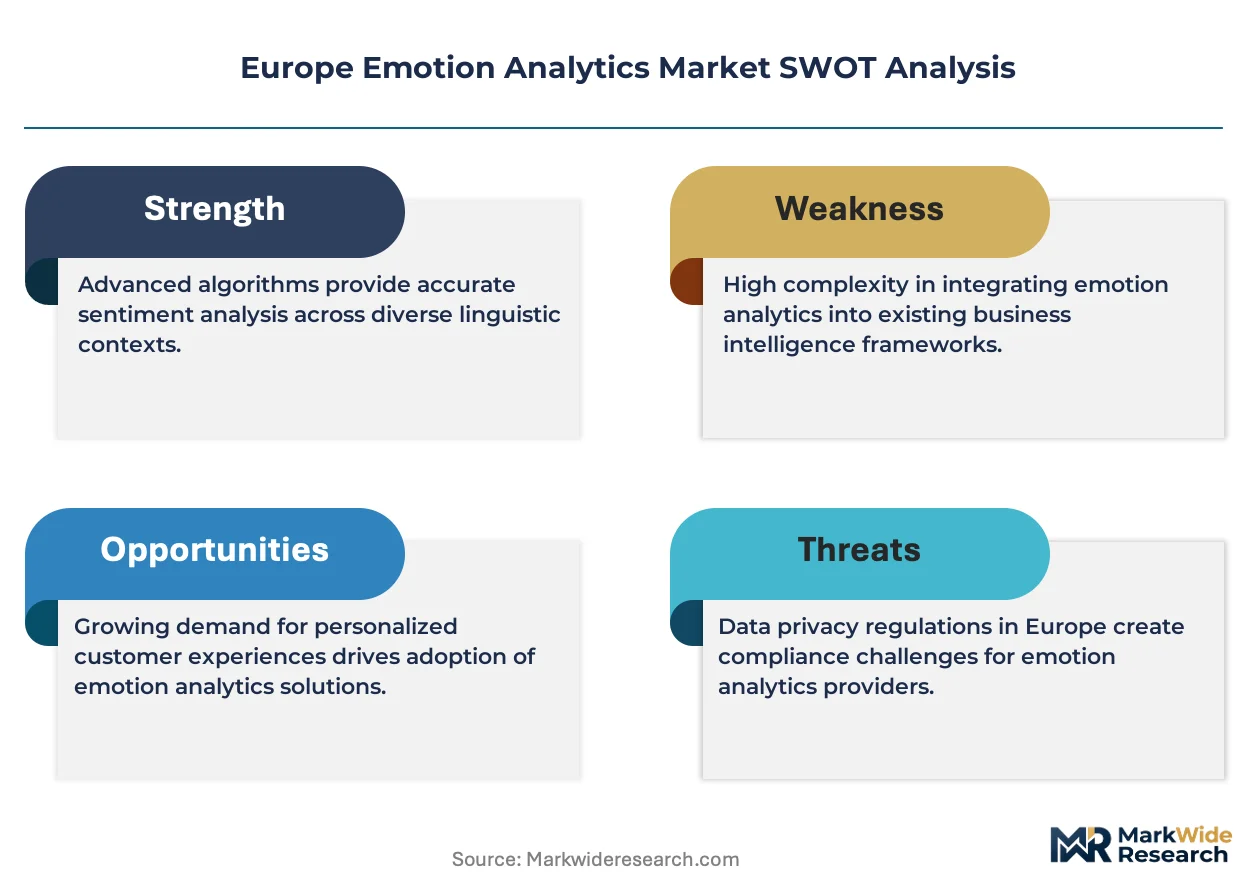
CE marking pathways under the EU AI Act gate both vendor qualification and price differentiation simultaneously, compressing margins for uncertified facial coding modules while expanding premium capture for conformity-assessed multimodal platforms. German healthcare providers and British retail banks now weight procurement decisions toward pre-certified emotion analytics stacks that embed compliance costs upstream.
Pricing Analysis
Next-generation multimodal fusion platforms command substantial premiums over legacy single-modality facial coding systems and experimental pilot-grade inference engines. Subscription-based SaaS tiers dominate cloud deployments among Dutch and Spanish mid-market buyers, while on-premises configurations in French hospital systems price according to GDPR Article 9 compliance depth and clinical validation documentation. Cost compression in basic facial coding is intensifying because GPU inference hardware costs fluctuate with NVIDIA Jetson chipset availability, squeezing margins for edge-optimized vendors. Mid-market enterprises exhibit highest price sensitivity, whereas Swiss pharmaceutical sponsors demonstrate lowest sensitivity due to therapeutic efficacy study requirements.
Supply Chain Analysis
Inventory lead times for specialized inference hardware stretch procurement cycles for on-premises emotion analytics deployments, particularly affecting German automotive OEMs and French defense contractors requiring localized processing. Cloud infrastructure concentrates among hyperscale providers in Ireland, Germany, and the Netherlands, creating data residency guarantees for European buyers. NVIDIA Jetson chipsets, high-resolution optical sensors, and proprietary affect datasets constitute critical input dependencies. Single-source vulnerability in GPU supply chains poses structural risk for edge-deployment vendors. Distribution runs through direct enterprise sales teams for research-grade platforms and API marketplaces for scalable customer experience services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized machine learning engineers capable of multimodal emotion fusion remain concentrated in London, Berlin, and Paris, constraining R&D scaling for vendors outside these talent clusters and amplifying acquisition premiums for teams with validated clinical pipelines.
For Market Incumbents: Consolidate market position by acquiring certified multimodal platform specialists before EU AI Act enforcement deadlines compress available targets, and deepen backward integration into proprietary affect dataset collection to reduce dependency on third-party training data licensing. Emerging cloud-native entrants threaten mid-market share through API-first pricing, making channel control through pre-built SAP S/4HANA and Oracle Cloud HCM connectors a critical defensive lever. For New Entrants and Emerging Players: Differentiate on regulatory pre-certification by securing CE marking pathways for high-risk biometric deployments ahead of incumbent rearchitecture timelines, targeting Swedish and Finnish public sector customer service where emotion analytics penetration remains low despite high digital maturity. White-space opportunities concentrate in voice biometrics-prosodic analysis convergence for contact center operators, with outcome-based performance contracts offering the most penetrable go-to-market angle in British telecommunications and Italian insurance verticals. For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape toward conformity-assessed assets with documented ethics review boards and external audit partnerships. Long-term viability over the next decade hinges on regulatory moat depth rather than feature breadth alone. Acquisition targets should display research-grade multimodal validation pipelines serving Swiss pharmaceutical sponsors or German university hospitals. The signal to watch is CNIL enforcement intensity against non-compliant facial recognition deployments, which would accelerate distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Establishment | Secures lawful deployment in French and German healthcare systems under EU AI Act high-risk biometric classifications. |
| Ethics Review Board Formation | Demonstrates algorithmic accountability to EMA and ANSM for therapeutic emotion analytics validation. |
| API-First Architecture Development | Captures Dutch and Spanish mid-market demand through scalable subscription services bypassing infrastructure builds. |
| Backward Integration into Affect Datasets | Reduces training data licensing costs and accelerates model retraining cycles for proprietary emotion classification pipelines. |
| Pre-Built ERP Connector Certification | Extends platform reach to existing SAP AG and Oracle enterprise clients through seamless HCM integration. |
Research Methodology
A spread of perspectives from emotion analytics platform engineers, GDPR compliance officers at German healthcare providers, British retail banking procurement leads, and Swiss pharmaceutical clinical operations directors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with these stakeholders alongside secondary validation through EU AI Act implementation guidance, EMA digital health policy documents, CNIL biometric enforcement decisions, and hyperscaler cloud infrastructure capex disclosures. Bottom-up triangulation across vendor revenue estimates and top-down cross-checks against enterprise software spending patterns anchored the market sizing framework.
Segmentation dimensions modeled span technology type, end-user vertical, deployment architecture, and application use case across the analysis window. Deployment splits between cloud API-first services and on-premises GDPR-compliant configurations received particular analytical weight given jurisdictional variation in lawful processing grounds. CAGRs were derived from regression analysis of historical adoption curves in customer experience management and healthcare diagnostic applications, with inputs including GPU hardware cost trajectories and regulatory enforcement timeline probabilities.
Material uncertainties — divergent national interpretations of GDPR Article 9 between CNIL and ICO, EU AI Act delegated act finalization, and NVIDIA chipset supply volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions about compliance cost absorption and enterprise procurement cycle lengths. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Datacenter Analytics Market
Analytics
Document Analytics Market
Analytics
Human Resource Analytics Market
Analytics
Big Data Analytics in Automotive Market
Analytics
Descriptive Analytics (Descriptive Statistics) Market
Analytics
AI Performance Marketing Market
Analytics
Extract, Transform, Load (ETL) Market
Analytics
Global High Performance Data Analytics (HPDA) Market
Analytics
France Contact Center Analytics Market
Analytics
Investigative Analytics Market
Analytics
IoT Analytics Market
Analytics
Regression Analysis Tool Market
Analytics
Capacity Management Analytics Market
Analytics
Workforce Analytics Market
Analytics
Global Subscription Analytics Software Market
Analytics
Israel ICT Market