
 Attribution Software Market | 2026-2036
Attribution Software Market Size, Share, and Industry Trends Forecast 2026-2036
Attribution Software Market Outlook
E-commerce's share of attribution software procurement is hardening as retailers abandon last-click models for multi-touch measurement across fragmented customer journeys. Google LLC leverages its advertising ecosystem dominance to embed attribution tools within existing media-buying workflows. Salesforce, Inc. anchors enterprise demand through native CRM-to-campaign linkage that reduces data fragmentation for B2B marketers. Adobe competes on creative-cloud integration, allowing creative teams to trace content performance through to revenue outcomes.
Attribution software assigns credit to marketing touchpoints along a conversion path using algorithmic models, rule-based frameworks, or probabilistic methods that process impression logs, clickstreams, and transaction records across digital and offline channels. Multi-touch attribution models now command the deepest enterprise engagements as CMOs reject single-touch simplifications that misallocate media spend across complex buyer journeys. Cloud-based deployment via SaaS delivery dominates new implementations, though hybrid architectures persist among financial services firms with strict data residency requirements.
The EU AI Act and GDPR constrain how European vendors train algorithmic attribution models on personal data, while the US lacks federal privacy legislation but faces FTC scrutiny of deceptive measurement claims. ISO standards for marketing measurement quality are gaining traction among procurement departments evaluating vendor proposals. Stakeholders must decide whether to build in-house attribution stacks or accept platform dependency as walled gardens tighten data access policies.
Market Dynamics
Multi-touch attribution is unifying measurement across walled gardens as marketers reject fragmented single-channel metrics that misallocate spend across complex customer journeys. Platform consolidation and privacy regulations are forcing vendors to rebuild identity graphs around first-party data and probabilistic modeling.
Growth Catalysts
- GDPR and EU AI Act:European compliance mandates are accelerating investment in privacy-preserving attribution architectures that process consumer journey data without personal identifiers.
- E-commerce platforms:Online retailers demand precise cross-channel measurement as customer touchpoints fragment across mobile apps, social commerce, and physical stores.
- Algorithmic modeling:Machine learning-based attribution is displacing rule-based frameworks by weighting touchpoints dynamically based on actual conversion patterns.
Market Restraints
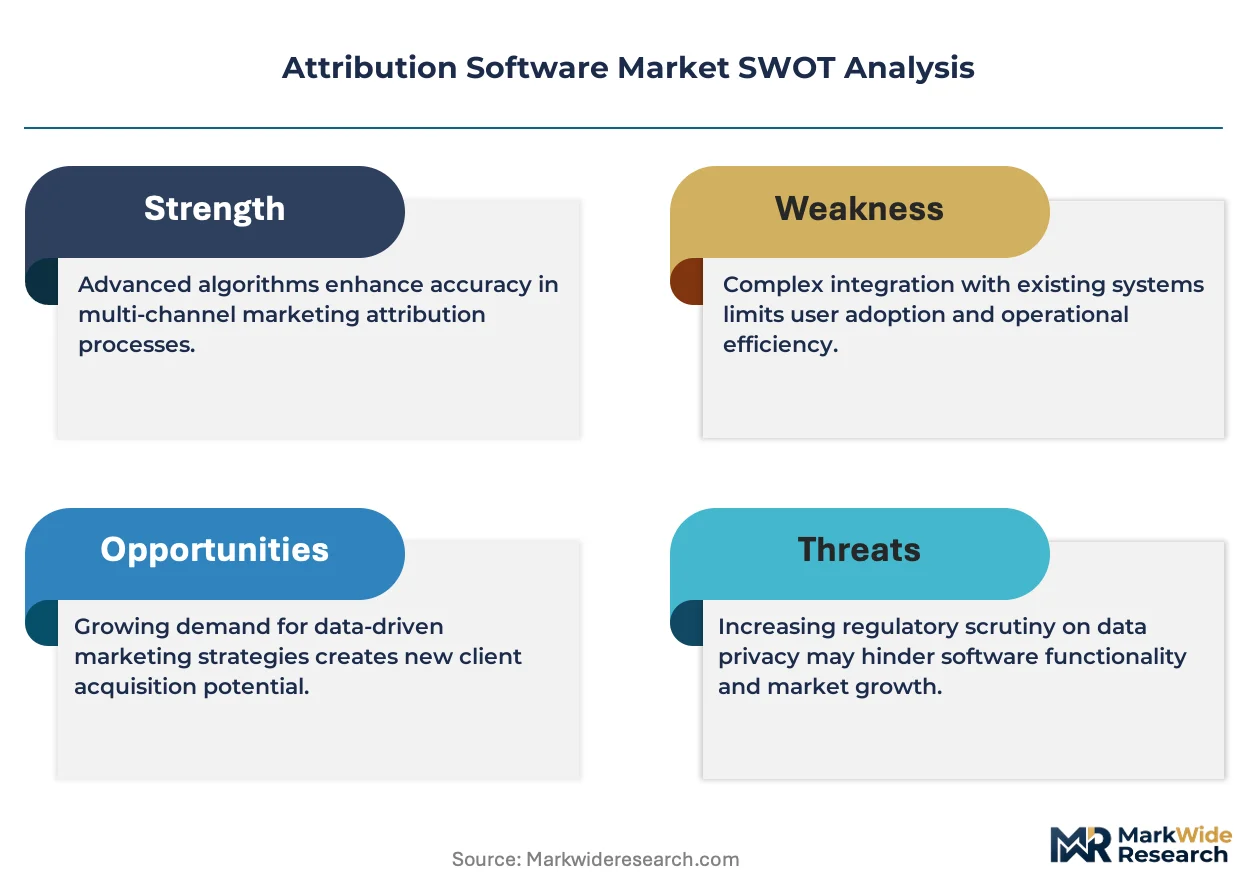
- Data residency requirements:Financial services firms in Germany and Switzerland demand hybrid cloud deployments that increase infrastructure costs versus pure SaaS delivery.
- Platform dependency:Google's advertising ecosystem dominance creates concentration risk as the company tightens data access policies for third-party measurement vendors.
- Signal loss from cookie deprecation:Browser privacy changes are degrading clickstream quality, forcing attribution models to rely on smaller, noisier training datasets.
Strategic Opportunities
- CTV and streaming audio:Connected television and podcast advertising lack mature attribution, creating white space for vendors that unify digital and linear measurement.
- B2B account-based marketing:Long sales cycles with multiple stakeholders require attribution models that map influence across buying committees rather than individual consumers.
- ISO standards for marketing measurement:Procurement departments are mandating certified quality frameworks, favoring vendors with audited methodologies.
Industry Challenges
- Data engineering talent scarcity:Building probabilistic attribution models requires scarce expertise in Bayesian statistics and distributed systems architecture.
- Legacy CRM integration:Enterprise marketers struggle to connect modern attribution platforms to decades-old customer databases with inconsistent schema.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Attribution Software Market |
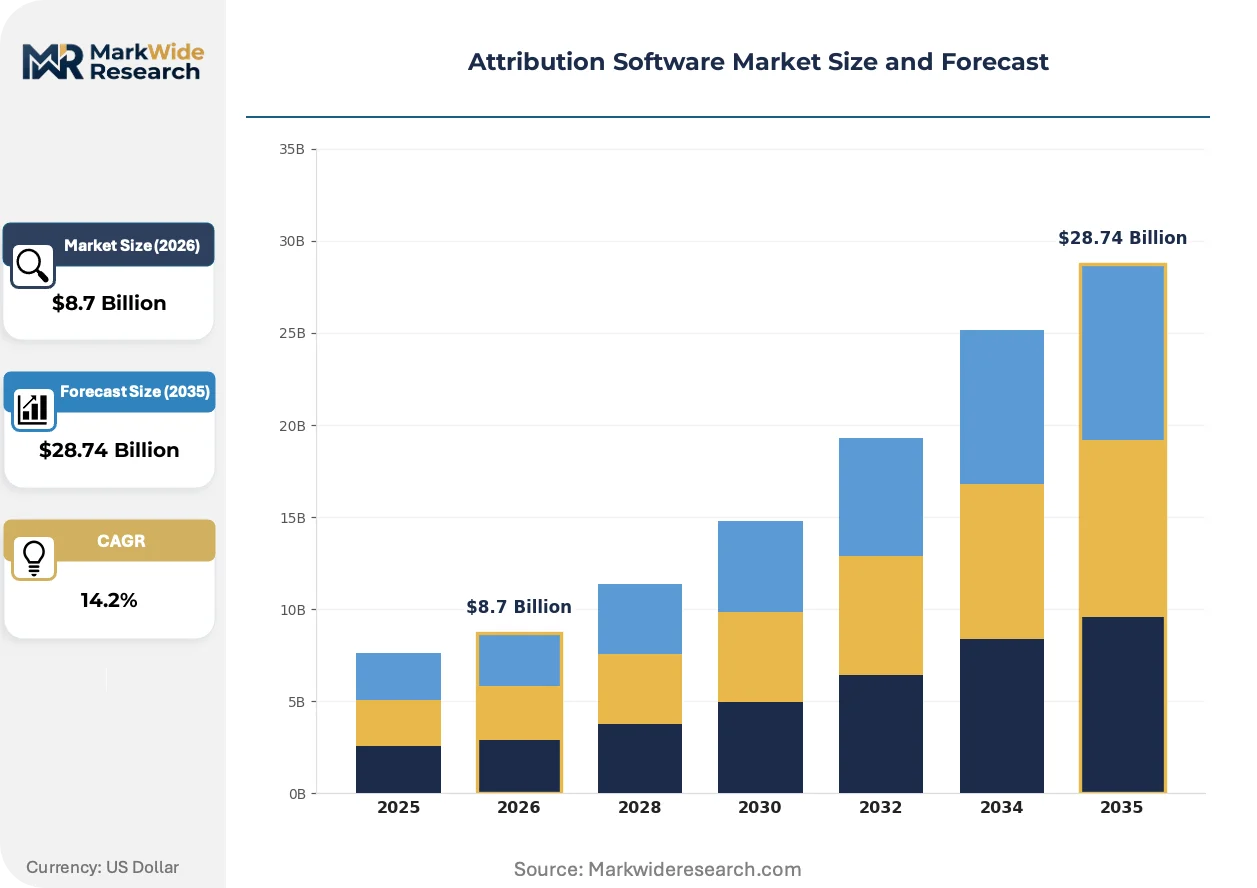
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Touch, Multi-Touch, Cross-Channel, Marketing Mix Models Deployment: Cloud-Based, On-Premise, Hybrid, SaaS End User: Retail, E-Commerce, Hospitality, Media Integration Level: API Integration, Data Warehouse, CRM, Analytics Tools |
| Companies Covered | Adobe, Google LLC, Salesforce, Inc., HubSpot, Inc., IBM Corporation, Rockerbox, Inc., Northbeam, Dreamdata, Ruler Analytics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Attribution Software Market Strategic Shifts
Attribution technology is pivoting from retrospective reporting to predictive optimization as marketers demand real-time budget reallocation. Vendors are racing to embed machine learning directly into media-buying workflows rather than delivering static post-campaign analysis.
Probabilistic identity resolution is unifying fragmented consumer profiles across devices and channels without third-party cookies. Retailers with large authenticated user bases are adopting these techniques fastest. This capability is compressing the advantage of walled gardens by enabling comparable cross-platform measurement for independent brands.
The EU AI Act's risk classification system is reshaping how vendors train algorithmic attribution models on European consumer data. High-risk systems must maintain audit trails and human oversight, increasing compliance costs. Attribution vendors serving European e-commerce platforms are responding by segmenting model training pipelines to isolate EU data flows.
Enterprise procurement teams are consolidating measurement vendors to reduce contract complexity and improve data interoperability. Marketing technology stacks that previously maintained separate tools for each channel are collapsing toward unified platforms. This concentration is most visible among US retailers with mature technology procurement functions and multi-hundred-million-dollar media budgets.
Attribution Software Market Segmentation
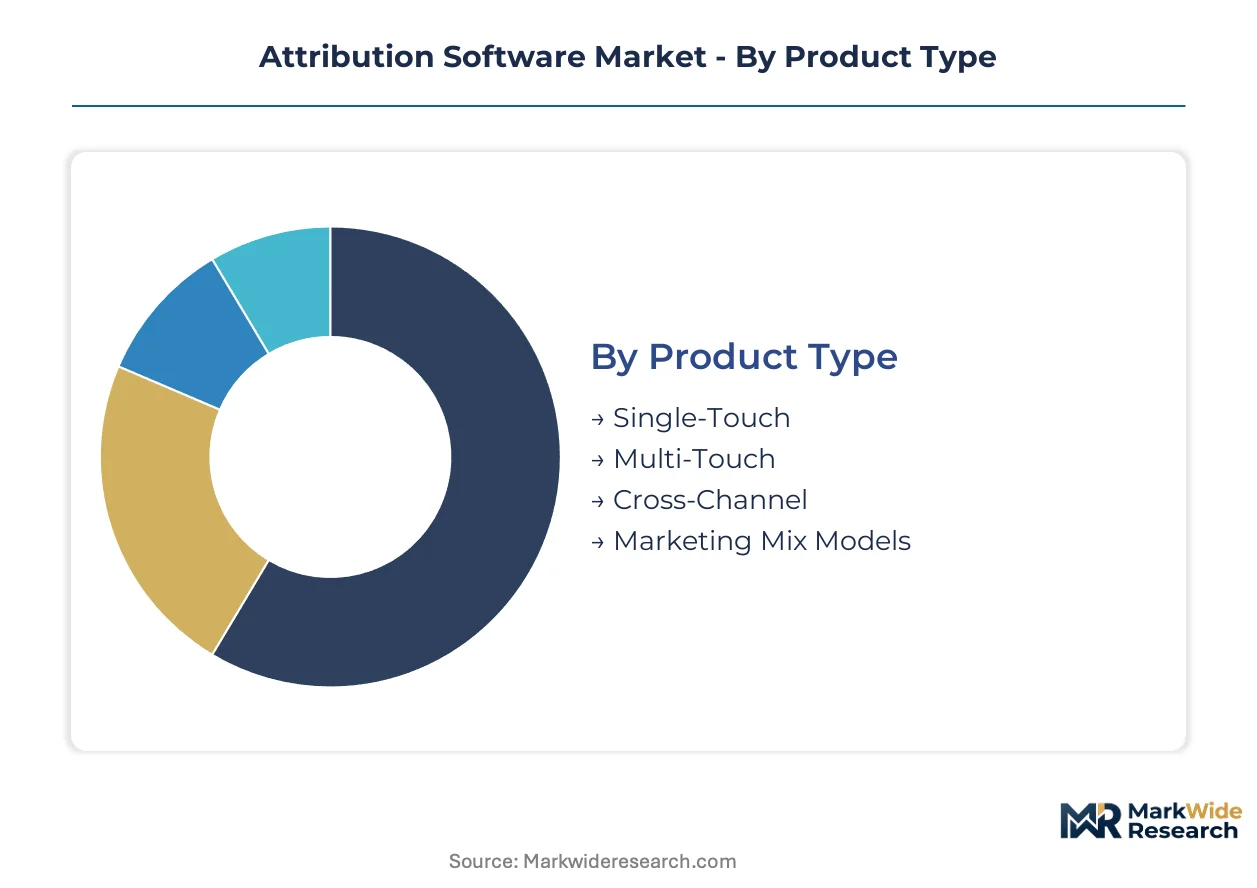
Attribution software procurement diverges sharply by organizational maturity and data infrastructure sophistication. Buyers select product architectures and deployment modes based on existing technology stack investments, regulatory exposure, and the complexity of their customer journey mapping requirements.
Product Type:
Buyers choose attribution models based on journey complexity and media mix breadth, with algorithmic sophistication commanding premium pricing.
- Multi-Touch:Algorithmic frameworks weight touchpoints dynamically across the conversion path using machine learning on impression logs and clickstream data. Enterprise CMOs in the United States with multi-hundred-million-dollar media budgets are consolidating procurement around these systems to replace rule-based misallocations. This segment leads on scale; Cross-Channel leads on momentum.
- Cross-Channel:Unified measurement architectures integrate digital, linear television, and physical store touchpoints into coherent attribution logic. E-commerce platforms expanding into brick-and-mortar footprints and connected television advertising drive demand as customer journeys fragment across screens.
- Single-Touch:First-click or last-click models assign full credit to one interaction point. Small retailers with limited marketing technology budgets and simple funnel structures remain the core buyer base.
- Marketing Mix Models:Econometric approaches isolate media effectiveness using aggregated time-series data rather than individual-level tracking. Consumer packaged goods manufacturers with sparse first-party data rely on these macro-level analyses.
Multi-Touch leads on scale; Cross-Channel leads on momentum.
Deployment:
Data residency mandates and latency requirements shape infrastructure decisions, with compliance costs widening the gap between delivery modes.
- Cloud-Based:SaaS delivery through vendor-managed infrastructure enables rapid implementation and automatic feature updates. Mid-market retailers without dedicated data engineering teams dominate this procurement tier.
- SaaS:Subscription access to attribution platforms eliminates capital expenditure and shifts operational burden to vendors. This deployment mode attracts e-commerce platforms prioritizing speed-to-insight over customization depth. Cloud-Based leads on scale; Hybrid leads on momentum.
- Hybrid:Split architectures process sensitive data on-premise while leveraging cloud analytics for modeling workloads. Financial services firms in Germany and Switzerland facing strict data localization requirements from national banking regulators are expanding this segment fastest.
- On-Premise:Fully captive infrastructure hosts all data and computation within organizational firewalls. Defense contractors and government agencies with classified media buying activities represent the residual demand pool.
Cloud-Based leads on scale; Hybrid leads on momentum.
End User:
Industry-specific measurement requirements drive feature prioritization, with digital-native sectors advancing sophistication fastest.
- E-Commerce:Online retailers demand precise cross-channel attribution as customer touchpoints fragment across mobile apps, social commerce interfaces, and physical store networks. GDPR and EU AI Act compliance requirements are accelerating investment in privacy-preserving architectures among European merchants.
- Retail:Omnichannel merchants trace digital advertising influence through to in-store purchase behavior using loyalty program identifiers and point-of-sale integration. United States-based department store chains with mature marketing technology stacks represent the core enterprise demand.
- Media:Publishers and broadcasters measure content monetization effectiveness across subscription and advertising revenue streams. Streaming audio and connected television platforms lacking mature attribution create expansion opportunities.
- Hospitality:Hotels and travel aggregators attribute bookings across metasearch engines, direct websites, and partner distribution channels. Long booking windows and cancellation volatility complicate model calibration for this sector.
E-Commerce leads on scale; Retail leads on momentum.
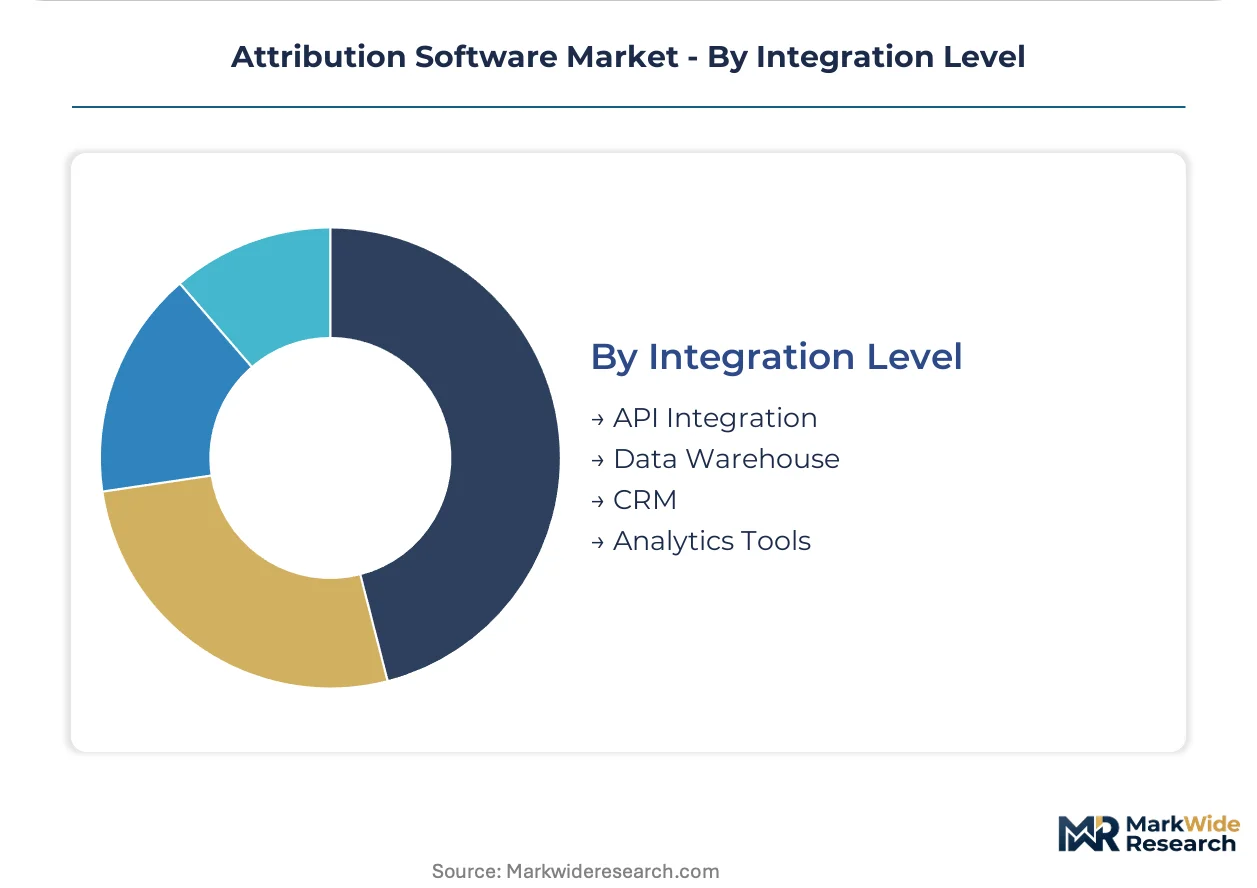
Integration Level:
Connectivity depth determines data quality and workflow efficiency, with procurement teams favoring pre-built connectors over custom development.
- CRM:Native linkage to customer relationship management systems enables account-level attribution for B2B buying committees. Salesforce, Inc. anchors enterprise demand through embedded measurement workflows.
- API Integration:Programmatic interfaces connect attribution platforms to advertising networks, data clean rooms, and custom applications. Marketing technology stacks with fragmented best-of-breed architectures rely on these flexible pipelines.
- Data Warehouse:Direct ingestion from cloud data warehouses like Snowflake and Databricks unifies attribution with enterprise analytics. Technology companies with centralized data governance functions prioritize this integration depth. CRM leads on scale; Data Warehouse leads on momentum.
- Analytics Tools:Embedded visualization and reporting within business intelligence platforms reduces context switching for marketing analysts. Organizations with established Tableau or Looker deployments favor this shallow integration tier.
CRM leads on scale; Data Warehouse leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor investment patterns as compliance cost differentials widen between jurisdictions. The United States maintains procurement leadership while European privacy mandates accelerate architectural innovation. Asia-Pacific markets are emerging as testbeds for privacy-preserving attribution models.
United States
Enterprise marketing technology stacks in the United States command the deepest procurement budgets for measurement tools. FTC scrutiny of deceptive measurement claims shapes vendor disclosure practices without imposing prescriptive technical mandates. The San Francisco Bay Area and New York Metro anchor demand concentration as retailers with multi-hundred-million-dollar media budgets consolidate vendor relationships.
Germany
Financial services firms in Germany demand hybrid cloud deployments to satisfy strict data residency requirements from national banking regulators. The EU AI Act and GDPR constrain algorithmic model training on personal identifiers, forcing architectural segmentation. Frankfurt's fintech cluster drives specialized demand for privacy-preserving attribution that processes consumer journeys without cross-border data flows.
United Kingdom
B2B technology vendors in the United Kingdom prioritize CRM-native attribution to map influence across buying committees with extended sales cycles. Post-Brexit regulatory divergence from EU AI Act implementation creates compliance complexity for vendors serving both markets. London's enterprise software procurement hub concentrates demand for unified measurement platforms with pre-built Salesforce connectors.
Japan
Consumer electronics manufacturers in Japan apply attribution software to trace content performance through omnichannel retail networks. METI guidance on marketing technology quality standards influences procurement evaluation criteria without binding mandate. Tokyo's advertising technology cluster favors vendors integrating with domestic CRM platforms and retail loyalty systems.
Australia
Streaming audio and connected television platforms in Australia seek attribution vendors that unify digital and linear measurement across fragmented media consumption. TGA-equivalent consumer protection frameworks govern marketing claim substantiation without sector-specific technical regulation. Sydney's media buying concentration drives demand for cross-channel measurement architectures serving subscription and advertising revenue models.
Attribution Software Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with enterprise SaaS vendors commanding premium pricing against mid-market challengers. The vendor landscape organizes around three strategic archetypes: advertising ecosystem incumbents leveraging media-buying workflow integration, CRM-native platforms reducing data fragmentation, and independent measurement specialists competing on methodological transparency. Consolidation pressure intensifies as procurement teams collapse fragmented best-of-breed stacks toward unified platforms. Strategic partnerships between attribution vendors and cloud data warehouses are displacing standalone implementations.
Within the advertising ecosystem tier, Google LLC and Adobe exemplify platform dependency dynamics as walled gardens tighten data access policies. Salesforce, Inc. anchors enterprise demand through native CRM-to-campaign linkage. Independent specialists including Rockerbox, Inc., Northbeam, and Dreamdata occupy positions emphasizing methodological differentiation and cross-platform measurement autonomy. These vendors represent alternatives for merchants seeking to reduce concentration risk in media-buying workflows.
| Leading Market Players |
|---|
| Adobe |
| Google LLC |
| Salesforce, Inc. |
| HubSpot, Inc. |
| IBM Corporation |
| Rockerbox, Inc. |
| Northbeam |
| Dreamdata |
| Ruler Analytics |
| Others |
Value Chain & Pricing Dynamics
EU AI Act algorithmic accountability requirements gate qualified supply for attribution software vendors, restricting premium-tier pricing access to vendors with auditable model training pipelines and human oversight capabilities that satisfy high-risk system classification.
Pricing Analysis
Direct-to-enterprise SaaS subscriptions bypass distributor margins entirely, with vendor-managed cloud delivery capturing 85-90% of contract value. Three-tier pricing structure across premium algorithmic, standard rule-based, and economy single-touch levels segments buyers by data infrastructure sophistication. Price differentiation hinges on ISO 27001 certification status and cross-channel integration depth. Cost compression in the standard tier intensifies as mid-market vendors compete on implementation speed.
Supply Chain Analysis
Refurbishment of legacy on-premise deployments into hybrid architectures creates secondary value flows for systems integrators serving financial services clients. Engineering talent concentrates in the United States, Germany, and India, with Bayesian statistics expertise anchoring in academic clusters. Cloud compute infrastructure draws from Amazon Web Services, Microsoft Azure, and Google Cloud Platform. Single-source vulnerability in identity graph data providers threatens model accuracy. Distribution runs through direct vendor sales teams and systems integration partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Attribution software procurement functions as a geographic-arbitrage play: vendors can capture 40-60% cost advantages by training base models in the United States while deploying privacy-preserving inference architectures in Germany that satisfy EU AI Act constraints without full retraining pipelines.
For Market Incumbents: Anticipate platform dependency backlash as Google's data access tightening forces enterprise buyers toward independent measurement specialists. Defend position by deepening first-party data infrastructure partnerships with major retailers and accelerating ISO 27701 privacy certification investments that procurement departments now mandate.
For New Entrants and Emerging Players: Mid-market B2B technology vendors in the United Kingdom represent an underserved buyer archetype with extended sales cycles requiring account-level attribution. Penetrate this segment through native Salesforce connector development and subscription pricing 30% below enterprise incumbents.
For Investors and Strategic Acquirers: Roll-up economics work for independent measurement specialists because enterprise procurement consolidation is collapsing fragmented best-of-breed stacks toward unified platforms. Target vendors with proven probabilistic identity resolution and existing cloud data warehouse partnerships. Monitor connected television attribution capability announcements as inflection indicators for platform viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Preserving Architecture Development | EU AI Act compliance enables continued European market access for algorithmic vendors. |
| Cloud Data Warehouse Partnership | Snowflake and Databricks integrations displace standalone attribution implementations. |
| CTV Attribution Capability Launch | Streaming audio and connected television measurement captures advertising budget shifts. |
| ISO Certification Investment | ISO 27001 and 27701 credentials satisfy procurement department evaluation criteria. |
| First-Party Data Infrastructure Buildout | Authenticated user bases reduce dependency on deprecating third-party cookies. |
Study Parameters
Bottom-up e-commerce platform modeling reconciled against top-down cloud infrastructure tracking forms the analytical core of this study. Primary interviews with CMOs, marketing technology procurement officers, data engineering directors, and attribution platform product managers informed demand-side assumptions. Secondary validation drew from SEC filings of publicly traded marketing technology vendors, hyperscaler advertising revenue disclosures, EU regulatory implementation guidance, and ISO certification registries.
Input-output matrices map algorithmic model deployment counts against cloud compute consumption patterns across the projection horizon. Segmentation dimensions include attribution model type, deployment architecture, end-user industry, and integration complexity level. CAGRs derive from regression analysis of historical procurement velocity and privacy regulation implementation timelines. Forecast inputs incorporate cookie deprecation schedules and retail media network expansion trajectories.
Underlying measurement precision varies by segment; cloud-based SaaS deployments carry tighter precision than hybrid on-premise implementations due to standardized telemetry availability. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and platform data access policy evolution. Practitioners should monitor EU AI Act high-risk system designations and Google Privacy Sandbox rollout milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global in-Store Analytics Market
Analytics
Embedded Analytics Market
Analytics
App Analytics Tools Market
Analytics
Personal Analytics Market
Analytics
Embedded Analytics Software Market
Analytics
Global Sentiment Analytics Software Market
Analytics
Global Web Analytics Software Market
Analytics
North America Crowd Analytics Market
Analytics
Operational Intelligence Market
Analytics
Location Analytics Adoption Spending Market
Analytics
Application Analytics Market
Analytics
Global Data Fusion Market
Analytics
Mobile Analytics Market
Analytics
France Contact Center Analytics Market
Analytics
Marketing Analytics Software Market
Analytics
Business Analytics Market