
 DC Contactor Market | 2026-2036
DC Contactor Market Size, Share, and Industry Trends Forecast 2026-2036
DC Contactor Market Analysis
Software-defined thermal monitoring is repositioning how DC contactor vendors capture lifetime value beyond the hardware sale. Siemens leverages its digital twin platform to embed predictive maintenance contracts into industrial automation deployments. Hongfa anchors its competitive stance through captive production of hermetically sealed ceramic housings for high-voltage miniature contactors. Schneider Electric extends its service reach by bundling DIN rail mount contactors with cloud-based energy management dashboards.
A DC contactor is an electrically controlled switch engineered to make and break DC circuits carrying currents from tens to thousands of amperes, typically employing silver alloy contacts within vacuum or gas-filled chambers to suppress arc formation during interruption. Its core industrial purpose lies in isolating fault currents and managing power flow in battery storage arrays, traction systems, and DC fast-charging infrastructure where AC contactors would fail from sustained arcing. Electromechanical contactors still dominate installed base volumes across rail transport and heavy industrial automation, though solid state contactors are displacing them in battery management systems where million-cycle endurance eliminates mechanical wear. Panel mount installations retain the largest share of legacy retrofit demand, while PCB mount configurations are expanding fastest within integrated battery pack designs where space and weight constraints tighten.
The EU AI Act and CE marking requirements under the Machinery Directive are forcing DC contactor manufacturers to document functional safety ratings for emergency shutdown circuits in automated production lines. China's MIIT enforces GB/T standards on DC switching devices for new energy vehicles, creating a dual compliance burden for exporters serving both European and Chinese automotive OEMs. India's BIS certification mandates for industrial electrical equipment add a third regulatory checkpoint for suppliers targeting the country's renewable energy buildout. Stakeholders must weigh whether to pursue region-specific product certifications or architect unified platforms that satisfy the most stringent jurisdiction.
Market Dynamics
High-voltage electrification across automotive and industrial sectors is forcing DC contactor architectures toward hermetic sealing and arc-quenching innovations that can survive million-cycle duty in battery management systems. This structural pressure cascades through material selection, manufacturing location decisions, and service model reinvention.
Growth Catalysts
- EU F-Gas Regulation:Industrial electrification mandates under this framework accelerate replacement of gas-insulated switchgear with vacuum-sealed DC contactors in manufacturing plants across Germany and France.
- Traction systems:Rail operators in Japan and Switzerland specify electromechanical DC contactors for regenerative braking circuits, sustaining demand for high-amperage switching hardware.
- Solid-state displacement:Silicon carbide power electronics are penetrating battery management systems where mechanical wear elimination justifies premium positioning.
Market Restraints
- Silver alloy cost volatility:Contact material prices fluctuate with precious metal markets, compressing margins for standard-grade product lines.
- Ceramic housing supply concentration:Hermetic component fabrication clusters in China's eastern provinces create single-source vulnerability for sealed miniature contactors.
- CE marking complexity:Machinery Directive compliance documentation for emergency shutdown circuits extends product launch timelines by 8-14 months.
Strategic Opportunities
- India renewable buildout:Grid-scale solar and wind installations require DC switching arrays for battery storage integration, opening volume deployment potential.
- Digital twin bundling:Predictive maintenance contracts attached to hardware sales capture recurring revenue streams in industrial automation.
- PCB mount expansion:Integrated battery pack designs favor lightweight contactor configurations that eliminate panel wiring harnesses.
Industry Challenges
- Dual certification burden:Suppliers serving European and Chinese automotive OEMs must simultaneously satisfy EU AI Act documentation and MIIT GB/T standards.
- High-voltage testing infrastructure:Validation equipment for 1000V+ switching cycles requires capital investment that excludes smaller contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DC Contactor Market |
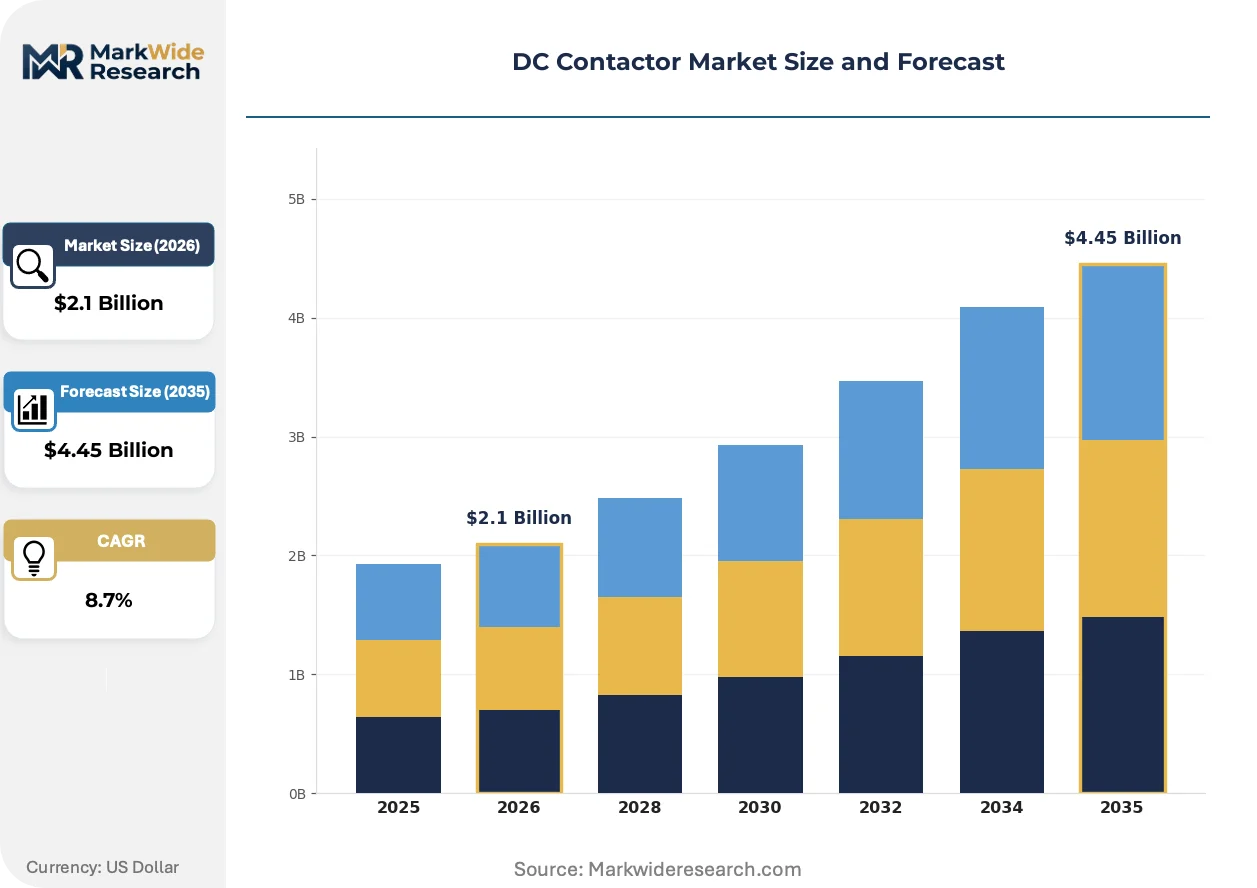
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical Contactors, Solid State Contactors, Miniature Contactors, Standard Contactors End User: Automotive, Renewable Energy, Industrial Automation, Rail Transport Application: Battery Management Systems, Motor Control, Power Distribution, Emergency Shutdown Installation: Panel Mount, DIN Rail Mount, PCB Mount, Surface Mount |
| Companies Covered | Eaton, Sensata Technologies, Siemens, LS Electric, Panasonic Corporation, Schneider Electric, BYD, Hongfa, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DC Contactor Market Emerging Trajectories
Solid-state and electromechanical architectures are diverging into distinct competitive arenas, with material science and software integration determining vendor positioning. Three forces are actively restructuring how value gets captured.
Vacuum interrupter technology is rewriting durability benchmarks for DC contactor applications. Rail operators in Switzerland and Japan specify ceramic-sealed vacuum chambers for regenerative braking systems where mechanical contacts face million-cycle endurance requirements. This material shift compresses maintenance intervals from annual to decadal, enabling outcome-based service contracting that locks out lower-tier suppliers.
China's MIIT enforcement of GB/T standards on DC switching devices for new energy vehicles creates compliance friction for exporters. The regulations mandate specific arc-quenching performance and thermal cycling documentation that European manufacturers must replicate in-country testing facilities to access automotive OEM supply chains. German suppliers around Stuttgart have responded by establishing joint validation laboratories with Chinese partners.
Automotive battery pack designers now specify PCB-mounted contactors that eliminate traditional panel wiring. This consumption-pattern shift favors miniature hermetic configurations with integrated driver circuits, displacing discrete component assemblies. South Korean and Japanese electric vehicle programs are driving fastest adoption, with procurement teams prioritizing weight reduction over field-service accessibility.
DC Contactor Market Segmentation
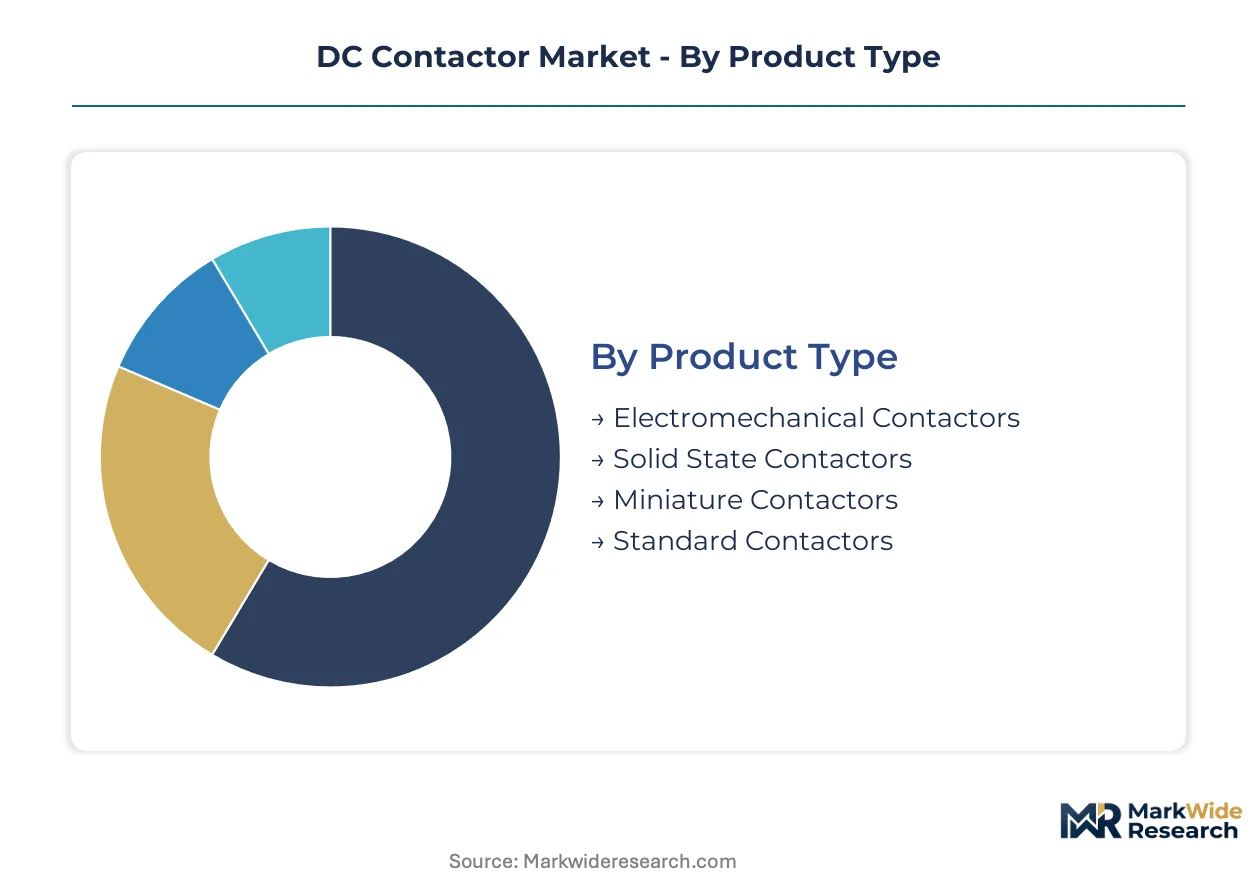
DC contactor architectures diverge sharply across voltage ratings, switching cycles, and thermal constraints. Each segment carries distinct margin profiles and certification burdens that reshape vendor positioning.
Product Type:
Electromechanical variants still command the largest installed base volumes, while solid-state alternatives capture premium positioning through elimination of mechanical wear.
- Electromechanical Contactors:Silver alloy contacts within vacuum or gas-filled chambers suppress arc formation during high-amperage interruption. Rail operators in Switzerland and Japan specify these for regenerative braking circuits where million-cycle endurance justifies the mechanical complexity.
- Solid State Contactors:Silicon carbide power electronics enable switching without moving parts. Battery management systems in South Korean and Japanese electric vehicle programs favor these configurations where weight reduction and cycle life outweigh cost premiums.
- Miniature Contactors:Hermetically sealed ceramic housings serve space-constrained applications.
- Standard Contactors:General-purpose designs dominate legacy industrial retrofits.
Mature deployment sits with Electromechanical Contactors. Newer deployment is concentrated in Solid State Contactors.
End User:
Application environments dictate arc-quenching requirements and thermal cycling documentation standards.
- Automotive:OEM procurement teams specify PCB-mounted configurations for integrated battery packs. China's MIIT enforces GB/T standards that mandate specific arc-quenching performance, creating compliance friction for European suppliers.
- Renewable Energy:Grid-scale solar and wind installations in India require DC switching arrays for battery storage integration. The country's BIS certification mandates add regulatory checkpoints for industrial electrical equipment.
- Industrial Automation:The EU AI Act and CE marking requirements under the Machinery Directive force manufacturers to document functional safety ratings for emergency shutdown circuits.
- Rail Transport:Operators specify ceramic-sealed vacuum chambers where maintenance intervals compress from annual to decadal.
Procurement is shifting toward Automotive as electrification accelerates. Industrial Automation retains the deepest installed base.
Application:
Voltage thresholds and switching frequency determine whether electromechanical or solid-state architectures prevail.
- Battery Management Systems:PCB mount configurations eliminate panel wiring harnesses. South Korean electric vehicle programs drive fastest adoption with weight reduction prioritized over field-service accessibility.
- Motor Control:High-amperage switching demands vacuum interrupter technology for durability.
- Power Distribution:Industrial electrification mandates under the EU F-Gas Regulation accelerate replacement of gas-insulated switchgear with vacuum-sealed alternatives in German and French manufacturing plants.
- Emergency Shutdown:Functional safety ratings require extensive CE marking documentation that extends product launch timelines.
Battery Management Systems are expanding most quickly. Motor Control represents the most mature application segment.
Installation:
Physical mounting method determines wiring complexity, thermal management, and service accessibility trade-offs.
- Panel Mount:Traditional enclosures with discrete wiring dominate legacy retrofit demand across heavy industrial automation.
- DIN Rail Mount:Schneider Electric bundles these with cloud-based energy management dashboards to extend service reach.
- PCB Mount:Integrated driver circuits and hermetic sealing serve battery pack designs where space and weight constraints tighten most severely.
- Surface Mount:Compact configurations address specialized miniature applications.
Panel Mount retains the largest legacy volume. PCB Mount is gaining share fastest as automotive integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of hermetically sealed ceramic housings for DC contactors, while Germany and Japan absorb premium volumes for automotive and rail applications. Demand concentrates in industrial clusters where electrification mandates intersect with established supplier ecosystems.
Germany
Automotive OEMs around Stuttgart and Munich specify PCB-mounted contactors for integrated battery packs. The EU F-Gas Regulation accelerates replacement of gas-insulated switchgear with vacuum-sealed alternatives in manufacturing plants. Baden-Württemberg's supplier corridor hosts validation laboratories serving both domestic and Chinese automotive programs.
China
MIIT enforcement of GB/T standards on DC switching devices creates compliance requirements for new energy vehicle programs. Eastern provinces concentrate hermetic component fabrication for sealed miniature contactors. Joint validation facilities in Shanghai and Shenzhen enable European suppliers to access automotive OEM supply chains.
Japan
Rail operators specify ceramic-sealed vacuum chambers for regenerative braking systems requiring million-cycle endurance. METI industrial electrification programs sustain demand for high-amperage switching hardware. Nagoya and Osaka manufacturing belts produce vacuum interrupter technology for export markets.
India
Grid-scale solar and wind installations require DC switching arrays for battery storage integration. BIS certification mandates for industrial electrical equipment add regulatory checkpoints for equipment imports. Gujarat and Maharashtra renewable energy corridors drive procurement volumes for power distribution applications.
South Korea
Electric vehicle programs prioritize PCB mount configurations with weight reduction over field-service accessibility. The country's national industrial regulator enforces performance documentation for high-voltage switching devices. Seoul metropolitan area battery pack designers specify miniature hermetic configurations with integrated driver circuits.
DC Contactor Market Vendor Landscape
Top-tier vendors anchor premium positioning through digital service bundling, while mid-tier fabricators compete on ceramic housing supply security. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with predictive maintenance platforms, specialized hermetic component producers with captive ceramic supply, and scale-driven electrical equipment manufacturers with broad distribution networks. M&A activity targets digital twin capabilities, and capacity expansion concentrates in vacuum interrupter fabrication.
Within the diversified industrial tier, Siemens and Schneider Electric exemplify platform-based positioning through digital service integration. Hongfa occupies a position representing specialized hermetic component production. Among Asia-Pacific-based fabricators, LS Electric and BYD sit within the scale-driven archetype serving battery management system procurement.
| Leading Market Players |
|---|
| Eaton |
| Sensata Technologies |
| Siemens |
| LS Electric |
| Panasonic Corporation |
| Schneider Electric |
| BYD |
| Hongfa |
| ABB |
| Others |
Supply Flow & Price Mechanics
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating vacuum-sealed DC contactor architectures that exclude uncertified fabricators from automotive and industrial procurement channels.
Pricing Analysis
Margin tightening in standard-grade electromechanical tiers reflects silver alloy cost volatility and ceramic housing supply concentration in China's eastern provinces. Three-tier pricing structure across hermetic miniature, industrial panel-mount, and solid-state configurations stratifies by certification grade and cycle-life documentation. Cost compression accelerates as battery management system procurement teams consolidate volumes with suppliers offering integrated driver circuits. Automotive OEMs exhibit lowest price sensitivity, prioritizing weight reduction and million-cycle endurance over per-unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from South Korean and Japanese electric vehicle programs, while distributor networks serve legacy industrial retrofit markets. Manufacturing gravity centers on China for hermetic ceramic housings, Germany for vacuum interrupter technology, and Japan for rail-grade electromechanical assemblies. Raw material dependencies span silver alloy contacts, silicon carbide substrates, and high-purity alumina ceramics. Single-source vulnerability concentrates in China's eastern provinces for sealed miniature contactor fabrication. Distribution runs through authorized distributors for DIN rail and panel mount configurations, with direct technical sales teams managing PCB mount specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic housing fabrication capacity constraints prop pricing power for qualified suppliers, creating a supply-constrained market structure favoring incumbents with captive production assets.
For Market Incumbents: Deploy predictive maintenance platform bundling to lock in industrial automation accounts against solid-state displacement threats. Deepen backward integration into vacuum interrupter fabrication to secure rail transport procurement. Accelerate joint validation laboratory partnerships in China to neutralize MIIT GB/T compliance friction for European automotive OEMs. For New Entrants and Emerging Players: The price-point gap between premium hermetic miniature contactors and economy-grade panel mount alternatives opens white-space in India's renewable energy buildout. Target grid-scale solar and wind battery storage integration where BIS certification mandates have slowed established supplier entry. Pursue PCB mount qualification for South Korean electric vehicle programs as a beachhead into automotive-grade procurement. For Investors and Strategic Acquirers: German automotive OEM establishment of in-country validation facilities with Chinese partners is the leading indicator that dual-certification capabilities will separate viable acquisition targets from stranded assets. Position for five-to-ten year consolidation around digital twin-enabled service platforms and captive ceramic supply chains. Monitor MIIT enforcement actions against non-compliant imports as the inflection signal for regulatory barrier height.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Validation Laboratory Partnership | Enables European suppliers to satisfy MIIT GB/T standards for Chinese automotive OEM access. |
| Ceramic Housing Capacity Expansion | Captive supply of hermetic components insulates margins from eastern China concentration risk. |
| Digital Twin Platform Integration | Siemens and Schneider Electric leverage predictive maintenance contracts to extend service reach. |
| Solid-State Contactor R&D Investment | Silicon carbide power electronics displace electromechanical architectures in battery management systems. |
| India Distribution Channel Buildout | BIS certification expertise unlocks grid-scale solar and wind battery storage procurement volumes. |
Methodological Framework
Independent corroboration across primary interviews with OEM procurement managers, Tier 1 supplier quality directors, rail operator maintenance heads, and aftermarket distribution partners underwrites the qualitative findings. Secondary validation draws from MIIT GB/T standard filings, EU F-Gas Regulation implementation guidance, customs trade data for ceramic component flows, and SEC disclosures from diversified industrial conglomerates. Bottom-up segmentation modeling triangulates against top-down electrification capex projections from automotive and renewable energy sectors.
Comparable-period anchoring to historical DC contactor deployment in rail transport and heavy industrial automation establishes baseline assumptions across the projection horizon. The analytical framework models product type, end user vertical, voltage rating tier, and installation configuration dimensions. CAGRs derive from installed base replacement cycles, electrification mandate timelines, and solid-state displacement curves. Forecast inputs incorporate battery pack integration density trends and hermetic component yield rates from Chinese fabrication clusters.
Inputs from OEM procurement databases and rail operator maintenance records were available through the study window; gaps in solid-state contactor field-failure data introduce uncertainty bands around million-cycle endurance claims. Forecasts reflect documented assumptions regarding MIIT enforcement consistency and EU F-Gas Regulation implementation pace. Practitioners should monitor ceramic housing spot pricing and Chinese export license processing times for early signals of supply constraint severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Industrial Plugs and Sockets Market
Electrical Equipment
Cable Distribution Cabinets Market
Electrical Equipment
Saudi Arabia Electric Motor Market
Electrical Equipment
Ultra High Voltage (UHV) Appliances Market
Electrical Equipment
Motor Control Centers (MMC) Market
Electrical Equipment
US Electric Enclosure Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Hermetic Reciprocating Refrigerator Compressor Market
Electrical Equipment
Surface Mounting Distribution Panel Market
Electrical Equipment
Pad-Mounted Transformer Market
Electrical Equipment
Low Voltage Electric Motor Market
Electrical Equipment
Global General Purpose Contactor Market
Electrical Equipment
Soft Starter Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Global Dehumidifier Market
Electrical Equipment
Voltage Transformer Market