
 Motor Control Centers (MMC) Market | 2026-2036
Motor Control Centers (MMC) Market Size, Share, and Industry Trends Forecast 2026-2036
Motor Control Centers (MMC) Market Foresight
Copper-to-aluminum busbar substitution is recalibrating cost structures across medium-voltage MMC assemblies without compromising current-carrying thresholds. ABB leverages its European manufacturing footprint to sustain premium positioning in intelligent motor control systems. Siemens anchors its competitive stance through deep R&D intensity in digital twin integration for predictive maintenance. WEG competes aggressively on manufacturing scale across Latin American and Southeast Asian markets.
Motor control centers are engineered assemblies of motor starters, variable frequency drives, and protective devices housed in standardized enclosures, typically rated for 480V to 15kV distribution and designed to centralize motor control, protection, and monitoring for industrial process loads. Their primary purpose is to reduce wiring complexity, enable coordinated motor protection, and provide localized operator control for clusters of electric motors in continuous-process environments. Intelligent MCs command the widest margin pools as plant operators prioritize condition-based monitoring and energy analytics over basic electromechanical protection. Modular MCs represent the fastest-growing configuration, driven by project-scale flexibility and reduced commissioning downtime in brownfield expansions across manufacturing and water treatment sectors.
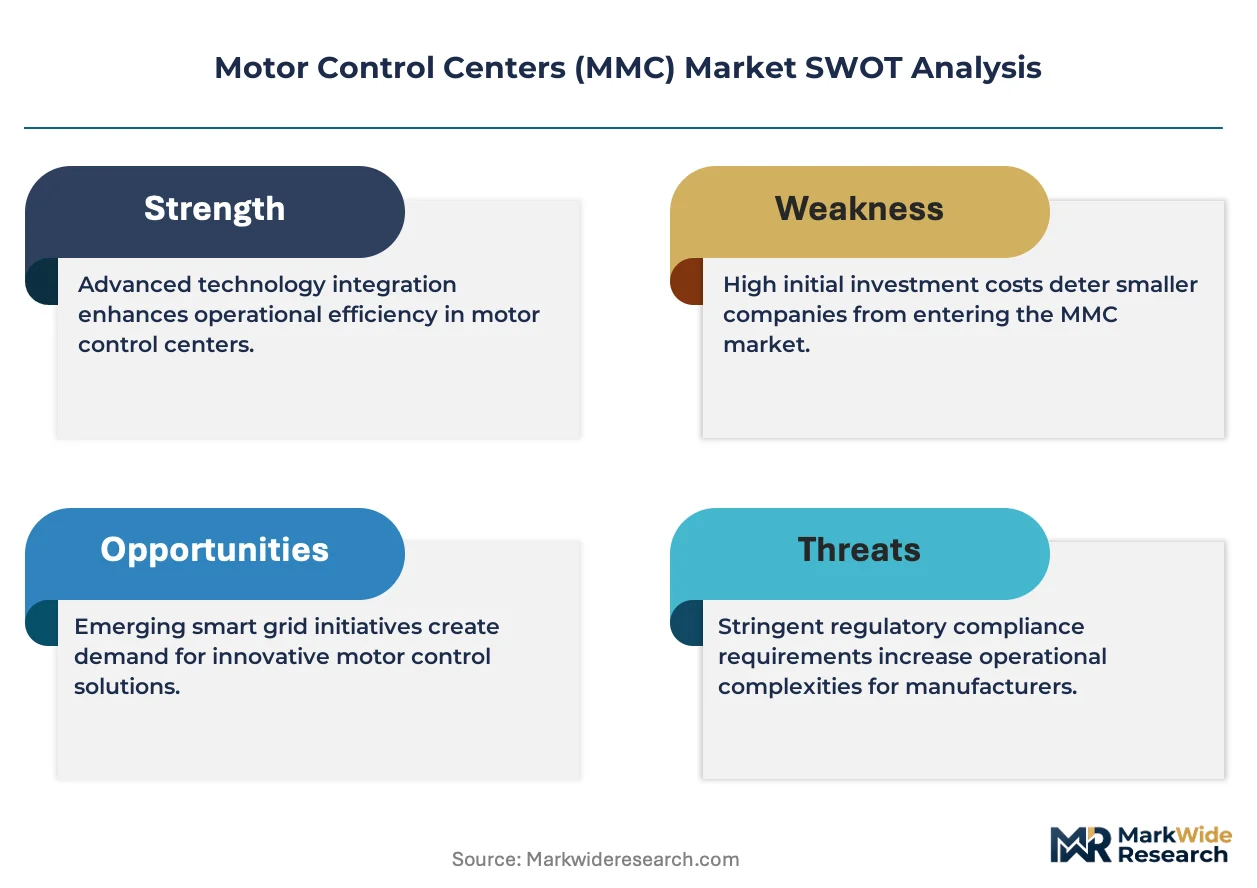
IEC 61439 and NEMA ICS 2 standards govern enclosure integrity, temperature rise limits, and short-circuit withstand ratings, compelling manufacturers to redesign thermal management systems and validate assemblies through third-party witnessed testing. The US Department of Energy and EU Ecodesign directives are tightening efficiency thresholds for motor-driven systems, indirectly mandating smarter control architectures that optimize load profiles. OSHA electrical safety regulations in the United States and CE marking requirements under the EU Low Voltage Directive shape procurement specifications, particularly for arc-flash containment and lockout-tagout integration. Stakeholders must weigh the capital cost of intelligent retrofit packages against the operational savings from reduced unplanned downtime and energy recovery.
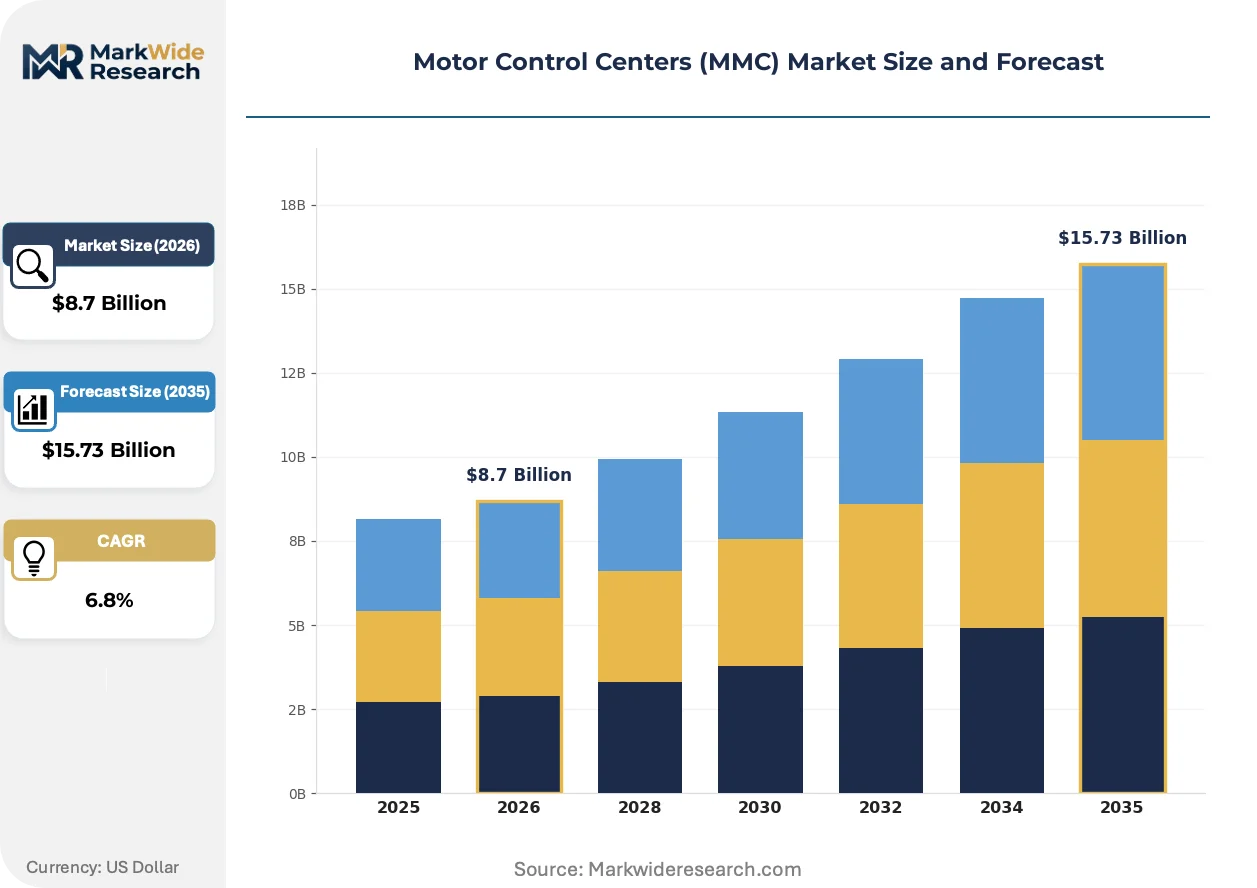
Market Dynamics
IEC 61439 certification mandates are compressing supplier margins while accelerating consolidation among low-voltage switchgear manufacturers. Copper price volatility and aluminum busbar substitution are redrawing cost structures across medium-voltage assemblies.
Growth Catalysts
- Industrial electrification in China:Smart factory investments are accelerating motor control infrastructure upgrades across automotive and electronics manufacturing clusters.
- Water treatment automation:Municipal pump station modernization is expanding MMC deployment for remote monitoring and energy optimization.
- EU Ecodesign directives:Efficiency thresholds for motor-driven systems are mandating smarter control architectures that optimize load profiles.
Market Restraints
- Copper price volatility:Raw material cost swings above historical baselines are compressing assembly margins and forcing hedging costs onto smaller fabricators.
- Third-party witnessed testing:IEC 61439 validation requirements are extending certification timelines by 8-14 weeks for new product introductions.
- Technical skill concentration:Arc-flash engineering and thermal modeling expertise pools narrowly in Germany, the US, and Japan.
Strategic Opportunities
- Brownfield manufacturing in Southeast Asia:Modular MMC configurations are capturing project-scale flexibility demand in Vietnam and Indonesia.
- Digital twin convergence:Integration of asset performance management with motor control hardware is opening predictive maintenance revenue streams.
- US IRA industrial incentives:Domestic content bonuses for clean energy manufacturing are stimulating localized MMC production investments.
Industry Challenges
- Arc-flash engineering talent scarcity:Specialized electrical safety design skills are concentrated among aging practitioners in North America and Western Europe.
- Legacy system integration friction:Retrofitting intelligent monitoring into 480V electromechanical assemblies requires custom gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motor Control Centers (MMC) Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular MCs, Intelligent MCs, Conventional MCs, Integrated MCs End User: Manufacturing, Oil & Gas, Water Treatment, Mining Technology: Digital Control, Analog Control, Hybrid Control, Remote Monitoring Installation: Indoor, Outdoor, Panel-Mounted, Floor-Mounted |
| Companies Covered | ABB, Schneider Electric, Siemens, Rockwell Automation, Eaton, Mitsubishi Electric, WEG, Fuji Electric, Powell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motor Control Centers (MMC) Market Shifts & Advancements
Digitalization of motor control architectures is compressing maintenance cycles and enabling energy analytics that were previously cost-prohibitive. Three distinct vectors are reshaping product development and buyer expectations.
Edge computing modules embedded within intelligent motor control centers are automating real-time vibration analysis and thermal profiling without upstream SCADA dependency. Water treatment utilities in the US and Germany are deploying these systems at brownfield pump stations. The technology is automating condition-based maintenance scheduling that previously required manual technician rounds.
EU Ecodesign directives and US Department of Energy efficiency thresholds are tightening in parallel, compelling manufacturers to redesign thermal management systems and validate short-circuit withstand ratings through witnessed testing. Assembly vendors are responding by pre-certifying modular platforms that span multiple voltage classes. The regulatory pressure is most acute in process industries where motor loads exceed 500 horsepower.
Buyer preference is migrating toward lifecycle service contracts that bundle hardware, commissioning, and predictive analytics under single-source accountability. Industrial operators in China's Yangtze River Delta are pioneering this procurement model for smart factory expansions. Channel intermediaries in traditional electrical distribution are ceding margin to OEM-direct engagement teams.
Motor Control Centers (MMC) Market Segmentation
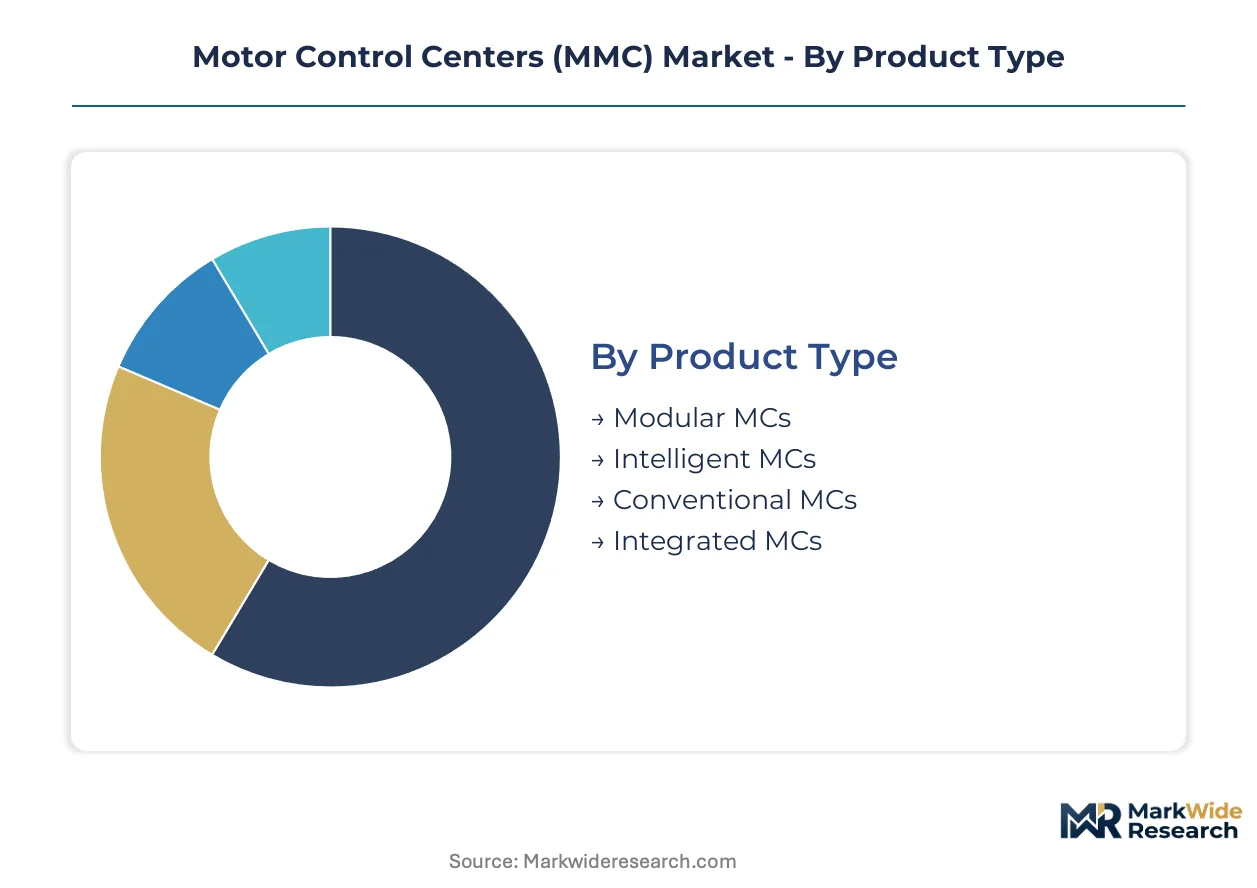
Motor control center procurement patterns diverge sharply across voltage classes and intelligence tiers. Plant operators segment investments by brownfield retrofit complexity versus greenfield standardization potential.
Product Type:
Supply concentration in intelligent MC assemblies tilts toward vendors with captive software development and thermal modeling capabilities.
- Intelligent MCs:Embedded edge computing modules automate vibration analysis and thermal profiling without upstream SCADA dependency. Water treatment utilities in Germany and the US deploy these at brownfield pump stations for condition-based maintenance scheduling.
- Modular MCs:Standardized enclosure platforms enable project-scale flexibility and reduced commissioning downtime. Vietnam and Indonesia manufacturing expansions are absorbing these configurations fastest.
- Conventional MCs:Electromechanical starter assemblies dominate legacy industrial infrastructure across US Midwest manufacturing corridors.
- Integrated MCs:Pre-engineered combinations of motor starters, drives, and protection devices ship as factory-tested skids for oil and gas process trains.
Conventional MCs absorb the bulk of installed capacity; modular MCs are expanding most quickly.
End User:
Application-driven specification intensity varies by sector exposure to continuous-process uptime requirements and arc-flash safety mandates.
- Water Treatment:Municipal pump station automation demands remote monitoring capabilities and energy optimization protocols. US EPA compliance deadlines for combined sewer overflow mitigation are accelerating MMC deployment timelines.
- Manufacturing:Automotive and electronics clusters in China's Yangtze River Delta prioritize intelligent MCs bundled under lifecycle service contracts with predictive analytics.
- Oil & Gas:Offshore platform electrification and onshore shale processing require explosion-proof enclosures and IECEx certification.
- Mining:Harsh-environment assemblies with enhanced ingress protection serve open-pit and underground extraction operations across Australia and Chile.
Manufacturing commands the deepest vendor engagement; water treatment is climbing the fastest.
Technology:
Control architecture migration patterns reflect workforce digital literacy gaps and legacy technician retention challenges.
- Digital Control:Microprocessor-based motor protection relays enable precise overload curves and network communication. EU Ecodesign directive compliance is mandating these architectures for motors above 500 horsepower.
- Remote Monitoring:Cloud-connected asset performance management platforms aggregate data from distributed pump stations. German water utilities lead deployment density for predictive maintenance revenue models.
- Hybrid Control:Electromechanical contactors paired with digital overload relays bridge legacy infrastructure and modern analytics requirements.
- Analog Control:Bimetallic overload relays and electromechanical timers persist in cost-sensitive applications with minimal automation needs.
Digital control captures the majority of new specification activity; remote monitoring is gaining share fastest.
Installation:
Enclosure configuration selection tracks site-specific environmental exposure and maintenance access constraints.
- Indoor:Climate-controlled electrical rooms in process manufacturing facilities house assemblies rated for NEMA 1 or IEC IP30 ingress protection.
- Floor-Mounted:Freestanding enclosures with front and rear access accommodate high-density starter buckets in automotive stamping plants.
- Outdoor:NEMA 3R or IEC IP54 enclosures with sun shields and heater circuits serve remote oil field pump jacks and mining conveyors.
- Panel-Mounted:Space-constrained retrofits in aging municipal infrastructure utilize distributed starter modules mounted within existing switchgear lineups.
Indoor installations retain the largest footprint; outdoor configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the deepest demand pool for motor control infrastructure, with industrial electrification programs and smart factory mandates driving procurement intensity across multiple manufacturing belts.
China
Automotive and electronics manufacturing clusters in the Yangtze River Delta are accelerating MMC deployment for production line automation. MIIT industrial upgrade directives mandate energy efficiency thresholds for motor systems above 500 horsepower. Shenzhen and Suzhou industrial parks are absorbing intelligent motor control configurations bundled under lifecycle service contracts.
United States
Municipal water treatment utilities are modernizing pump station infrastructure for remote monitoring and combined sewer overflow compliance. EPA enforcement deadlines and OSHA electrical safety regulations are tightening arc-flash containment specifications. Ohio River Valley manufacturing corridors retain substantial conventional motor control installed base requiring intelligent retrofit integration.
Germany
Process industries along the Rhine-Ruhr industrial zone are deploying edge-computing motor control modules for predictive maintenance automation. EU Ecodesign directives and CE marking requirements under the Low Voltage Directive are compressing certification timelines for thermal management redesigns. Bavarian automotive suppliers are pioneering digital twin integration for motor asset performance management.
Brazil
Mining operations in Minas Gerais and open-pit extraction sites across the Carajás mineral province are demanding harsh-environment motor control assemblies with enhanced ingress protection. ANVISA and national electrical safety frameworks are aligning with IEC 61439 validation protocols for industrial equipment certification. São Paulo state manufacturing expansions are absorbing modular MMC configurations for project-scale flexibility.
India
Textile processing clusters in Gujarat and automotive component manufacturing in Tamil Nadu are upgrading motor control infrastructure under PLI scheme incentives. CEA electrical standards and BIS certification mandates are tightening short-circuit withstand rating requirements for low-voltage switchgear. Delhi-Mumbai Industrial Corridor projects are specifying floor-mounted intelligent motor control centers for high-density starter applications.
Motor Control Centers (MMC) Market Competitive Landscape
Capacity expansion dominates the current landscape as established electrical equipment manufacturers scale manufacturing footprints to capture localized production incentives and reduce logistics exposure to copper price volatility. The vendor base organizes around three strategic archetypes: integrated industrial conglomerates with captive software development, specialized switchgear fabricators with regional manufacturing density, and emerging scale players from industrializing economies. M&A activity and strategic technology licensing partnerships represent the two dominant competitive vectors, with incumbents acquiring predictive analytics capabilities and modular platform intellectual property.
Among European-based industrial conglomerates, ABB and Siemens occupy positions exemplifying the intelligent systems archetype through embedded edge computing and digital twin integration. WEG anchors the scale-driven manufacturing tier with production density across Latin American and Southeast Asian markets. These three companies represent distinct competitive positioning vectors: premium-tier software-hardware integration, comprehensive lifecycle service bundling, and cost-optimized modular platform supply.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Siemens |
| Rockwell Automation |
| Eaton |
| Mitsubishi Electric |
| WEG |
| Fuji Electric |
| Powell |
| Others |
Supply & Pricing Matrix
Aluminum busbar substitution in medium-voltage assemblies is simultaneously compressing material costs and redrawing supplier concentration toward fabricators with captive metallurgical processing. This transition rewards integrated manufacturers while squeezing margin pools for distributors dependent on spot copper procurement.
Pricing Analysis
Volume absorbs conventional MC assemblies while margins concentrate in intelligent configurations. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61439-certified intelligent systems from modular platforms and basic electromechanical units. Price differentiation hinges on certification tier and after-sales service bundling. Cost compression in standard-tier modular assemblies is intensifying because aluminum busbar adoption forces copper-dependent fabricators into defensive discounting. Municipal water utilities exhibit highest price sensitivity; oil and gas operators prioritize certification grade over unit cost.
Supply Chain Analysis
Arc-flash engineering talent scarcity in Germany, the United States, and Japan constrains production scaling for intelligent MC assemblies. Manufacturing concentrates in China, Germany, and Brazil, with component sourcing drawing from copper smelters in Chile, aluminum producers in Australia, and semiconductor fabricators in Taiwan. Single-source vulnerability in IGBT module supply creates chokepoint exposure for variable frequency drive integration. Distribution runs through electrical wholesale networks with OEM-direct engagement teams capturing share in lifecycle service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IEC 61439 certification mandates erect a cost-of-compliance barrier that moats established players against commodity assemblers. Third-party witnessed testing requirements extend validation timelines, privileging incumbents with pre-certified modular platforms.
For Market Incumbents: Lock in thermal modeling expertise pools through targeted hiring in Germany and Japan, insulating against arc-flash engineering talent scarcity. Expand captive aluminum busbar processing to neutralize copper price volatility exposure. Defensive consolidation of regional switchgear fabricators in Southeast Asia preempts emerging scale players from capturing modular MC share in Vietnam and Indonesia manufacturing corridors.
For New Entrants and Emerging Players: Direct-to-utility digital sales channels bypass entrenched electrical distribution intermediaries ceding margin in lifecycle service contracts. Target brownfield water treatment pump stations in US Midwest and German municipal systems for intelligent retrofit integration. White-space opportunity concentrates in custom gateway development for legacy 480V electromechanical assembly upgrades.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by industrial conglomerates seeking predictive analytics capabilities and modular platform intellectual property. Long-term viability favors vendors with software-hardware integration depth over pure-play fabricators. Watch for inflection in US IRA domestic content bonus utilization rates as signal for localized production investment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Validation | IEC 61439 witnessed testing completion ahead of product launch compresses time-to-revenue for modular platform introductions. |
| Backward Integration into Busbar Processing | Captive aluminum metallurgy capacity insulates margin structures from London Metal Exchange copper volatility. |
| Digital Twin Integration Partnership | Siemens and ABB anchor competitive positioning through predictive maintenance software bundled with hardware shipments. |
| Lifecycle Service Contract Bundling | Yangtze River Delta automotive clusters pioneer single-source accountability models spanning commissioning through energy analytics. |
| Regional Manufacturing Footprint Expansion | WEG scales Latin American and Southeast Asian production density to capture localized content incentives and reduce logistics exposure. |
Research Methodology
Multi-period observation of motor control infrastructure deployment rates, certification timeline extensions, and raw material substitution patterns anchored the trend analysis, supplemented by interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads at water treatment utilities and manufacturing facilities. Secondary validation drew from IEC standards documentation, US Department of Energy efficiency threshold filings, EU Ecodesign directive implementations, and customs trade data for copper and aluminum busbar imports. Bottom-up assembly vendor capacity assessments and top-down end-user expenditure tracking were triangulated against regional electrification program budgets.
Input-output matrix modeling structured the analytical framework across voltage class, intelligence tier, end-use sector, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from segment-level demand elasticity coefficients and replacement cycle analysis. Forecast inputs incorporated MIIT industrial upgrade directive compliance deadlines, US EPA combined sewer overflow mitigation enforcement schedules, and PLI scheme incentive utilization trajectories in Indian manufacturing corridors.
The model holds under stable copper-aluminum price spreads and consistent IEC 61439 enforcement intensity; deviation in tariff regimes or regulatory harmonization failures would shift supplier margin distribution and consolidation velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Panelboards Market
Electrical Equipment
Global General Purpose Contactor Market
Electrical Equipment
Electrical Enclosures Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
Medium Voltage Fuse Market
Electrical Equipment
Ceiling Fans Market
Electrical Equipment
Passover Humidifiers Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Global Electric Plugs and Sockets Market
Electrical Equipment
High-Speed Busbar Transfer Devices Market
Electrical Equipment
Electrical Steel Coatings Market
Electrical Equipment
Europe Electric Drives Market
Electrical Equipment
High Voltage Electric Capacitor Market
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
Laminated Busbar Market
Electrical Equipment
Global Cooling Fan Market