
 India Electrical Enclosures Market | 2026-2036
India Electrical Enclosures Market Size, Share, and Industry Trends Forecast 2026-2036
India Electrical Enclosures Market Insights
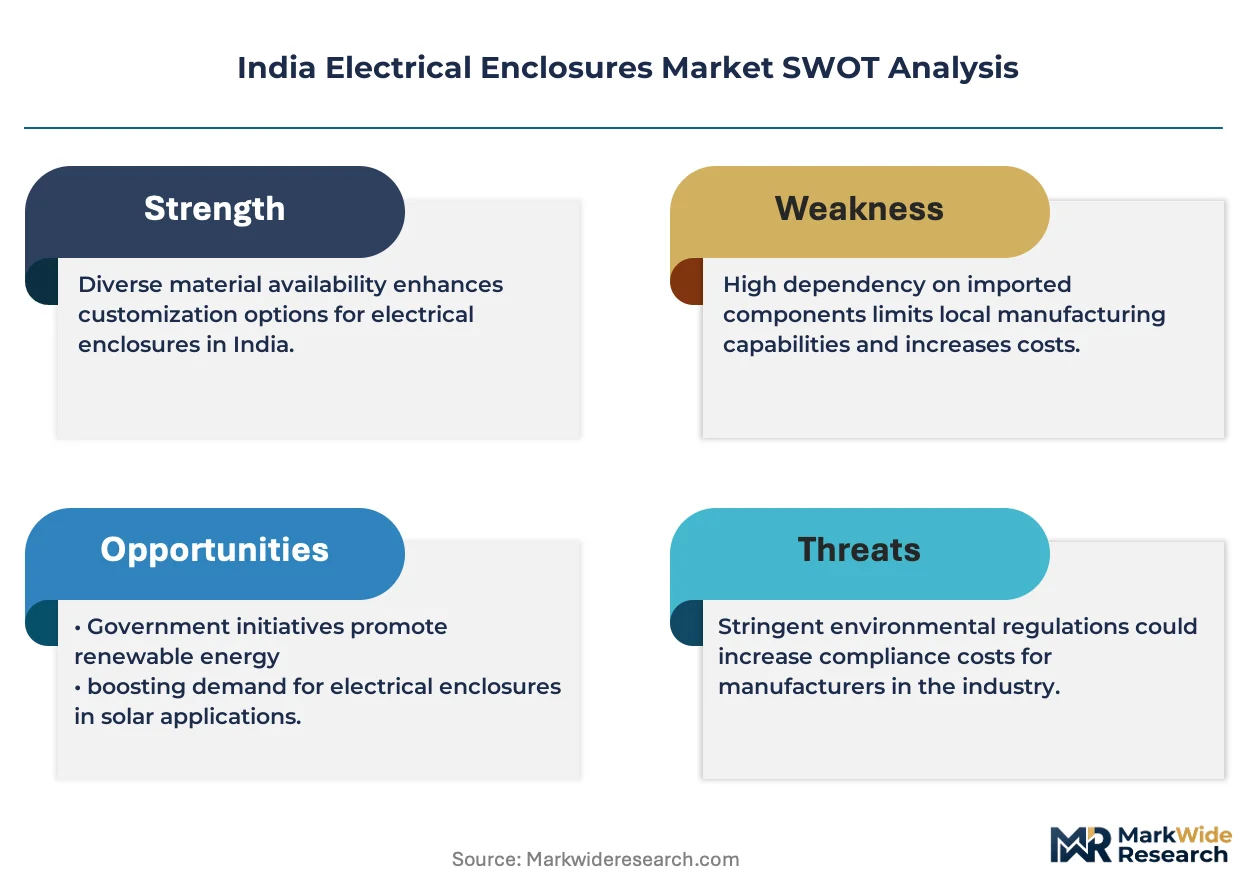
Renewable energy deployment is rebalancing the end-use vertical mix for electrical enclosures in India. Larsen and Toubro Limited anchors utility-scale solar and wind farm projects with heavy-duty floor-standing enclosures. Schneider Electric leverages its pan-India distribution network to sustain leadership in smart grid infrastructure. Siemens AG differentiates through IEC-certified product lines that meet stringent utility specifications.
An electrical enclosure is a protective housing fabricated from metal, plastic, or fiberglass composites, designed to shield electrical components from environmental contaminants, moisture, and mechanical impact while maintaining specified ingress protection ratings. Fabrication involves sheet metal stamping, powder coating, and gasket sealing to achieve IP55 or IP65 ratings for outdoor durability. Floor-standing and wall-mount enclosures dominate current volume, with rack-mount formats expanding fastest alongside data center buildouts. Metal enclosures command the largest share of material value, though polycarbonate alternatives are gaining traction in corrosive coastal zones where weight reduction matters.
Bureau of Indian Standards certification and Central Electricity Authority grid-connection norms shape product compliance requirements for enclosure manufacturers serving Indian utilities. The PLI scheme for domestic manufacturing intensifies cost competition while rewarding localized supply chains. Stakeholders must monitor evolving BIS amendments on fire-retardant enclosure materials and anticipate how state-level renewable purchase obligations will redirect procurement volumes toward outdoor-rated systems.
Market Dynamics
Hyperscale data center buildouts by cloud operators are compressing procurement cycles for rack-mount enclosures while tightening IP rating requirements for outdoor renewable installations reshape supplier qualification criteria.
Growth Catalysts
- PLI scheme incentives:Domestic manufacturing subsidies under India's Production Linked Incentive scheme reduce landed costs for metal enclosure fabricators serving utility-scale solar farms.
- CEA grid norms:Central Electricity Authority interconnection standards mandate outdoor-rated enclosures for renewable assets, accelerating replacement of legacy indoor systems.
- Maharashtra corridor concentration:Industrial clustering around Pune and Mumbai creates dense demand pools for floor-standing enclosures in automotive and pharmaceutical manufacturing facilities.
Market Restraints
- Steel price volatility:Cold-rolled steel input costs fluctuate with import duties and global commodity cycles, compressing fabrication margins for small-scale suppliers.
- BIS certification timelines:Bureau of Indian Standards testing protocols for fire-retardant materials extend product launch cycles by 4-6 months versus uncertified alternatives.
- Polycarbonate substitution:Coastal corrosion environments drive specification shifts toward fiberglass-reinforced polymer housings that bypass traditional metal fabrication channels.
Strategic Opportunities
- Tamil Nadu wind belt:Underpenetrated nacelle and substation enclosure demand in southern coastal districts offers first-mover positioning for IP66-certified suppliers.
- Smart metering rollout:State-level deployment mandates for advanced metering infrastructure create specialized demand for compact wall-mount housings with tamper-evident sealing.
- E-commerce channel emergence:Direct procurement platforms for MRO supplies enable mid-tier fabricators to bypass traditional distributor markups in tier-2 industrial cities.
Industry Challenges
- Skilled welder scarcity:Precision TIG welding for gasket-sealed enclosures faces labor pipeline constraints in Gujarat and Rajasthan manufacturing hubs.
- Legacy system integration:Retrofit projects require mechanical compatibility with decades-old switchgear footprints, constraining enclosure dimensional standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electrical Enclosures Market |
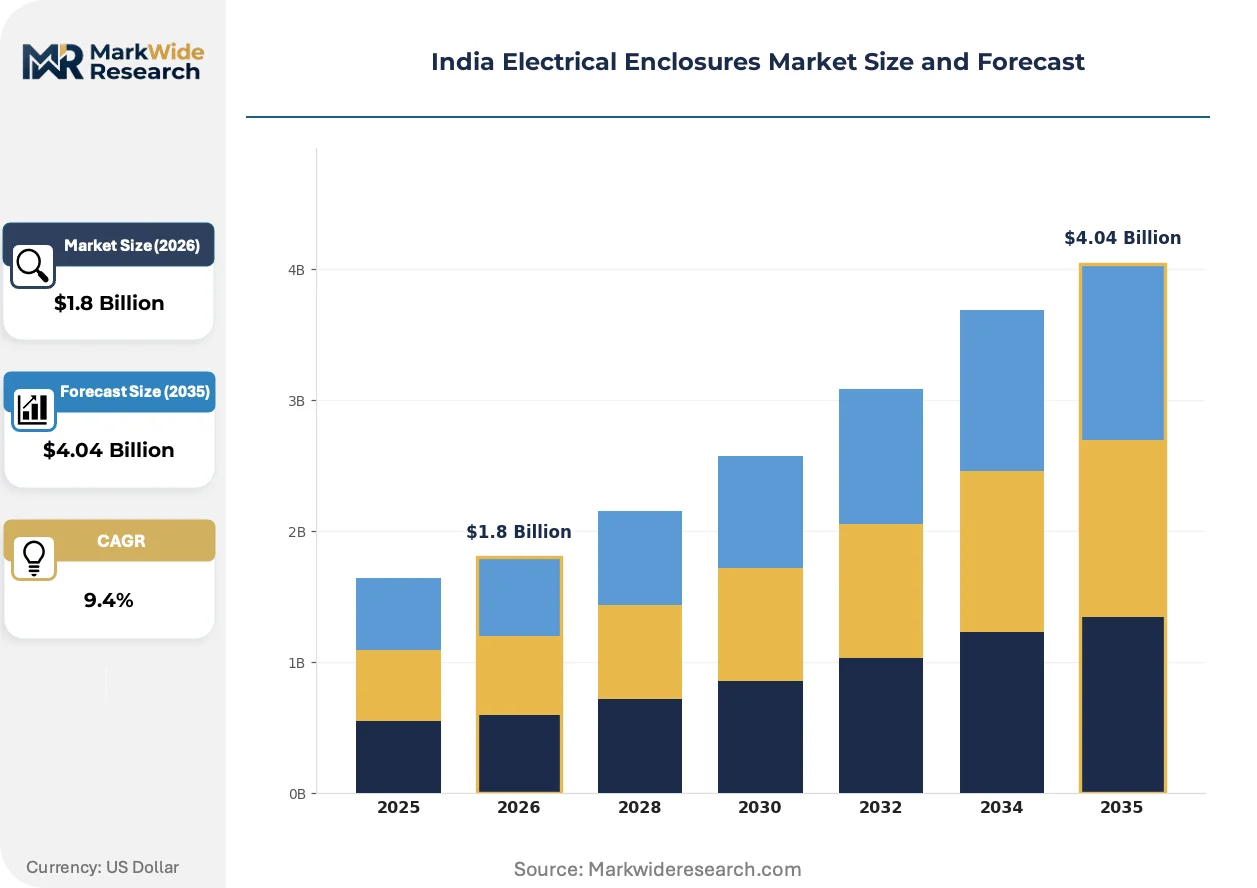
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Mount, Floor Standing, Rack Mount, Portable Material: Metal, Plastic, Fiberglass, Polycarbonate Application: Industrial Equipment, Telecommunications, Renewable Energy, HVAC End User: Manufacturing, IT & Telecom, Construction, Energy |
| Companies Covered | Eaton Corporation, Larsen and Toubro Limited, BCH Electric Ltd, Legrand SA, Siemens AG, Schneider Electric, Emerson Electric, Rittal GmbH and Co. KG, ABB Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electrical Enclosures Market Trends and Innovations
Material substitution and digital specification tools are compressing traditional procurement patterns while regulatory pressure on fire safety accelerates certification-driven supplier selection.
Modular busbar integration within floor-standing enclosures is consolidating power distribution architecture for data center operators. Hyperscale facilities in Hyderabad and Chennai specify factory-integrated busbar systems that eliminate field cable termination. This consolidation reduces installation labor by half and compresses commissioning timelines for cloud infrastructure deployments.
BIS amendments on fire-retardant enclosure materials entered force in late 2023, mandating UL94 V-0 compliance for indoor electrical housings above certain voltage thresholds. Fabricators serving commercial building segments must reformulate polycarbonate blends or source certified resins. Maharashtra and Karnataka state electrical inspectorates have begun field verification of material markings, accelerating supplier qualification audits.
Direct-to-factory specification platforms are displacing traditional distributor relationships for standardized enclosure SKUs. Maintenance teams at cement and steel plants in Chhattisgarh and Odisha now configure wall-mount dimensions through online portals. Channel disintermediation is most visible in mid-volume replacement procurement where lead time transparency outweighs technical consulting value.
India Electrical Enclosures Market Segmentation
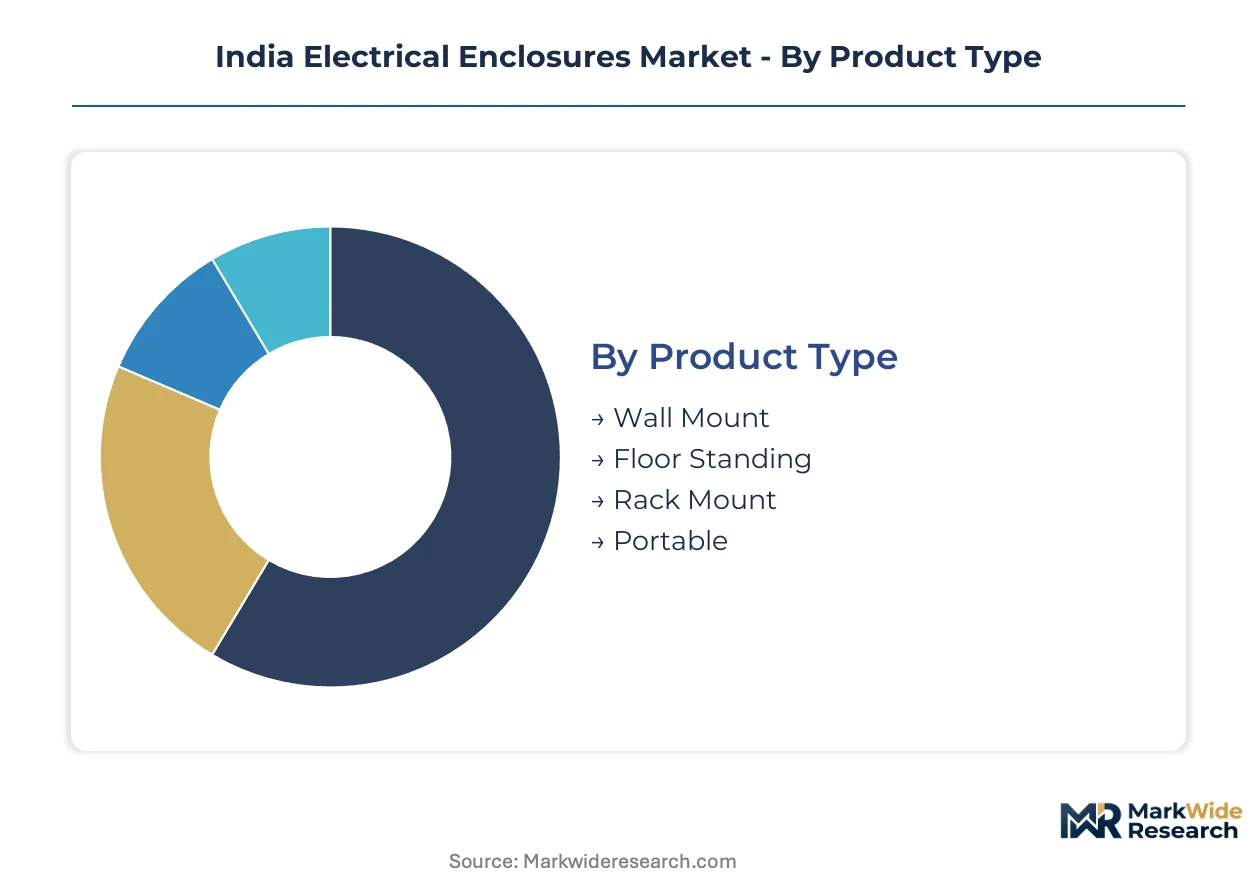
Electrical enclosure procurement in India diverges sharply by deployment environment and load-bearing requirements. Segment-specific capital commitments shape vendor qualification tiers and fabrication capacity allocation across the value chain.
Product Type:
Capital intensity varies most dramatically across enclosure formats, with floor-standing systems demanding the heaviest upfront tooling investment for structural welding and seismic bracing.
- Floor Standing:Heavy-gauge steel fabrication with integrated busbar channels and seismic anchoring systems serves utility-scale solar inverters and primary switchgear. Maharashtra's industrial corridor around Pune and Mumbai concentrates procurement for automotive and pharmaceutical manufacturing facilities where IP55-rated floor-standing units protect motor control centers.
- Wall Mount:Compact stamped-metal housings with hinged gasket-sealed doors dominate commercial building electrical distribution. Smart metering rollouts across Karnataka and Tamil Nadu accelerate demand for tamper-evident wall-mount enclosures with transparent polycarbonate windows for meter visibility.
- Rack Mount:Standardized 19-inch EIA rail compatibility supports server and networking equipment in hyperscale data centers. Hyderabad and Chennai cloud campuses specify factory-integrated cable management.
- Portable:Lightweight wheeled enclosures with quick-connect power inlets serve temporary construction site electrification and event infrastructure. Gujarat infrastructure projects drive seasonal procurement spikes.
Most installed capacity flows through Floor Standing. Expansion is steepest in Rack Mount.
Material:
Raw material selection determines corrosion resistance, weight constraints, and compliance pathways for specific deployment zones.
- Metal:Cold-rolled steel with epoxy powder coating commands the largest value share, though input cost volatility compresses fabrication margins. BIS-certified fire-retardant formulations now mandatory for indoor installations above specified voltage thresholds.
- Polycarbonate:UV-stabilized thermoplastic housings bypass coastal corrosion issues in Tamil Nadu and Kerala wind farm zones where salt spray degrades steel within months. Weight reduction enables easier nacelle installation.
- Fiberglass:Glass-reinforced polymer composites deliver dielectric isolation for substation environments with high electromagnetic interference. Chemical processing plants in Gujarat specify FRP for acid resistance.
- Plastic:ABS and PVC enclosures serve low-voltage indoor applications where cost minimization outweighs mechanical durability. Tier-2 city commercial construction drives volume.
Metal absorbs the bulk of current fabrication throughput. Polycarbonate is climbing the fastest as renewable deployment shifts toward coastal wind belts.
Application:
End-use verticals impose distinct thermal management, ingress protection, and integration specifications that reshape supplier qualification criteria.
- Renewable Energy:Outdoor-rated IP66 enclosures with active ventilation protect solar inverters and wind turbine power converters from dust ingress and monsoon moisture. CEA grid interconnection norms mandate these specifications for utility-scale asset connection.
- Industrial Equipment:Floor-standing NEMA-rated housings with integrated cooling fans serve motor control centers and variable frequency drives. Automotive OEMs in the Maharashtra corridor specify custom dimensions for production line integration.
- Telecommunications:Compact wall-mount and pole-mount enclosures with RF-transparent windows house base station power distribution. 5G small cell densification accelerates compact form factor demand.
- HVAC:Weatherproof disconnect housings and control panel enclosures for commercial building climate systems. Smart building retrofits in Bengaluru and Hyderabad drive replacement cycles.
Industrial Equipment retains the deepest installed base. Renewable Energy shows the steepest expansion trajectory as state-level renewable purchase obligations redirect procurement volumes.
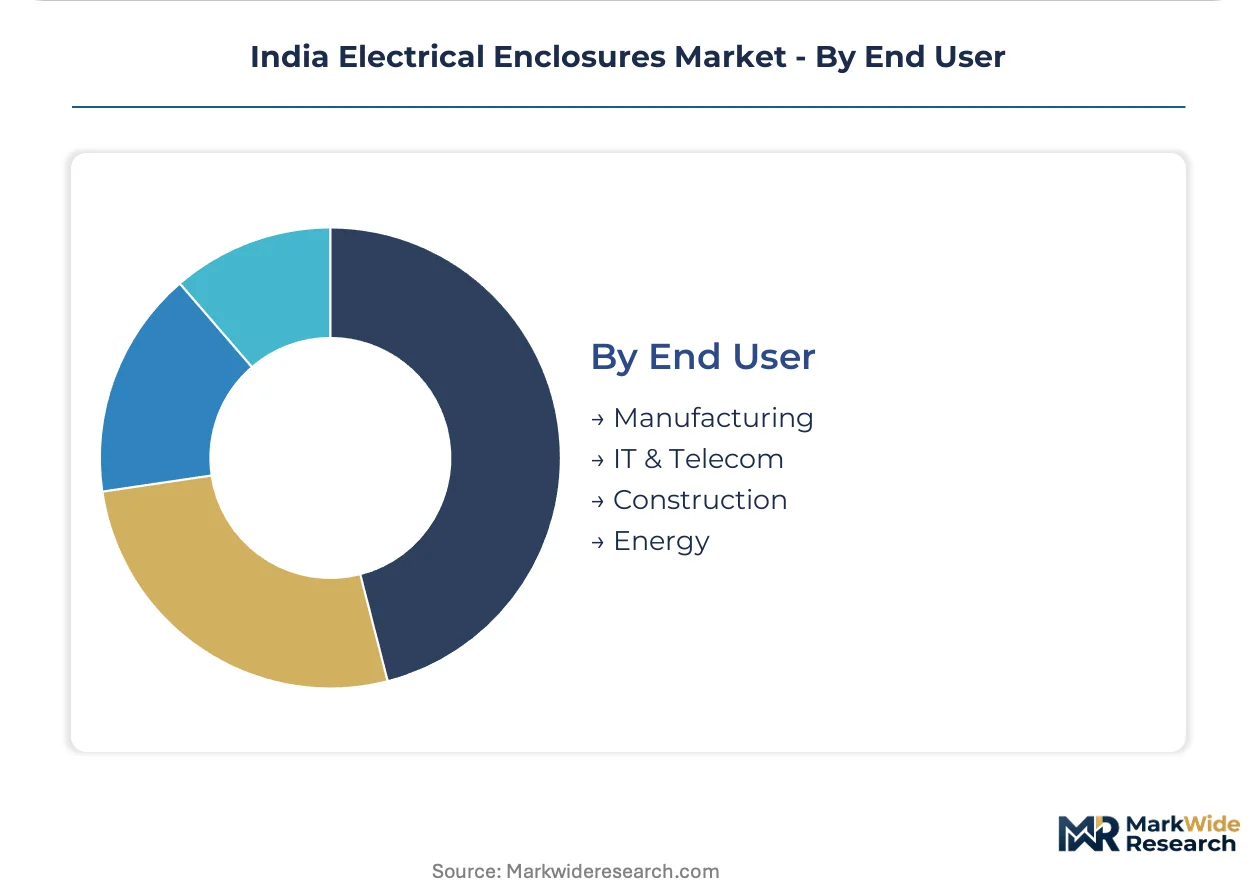
End User:
Customer procurement sophistication spans from specification-heavy utility tenders to price-sensitive MRO spot buying.
- Energy:Central and state utilities, plus independent power producers, enforce the most stringent BIS and CEA compliance requirements. Larsen and Toubro anchors utility-scale procurement through EPC bundling.
- Manufacturing:Automotive, pharmaceutical, and process industry buyers demand just-in-time delivery cadences and dimensional customization. Pune and Mumbai clusters create dense demand pools.
- IT & Telecom:Hyperscale cloud operators and tower companies compress procurement cycles with factory-integrated specifications. Direct-to-factory specification platforms displace traditional distributor relationships.
- Construction:Project-based procurement with high price elasticity and minimal technical specification. E-commerce MRO channels gain traction in tier-2 industrial cities.
Energy sector procurement absorbs the most certified fabrication capacity. IT & Telecom is expanding most quickly as data center buildouts compress equipment procurement timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between state electrical inspectorates are redirecting fabrication capacity toward jurisdictions with streamlined BIS certification pathways. Manufacturers migrate toward zones where CEA grid norms harmonize with local industrial policy. This regulatory arbitrage concentrates investment in states offering integrated testing facilities and PLI scheme disbursement efficiency.
Maharashtra
Automotive OEMs and pharmaceutical manufacturers in Pune and Mumbai drive dense demand for IP55-rated floor-standing enclosures. The state electrical inspectorate enforces BIS certification rigor that filters out uncertified imports. Larsen and Toubro anchors utility-scale procurement through bundled EPC contracts in this corridor.
Gujarat
Chemical processing clusters and port infrastructure projects generate seasonal spikes in corrosion-resistant enclosure demand. The state's industrial promotion schemes align with PLI scheme incentives for domestic metal fabrication. Skilled TIG welder scarcity constrains expansion in Ahmedabad and Vadodara manufacturing hubs despite order backlog.
Karnataka
Bengaluru's smart building retrofits and Hyderabad-adjacent data center spillover create dual demand tracks for wall-mount and rack-mount formats. State renewable purchase obligations redirect procurement toward outdoor-rated systems for solar parks in the northern districts. BIS fire-retardant material amendments face strict enforcement by Karnataka electrical inspectorates.
Tamil Nadu
Southern coastal wind belts generate underpenetrated demand for IP66-certified nacelle and substation enclosures. Salt spray degradation accelerates specification shifts toward polycarbonate alternatives in Tuticorin and Kanyakumari zones. The state distribution utility's smart metering rollout creates specialized demand for tamper-evident wall-mount housings.
Telangana
Hyderabad's hyperscale cloud campuses compress procurement cycles for factory-integrated rack-mount enclosures with modular busbar systems. Direct-to-factory specification platforms displace traditional distributor relationships among data center operators. CEA interconnection standards for captive renewable assets mandate outdoor-rated enclosures for campus microgrids.
India Electrical Enclosures Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with utility tenders favoring certified incumbents while industrial MRO channels absorb fragmented local supply. The vendor base stratifies into three tiers: multinational electrical majors with pan-India distribution, domestic integrated fabricators with EPC bundling capability, and regional stampers serving price-sensitive replacement demand. Two dominant competitive moves are reshaping positioning: backward integration into cold-rolled steel processing to hedge input volatility, and technology licensing partnerships for smart enclosure monitoring systems.
Among diversified electrical majors, Schneider Electric and Siemens AG exemplify the certification-driven tier that dominates utility and data center procurement through IEC-compliant product lines. Larsen and Toubro Limited occupies a distinct position as a domestic integrated player bundling enclosure supply with utility-scale EPC execution. These three anchors illustrate how competitive advantage in this market derives from regulatory compliance depth rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Eaton Corporation |
| Larsen and Toubro Limited |
| BCH Electric Ltd |
| Legrand SA |
| Siemens AG |
| Schneider Electric |
| Emerson Electric |
| Rittal GmbH and Co. KG |
| ABB Ltd |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap fabricators clustered in Gujarat and Maharashtra maintain pricing discipline through captive relationships with cold-rolled steel distributors, insulating them from spot-market volatility that erodes margins at smaller stampers serving construction MRO channels.
Pricing Analysis
Distributor markups of 18-22 percent on imported IEC-certified enclosures compress margin capture for domestic fabricators competing against Schneider Electric and Siemens AG direct sales teams. Three-tier pricing structure across premium certified, standard BIS-compliant, and economy non-certified levels segments buyer pools, with state utilities least price-sensitive due to EPC bundling while construction contractors drive aggressive spot-market negotiation. Cost compression in the economy tier is intensifying because polycarbonate substitution bypasses traditional metal fabrication channels entirely.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale data center demand in Hyderabad and Chennai, while distributor networks dominate tier-2 industrial city procurement for replacement floor-standing units. Raw material sourcing draws from domestic cold-rolled steel mills in Jharkhand and Odisha, supplemented by Korean and Japanese specialty-grade imports for gasket-sealed precision enclosures. Single-source vulnerability concentrates in BIS-certified fire-retardant resin formulations, where reformulation timelines extend product launch cycles. Distribution runs through regional electrical wholesalers in Pune, Ahmedabad, and Bengaluru who maintain field inventory for just-in-time delivery to automotive and pharmaceutical manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Maharashtra's high-compliance, high-margin utility corridor and Tamil Nadu's underpenetrated coastal wind belt where certification requirements are tightening but enforcement lags 12-18 months behind western states.
For Market Incumbents: Deepen backward integration into cold-rolled steel processing to hedge against import duty volatility and global commodity cycles compressing fabrication margins. Anchor certification investment in BIS fire-retardant material compliance ahead of state electrical inspectorate enforcement waves, while building captive TIG welding training pipelines in Gujarat and Rajasthan to offset skilled labor scarcity threatening expansion timelines. For New Entrants and Emerging Players: E-commerce MRO platforms offer the most penetrable route for mid-tier fabricators to bypass traditional distributor markups in tier-2 industrial cities like Nagpur, Indore, and Coimbatore. Target tamper-evident wall-mount enclosures for Karnataka and Tamil Nadu smart metering rollouts where state mandates create demand visibility without requiring deep utility EPC relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional stampers with BIS certification capability but no EPC bundling relationships, offering bolt-on acquisition targets for incumbents seeking Maharashtra corridor density. The long-term viability window favors suppliers with demonstrated CEA grid norm compliance as renewable purchase obligations redirect procurement volumes toward outdoor-rated systems. Watch for BIS amendment enforcement consistency across state electrical inspectorates as the inflection signal for certification-premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Processing | Captive cold-rolled steel supply hedges Gujarat and Maharashtra fabricators against import duty volatility. |
| BIS Fire-Retardant Certification Investment | UL94 V-0 compliance ahead of state enforcement waves secures premium positioning in commercial building segments. |
| Direct-to-Factory Specification Platform Launch | Channel disintermediation captures maintenance procurement from cement and steel plants in Chhattisgarh and Odisha. |
| Modular Busbar System Integration | Factory-integrated power distribution halves installation labor for Hyderabad and Chennai hyperscale data centers. |
| Tamil Nadu Wind Belt Market Entry | First-mover IP66 certification for nacelle enclosures captures underpenetrated demand in Tuticorin coastal zones. |
Research Methodology
Direct dialogue with enclosure fabrication plant managers, utility EPC procurement leads, state electrical inspectorate officials, and distributor channel partners grounded qualitative findings, cross-referenced against BIS certification databases, CEA grid interconnection filings, PLI scheme disbursement records, and customs trade data for cold-rolled steel and polycarbonate resin imports. Bottom-up demand modeling from state-level renewable purchase obligations and top-down market sizing from industrial electrical equipment capex disclosures were triangulated to constrain projection variance.
Segment-level value outputs across the projection horizon reflect discrete modeling of floor-standing, wall-mount, rack-mount, and portable formats by material type and end-use vertical, with CAGRs derived from regression against historical utility-scale solar and wind deployment trajectories. Key inputs included hyperscale data center construction timelines from cloud operator infrastructure disclosures and smart metering rollout schedules from state distribution utility procurement notices.
The model assumes a particular technology adoption path for polycarbonate and fiberglass-reinforced polymer substitution in coastal corrosion environments; alternative pathways for metal alloy surface treatment advancement would alter the outlook for material segment shares. Forecasts reflect assumptions on BIS enforcement consistency and PLI scheme continuity that regulatory amendment or administrative delay could materially revise. Periodic stress-testing of base assumptions against quarterly state utility procurement data and steel import duty notifications is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Smart Fan Market
Electrical Equipment
US Industrial Ceiling Fan Market
Electrical Equipment
Asia-Pacific Electrical Bushing Market
Electrical Equipment
Electrical Resistor Market
Electrical Equipment
Flexible Heating Element Market
Electrical Equipment
Global Panelboards Market
Electrical Equipment
Low Voltage Electric Motor Market
Electrical Equipment
Smart Heater Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
Low Voltage Motor Control Centers Market
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
Europe Busbar Market
Electrical Equipment
Global Dehumidifier Market
Electrical Equipment
Magnetic Shielding Device Market
Electrical Equipment
Asia-Pacific Vacuum Circuit Breakers Market
Electrical Equipment
Voltage Transformer Market