
 Autonomous Bus Market | 2026-2036
Autonomous Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Bus Market Analysis
A shift from single-source sensor contracts to multi-source LiDAR-computer vision packages is repositioning how tier-one suppliers contract with OEMs. Yutong Bus Co. Ltd. leverages captive manufacturing in Zhengzhou to control module costs. Navya SAS anchors European deployment through its Lyon-based validation center. AB Volvo competes by integrating its proprietary drive platform with external perception stacks.
An autonomous bus is a self-driving commercial passenger vehicle operating at SAE Level-4 autonomy or higher, typically incorporating redundant LiDAR arrays, stereo camera clusters, and edge-computing units processing real-time obstacle classification at sub-50-millisecond latency; its primary purpose is to deliver fixed-route or on-demand mobility without a human safety driver. Electric platforms within the Vehicle Type segment command the deepest capital commitment from municipal buyers due to overlapping decarbonization mandates. LiDAR-based Technology configurations lead unit economics while Computer Vision alternatives gain share in constrained campus environments where geofencing reduces sensor complexity.
The EU AI Act imposes conformity requirements on algorithmic decision-making in public transport, while the U.S. NHTSA maintains exemption thresholds for low-speed automated shuttle deployments that shape pilot scalability. Germany's KBA and France's ANSM enforce divergent homologation timelines, fragmenting go-to-market cadence for cross-border operators. Stakeholders must track which regulator first mandates fail-operational braking as a baseline requirement, as this standard will cascade through procurement specifications faster than technology readiness alone.
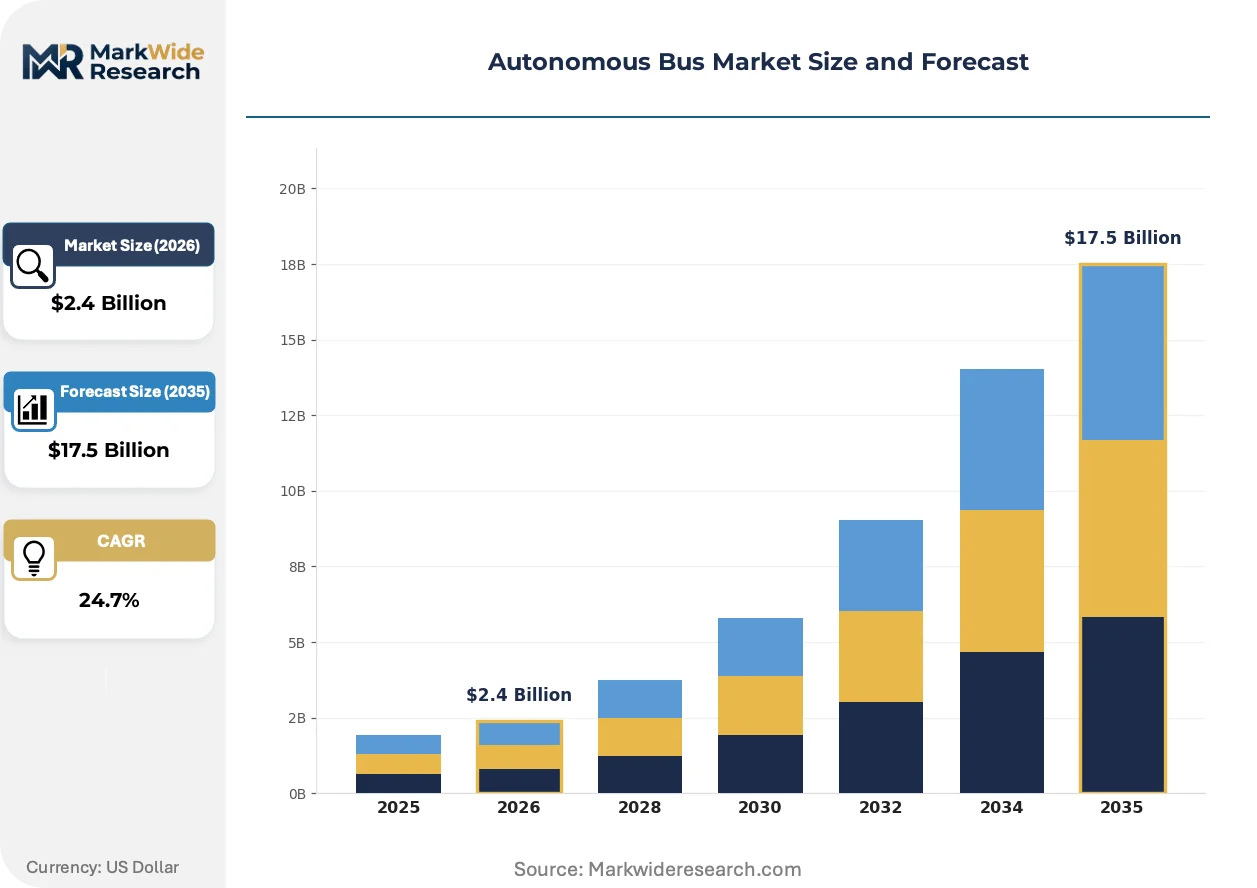
Market Dynamics
Driver shortages across European municipal transit systems are compressing procurement timelines and forcing authorities to accelerate Level-4 pilot programs before full regulatory frameworks mature.
Growth Catalysts
- EU AI Act Conformity Pathways:The regulation establishes algorithmic transparency requirements for public transport decision-making, creating certification clarity that reduces procurement risk for transit agencies evaluating autonomous platforms.
- Electric-Autonomous Fleet Bundling:German federal transit authorities are consolidating electric drivetrain and autonomous system procurement into single tender packages, lowering integration costs for municipal buyers.
- LiDAR-Computer Vision Fusion:Multi-source sensor architectures are replacing single-source contracts, enabling tier-one suppliers to offer redundant perception stacks that satisfy fail-operational requirements without proprietary lock-in.
Market Restraints
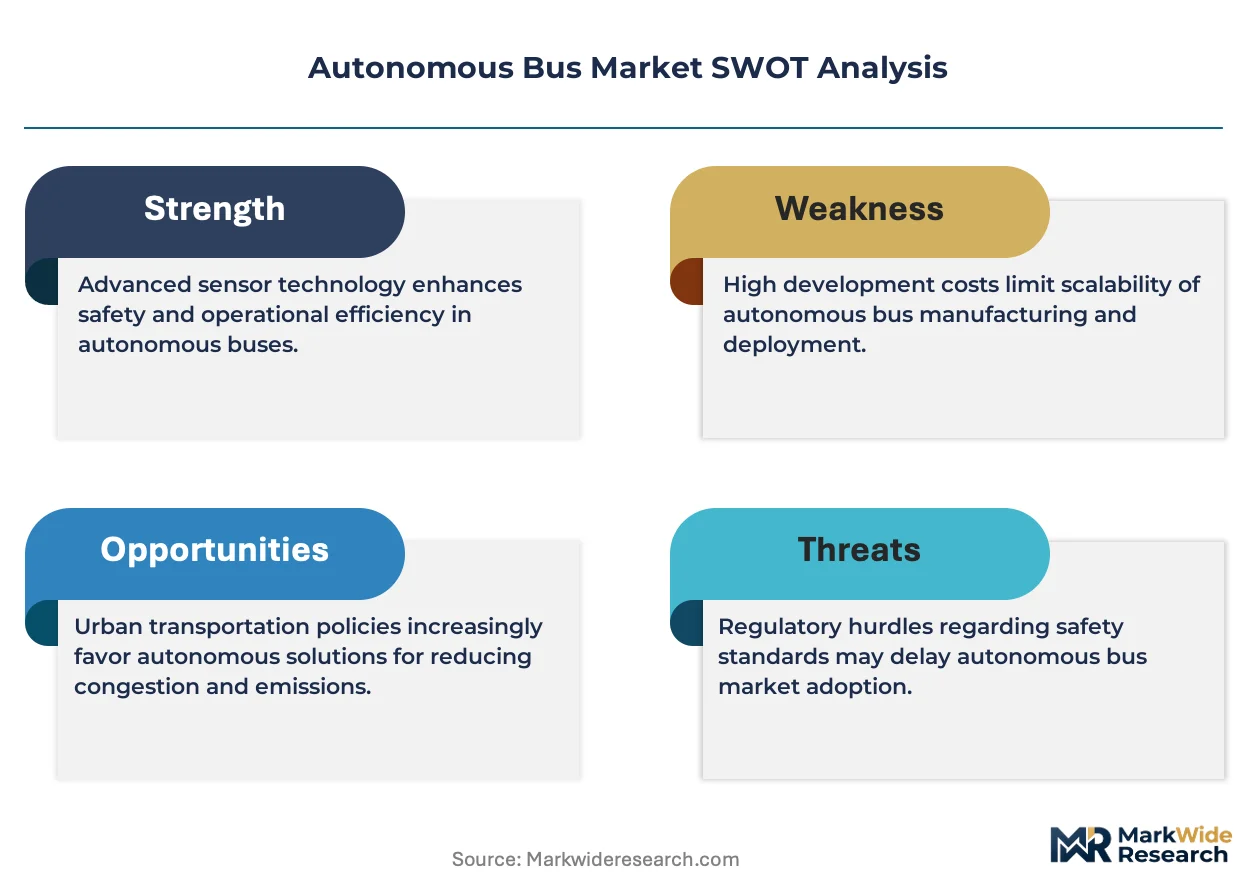
- Homologation Fragmentation:Germany's KBA and France's ANSM enforce divergent type-approval timelines for Level-4 platforms, forcing cross-border operators to maintain parallel certification tracks that extend time-to-revenue.
- LiDAR Supply Concentration:Critical sensor modules depend on a narrow base of precision optics manufacturers concentrated in East Asian production clusters, exposing fleet operators to input volatility and extended lead times.
- Campus-to-Urban Capability Gap:Geofenced shuttle deployments operate within constrained operational design domains that do not transfer to complex mixed-traffic environments, limiting revenue scalability beyond controlled environments.
Strategic Opportunities
- On-Demand Microtransit Integration:Autonomous buses configured for dynamic routing rather than fixed schedules can capture first-last-mile trips currently served by ride-hailing platforms, with Nordic municipalities piloting app-based hailing for rural corridors.
- Fail-Operational Braking Mandates:The first regulator to mandate redundant braking as baseline procurement specification will cascade this standard across European tender documents faster than technology readiness alone, creating first-mover advantage for certified suppliers.
- Edge-Computing Latency Compression:Sub-50-millisecond obstacle classification at the vehicle level is enabling removal of remote operator oversight in designated zones, reducing per-vehicle operating costs for fleet-scale deployments.
Industry Challenges
- Safety Driver Transition:Remote monitoring center staffing requires retrained personnel capable of interpreting multi-sensor fusion outputs under latency constraints, creating a skills gap that outpaces vocational training program development.
- Legacy Fleet Integration:Autonomous platforms must interoperate with existing depot maintenance systems, passenger information displays, and fare collection infrastructure originally designed for human-operated vehicles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Bus Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $17.5 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Electric, Hybrid, Fuel Cell, Conventional Technology: LiDAR, Computer Vision, GPS Navigation, V2X Communication End User: Public Transport Authorities, Private Operators, Educational Institutions, Corporate Shuttles Application: Urban Transit, Campus Transportation, Intercity Travel, Shuttle Services |
| Companies Covered | Yutong Bus Co. Ltd., Navya SAS, AB Volvo, Alexander Dennis Limited, EasyMile, Daimler Truck, Proterra Inc., NFI Group Inc., BYD Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Bus Market Emerging Trajectories
Sensor fusion architectures and regulatory sandbox programs are simultaneously expanding operational design domains and compressing certification cycles for urban deployment.
Multi-source LiDAR-computer vision packages are automating real-time obstacle classification at sub-50-millisecond latency. Municipal transit authorities in Germany and France are specifying these redundant perception stacks in tender documents. The technology is automating the transition from safety-driver-present pilots to fully unattended revenue service in geofenced districts.
The EU AI Act imposes conformity assessment requirements on algorithmic decision-making in public transport applications. Industrial consequence includes mandatory documentation of training data provenance and decision audit trails for collision-avoidance systems. Level-4 platform developers targeting European deployment are restructuring engineering workflows to satisfy these transparency mandates before type-approval submission.
Fixed-route procurement models face displacement by outcome-based service contracts where operators guarantee availability and passenger throughput rather than vehicle supply. Transit authorities in the Netherlands and Sweden are piloting these performance-guarantee structures for suburban feeder lines. This shift concentrates risk with technology providers and favors vertically integrated suppliers capable of controlling both platform reliability and fleet maintenance costs.
Autonomous Bus Market Segmentation
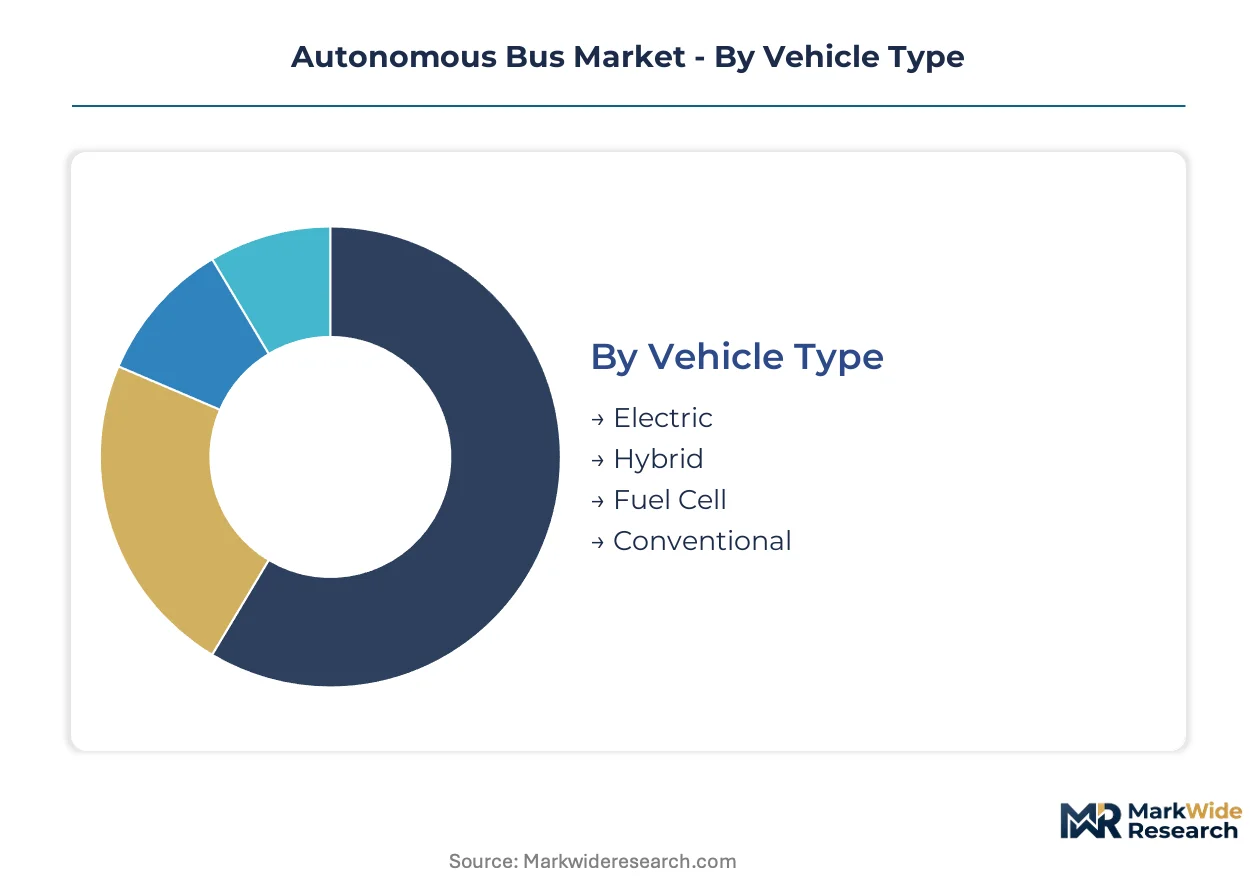
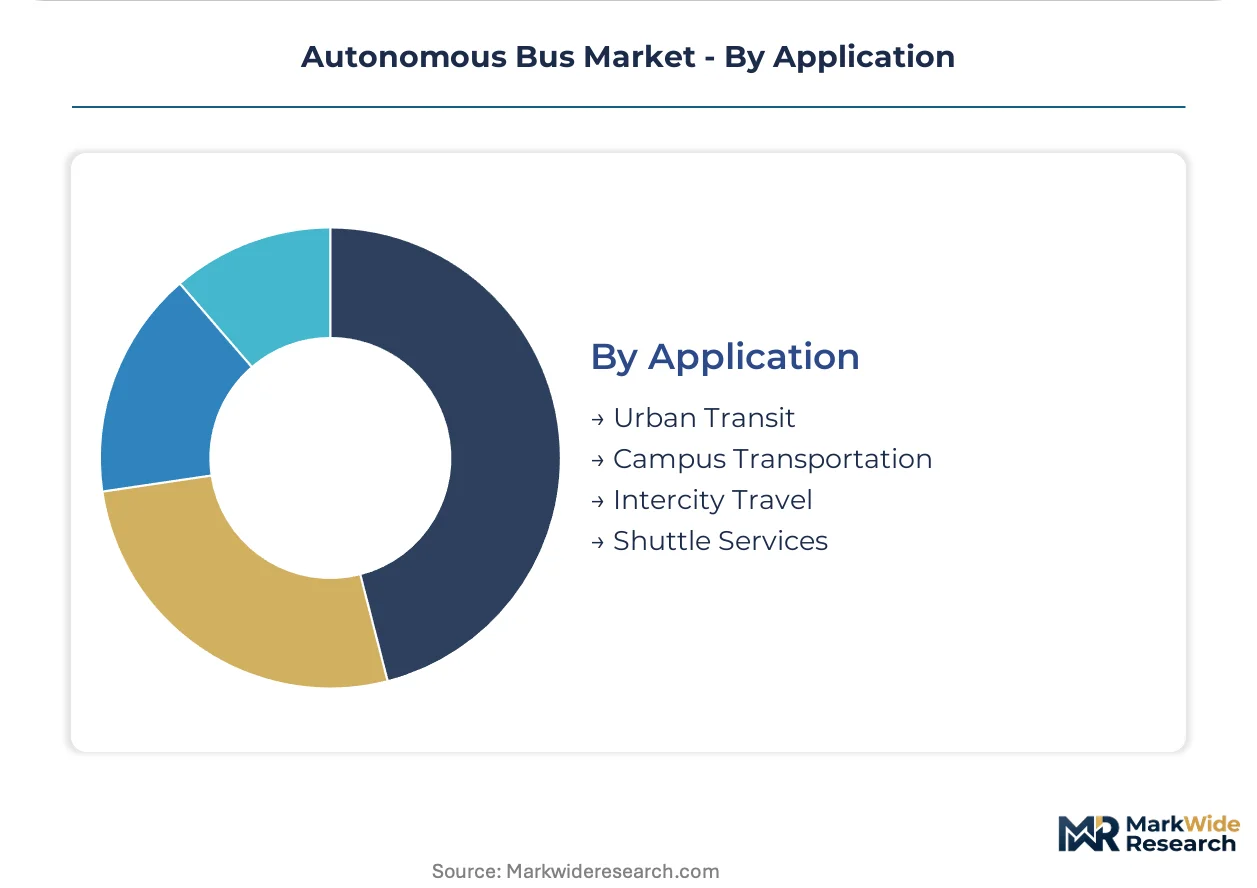
Autonomous bus segmentation reveals how certification burdens distribute unevenly across platform architectures. Municipal procurement teams weight electric drivetrains and LiDAR perception stacks differently depending on operational design domain complexity.
Vehicle Type:
Electric platforms face the heaviest conformity assessment under EU battery-safety directives, while fuel cell variants navigate hydrogen storage certifications that extend homologation timelines.
- Electric:Battery-electric architectures integrate high-voltage systems requiring ECE R100 compliance alongside autonomous function validation. German federal transit agencies bundle these platforms into consolidated tenders that lower total cost of ownership across depot charging infrastructure.
- Hybrid:Dual-powertrain configurations offer operational flexibility where charging infrastructure remains sparse. Demand concentrates in French regional networks where ANSM permits intermediate certification stages during fleet transition periods.
- Fuel Cell:Hydrogen fuel cell platforms carry additional pressure-vessel certification requirements under UN ECE R134 that complicate cross-border deployment.
- Conventional:Internal combustion variants retain niche demand for rapid pilot deployment where electric infrastructure lags.
Electric sits at the top of the volume ranking, with Fuel Cell climbing the fastest as hydrogen corridor investments mature.
Technology:
Perception system selection determines whether platforms qualify for unattended operation or retain remote oversight requirements.
- LiDAR:Solid-state and mechanical LiDAR arrays deliver centimeter-range precision for obstacle detection in mixed-traffic environments. Procurement specifications in the Netherlands mandate redundant LiDAR configurations for urban transit routes exceeding 50 km/h operational speeds.
- Computer Vision:Stereo camera clusters process visual data at lower unit cost, enabling campus shuttle deployments where geofencing reduces sensor complexity. Swedish municipalities specify these systems for controlled-access environments with predictable pedestrian patterns.
- GPS Navigation:High-precision positioning supplements perception stacks in corridor-based deployments with dedicated right-of-way.
- V2X Communication:Vehicle-to-everything protocols enable cooperative perception at intersections but require infrastructure-side deployment that fragments procurement decisions between fleet operators and road authorities.
LiDAR dominates current procurement volumes, with V2X gaining share fastest where smart corridor investments precede fleet deployment.
End User:
Buyer type shapes contract structures from capital purchase to availability-based service agreements.
- Public Transport Authorities:Municipal and regional transit agencies specify fail-operational braking and redundant perception as baseline procurement requirements. Bundled electric-autonomous tenders in Germany concentrate demand among vertically integrated suppliers capable of meeting KBA type-approval timelines.
- Private Operators:Commercial fleet managers prioritize rapid deployment over full regulatory compliance, accepting remote oversight models that accelerate revenue service.
- Educational Institutions:University campuses operate under simplified exemption frameworks that reduce sensor redundancy requirements.
- Corporate Shuttles:Private campus networks specify passenger experience metrics including ride smoothness and information system integration over raw autonomy capability.
Public Transport Authorities anchor procurement volumes, with Corporate Shuttles expanding most quickly as employer-sponsored mobility programs proliferate.
Application:
Operational design domain complexity determines which technology configurations satisfy safety case requirements.
- Urban Transit:Mixed-traffic operation with unprotected left turns and dense pedestrian interaction demands full LiDAR-computer vision fusion. French and German regulators apply divergent test-scenario requirements that fragment platform certification for cross-border routes.
- Campus Transportation:Controlled-access environments with dedicated lanes and gated crossings enable reduced sensor configurations. Nordic educational institutions pilot these deployments under simplified national exemption frameworks.
- Intercity Travel:Higher-speed operation on dedicated corridors introduces new validation requirements for lane-keeping precision and emergency stopping distances.
- Shuttle Services:First-last-mile feeder routes combine dynamic routing with fixed infrastructure, requiring interoperability between autonomous platforms and conventional transit scheduling systems.
Urban Transit commands the steepest investment commitment, with Shuttle Services gaining share fastest as microtransit integration models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting autonomous bus platform development toward jurisdictions offering streamlined type-approval pathways. Compliance cost differentials between national homologation regimes are reshaping where validation centers and pilot fleets concentrate.
Germany
Federal transit agencies are bundling electric-autonomous procurement into consolidated tenders that lower integration costs for municipal buyers. The KBA enforces fail-operational braking requirements that cascade through cross-border tender specifications. Munich and Stuttgart host validation partnerships between OEMs and tier-one perception stack suppliers.
France
ANSM permits intermediate certification stages that accelerate fleet transition periods for regional network operators. The EU AI Act conformity pathways reduce procurement risk for transit agencies evaluating algorithmic decision-making platforms. Lyon anchors European deployment through Navya SAS and its validation center infrastructure.
Netherlands
Rotterdam and Amsterdam specify redundant LiDAR configurations for urban transit routes exceeding operational speed thresholds. Outcome-based service contracts are displacing fixed-route procurement models for suburban feeder lines. Dutch municipalities pilot performance-guarantee structures that concentrate risk with technology providers.
Sweden
Nordic municipalities are piloting app-based hailing for rural corridor microtransit integration. Simplified national exemption frameworks enable reduced sensor configurations in controlled-access campus environments. Stockholm and Gothenburg test dynamic routing platforms for first-last-mile connectivity.
United States
NHTSA exemption thresholds for low-speed automated shuttle deployments shape pilot scalability in university and corporate campus networks. State-level regulatory sandboxes in California and Arizona compress deployment timelines for geofenced districts. Remote operator oversight models accelerate revenue service ahead of full federal compliance.
Autonomous Bus Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue campus-to-urban capability expansion and sensor fusion specialization. The vendor base stratifies across vertically integrated platform developers, perception stack specialists, and electric drivetrain converters. Three archetypes dominate: captive manufacturers controlling module costs, validation-centric European deployers, and integrated drive-platform engineers. Competitive moves concentrate on multi-source sensor contracting and bundled electric-autonomous tender participation.
Within the captive manufacturing tier, Yutong Bus Co. Ltd. exemplifies upstream control over production economics. Navya SAS and AB Volvo occupy positions as European validation anchors and integrated platform developers respectively. These three entities represent divergent strategic postures: Zhengzhou-based scale fabrication, Lyon-centered regulatory navigation, and Gothenburg-originated drive-system integration.
| Leading Market Players |
|---|
| Yutong Bus Co. Ltd. |
| Navya SAS |
| AB Volvo |
| Alexander Dennis Limited |
| EasyMile |
| Daimler Truck |
| Proterra Inc. |
| NFI Group Inc. |
| BYD Company Limited |
| Others |
Supply Flow & Price Mechanics
Fail-operational certification tiers bifurcate autonomous bus procurement into premium LiDAR-fusion platforms and cost-optimized computer vision alternatives, with German KBA requirements compressing margins on entry-level configurations while bundling electric-autonomous tenders concentrates buyer leverage in multi-year contracts. This tier divergence manifests in divergent supplier sourcing strategies: premium platforms draw from redundant East Asian sensor arrays while constrained-campus deployments source lower-complexity modules from regional integrators.
Pricing Analysis
Distributor margins on LiDAR modules absorb 12-18 percent of landed sensor costs before OEM integration, compressing effective procurement budgets for municipal buyers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling, with fail-operational braking mandates commanding 35-40 percent premiums over remote-oversight alternatives. Pricing pressure stems from LiDAR supply concentration in Taiwanese and Chinese production clusters, exposing fleet operators to input volatility. Public transport authorities exhibit highest price sensitivity due to consolidated tender structures, while corporate shuttle buyers prioritize passenger experience metrics over unit economics.
Supply Chain Analysis
KBA and ANSM certification gating fragments component qualification timelines, forcing tier-one suppliers to maintain parallel validation tracks for cross-border deployment. Solid-state LiDAR arrays, high-voltage battery management systems, and edge-computing units draw from concentrated manufacturing bases in China, South Korea, and Germany. Single-source vulnerability in precision optics exposes procurement timelines to extended lead time volatility. Distribution runs through OEM-direct contracts for municipal fleet operators and systems integrators for campus shuttle deployers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate where ANSM intermediate certification stages accelerate revenue service 18-24 months ahead of KBA fail-operational mandates, compressing payback periods for early movers in French regional networks.
For Market Incumbents: To counter margin compression from bundled electric-autonomous tenders, Yutong and Volvo must deepen backward integration into captive LiDAR module production and establish validation partnerships in Lyon to capture ANSM pathway advantages. Certification investment in redundant braking architectures secures first-mover positioning before mandates cascade through procurement specifications. For New Entrants and Emerging Players: Capture rural corridor microtransit deployments in Nordic municipalities where simplified exemption frameworks reduce sensor redundancy requirements and app-based hailing models displace fixed-route procurement. Campus transportation segments offer lowest certification barriers with predictable operational design domains and gated pedestrian patterns. For Investors and Strategic Acquirers: Consolidation pressure builds where LiDAR-computer vision fusion capabilities concentrate among perception stack specialists lacking electric drivetrain integration. Long-term viability favors vertically integrated platform developers controlling both autonomous function validation and fleet maintenance cost structures. Watch for the first regulator mandating fail-operational braking as baseline procurement specification, which will trigger rapid standardization across European tender documents.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Sensor Contracting | Redundant LiDAR-computer vision packages reduce proprietary lock-in for municipal buyers. |
| Electric-Autonomous Bundling | German federal tenders consolidate drivetrain and autonomy procurement into single packages. |
| Validation Center Partnership | Lyon-based facilities accelerate ANSM certification timelines for cross-border operators. |
| Fail-Operational Braking Certification | KBA mandates cascade through procurement specifications faster than technology readiness. |
| Edge-Computing Latency Reduction | Sub-50-millisecond obstacle classification enables removal of remote operator oversight. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with transit authority procurement directors, tier-one supplier platform engineers, KBA homologation specialists, and municipal fleet maintenance heads with secondary validation against EU AI Act implementation documents, NHTSA exemption filings, and national transit procurement databases. Bottom-up fleet deployment tracking and top-down regulatory pathway analysis were triangulated against electric-autonomous tender announcements.
Comparable-period anchoring linked projection assumptions to historical pilot fleet deployment rates and certification timeline precedents across the modeling period. Segmentation dimensions modeled include vehicle type, perception technology configuration, operational design domain complexity, and buyer procurement structure. CAGRs were derived from deployment trajectory analysis incorporating driver shortage severity indices and regulatory sandbox expansion schedules.
Regulatory mandate delays, LiDAR supply disruptions, and campus-to-urban capability transfer failures are the dominant revision risks to deployment forecasts. A model refresh is warranted upon material change in EU AI Act enforcement timelines or KBA fail-operational braking mandate announcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Vehicle ECU Market
Autonomous Vehicles
Europe IoT Connected Cars Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) System Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
Driverless Cab Service Market
Autonomous Vehicles
Germany Autonomous Navigation Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Autonomous Truck Technology Market
Autonomous Vehicles
China Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicle Sensor Market
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
Global Autonomous Trucks Market
Autonomous Vehicles
Middle East and Africa Automated Guided Vehicles Market