
 Wicketed Bags Market | 2026-2036
Wicketed Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Wicketed Bags Market Intelligence
High-clarity food-grade specification tiers is collapsing the distinction between commodity and premium wicketed bag offerings. Sun Packaging Technologies, Inc. leverages vertical integration across blown film extrusion and wicketed conversion to control specification consistency. Maco PKG anchors its position through specialized high-speed wicket printing capabilities for retail-ready applications. St. Johns Packaging competes on geographic dominance, operating manufacturing footprints that span multiple North American distribution corridors.
Wicketed bags are pre-opened, stacked polyethylene or polypropylene film enclosures mounted on metal wickets for automated dispensing, typically featuring bottom seals and side gussets to accommodate volume expansion during high-speed filling operations. Gusseted bags and flat bags represent the core product architecture, with gusseted configurations capturing premium positioning due to expanded cubic capacity for irregular produce and bakery items. Polyethylene dominates material throughput given its cost-performance balance in moisture barrier applications, while biodegradable films represent the fastest-growing material trajectory as compostability mandates intensify across food industry supply chains.
The FDA regulates food-contact substances under 21 CFR, directly shaping resin selection and additive packages for wicketed bags serving the food industry, while EPA guidelines on plastic waste streams influence recyclability labeling and post-consumer content claims. ISO 22000 food safety management standards and ASTM D882 tensile property specifications further define quality thresholds for film gauge and seal integrity. Stakeholders must monitor how evolving extended producer responsibility frameworks in multiple states reshape material specifications and regional manufacturing requirements.
Market Dynamics
Food industry packaging automation is collapsing the distinction between commodity and premium wicketed bag tiers as high-speed bakery and produce operations demand specification consistency across automated filling lines. FDA food-contact material requirements under 21 CFR are simultaneously reshaping resin selection and additive packages, forcing converters to requalify film formulations.
Growth Catalysts
- Automation penetration:High-speed bakery and produce filling lines require pre-opened wicketed bags for robotic dispensing, converting manual operations to automated throughput.
- Extended producer responsibility frameworks:Multiple US state mandates on post-consumer content claims and recyclability labeling are accelerating demand for certified recyclable polyethylene films.
- Compostability mandates:Food industry supply chain requirements for biodegradable packaging are pulling biodegradable film formulations into wicketed bag specifications.
Market Restraints
- Resin price volatility:Polyethylene feedstock costs tied to ethylene cracking economics create margin compression for converters without backward integration into blown film extrusion.
- Supply concentration:Blown film extrusion capacity clusters in the US Gulf Coast and Midwest, creating geographic vulnerability to weather-related production disruptions.
- Technical limitation:Biodegradable films currently exhibit inferior moisture barrier performance versus polyethylene, restricting their deployment in high-humidity produce applications.
Strategic Opportunities
- Underpenetrated foodservice:Automated quick-service restaurant back-of-house operations in the United States remain underpenetrated for wicketed bag dispensing systems.
- Regulatory tailwind:The EPA's evolving plastic waste stream guidelines create first-mover advantage for converters with verified post-industrial and post-consumer content certification.
- Technology convergence:Integration of inline printing with high-speed wicket conversion enables retail-ready packaging with variable data and brand differentiation.
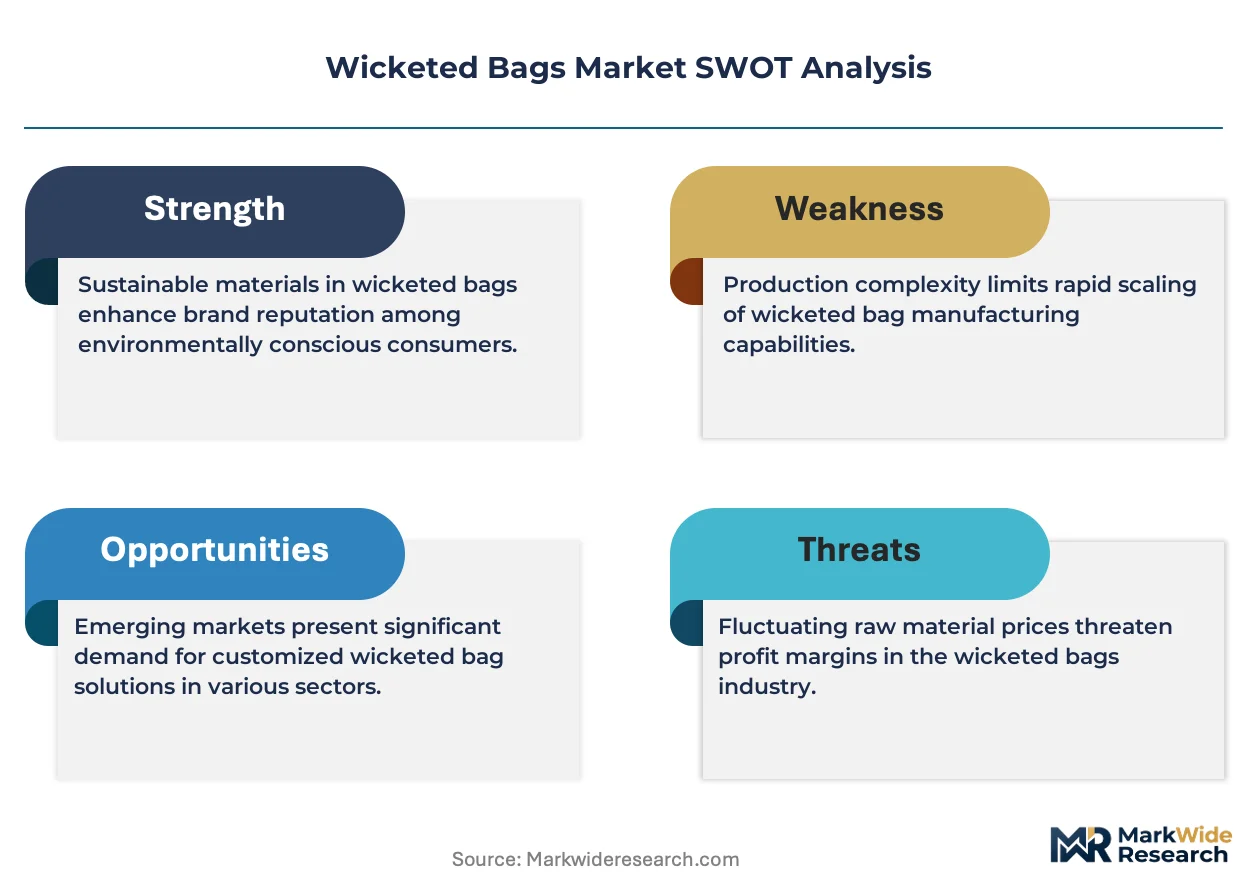
Industry Challenges
- Skill gap in blown film extrusion:Qualified technicians for gauge control and bubble stability are scarce, constraining capacity expansion timelines.
- Capex intensity for inline printing:Flexographic and digital printing equipment for high-speed wicket lines requires substantial capital deployment with extended payback periods.
- ISO 22000 certification timeline:Food safety management system implementation for film extrusion and conversion operations demands 12-18 month qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wicketed Bags Market |
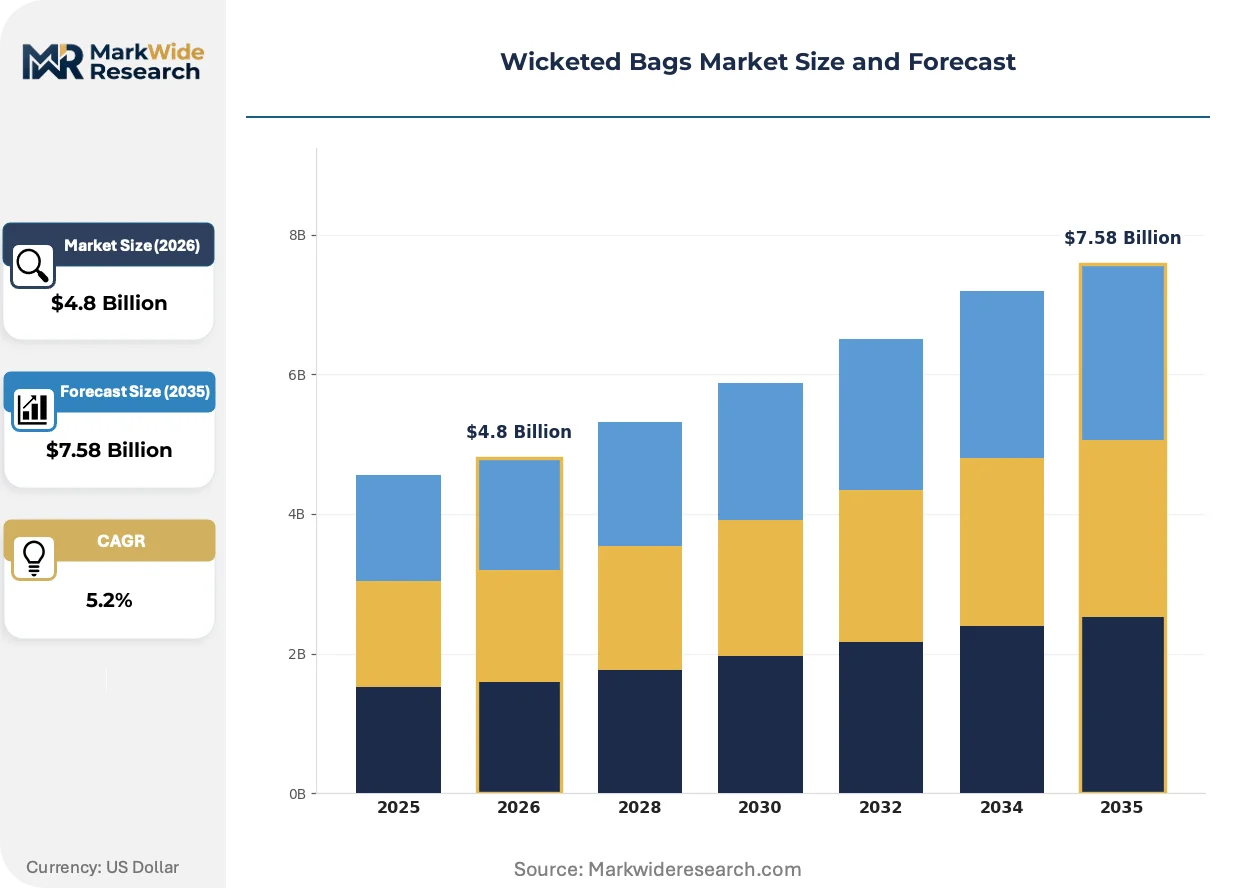
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Liner Bags, Pouch Bags Material: Polyethylene, Polypropylene, Paper, Biodegradable Films End User: Food Industry, Retail, Pharmaceuticals, Agricultural Sector Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Sun Packaging Technologies, Inc., Maco PKG, Neway Packaging Corporation, St. Johns Packaging, Bagmasters, Mann-Pak, Inc., Universal Plastic, PPC Flex, Dana Poly, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wicketed Bags Market Strategic Shifts & Innovations
Material science advances and regulatory pressure on plastic waste streams are forcing simultaneous evolution across film formulations, printing technologies, and dispensing system integration. Three distinct trajectories are reshaping competitive positioning.
Biodegradable film technology is decomposing the traditional polyethylene dominance in wicketed bag specifications. European bakery chains and North American organic produce distributors are piloting polylactic acid and polyhydroxyalkanoate formulations at scale. The technology is decomposing the commodity-premium pricing boundary by introducing certification-grade tiers that command measurable premiums.
REACH restrictions on persistent organic pollutants and the EU Green Deal's packaging waste targets are accelerating migration to mono-material polyethylene constructions. Converters are eliminating multi-layer barrier films to improve mechanical recyclability. European fresh produce and bakery segments are absorbing compliance costs fastest, with US operations tracking 18-24 months behind.
Buyer consolidation among national bakery and produce distributors is compressing supplier qualification cycles and unbundling after-sales technical service. Large-scale automated operations are internalizing film specification expertise and demanding direct extrusion relationships. This pattern is most visible in the US Midwest and Southeast, where regional bakery cooperatives have consolidated procurement functions.
Wicketed Bags Market Segmentation
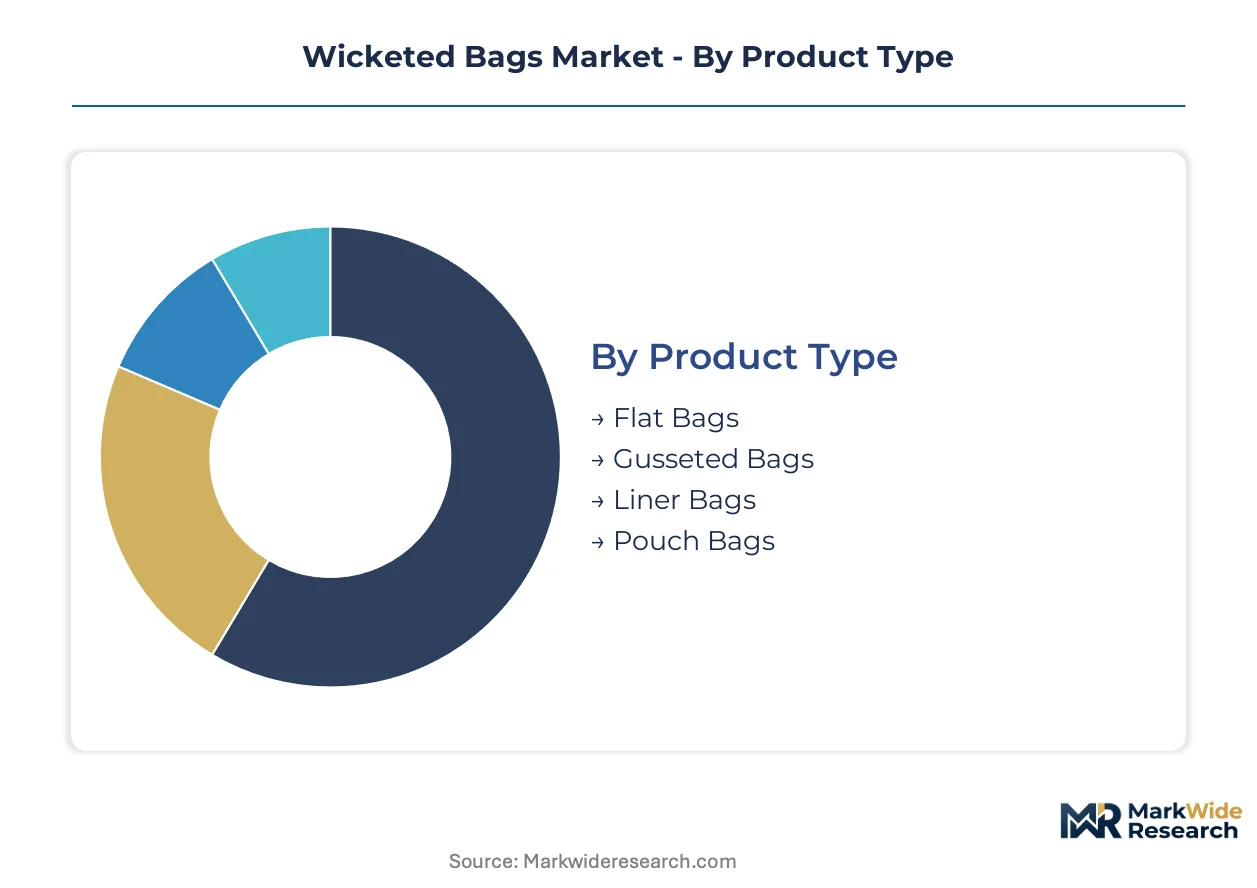
Wicketed bag procurement decisions trace directly to regulatory exposure and automation compatibility. FDA food-contact classifications under 21 CFR segment material specifications sharply, while filling line speeds dictate product architecture choices.
Product Type:
FDA seal integrity standards under 21 CFR Part 177 differentiate performance tiers across wicketed bag architectures, with bottom-seal specifications varying by automated dispensing requirements.
- Gusseted Bags:Side-folded film construction expands cubic capacity for irregular produce and bakery items. High-speed automated filling lines in United States bakery cooperatives demand consistent wicket spacing and gusset symmetry for robotic dispensing reliability.
- Flat Bags:Two-dimensional polyethylene or polypropylene enclosures without side expansion panels. United States produce distributors favor these for pre-portioned items where volume predictability simplifies line calibration.
- Liner Bags:Secondary containment films for bulk transport protection.
- Pouch Bags:Three-dimensional configurations with bottom gussets for stand-up presentation.
Gusseted bags handle the majority of throughput; biodegradable pouch configurations are expanding most quickly on share.
Material:
Cost tier stratification separates commodity resin grades from certified food-contact and compostable specifications.
- Polyethylene:Dominant material throughput given moisture barrier performance and cost position. Blown film extrusion capacity clusters along the United States Gulf Coast and Midwest, creating regional supply concentration for bakery and produce converters.
- Biodegradable Films:Polylactic acid and polyhydroxyalkanoate formulations. European bakery chains and North American organic produce distributors are piloting these at scale despite inferior moisture barrier performance in high-humidity applications.
- Polypropylene:Higher clarity and temperature resistance for retail-ready applications.
- Paper:Limited penetration constrained by moisture sensitivity in fresh produce handling.
Polyethylene dominates current volume; biodegradable films are climbing the fastest on specification share.
End User:
Customer type determines certification burden and replacement cycle velocity.
- Food Industry:Primary demand concentration spanning automated bakery lines and produce packing operations. ISO 22000 certification requirements extend qualification timelines to 12-18 months for film extrusion and conversion suppliers.
- Retail:Variable data printing requirements for private-label differentiation.
- Pharmaceuticals:Stringent particulate and sterility specifications.
- Agricultural Sector:Seasonal demand patterns tied to harvest cycles.
Food industry procurement handles the majority of throughput; retail applications are gaining share fastest through inline printing integration.
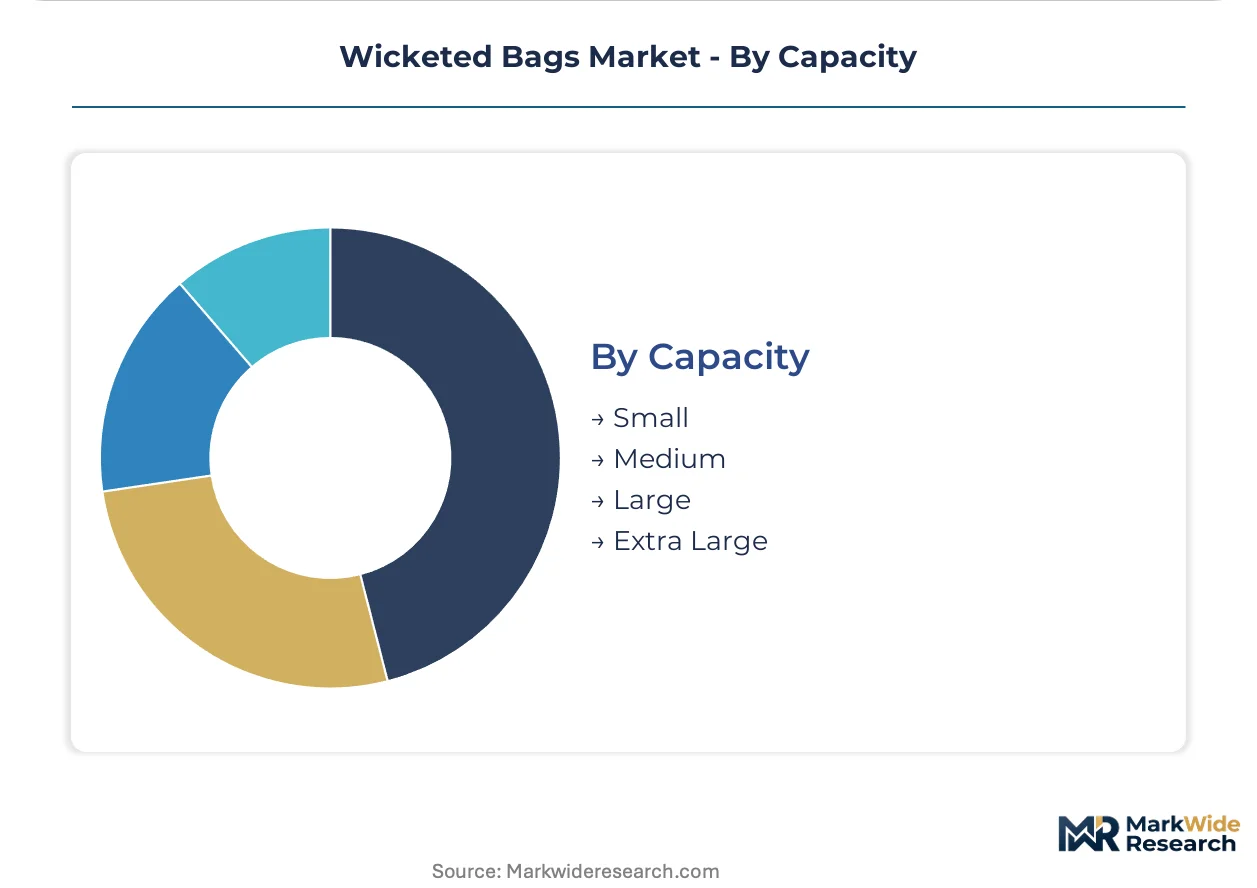
Capacity:
Volume scale aligns with automation capital deployment and line speed specifications.
- Medium:Standard workhorse specification for automated filling lines. United States high-speed bakery operations specify these for throughput optimization without excessive material waste.
- Large:Bulk produce and bakery item handling. Regional distributors in the United States Midwest and Southeast specify these for consolidated shipment efficiency.
- Small:Portion-controlled retail and foodservice applications.
- Extra Large:Industrial bulk containment with limited automation compatibility.
Medium capacity handles the majority of throughput; large capacity is expanding fastest on share through distributor consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wicketed bag trade flows track polyethylene resin availability and automated food processing density. Import dependence concentrates in regions lacking blown film extrusion infrastructure, while export capacity clusters near petrochemical feedstock and high-speed bakery equipment installations.
United States
Automated bakery lines across the Midwest and Southeast drive replacement cycles for wicketed bag inventories. FDA food-contact requirements under 21 CFR Part 177 reshape resin specifications annually. Chicago and Atlanta anchor distribution corridors where regional bakery cooperatives have consolidated procurement functions.
Germany
REACH restrictions on persistent organic pollutants accelerate migration to mono-material polyethylene constructions for mechanical recyclability. The EU Green Deal's packaging waste targets compress converter qualification timelines. The Rhine-Ruhr industrial corridor hosts extrusion capacity serving fresh produce distributors across Northern Europe.
China
Dual carbon goals and GB standards for food-contact plastics force reformulation of additive packages in blown film production. The Yangtze River Delta concentrates wicketed bag fabricators supplying automated processing equipment for domestic bakery chains. Shanghai-based converters face escalating post-consumer content mandates from major export buyers.
India
FSSAI food safety standards extend qualification timelines for imported resin formulations. The PLI scheme for packaging materials attracts domestic extrusion capacity expansion. Maharashtra and Gujarat host emerging clusters where regional dairy cooperatives pilot wicketed bag automation for chilled distribution.
Brazil
ANVISA pharmaceutical-grade specifications create certification overlap with food-contact wicketed bag production. Seasonal agricultural harvests generate demand spikes for bulk produce containment. São Paulo state anchors conversion capacity serving automated protein processing lines for domestic and export markets.
Wicketed Bags Market Key Industry Players
Concentration sits with vertically integrated blown film specialists and regional conversion houses serving automated food lines. The vendor base splits between captive extrusion operations and merchant converters purchasing resin on spot markets. Two archetypes dominate: integrated film-to-bag producers controlling specification consistency, and specialized high-speed printing converters capturing retail-ready applications. Competitive moves center on backward integration into resin compounding and geographic expansion along bakery distribution corridors.
Among North American fabricators, Sun Packaging Technologies, Inc. and Maco PKG exemplify divergent strategic positions. Sun Packaging Technologies represents the integrated archetype with captive blown film capacity, while Maco PKG occupies a position emphasizing high-speed wicket printing capabilities. St. Johns Packaging anchors a geographic concentration play across multiple distribution corridors. These three names illustrate how scale, specialization, and footprint each command distinct competitive space.
| Leading Market Players |
|---|
| Sun Packaging Technologies, Inc. |
| Maco PKG |
| Neway Packaging Corporation |
| St. Johns Packaging |
| Bagmasters |
| Mann-Pak, Inc. |
| Universal Plastic |
| PPC Flex |
| Dana Poly, Inc. |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day resin inventory cycles at United States Gulf Coast converters concentrate pricing power with backward-integrated producers, while merchant buyers absorb polyethylene spot volatility through quarterly contract renegotiations. FDA food-contact requalification requirements under 21 CFR Part 177 extend supplier switching costs, locking bakery and produce distributors into premium-tier specifications regardless of commodity resin price movements.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in wicketed bag procurement. Price differentiation hinges on ISO 22000 certification grade and inline printing capability, with certified food-contact tiers commanding measurable premiums over commodity specifications. Cost compression in standard-grade polyethylene formulations is intensifying because merchant converters without captive extrusion face margin pressure from ethylene feedstock volatility. Regional bakery cooperatives in the United States Midwest exhibit highest price sensitivity due to consolidated procurement volumes, while pharmaceutical-grade buyers show least sensitivity given ANVISA and FDA compliance requirements.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes elevate inbound logistics costs for resin formulations and conversion equipment. Blown film extrusion capacity clusters in the United States, China, and Germany, with feedstock supply drawing from Gulf Coast petrochemical complexes and Middle Eastern ethylene crackers. Raw material dependencies center on high-density polyethylene resin, metallocene catalyst packages, and wicket wire metal components. Single-source vulnerability concentrates in specialty additive suppliers for FDA-compliant food-contact grades. Distribution runs through regional bakery and produce distribution corridors anchored by Chicago and Atlanta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated United States bakery cooperatives that have centralized procurement functions across Midwest and Southeast operations. This consolidation compresses supplier qualification timelines and demands direct extrusion relationships.
For Market Incumbents: Compound defensive positioning through backward integration into blown film extrusion and ISO 22000 certification investment. Captive resin compounding capabilities neutralize polyethylene spot price volatility threats from Gulf Coast feedstock concentration. Geographic capacity expansion along Atlanta and Chicago distribution corridors reinforces channel control against regional merchant converters.
For New Entrants and Emerging Players: FDA food-contact certification fast-tracks open access to underpenetrated quick-service restaurant back-of-house automation in the United States. Biodegradable film formulations for organic produce distributors represent the most penetrable specification tier given incumbent polyethylene lock-in. Lead with compostability certification and moisture-barrier improvement R&D as the go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underoptimized wicketed bag divisions lacking inline printing integration. Long-term viability over the mid-term projection horizon rests on mono-material recyclability compliance and post-consumer content certification capabilities. Monitor EPA plastic waste stream guideline evolution as the signal to watch for regulatory inflection timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blown Film Extrusion | Captive resin supply neutralizes Gulf Coast feedstock price volatility for FDA-compliant specifications. |
| ISO 22000 Certification Investment | Food safety management qualification unlocks 12-18 month procurement cycles with United States bakery cooperatives. |
| Inline Printing Capability Expansion | Flexographic and digital integration enables retail-ready wicketed bags with variable data for private-label differentiation. |
| Biodegradable Film Formulation Development | Polylactic acid and polyhydroxyalkanoate pilot programs capture compostability mandate premiums from European bakery chains. |
| Geographic Expansion Along Distribution Corridors | Midwest and Southeast footprint proximity reduces logistics costs to consolidated regional bakery procurement hubs. |
Research Approach
Initial hypotheses were tested against primary input from blown film extrusion plant managers, bakery cooperative procurement directors, produce distributor operations heads, and FDA regulatory affairs specialists, then refined through secondary validation. Primary fieldwork combined structured interviews with secondary triangulation across SEC 10-K filings of packaging converters, American Chemistry Council resin production data, FDA 21 CFR food-contact substance inventories, and United States customs import records for polyethylene film grades. Bottom-up capacity modeling and top-down demand estimation were reconciled across the analysis window.
Variance decomposition across product architecture, material specification, end-use certification burden, and regional automation penetration shaped the analytical framework. CAGRs were derived from segment-level volume trajectories weighted by value-per-unit differentials across gusseted, flat, and biodegradable pouch configurations. Forecast inputs incorporated high-speed filling line installation rates at United States bakery operations and European REACH compliance cost absorption timelines.
Underlying assumptions cover sustained FDA food-contact regulatory stability, polyethylene resin supply continuity from Gulf Coast crackers, and automation penetration rates at quick-service restaurant operations, with deviation risk concentrated in biodegradable film moisture-barrier breakthrough timing and extended producer responsibility framework adoption velocity across United States state legislatures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Inclusion Bags Market
Bags and Containers
Leno Bags Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Tamper Evident Bag Sealers Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Disposable Garbage Bags Market
Bags and Containers
Bulk Bag Divider Market
Bags and Containers
Cross Corner Industrial Bags Market
Bags and Containers
Circular Industrial Bags Market
Bags and Containers
Packaging Nets Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Shrink Bags Market
Bags and Containers
Refuse Bags Market
Bags and Containers
Pre-Made Bags Market
Bags and Containers
Vacuum Shrink Bags Market
Bags and Containers
Conical Top Bulk Bag Market