
 Woven Bags Market | 2026-2036
Woven Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Woven Bags Market Analytics
Reusable bag subscription and maintenance programs is realigning how woven bag producers capture recurring revenue beyond one-time hardware sales. Mondi Group leverages its European recycling infrastructure to offer closed-loop PP recovery services for agricultural clients. Berry Global Inc. anchors North American food-grade woven supply through FDA-compliant laminating capabilities. Emmbi Industries Limited specializes in customized FIBC and woven solutions for Indian fertilizer and chemical exporters, dominating domestic bulk packaging channels.
Woven bags are flexible containers fabricated from interlaced polypropylene, high-density polyethylene, jute, or cotton yarns, typically constructed with warp and weft weaving at densities of 8×8 to 14×14 threads per inch for load-bearing applications ranging from 25 kg to 2,000 kg. These structures serve primary industrial purposes in agricultural grain storage, cement transport, and retail merchandise carriage where tensile strength, moisture resistance, and stackability outperform paper or non-woven alternatives. PP Woven Bags command the largest volume share due to their cost-efficiency in fertilizer and grain logistics, while Jute Bags sustain premium positioning in EU and North American organic food retail channels where biodegradability requirements tighten. HDPE Woven Bags occupy specialized construction and chemical applications where ultraviolet degradation resistance and caustic material compatibility prove essential.
India's BIS mandates IS 16008 standards for food-contact woven polypropylene, compelling domestic mills to upgrade extrusion and lamination lines or forfeit institutional catering contracts. China's SAMR enforces GB/T 8946 technical specifications for woven sack tensile performance, directly shaping export qualification criteria for Southeast Asian-bound shipments. The EU REACH regulation restricts certain phthalate plasticizers in PP woven laminates, redirecting European sourcing toward certified Indian and Bangladeshi suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks in major demand centers and pre-position recycling partnerships before compliance deadlines harden into market access barriers.
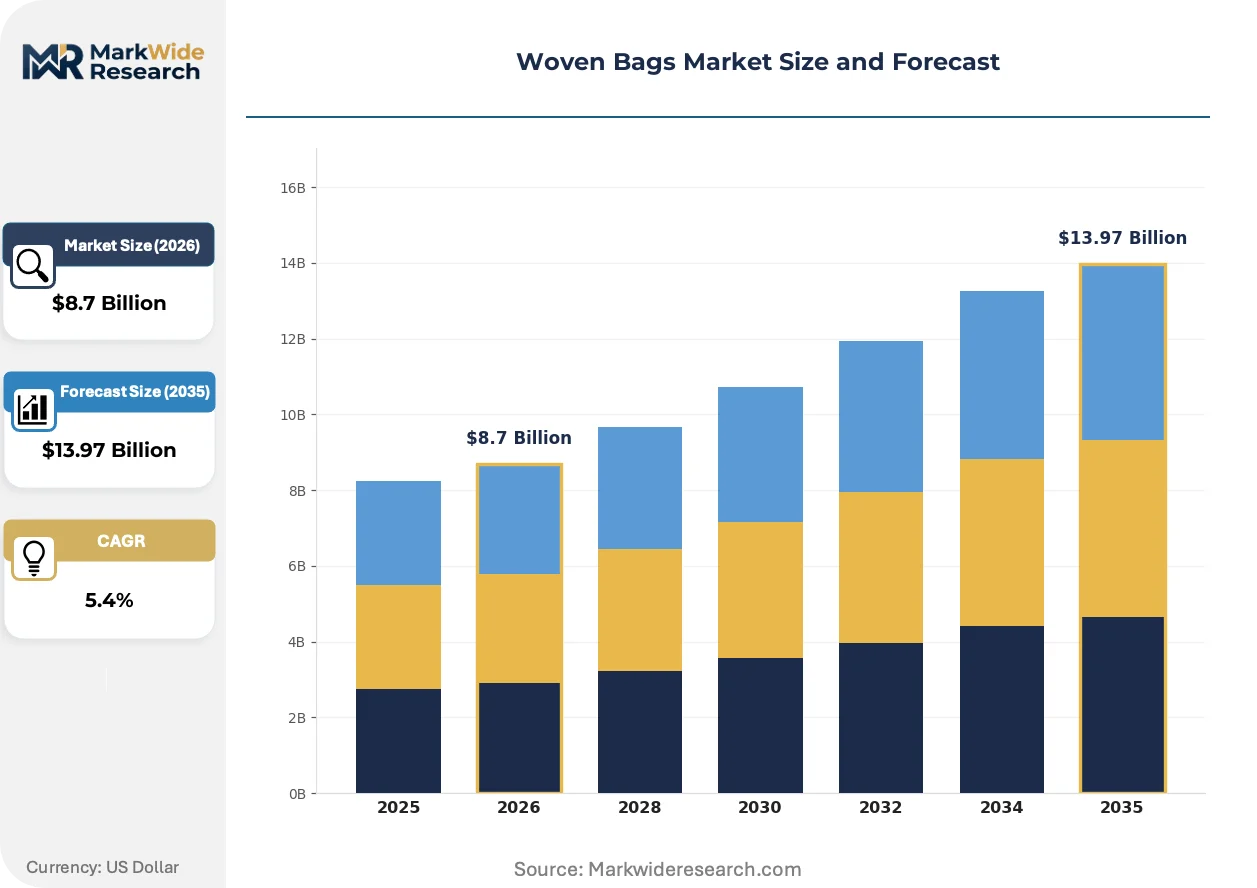
Market Dynamics
Agricultural bulk packaging demand in India and Southeast Asia is compressing production cycles while tightening material certification requirements, forcing woven bag manufacturers to reconfigure extrusion lines for simultaneous food-grade and chemical-resistant output.
Growth Catalysts
- India's BIS IS 16008 mandate:Food-contact certification requirements for woven polypropylene are institutionalizing quality upgrades across Gujarat and Maharashtra manufacturing clusters, locking in domestic institutional catering contracts for compliant mills.
- EU REACH phthalate restrictions:European restrictions on plasticizers in PP woven laminates are redirecting sourcing volumes toward certified Indian and Bangladeshi suppliers with verified substitution protocols.
- Jute-PP hybrid construction:Blended yarn technologies are capturing premium positioning in organic food retail channels where biodegradability specifications outrule pure synthetic alternatives.
Market Restraints
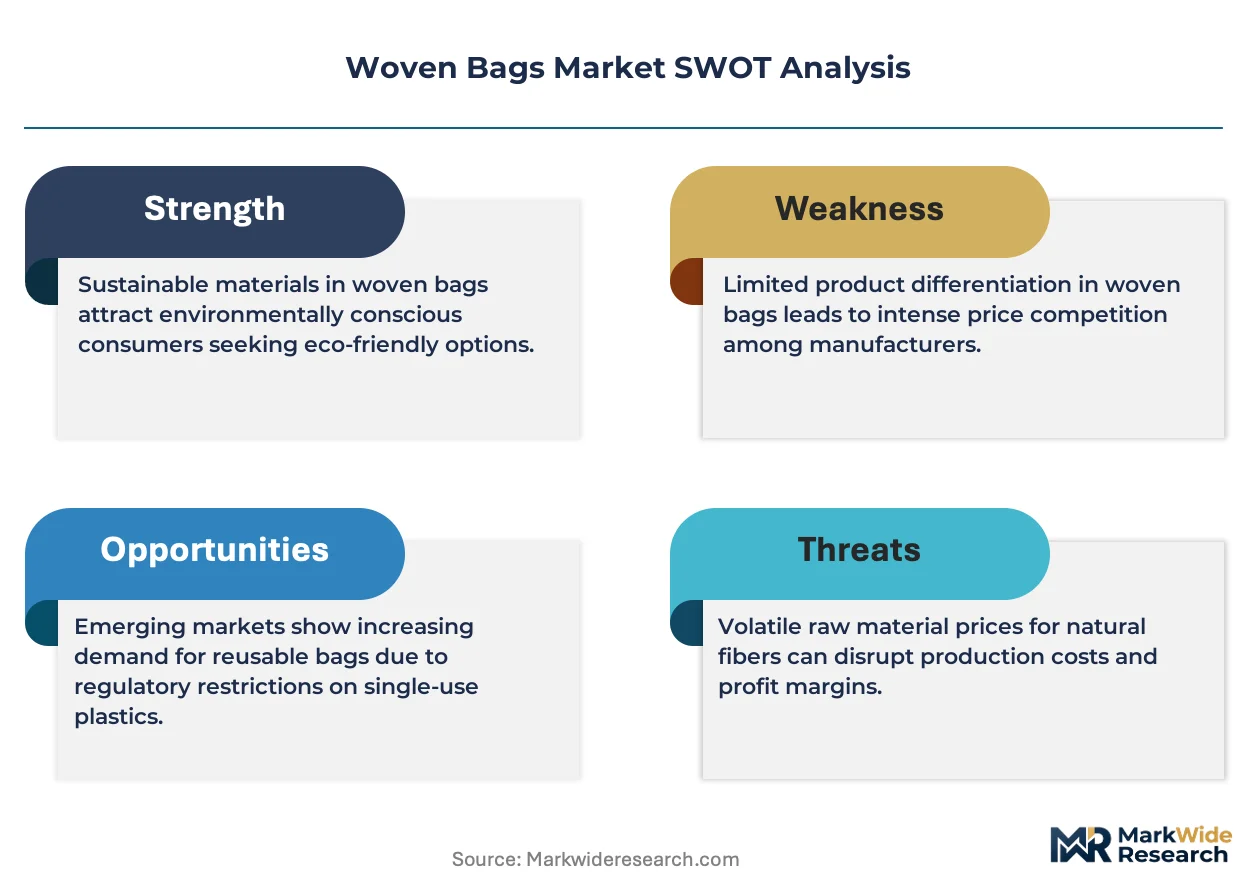
- Polypropylene resin cost volatility:Crude-linked feedstock pricing swings compress margin predictability for extrusion-dependent producers lacking backward integration into polymer supply.
- China GB/T 8946 export qualification:SAMR-mandated tensile performance specifications create technical barriers for Southeast Asian-bound shipments from non-certified regional mills.
- Paper and non-woven substitution:Retail merchandise carriage segments in climate-stable logistics corridors are migrating toward lower-cost alternatives where moisture resistance proves non-critical.
Strategic Opportunities
- Closed-loop recovery services:European extended producer responsibility frameworks are creating service-revenue streams for producers with captive recycling infrastructure and agricultural client relationships.
- Fertilizer export packaging from India:Customized FIBC and woven solutions for chemical exporters represent underpenetrated white space in domestic bulk packaging channels serving Middle Eastern and African destinations.
- UV-stabilized HDPE construction applications:Ultraviolet degradation resistance specifications in infrastructure and chemical handling are opening specialized premium tiers beyond commodity PP volumes.
Industry Challenges
- Multi-standard extrusion line reconfiguration:Simultaneous compliance with India's BIS food-grade mandates and China's chemical-resistant GB specifications demands capital-intensive lamination upgrades with uncertain contract conversion timelines.
- Skilled weaving technician scarcity:Warp and weft density control expertise for 8×8 to 14×14 threads-per-inch construction is concentrating in legacy textile regions, constraining quality-scaled expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Woven Bags Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PP Woven Bags, HDPE Woven Bags, Jute Bags, Cotton Bags End User: Agriculture, Retail, Construction, Food Packaging Distribution Channel: Online, Supermarkets, Wholesale, Specialty Stores Application: Packaging, Shopping, Industrial, Promotional |
| Companies Covered | United Bags Inc., Palmetto Industries, Mondi Group, Emmbi Industries Limited, Cady Bag Company, Berry Global Inc., Anduro Manufacturing, Bhaichand Patel, Uflex Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Woven Bags Market Evolving Landscape
Material science advances and regulatory fragmentation are forcing woven bag producers to decouple hardware manufacturing from compliance services, creating modular business architectures that separate commodity extrusion from certified finishing operations.
Co-extruded multi-layer PP films with integrated oxygen barriers are modularizing how agricultural grain storage specifications get met without separate lamination stages. Large-scale fertilizer distributors in India's western industrial corridors are specifying these constructions for 50 kg unit loads, collapsing traditional supply chains that separated substrate production from functional coating. The technology is modularizing vendor relationships by allowing end-users to source barrier performance independently from bag structural integrity.
China's NMPA standards for chemical-resistant PP constructions are tightening material specifications for export-oriented production. Domestic mills serving Southeast Asian chemical distributors must now maintain dual certification tracks for food-contact and caustic-material compatibility, diverting technical resources toward compliance documentation. Fertilizer and agrochemical packaging segments bear the heaviest adaptation burden, with producers in Shandong and Jiangsu provinces accelerating laboratory investment to maintain cross-border market access.
Subscription-based maintenance programs for reusable bulk containers are displacing one-time hardware transactions in European agricultural logistics. Grain cooperatives in Germany and France are contracting woven bag producers for multi-season durability guarantees with embedded recovery logistics, shifting procurement evaluation from unit price toward total cost-per-trip metrics. This behavioral pivot is most visible in rapeseed and sugar beet supply chains where seasonal volume concentration justifies dedicated container pools.
Woven Bags Market Segmentation
Woven bag procurement decisions hinge on load-bearing requirements, regulatory compliance tiers, and end-use durability specifications. Material selection directly determines certification pathways and customer retention in institutional channels.
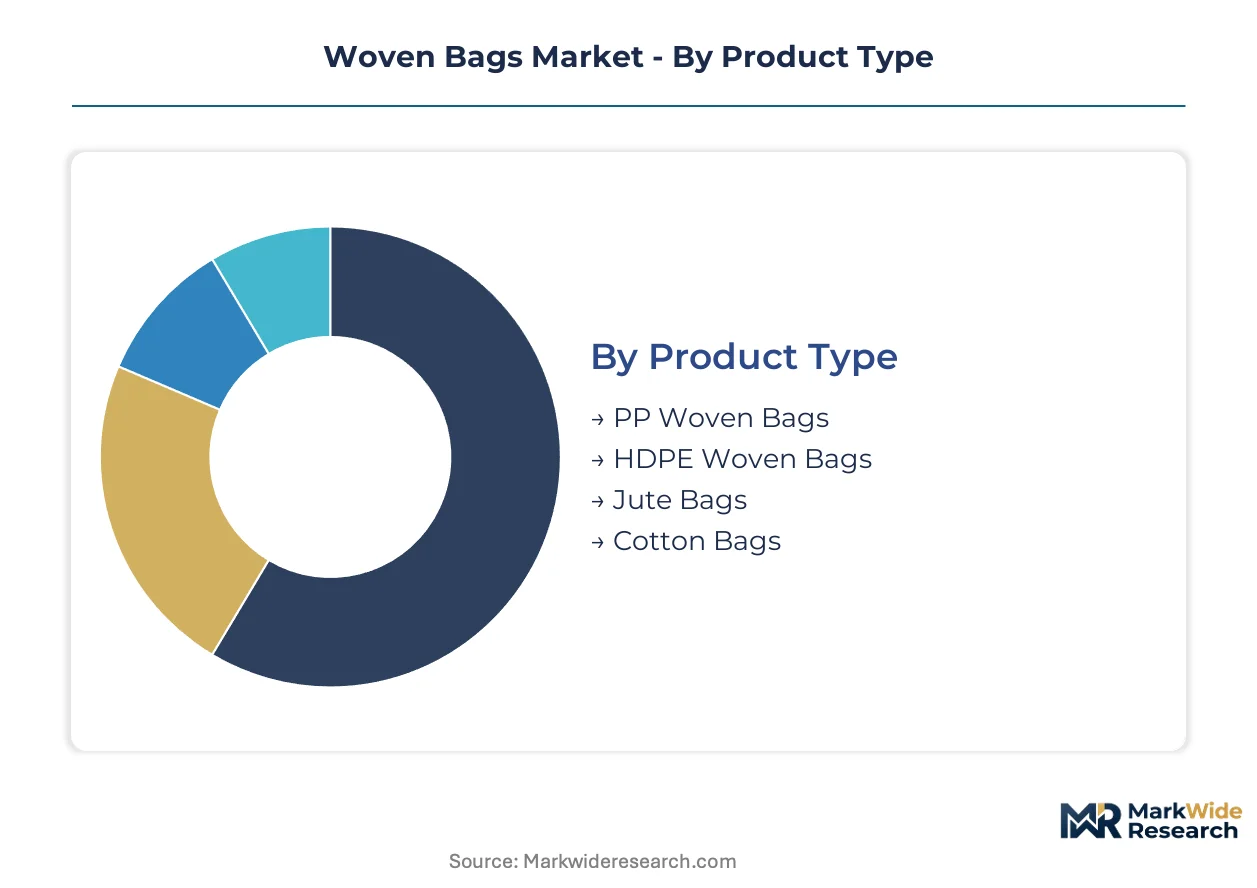
Product Type:
Buyers prioritize cost-efficiency against performance thresholds when selecting substrate materials for specific load and environmental conditions.
- PP Woven Bags:Polypropylene constructions deliver tensile strength of 8×8 to 14×14 threads per inch with moisture barrier laminates. India's Gujarat and Maharashtra industrial corridors concentrate extrusion capacity for fertilizer and grain logistics serving domestic institutional catering and Middle Eastern export contracts.
- HDPE Woven Bags:High-density polyethylene formulations provide ultraviolet degradation resistance and caustic material compatibility. Construction and chemical handling applications in infrastructure projects specify these for extended outdoor exposure where PP alternatives fail.
- Jute Bags:Natural fiber constructions meet EU organic food retail biodegradability mandates.
- Cotton Bags:Premium retail merchandise carriage segments favor these for reusability branding.
PP Woven Bags leads on scale; Jute Bags leads on momentum.
End User:
Volume concentration varies sharply by sector, with bulk agricultural procurement dominating unit economics while retail channels command premium pricing tiers.
- Agriculture:Grain storage and fertilizer distribution drive 25 kg to 2,000 kg load specifications across India's western industrial corridors. BIS IS 16008 food-contact certification requirements lock in compliant mills for institutional catering contracts.
- Construction:Cement transport and chemical-resistant applications demand UV-stabilized constructions. China's GB/T 8946 tensile specifications shape qualification criteria for Southeast Asian-bound shipments.
- Retail:Merchandise carriage segments migrate toward lower-cost alternatives where moisture resistance proves non-critical.
- Food Packaging:REACH phthalate restrictions redirect European sourcing toward certified Indian and Bangladeshi suppliers.
Agriculture dominates absolute volume; Food Packaging climbs the fastest on regulatory premium capture.
Distribution Channel:
Channel selection determines margin structure and customer relationship depth, with direct wholesale relationships anchoring bulk contracts.
- Wholesale:Agricultural cooperatives and fertilizer distributors in India and Southeast Asia procure through direct mill relationships. Large-scale buyers in Maharashtra specify co-extruded multi-layer films with integrated oxygen barriers for 50 kg grain unit loads.
- Online:Reusable bag subscription programs capture recurring revenue beyond one-time hardware sales. European grain cooperatives contract producers for multi-season durability guarantees with embedded recovery logistics.
- Supermarkets:Standard retail merchandise carriage with limited customization.
- Specialty Stores:Premium organic food retail channels in EU and North American markets.
Wholesale anchors revenue concentration; Online gains share fastest on service-model displacement.
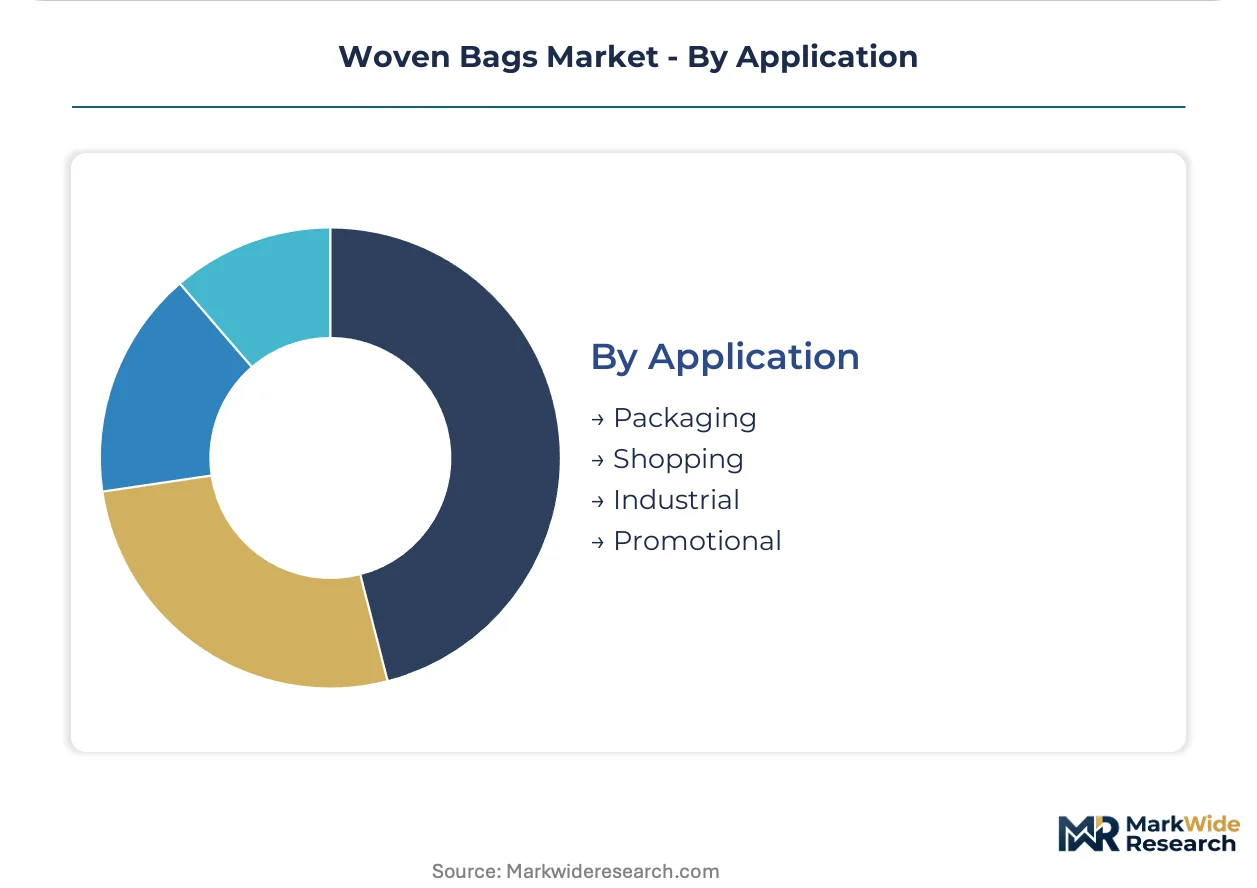
Application:
Functional use cases dictate weaving density, lamination requirements, and certification documentation burdens.
- Packaging:Agricultural bulk storage and chemical transport applications specify warp and weft densities for load-bearing performance. China's NMPA standards for chemical-resistant PP constructions tighten material specifications for export-oriented production in Shandong and Jiangsu provinces.
- Industrial:Construction material handling and infrastructure projects require UV-stabilized HDPE formulations. Dual certification tracks for food-contact and caustic-material compatibility divert technical resources toward compliance documentation.
- Shopping:Retail merchandise carriage with lower performance thresholds.
- Promotional:Branded reusable programs with durability guarantee contracting.
Packaging commands the steepest expansion trajectory; Industrial maintains premium pricing power on specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production maps as mills relocate to jurisdictions with lower compliance costs while maintaining export qualification. BIS mandates in India and REACH restrictions in Europe create divergent cost structures that advantage South Asian suppliers serving cross-border agricultural clients.
India
Gujarat and Maharashtra industrial corridors host jute-PP hybrid manufacturing clusters serving domestic food packaging and fertilizer export channels. BIS IS 16008 certification requirements for food-contact woven polypropylene are institutionalizing quality upgrades across extrusion and lamination lines. Ahmedabad and Surat mills dominate institutional catering contracts through compliant output.
China
Shandong and Jiangsu provinces concentrate chemical-resistant PP construction capacity for Southeast Asian-bound fertilizer shipments. SAMR-enforced GB/T 8946 tensile performance specifications shape export qualification criteria. NMPA standards for caustic-material compatibility are accelerating laboratory investment among mills serving cross-border agrochemical distributors.
Germany
Grain cooperatives in Bavaria and Lower Saxony are contracting multi-season durability guarantees with embedded recovery logistics. EU REACH phthalate restrictions on PP woven laminates are redirecting sourcing toward certified South Asian suppliers. Closed-loop subscription models for reusable bulk containers are displacing one-time hardware transactions in rapeseed and sugar beet supply chains.
Bangladesh
Verified substitution protocols for REACH-compliant plasticizers are capturing redirected European sourcing volumes. Natural fiber construction expertise in Dhaka and Chittagong industrial zones supports jute-PP hybrid output for organic food retail channels. Biodegradability specifications in EU markets sustain premium positioning against pure synthetic alternatives.
United States
FDA-compliant laminating capabilities anchor North American food-grade woven supply through Midwest and Southeast production bases. Berry Global Inc. leverages regional infrastructure for agricultural and retail distribution channels. UV-stabilized HDPE construction applications in infrastructure projects command specialized premium tiers beyond commodity PP volumes.
Woven Bags Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium certification holders capturing institutional catering contracts while commodity extruders serve spot agricultural markets. The vendor base concentrates around three strategic archetypes: integrated polymer-to-bag producers with captive recycling infrastructure, regional mills specializing in hybrid natural-synthetic constructions, and multinational laminators with FDA and REACH compliance documentation. Competitive moves center on backward integration into polymer supply and geographic expansion through distribution partnerships in high-growth fertilizer export corridors.
Among North American fabricators, United Bags Inc. and Palmetto Industries occupy positions in the branded specialist tier, while Mondi Group exemplifies the integrated infrastructure archetype with European recycling capabilities. Emmbi Industries Limited represents the regional scale model within Indian bulk packaging channels. These anchors illustrate how competitive positioning stratifies across certification depth, geographic proximity to agricultural demand, and service-model sophistication.
| Leading Market Players |
|---|
| United Bags Inc. |
| Palmetto Industries |
| Mondi Group |
| Emmbi Industries Limited |
| Cady Bag Company |
| Berry Global Inc. |
| Anduro Manufacturing |
| Bhaichand Patel |
| Uflex Limited |
| Others |
Value Network & Pricing Analysis
Co-extruded multi-layer PP film adoption is compressing production economics while concentrating supply relationships around mills with integrated barrier-lamination capabilities. This technology shift simultaneously collapses traditional two-stage supply chains and rewards producers with captive extrusion-coating lines, reshaping how agricultural buyers evaluate total landed cost against certification bundled pricing.
Pricing Analysis
Distributor margin layers compress most acutely in commodity PP woven segments where spot resin pricing feeds directly through to agricultural procurement contracts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified food-contact laminates from industrial-grade chemical-resistant constructions and uncoated commodity grain sacks. Price differentiation hinges on BIS IS 16008 certification attainment and volume scale commitments exceeding 500-ton annual offtake. Margins are tightening due to polypropylene resin cost volatility linked to crude feedstock swings. Fertilizer distributors in India's western corridors demonstrate highest price sensitivity, while EU organic food retailers show least sensitivity given biodegradability mandates that foreclose synthetic alternatives.
Supply Chain Analysis
Dual-sourcing requirements from European grain cooperatives are mandating multi-supplier qualification across at least two certified production jurisdictions. Geographic supply concentration centers on India, China, and Bangladesh for woven substrate manufacturing. Raw material dependencies draw from Saudi and Qatari polypropylene resin supply, Indian jute fiber cultivation, and German laminating chemical formulations. Supply chain risk rests on single-source vulnerability in oxygen-barrier film additives where European specialty chemical producers dominate. Distribution runs through direct mill relationships for agricultural bulk contracts and subscription-service platforms for reusable container pools in German and French rapeseed logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Woven Bags Market represents a late-cycle quality story where premium specifications for food-contact certification and biodegradability are displacing undifferentiated commodity volume. Agricultural buyers in India and EU organic retail channels now prioritize compliance documentation over unit price in vendor selection.
For Market Incumbents: Anticipate margin compression in uncoated PP commodity tiers as Chinese mills with GB/T 8946 certification expand Southeast Asian export share. Defensive consolidation through backward integration into polymer supply secures resin cost predictability against crude-linked volatility. Certification investment in dual BIS-NMPA compliance tracks locks in cross-border fertilizer packaging contracts before 2026 regulatory deadlines harden.
For New Entrants and Emerging Players: Direct-to-farm digital procurement platforms offer the most penetrable route into Indian agricultural cooperatives currently underserved by legacy mill sales networks. Target customized FIBC solutions for Middle Eastern and African fertilizer exporters as white-space expansion. White-space exists in UV-stabilized HDPE construction applications for infrastructure projects where specification intensity supports premium pricing. Launch through technical sales partnerships with regional distributors holding existing cement and chemical handling relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional mills with certified laminating capabilities but underdeveloped subscription-service revenue models. Long-term viability over the next decade hinges on extended producer responsibility framework positioning before EU compliance deadlines. Acquisition target archetype: mid-scale Indian producers with BIS IS 16008 certification and latent capacity for jute-PP hybrid output. Watch for inflection in European grain cooperative procurement shifting from unit price to total cost-per-trip metrics for reusable container pools.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Supply | Captive resin sourcing insulates margin from crude-linked PP price volatility affecting extrusion-dependent competitors. |
| Dual Certification Investment | Simultaneous BIS IS 16008 and NMPA compliance opens cross-border fertilizer packaging contracts in India and Southeast Asia. |
| Closed-Loop Recovery Service Launch | European EPR frameworks create recurring revenue streams from agricultural clients with embedded container return logistics. |
| Jute-PP Hybrid Capacity Expansion | Biodegradability specifications in EU organic retail channels sustain premium positioning against pure synthetic alternatives. |
| Direct-to-Farm Digital Platform | Bypassing distributor layers captures margin from Indian agricultural cooperatives currently paying legacy channel markups. |
Research Methodology
Coverage spans India, China, Germany, Bangladesh, and the United States, with primary inputs from each regional production cluster. The approach combines interviews with extrusion plant managers, procurement leads at fertilizer distributors, laminating technical directors, and agricultural cooperative supply officers with secondary validation from BIS certification databases, SAMR GB standard filings, ECHA REACH restriction lists, and customs trade records. Bottom-up capacity modeling triangulates against top-down agricultural output forecasts.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including material substrate type, end-use sector, load-bearing specification tier, and regional regulatory cluster. CAGRs derive from trend extrapolation of agricultural bulk packaging demand, certification penetration curves, and substitution elasticity between synthetic and natural fiber constructions. Industry-specific inputs include jute fiber harvest variability and polypropylene resin price correlation coefficients with crude benchmarks.
Polypropylene feedstock price spikes, unanticipated regulatory timeline acceleration, and jute crop failure are the dominant revision risks to modeled outputs. Deviation in resin cost volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
FIBC Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Bakery Bread Bag Market
Bags and Containers
Big Bag Discharge Station Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Household and Cleaning Container Market
Bags and Containers
Isothermal Bags Market
Bags and Containers
Drink Carrier Poly Bags Market
Bags and Containers
Freezer Bags Market
Bags and Containers
Laser Scored Bags Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Frosted Bag Market
Bags and Containers
Zipper Bags Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Centerfold Laminated Bags Market