
 Bulgaria Automotive Lubricants Market | 2026-2036
Bulgaria Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Bulgaria Automotive Lubricants Market Outlook
Low-viscosity synthetic formulations is rewriting how automotive lubricants are engineered for fuel efficiency in Bulgaria's aging vehicle fleet. Shell leverages its blending facility near Burgas to sustain supply chain proximity to Black Sea logistics. Castrol anchors the premium synthetic segment through specialized service partnerships with Sofia-based maintenance chains. Prista Oil dominates the domestic mid-tier channel with extensive wholesale coverage across secondary cities.
Automotive lubricants are formulated base oil mixtures enhanced with detergents, dispersants, and viscosity modifiers, typically rated by SAE grades from 0W-16 to 20W-50, designed to reduce friction, dissipate heat, and prevent engine wear under varying thermal and mechanical loads. Engine oil occupies the largest value share given the high replacement frequency and technical complexity of modern powertrains in Bulgaria's mixed-age fleet. The aftermarket provider channel leads volume distribution, while OEM supply contracts concentrate margin pools among multinational blenders with direct assembler relationships. E-commerce is the fastest-growing distribution channel, though retail and wholesale still control the bulk of transactions outside Sofia.
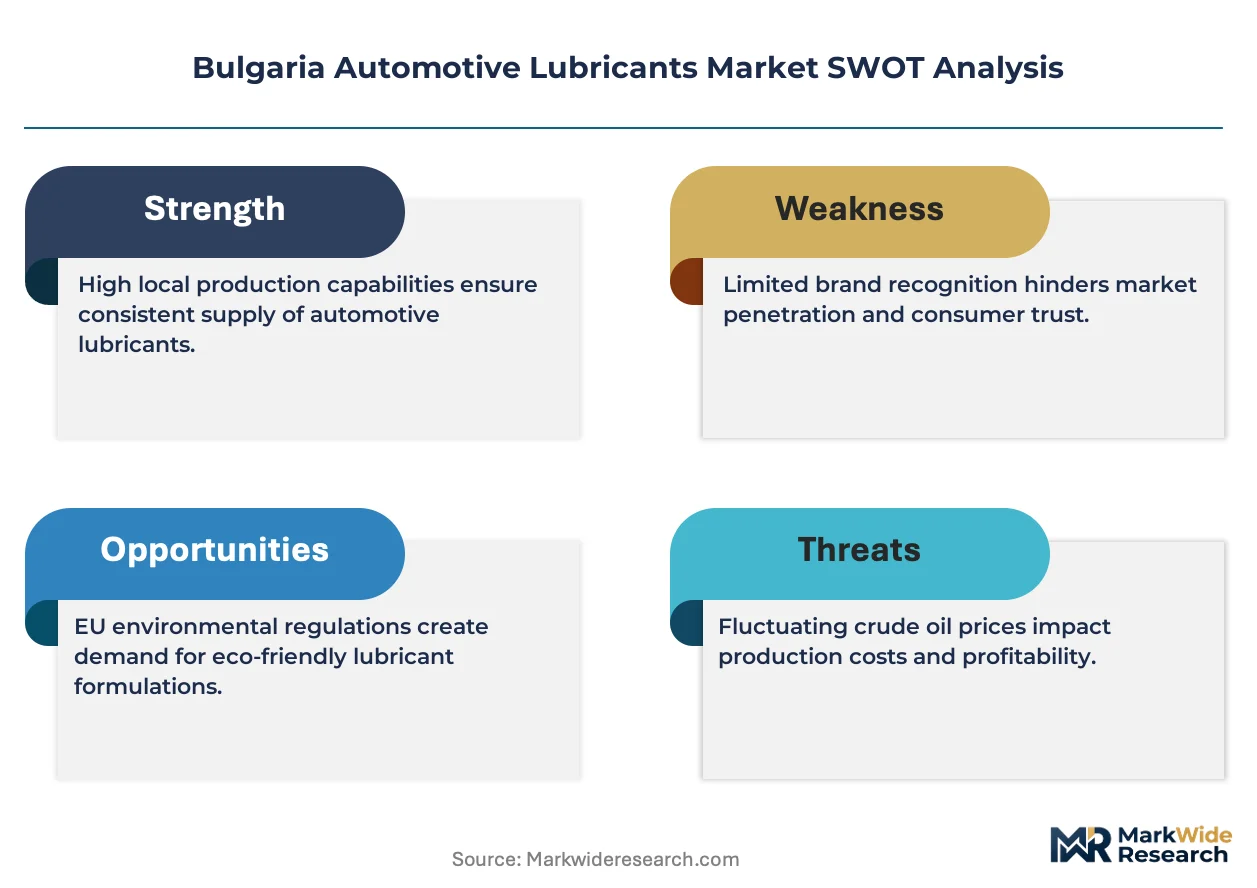
Bulgaria's automotive lubricant market operates under EU REACH chemical registration requirements, the EU Green Deal's decarbonization benchmarks, and national adaptation of CE marking standards enforced by the Bulgarian Institute for Standardization. REACH compliance elevates formulation costs for imported additive packages while creating barriers for non-EU suppliers without local registration. The EU Green Deal pushes blenders toward lower-carbon base stocks and biodegradable alternatives. Stakeholders must monitor how EU F-Gas Regulation amendments and potential carbon border adjustments reshape competitive cost structures for domestic versus imported lubricant portfolios.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant-lubricant formulation windows while fleet operators in Sofia and Plovdiv accelerate synthetic adoption to maintain compliance.
Growth Catalysts
- EU Green Deal decarbonization benchmarks:Blenders reformulate toward lower-carbon base stocks to satisfy tightening lifecycle emission requirements across Bulgarian commercial transport corridors.
- Black Sea logistics proximity:Burgas port infrastructure enables rapid additive package importation, reducing lead times for domestic blending operations serving southeastern European markets.
- Synthetic lubricant performance premiums:Extended drain intervals and fuel economy gains drive replacement of mineral formulations in Bulgaria's aging heavy-duty fleet.
Market Restraints
- REACH registration cost concentration:Imported additive packages face elevated compliance burdens that disadvantage non-EU suppliers lacking Bulgarian Institute for Standardization partnerships.
- Base stock supply geography:Group III and PAO feedstock dependence on northwestern European refiners exposes blenders to cross-border logistics volatility.
- Mineral oil substitution ceiling:Price-sensitive owner-operators in secondary cities resist synthetic premiums despite documented total-cost-of-ownership advantages.
Strategic Opportunities
- E-commerce channel expansion:Direct-to-workshop platforms bypass traditional wholesale tiers in Sofia's dense maintenance cluster, capturing margin pool redistribution.
- EU carbon border adjustment anticipation:Early positioning on biodegradable ester formulations hedges against future import tariff exposure on high-carbon lubricant categories.
- Plovdiv industrial corridor penetration:Underdeveloped service partnerships in Bulgaria's second-largest city present whitespace for specialized synthetic distribution networks.
Industry Challenges
- Formulation chemist scarcity:Bulgaria's technical universities produce insufficient lubricant additive specialists to support rapid synthetic portfolio expansion.
- CE marking timeline compression:Accelerated EU regulatory amendment cycles strain domestic testing laboratory capacity for product recertification.
- Legacy fleet compatibility verification:Seal material interaction testing for backward-compatible synthetic formulations demands capital-intensive bench equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulgaria Automotive Lubricants Market |
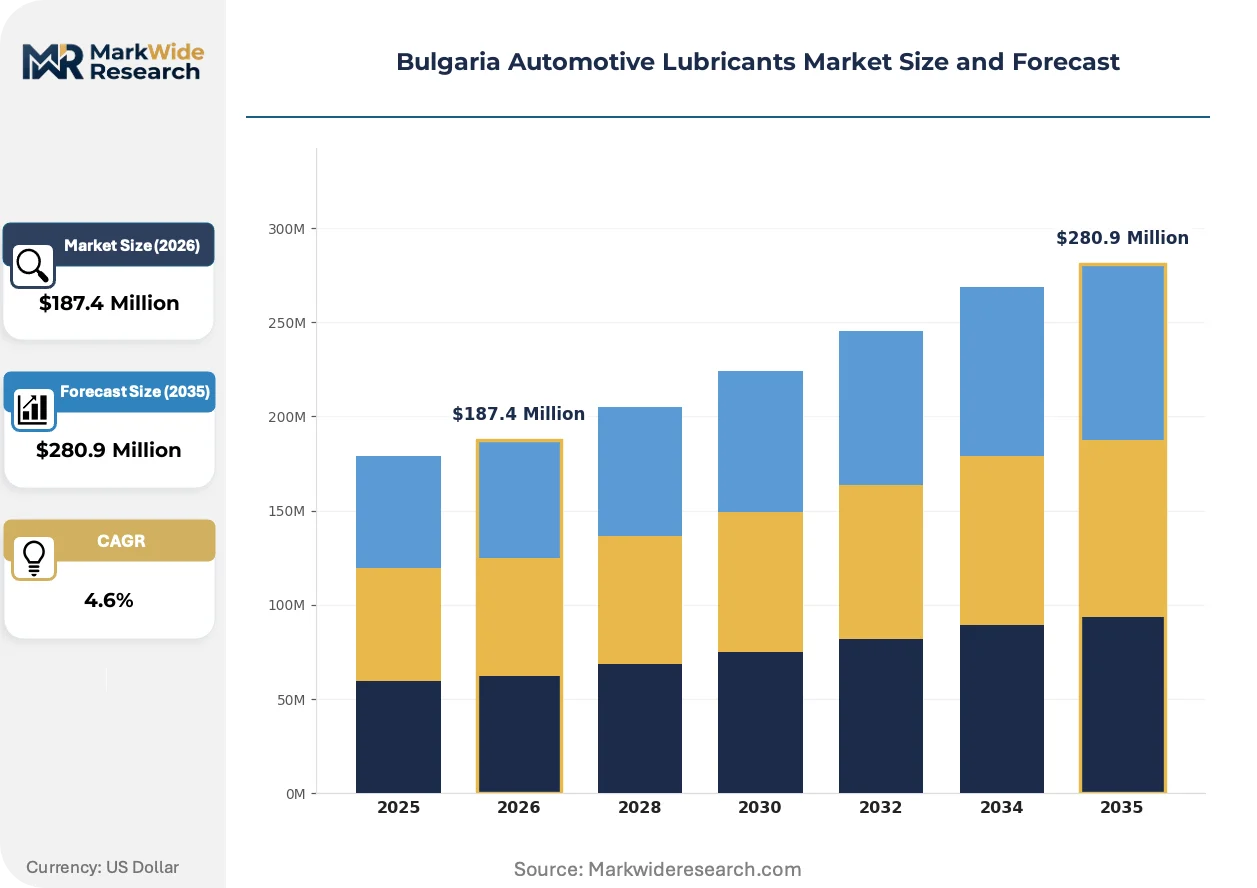
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Maintenance Shops Packaging Type: Bottles, Drums, Pails, Bulk Distribution Channel: Retail, Wholesale, E-commerce, Direct Sales |
| Companies Covered | Shell, Castrol, TotalEnergies, Prista Oil, Lukoil, Fuchs Petrolub, Chevron, ExxonMobil, AVIA International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulgaria Automotive Lubricants Market Strategic Shifts
Digital integration of lubricant condition monitoring is collapsing preventive maintenance schedules into predictive replacement cycles across Bulgarian commercial fleets.
Real-time oil analysis sensors embedded in engine blocks transmit viscosity and oxidation data to fleet management platforms. Transport operators along the Trakia motorway corridor are piloting these systems at the fastest adoption rates in southeastern Europe. This capability is digitizing inventory planning for workshop chains that previously relied on fixed-interval bulk purchasing.
The EU F-Gas Regulation amendments are mandating lower-GWP refrigerant compatibility in automotive air-conditioning lubricants. Bulgarian blenders must reformulate PAG and POE base stocks to accommodate HFO-1234yf and R-744 systems entering the aftermarket. Sofia-based service chains face the steepest retraining burden as hybrid and electric vehicle thermal management complexity escalates.
Workshop procurement consolidation is compressing supplier relationships toward fewer, larger-volume contracts. Independent garages in Bulgaria's secondary cities are abandoning fragmented multi-brand sourcing in favor of single-distributor agreements with technical support commitments. This behavioral shift concentrates most visibly in Varna and Burgas, where maintenance chain density has enabled collective purchasing cooperatives.
Bulgaria Automotive Lubricants Market Segmentation
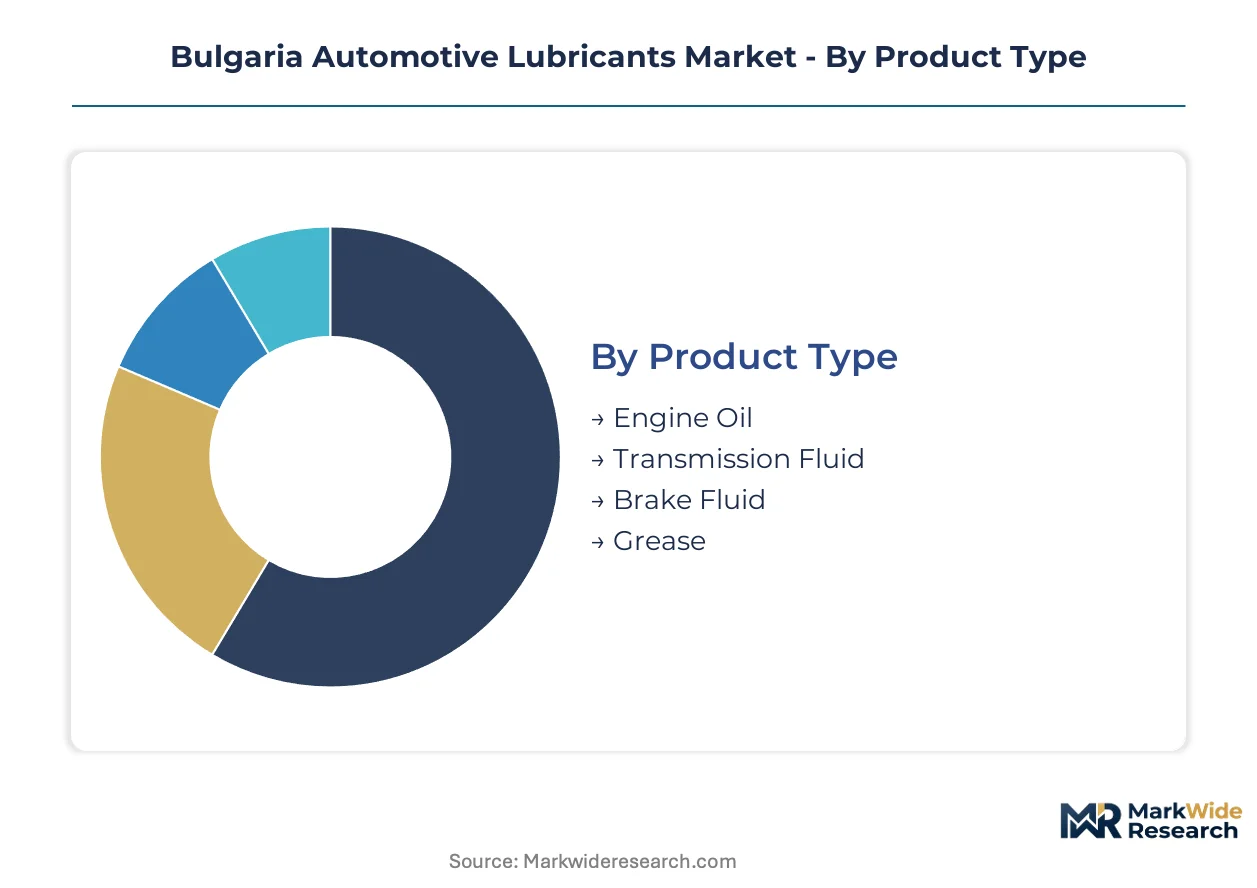
Segmentation in Bulgaria's automotive lubricants market reveals how formulation specifications, procurement patterns, and channel economics split demand across incompatible use cases. Understanding these divisions exposes where margin pools concentrate and where substitution threats emerge.
Product Type:
Formulation chemistry spans friction-reduction, thermal-transfer, and sealing functions across powertrain subsystems with divergent replacement cycles.
- Engine Oil:Base oil mixtures rated SAE 0W-16 to 20W-50 carry detergent and dispersant packages for friction reduction and heat dissipation. Sofia-based fleet operators driving the Trakia motorway corridor prioritize extended-drain synthetics to minimize downtime. REACH registration requirements for additive packages elevate formulation costs for imported blends.
- Transmission Fluid:Viscosity-stabilized formulations for automatic and manual gearboxes demand precise shear stability under cyclic thermal loading. Plovdiv industrial corridor maintenance shops report accelerating synthetic ATF adoption as dual-clutch and CVT penetration rises in Bulgaria's aging fleet. Compatibility certification with legacy seal materials constrains rapid formulation turnover.
- Brake Fluid:Glycol-ether or silicone-based hydraulic media with defined boiling point specifications for DOT 3, 4, and 5.1 classifications. Bulgarian safety inspectors enforce periodic replacement intervals.
- Grease:Thickened lubricants for chassis, wheel bearings, and high-load joints requiring extreme-pressure additive packages. Mining and agricultural equipment in secondary cities sustains demand.
Established volume favors Engine Oil; emerging adoption favors Transmission Fluid.
End User:
Procurement scale and technical specification authority separate direct assembler relationships from fragmented workshop demand.
- OEMs:Original equipment manufacturers specify factory-fill lubricants with direct assembler relationships governing margin concentration. Multinational blenders with Burgas port logistics proximity capture contract volumes for Bulgarian vehicle production facilities. CE marking alignment with EU Green Deal benchmarks shapes qualification timelines.
- Aftermarket Providers:Independent distributors and workshop chains purchase bulk formulations for resale to vehicle owners. Sofia's dense maintenance cluster consolidates toward single-distributor agreements with technical support commitments.
- Vehicle Assemblers:Domestic production facilities requiring just-in-time lubricant delivery synchronized with assembly line schedules. Black Sea port infrastructure enables rapid additive package importation.
- Maintenance Shops:Small independent garages in Varna, Burgas, and secondary cities procuring through wholesale tiers or emerging e-commerce platforms. Collective purchasing cooperatives compress supplier fragmentation.
Margin concentration sits with OEMs; volume expansion accelerates through Aftermarket Providers.
Packaging Type:
Container economics align with consumption scale, storage constraints, and handling infrastructure across urban and rural service points.
- Bottles:Retail-format containers for single-vehicle servicing and consumer DIY segments. Shelf-space competition in Sofia automotive retail chains drives brand visibility investments.
- Drums:Intermediate bulk packaging for high-throughput workshops and fleet maintenance depots along commercial transport corridors.
- Pails:Portable mid-volume containers suited to mobile service operations and secondary city garages with limited storage footprint.
- Bulk:Tanker or tote deliveries to large fleet operators and industrial maintenance facilities with on-site storage infrastructure. Plovdiv industrial corridor penetration presents whitespace for specialized bulk distribution networks.
Drums dominate workshop procurement; Bulk gains traction among consolidated fleet operators.
Distribution Channel:
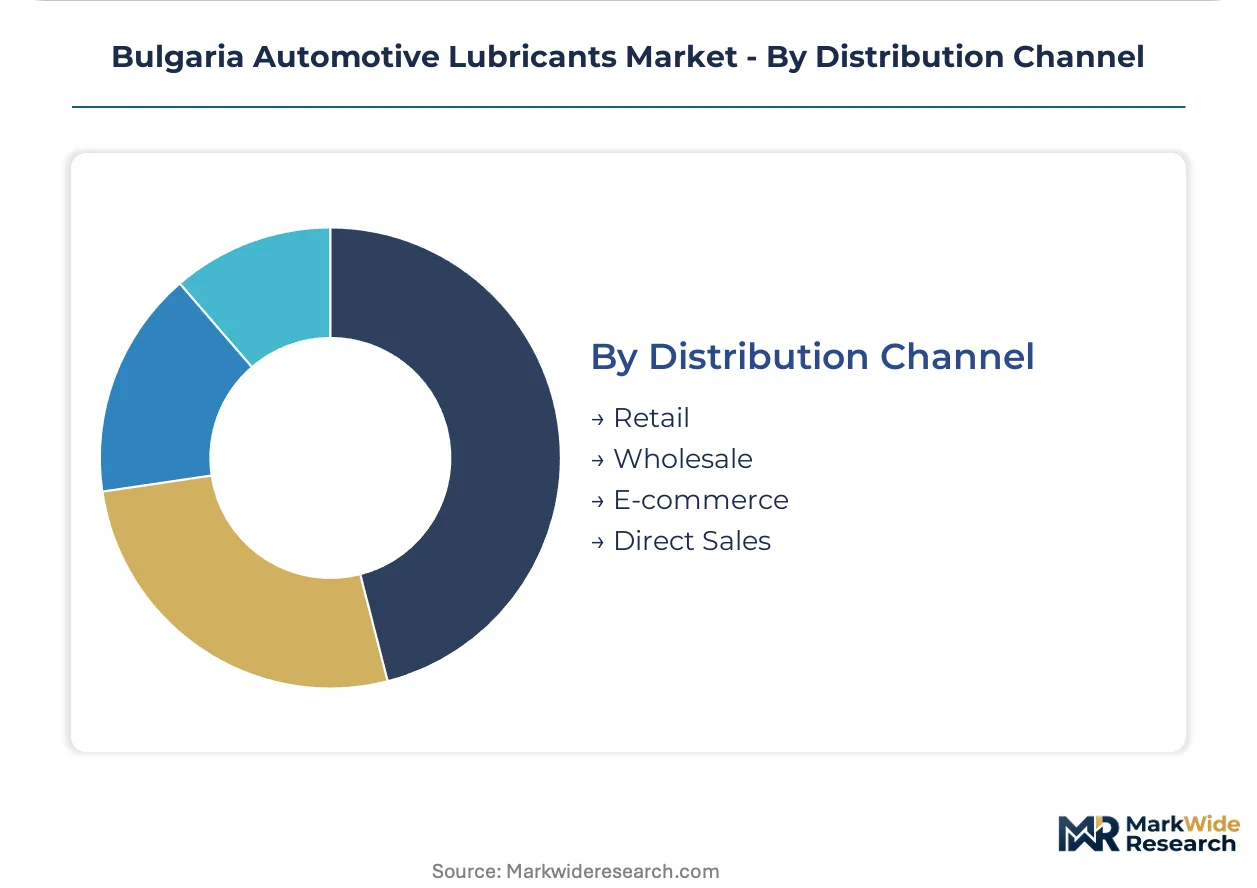
Channel selection reflects customer density, technical service requirements, and price transparency preferences across Bulgaria's urban hierarchy.
- Retail:Automotive parts stores and service stations serving consumer DIY and emergency replacement demand. Physical presence requirements limit penetration outside Sofia and major regional centers.
- Wholesale:Distributor networks supplying workshop chains and independent garages with inventory financing and technical training. Prista Oil's extensive wholesale coverage across secondary cities anchors domestic mid-tier channel control.
- E-commerce:Direct-to-workshop platforms collapsing traditional wholesale tiers through price transparency and consolidated logistics. This channel is expanding most quickly in Sofia's dense maintenance cluster, capturing margin pool redistribution.
- Direct Sales:Manufacturer-to-fleet contracts bypassing intermediary markups for large-volume purchasers with predictable consumption patterns. Shell's Burgas blending facility proximity enables competitive direct pricing to Black Sea logistics operators.
Wholesale retains volume leadership; E-commerce demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bulgaria's automotive lubricant trade flows reflect southeastern Europe's position as a net importer of high-performance additive packages, with domestic blending capacity concentrated around Burgas port infrastructure serving both local consumption and re-export to neighboring markets.
Sofia Capital Region
Fleet operators along the Trakia motorway corridor drive synthetic lubricant demand for extended-drain intervals and fuel economy compliance. The Bulgarian Institute for Standardization enforces CE marking alignment with EU Green Deal benchmarks for all commercial transport formulations. Dense maintenance clusters in Sofia's industrial zones consolidate procurement toward single-distributor agreements with technical support commitments.
Plovdiv Industrial Corridor
Dual-clutch and CVT penetration in Bulgaria's aging fleet accelerates synthetic ATF adoption among independent workshops. REACH registration requirements for additive packages elevate formulation costs for imported transmission fluids. Underdeveloped service partnerships in Plovdiv present whitespace for specialized synthetic distribution networks targeting the city's manufacturing base.
Black Sea Coastal Zone
Burgas port infrastructure enables rapid additive package importation, reducing lead times for domestic blending operations. Shell leverages its blending facility near Burgas to sustain supply chain proximity for southeastern European markets. Collective purchasing cooperatives in Varna compress supplier fragmentation among independent garages.
Secondary City Networks
Price-sensitive owner-operators in Ruse, Stara Zagora, and Pleven resist synthetic premiums despite documented total-cost-of-ownership advantages. Prista Oil anchors mid-tier channel control through extensive wholesale coverage across these secondary markets. E-commerce platforms bypass traditional wholesale tiers slowly outside Sofia's dense maintenance cluster.
Bulgaria Automotive Lubricants Market Competitive Environment
On the supply side, the industry is tiered between multinational blenders with direct assembler relationships and domestic distributors controlling mid-tier wholesale channels. Three strategic archetypes dominate: premium synthetic specialists leveraging technical service partnerships, scale-driven refiners with captive port infrastructure, and regional wholesale networks with secondary city coverage. Competitive moves concentrate on e-commerce channel expansion and biodegradable formulation positioning ahead of anticipated carbon border adjustments.
Within the premium synthetic tier, Castrol and Shell exemplify multinational blender archetypes with differentiated supply chain configurations. Castrol occupies a position emphasizing specialized service partnerships with maintenance chains, while Shell anchors scale-driven supply through its Burgas blending facility proximity. Prista Oil sits within the domestic mid-tier archetype, representing extensive wholesale coverage across Bulgaria's secondary city networks. These three players collectively illustrate how formulation sophistication, logistics positioning, and channel density segment competitive advantage in this market.
| Leading Market Players |
|---|
| Shell |
| Castrol |
| TotalEnergies |
| Prista Oil |
| Lukoil |
| Fuchs Petrolub |
| Chevron |
| ExxonMobil |
| AVIA International |
| Others |
Value Chain & Pricing Dynamics
REACH registration cost concentration for imported additive packages widens pricing spreads between premium synthetic and mineral formulations while compressing mid-tier margins. Bulgarian blenders face dual pressure: EU Green Deal compliance investments elevate base stock costs, while fleet operators in Sofia and Plovdiv demand extended-drain synthetics that reward technical performance over commodity positioning.
Pricing Analysis
The technology-generation pricing gap separates next-generation low-viscosity synthetics from legacy mineral oils and current mid-tier semi-synthetics. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity, with PAO and Group III base stocks commanding premiums over Group I/II mineral stocks. Price differentiation rests on certification grade alignment with EU F-Gas Regulation and after-sales technical support bundling. Cost compression in the mid-tier is intensifying because REACH-registered additive packages concentrate among fewer suppliers. Owner-operators in secondary cities exhibit highest price sensitivity; OEM supply contracts show lowest sensitivity due to total-cost-of-ownership accounting.
Supply Chain Analysis
Tariff exposure between northwestern European refiners and Bulgarian blenders dominates supply chain risk calculations for Group III and PAO feedstock procurement. Geographic supply concentration centers on Germany, the Netherlands, and Belgium for high-performance base stocks, while additive packages draw from specialized chemical producers in France and Italy. Raw material dependencies include polyalphaolefin base stocks, detergent-dispersant additive packages, and viscosity modifier polymers. Single-source vulnerability exists for REACH-registered additive formulations lacking domestic Bulgarian alternatives. Distribution runs through Burgas port infrastructure into wholesale networks serving Sofia's dense maintenance cluster and secondary city cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bulgaria's automotive lubricant market rewards service-attach strategies where technical support partnerships and predictive maintenance platforms expand recurring revenue faster than standalone product sales. Workshop procurement consolidation creates durable subscription-like relationships for blenders investing in diagnostic capabilities and inventory management systems.
For Market Incumbents: Harden channel control through exclusive technical service partnerships with Sofia-based maintenance chains facing EU F-Gas Regulation retraining burdens. Deepen backward integration into additive package blending at Burgas to offset REACH registration cost concentration. Incumbents must defend against e-commerce platforms collapsing wholesale tiers by embedding proprietary condition monitoring tools that lock in fleet operator loyalty through predictive replacement scheduling. For New Entrants and Emerging Players: Plovdiv's underdeveloped synthetic distribution networks represent the most penetrable entry point among Bulgaria's major urban centers. Secondary city maintenance cooperatives in Varna and Burgas offer whitespace for specialized bulk delivery models bypassing Prista Oil's wholesale dominance. New entrants should anchor go-to-market strategies on direct-to-workshop digital platforms with technical documentation support, targeting independent garages abandoning fragmented multi-brand sourcing. For Investors and Strategic Acquirers: Domestic mid-tier distributors with established Bulgarian Institute for Standardization partnerships and secondary city wholesale coverage offer the strongest acquisition target archetype for platform consolidation plays. Long-term viability hinges on positioning ahead of EU carbon border adjustments through biodegradable ester formulation capabilities. Investors should monitor F-Gas Regulation amendment timelines as inflection indicators for refrigerant-lubricant compatibility investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Ester Formulation Development | Positions blenders ahead of EU carbon border adjustments on high-carbon lubricant imports. |
| Predictive Maintenance Platform Integration | Transforms Sofia fleet operators from transactional buyers into recurring-revenue service subscribers. |
| Plovdiv Distribution Network Expansion | Captures whitespace in Bulgaria's second-largest city with specialized synthetic ATF penetration. |
| REACH Registration Partnership Consolidation | Reduces compliance cost burden for additive package importation through shared Bulgarian Institute for Standardization pathways. |
| E-commerce Direct-to-Workshop Launch | Bypasses traditional wholesale tiers in Sofia's dense maintenance cluster to capture margin pool redistribution. |
Study Parameters
A standing panel of lubricant formulation chemists, fleet procurement managers at Sofia-based transport operators, aftermarket distributors along the Trakia motorway corridor, and Bulgarian Institute for Standardization certification officers provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation from EU REACH registration databases, Bulgarian customs trade statistics, and SEC filings of multinational blenders with Burgas port operations. Bottom-up channel volume estimates triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing framed the analytical approach, with growth projections tested against regulatory acceleration and mineral oil substitution ceiling constraints. Segmentation dimensions modeled include formulation chemistry tier, end-user procurement scale, packaging volume class, and distribution channel density. CAGRs derived from historical volume trajectories adjusted for synthetic adoption elasticity and fleet operator consolidation patterns. Industry-specific inputs encompassed EU F-Gas Regulation amendment timelines and Black Sea logistics capacity utilization rates.
Practitioners should monitor REACH registration cost inflation, EU carbon border adjustment proposal advancement, and synthetic formulation chemist availability at Bulgarian technical universities for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Axle and Propeller Shaft Market
Automotive Parts
Automotive All Wheel Drive Market
Automotive Parts
Off-Road Hoses Market
Automotive Parts
Automotive Oil Pressure Switch Market
Automotive Parts
Global EV Speed Reducer Market
Automotive Parts
Automotive AHSS Market
Automotive Parts
Germany Automotive Parts Zinc Die Casting Market
Automotive Parts
Undercarriage Systems Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
Accelerator Pedal Module Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Malaysia Passenger Vehicles Lubricants Market
Automotive Parts
Fuel Injection Cleaning Machine Market
Automotive Parts
Global Automotive Brake Hose Market
Automotive Parts
Qatar Passenger Vehicles Lubricants Market