
 Industrial Barrier Systems Market | 2026-2036
Industrial Barrier Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Barrier Systems Market Analytics
Multi-source procurement for polymer components is recalibrating how system integrators manage supply risk across the industrial barrier value chain. A-Safe leverages in-house polyethylene extrusion to control resin specifications for its flexible barrier line. Rite-Hite sustains manufacturing scale through captive steel fabrication for its loading dock safety gates. BOPLAN competes on modular design architecture that reduces on-site installation labor.
Industrial barrier systems are engineered protective structures—fabricated from steel, polyethylene, concrete, or rubber—that demarcate hazard zones, control vehicle traffic, and absorb impact energy in industrial environments, typically rated for specific load capacities measured in kilonewtons. Their primary purpose is to prevent personnel injury and equipment damage in high-risk operational areas. Permanent barriers dominate installed base value due to infrastructure longevity requirements in manufacturing plants, while temporary barriers represent the fastest-expanding product category driven by cyclical construction site demand. Steel anchors margin pools in heavy-duty applications, though polyethylene is displacing legacy materials in food-grade warehouse environments where corrosion resistance and cleanability matter.
OSHA mandates impact-resistance testing for workplace barriers, while the EU Machinery Directive through CE marking governs safety gate interlock standards for European exports. China's MEE enforces environmental compliance on concrete barrier production, adding embodied-carbon documentation requirements. Stakeholders must monitor evolving polymer recycling regulations and their effect on material specification decisions across customer segments.
Market Dynamics
Polyethylene formulation advances are compressing steel's historical dominance in medium-duty warehouse applications, forcing incumbent fabricators to recalibrate material portfolios and captive extrusion investments.
Growth Catalysts
- OSHA workplace safety mandates:Federal requirements for impact-rated pedestrian protection in distribution facilities are accelerating barrier replacement cycles across US logistics networks.
- Food-grade corrosion resistance:Polyethylene barriers eliminate rust contamination risks in cold storage environments, displacing legacy steel installations in pharmaceutical and protein processing plants.
- Gulf Coast petrochemical corridor:Concentrated capital expansion around Houston and Corpus Christi is generating sustained demand for heavy-duty vehicle restraint systems at new processing facilities.
Market Restraints
- Steel price volatility:Input cost swings for hot-rolled coil compress margin predictability for fabricators serving heavy-duty mining and port applications.
- Concrete embodied-carbon documentation:China's MEE environmental compliance standards add administrative burden and certification delays to cast-in-place barrier projects.
- Modular plastic substitution:Interlocking polyethylene systems threaten permanent concrete installations in temporary construction site applications.
Strategic Opportunities
- India warehouse automation:Underpenetrated cold chain infrastructure presents white space for corrosion-resistant barrier specifications in emerging distribution hubs near Mumbai and Delhi.
- EU Machinery Directive convergence:CE marking requirements for safety gate interlocks create upgrade demand at European manufacturing exporters serving unified market access.
- Rental fleet expansion:Equipment-as-a-service models for temporary barriers unlock construction contractor segments previously priced out of capital purchase.
Industry Challenges
- Polymer recycling specification gaps:Divergent national standards for post-industrial polyethylene content complicate multi-territory product line management.
- Installation labor coordination:Site-specific anchoring requirements demand specialized contractor networks that fragment project execution timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Barrier Systems Market |
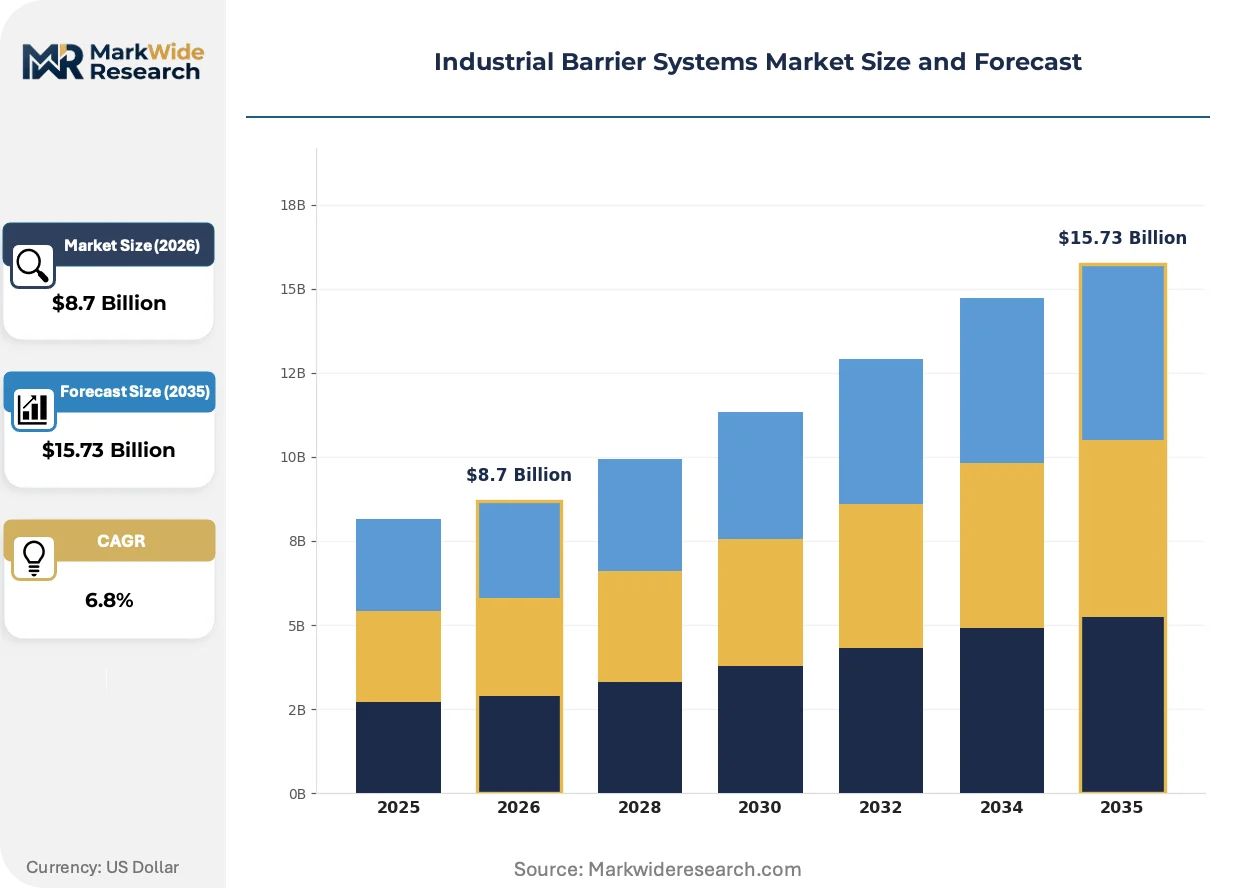
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temporary Barriers, Permanent Barriers, Safety Gates, Traffic Barriers Material: Steel, Polyethylene, Concrete, Rubber Application: Construction Sites, Warehouses, Manufacturing Plants, Road Safety End User: Industrial Facilities, Logistics Companies, Government Agencies, Educational Institutions |
| Companies Covered | A-Safe, BOPLAN, Rite-Hite, Betafence, Valmont Industries Inc., Hill & Smith PLC, Lindsay Corporation, CAI Safety Systems, Inc., Kirchdorfer Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Barrier Systems Market Evolving Landscape
Material science breakthroughs and regulatory harmonization pressures are restructuring competitive advantage around formulation control and modular system architecture rather than fabrication scale alone.
Advanced polyethylene compounds with embedded colorants and UV stabilizers are converging with automated guided vehicle navigation requirements in high-throughput distribution centers. E-commerce fulfillment operators specify these materials for their radar-transparency and cleanability. The technology is converging with warehouse management system integration, compressing the traditional separation between physical infrastructure and digital floor planning.
REACH substance restrictions and RoHS compliance deadlines in Europe are eliminating legacy plasticizers from barrier polymer formulations. Compounders must reformulate for halogen-free flame retardancy without sacrificing impact resistance ratings. Medical device and food processing exporters to the EU face the steepest recertification timelines, accelerating supplier qualification processes.
Buyers are unbundling installation services from hardware procurement, treating on-site labor as a separately sourced line item. General contractors and facility managers now compare turnkey quotes against material-only purchases with self-managed subcontractor deployment. This pattern is most pronounced in the United States Midwest distribution hub construction, where developer-owners seek capital expenditure flexibility through phased occupancy.
Industrial Barrier Systems Market Segmentation
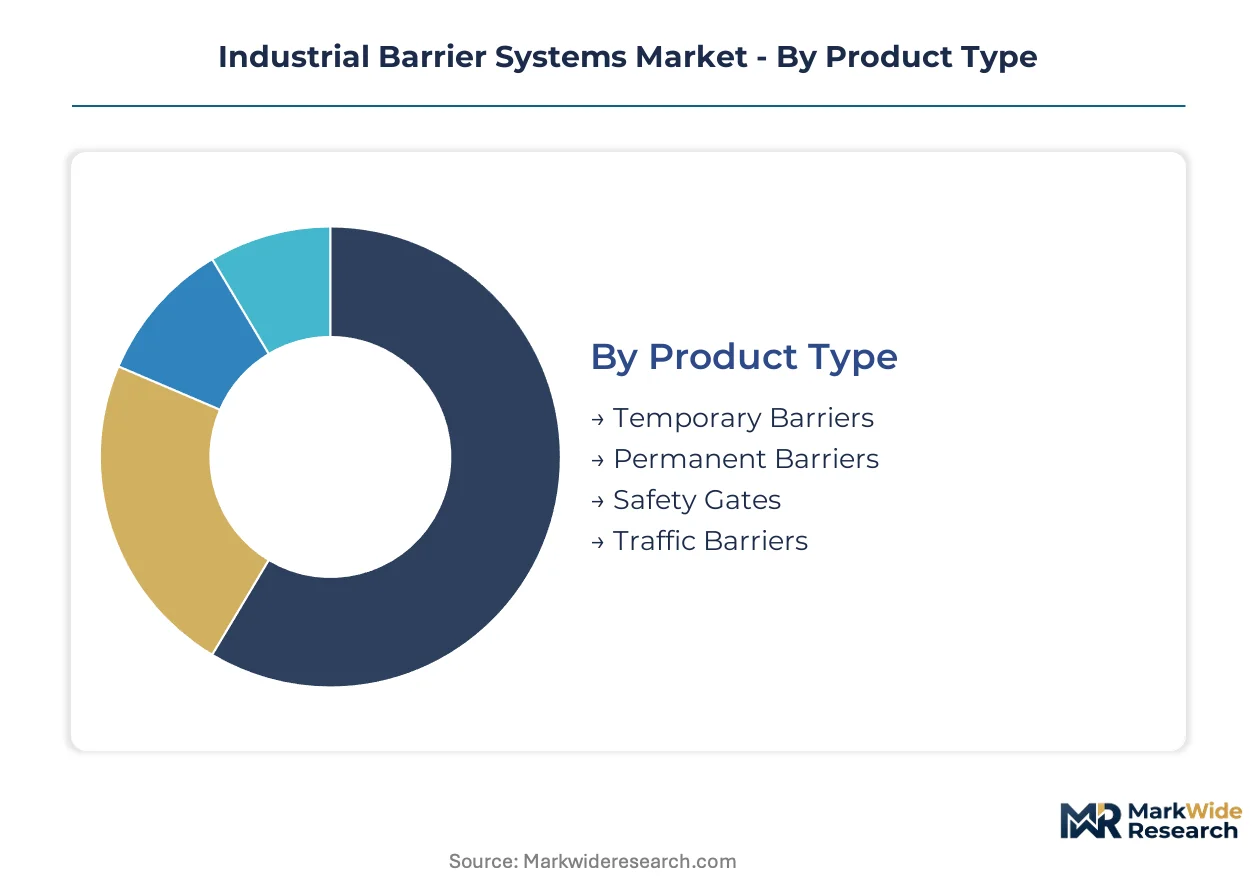
Industrial barrier procurement decisions split across durability requirements, regulatory exposure, and installation permanence. Buyers weigh capital intensity against operational flexibility when matching product specifications to hazard profiles and facility lifecycle planning.
Product Type:
Capital deployment horizons and site mobility requirements dominate product selection across end-use sectors.
- Permanent Barriers:Cast-in-place concrete and anchored steel systems rated for multi-ton impact loads. Demand concentrates in Gulf Coast petrochemical processing facilities where OSHA mandates fixed pedestrian protection corridors alongside heavy vehicle traffic.
- Temporary Barriers:Modular polyethylene and interlocking rubber systems designed for rapid deployment and relocation. Cyclical construction site demand in the United States Midwest distribution hub corridor drives replacement cycles and rental fleet utilization.
- Safety Gates:Interlocking access control systems with mechanical or electronic actuation. Pharmaceutical cleanrooms and cold storage facilities specify corrosion-resistant polyethylene variants to eliminate rust contamination.
- Traffic Barriers:Directional flow management systems for vehicle and pedestrian separation. Road safety applications around Houston and Corpus Christi industrial zones absorb sustained public infrastructure investment.
Permanent barriers lead on installed base value; temporary barriers lead on momentum.
Material:
Corrosion exposure, impact rating requirements, and cleanability standards dictate material specification across facility types.
- Polyethylene:UV-stabilized extruded compounds with embedded colorants for AGV radar transparency. Food-grade warehouse operators in protein processing and pharmaceutical cold storage prioritize polyethylene for rust elimination and washdown compatibility.
- Steel:Hot-rolled coil fabrication with galvanized or powder-coated finishes for heavy-duty mining and port applications. Margin predictability compresses when raw material price volatility disrupts fabricator pricing power.
- Concrete:Cast-in-place and precast systems with documented embodied-carbon footprints. China's MEE environmental compliance standards add certification delays that disadvantage concrete against modular alternatives in time-sensitive projects.
- Rubber:Recycled and virgin polymer blends for impact absorption and noise dampening. Modular interlocking designs threaten permanent installations in temporary construction site specifications.
Steel dominates heavy-duty value; polyethylene climbs the fastest in warehouse conversion projects.
Application:
Regulatory enforcement intensity and operational hazard density shape application-level demand concentration.
- Warehouses:High-throughput distribution centers specify radar-transparent polyethylene barriers for AGV navigation integration. E-commerce fulfillment operators in the United States drive specification convergence between physical infrastructure and warehouse management systems.
- Manufacturing Plants:Permanent anchored systems for fixed production line protection. OSHA workplace safety mandates accelerate barrier replacement cycles across automotive and electronics assembly facilities.
- Construction Sites:Modular temporary systems for phased project deployment. General contractors unbundle installation from hardware procurement to preserve capital expenditure flexibility.
- Road Safety:Public infrastructure barriers for highway work zones and permanent traffic separation. Government procurement cycles introduce budget-dependent demand volatility.
Warehouses lead on specification innovation; construction sites lead on volume cyclicality.
End User:
Procurement centralization and compliance liability exposure differentiate end-user segment behavior.
- Logistics Companies:National distribution networks with standardized safety protocols and multi-site rollout programs. Midwest hub operators prioritize phased occupancy flexibility through rental fleet arrangements.
- Industrial Facilities:Petrochemical processors and heavy manufacturers with captive maintenance teams and long capital planning horizons. Gulf Coast corridor expansion sustains heavy-duty vehicle restraint demand.
- Government Agencies:Public works and transportation departments with bid-driven procurement and domestic content preferences. Budget authorization timelines fragment project execution.
- Educational Institutions:Campus safety and research facility applications with decentralized decision-making. Smaller transaction sizes limit direct manufacturer engagement.
Logistics companies lead on standardization velocity; industrial facilities lead on contract scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor generates concentrated demand for heavy-duty vehicle restraint systems as processing capacity expands around Houston and Corpus Christi. Midwest distribution hubs absorb modular polyethylene barriers for phased warehouse construction. Regulatory tightening across OSHA jurisdictions and China's MEE standards recalibrates installation specifications.
United States
OSHA workplace safety mandates accelerate barrier replacement cycles across automotive assembly and electronics manufacturing facilities. Federal impact-resistance testing requirements for pedestrian protection corridors tighten specification standards. The Houston-Corpus Christi petrochemical corridor sustains heavy-duty anchored steel demand for multi-ton vehicle restraint at new processing plants.
China
MEE environmental compliance standards impose embodied-carbon documentation requirements on concrete barrier production, extending certification timelines. Cold chain infrastructure expansion around Shanghai and Shenzhen drives food-grade polyethylene specifications in pharmaceutical and protein processing applications. GB standards for workplace safety equipment tighten testing protocols for imported barrier systems.
Germany
EU Machinery Directive CE marking requirements for safety gate interlocks create upgrade demand at manufacturing exporters serving unified market access. REACH substance restrictions and RoHS compliance deadlines eliminate legacy plasticizers from polymer formulations. The Ruhr industrial region and Bavarian automotive clusters specify corrosion-resistant barriers for cleanroom and cold storage environments.
India
BIS certification requirements for industrial safety equipment add compliance layers to barrier procurement decisions. Underpenetrated cold chain infrastructure near Mumbai and Delhi presents specification opportunities for corrosion-resistant polyethylene systems. The Delhi-Mumbai Industrial Corridor and Gujarat manufacturing zones absorb modular temporary barriers for construction-phase deployment.
United Kingdom
CDM Regulations 2015 impose construction-phase safety planning requirements that elevate temporary barrier specifications on major infrastructure projects. Post-Brexit divergence from EU Machinery Directive standards creates certification complexity for safety gate exporters. The Midlands distribution hub and Thames Gateway logistics corridors specify AGV-compatible radar-transparent polyethylene barriers for automated warehouse integration.
Industrial Barrier Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular rental-fleet and equipment-as-a-service models. The vendor base clusters around three strategic archetypes: captive extrusion specialists controlling resin formulation, scale fabricators with backward integration into steel coil processing, and modular design architects optimizing for rapid on-site deployment. Competitive moves concentrate on geographic expansion through distribution partnerships and portfolio diversification into adjacent safety equipment categories.
Within the formulation-control archetype, A-Safe anchors polyethylene specification expertise through in-house extrusion capabilities. Rite-Hite occupies a position exemplifying scale-driven fabrication with captive steel processing infrastructure. BOPLAN represents modular architecture specialization, competing on reduced installation labor requirements through interlocking system design. These three fabricators illustrate the strategic segmentation between material control, manufacturing scale, and deployment efficiency that defines competitive positioning.
| Leading Market Players |
|---|
| A-Safe |
| BOPLAN |
| Rite-Hite |
| Betafence |
| Valmont Industries Inc. |
| Hill & Smith PLC |
| Lindsay Corporation |
| CAI Safety Systems, Inc. |
| Kirchdorfer Industries |
| Others |
Value Network & Pricing Analysis
China's MEE embodied-carbon documentation requirements for concrete barrier production gate qualified supply access and premium-tier pricing for projects requiring environmental certification. Buyers seeking MEE-compliant documentation face extended lead times and elevated procurement costs, while polyethylene system integrators capture margin premiums through faster qualification pathways.
Pricing Analysis
Hot-rolled coil price volatility passes through directly to steel-fabricated barrier pricing, compressing margin predictability for heavy-duty mining and port applications. Three-tier pricing structure across premium, standard, and economy levels separates OSHA-certified impact-rated systems from uncertified commodity alternatives. Cost compression in standard-grade polyethylene runs through multi-source resin procurement strategies. Logistics companies with national distribution networks exhibit lowest price sensitivity due to standardized safety protocols, while small educational institutions face acute budget constraints.
Supply Chain Analysis
CE marking and OSHA certification requirements gate supplier qualification, filtering access to European and North American project specifications. Manufacturing concentrates in the United States, Germany, and China, with each hub serving distinct regulatory jurisdictions. Resin formulation draws from petrochemical feedstocks anchored in Gulf Coast processing capacity. Single-source vulnerability persists in specialized UV-stabilizer additives for AGV-transparent polyethylene compounds. Distribution runs through system integrators and industrial safety distributors with certified installation contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial barrier markets offer margin expansion through formulation-control investments that displace commodity steel alternatives, with polyethylene compounders capturing value from corrosion-resistant specification shifts in food-grade warehouse environments.
For Market Incumbents: Extend captive extrusion capabilities to lock in resin specification control and defend against modular polyethylene entrants threatening permanent concrete installations. Deepen backward integration into polymer compounding to secure halogen-free flame retardant formulations ahead of REACH compliance deadlines. Channel control through certified installer networks preserves pricing power against unbundled procurement trends. For New Entrants and Emerging Players: Equipment rental fleet operators represent the most penetrable channel partner type for construction contractor segments previously priced out of capital purchase. Target India's underpenetrated cold chain infrastructure near Mumbai and Delhi with corrosion-resistant polyethylene specifications. Pursue equipment-as-a-service models that unlock recurring revenue streams from cyclical construction demand. For Investors and Strategic Acquirers: Valuations sit cheapest among regional steel fabricators lacking polymer formulation capabilities or AGV-integration expertise. Long-term viability centers on material science differentiation rather than fabrication scale alone. Watch for inflection signals in OSHA pedestrian protection mandate enforcement intensity across Midwest distribution hub construction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH-compliant halogen-free formulations secure EU market access for food-grade barrier exporters. |
| Rental Fleet Expansion | Equipment-as-a-service models capture construction contractor demand through capital expenditure flexibility. |
| AGV-Compatible Product Line Development | Radar-transparent polyethylene compounds align with warehouse automation specifications in e-commerce fulfillment. |
| Certified Installer Network Control | OSHA-compliant installation services defend margin against unbundled procurement trends in Midwest distribution. |
| India Market Entry Partnership | BIS certification navigation through local joint ventures accelerates access to Delhi-Mumbai Industrial Corridor projects. |
Research Methodology
Direct dialogue with plant safety managers, logistics procurement directors, polymer compound technical leads, and construction project managers grounded qualitative insights in operational reality. Secondary validation drew from OSHA enforcement databases, EU Machinery Directive CE marking registries, China's MEE environmental compliance filings, and customs trade records for industrial safety equipment. Bottom-up demand modeling triangulated against top-down market sizing across product type, material specification, application sector, and end-user category dimensions.
Bottom-up volume builds aggregated facility-level barrier deployment rates by sector, while top-down cross-checks calibrated against regional construction spending and warehouse automation investment flows. Segmentation dimensions spanned permanent versus temporary installation permanence, polyethylene versus steel versus concrete material tiers, warehouse versus manufacturing versus construction site applications, and logistics company versus industrial facility versus government agency end-user archetypes. CAGRs derived from regression-adjusted deployment trajectories incorporating OSHA mandate phase-in schedules and MEE compliance timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to polymer recycling regulation divergence across jurisdictions and steel price volatility persistence. Model assumptions reflect documented regulatory enforcement patterns and material substitution elasticities observed in warehouse conversion projects. A model refresh is warranted upon material change in OSHA pedestrian protection corridor mandate expansion or REACH substance restriction amendment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Europe Airport Passenger Screening Systems Market
Access Control Systems
Europe Cylinder Lock Market
Access Control Systems
Asia-Pacific Access Control Hardware Market
Access Control Systems
Global Industrial Access Control Market
Access Control Systems
Electronic Security Systems Market
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
North America Access Control Software Market
Access Control Systems
Germany Access Control Market
Access Control Systems
North America Smart Locks Market
Access Control Systems
Global Smart Lock Market
Access Control Systems
Airport Passenger Screening System Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Mode Locking Device Market
Access Control Systems
Pedestrian Entrance Control System Market
Access Control Systems
Wireless Security System Market