
 Japan Access Control Market | 2026-2036
Japan Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Access Control Market Insights
Japan's cybersecurity technician shortage is reorganizing procurement priorities across the access control value chain. NEC Corporation leverages deep biometric R&D pipelines to anchor government facility deployments nationwide. Panasonic Corporation sustains manufacturing scale advantages in smart card and NFC reader production for commercial building integrators. ASSA ABLOY competes through door hardware-to-electronics integration that reduces installation complexity for shrinking installer pools.
Access control systems encompass electromechanical and electronic solutions that authenticate identity through credential verification, biometric template matching, or encrypted token validation to regulate physical entry points. These systems integrate with building management platforms to log audit trails, manage time-and-attendance records, and enforce zone-based permissions across multi-tenant facilities. Biometric technology leads segment value generation as vein-pattern and facial recognition systems displace legacy card readers in high-security government and financial installations. Cloud-based deployment represents the fastest-expanding architecture as Japanese enterprises migrate from on-premises servers to subscription-managed identity platforms that reduce IT maintenance burdens. Mobile solutions occupy emerging niche positions in hospitality and retail settings where smartphone credentialing eliminates physical card distribution costs.
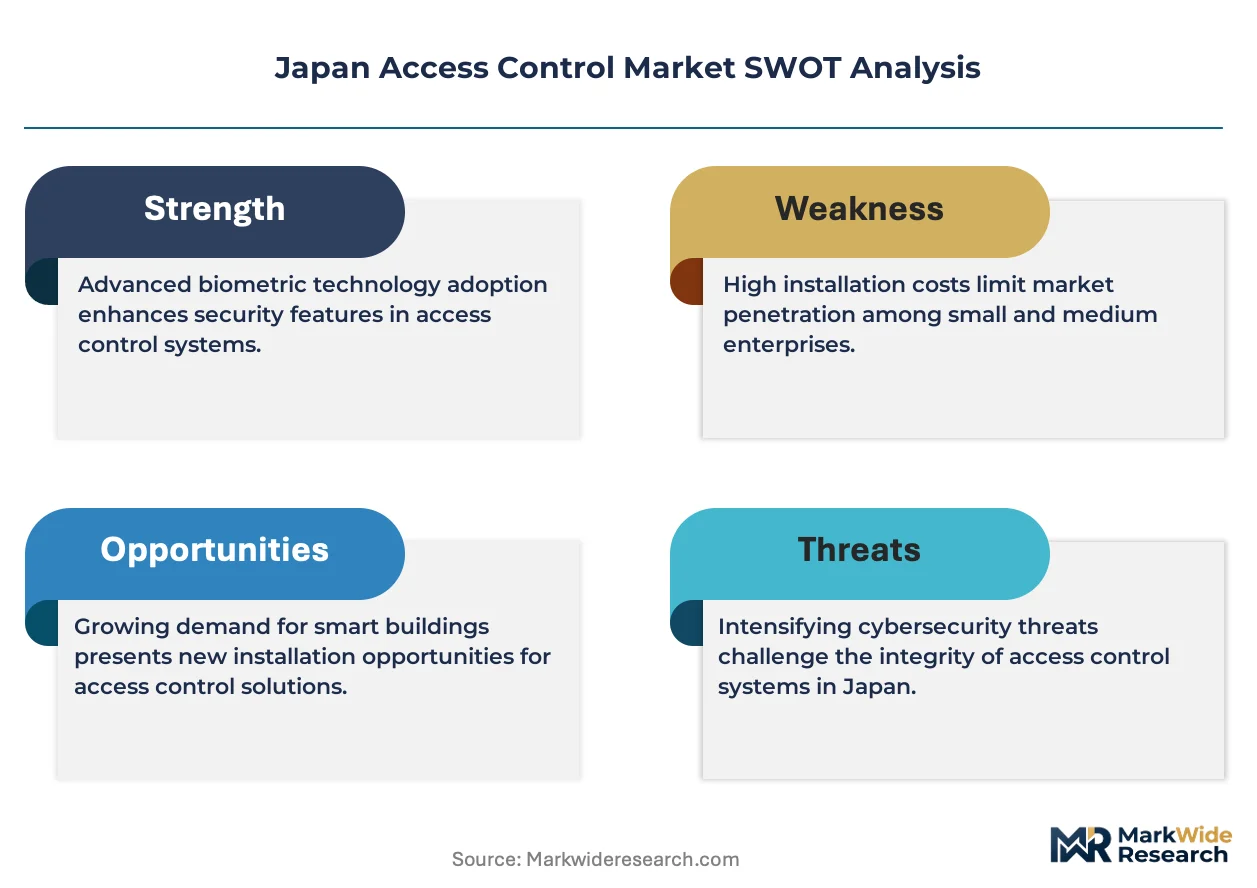
METI's cybersecurity guidelines for critical infrastructure operators mandate multi-factor authentication protocols that directly expand biometric and smart card system procurement. JIS standards for building automation interoperability shape product certification requirements that vendors must satisfy for commercial project eligibility. PMDA facility security rules for pharmaceutical manufacturing sites add compliance-driven demand layers for access control with audit-grade logging capabilities. Stakeholders must weigh cloud migration timelines against lingering data sovereignty preferences that continue favoring hybrid architectures in defense-adjacent and healthcare verticals.
Market Dynamics
Japan's contracting security technician workforce is compressing deployment timelines and forcing integrators toward pre-configured, cloud-managed systems that reduce on-site configuration demands. This labor scarcity is reshaping procurement specifications across commercial real estate and critical infrastructure verticals.
Growth Catalysts
- METI Cybersecurity Framework:Mandatory multi-factor authentication for critical infrastructure operators directly expands biometric reader and smart card system procurement across energy and transportation facilities.
- Smart City Infrastructure:Tokyo, Osaka, and Fukuoka metropolitan investments cluster access control within integrated building management platforms for new commercial construction.
- Vein-Pattern Biometrics:Financial institutions and government facilities adopt finger-vein authentication for its liveness-detection advantages over legacy fingerprint systems.
Market Restraints
- Semiconductor Component Concentration:Specialized NFC and biometric sensor chip supply concentrates among limited Asian foundry sources, creating procurement vulnerability.
- Data Sovereignty Preferences:Defense-adjacent and healthcare verticals resist full cloud migration due to lingering concerns over cross-border data flows.
- Legacy System Interoperability:Existing Wiegand-protocol installations impose technical friction on IP-based upgrade paths, extending replacement cycles.
Strategic Opportunities
- Mobile Credential Convergence:Smartphone-based access is penetrating hospitality and retail settings where physical card distribution costs burden high-turnover operations.
- Building Energy Code Alignment:JIS standards for automation interoperability create certification pathways for integrated access-HVAC systems in commercial retrofits.
- Regional Smart City Expansion:Sapporo and Sendai smart infrastructure investments extend deployment opportunities beyond the three dominant metropolitan corridors.
Industry Challenges
- Cybersecurity Technician Scarcity:The national shortage of qualified integration specialists extends project timelines and elevates labor cost components.
- Hybrid Architecture Complexity:Enterprises managing mixed on-premises and cloud identity platforms face elevated operational overhead during transition phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Access Control Market |
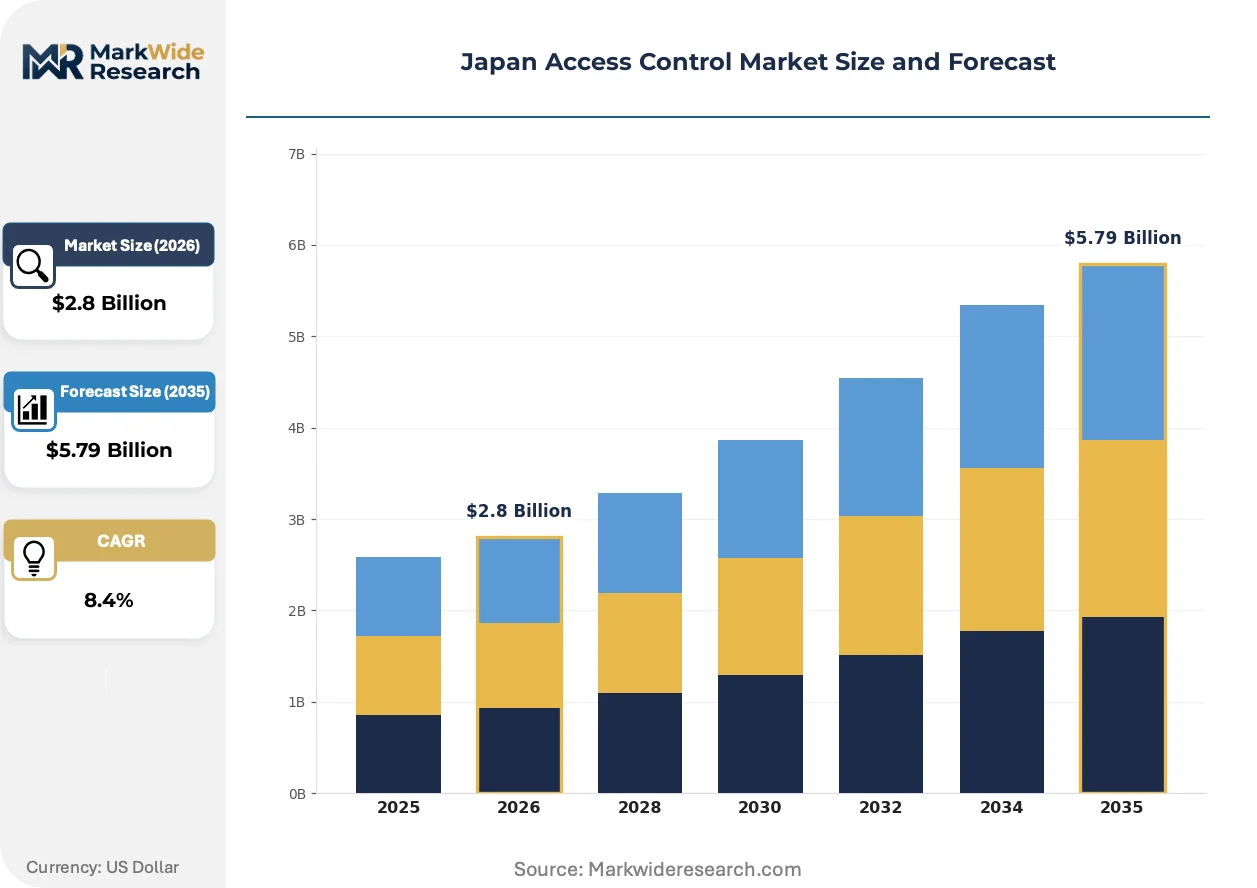
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biometric, Smart Card, NFC, RFID Application: Commercial Buildings, Government Facilities, Residential Properties, Transportation Hubs End User: Retail, Education, Healthcare, Hospitality Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Solutions |
| Companies Covered | NEC Corporation, Panasonic Corporation, ASSA ABLOY, HID Global Corporation, Honeywell International Inc, Bosch Security System Inc, Thales Group, Axis Communications AB, Dormakaba Holding AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Access Control Market Trends and Innovations
Cloud-native identity platforms are compressing traditional hardware-centric business models while biometric modalities shift toward contactless formats. Regulatory pressure on critical infrastructure authentication is accelerating technology refresh cycles.
Vein-pattern recognition is supplanting fingerprint systems in high-security deployments. The technology's liveness-detection capabilities prevent spoofing attempts that defeat optical sensors. Government facilities and financial institutions in Tokyo and Osaka are standardizing on finger-vein terminals. This modality shift is compressing demand for legacy card-plus-biometric dual-factor configurations.
METI's cybersecurity guidelines for critical infrastructure mandate multi-factor authentication protocols that expand procurement specifications. Energy utilities and transportation operators must upgrade existing single-factor systems. The regulation most affects aging on-premises installations requiring hardware replacement. Vendors are pre-certifying products to JIS interoperability standards to accelerate project eligibility.
Facility managers are unbundling after-sales service contracts from initial hardware procurement. Traditional integrator-led maintenance agreements face displacement by manufacturer-direct subscription models. Cloud-managed platforms enable remote diagnostics that reduce technician dispatch frequency. This shift is most visible in commercial real estate portfolios concentrated in the Greater Tokyo Area.
Japan Access Control Market Segmentation
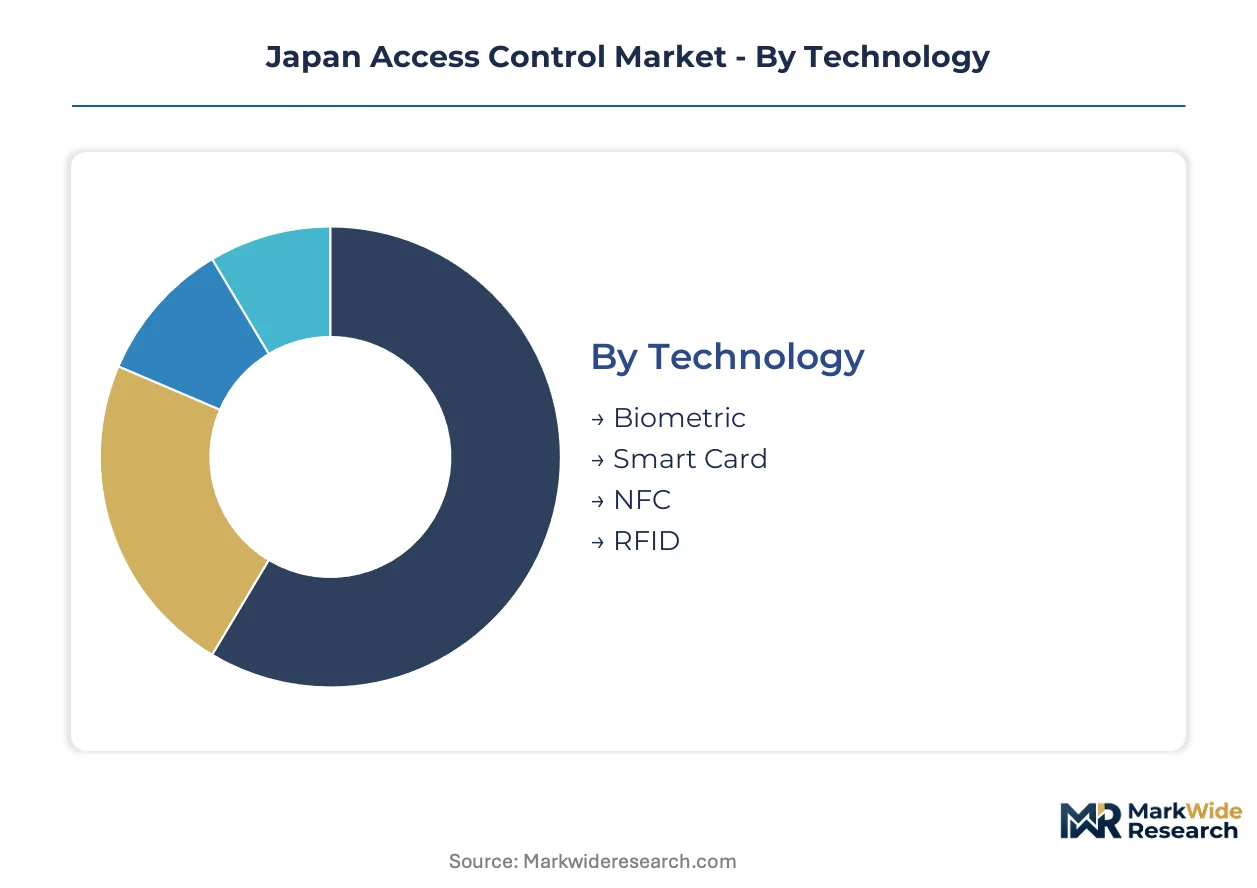
Japan's access control market fragments across technology, application, and deployment dimensions that reflect distinct procurement logics. Segment boundaries are blurring as biometric systems displace credential-based authentication and cloud architectures subsume on-premises infrastructure.
Technology:
Substitution pressure runs strongest against legacy credential formats as biometric liveness detection eliminates spoofing vulnerabilities that plague card-based systems.
- Biometric:Finger-vein and facial recognition systems deploy liveness-detection algorithms that prevent presentation attacks. Tokyo government facilities and Osaka financial institutions standardize on these modalities for high-assurance entry points. METI cybersecurity guidelines mandate multi-factor protocols that accelerate displacement of single-factor alternatives.
- Smart Card:Contact and contactless credential formats retain installed-base dominance across commercial real estate portfolios. Panasonic Corporation maintains manufacturing scale for MIFARE and FeliCa-compatible readers serving building automation integrators in the Greater Tokyo Area. JIS interoperability certification requirements preserve procurement relevance despite biometric encroachment.
- NFC:Short-range wireless credentialing enables smartphone-tap entry without dedicated reader hardware.
- RFID:Long-range passive tags support hands-free vehicle and personnel tracking at logistics facilities.
Smart card anchors the volume base while biometric gains share at the steepest rate.
Application:
Cost-tier differentiation separates high-compliance government deployments from price-sensitive residential installations.
- Commercial Buildings:Multi-tenant office towers in Tokyo, Osaka, and Fukuoka integrate access control with building management platforms for unified HVAC and security orchestration. JIS automation interoperability standards shape product certification requirements for new construction and retrofit projects.
- Government Facilities:Defense-adjacent sites and critical infrastructure operators face METI-mandated multi-factor authentication upgrades. PMDA pharmaceutical manufacturing security rules add audit-grade logging requirements that elevate system specifications above commercial norms.
- Residential Properties:Apartment complexes and gated communities prioritize cost-efficient credential systems with minimal IT overhead.
- Transportation Hubs:Rail stations and airports require high-throughput authentication for passenger flow management.
Commercial buildings anchor the volume base while government facilities climb the fastest on regulatory compulsion.
End User:
Customer-type fragmentation reflects divergent turnover rates and credential distribution economics.
- Retail:High employee churn drives demand for low-friction credential provisioning and rapid deactivation capabilities.
- Education:Universities and K-12 campuses manage seasonal population fluctuations through semester-based access permissions.
- Healthcare:Hospitals and clinics require zone-based permissions that segregate patient, staff, and pharmaceutical storage areas. PMDA facility security mandates enforce audit-trail retention that shapes system procurement specifications.
- Hospitality:Hotels and resorts adopt mobile credentialing to eliminate front-desk card distribution bottlenecks.
Healthcare anchors the volume base while hospitality expands most quickly on mobile credential adoption.
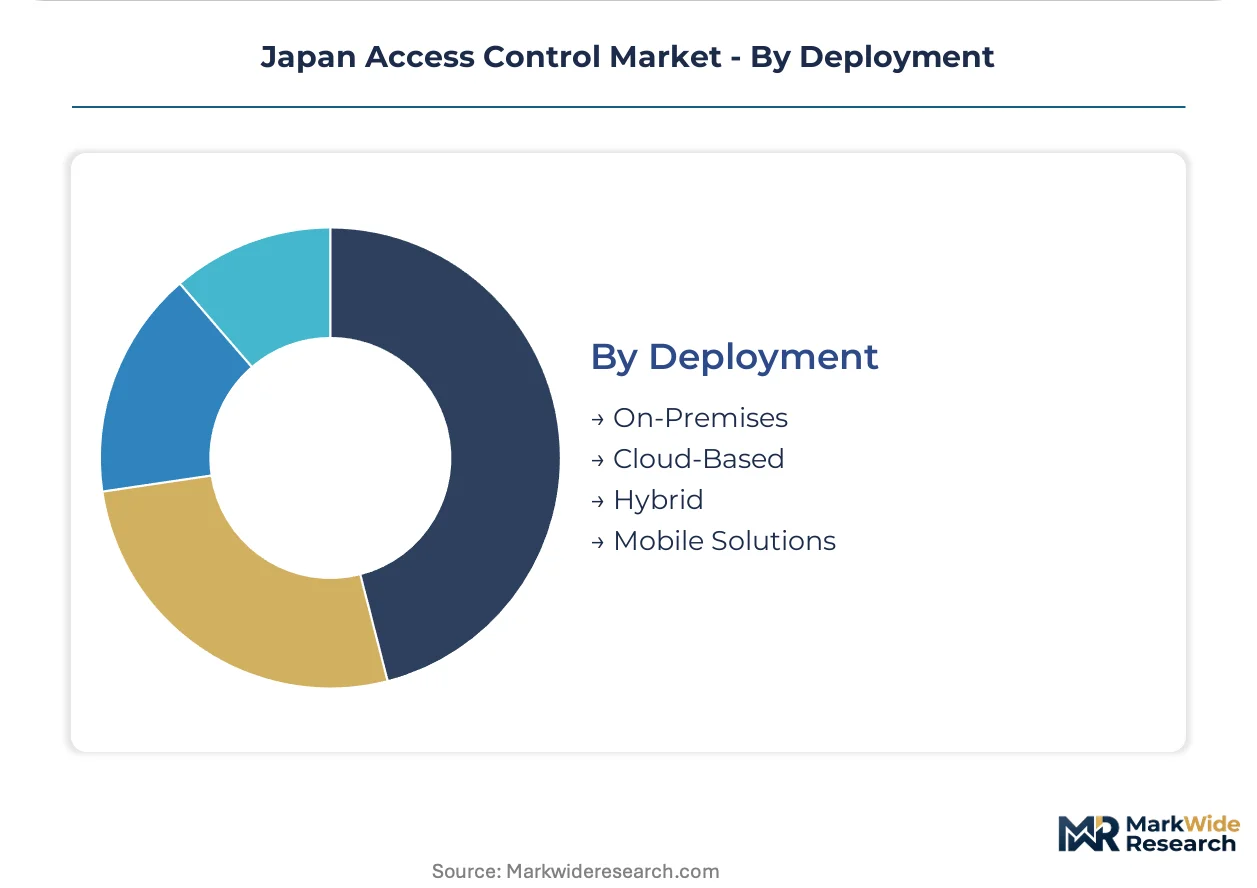
Deployment:
Architecture maturity separates legacy on-premises installations from cloud-native platforms that compress operational overhead.
- On-Premises:Local server architectures retain preference among defense-adjacent and healthcare verticals with data sovereignty constraints. Aging Wiegand-protocol installations impose technical friction on IP-based upgrade paths.
- Cloud-Based:Subscription-managed identity platforms reduce IT maintenance burdens and enable remote diagnostics that address technician scarcity. Commercial real estate portfolios in the Greater Tokyo Area lead migration toward manufacturer-direct service models.
- Hybrid:Mixed architectures accommodate transition-phase enterprises managing legacy system coexistence.
- Mobile Solutions:Smartphone credentialing penetrates hospitality and retail settings where physical card logistics burden high-turnover operations.
On-premises anchors the volume base while cloud-based gains share fastest on labor scarcity and remote management advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Japan's major metropolitan corridors diverge sharply from rural prefectures. Tokyo and Osaka prioritize biometric integration for high-security government and financial installations, while regional cities emphasize cost-efficient credential systems for commercial retrofits.
Kanto/Tokyo
Tokyo's concentration of government ministries and financial headquarters drives premium biometric deployments. METI cybersecurity mandates for critical infrastructure operators accelerate finger-vein and facial recognition procurement across defense-adjacent facilities. The Greater Tokyo Area anchors cloud-managed platform adoption as facility managers unbundle service contracts from hardware procurement.
Kansai/Osaka
Osaka's manufacturing and pharmaceutical clusters generate compliance-driven demand for audit-grade access logging. PMDA facility security rules for drug manufacturing sites elevate system specifications above commercial norms. The Osaka-Kobe corridor leads vein-pattern biometric standardization among financial institutions seeking liveness-detection advantages.
Chubu/Nagoya
Nagoya's automotive and industrial machinery sectors prioritize ruggedized credential systems for factory floor environments. JIS building automation interoperability standards shape product certification requirements for integrated access-HVAC deployments. The Aichi prefecture industrial belt concentrates retrofit demand from aging manufacturing campuses.
Kyushu/Fukuoka
Fukuoka's emerging smart city investments cluster access control within integrated building management platforms for new commercial construction. Regional government technology subsidies accelerate cloud migration among mid-sized enterprises. The Fukuoka metropolitan corridor represents the fastest-expanding deployment geography outside the dominant Tokyo-Osaka axis.
Hokkaido/Tohoku
Sapporo and Sendai smart infrastructure investments extend deployment opportunities into historically underpenetrated northern markets. Cold-climate durability requirements favor contactless biometric modalities over card readers vulnerable to temperature extremes. Regional integrators address technician scarcity through pre-configured, remote-managed system architectures.
Japan Access Control Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Japan's access control structure. NEC Corporation and Panasonic Corporation anchor the upper tier through captive biometric R&D and manufacturing scale advantages. ASSA ABLOY and Dormakaba Holding AG occupy the hardware-to-electronics integration specialist tier. Competitive moves concentrate on cloud-native platform development and strategic partnerships that reduce on-site configuration demands for shrinking installer pools.
Among Japan-based technology conglomerates, NEC Corporation and Panasonic Corporation exemplify the integrated-leader archetype through deep domestic R&D pipelines and government facility relationships. ASSA ABLOY represents the hardware-electronics convergence specialist tier competing on installation simplicity. These three companies anchor procurement specifications across METI-mandated critical infrastructure upgrades and commercial building automation projects.
| Leading Market Players |
|---|
| NEC Corporation |
| Panasonic Corporation |
| ASSA ABLOY |
| HID Global Corporation |
| Honeywell International Inc |
| Bosch Security System Inc |
| Thales Group |
| Axis Communications AB |
| Dormakaba Holding AG |
| Others |
Pricing and Supply Chain Analysis
Panasonic Corporation's captive manufacturing scale for MIFARE and FeliCa-compatible readers compresses unit economics for domestic integrators while elevating price floors for specialized biometric terminals. This concentration of domestic production capacity shapes procurement negotiations across commercial real estate portfolios and government facility deployments.
Pricing Analysis
Long-term service contracts dominate procurement structures as facility managers unbundle hardware from manufacturer-direct subscription models. Three-tier pricing structure across premium biometric, standard smart card, and economy credential systems reflects JIS certification tiers and after-sales bundling levels. Pricing pressure stems from cloud-native platform commoditization as remote diagnostics reduce technician dispatch premiums. Commercial real estate portfolios exhibit highest price sensitivity while defense-adjacent facilities absorb premium tiers for audit-grade logging capabilities.
Supply Chain Analysis
Taiwan and South Korea anchor semiconductor fabrication for specialized NFC and biometric sensor chips that feed Japanese reader assembly. Component sourcing draws from limited Asian foundry sources for liveness-detection optical modules and encrypted token processors. Single-source vulnerability concentrates procurement risk for vein-pattern recognition terminals. Distribution runs through building automation integrators and security system contractors concentrated in the Greater Tokyo Area.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's access control market sits at a platform-economics inflection as JIS interoperability standards reshape vendor ecosystems around unified building management platforms. Cloud-native identity architectures are displacing hardware-centric business models.
For Market Incumbents: Compound biometric R&D pipelines into government facility relationships before NEC Corporation consolidates METI-mandated critical infrastructure deployments. Deepen backward integration into finger-vein sensor production to defend margins against commoditizing smart card readers. Channel control through pre-certified JIS product portfolios addresses installer scarcity. For New Entrants and Emerging Players: Differentiate on mobile credential convergence for hospitality and retail verticals where smartphone-based access eliminates physical card logistics. Target Sapporo and Sendai smart city investments as underpenetrated deployment geographies outside Tokyo-Osaka dominance. Partner with regional system integrators lacking cloud platform capabilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native platform specialists with recurring revenue models over hardware-dependent incumbents. Acquisition targets with JIS certification pipelines and government facility relationships offer longest viability through regulatory compulsion. Watch METI cybersecurity guideline enforcement velocity as inflection indicator for biometric procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Subscription models reduce IT maintenance burdens for shrinking installer pools across commercial portfolios. |
| JIS Interoperability Certification | Pre-certified products accelerate project eligibility for building automation integration in Tokyo construction. |
| Vein-Pattern Biometric R&D | Liveness-detection capabilities meet METI multi-factor mandates for financial and government facilities. |
| Regional Smart City Partnership | Fukuoka infrastructure investments extend deployment opportunities beyond dominant metropolitan corridors. |
| Mobile Credential Development | Smartphone-based access eliminates front-desk distribution costs in high-turnover hospitality operations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with security system integrators, building facility managers, government procurement officers, and biometric R&D directors. Secondary validation drew from METI regulatory filings, JIS standards documentation, PMDA facility security guidelines, and commercial construction permit databases. Bottom-up deployment estimates triangulated against top-down market sizing across technology and application segments.
Across the analysis window, projections modeled technology substitution rates, cloud migration timelines, and regulatory compliance deadlines. Segmentation dimensions spanned biometric modality, deployment architecture, facility type, and metropolitan corridor. CAGRs derived from technology penetration curves and replacement cycle analysis. Forecast inputs incorporated semiconductor supply constraints and cybersecurity technician labor pool trajectories.
Material uncertainties — semiconductor supply disruptions, regulatory enforcement delays, data sovereignty policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions about JIS standard adoption velocity and cloud platform security certification timelines. Recalibration cycles align with material shifts in METI cybersecurity guideline revisions and smart city infrastructure investment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Italy Access Control Market
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
Global Smart Lock Market
Access Control Systems
Germany Access Control Market
Access Control Systems
Europe Airport Passenger Screening Systems Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
Physical Access Control Market
Access Control Systems
Industrial Barrier Systems Market
Access Control Systems
Pre-Departure Clearance System Market
Access Control Systems
Europe Access Control Software Market
Access Control Systems
Smart Locker Locks Market
Access Control Systems
US Access Control Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
Automated Smart Locker System Market
Access Control Systems
Smart Door Lock Market