
 Global Kitchen Woks Market | 2026-2036
Global Kitchen Woks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Kitchen Woks Market Outlook
China's Guangdong province is reconfiguring global wok supply chains through concentrated carbon steel forging capacity and integrated coating facilities. Supor leverages vertical integration across raw material sourcing and domestic retail channels to sustain cost leadership. Meyer Corporation anchors North American demand through specialty retail partnerships and cast iron foundry operations. Lodge Manufacturing Company dominates heirloom-grade cast iron wok segments with seasoned surface technology and made-in-USA positioning.
A kitchen wok is a concave cooking vessel, typically 10 to 16 inches in diameter, engineered from carbon steel, cast iron, stainless steel, or coated aluminum to achieve high-heat thermal conductivity and rapid ingredient movement. The 14-inch carbon steel configuration leads commercial restaurant adoption due to heat responsiveness and maneuverability over gas burners. Cast iron woks occupy the premium household tier where thermal retention and seasoning durability command price premiums. Non-stick coated variants compete in entry-level online retail channels where convenience outweighs longevity considerations.
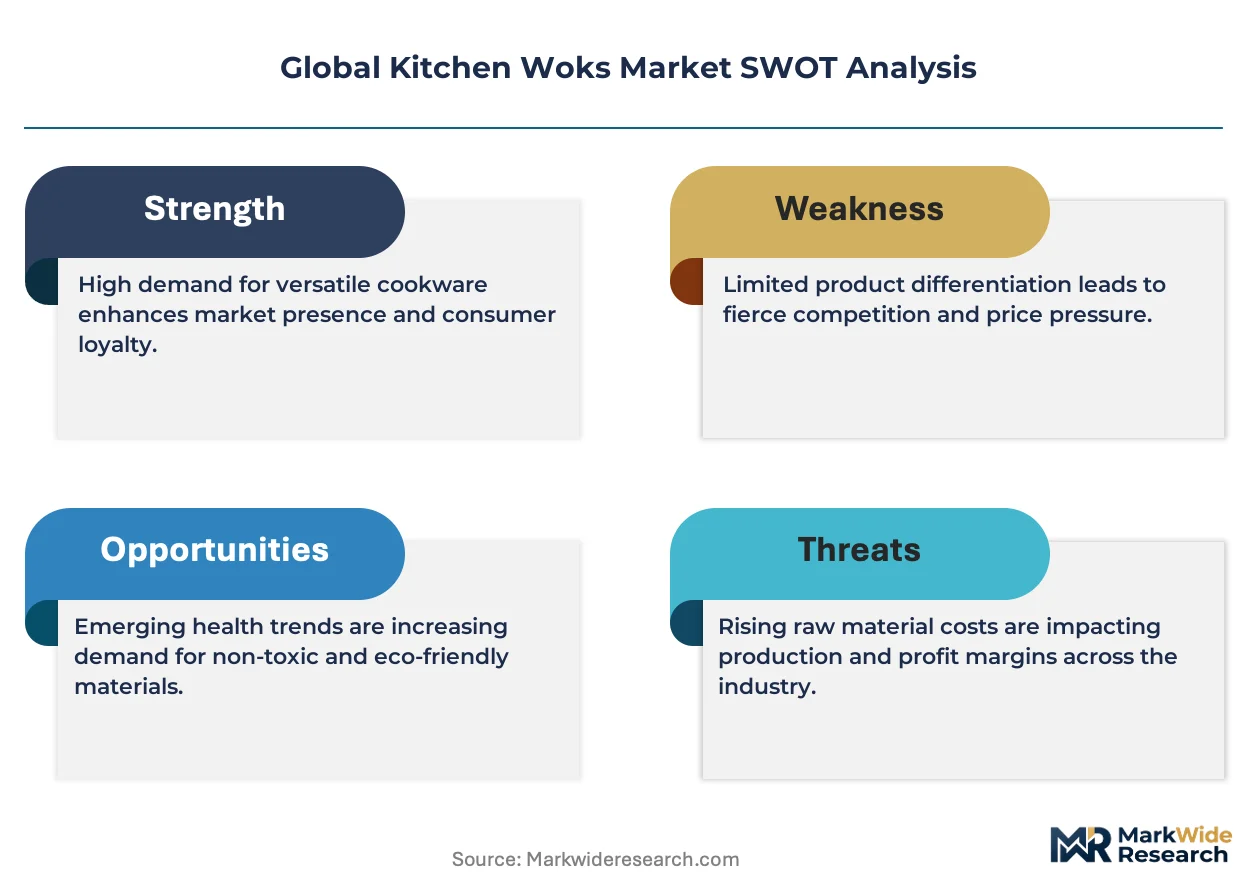
China's SAMR enforces GB food-contact material standards that restrict perfluorinated compound migration in non-stick coatings, directly shaping import eligibility for coated wok imports. The US FDA maintains indirect food additive regulations under 21 CFR that govern polymer and resin coatings on metal cookware, while California's Proposition 65 labeling requirements create compliance thresholds for heavy metal content in cast iron products. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions as coating chemistry transitions accelerate.
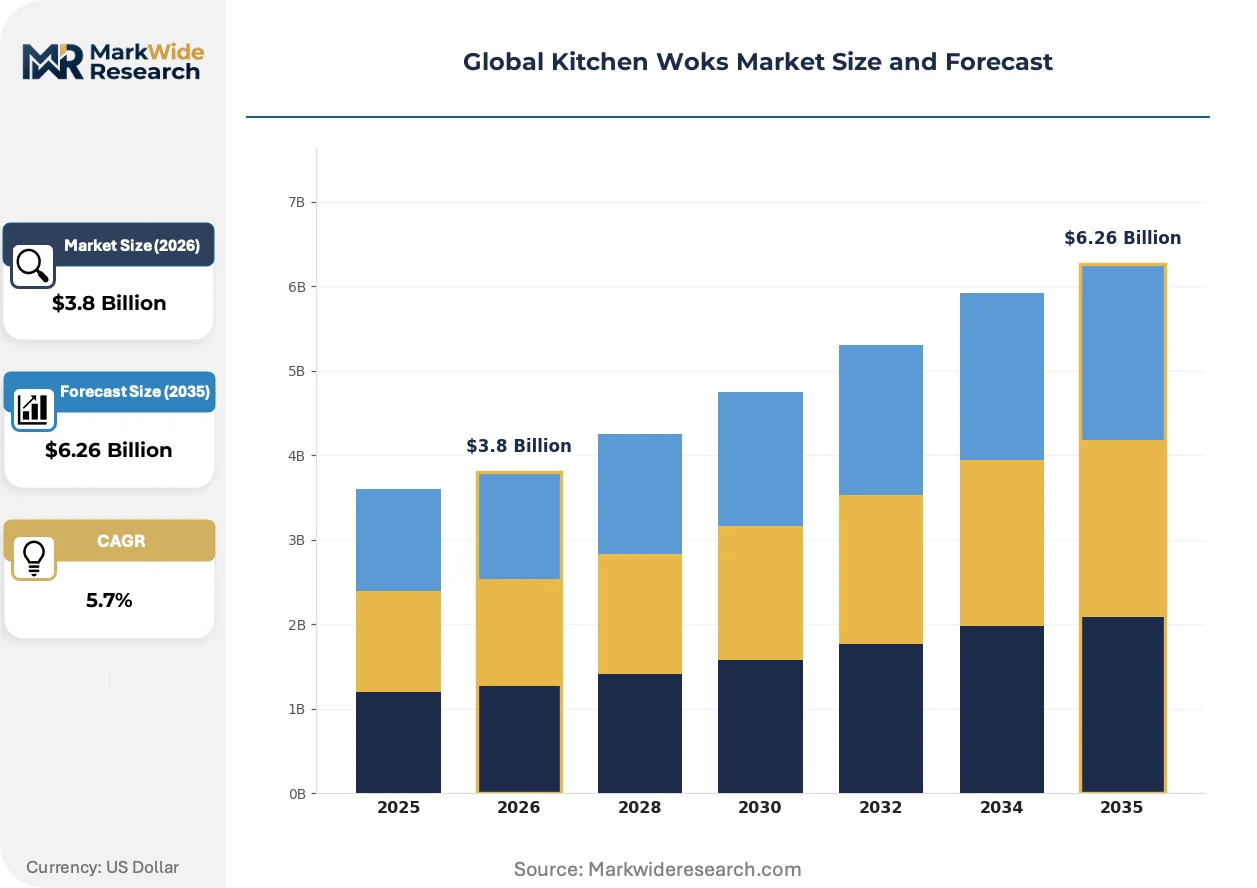
Market Dynamics
Carbon steel forging clusters in China's Guangdong province are consolidating global wok supply chains through integrated coating facilities and captive raw material sourcing, compressing lead times for export markets while tightening compliance scrutiny on food-contact surface chemistry.
Growth Catalysts
- Commercial Kitchen Expansion:Asia-Pacific restaurant infrastructure investment is accelerating wok station deployment in high-volume cooking environments. Gas burner compatibility drives specification standards across foodservice procurement.
- GB Standard Harmonization:China's SAMR enforcement of food-contact material protocols is elevating coating safety benchmarks, filtering import eligibility and rewarding compliant domestic manufacturers.
- Carbon Steel Thermal Performance:Heat responsiveness over open flame configurations sustains professional chef preference, anchoring replacement cycles in commercial end-uses.
Market Restraints
- Input Cost Volatility:Scrap steel and ferroalloy price swings compress margin predictability for carbon steel forging operations.
- Coating Chemistry Transition:Perfluorinated compound restrictions under REACH and FDA 21 CFR are forcing reformulation timelines and certification delays.
- Substitution Pressure:Multi-clad stainless cookware is displacing entry-level wok purchases in Western household segments.
Strategic Opportunities
- Underpenetrated Southeast Asia:Vietnam and Indonesia foodservice modernization is creating first-mover positioning for forged carbon steel supply contracts.
- Seasoning-as-Service:Pre-seasoned cast iron offerings are capturing premium household tiers seeking convenience without coating dependency.
- EU Green Deal Alignment:Ecodesign criteria for durable cookware are rewarding extended-lifecycle product positioning in European distribution.
Industry Challenges
- Skilled Forging Labor Scarcity:Hand-hammered carbon steel production requires experienced metalworkers, constraining capacity expansion in traditional manufacturing clusters.
- Cross-Jurisdiction Compliance Burden:Simultaneous FDA, REACH, and GB standard adherence is fragmenting product variants and complicating inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Kitchen Woks Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Cast Iron, Non-Stick, Carbon Steel Size: 10 Inch, 12 Inch, 14 Inch, 16 Inch End User: Households, Restaurants, Hotels, Catering Services Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Others |
| Companies Covered | The Wok Shop, Joyce Chen, Ecxel Steel, T-fal, Lodge Manufacturing Company, Groupe SEB, Meyer Corporation, Supor, TTK Prestige, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Kitchen Woks Market Strategic Shifts
Surface engineering and thermal management technologies are converging to redefine wok performance benchmarks, while regulatory chemistry restrictions and procurement centralization are reshaping competitive positioning across manufacturing and distribution layers.
Multi-layer composite construction is hybridizing traditional carbon steel responsiveness with stainless steel corrosion resistance. Commercial foodservice operators in South Korea and Japan are specifying these hybrids for high-acid ingredient compatibility. The technology is hybridizing material selection criteria, compressing the historical trade-off between thermal performance and maintenance durability.
REACH restrictions on per- and polyfluoroalkyl substances are accelerating coating chemistry transitions across European import channels. Industrial consequence includes forced supplier requalification and accelerated R&D allocation to ceramic and silicone-based alternatives. Cast iron and bare carbon steel categories are capturing displaced demand as buyers preempt regulatory uncertainty.
Centralized procurement through foodservice distribution cooperatives is consolidating specification authority away from individual restaurant operators. Broadline distributors in North America are private-labeling wok SKUs, compressing manufacturer brand equity and shifting margin capture downstream. This pattern is most visible in US multi-unit chain accounts where standardization overrides chef-level equipment preference.
Global Kitchen Woks Market Segmentation
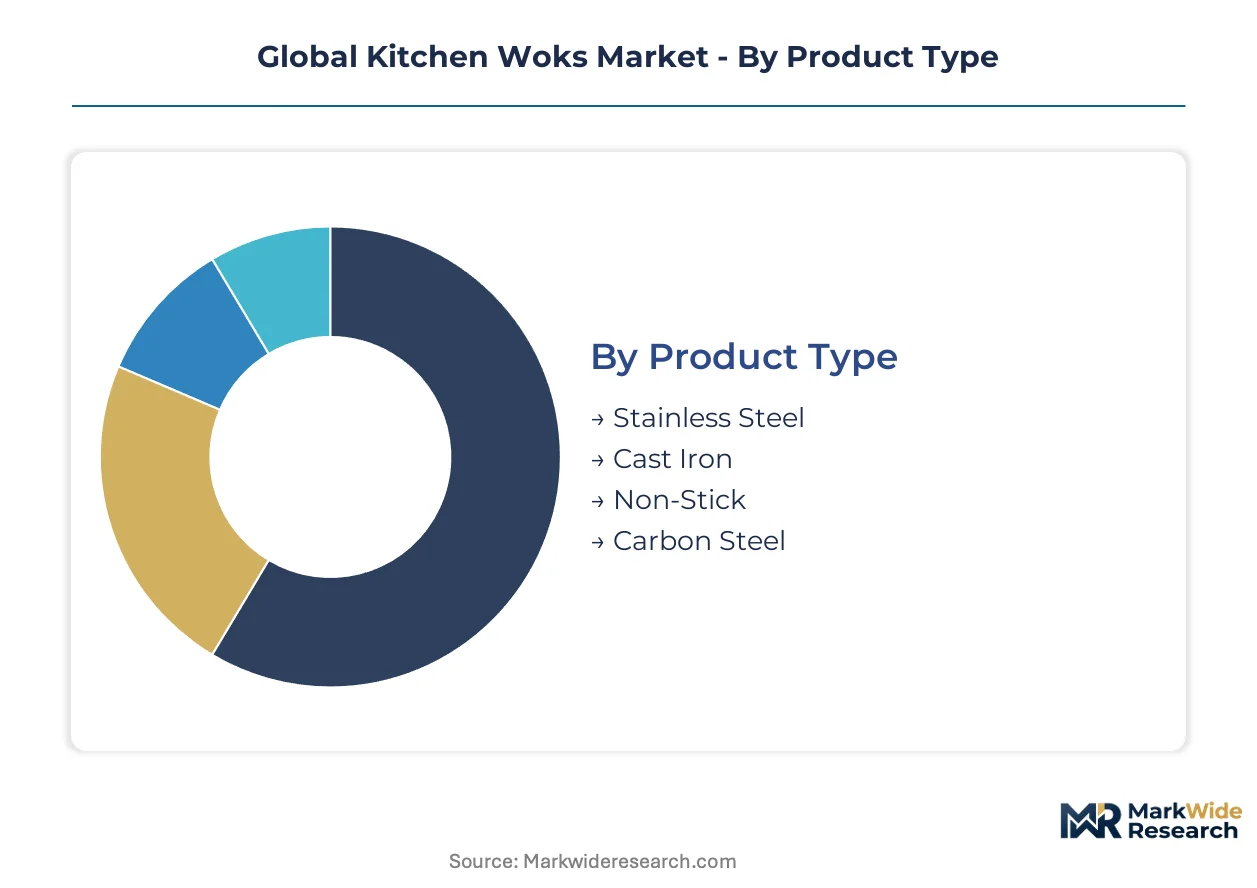
Wok market segmentation reveals divergent performance requirements across cooking environments. Material selection and diameter specifications directly determine thermal behavior, maintenance protocols, and replacement cycles in professional versus residential settings.
Product Type:
Mature forging techniques anchor carbon steel and cast iron categories, while coating chemistry transitions are accelerating non-stick and stainless steel development timelines.
- Carbon Steel:Hand-forged or stamped construction delivers rapid heat responsiveness over gas flame configurations. Guangdong forging clusters supply commercial kitchens across Vietnam and Thailand where wok hei flavor development drives procurement specifications.
- Cast Iron:Molten iron pouring into sand molds creates dense thermal mass retaining heat across ingredient batches. Pre-seasoned surface treatments from Lodge Manufacturing and Meyer Corporation capture North American household segments seeking heirloom durability without active maintenance.
- Stainless Steel:Chromium-nickel alloys resist corrosion from acidic ingredients in hybrid Asian-Western cooking. South Korean and Japanese foodservice operators specify multi-ply variants for compatibility with induction and electric heat sources.
- Non-Stick:Polymer or ceramic coatings reduce oil requirements for entry-level home cooks. China's SAMR GB standard enforcement and REACH perfluorinated compound restrictions are compressing coating chemistry options and extending supplier requalification timelines.
Carbon steel retains volume leadership in commercial channels; non-stick formulations face the steepest regulatory headwinds despite household convenience appeal.
Size:
Commercial kitchen infrastructure and residential burner dimensions dictate diameter adoption patterns across end-use segments.
- 14 Inch:The standard commercial specification balances ingredient volume with maneuverability over high-BTU gas burners. Restaurant chains in Malaysia and Singapore standardize this diameter across wok station installations.
- 12 Inch:Compact residential formats suit apartment-scale gas and induction cooktops. Japanese and South Korean manufacturers dominate export supply for this segment through precision spinning and automated surface finishing.
- 10 Inch:Single-portion cooking for one to two diners. Online retail channels in Germany and France stock this diameter for European household penetration where wok cooking remains technique-driven rather than cultural default.
- 16 Inch:High-volume catering and banquet preparation requiring two-hand operation. Limited production concentrates in Guangdong manual forging shops where skilled labor scarcity constrains capacity expansion.
Fourteen-inch configurations dominate foodservice procurement volumes; twelve-inch formats are climbing fastest in e-commerce residential channels.
End User:
Operational intensity and equipment turnover rates create distinct specification and sourcing behaviors across customer categories.
- Restaurants:High-heat cycling demands carbon steel durability with quarterly replacement schedules in high-volume Chinese and Southeast Asian kitchens. Centralized procurement through broadline distributors is compressing manufacturer brand visibility.
- Households:Convenience prioritization drives non-stick and pre-seasoned cast iron adoption. Amazon and direct-to-consumer channels capture margin through subscription seasoning products and replacement lid attachments.
- Hotels:Buffet display and room service applications favor polished stainless steel aesthetics over thermal performance. Dubai and Riyadh hospitality construction pipelines are specifying induction-compatible multi-ply construction.
- Catering Services:Mobile cooking infrastructure requires lightweight spun steel or aluminum-core hybrids. Indonesian and Vietnamese event catering growth is stimulating regional manufacturing investment.
Restaurant channels absorb the highest unit volumes; hotel specifications are gaining share fastest in Middle East hospitality development corridors.
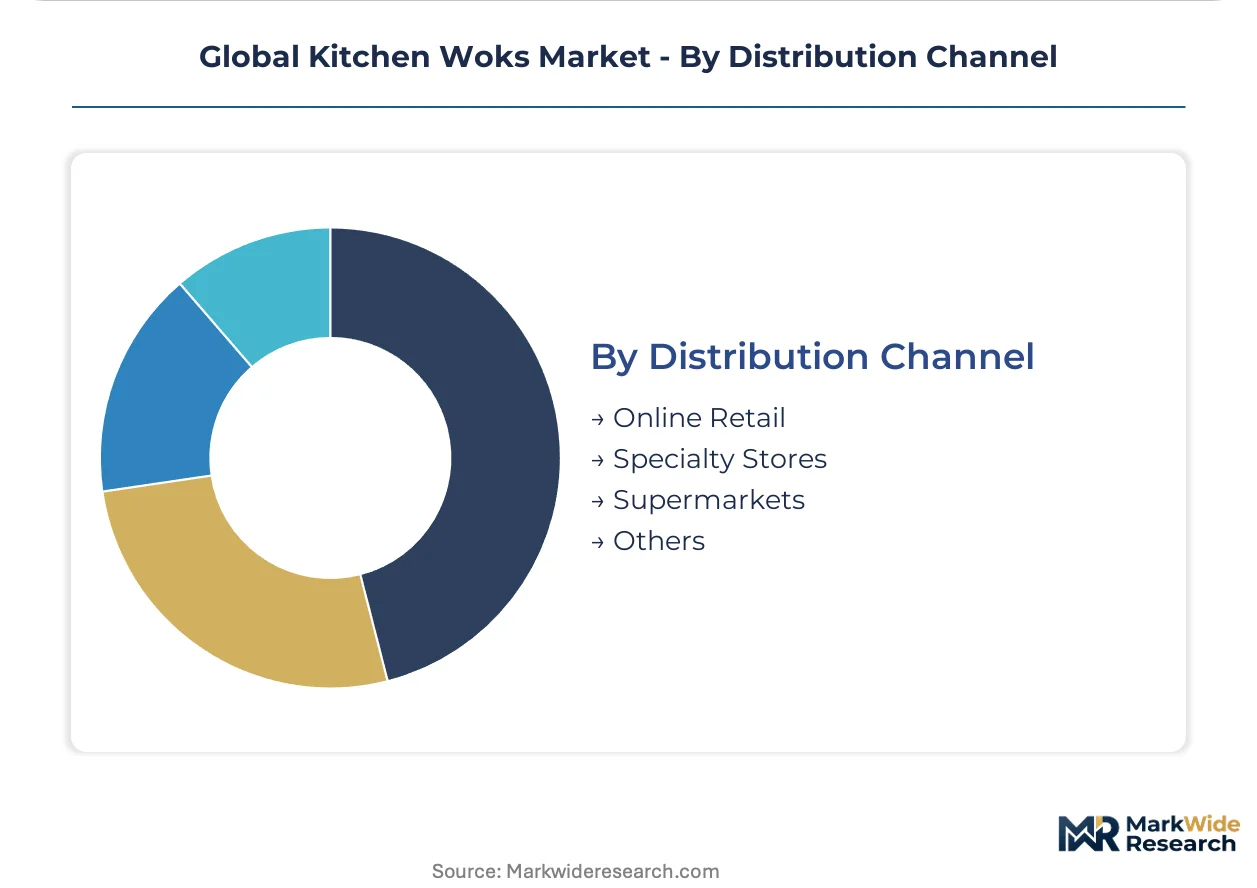
Distribution Channel:
Channel selection determines margin capture allocation and brand equity retention across manufacturer and intermediary layers.
- Online Retail:Amazon, Tmall, and Rakuten platforms enable direct manufacturer-consumer relationships. Review-driven discovery favors visual differentiation through packaging design and seasoning tutorial content.
- Specialty Stores:Williams Sonoma and Sur La Table curate premium cast iron and carbon steel assortments with in-person seasoning demonstrations. Staff expertise justifies price premiums over mass-market alternatives.
- Supermarkets:Walmart and Carrefour hypermarket placements reach convenience-oriented non-stick buyers. Private-label sourcing from Guangdong OEMs compresses branded manufacturer shelf space.
- Others:Restaurant supply cooperatives and direct foodservice contracts bypass retail markup. Sysco and US Foods private-label programs specify custom handle geometries and thickness profiles.
Specialty stores maintain premium positioning; online retail is expanding most quickly through platform algorithm optimization and video content integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB food-contact material standards anchor China's dominant manufacturing position, with regulatory harmonization across multiple jurisdictions shaping import eligibility and production compliance costs worldwide.
China
Guangdong province's carbon steel forging clusters supply commercial kitchens across Southeast Asia with 14-inch hand-hammered configurations. SAMR enforces GB standards restricting perfluorinated compound migration in non-stick coatings, filtering export eligibility for coated products. Shenzhen and Foshan manufacturing hubs integrate captive raw material sourcing with automated surface finishing lines.
United States
Specialty retail channels and broadline foodservice distributors drive specification standards for cast iron and carbon steel categories. FDA maintains 21 CFR indirect food additive regulations governing polymer coatings on metal cookware, while California's Proposition 65 mandates heavy metal content labeling. Lodge Manufacturing's Tennessee foundry operations anchor heirloom-grade production with seasoned surface technology.
Germany
EU Green Deal ecodesign criteria reward extended-lifecycle cookware positioning in European distribution channels. ECHA REACH restrictions on per- and polyfluoroalkyl substances accelerate coating chemistry transitions and supplier requalification timelines. Solingen's metalworking heritage supports precision stainless steel fabrication for induction-compatible multi-ply construction.
Japan
Commercial foodservice operators specify hybrid carbon steel-stainless steel constructions for high-acid ingredient compatibility. METI oversees industrial standards coordination while JIS specifications govern material grades for food-contact applications. Osaka and Nagoya manufacturing bases supply precision-spun 12-inch formats for residential induction cooktop adoption.
India
TTK Prestige and domestic competitors expand forged aluminum and hard-anodized offerings through modern trade and e-commerce channels. BIS certification requirements for food-contact metals elevate import barriers for uncoated Chinese carbon steel. Mumbai and Bangalore urban households drive demand for compact 10-inch formats suited to apartment-scale gas burner configurations.
Global Kitchen Woks Market Competitive Environment
Vertically integrated manufacturers and brand-centric distributors split the market between cost-engineered supply and premium positioning. The vendor base concentrates around three strategic archetypes: captive-forging Asian producers controlling upstream metal supply, heritage-brand Western foundries commanding retail price premiums, and broadline-sourced private-label programs capturing foodservice volume. Competitive maneuvering centers on coating chemistry certification acceleration and Southeast Asian distribution partnership formation.
Among heritage-brand Western foundries, Lodge Manufacturing Company exemplifies made-in-USA positioning with seasoned cast iron technology. Supor represents the vertically integrated Chinese archetype through Guangdong-based forging capacity and domestic retail channel control. Meyer Corporation occupies the multinational brand-aggregator position, bridging Asian manufacturing origins with North American specialty retail partnerships. These three anchors illustrate divergent pathways to margin capture across material-grade and channel-strategy combinations.
| Leading Market Players |
|---|
| The Wok Shop |
| Joyce Chen |
| Ecxel Steel |
| T-fal |
| Lodge Manufacturing Company |
| Groupe SEB |
| Meyer Corporation |
| Supor |
| TTK Prestige |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Guangdong's hand-forged carbon steel segment is tightening supplier leverage and compressing negotiation windows for North American distributors seeking 14-inch commercial specifications. This utilization squeeze feeds directly into pricing posture, as captive raw material sourcing and integrated coating facilities reward vertically integrated Chinese manufacturers with margin buffers unavailable to import-dependent competitors.
Pricing Analysis
Price spreads between Guangdong-origin carbon steel and Tennessee-made cast iron woks now exceed three-to-one at wholesale, reflecting divergent labor intensities and tariff exposure. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification tier and volume commitment, with FDA-compliant coated variants commanding premiums over bare carbon steel. Pricing pressure stems from REACH-driven coating reformulation costs that suppliers struggle to pass through to price-sensitive foodservice distributors. Restaurant supply cooperatives exhibit highest price sensitivity, while specialty retail channels absorb premiums for heirloom-grade positioning.
Supply Chain Analysis
Scrap steel and ferroalloy feedstock sourcing draws from China's domestic metallurgical complex, with secondary dependence on Australian iron ore and Indonesian nickel for stainless steel variants. Manufacturing concentrates in Guangdong forging clusters, Japanese precision-metalworking bases, and Tennessee foundry operations. Single-source vulnerability runs through Guangdong's hand-hammered capacity where skilled labor scarcity constrains expansion. Distribution runs through broadline foodservice cooperatives in North America, platform e-commerce in Asia-Pacific, and specialty kitchen retailers in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward centralized foodservice procurement cooperatives, fragmenting manufacturer brand equity as broadline distributors consolidate specification authority across multi-unit restaurant accounts.
For Market Incumbents: Insulate margin position by accelerating backward integration into captive scrap steel sourcing and pre-seasoned surface treatment facilities. Lodge Manufacturing's Tennessee foundry model demonstrates how made-in-USA positioning defends against Guangdong cost competition. Invest in SAMR GB standard pre-certification to filter import eligibility before competitors complete reformulation timelines. Channel control through exclusive specialty retail partnerships preserves price integrity against private-label compression. For New Entrants and Emerging Players: Vietnamese and Indonesian foodservice modernization offers white-space positioning for forged carbon steel supply contracts unclaimed by Guangdong incumbents. Target catering services in Southeast Asia's event infrastructure growth corridor, where lightweight spun steel demand outpaces local manufacturing capacity. Pursue direct-to-chef digital distribution with video-based seasoning tutorials to bypass entrenched broadline distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across coating chemistry transition segments as ceramic and silicone-based R&D yields scalable alternatives to perfluorinated compounds. Long-term viability favors manufacturers with dual carbon steel and cast iron production flexibility across the analysis window. Acquisition targets should display integrated forging capacity with SAMR compliance documentation. Monitor ECHA REACH restriction expansion timelines as inflection signals for coating chemistry displacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Certification Acceleration | REACH and GB standard pre-compliance secures European and Chinese import eligibility before reformulation deadlines. |
| Southeast Asian Distribution Partnership Formation | Vietnamese and Indonesian foodservice cooperatives seek forged carbon steel suppliers outside Guangdong pricing structures. |
| Pre-Seasoned Cast Iron Capacity Expansion | Lodge Manufacturing's Tennessee model demonstrates premium capture in household segments seeking coating-free convenience. |
| Hybrid Material R&D Investment | Carbon steel-stainless steel multi-ply construction addresses South Korean and Japanese high-acid ingredient compatibility requirements. |
| Direct-to-Consumer Platform Optimization | Amazon and Tmall algorithm integration enables margin retention bypassing broadline distributor private-label compression. |
Study Parameters
The analysis maps carbon steel forging, cast iron foundry, stainless steel fabrication, and non-stick coating sub-sectors, each validated through primary interviews with restaurant procurement directors, specialty retail category buyers, Guangdong manufacturing plant managers, and foodservice distribution executives. Secondary validation draws from SAMR GB standard filings, FDA 21 CFR indirect food additive regulations, ECHA REACH restriction updates, and customs trade data. Bottom-up unit economics triangulate against top-down market sizing across material-grade and end-use dimensions.
Forecast assumptions held regulatory transition timelines and scrap steel price volatility as fixed boundary conditions while varying commercial kitchen expansion rates and coating chemistry adoption curves across the projection horizon. Segmentation modeling incorporates material type, diameter specification, end-user category, and distribution channel dimensions. CAGRs derive from replacement cycle analysis in restaurant channels and household penetration rate trajectories in e-commerce segments, with cross-reference to foodservice infrastructure investment pipelines and hospitality construction databases.
Practitioners should monitor ECHA REACH perfluorinated compound restriction expansion and SAMR enforcement intensity for early signals requiring forecast revision. Cross-checking against broadline distributor inventory build patterns and Guangdong export customs data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Banquet Carts and Heated Cabinets Market
Kitchen and Dining
Latin America Kitchen Furniture Market
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
US Tableware Market
Kitchen and Dining
Dining Table Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Europe Kitchen Hobs Market
Kitchen and Dining
Brightwood Tray Market
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
GCC Modular Kitchen Market
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
Popover Pan Market
Kitchen and Dining
Skillets and Frying Pans Market
Kitchen and Dining
Restaurant Chairs Market
Kitchen and Dining
Egypt Kitchen Hood Market