
 United States Home Decor Market | 2026-2036
United States Home Decor Market Size, Share, and Industry Trends Forecast 2026-2036
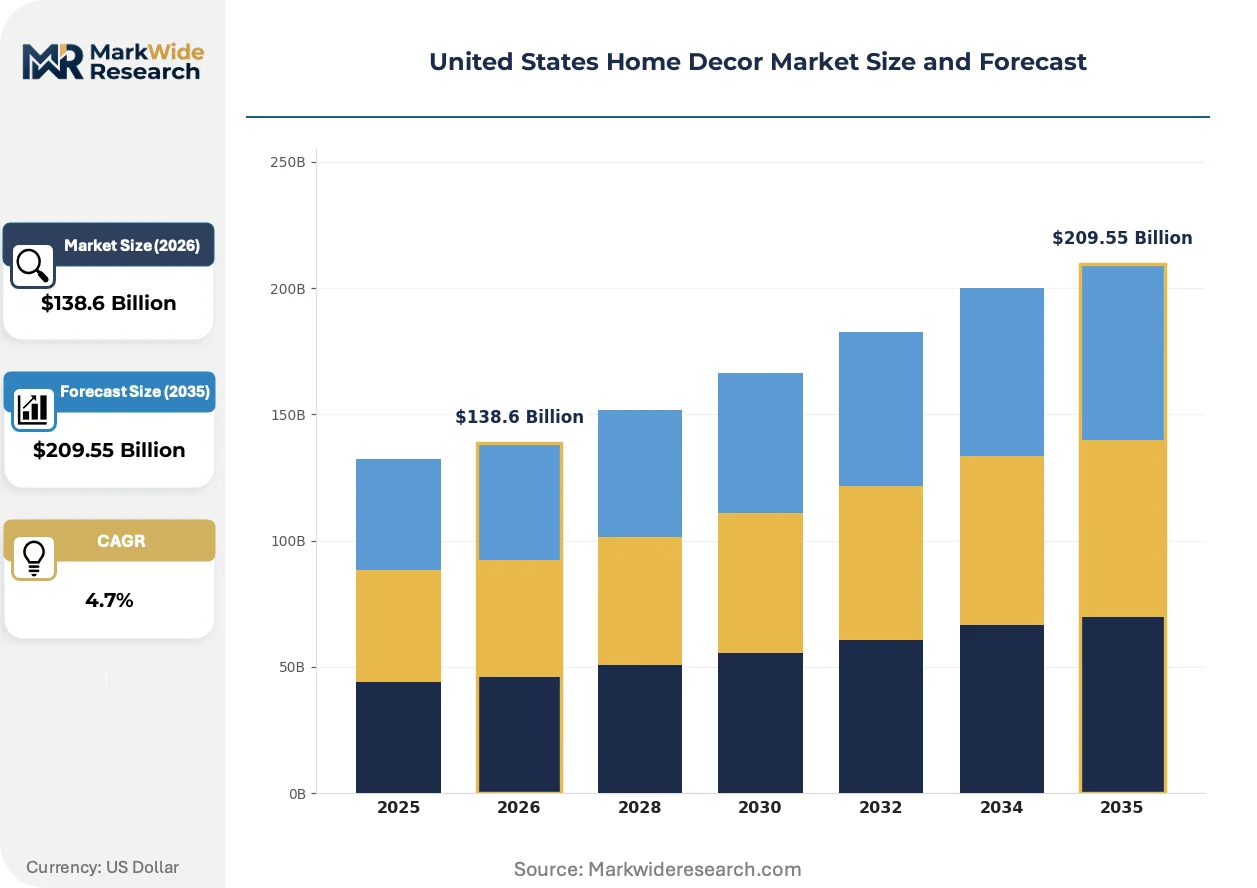
United States Home Decor Market Outlook
Direct-to-consumer digital channels are reshaping how Americans discover and purchase home decor. Wayfair leverages proprietary logistics networks to sustain next-day delivery promises in dense coastal corridors. The Home Depot anchors professional contractor demand through dedicated pro desks and bulk pricing tiers. Williams-Sonoma differentiates via in-house design studios that control aesthetic direction across multiple lifestyle brands.
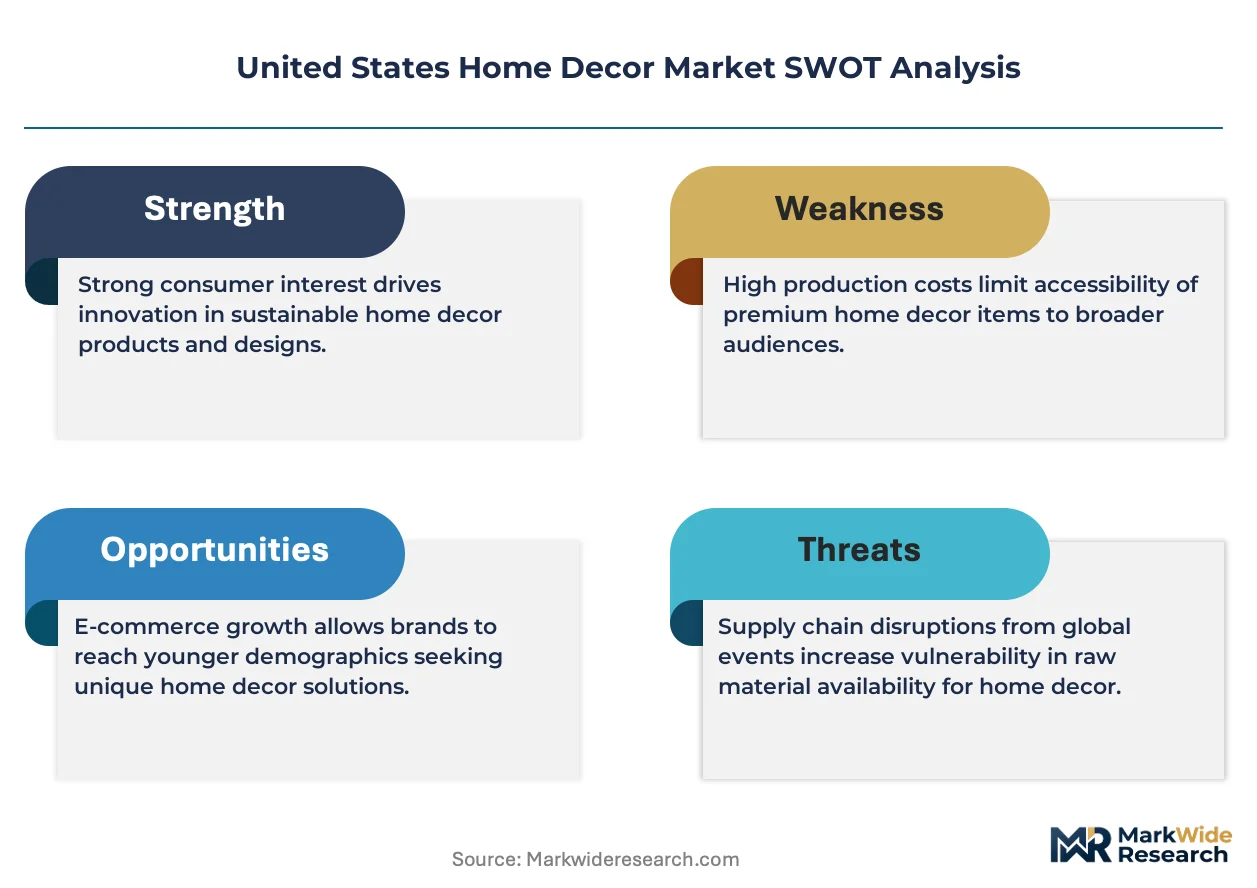
United States home decor encompasses movable ornamental and functional objects—including furniture, lighting fixtures, textiles, and wall-mounted elements—crafted from wood, metal, fabric, or glass and finished to specified dimensional tolerances for residential interior environments. These products serve both utilitarian purposes and identity-expression functions within domestic spaces. Furniture commands the largest revenue pool among product types, though lighting is gaining share as LED retrofits and smart-home integration expand. Wood dominates material consumption by volume, yet metal and glass are capturing margin in modern and minimalist style segments where fabrication precision justifies premium positioning.
The Consumer Product Safety Commission enforces flammability standards for upholstered furniture, while California's Bureau of Household Goods and Services maintains stricter labeling requirements that de facto shape national inventory decisions. EPA guidelines on formaldehyde emissions from composite wood products further constrain substrate sourcing for manufacturers serving mass-market retailers. Stakeholders must monitor evolving state-level chemical disclosure mandates that could fragment compliance costs across multi-channel supply chains.
Market Dynamics
Millennial first-time homebuyers are compressing refresh cycles across furnishings and accents, while California's Title 24 energy efficiency standards are forcing LED lighting adoption and reshaping product assortments nationwide. These dual pressures are restructuring manufacturer priorities and retail inventory decisions.
Growth Catalysts
- Title 24 Energy Standards:California's building code mandates are accelerating LED fixture penetration and creating pull-through demand for complementary smart-home controls across residential new construction.
- Texas Metropolitan Housing Starts:Dallas-Fort Worth and Houston metro areas are outpacing national averages for population inflows and residential permits, concentrating demand for furniture and lighting.
- Composite Wood Product Regulations:EPA formaldehyde emission standards are driving substrate substitution toward certified low-emission engineered woods and solid alternatives.
Market Restraints
- Lumber Input Volatility:Softwood lumber prices fluctuate with North American mill capacity and tariff exposure, compressing margin predictability for wood-dominant furniture lines.
- Asia-Pacific Supply Concentration:Upholstery fabric and metal component sourcing clusters in Vietnam and Indonesia create vulnerability to shipping rate spikes and port congestion.
- Upholstered Furniture Flammability Standards:CPSC flammability testing requirements add certification lag and reformulation costs for foam and fabric suppliers serving mass-market retailers.
Strategic Opportunities
- Professional Contractor Channel:Home improvement retailers with dedicated pro desks and bulk pricing tiers are capturing renovation-driven volume from investor-owned rental properties.
- Direct-to-Consumer Logistics:Proprietary last-mile networks enabling next-day delivery promises in dense coastal corridors are opening secondary market penetration without wholesale intermediaries.
- In-House Design Studio Control:Captive aesthetic direction across multiple lifestyle brands allows coordinated collection launches and margin capture from trend velocity.
Industry Challenges
- Multi-State Chemical Disclosure Fragmentation:Evolving state-level labeling mandates beyond California's BHGS requirements are multiplying compliance documentation burdens for national inventory planning.
- Legacy ERP Integration:Wholesale-to-digital channel pivots require reconfiguration of order management and inventory allocation systems built for seasonal furniture market cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Home Decor Market |
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $209.55 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furniture, Lighting, Rugs, Wall Art Material: Wood, Metal, Fabric, Glass Style: Modern, Rustic, Minimalist, Bohemian End User: Homeowners, Renters, Interior Designers, Contractors |
| Companies Covered | The TJX Companies Inc., IKEA USA, The Home Depot Inc., Floor & Decor Holdings Inc., Ashley Furniture Industries, Lowe's Companies Inc., Williams-Sonoma Inc., Target Corporation, Wayfair Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Home Decor Market Strategic Shifts
Smart-home integration is hybridizing with traditional fixture categories, while regulatory pressure on material safety and energy performance is accelerating product redesign cycles. These forces are compressing development timelines and reshaping competitive differentiation.
Smart lighting technology is hybridizing with architectural fixture design, embedding sensors and connectivity into ceiling mounts and portable lamps. High-income suburban homeowners are adopting these systems fastest, with whole-home installations replacing piecemeal bulb upgrades. This convergence is compressing the traditional separation between electrical contractors and interior designers, forcing new coordination protocols.
EPA formaldehyde emission standards for composite wood products are tightening substrate sourcing requirements for case goods and shelving manufacturers. Mills serving mass-market retailers must certify particleboard and MDF to CARB Phase II or TSCA Title VI levels, adding testing overhead. California's Bureau of Household Goods and Services labeling requirements have de facto become the national standard, with retailers refusing non-compliant inventory.
Refresh-cycle compression among millennial first-time buyers is shortening furniture replacement timelines from decade-long investments to 3-5 year rotations. This pattern favors fast-fashion retail models and rental-to-own platforms over heirloom-positioned traditional dealers. Texas and Florida metro markets exhibit this behavior most visibly, where younger household formation rates exceed national benchmarks.
United States Home Decor Market Segmentation
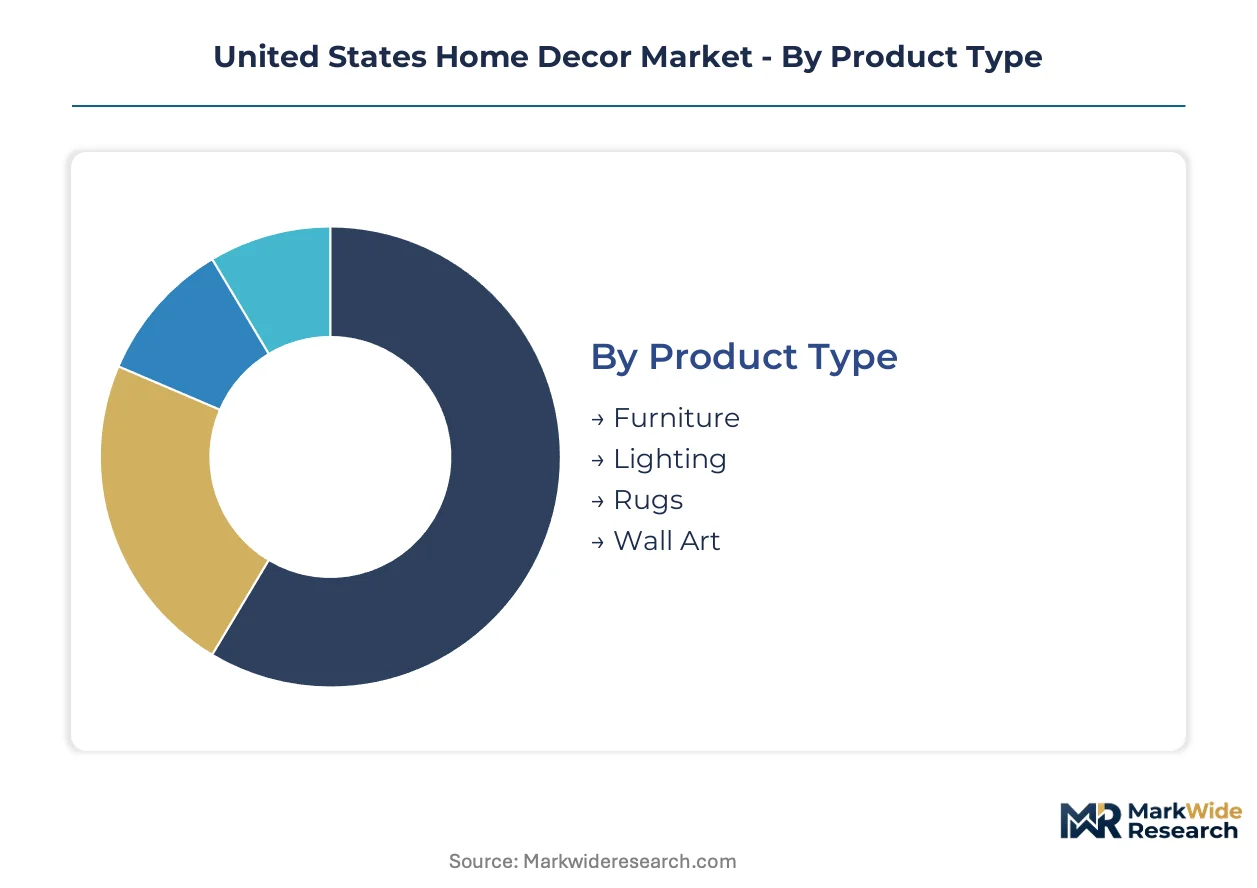
Segmentation in United States home decor reveals divergent replacement rhythms and margin profiles across product categories. Understanding these velocity differences allows manufacturers to align inventory turns with channel-specific demand patterns and regulatory exposure.
Product Type:
Furniture cycles span years while lighting refreshes accelerate under energy mandates, creating distinct production planning horizons across the four product categories.
- Furniture:Sofas, tables, and storage units constructed from composite wood, solid timber, or metal frames dominate revenue pools. Case goods face EPA formaldehyde certification requirements that extend procurement timelines for mass-market retailers serving Texas and California metro areas.
- Lighting:Ceiling mounts, portable lamps, and architectural fixtures embed LED modules and smart-home connectivity. California Title 24 mandates are compressing refresh cycles to 3-5 years as homeowners retrofit for compliance and automation integration.
- Rugs:Woven and tufted floor coverings in natural and synthetic fibers serve acoustic and zoning functions. Millennial first-time buyers in Dallas-Fort Worth and Houston drive faster turnover through rental-to-own platforms.
- Wall Art:Framed prints, canvas works, and sculptural installations complete interior schemes. Digital printing and dropship fulfillment enable rapid trend response without inventory carrying costs.
Furniture anchors the volume base while lighting gains share at the steepest rate.
Material:
Raw material selection determines regulatory compliance burden and fabrication precision, with emissions standards and tariff exposure reshaping sourcing priorities.
- Wood:Solid hardwoods and engineered substrates supply case goods and shelving. CARB Phase II and TSCA Title VI certification requirements constrain particleboard and MDF sourcing for manufacturers serving national retail chains.
- Metal:Steel, aluminum, and brass enable precision fabrication for modern and minimalist furniture frames. Component sourcing clusters in Vietnam create vulnerability to shipping rate volatility and port congestion.
- Fabric:Upholstery textiles and window treatments face CPSC flammability testing requirements that add certification lag for foam and fabric suppliers. Natural fiber blends command premium positioning in bohemian and rustic style segments.
- Glass:Tempered and decorative glass elements serve lighting diffusers and accent tables. Fabrication precision justifies premium positioning in contemporary fixture design where dimensional tolerances are tightest.
Wood commands the largest procurement volume while metal captures margin in precision-dependent segments.
Style:
Aesthetic positioning determines distribution channel access and price realization, with design studios controlling coordinated collection launches across lifestyle tiers.
- Modern:Clean lines, neutral palettes, and mixed material construction characterize this segment. High-income suburban homeowners in coastal corridors adopt smart-integrated modern fixtures fastest, compressing the traditional separation between electrical contractors and interior designers.
- Rustic:Reclaimed wood, distressed finishes, and farmhouse influences dominate this category. Texas metropolitan markets exhibit strongest demand where younger household formation rates exceed national benchmarks.
- Minimalist:Reduced ornamentation and functional purity drive specification of metal and glass components. Fabrication precision requirements favor vertically integrated manufacturers with captive machining capabilities.
- Bohemian:Layered textiles, global patterns, and eclectic mixing define this aesthetic. Fast-fashion retail models and rental platforms favor this segment's shorter replacement timelines.
Modern style leads professional channel specification while rustic dominates mass-market volume.
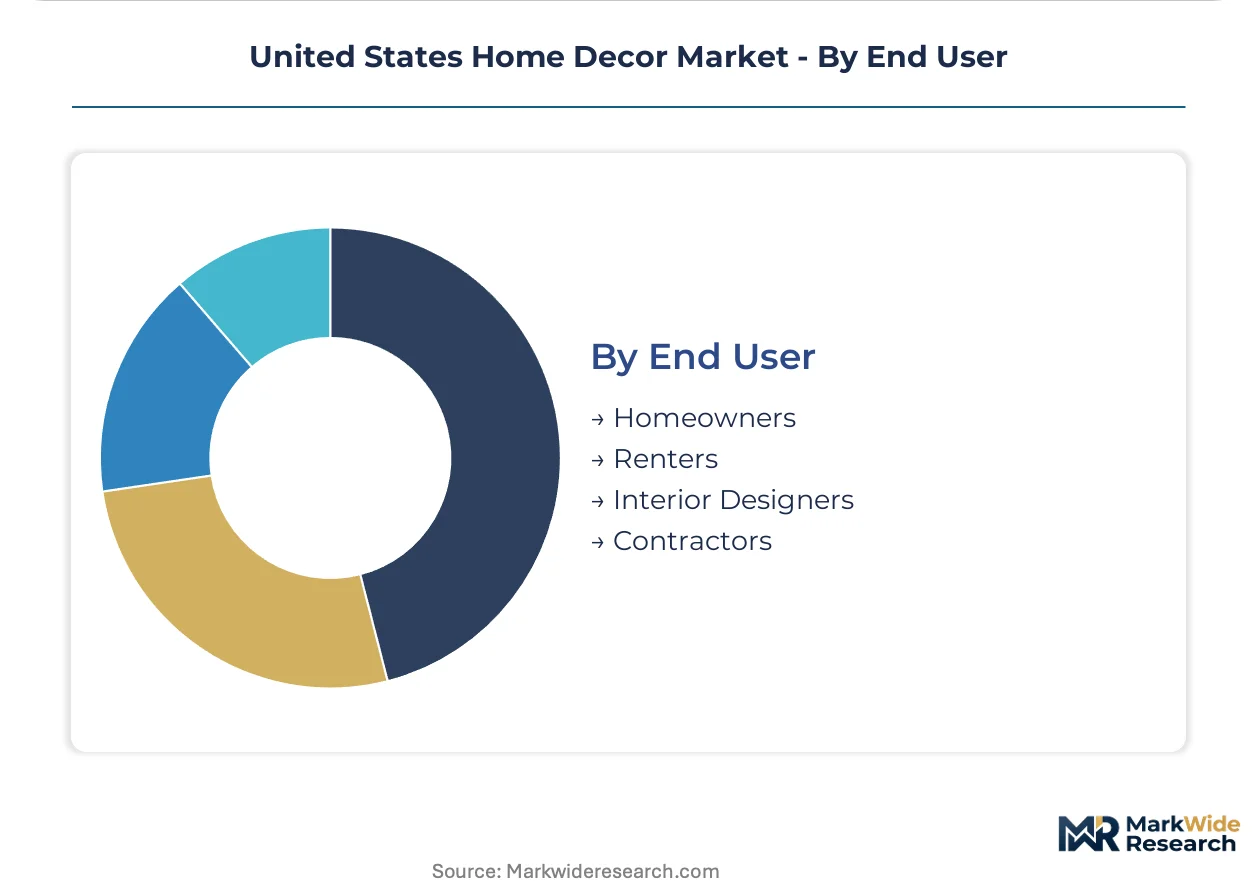
End User:
Customer type determines purchase frequency, project scale, and service intensity, with contractor and designer channels requiring distinct fulfillment infrastructure.
- Homeowners:Primary residential purchasers drive replacement demand with 3-5 year refresh cycles among millennial first-time buyers. Whole-home renovation projects concentrate in Florida and Texas metro areas where housing starts outpace national averages.
- Renters:Transient households favor portable, non-permanent decor solutions. Rental-to-own platforms and fast-fashion retailers capture this segment through lower commitment thresholds and trend velocity.
- Interior Designers:Specification professionals coordinate aesthetic direction across multiple lifestyle brands. In-house design studios at major retailers capture this channel through coordinated collection launches and trade pricing tiers.
- Contractors:Professional renovators and builders source through dedicated pro desks at home improvement retailers. Bulk pricing tiers and next-day delivery promises in dense coastal corridors capture renovation-driven volume from investor-owned rental properties.
Homeowners generate the largest transaction volume while interior designers drive the highest margin capture per project.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal metros command 40% pricing premiums over interior states, while Texas corridor absorption rates outpace national benchmarks by 3 percentage points. This geographic asymmetry reshapes manufacturer allocation decisions and inventory positioning strategies.
California
Los Angeles and San Francisco metros drive LED fixture penetration through Title 24 energy mandates that compress refresh cycles to 3-5 years. EPA formaldehyde standards and BHGS labeling requirements de facto govern national inventory decisions. Sacramento's regulatory influence extends through retail compliance chains that refuse non-certified substrate shipments.
Texas
Dallas-Fort Worth and Houston housing starts exceed national averages, concentrating furniture demand among millennial first-time buyers. State energy codes lag California but municipal adoption of green building standards accelerates in Austin and San Antonio. Houston's port infrastructure anchors upholstery fabric import flows from Vietnam and Indonesia.
New York Metro
High-density residential construction in Brooklyn and Queens favors space-efficient furniture formats and smart-home integration. Local Law 97 carbon emission caps pressure commercial-to-residential conversion projects toward LED retrofits. New Jersey distribution corridors serve last-mile fulfillment promises into Manhattan and coastal Connecticut.
Florida
Orlando and Tampa metros exhibit younger household formation rates that drive 3-5 year furniture rotation patterns. Hurricane-resistant building codes shape window treatment and fixture specifications distinct from national catalogs. Miami's design district anchors bohemian and modern aesthetic import flows from Latin American suppliers.
Pacific Northwest
Seattle and Portland metros prioritize sustainable material sourcing and reclaimed wood aesthetics in response to consumer preference shifts. Washington State chemical disclosure mandates add compliance documentation burdens for national retailers. Vancouver BC cross-border sourcing relationships influence solid timber procurement patterns for regional case goods manufacturers.
United States Home Decor Market Competitive Environment
Big-box retailers and direct-to-consumer platforms split the market into distinct fulfillment ecosystems with incompatible inventory models. The vendor base concentrates around three strategic archetypes: vertically integrated manufacturers controlling substrate-to-showroom chains, platform aggregators leveraging proprietary logistics networks, and specialty retailers anchoring professional contractor channels. Dominant competitive moves include captive design studio acquisitions and last-mile infrastructure expansion into secondary metros.
Within the platform-aggregator tier, Wayfair Inc. and Target Corporation exemplify divergent approaches to inventory risk management. Among big-box incumbents, The Home Depot Inc. anchors professional channel access through dedicated pro desks. Williams-Sonoma Inc. occupies a position within the specialty-retail vector, representing in-house design studio control across multiple lifestyle brands. These three companies illustrate how scale, specialization, and vertical integration separate winners from margin-compressed followers.
| Leading Market Players |
|---|
| The TJX Companies Inc. |
| IKEA USA |
| The Home Depot Inc. |
| Floor & Decor Holdings Inc. |
| Ashley Furniture Industries |
| Lowe's Companies Inc. |
| Williams-Sonoma Inc. |
| Target Corporation |
| Wayfair Inc. |
| Others |
Value Chain & Pricing Dynamics
Houston's port infrastructure anchors upholstery fabric import flows from Vietnam and Indonesia, concentrating inbound capacity for Texas metropolitan furniture demand. This geographic clustering amplifies pricing power for mills with certified CARB Phase II substrate access, while squeezing margin for distributors lacking direct mill relationships.
Pricing Analysis
Configured-to-order pricing for custom upholstery commands 40-60% premiums over standard SKUs in mass-market retail channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with EPA TSCA Title VI compliance separating premium tiers. Price erosion runs through economy furniture lines as softwood lumber input volatility compresses margin predictability. Professional contractors exhibit lowest price sensitivity due to pass-through mechanisms in renovation contracts, while millennial first-time buyers in rental-to-own platforms show highest elasticity.
Supply Chain Analysis
Tariff exposure between Vietnam and the United States dominates risk calculus for metal component and upholstery fabric sourcing. Vietnam, Indonesia, and China supply 70% of woven textiles and precision metal frames feeding American furniture assembly. Raw material dependencies center on Southeast Asian polyester yarn, North American softwood lumber, and Chinese LED module components. Single-source vulnerability concentrates in Houston port congestion during peak import seasons. Distribution runs through big-box retail pro desks and direct-to-consumer platforms with incompatible inventory models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across style tiers and end-user channels creates niche formation opportunities as millennial refresh-cycle compression displaces traditional decade-long furniture investment patterns.
For Market Incumbents: Insulate core margin pools by acquiring captive upholstery mills in Vietnam to secure tariff-advantaged fabric supply. Invest in CARB Phase II certification infrastructure to maintain retail channel access as California's BHGS labeling requirements tighten. Backward integration into engineered wood substrate production defends against EPA formaldehyde standard escalation.
For New Entrants and Emerging Players: Build out rental-to-own platform partnerships targeting Dallas-Fort Worth and Houston millennial households with 3-5 year rotation preferences. Capture white space in smart-integrated lighting fixtures for Title 24 retrofit compliance, where electrical contractor coordination protocols remain undeveloped. Pursue direct-to-consumer last-mile fulfillment in secondary Texas metros lacking Wayfair density.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with captive design studios controlling aesthetic direction across multiple lifestyle brands. Long-term viability hinges on substrate-to-showroom chain ownership that buffers tariff and certification volatility. Monitor LED fixture penetration rates in California new construction as inflection indicator for smart-home integration demand spreads.
| Strategic Initiative | Industry Significance |
|---|---|
| Design Studio Acquisition | Captive aesthetic direction accelerates coordinated collection launches across lifestyle tiers. |
| Last-Mile Network Expansion | Proprietary fulfillment infrastructure enables next-day delivery promises in dense coastal corridors. |
| Certification Infrastructure Investment | CARB Phase II and TSCA Title VI compliance secures retail channel access nationwide. |
| Direct-to-Consumer Platform Launch | Bypass wholesale intermediaries to capture millennial refresh-cycle volume in secondary metros. |
| Professional Contractor Channel Development | Dedicated pro desks with bulk pricing tiers capture renovation-driven volume from investor-owned rentals. |
Study Parameters
A standing panel of furniture manufacturing executives, retail category buyers, interior design studio directors, and residential construction procurement managers provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against EPA regulatory filings, California BHGS enforcement data, and customs import records tracking Vietnam and Indonesia textile flows. Bottom-up demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing framed volume projections across product type, material, style, and end-user segmentation dimensions. CAGRs derived from replacement cycle velocity analysis, housing start correlations, and regulatory compliance cost trajectories. Forecast inputs incorporated Title 24 adoption curves, millennial household formation rates, and LED fixture technology cost declines.
Practitioners should monitor lumber futures volatility, Vietnam tariff policy shifts, and California chemical disclosure mandate expansion for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
USA Bed Pillow Market
Homecare and Decor
Smart Vase Market
Homecare and Decor
Digital Printed Wallpaper Market
Homecare and Decor
Wall Art Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
Pillow Cases Market
Homecare and Decor
US Halloween Decorations Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
India Sustainable Home Decor Market
Homecare and Decor
Vinyl Wallpaper Market
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
US Wallpaper Market
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
Flush Door Market
Homecare and Decor
United Arab Emirates Interior Design Market