
 Furniture & Cabinet Hardware Market | 2026-2036
Furniture & Cabinet Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Furniture & Cabinet Hardware Market Insights
The furniture and cabinet hardware sector is pivoting around a widening split between premium soft-close systems and commodity-grade basic hinges. Hettich leverages its German engineering heritage to dominate European kitchen OEM channels with integrated drawer systems. Blum sustains technology leadership in lift mechanisms and concealed hinge platforms. Hi-Gold anchors Asia-Pacific supply through cost-optimized zinc alloy production at scale.
Furniture and cabinet hardware comprises mechanical and electromechanical fittings—hinges, slides, locks, and pulls—typically fabricated from stainless steel, zinc alloy, or brass through die-casting, stamping, and surface plating processes, designed to enable motion control, security, and ergonomic access in storage applications. Hinges and slides occupy the largest volume share as replacement-cycle staples in residential furniture, while soft-close and push-to-open mechanisms command premium positioning in hospitality installations. Stainless steel and zinc alloy materials lead value contribution due to durability requirements in humid environments, though aluminum gains traction in lightweight office fixtures.
REACH in Europe restricts hexavalent chromium in plating processes, while China's GB standards enforce corrosion-resistance grades for domestic and export-bound hardware. The US EPA regulates volatile organic compound emissions from coating operations, pushing manufacturers toward water-based finishes. Stakeholders must monitor evolving material compliance thresholds and decide between regional certification investments or modular platform designs that span multiple regulatory regimes.
Market Dynamics
The furniture and cabinet hardware sector is bifurcating around soft-close mechanism adoption versus commodity hinge replacement cycles, with regulatory corrosion standards in Europe and China forcing material upgrades across plating processes.
Growth Catalysts
- Residential renovation intensity:Home improvement spending in Germany and the United States is accelerating cabinet refacing projects that demand premium drawer systems and concealed hinges.
- REACH compliance migration:European manufacturers are converting hexavalent chromium plating lines to trivalent alternatives, creating upgrade demand for compliant zinc alloy and stainless steel hardware.
- Smart storage integration:Electromechanical lift mechanisms and sensor-activated opening systems are penetrating hospitality and healthcare furniture specifications.
Market Restraints
- Zinc price volatility:Die-cast zinc alloy feedstock costs fluctuate with London Metal Exchange pricing, compressing margin on economy-grade hinges and slides produced at scale.
- Guangdong supply concentration:Over half of global cabinet hardware fabrication clusters in China's Pearl River Delta, exposing buyers to concentrated logistics disruption and trade policy friction.
- Technical ceiling on miniaturization:Concealed hinge torque ratings face physics constraints below 15mm cup diameters, limiting ultra-compact furniture applications.
Strategic Opportunities
- India residential construction:Affordable housing programs and urban kitchen modernization are creating first-time demand for organized-brand hardware over unbranded local alternatives.
- Water-based coating mandates:EPA volatile organic compound regulations are pushing manufacturers to develop compliant surface finishes that command specification in LEED-certified commercial projects.
- E-commerce specification tools:Digital configurators allowing architects to preload hardware schedules into BIM models are bypassing traditional distributor relationships.
Industry Challenges
- Surface engineering talent scarcity:Electrochemical plating specialists with trivalent chromium expertise are in short supply relative to conversion demand from REACH-affected facilities.
- Multi-jurisdiction certification timelines:Simultaneous GB standard testing for China, CE marking for Europe, and ANSI/BHMA certification for North America extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Furniture & Cabinet Hardware Market |
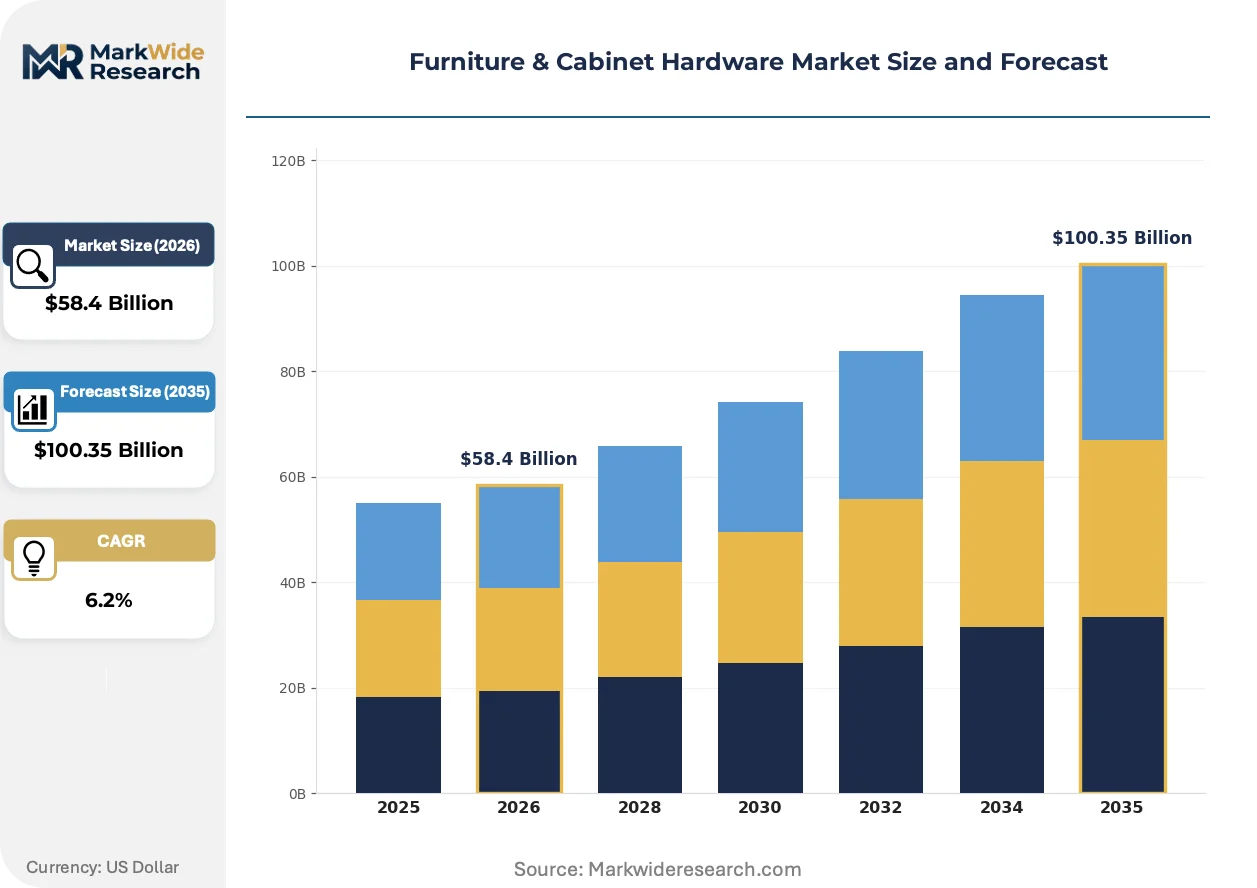
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $100.35 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knobs, Pulls, Hinges, Slides, Locks, Catches Material: Stainless Steel, Zinc Alloy, Aluminum, Brass, Plastic, Wood Application: Residential Furniture, Office Fixtures, Hospitality Installations, Educational Institutions Customer Type: Retailers, Distributors, Contractors, Interior Designers, OEMs |
| Companies Covered | Hettich, Blum, Salice, Accuride, Vauth Sagel, Kesseböhmer, Hi-Gold, ADAMS, Hafele, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Furniture & Cabinet Hardware Market Trends and Innovations
Motion control technologies and regulatory material bans are compressing traditional hardware replacement economics while elevating electromechanical systems in premium specifications.
Sensor-integrated cabinet access systems is electrifying residential kitchen and bathroom vanity segments. High-end condominium developers in Singapore and the United Arab Emirates are specifying touchless lift mechanisms for overhead storage. This convergence of mechanical hardware with IoT controls is compressing the addressable market for purely mechanical premium hinges.
REACH Annex XVII restrictions on hexavalent chromium compounds are forcing plating process reinvestment across European supply chains. Trivalent chromium and nickel-free alternatives now dominate new line installations. German and Italian OEMs are qualifying these finishes for marine-grade corrosion resistance in humid climate exports.
Architects are consolidating hardware specifications into master agreements with direct manufacturer relationships. Traditional two-step distribution through regional building material wholesalers is losing share in commercial furniture channels. This consolidation is most visible in United States healthcare and education verticals where facility standardization programs predominate.
Furniture & Cabinet Hardware Market Segmentation
Furniture and cabinet hardware segments diverge sharply by capital intensity, with electromechanical systems demanding precision tooling while commodity hinges run on legacy stamping equipment. Material selection and finish compliance drive working capital requirements more than volume scale in this market.
Product Type:
Die-casting and plating infrastructure requirements vary dramatically across mechanical fitting categories, with soft-close mechanisms commanding the highest upfront tooling investment.
- Hinges:Concealed cup hinges with integrated damping cylinders require multi-cavity molds and torque-calibration testing rigs. German kitchen OEMs specify these for residential renovation projects, though technical constraints below 15mm cup diameters limit ultra-compact applications.
- Slides:Ball-bearing drawer systems with full-extension channels demand precision rolling mills and corrosion-resistant coating lines. Hospitality installations in Singapore and the United Arab Emirates drive specification of heavy-duty load-rated variants for commercial cabinetry.
- Knobs:Die-cast or machined gripping elements with surface plating.
- Pulls:Bar and cup-handle configurations in varying center-to-center dimensions.
- Locks:Cam and pin-tumbler mechanisms for security applications.
- Catches:Magnetic and roller latches for door retention.
Most installed capacity flows through Hinges. Expansion is steepest in Slides.
Material:
Raw material sourcing strategies separate premium positioning from economy-grade production, with nickel-free alternatives requiring qualified supply chains.
- Zinc Alloy:Die-cast ZAMAK formulations dominate volume production for economy hinges and decorative pulls. Pearl River Delta fabricators leverage scale advantages, though London Metal Exchange price volatility compresses margins on undifferentiated output.
- Stainless Steel:Austenitic grades deliver marine-grade corrosion resistance for humid climate exports. Italian and German OEMs qualify these finishes under REACH-compliant trivalent chromium processes for European kitchen channels.
- Aluminum:Extruded and machined lightweight components for office fixtures.
- Brass:Cast and forged traditional hardware with living finishes.
- Plastic:Injection-molded polymer components for cost-sensitive applications.
- Wood:Turned and carved decorative elements for artisan furniture.
Zinc Alloy commands the greatest production volume. Stainless Steel is gaining specification fastest in premium channels.
Application:
End-use environments dictate performance tier requirements, with commercial installations demanding cycle-life certification absent from residential replacement markets.
- Residential Furniture:Kitchen and bathroom vanity installations drive replacement-cycle demand for concealed hinges and soft-close drawer systems. Refacing projects in Germany and the United States accelerate specification of premium integrated hardware over commodity alternatives.
- Hospitality Installations:Hotel guest room and back-of-house specifications require cycle-tested durability and standardized master keying. Sensor-activated lift mechanisms are penetrating this segment in Singapore and the United Arab Emirates high-rise developments.
- Office Fixtures:Modular workstation and storage systems for commercial interiors.
- Educational Institutions:Heavy-duty applications for school and university furniture.
Residential Furniture absorbs the majority of unit volume. Hospitality Installations show the steepest specification upgrade trajectory.
Customer Type:
Channel economics fragment between specification-driven direct relationships and price-sensitive wholesale procurement.
- OEMs:Kitchen and bathroom cabinet manufacturers qualify hardware through extended testing protocols and multi-year supply agreements. Architects in United States healthcare and education verticals are consolidating specifications into master agreements that bypass traditional distribution.
- Distributors:Regional building material wholesalers stock breadth across price tiers for contractor pickup.
- Retailers:Big-box and specialty stores serving DIY replacement demand.
- Contractors:Installation professionals sourcing for project fulfillment.
- Interior Designers:Specification consultants curating aesthetic-coordinated hardware packages.
OEMs represent the highest-value channel. Distributors retain volume dominance in replacement markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plating specialists with trivalent chromium expertise cluster disproportionately in Germany and Italy, anchoring European supply for REACH-compliant finishes. Tooling engineers for precision die-casting concentrate in China's Pearl River Delta and Japan's Kansai region.
China
Residential kitchen modernization and affordable housing programs in tier-two cities are accelerating specification of organized-brand hardware. GB standards enforced by SAMR mandate corrosion-resistance grades for both domestic sales and export-bound production. The Pearl River Delta manufacturing cluster around Dongguan and Foshan houses over half of global cabinet hardware fabrication capacity.
Germany
Kitchen OEMs in Baden-Württemberg and North Rhine-Westphalia are converting hexavalent chromium plating lines to REACH-compliant trivalent alternatives under ECHA enforcement. Extended producer responsibility frameworks are tightening material traceability requirements across supply chains. Stuttgart and Bielefeld anchor precision tooling networks for concealed hinge systems.
United States
Home improvement spending in Texas and Florida is accelerating cabinet refacing projects demanding premium drawer systems. EPA volatile organic compound regulations are pushing manufacturers toward water-based coating technologies. The Southeast manufacturing corridor spanning Georgia and the Carolinas is attracting plating facility reinvestment.
India
Urban kitchen modernization in Maharashtra and Gujarat is creating first-time demand for branded hardware over unbrased local alternatives. BIS certification requirements are tightening for imported zinc alloy components. The Pune-Ahmedabad industrial belt is emerging as a fabrication hub for cost-optimized hinge production.
Italy
High-end furniture exporters in Lombardy and Veneto are qualifying nickel-free finishes for marine-grade corrosion resistance. CE marking requirements under EU construction product regulations are extending testing protocols for hardware cycle life. The Brianza furniture district north of Milan concentrates premium hinge specification relationships with German kitchen OEMs.
Furniture & Cabinet Hardware Market Competitive Landscape
Top-tier vendors anchor premium specification channels through integrated drawer systems and concealed hinge platforms, while mid-tier fabricators compete on cost-optimized zinc alloy production at scale. The vendor base stratifies across three strategic archetypes: German engineering-led system integrators, Asia-Pacific scale manufacturers, and Italian design-specialist finish houses. Dominant competitive moves include backward integration into captive plating operations and geographic expansion through specification relationships with architects.
Among German-origin system integrators, Hettich GmbH and Blum GmbH exemplify the engineering-led archetype through multi-year supply agreements with kitchen OEMs. Hi-Gold Hardware Group Co., Ltd. anchors the Asia-Pacific scale tier with cost-optimized production capabilities. These three entities collectively represent the competitive spectrum from premium concealed hinge platforms to volume-driven zinc alloy fabrication.
| Leading Market Players |
|---|
| Hettich |
| Blum |
| Salice |
| Accuride |
| Vauth Sagel |
| Kesseböhmer |
| Hi-Gold |
| ADAMS |
| Hafele |
| Others |
Pricing and Supply Chain Analysis
Plating specialists with trivalent chromium expertise cluster disproportionately in Germany and Italy, creating labor-cost differentials that widen pricing spreads between REACH-compliant premium hardware and commodity-grade zinc alloy alternatives sourced from China's Pearl River Delta.
Pricing Analysis
The bundled-vs-unbundled service split separates premium hardware from commodity alternatives. Pricing stratifies across premium, standard, and economy tiers based on corrosion-resistance certification grade and after-sales technical support. Cost compression in economy-grade zinc alloy hinges is intensifying because London Metal Exchange price volatility squeezes fabricator margins. DIY retailers and contractor channels exhibit highest price sensitivity, while kitchen OEMs under extended supply agreements show lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Die-cast zinc alloy feedstock supply rests on London Metal Exchange pricing mechanisms and Chinese smelter output from Yunnan and Hunan provinces. Raw material sourcing draws from zinc concentrate, stainless steel coils, and specialty plating chemicals. Single-source vulnerability concentrates in Guangdong's Pearl River Delta fabrication cluster, where over half of global cabinet hardware capacity sits within 100 kilometers of Dongguan. Distribution runs through regional building material wholesalers for contractor pickup, though architects in United States healthcare and education verticals are consolidating specifications into direct manufacturer master agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The furniture and cabinet hardware market functions as a stable compounder, with residential renovation cycles providing steady replacement demand that smooths volatility across economic periods.
For Market Incumbents: Lock in specification relationships with kitchen OEMs through multi-year supply agreements that embed soft-close and push-to-open mechanisms as standard offerings. Deepen backward integration into captive trivalent chromium plating operations to defend margin position against REACH compliance cost inflation. Prioritize certification investment for marine-grade corrosion resistance to capture humid climate export demand from Southeast Asian condominium developers.
For New Entrants and Emerging Players: E-commerce specification tools represent the most penetrable channel wedge, enabling direct architect relationships that bypass entrenched two-step distribution. Target India's urban kitchen modernization wave in Maharashtra and Gujarat, where affordable housing programs create first-time demand for organized-brand hardware over unbranded local alternatives. Pursue water-based coating technology partnerships to qualify for LEED-certified commercial project specifications under EPA volatile organic compound mandates.
For Investors and Strategic Acquirers: Kitchen OEMs are the most active acquirer in this space, seeking captive hardware supply to secure specification control and margin capture. The 5-10 year investment horizon favors plating specialists with qualified trivalent chromium expertise and established REACH compliance infrastructure. Watch for inflection when sensor-integrated electromechanical systems achieve cost parity with premium mechanical hinges in hospitality specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plating Operations | Captive trivalent chromium capacity insulates margins from REACH compliance cost spikes in European supply chains. |
| Smart Storage Technology Partnership | Electromechanical lift mechanism alliances with IoT controls penetrate Singapore and UAE high-rise hospitality specifications. |
| Water-Based Coating Certification | EPA-compliant surface finishes unlock specification in United States healthcare and education LEED-certified projects. |
| India Manufacturing Footprint Expansion | Pune-Ahmedabad hub proximity reduces logistics costs for affordable housing program hardware demand. |
| BIM Configurator Platform Launch | Digital specification tools bypass traditional distributor relationships in United States healthcare facility standardization programs. |
Research Methodology
Coverage spans Europe, North America, Asia-Pacific, and India, with primary inputs from each region combined through structured interviews with plating facility operations managers, kitchen OEM procurement directors, architectural specification consultants, and regional building material distributors. Secondary validation draws from ECHA REACH enforcement documentation, EPA volatile organic compound regulatory filings, SAMR GB standard publications, and customs trade data. Bottom-up capacity assessments and top-down demand modeling triangulate volume and value estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product type, material grade, application environment, and customer channel. CAGRs derive from regression analysis against residential construction permits, renovation spending indices, and regulatory compliance cost curves. Industry-specific forecast inputs incorporate London Metal Exchange zinc price scenarios and REACH Annex XVII enforcement timelines.
Revisions become necessary when zinc price volatility exceeds historical bands, when REACH enforcement accelerates plating line conversion timelines, or when electromechanical system adoption curves steepen beyond current trajectory assumptions. A small set of named triggers warrants ongoing watch: Pearl River Delta logistics disruptions, trivalent chromium specialist labor availability, and smart storage integration cost crossover points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Asia-Pacific Home Furniture Market
Furniture
Europe Home Furniture Market
Furniture
Middle East and Africa Wood Based Panel Market
Furniture
Europe Sustainable Office Furniture Market
Furniture
GCC Furniture Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
HORECA Furniture Market
Furniture
High Density Fiberboard (HDF) Market
Furniture
Europe Multifunctional Furniture Market
Furniture
Wood Furniture Market
Furniture
Italy Furniture Retail Market
Furniture
Back Mount Frames Market
Furniture
North America High-End Furniture Market
Furniture
Indonesia Home Furniture Market
Furniture
Eco-Friendly Furniture Market
Furniture
Japan Home Furniture Market