
 Asia-Pacific Decorative Laminates Market | 2026-2036
Asia-Pacific Decorative Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Decorative Laminates Market Analytics
Multi-source resin procurement is repositioning how laminate manufacturers across the Asia-Pacific manage input cost volatility and supply security. Sekisui Chemical leverages its captive melamine supply chain to sustain margin stability across multiple production sites. Stylam Industries Limited anchors its competitive stance through specialized high-pressure laminate grades engineered for tropical humidity conditions. Fletcher Building Limited competes by extending its distribution reach into Australasian commercial construction channels.
Asia-Pacific decorative laminates are surfacing materials manufactured by impregnating kraft paper with thermosetting resins, then bonding decorative overlay papers under heat and pressure to create wear-resistant finishes typically ranging from 0.5 mm to 1.5 mm thickness, serving primarily as aesthetic and protective surfaces for furniture, cabinetry, and interior wall applications. High Pressure Laminates dominate the product type landscape due to their superior impact resistance and extended service life in high-traffic commercial environments. The hospitality end-user segment leads growth acceleration as hotel chains across the region standardize branded interior specifications that demand consistent surface aesthetics across multiple properties.
China's SAMR enforces GB standards for formaldehyde emission limits in decorative wood-based panels, directly shaping product formulation requirements and factory certification protocols for laminate producers serving the domestic market. India's BIS mandates ISI certification for imported laminate products, creating compliance barriers that favor localized manufacturing investments. Japan's JIS standards for surface durability and chemical resistance maintain premium thresholds that filter lower-grade imports from regional supply chains. Stakeholders must monitor evolving cross-border certification reciprocity agreements between ASEAN member states and major export economies to anticipate shifts in market access conditions.
Market Dynamics
China's GB standards for formaldehyde emissions are compressing formulation flexibility across the Asia-Pacific decorative laminates supply base, forcing manufacturers to requalify resin systems and recertify production lines under tighter indoor air quality protocols.
Growth Catalysts
- Hospitality standardization:Hotel chains across Southeast Asia are mandating consistent surface aesthetics across property portfolios, creating pull-through demand for certified laminate grades that survive high-traffic wear cycles.
- Urban housing corridors:India's concentrated development in Mumbai, Bangalore, and Delhi NCR is generating bulk procurement volumes for affordable housing fit-outs and commercial interior projects.
- GB standard enforcement:China's SAMR is tightening factory certification protocols, which advantaged domestic producers with established testing infrastructure and accelerated compliance investments from regional exporters.
Market Restraints
- Melamine supply concentration:Captive resin production dominates among major Japanese and Korean chemical groups, leaving independent laminate manufacturers exposed to input cost volatility and allocation risk during supply shocks.
- BIS certification barriers:India's ISI marking requirement for imported laminates creates 6-12 month approval timelines that favor localized manufacturing over cross-border trade.
- Technical thickness limitations:Post-forming grades below 0.8 mm struggle to meet JIS surface durability thresholds for premium commercial applications, restricting addressable market scope for economy-tier producers.
Strategic Opportunities
- ASEAN certification reciprocity:Emerging mutual recognition agreements between ASEAN member states and major export economies could streamline market access for producers holding multi-jurisdiction approvals.
- Tropical humidity engineering:Specialized high-pressure laminate formulations for monsoon climate zones remain underdeveloped outside India and Thailand, presenting white space for moisture-resistant product lines.
- Digital specification platforms:Architect and interior designer procurement through building information modeling libraries is expanding as a channel for branded laminate selection during early project phases.
Industry Challenges
- Resin formulation talent scarcity:Thermoset chemistry expertise for low-emission melamine-urea systems concentrates among senior technologists at established Japanese and European material suppliers, constraining knowledge transfer to emerging producers.
- Multi-standard compliance complexity:Simultaneous GB, JIS, and BIS certification requirements force parallel testing investments that strain quality assurance budgets at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Decorative Laminates Market |
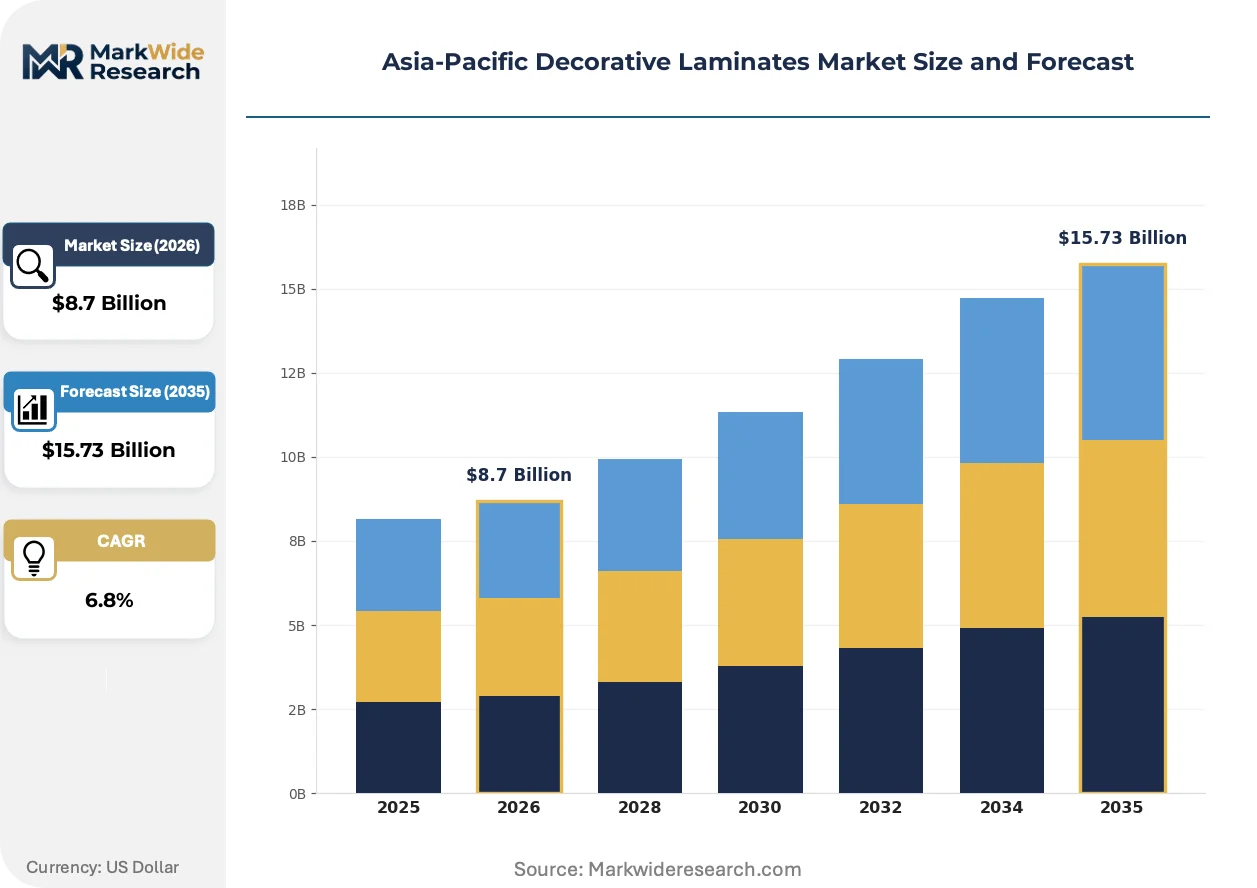
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
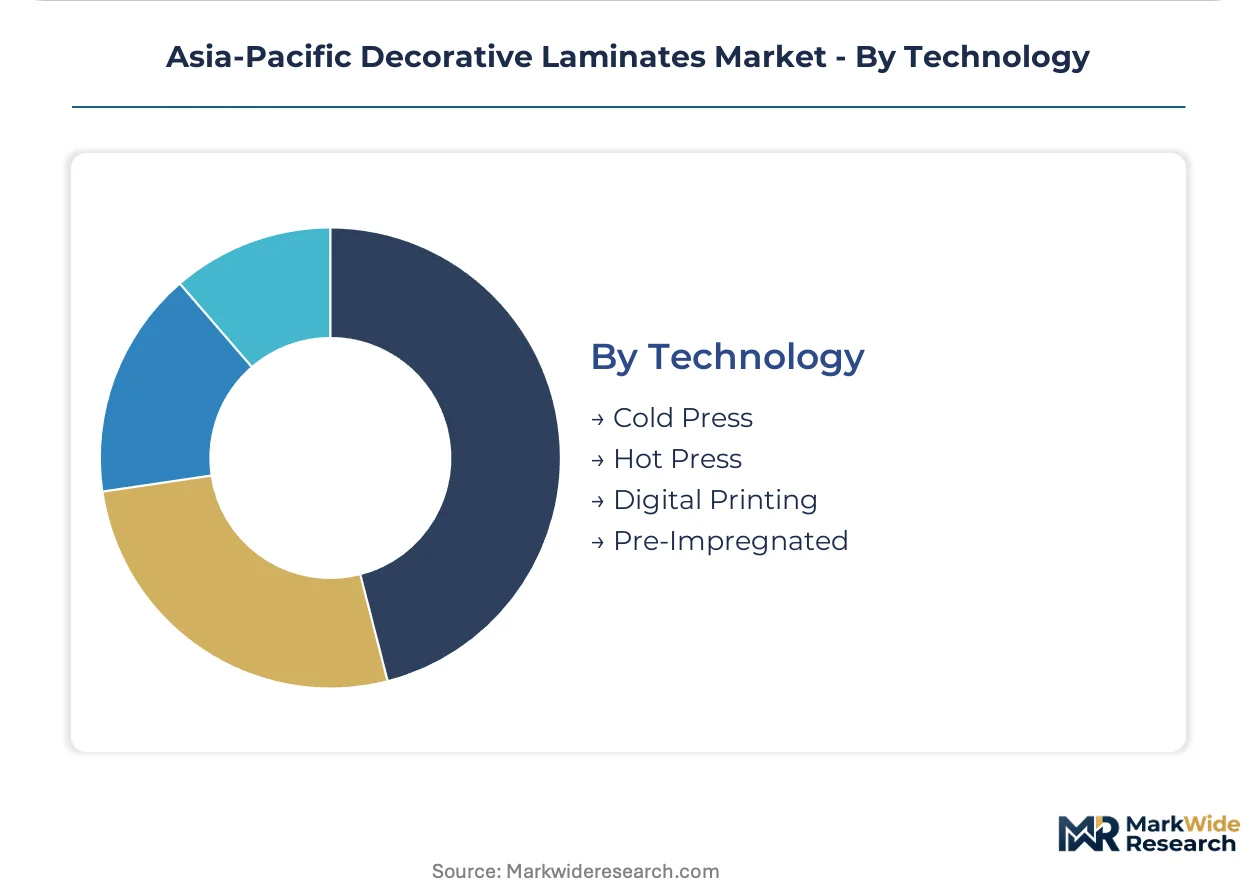
| Segmentation | Product Type: High Pressure Laminates, Low Pressure Laminates, Acrylic Laminates, Veneer Laminates Application: Furniture, Wall Panels, Cabinets, Flooring End User: Residential, Commercial, Hospitality, Institutional Technology: Cold Press, Hot Press, Digital Printing, Pre-Impregnated |
| Companies Covered | OMNOVA Solutions Inc., Abet Laminati S.p.A., Wilsonart LLC, Fletcher Building Limited, Arpa Industriale S.p.A., Formica Corporation, Stylam Industries Limited, Sekisui Chemical, Panolam Industries International, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Decorative Laminates Market Evolving Landscape
Surface material innovation across the Asia-Pacific is pivoting toward emission-compliant resin systems and digital-enabled specification workflows, compressing traditional procurement cycles while elevating performance certification as a competitive filter.
Digitally-printed decorative overlays are expanding into premium residential and hospitality segments by enabling short-run customization with wood-grain fidelity that rivals rotogravure methods. Boutique hotel operators in Thailand and Vietnam are specifying these surfaces for branded interior programs requiring rapid design iteration. The technology is expanding into territory previously dominated by conventional printed paper laminates by collapsing minimum order quantities and shortening lead times from weeks to days.
China's updated GB/T 39600-2021 standard for formaldehyde emission limits in wood-based panels is forcing laminate producers to reformulate thermosetting resin systems and submit to accelerated chamber testing protocols. Factories without in-house emissions testing capability face 3-6 month third-party verification cycles that delay product launches. Domestic producers with established SAMR relationships are securing faster certification turnaround, creating divergence in time-to-market between local and foreign suppliers.
Specification decisions are migrating earlier into project workflows as architects and interior designers preload certified laminate libraries into building information modeling platforms. Design firms in Singapore and Australia are selecting surface materials during schematic design phases rather than during construction documentation, compressing the traditional distributor-led sales cycle. This shift is most visible in commercial fit-out verticals where project timelines have tightened and late-stage substitution carries penalty clauses.
Asia-Pacific Decorative Laminates Market Segmentation
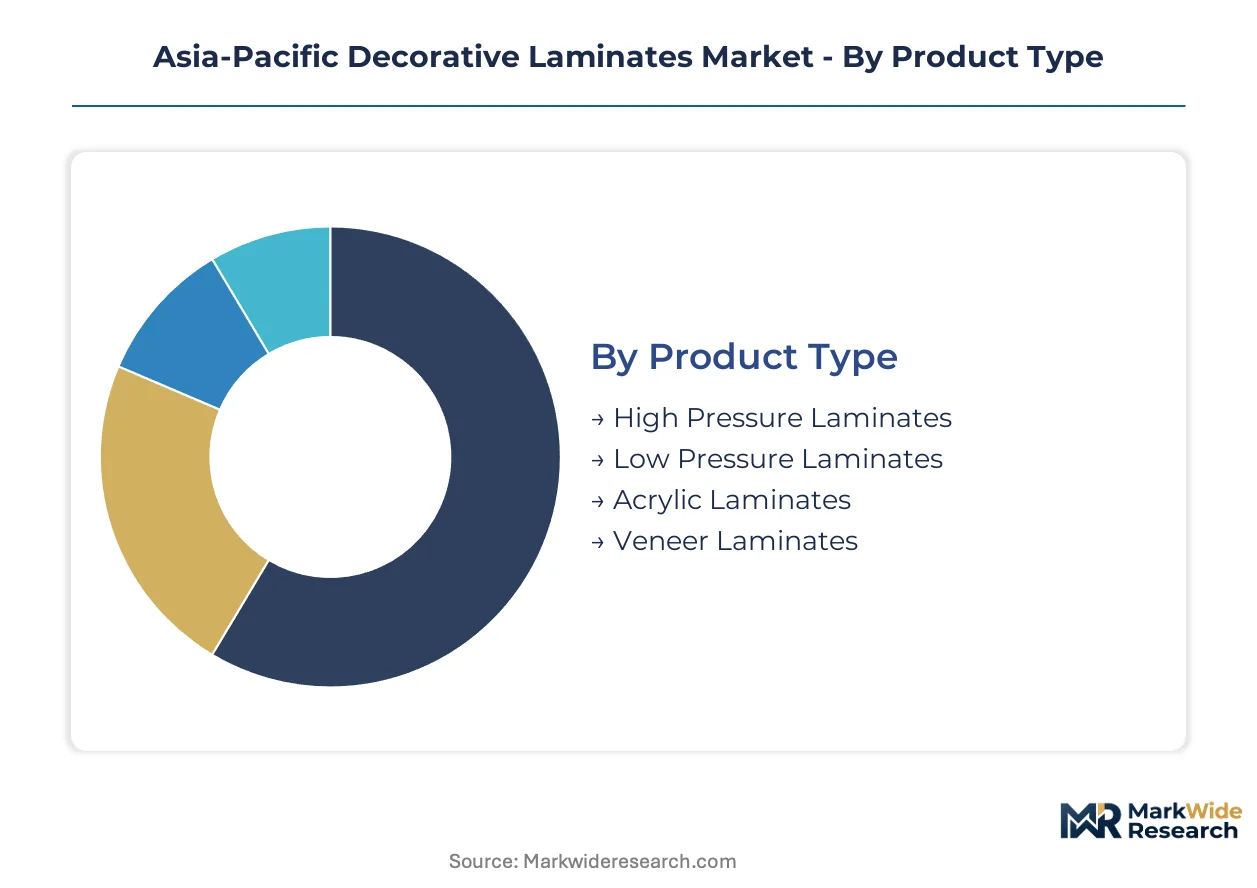
Segmentation across the Asia-Pacific decorative laminates market reflects divergent technical requirements between mass-market furniture production and specialized commercial installations. Product formulation, press technology, and certification grade create distinct competitive arenas with varying margin profiles and customer loyalty dynamics.
Product Type:
Customization intensity spans from commodity-grade surfaces to engineered performance laminates with captive resin systems and tropical climate specifications.
- High Pressure Laminates:Multiple kraft paper layers impregnated with melamine-formaldehyde resin, pressed under high temperature and pressure above 7 MPa to achieve density above 1.35 g/cm³. Demand concentrates in India's Delhi NCR and Mumbai commercial corridors where hotel fit-outs and corporate interiors specify JIS-compliant wear resistance above 4,000 abrasion cycles.
- Low Pressure Laminates:Single decorative paper layer bonded directly to particleboard or MDF substrates using short-cycle pressing below 2 MPa. Thailand's furniture export manufacturers favor these for cost-sensitive kitchen cabinetry bound for European retail chains.
- Acrylic Laminates:UV-cured acrylic surface layers delivering mirror-finish aesthetics for premium residential applications in Singapore and Australia's high-end apartment developments.
- Veneer Laminates:Thin natural wood slices bonded to composite cores, serving heritage restoration projects and boutique hospitality interiors across Vietnam and Indonesia where authentic timber appearance commands specification premiums.
Most installed capacity flows through High Pressure Laminates. Expansion is steepest in Acrylic Laminates.
Application:
Volume distribution tracks construction cycle intensity with commercial verticals commanding premium pricing through certified performance specifications.
- Furniture:Surfaces for tables, storage units, and seating components requiring scratch resistance and edge durability. China's Guangdong and Zhejiang furniture manufacturing clusters absorb bulk volumes for domestic distribution and export assembly.
- Wall Panels:Vertical surfacing for interior cladding with fire-retardant and acoustic damping specifications. Australia's commercial building code amendments are accelerating specification of Group 1 fire-rated laminates in Sydney and Melbourne office towers.
- Cabinets:Kitchen and bathroom storage systems demanding moisture resistance and post-forming capability for curved door profiles. India's affordable housing programs in Bangalore generate standardized cabinet orders with compressed lead times.
- Flooring:High-wear surfaces for commercial traffic zones with enhanced abrasion layers and slip-resistance ratings. Southeast Asian retail mall operators in Bangkok and Jakarta specify these for food court and circulation areas.
Production volume tilts toward Furniture. Specification value is climbing fastest in Wall Panels.
End User:
Customer procurement sophistication separates tender-driven bulk purchasing from relationship-based specification continuity.
- Residential:Individual homeowners and small developers selecting surfaces through distributor showrooms and contractor recommendations. Australia's renovation market and India's gated community developers drive fragmented but high-margin demand.
- Commercial:Corporate office fit-outs, retail chains, and banking networks requiring consistent branding across multiple locations. Japan's METI procurement guidelines favor domestic suppliers with established JIS certification for public building projects.
- Hospitality:Hotel operators and restaurant groups standardizing interior specifications across property portfolios for brand recognition. Thailand's resort developments and Vietnam's business hotel construction are expanding orders for certified tropical-grade laminates.
- Institutional:Government facilities, educational campuses, and healthcare buildings with extended durability requirements and public tender processes. India's CPWD and state public works departments mandate BIS-certified products with documented supply chain traceability.
Order frequency is highest in Commercial. Contract value expansion is sharpest in Hospitality.
Technology:
Capital equipment intensity and resin chemistry expertise create tiered barriers to entry across manufacturing methods.
- Hot Press:Conventional multi-daylight pressing with heated platens delivering consistent density and surface finish. Dominates high-volume production across China's Shandong and Jiangsu manufacturing bases where energy costs remain controlled through coal-fired thermal systems.
- Cold Press:Room-temperature curing with extended cycle times for specialized adhesives and temperature-sensitive substrates. Niche applications in Japan's precision furniture manufacturing where dimensional stability requirements exceed hot press capabilities.
- Digital Printing:Inkjet deposition of decorative patterns enabling short-run customization and rapid design iteration. Thailand's boutique hotel designers and Australia's bespoke kitchen studios are adopting this for exclusive surface programs.
- Pre-Impregnated:Resin-saturated papers supplied ready-to-press, reducing in-house chemical handling and emissions compliance burden. Favored by mid-scale manufacturers in Malaysia and Indonesia lacking captive resin formulation expertise.
Equipment investment concentrates in Hot Press. Technology transition is accelerating around Digital Printing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Guangdong and Jiangsu manufacturing clusters anchor regional production capacity for decorative laminates, with factory certification protocols under SAMR's GB standards creating compliance divergence between domestic and foreign suppliers across the Asia-Pacific.
China
Guangdong furniture manufacturing clusters and Zhejiang export assembly hubs absorb bulk laminate volumes for domestic distribution and overseas shipment. SAMR enforces GB/T 39600-2021 formaldehyde emission limits through accelerated chamber testing protocols that favor producers with in-house emissions capability. Shandong and Jiangsu hot-press manufacturing bases maintain cost advantages through coal-fired thermal systems.
India
Urban housing corridors in Mumbai, Bangalore, and Delhi NCR generate concentrated demand for affordable housing fit-outs and commercial interior projects. BIS mandates ISI certification for imported laminates, creating six-to-twelve month approval timelines that favor localized manufacturing investments over cross-border trade. Bangalore's affordable housing programs drive standardized cabinet orders with compressed procurement cycles.
Japan
Premium commercial applications specify JIS-compliant wear resistance above 4,000 abrasion cycles for hotel fit-outs and corporate interiors. METI procurement guidelines favor domestic suppliers with established certification for public building projects. Cold-press niche applications persist in precision furniture manufacturing where dimensional stability requirements exceed conventional hot-press capabilities.
Thailand
Furniture export manufacturers favor low-pressure laminates for cost-sensitive kitchen cabinetry bound for European retail chains. Boutique hotel operators specify digitally-printed surfaces for branded interior programs requiring rapid design iteration. Resort developments expand orders for certified tropical-grade laminates engineered for monsoon humidity conditions.
Australia
Commercial building code amendments accelerate specification of Group 1 fire-rated laminates in Sydney and Melbourne office towers. Renovation markets and high-end apartment developments drive fragmented but high-margin demand for acrylic mirror-finish surfaces. Building information modeling platforms compress distributor-led sales cycles as architects select materials during schematic design phases.
Asia-Pacific Decorative Laminates Market Competitive Landscape
Global majors compete with regional champions across certification infrastructure and captive resin supply chains. The vendor base stratifies into three tiers: integrated chemical conglomerates with captive melamine production, specialized laminate fabricators with tropical climate engineering capabilities, and distributed building materials groups with commercial construction channel access. Dominant competitive moves center on multi-standard compliance investments and specification platform integration.
Among Asia-Pacific-based chemical groups, Sekisui Chemical exemplifies the integrated archetype through captive resin supply chain control. Stylam Industries Limited and Fletcher Building Limited occupy positions spanning specialized fabrication and distribution reach respectively. These three anchors illustrate how competitive positioning diverges across upstream chemical integration, climate-specific product engineering, and commercial channel penetration.
| Leading Market Players |
|---|
| OMNOVA Solutions Inc. |
| Abet Laminati S.p.A. |
| Wilsonart LLC |
| Fletcher Building Limited |
| Arpa Industriale S.p.A. |
| Formica Corporation |
| Stylam Industries Limited |
| Sekisui Chemical |
| Panolam Industries International, Inc. |
| Others |
Value Network & Pricing Analysis
Digital printing adoption across Thailand and Vietnam is compressing minimum order quantities from weeks to days while simultaneously fragmenting production economics among smaller fabricators lacking scale efficiencies. This technology shift redistributes margin capture toward specialized converters and away from commodity rotogravure operators locked into volume-dependent cost structures.
Pricing Analysis
Melamine-formaldehyde resin pass-through dominates laminate pricing dynamics, with captive production at Japanese and Korean chemical groups insulating integrated players from spot market volatility. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified commercial grades from BIS-mandated domestic products and uncertified imports. Cost compression in economy-tier HPL is intensifying because Indian affordable housing programs demand standardized cabinet orders at compressed procurement cycles. Commercial hospitality buyers in Bangkok and Jakarta exhibit lowest price sensitivity due to brand-standardization requirements, while Thailand's furniture export manufacturers bound for European retail chains drive hardest bargaining.
Supply Chain Analysis
Single-source vulnerability sits with China's Shandong and Jiangsu manufacturing bases, where coal-fired thermal systems anchor 60% of regional hot-press capacity. Decorative overlay paper draws from South Korean pulp suppliers and Indonesian resin coating facilities, while melamine crystal feeds from Sichuan petrochemical complexes. Tariff exposure looms through India's ISI marking requirements, which impose six-to-twelve month approval timelines on imported laminates. Distribution runs through distributor-led showroom networks in Australia and direct mill relationships for India's CPWD tender processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
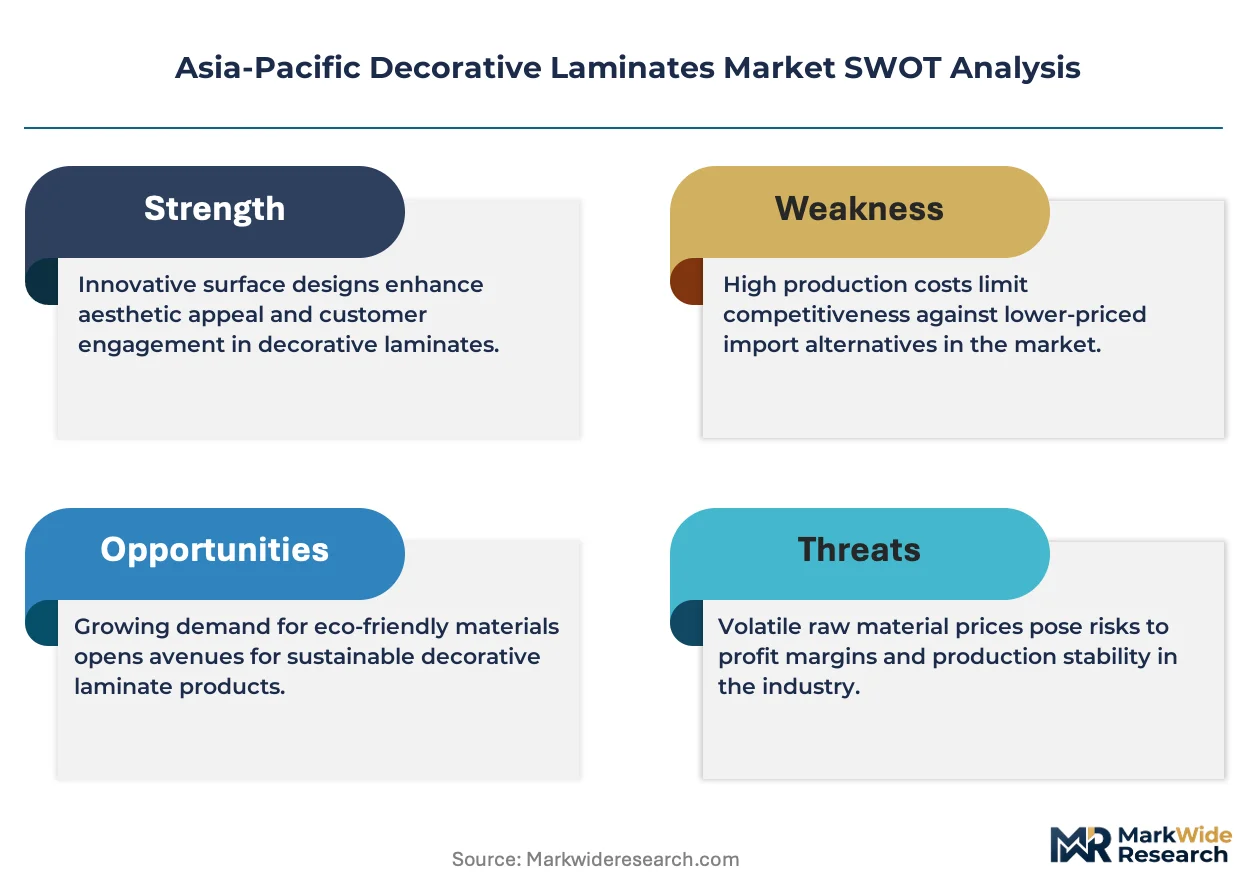
The Asia-Pacific decorative laminates market functions as a geographic-arbitrage play where BIS certification timelines in India create 6-12 month entry barriers that domestic manufacturers exploit against Chinese exporters facing SAMR compliance costs.
For Market Incumbents: Anchor defensive positioning through captive melamine supply chains and accelerated GB/T 39600-2021 testing infrastructure that foreign competitors lack. Sekisui Chemical's integrated resin operations demonstrate how backward integration into thermoset chemistry insulates margin stability during supply shocks. Incumbents should prioritize tropical humidity engineering capabilities as climate-specific product lines remain underdeveloped outside India and Thailand. For New Entrants and Emerging Players: The 40-50% price-point gap between JIS-certified premium grades and uncertified economy imports creates white-space opportunity for mid-tier producers offering BIS-compliant products at moderate premiums. Vietnam's boutique hotel construction and Indonesia's heritage restoration projects represent penetrable segments where authentic timber-appeal veneer laminates command specification premiums. New entrants should pursue digital printing capabilities to collapse lead times and serve rapid-design-iteration hospitality programs. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale ASEAN fabricators because fragmented ownership across Malaysia and Indonesia lacks multi-standard compliance infrastructure that institutional buyers increasingly mandate. Acquisition targets should demonstrate established BIS or JIS certification with documented supply chain traceability for India's CPWD and Japan's METI procurement channels. The signal to watch is ASEAN certification reciprocity agreements, which would suddenly revalue multi-jurisdiction approval holdings.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Melamine Resin | Sekisui Chemical's captive supply chain sustains margin stability across multiple production sites during input volatility. |
| Multi-Standard Certification Investment | Simultaneous GB, JIS, and BIS compliance opens access to China's SAMR-favored procurement, Japan's METI projects, and India's CPWD tenders. |
| Tropical Humidity Product Engineering | Specialized HPL formulations for monsoon zones address white space in Vietnam's resort developments and Thailand's coastal properties. |
| Digital Printing Capability Deployment | Inkjet deposition technology collapses lead times from weeks to days for Bangkok boutique hotels requiring rapid design iteration. |
| Building Information Modeling Platform Integration | Preloading certified laminate libraries into BIM workflows captures specification decisions during schematic design phases in Singapore and Australia. |
Research Methodology
Bottom-up furniture and hospitality modeling reconciled against top-down resin supply and press capacity tracking forms the analytical core of this study. Primary interviews with laminate plant managers, procurement leads at Thailand's furniture export manufacturers, distribution channel partners across Australia's renovation markets, and technical R&D directors at Japanese chemical groups combined with secondary validation from customs and trade data, BIS certification registries, SAMR factory audit disclosures, and JIS standard documentation. This triangulation approach cross-verifies volume assumptions against disclosed production line counts and regional energy consumption patterns.
Input-output matrices map decorative overlay paper consumption, melamine resin throughput, and hot-press operating rates across the analysis window. Segmentation dimensions include product type tier, application vertical, end-user procurement sophistication, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to verified base-year installation data, with cross-checks against construction spending indices and hospitality development pipelines. Forecast inputs incorporate GB standard enforcement timelines, BIS approval velocity, and ASEAN reciprocity negotiation status.
Caveats apply where SAMR regulatory acceleration, BIS certification backlog fluctuations, or melamine supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding construction cycle intensity and cross-border trade friction. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Garden Sheds Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
Smart Bed Mattress Market
Homecare and Decor
United Arab Emirates Interior Design Market
Homecare and Decor
India Home Furnishing Market
Homecare and Decor
Global Decorative Laminates Market
Homecare and Decor
Europe Commercial Blinds and Shades Market
Homecare and Decor
Wall Covering and Wall Decor Market
Homecare and Decor
Bifold Door Market
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
Revolving Doors Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
India Decorative Laminates Market
Homecare and Decor
Mattress and Mattress Component Market
Homecare and Decor
United States Wall Covering and Wall Decor Market
Homecare and Decor
Rift Sawn Lumber Market