
 United States Wall Covering and Wall Decor Market | 2026-2036
United States Wall Covering and Wall Decor Market Size, Share, and Industry Trends Forecast 2026-2036
United States Wall Covering and Wall Decor Market Analytics
The EPA's Safer Choice program is pivoting procurement criteria across institutional and commercial interiors toward low-emission wall covering substrates. Sherwin-Williams Company leverages its captive distribution network to sustain specification pull-through with national contractors. Brewster Home Fashions anchors the mid-market wallpaper segment through licensed brand portfolios and digital print capacity.
Wall covering and wall decor encompasses surface treatments and ornamental elements applied to interior vertical planes, including printed paper and vinyl substrates laminated to woven backings, typically installed with adhesive systems rated for specific substrate porosity and humidity exposure. The category serves both protective and aesthetic functions in built environments, managing abrasion resistance while enabling spatial branding and residential personalization. Wallpaper and wall art command the largest product type positions, though wall stickers represent the fastest-expanding format among renter demographics and short-lease commercial spaces. PVC and fabric materials split the specification market, with fabric gaining share in hospitality applications where acoustic performance and tactile quality justify premium positioning.
The EPA regulates volatile organic compound emissions through 40 CFR Part 59 architectural coatings standards, while OSHA governs installer exposure to adhesive solvents through permissible exposure limits in commercial application settings. California Air Resources Board (CARB) Phase 2 formaldehyde standards further constrain composite wood substrate usage in wall panel systems, pushing manufacturers toward certified recycled content and bio-based binders. Stakeholders must monitor evolving state-level chemical disclosure requirements and building code amendments that will determine which material platforms retain specification access across the country's fragmented regulatory landscape.
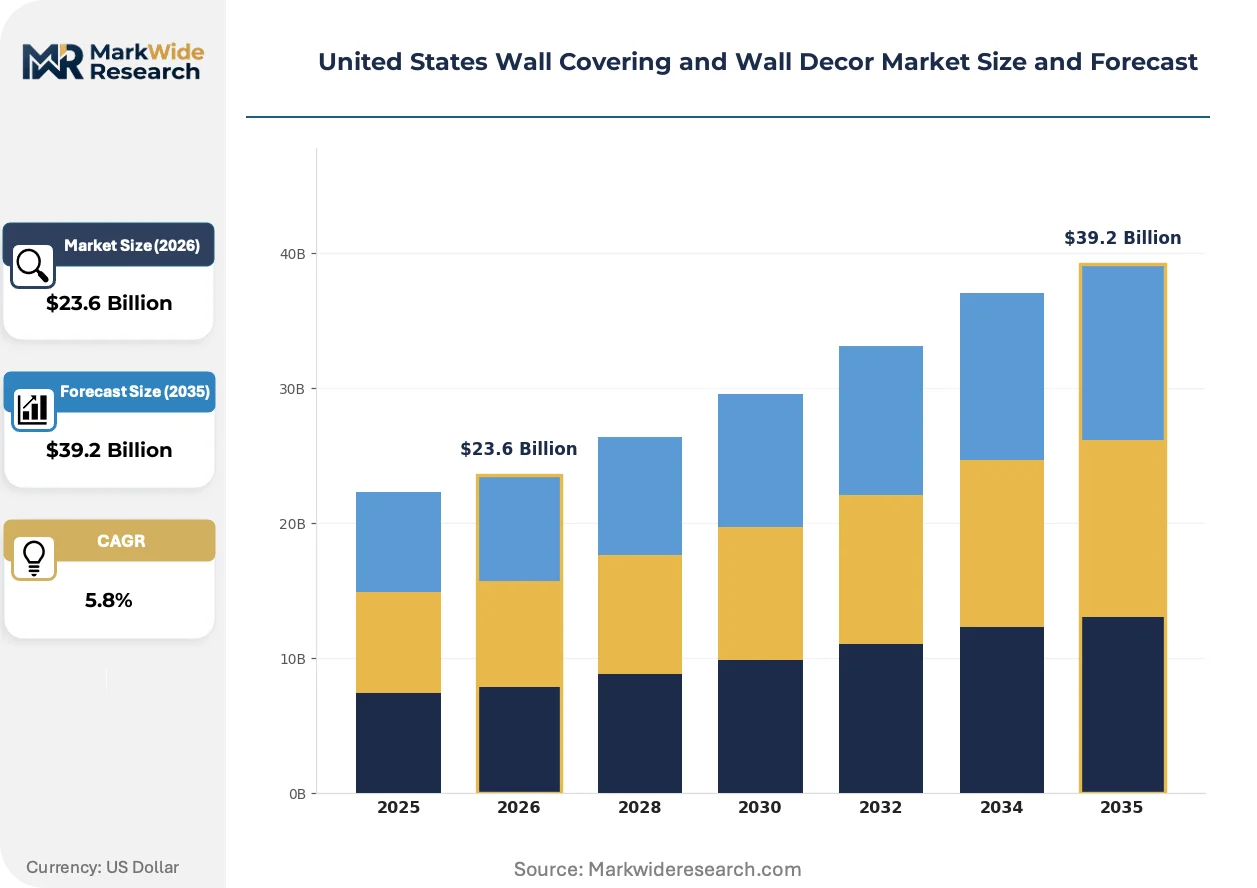
Market Dynamics
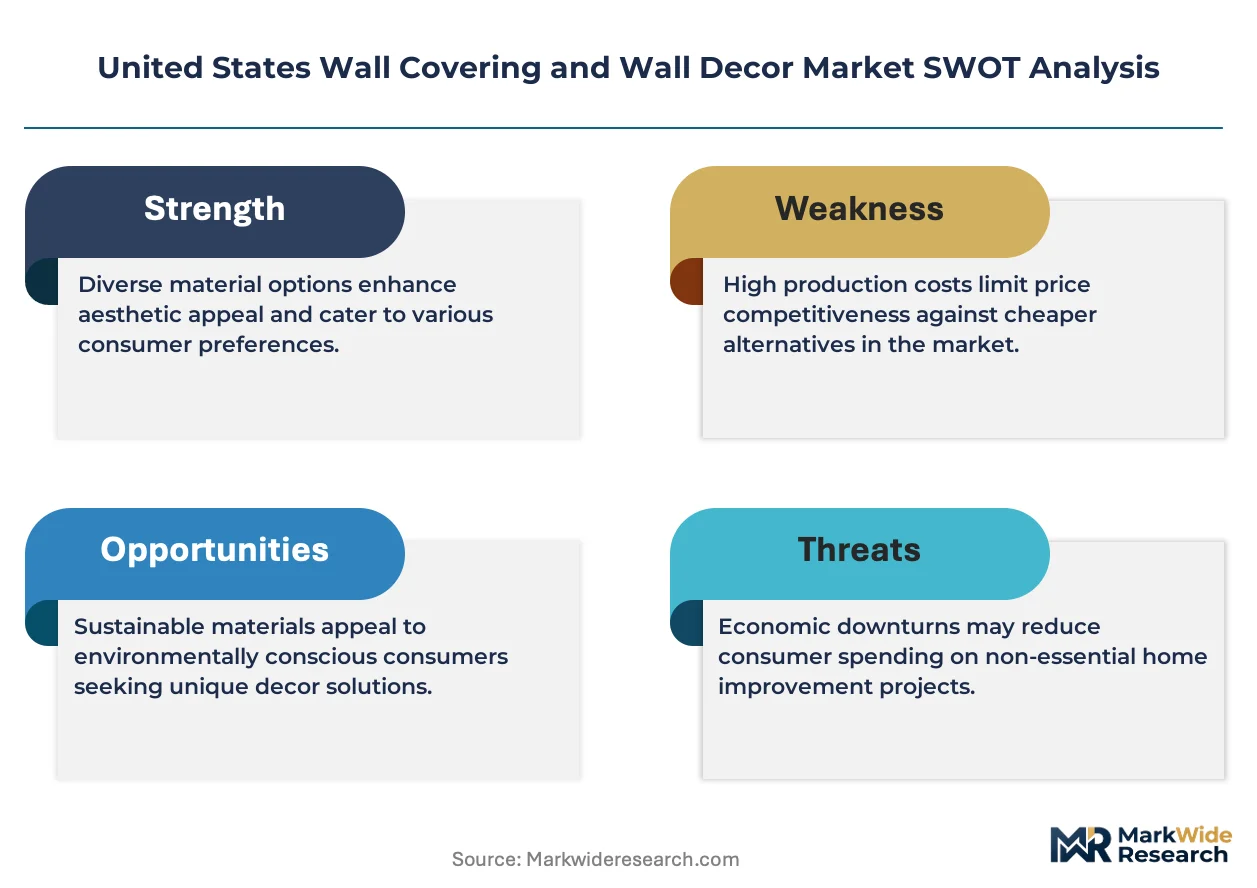
California's Title 24 energy standards and EPA Safer Choice procurement criteria are compressing specification windows for conventional vinyl substrates while accelerating bio-based material development across residential and commercial channels.
Growth Catalysts
- Residential renovation cycles:Sun Belt states including Texas and Florida sustain elevated interior refresh activity as housing stock ages and remote work persists.
- EPA Safer Choice program:Federal procurement criteria now mandate low-VOC wall covering substrates in institutional and commercial interiors, redirecting specification flows.
- Digital print capacity:On-demand manufacturing enables mass customization at mid-market price points, shortening lead times for licensed and bespoke designs.
Market Restraints
- Petrochemical input volatility:PVC resin and plasticizer costs fluctuate with crude oil derivatives, compressing margin visibility for vinyl substrate producers.
- CARB Phase 2 compliance:California formaldehyde standards constrain composite wood substrate usage in wall panel systems, requiring certified recycled content transitions.
- Adhesive solvent exposure:OSHA permissible exposure limits govern installer workplace conditions, adding compliance overhead to commercial application crews.
Strategic Opportunities
- Acoustic fabric panels:Hospitality specifications increasingly prioritize tactile quality and sound absorption, opening premium positioning above standard vinyl.
- Renter demographics:Wall stickers and removable substrates address short-lease commercial spaces and apartment dwellers seeking non-permanent personalization.
- State-level chemical disclosure:Fragmented building code amendments create first-mover advantage for manufacturers with certified transparency protocols.
Industry Challenges
- Installer certification timelines:Commercial crews must document solvent handling training under OSHA standards, constraining workforce scalability.
- Legacy adhesive compatibility:New low-VOC substrates often require reformulated application systems, complicating retrofit specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Wall Covering and Wall Decor Market |
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $39.2 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wallpaper, Wall Art, Mirrors, Wall Stickers Material: PVC, Fabric, Metal, Wood Application: Residential, Commercial, Institutional, Hospitality Design Style: Modern, Vintage, Rustic, Abstract |
| Companies Covered | Brewster Home Fashions, Crossville Inc., Sherwin-Williams Company, Wallquest Inc., Len-Tex Corporation, York Wallcoverings Inc., Benjamin Moore & Co., Maya Romanoff Corporation, F. Schumacher & Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Wall Covering and Wall Decor Market Evolving Landscape
Material science advances and regulatory disclosure requirements are converging to reshape substrate selection criteria across residential and commercial specification channels.
Non-woven fabric backings are expanding into premium residential and hospitality segments where acoustic performance and tactile quality justify cost premiums above traditional paper and vinyl constructions. Boutique hotel chains and high-end multifamily developers specify these materials for feature walls and public areas. The technology is expanding into specification territory previously dominated by solid vinyl, compressing the addressable market for conventional substrates in performance-sensitive applications.
EPA 40 CFR Part 59 architectural coatings standards enforce volatile organic compound emission ceilings on adhesive systems and surface treatments used in commercial interiors. Manufacturers must reformulate product lines to maintain specification access in federally funded projects. The institutional segment responds fastest, with K-12 and healthcare facilities now requiring third-party emission certifications as standard bid prerequisites.
Direct-to-consumer digital sampling platforms are compressing traditional distributor showroom models for residential wallpaper selection. Homeowners order peel-and-stick swatches online, bypassing brick-and-mortar channels for initial material evaluation. This pattern concentrates in coastal metropolitan markets where renovation activity intersects with e-commerce penetration rates.
United States Wall Covering and Wall Decor Market Segmentation
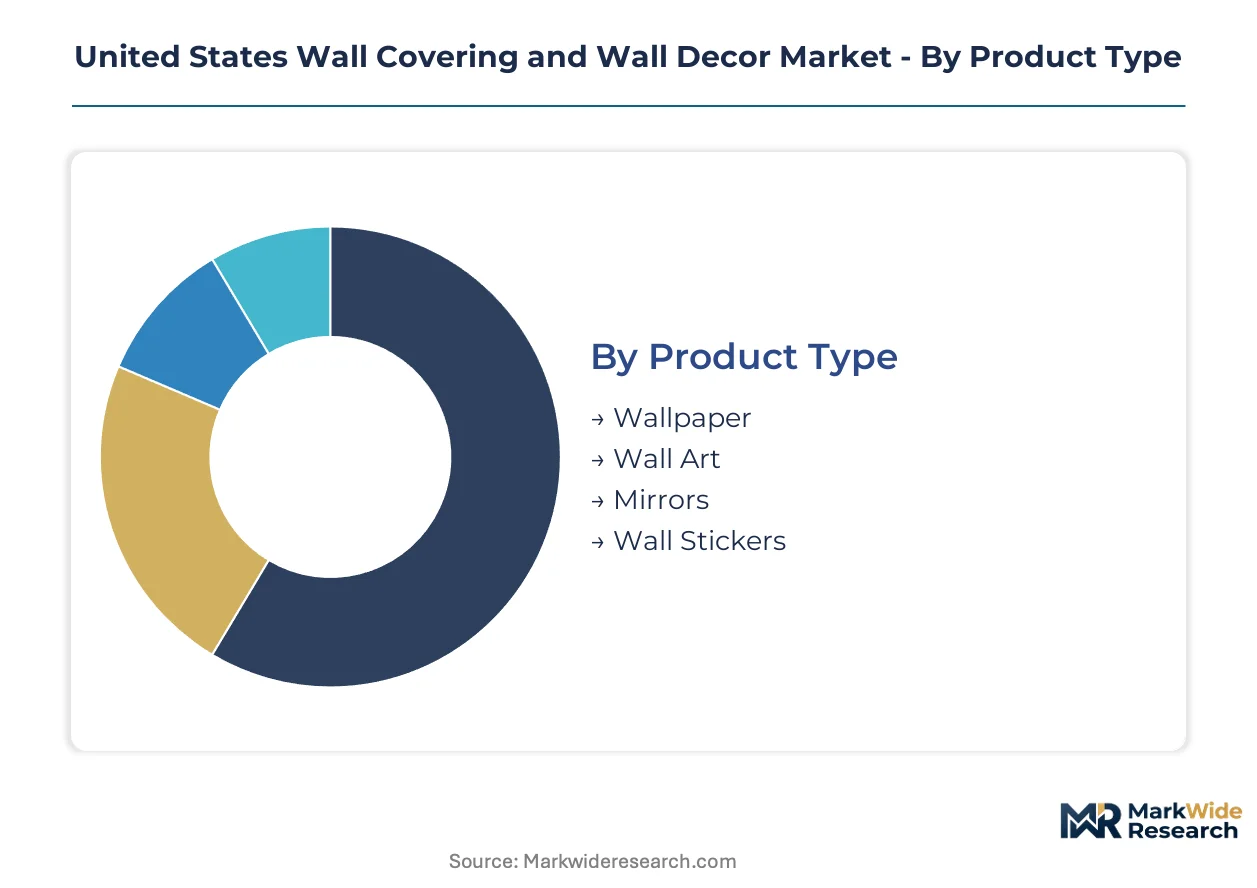
Segmentation in the United States wall covering and wall decor market reveals distinct procurement patterns across material specifications, installation permanence, and end-use durability requirements. Each dimension carries different margin profiles and regulatory exposure, shaping manufacturer portfolio priorities.
Product Type:
Volume concentrates in traditional substrates, while premium expansion concentrates in removable and customizable formats.
- Wallpaper:Printed paper and vinyl substrates laminated to woven backings serve permanent residential installations and commercial rebranding cycles. Sun Belt states including Texas and Florida sustain elevated refresh activity as housing stock ages and remote work persists.
- Wall Art:Framed and canvas-mounted decorative pieces command premium positioning in residential feature walls and hospitality public areas. Boutique hotel chains and high-end multifamily developers specify these for spatial branding where tactile quality justifies cost premiums above standard vinyl constructions.
- Mirrors:Functional and ornamental reflective surfaces address spatial expansion and lighting enhancement in residential and commercial interiors.
- Wall Stickers:Removable adhesive substrates target renter demographics and short-lease commercial spaces seeking non-permanent personalization. This format is expanding most quickly among apartment dwellers and temporary retail installations.
Today's leader: Wallpaper. Tomorrow's challenger: Wall Stickers.
Material:
Petrochemical-based substrates dominate specification volume, though bio-based alternatives gain share under tightening emission standards.
- PVC:Polyvinyl chloride resin provides abrasion resistance and humidity tolerance for high-traffic commercial corridors and healthcare facilities. EPA 40 CFR Part 59 architectural coatings standards enforce volatile organic compound emission ceilings, pushing manufacturers toward reformulated adhesive systems.
- Fabric:Non-woven and woven textile backings deliver acoustic performance and tactile quality for hospitality feature walls and premium residential applications. California Air Resources Board Phase 2 formaldehyde standards constrain composite wood substrate usage, accelerating certified recycled content transitions.
- Metal:Aluminum and steel panel systems address industrial aesthetic specifications and durability requirements in commercial and institutional settings.
- Wood:Solid and engineered timber substrates serve rustic design specifications and biophilic interior strategies in residential and hospitality segments.
Current specification dominance: PVC. Emerging pressure point: Fabric.
Application:
Residential renovation cycles anchor volume, while institutional procurement pivots fastest under federal emission mandates.
- Residential:Owner-occupied and rental property interiors drive wallpaper and wall art adoption through personalization and property value enhancement. Sun Belt housing markets sustain elevated interior refresh activity.
- Commercial:Office and retail rebranding cycles demand durable substrates with shorter installation windows and minimal business disruption.
- Institutional:K-12 and healthcare facilities now require third-party emission certifications as standard bid prerequisites, responding fastest to EPA Safer Choice procurement criteria.
- Hospitality:Boutique hotel chains prioritize acoustic fabric panels and tactile quality for guest experience differentiation, opening premium positioning above standard vinyl.
Largest volume pool: Residential. Fastest specification shift: Institutional.
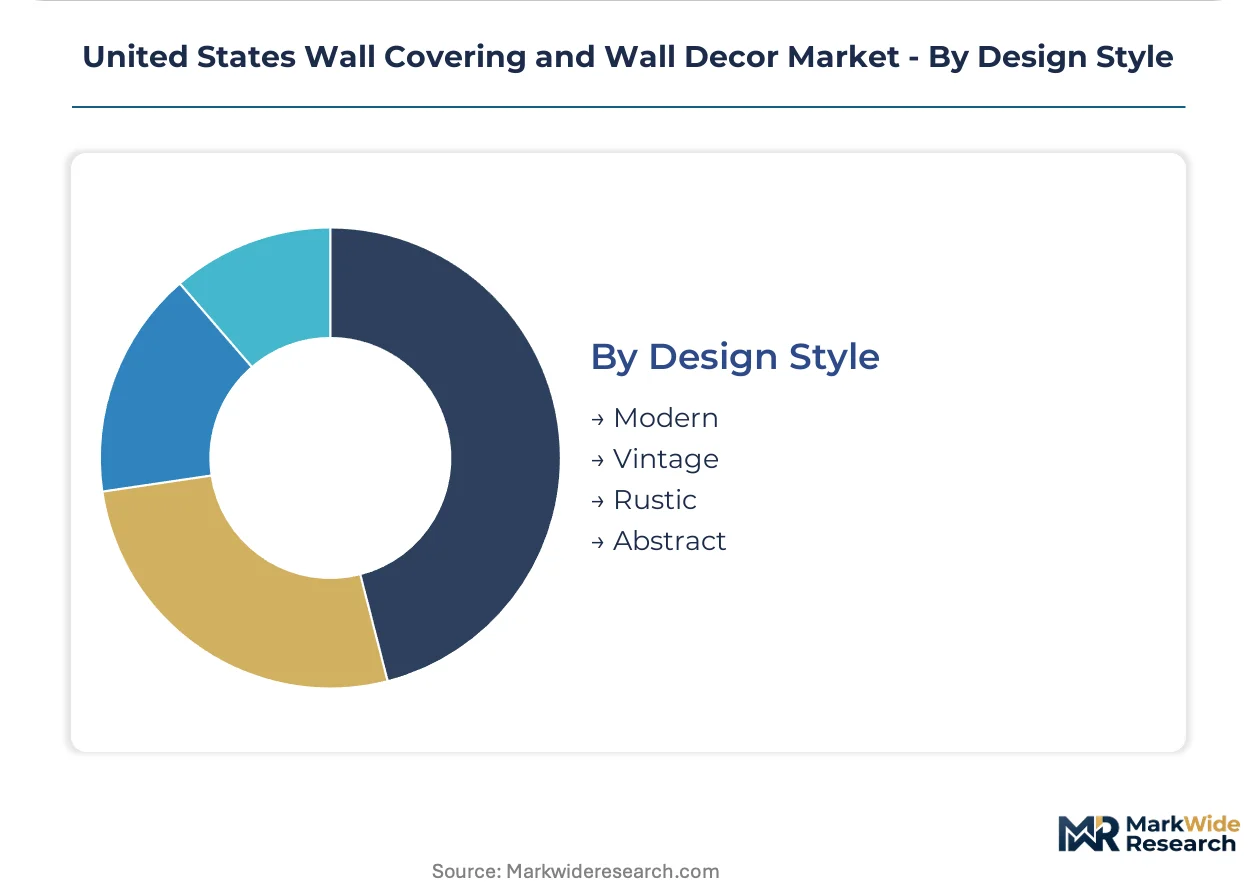
Design Style:
Aesthetic segmentation follows regional construction cycles and demographic migration patterns rather than uniform national trends.
- Modern:Clean lines and minimal ornamentation align with coastal metropolitan renovation activity and e-commerce-driven sampling platforms.
- Vintage:Period-appropriate reproductions serve historic preservation districts and heritage hospitality properties.
- Rustic:Natural textures and distressed finishes concentrate in mountain and rural residential markets seeking biophilic connection.
- Abstract:Non-representational patterns and bold color blocking target younger demographics and commercial spaces seeking spatial branding impact.
Current specification breadth: Modern. Steepest expansion trajectory: Abstract.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wall covering manufacturing in the United States traces its industrial roots to 18th-century Philadelphia textile mills and 19th-century New England paper mills, with contemporary production clustering in states with strong construction economies and regulatory innovation.
California
California's Title 24 building energy standards and CARB Phase 2 formaldehyde regulations are compressing specification windows for conventional vinyl substrates. The EPA Safer Choice program reinforces procurement criteria for low-VOC materials in institutional interiors. Los Angeles and San Francisco metropolitan areas anchor premium residential renovation activity and boutique hospitality development.
Texas
Texas sustains elevated interior refresh cycles as housing stock ages and remote work persists across Dallas-Fort Worth, Houston, and Austin metropolitan corridors. State building codes incorporate federal emission standards without additional chemical disclosure requirements. Dallas anchors distribution infrastructure serving Sun Belt construction markets with expedited lead times for commercial rebranding projects.
Florida
Florida's humidity-exposed construction environment drives demand for moisture-resistant substrate specifications in residential and hospitality applications. The state defers to federal OSHA standards for installer exposure limits without supplementary state-level mandates. Miami and Orlando metropolitan areas concentrate hospitality specification activity for feature wall treatments in boutique hotel developments.
New York Metro
The New York metropolitan corridor maintains heritage wallpaper manufacturing capacity alongside contemporary digital print operations serving Northeast residential markets. New York State Department of Environmental Conservation regulations align with federal VOC emission ceilings for architectural coatings. Brooklyn and Queens industrial zones retain specialized fabric backing production for acoustic panel applications.
Midwest
Illinois, Ohio, and Michigan manufacturing bases supply coated paper and vinyl substrates to national distribution networks. State environmental protection agencies enforce federal standards without California-equivalent chemical disclosure mandates. Chicago anchors commercial specification activity for office and healthcare facility interiors requiring institutional-grade durability ratings.
United States Wall Covering and Wall Decor Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification tiers and specification channel access. The vendor base organizes into three concentration clusters: integrated coating and substrate manufacturers with captive distribution, specialized wallpaper fabricators with licensed brand portfolios, and regional panel producers serving institutional bid markets. Two dominant competitive moves are reshaping positioning: backward integration into digital print capacity to capture customization premiums, and certification investments to retain specification access under tightening emission standards.
Among integrated coating specialists, Sherwin-Williams Company anchors premium specification channels through national contractor relationships, while York Wallcoverings Inc. and Brewster Home Fashions occupy positions across mid-market wallpaper segments. These three entities exemplify divergent strategic archetypes—captive distribution infrastructure, licensed brand portfolio depth, and digital manufacturing flexibility—each representing viable competitive positioning within fragmented procurement environments.
| Leading Market Players |
|---|
| Brewster Home Fashions |
| Crossville Inc. |
| Sherwin-Williams Company |
| Wallquest Inc. |
| Len-Tex Corporation |
| York Wallcoverings Inc. |
| Benjamin Moore & Co. |
| Maya Romanoff Corporation |
| F. Schumacher & Co. |
| Others |
Value Network & Pricing Analysis
Captive distribution networks anchor both supply position and pricing power for integrated coating specialists serving national contractor channels. This backward integration into controlled specification access compresses margin leakage while insulating premium-tier positioning from commodity substrate volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and brand portfolio depth. EPA Safer Choice compliance and CARB Phase 2 formaldehyde certification command 15-25% premiums above uncertified alternatives in institutional bid markets. Cost compression in mid-market vinyl substrates is intensifying because petrochemical input volatility erodes producer visibility. Commercial contractors exhibit highest price sensitivity due to project-budget constraints, while hospitality developers prioritize tactile quality over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from national retailers and institutional procurement officers mandate multi-supplier qualification for adhesive systems and substrate backings. Domestic manufacturing concentrates in Ohio, Pennsylvania, and North Carolina textile and paper mill corridors. Raw material flows draw from PVC resin producers along the Gulf Coast, woven textile suppliers in Georgia and South Carolina, and specialty chemical formulators in New Jersey. Tariff exposure on Chinese digital printing equipment creates single-source vulnerability for on-demand manufacturers. Distribution runs through regional building material distributors serving contractor networks and big-box retail channels for residential DIY segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in wall covering and wall decor rests on certified material premiums and digital print efficiency gains compressing customization costs. Bio-based substrate development and low-VOC adhesive transitions open pricing power in federally funded institutional channels.
For Market Incumbents: Deepen captive distribution infrastructure to lock specification access with national contractor networks against emerging digital-native competitors. Invest in CARB Phase 2 and EPA Safer Choice certification portfolios to defend institutional bid eligibility as chemical disclosure requirements fragment state-by-state. Prioritize backward integration into non-woven fabric backing production to capture hospitality premium-tier demand. For New Entrants and Emerging Players: E-commerce sampling platforms offer white-space entry for direct-to-consumer wallpaper brands bypassing traditional showroom channels. Target renter demographics in coastal metropolitan markets with peel-and-stick and removable substrate formats where incumbent presence remains thin. Pursue licensed brand partnerships with entertainment and lifestyle properties to differentiate digital print catalogs. For Investors and Strategic Acquirers: Roll-up economics work for regional panel producers and specialized wallpaper fabricators because specification access depends on certified production assets that scale poorly across fragmented state regulatory regimes. Acquisition targets should demonstrate established institutional bid relationships and compliance infrastructure transferable across geographies. Watch EPA enforcement intensity and state-level chemical disclosure expansion as inflection indicators for certified-content premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | CARB Phase 2 and EPA Safer Choice credentials unlock institutional procurement channels requiring third-party emission verification. |
| Digital Print Capacity Expansion | On-demand manufacturing shortens lead times for licensed designs while capturing customization premiums in mid-market residential segments. |
| Backward Integration into Fabric Backing | In-house non-woven production secures acoustic panel supply for hospitality specifications competing with solid vinyl alternatives. |
| Direct-to-Consumer Channel Launch | Peel-and-stick sampling platforms bypass distributor markups and concentrate margin capture in coastal metropolitan renovation markets. |
| Licensed Brand Portfolio Expansion | Entertainment and lifestyle property partnerships differentiate digital catalogs against commodity pattern competitors in residential channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate market sizing and specification flow dynamics. Primary fieldwork engaged wall covering manufacturers, national contractor procurement officers, hospitality interior designers, building material distributors, and regulatory compliance consultants. Secondary validation drew from EPA 40 CFR Part 59 filings, CARB composite wood certification databases, OSHA permissible exposure limit documentation, and building code amendment tracking across state legislatures. Bottom-up volume estimates from substrate production and adhesive consumption reconciled against top-down construction spending allocations.
Segment-weighting approaches distributed total market value across material type, installation permanence, end-use durability requirements, and geographic construction cycle intensity. The analytical framework modeled wallpaper, wall art, mirrors, and wall stickers as distinct product platforms with divergent margin profiles and regulatory exposure. Fabric, PVC, metal, and wood substrates carried separate input cost trajectories and certification overhead assumptions. CAGRs derived from housing stock aging curves, remote work persistence indicators, and institutional procurement policy shifts. Forecast inputs included Sun Belt migration patterns, boutique hospitality development pipelines, and federal emission standard enforcement trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical price volatility and state-level chemical disclosure fragmentation. Deviation in California regulatory stringency or EPA Safer Choice program expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Wall Art Market
Homecare and Decor
Christmas Tree Market
Homecare and Decor
Saudi Arabia Interior Design Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
Smart Vase Market
Homecare and Decor
Europe Flower Pots and Planters Market
Homecare and Decor
Pillow Cases Market
Homecare and Decor
Fireplace and Stove Market
Homecare and Decor
Flush Door Market
Homecare and Decor
Wall Covering Products Market
Homecare and Decor
Rift Sawn Lumber Market
Homecare and Decor
Europe Decorative Laminates Market
Homecare and Decor
Interior Design Services Market
Homecare and Decor
India Furniture Hardware Market