
 USA and Canada Teak Veneer Sheet Market | 2026-2036
USA and Canada Teak Veneer Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
USA and Canada Teak Veneer Sheet Market Analytics
Grade-A quarter-sawn specification upgrades is unwinding legacy inventory positions across North American distributors. GL Veneer, Inc. leverages its California-based mill network to anchor premium sheet availability for West Coast marine builders. Columbia Forest Products sustains broad coverage of architectural-grade backed teak through its integrated plywood operations. Sauers & Company Veneers specializes in custom flitch-matched sequences for high-end residential interiors.
Teak veneer sheets are thin decorative laminates sliced from Tectona grandis logs, typically ranging from 0.5 mm to 2.0 mm in thickness, bonded to substrates for furniture, yacht interiors, and architectural millwork requiring dimensional stability and aesthetic uniformity. Natural Teak commands the dominant value share among product types due to authentic grain patterns prized in luxury marine applications, while Laminated Teak gains traction among furniture manufacturers seeking cost-consistent alternatives with reduced defect rates. Prefinished Sheets within the Form dimension capture expanding margin pools as cabinet makers and interior designers outsource sanding and sealing steps to reduce in-shop labor and volatile finishing material costs.
The USFWS enforces Lacey Act declaration requirements for imported teak, compelling distributors to maintain chain-of-custody documentation from forest origin through retail sale. EPA formaldehyde emissions standards under TSCA Title VI constrain adhesive formulations used in veneer-backed panel production, favoring suppliers with certified low-emitting resin systems. Health Canada's PMRA oversees treated wood import protocols affecting preservative-coated teak alternatives entering Canadian provinces. Stakeholders must monitor pending CITES appendix revisions and cross-border tariff adjustments that could reroute supply through alternative port-of-entry strategies.
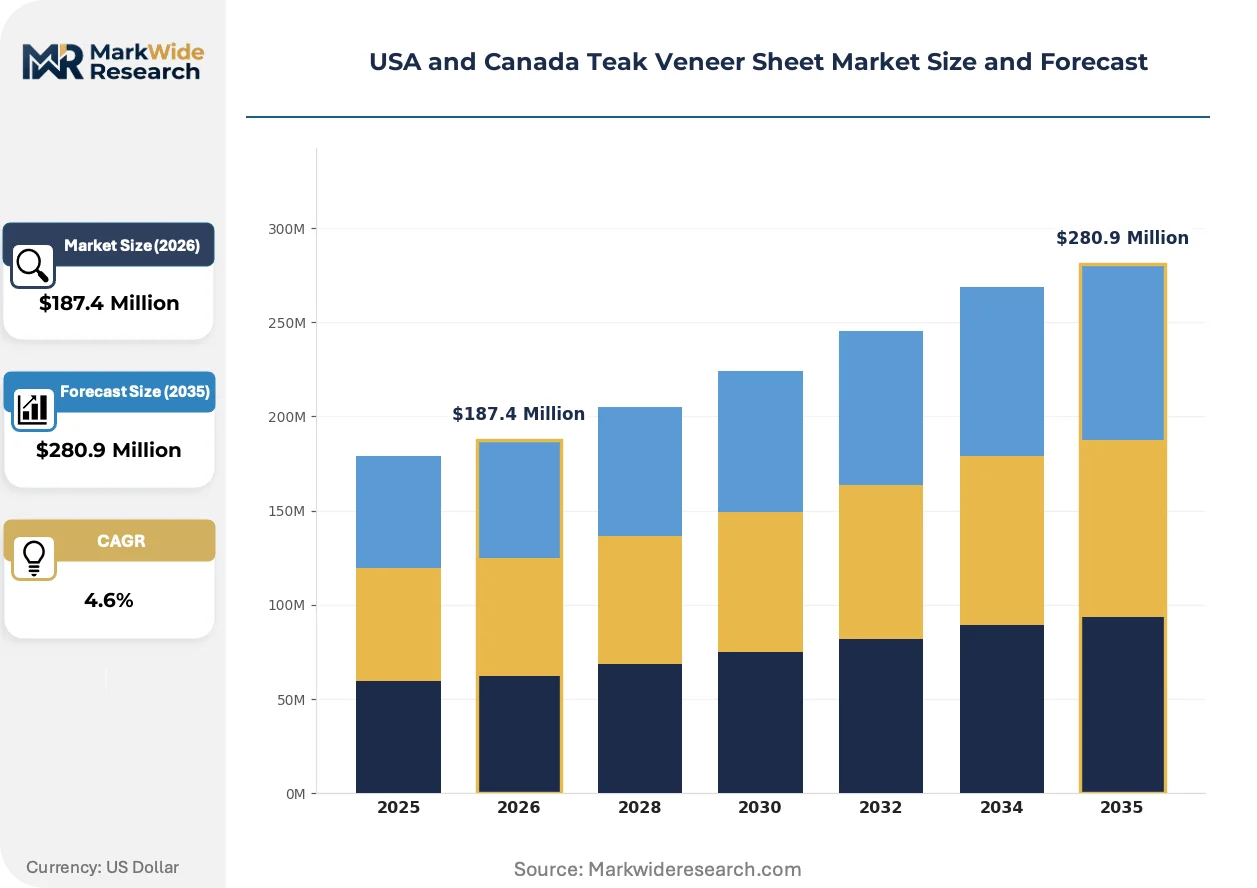
Market Dynamics
Lacey Act enforcement by USFWS and CITES permitting requirements are compressing supply chain documentation timelines, forcing distributors to restructure procurement relationships and inventory holding patterns across both countries.
Growth Catalysts
- Yacht Interior Refit Cycles:Florida and British Columbia marine builders are accelerating specification of premium-grade quarter-sawn sheets for superyacht cabin interiors, pulling forward replacement demand from legacy installations.
- EPA TSCA Title VI Certification:Low-emitting resin systems meeting formaldehyde emissions standards are unlocking specification access in California school and healthcare millwork projects previously closed to conventional adhesives.
- Custom Furniture Studio Expansion:Ontario and Pacific Northwest design-build workshops are scaling flitch-matched sequence orders for residential commissions requiring grain continuity across built-in cabinetry.
Market Restraints
- Myanmar Supply Concentration:Reliance on Burmese log origins for authentic Tectona grandis creates exposure to CITES appendix revision and trade suspension risk.
- Documentation Compliance Burden:Chain-of-custody requirements from forest origin through retail sale impose administrative overhead that smaller distributors struggle to absorb.
- Laminated Teak Substitution:Cost-consistent alternatives with reduced defect rates are capturing specification share in mid-market furniture manufacturing segments.
Strategic Opportunities
- Prefinished Sheet Outsourcing:California cabinet makers are delegating sanding and sealing steps to specialized mills, creating margin capture for suppliers with in-house finishing capacity.
- Health Canada PMRA Pathway:Treated wood import protocol clarity for preservative-coated alternatives opens provincial specification in Quebec and Alberta exterior applications.
- Digital Flitch Mapping:Barcode-tracked veneer bundles matched to architectural renderings are reducing waste and rejection rates for high-end residential projects.
Industry Challenges
- Grader Certification Pipeline:Shortage of trained personnel capable of distinguishing quarter-sawn from flat-sawn grain orientation at volume is constraining quality control throughput.
- Cross-Border Tariff Reconfiguration:Pending duty adjustments on Southeast Asian veneer imports are forcing distributors to model alternative port-of-entry strategies through Vancouver versus Long Beach.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA and Canada Teak Veneer Sheet Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Teak, Laminated Teak, Backed Teak, Veneered Panels End User: Furniture Manufacturers, Interior Designers, Cabinet Makers, Residential Users Form: Raw Sheets, Prefinished Sheets, Cut-to-Size, Custom Designs Grade: First Grade, Second Grade, Commercial Grade, Mill Run |
| Companies Covered | GL Veneer, Inc., Oakwood Veneer Company, FormWood Industries, Lenderink Technologies Inc., BC Veneer Products Ltd., Precision Veneer Products Ltd., Timber Products Company, Columbia Forest Products, Sauers & Company Veneers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA and Canada Teak Veneer Sheet Market Evolving Landscape
Digital documentation systems and automated finishing workflows are compressing lead times while regulatory pressure on forest provenance is elevating supply chain transparency to a competitive differentiator.
Ultrathin 0.5 mm veneer slicing technology is decomposing traditional thickness specifications across marine interior applications. Florida yacht builders are adopting these sheets for curved surface applications previously requiring solid lumber bending. The structural consequence is compressing substrate material costs while demanding tighter moisture-content control through the bonding process.
USFWS Lacey Act declaration requirements are tightening field-level enforcement through enhanced sampling at port-of-entry facilities. Distributors now face shipment detention risk for incomplete chain-of-custody documentation, compelling investment in blockchain-tracked provenance systems. California and Florida importers are most exposed given their volume concentration and inspection frequency.
Design-specifier direct purchasing is fragmenting traditional distributor relationships in high-end residential segments. Ontario and British Columbia interior designers are sourcing flitch-matched sequences directly from mill operators, bypassing wholesale intermediaries. This pattern is most visible in Vancouver and Toronto metropolitan markets where studio concentration supports direct relationship economics.
USA and Canada Teak Veneer Sheet Market Segmentation
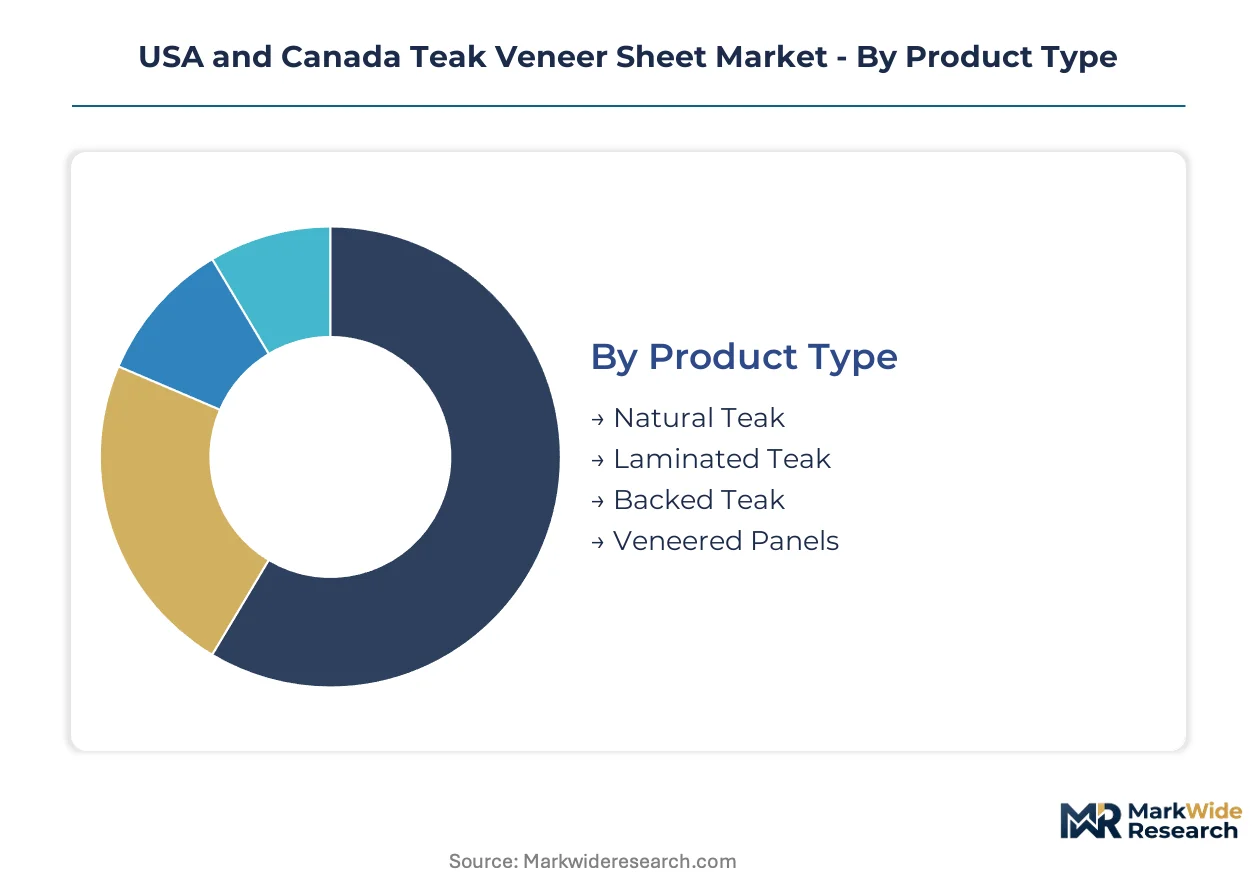
Teak veneer sheet procurement channels diverge sharply by segment, with marine builders sourcing through specialized distributors while furniture manufacturers leverage direct mill relationships. Understanding these pathway distinctions enables suppliers to align inventory positioning with actual purchase behavior rather than assumed category demand.
Product Type:
Channel concentration varies dramatically across product types, with premium grades flowing through marine-specialized distributors and cost-optimized alternatives reaching furniture manufacturers via direct import arrangements.
- Natural Teak:Authentic Tectona grandis laminates sliced from solid logs retain variable grain patterns and coloration prized for superyacht interiors. Florida and British Columbia marine builders specify quarter-sawn natural teak for cabin installations, though CITES documentation requirements constrain supply fluidity and extend procurement timelines.
- Laminated Teak:Engineered constructions bond multiple thin veneer layers to create uniform appearance with minimized defect rates. California furniture manufacturers are shifting specification toward laminated alternatives as labor costs for defect sorting and matching escalate in high-wage manufacturing environments.
- Backed Teak:Veneer sheets reinforced with fabric or paper substrates enhance dimensional stability during adhesive bonding and finishing operations. Cabinet makers across Ontario specify backed teak for curved architectural millwork where substrate flexibility prevents surface cracking.
- Veneered Panels:Pre-assembled substrate-and-veneer composites reduce field labor for large-surface applications. Pacific Northwest interior designers specify these for built-in residential installations where site conditions complicate on-site bonding.
Natural Teak dominates installed base. Laminated Teak is where expansion concentrates.
End User:
Customer scale and specification authority reshape pricing power across end-user categories, with institutional purchasers commanding volume discounts unavailable to fragmented residential buyers.
- Furniture Manufacturers:High-volume producers of case goods and seating frames source teak veneer through long-term supply agreements with Southeast Asian mill operators. California and North Carolina operations prioritize Laminated Teak for consistency across production runs exceeding 500 units.
- Interior Designers:Specification professionals in Vancouver and Toronto metropolitan markets increasingly source flitch-matched sequences directly from mill operators, bypassing wholesale intermediaries to secure grain continuity across commissioned residential projects.
- Cabinet Makers:Custom shop operations in Pacific Northwest and Ontario combine Prefinished Sheets with in-house fabrication to reduce finishing labor exposure to volatile solvent and coating costs.
- Residential Users:Small-scale purchasers acquiring material for single-room installations or repair projects typically access inventory through retail lumber yards with limited grade selection and extended lead times.
Furniture Manufacturers anchor volume throughput. Interior Designers are climbing the fastest in margin contribution per square foot.
Form:
Processing stage at point of sale determines labor allocation between supplier and purchaser, with outsourcing trends favoring forms that shift sanding and sealing burden upstream.
- Raw Sheets:Unfinished veneer requiring complete surface preparation and coating application. Marine builders in Florida prefer raw sheets for curved yacht interiors where custom finishing sequences accommodate complex geometries and moisture-exposure protocols.
- Prefinished Sheets:Factory-sanded and sealed products ready for substrate bonding. California cabinet makers delegate these steps to specialized mills, capturing margin through reduced in-shop labor and elimination of volatile finishing material inventory.
- Cut-to-Size:Dimensioned veneer pieces optimized for specific component requirements. Ontario furniture manufacturers specify cut-to-size for standardized drawer fronts and door panels, minimizing waste and handling damage.
- Custom Designs:Bespoke sequences including flitch-matched sets and book-matched pairs for architectural statement pieces. British Columbia and Toronto design studios commission these directly from mill operators with digital flitch mapping capabilities.
Raw Sheets retain the largest installed base. Prefinished Sheets represent the steepest expansion trajectory as labor costs climb.
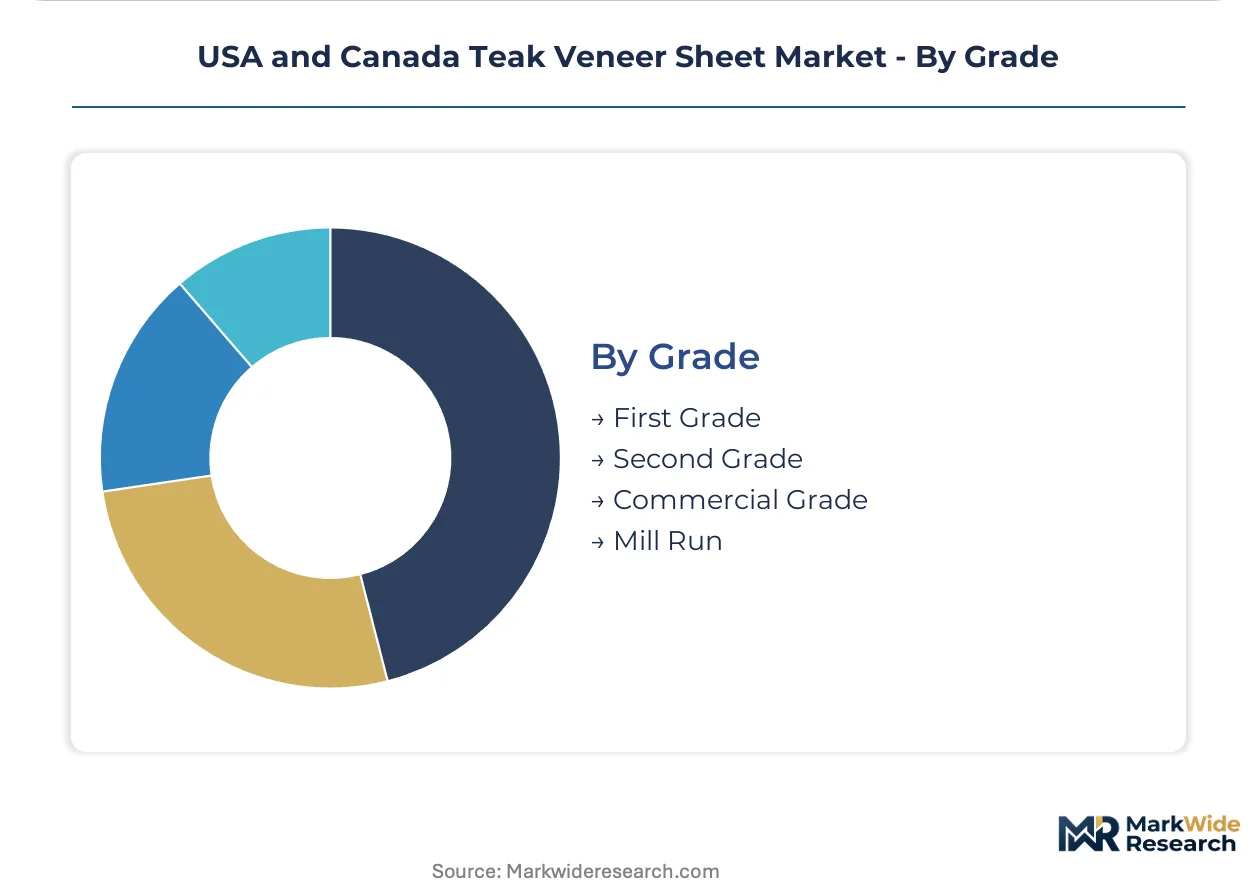
Grade:
Quality tiering aligns with end-use durability requirements and aesthetic exposure, with premium grades commanding substantial markups for visible surfaces while utility grades serve structural or concealed applications.
- First Grade:Premium quarter-sawn material with uniform color, minimal defects, and consistent grain orientation. Superyacht interior specifications in Florida and British Columbia require First Grade for cabin surfaces visible to owners and charter guests.
- Second Grade:Moderate defect allowance with color variation acceptable for painted or stained finishes. Residential furniture manufacturers in California specify Second Grade for frame components and interior panels where surface perfection is non-critical.
- Commercial Grade:Functional material with sound knots and mineral streaks permitted. Hospitality and multi-family residential developers in Ontario select Commercial Grade for high-traffic installations where replacement cycles compress amortization periods.
- Mill Run:Unsorted production output combining variable quality levels at discounted pricing. Small cabinet shops and repair contractors in Pacific Northwest purchase Mill Run for non-matching replacement panels and experimental prototypes.
First Grade dominates value capture in marine applications. Second Grade is gaining share fastest in mid-market furniture manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency on Southeast Asian log origins shapes regional procurement patterns across both countries. Distributors in Vancouver and Long Beach compete for containerized veneer shipments while navigating divergent customs enforcement protocols. Cross-border tariff differentials are rerouting some Canadian demand through US Gulf ports.
United States
Florida yacht builders and California furniture manufacturers anchor domestic consumption of premium-grade sheets. EPA TSCA Title VI certification requirements constrain adhesive formulations used in veneer-backed panel production, favoring suppliers with certified low-emitting resin systems. Miami-Dade and Fort Lauderdale marine clusters are accelerating specification of quarter-sawn material for superyacht refit cycles.
Canada
British Columbia interior designers and Ontario cabinet makers drive specification of flitch-matched sequences for residential commissions. Health Canada's PMRA oversees treated wood import protocols affecting preservative-coated teak alternatives entering Quebec and Alberta exterior applications. Vancouver metropolitan studios increasingly source directly from mill operators, bypassing wholesale intermediaries.
California
Custom furniture studios and architectural millwork shops concentrate demand for prefinished sheets to reduce in-shop labor exposure. CARB Phase II compliance requirements exceed federal formaldehyde emissions standards, creating a dual-certification burden for suppliers. Los Angeles and San Francisco design-build workshops are scaling digital flitch mapping for grain continuity across built-in cabinetry.
Florida
Marine interior refit specialists command premium pricing for Grade-A quarter-sawn specifications visible to yacht owners and charter guests. USFWS Lacey Act enforcement through Miami and Jacksonville port-of-entry facilities compels blockchain-tracked provenance documentation. Fort Lauderdale and Palm Beach County marine builders are adopting ultrathin 0.5 mm sheets for curved surface applications.
British Columbia
Pacific Northwest yacht interior manufacturers and Vancouver residential designers overlap in procurement of custom-matched veneer sequences. Provincial environmental regulations on wood waste disposal affect offcut recovery economics for cabinet shops. Victoria and Vancouver Island marine clusters are expanding specification of backed teak for dimensional stability in humid coastal installations.
USA and Canada Teak Veneer Sheet Market Competitive Landscape
Listed leaders compete with private specialists across documentation compliance and finishing capacity dimensions. The vendor base stratifies between integrated plywood operators, regional veneer distributors, and custom sequence specialists serving design-direct procurement. Three archetypes dominate: California-based mill networks anchoring West Coast marine supply, integrated forest products companies with captive resin certification, and boutique flitch-matched sequence providers. Competitive moves concentrate on prefinished sheet outsourcing partnerships and digital provenance system deployment.
Among California-based specialists, GL Veneer, Inc. and Sauers & Company Veneers exemplify divergent positioning strategies. Columbia Forest Products occupies a position bridging architectural-grade volume supply with certified low-emitting adhesive systems. These three entities represent the spectrum from boutique sequence matching to integrated panel production, anchoring competitive dynamics across premium and mid-market specification tiers.
| Leading Market Players |
|---|
| GL Veneer, Inc. |
| Oakwood Veneer Company |
| FormWood Industries |
| Lenderink Technologies Inc. |
| BC Veneer Products Ltd. |
| Precision Veneer Products Ltd. |
| Timber Products Company |
| Columbia Forest Products |
| Sauers & Company Veneers |
| Others |
Value Network & Pricing Analysis
EPA TSCA Title VI certification gates both supply qualification and price differentiation simultaneously, separating certified low-emitting resin systems from conventional alternatives while commanding premium positioning in California school and healthcare millwork projects.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with First Grade quarter-sawn material commanding substantial markups for superyacht interiors while Second Grade captures mid-market furniture manufacturing. Price differentiation rests on certification grade and volume scale, with CARB Phase II dual-certification burden adding compliance premiums. Cost compression in laminated alternatives is intensifying because California furniture manufacturers prioritize defect-rate consistency over authentic grain patterns. Small cabinet shops exhibit highest price sensitivity, while Florida marine builders demonstrate lowest sensitivity for visible-cabin specifications.
Supply Chain Analysis
Myanmar log origins underwrite raw material concentration for authentic Tectona grandis, with secondary sourcing from plantation-grown Latin American and African origins expanding as CITES documentation timelines compress. Supply draws from Burmese forest concessions, Southeast Asian mill operators, and West Coast veneer distributors. Single-source vulnerability runs through Myanmar supply concentration given pending CITES appendix revision risk. Distribution runs through specialized marine distributors in Florida and direct mill relationships for Ontario furniture manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trained grader certification pipeline constrains quality control throughput, creating a bottleneck where qualified personnel capable of distinguishing quarter-sawn from flat-sawn grain orientation at volume determine competitive capacity.
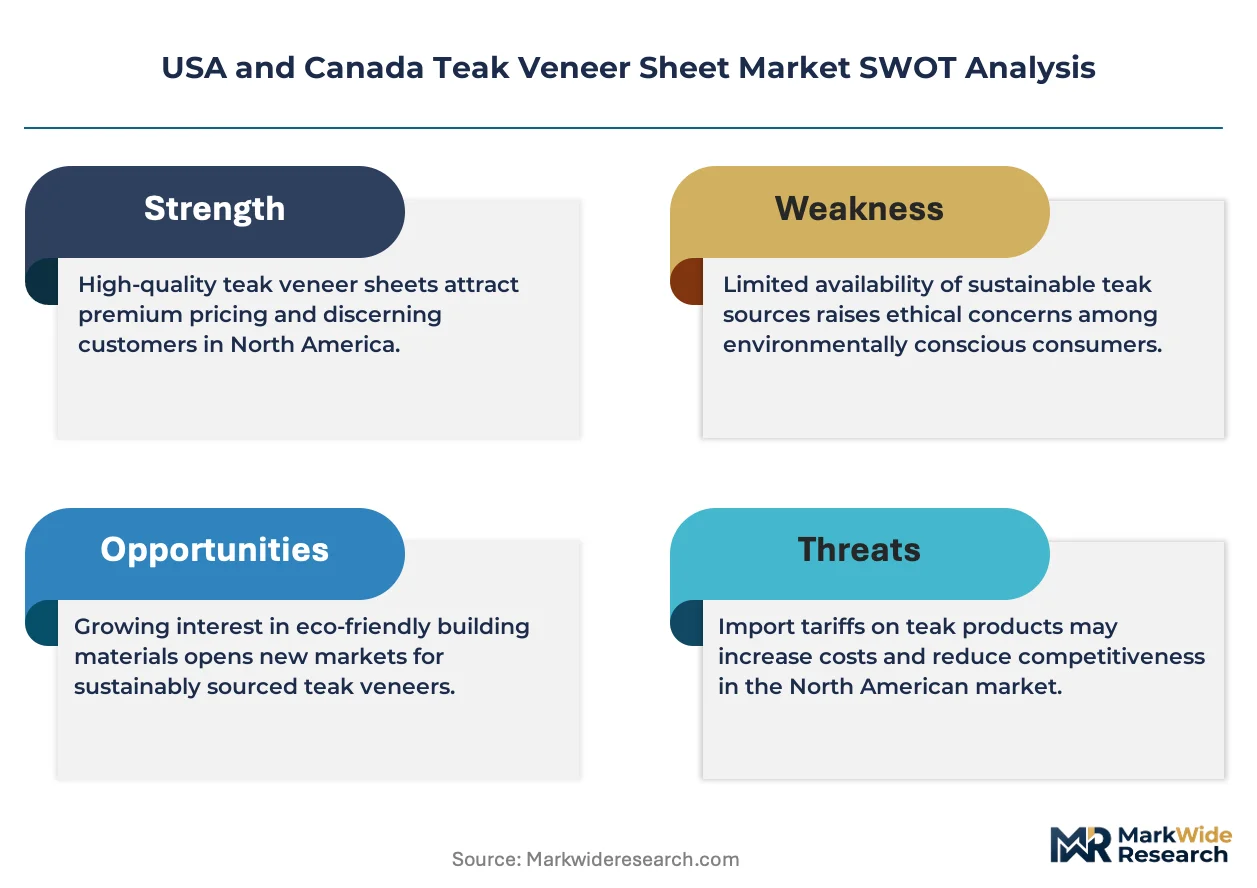
For Market Incumbents: Secure blockchain-tracked provenance documentation systems to defend against USFWS Lacey Act shipment detention risk, while expanding in-house prefinished sheet capacity to capture margin from California cabinet makers outsourcing sanding and sealing steps. Vertical integration into captive resin certification locks in EPA TSCA Title VI compliance advantage against adhesive formulation constraints. For New Entrants and Emerging Players: Digital flitch mapping services represent a service-layer gap where incumbents under-serve Vancouver and Toronto interior designers seeking grain continuity across built-in cabinetry. Target direct-to-designer procurement channels in Pacific Northwest metropolitan markets, leveraging barcode-tracked veneer bundles matched to architectural renderings as the go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across prefinished sheet manufacturing as specialized mills consolidate finishing capacity. Long-term viability favors acquisition targets with certified low-emitting resin systems and established Health Canada PMRA import protocol clarity. Watch CITES appendix revision timing as the signal indicating supply rerouting and valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Certification | EPA TSCA Title VI compliance locks in specification access to California institutional millwork projects. |
| Prefinished Sheet Capacity Expansion | California cabinet makers delegate finishing steps to reduce in-shop labor and volatile coating inventory costs. |
| Digital Flitch Mapping Deployment | Barcode-tracked veneer bundles matched to architectural renderings reduce waste and rejection rates for high-end residential projects. |
| Blockchain Provenance System Investment | USFWS Lacey Act enforcement through Miami and Jacksonville ports compels chain-of-custody documentation from forest origin. |
| Direct Designer Channel Development | Vancouver and Toronto interior designers increasingly bypass wholesale intermediaries to source flitch-matched sequences. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with marine interior procurement managers, custom furniture studio owners, veneer mill operators, and architectural millwork contractors; and secondary validation through USFWS Lacey Act enforcement records, EPA TSCA Title VI certification databases, CARB regulatory filings, and customs trade documentation. Bottom-up shipment data triangulated against top-down consumption estimates across product type, end user, form, and grade segmentation dimensions.
Across the analysis window, the forecasting framework modeled volume and value outputs through product type, end user category, processing form, and quality grade tier dimensions. CAGRs were derived from trend extrapolation of yacht refit cycle timing, furniture manufacturing labor cost trajectories, and regulatory compliance adoption curves. Industry-specific inputs included CITES permitting timeline projections and CARB Phase II enforcement intensity assumptions.
Forecasts assume regulatory continuity in EPA TSCA Title VI and USFWS Lacey Act regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include CITES appendix revisions affecting Myanmar log access, cross-border tariff reconfigurations rerouting supply through alternative ports, and grader certification pipeline constraints limiting quality control throughput. Practitioners should keep alternative scenarios live as CITES deliberation timelines and tariff adjustment announcements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Furniture & Cabinet Hardware Market
Furniture
Italy Home Furniture Market
Furniture
Ergonomic Chair for Children Market
Furniture
North America Free Standing Electrical Height-Adjustable Tables Market
Furniture
HORECA Furniture Market
Furniture
Global Furniture Fittings Market
Furniture
School Furniture Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
India Upholstered Furniture Market
Furniture
North America Smart Furniture Market
Furniture
UAE Luxury Furniture Market
Furniture
North America School Furniture Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
Furniture and Home Furnishing Store Market
Furniture
Spain Furniture Market
Furniture
Luxury RTA (Ready-To-Assemble) Furniture Market