
 Global Automotive Motor Market | 2026-2036
Global Automotive Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Motor Market Analysis
High-efficiency permanent magnet tiers is rotating demand toward premium motor architectures with superior power density and thermal performance. Bosch leverages in-house semiconductor integration to control magnet supply chains and reduce rare earth exposure. Nidec anchors Asia-Pacific production scale through dedicated EV motor facilities in China and Vietnam. Continental competes on modular platform designs that span hybrid and full-electric applications.
Automotive motors are electromechanical devices that convert electrical energy into mechanical torque through electromagnetic induction, typically operating at voltages from 48V to 800V depending on vehicle electrification level. Their primary purpose is to deliver propulsion, steering assistance, thermal management, and auxiliary functions across passenger and commercial vehicle platforms. Brushless technology leads volume share due to superior efficiency and reduced maintenance requirements, while switched reluctance designs are gaining traction in cost-sensitive commercial vehicle segments where magnet-free architectures eliminate supply risk. AC motors dominate OEM supply agreements for high-voltage traction applications, whereas DC architectures persist in aftermarket retrofits and legacy auxiliary systems.
FDA, EPA, and NHTSA frameworks in the United States enforce emissions benchmarks and safety certifications that directly determine motor efficiency thresholds and thermal runaway protocols. EMA and REACH in Europe mandate substance restrictions and end-of-life recyclability standards that reshape magnet composition and supplier qualification. Stakeholders must monitor regulatory divergence between jurisdictions to avoid redundant certification cycles and stranded tooling investments.
Market Dynamics
Powertrain electrification is compressing motor architecture cycles as OEMs pivot from 12V auxiliary systems to 800V traction platforms, forcing suppliers to retool for dual-voltage production lines within single facilities.
Growth Catalysts
- China MIIT dual carbon mandates:Domestic OEM procurement quotas for high-efficiency motors are accelerating local content requirements and expanding foundry capacity in Jiangsu and Zhejiang provinces.
- Commercial vehicle electrification:Last-mile delivery fleets in Germany and the United States are converting diesel auxiliary power units to electric thermal management motors.
- Silicon carbide inverter pairing:Wide-bandgap semiconductor integration enables higher switching frequencies that unlock permanent magnet motor efficiency gains at reduced thermal loads.
Market Restraints
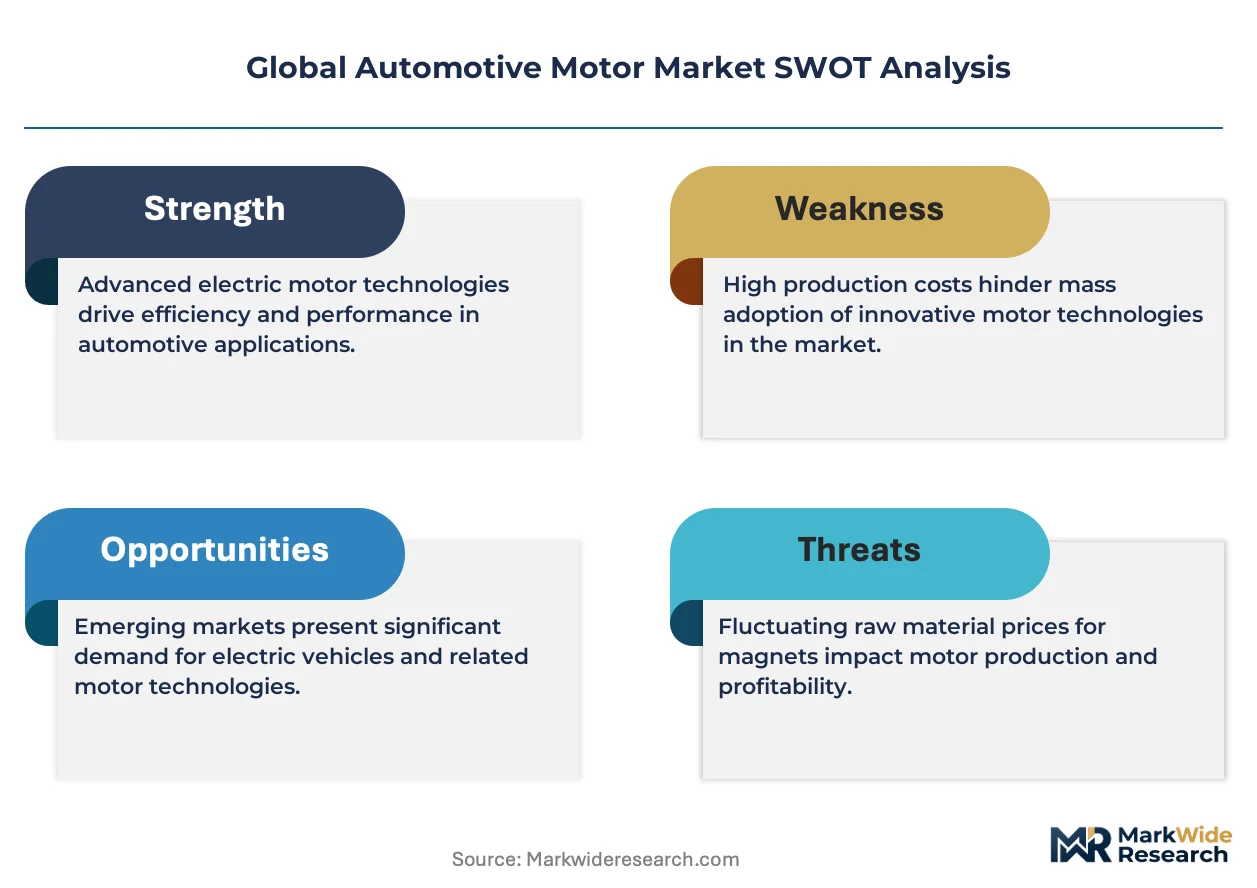
- Rare earth concentrate dependency:Dysprosium and terbium processing capacity concentrates in Chinese state-owned refineries, exposing non-domestic motor manufacturers to export quota volatility.
- Copper winding cost exposure:LME copper price swings above historical baselines compress margin structures for high-slot-fill motor designs requiring premium conductor grades.
- REACH substance restrictions:ECHA candidate list expansions for cobalt compounds force magnet reformulation cycles that extend qualification timelines by 18-24 months.
Strategic Opportunities
- India PLI scheme localization:Component-level incentives for power electronics and motor assembly create first-mover advantages for dedicated EV motor facilities in Tamil Nadu and Gujarat.
- 48V mild-hybrid retrofits:Belt-integrated starter-generator architectures offer penetration pathways in legacy internal combustion platforms where full electrification remains uneconomical.
- Japan METI hydrogen corridor alignment:Fuel cell air compressor motor specifications are converging with traction motor thermal management standards, enabling platform reuse.
Industry Challenges
- Electromagnetic compatibility certification:CISPR 25 radiated emissions testing for 800V systems requires anechoic chamber investments that strain mid-tier supplier capex budgets.
- Multiphysics simulation talent scarcity:Coupled thermal-electromagnetic-mechanical modeling expertise concentrates in German and Japanese engineering consultancies, constraining in-house design velocity elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Motor Market |
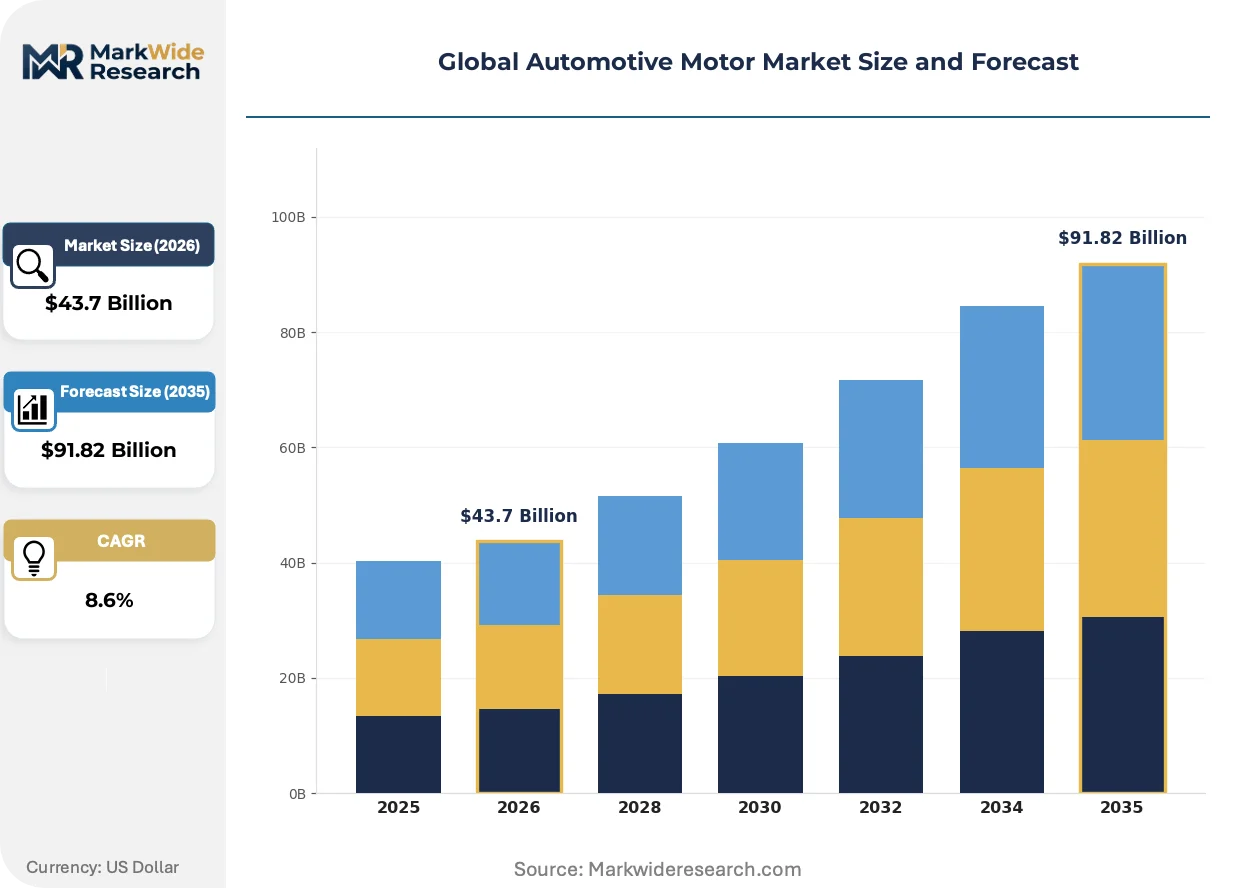
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $91.82 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DC Motors, AC Motors, Stepper Motors, Servo Motors Application: Electric Vehicles, Hybrid Vehicles, Conventional Vehicles, Commercial Vehicles Technology: Brushless, Brushed, Switched Reluctance, Permanent Magnet End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | ZF Friedrichshafen, Bosch, Denso, Magna International, Continental, Aisin, Johnson Electric, Nidec, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Motor Market Emerging Trajectories
Magnet-free motor topologies are gaining engineering bandwidth as supply security concerns override pure efficiency optimization, while software-defined motor control is collapsing hardware variant counts through parameter-tunable platforms.
Hairpin winding technology is displacing traditional round-wire stator construction in traction motor designs. Tier 1 suppliers in Germany and China are converting production lines to continuous hairpin forming equipment that reduces end-turn length and improves slot fill factors. The shift is displacing labor-intensive hand-winding operations and enabling automated quality inspection through machine vision systems.
EPA Tier 4 and Euro 7 emissions trajectories are tightening auxiliary load efficiency requirements for commercial vehicle alternators and cooling fans. The regulatory compression is forcing 12V motor redesigns that previously escaped electrification scrutiny. North American heavy-duty truck manufacturers are responding with integrated starter-alternator systems that recuperate braking energy at lower voltage thresholds.
Fleet operators are consolidating motor procurement through vehicle-as-a-service contracts that bundle maintenance, replacement, and performance guarantees. The contractual unbundling of hardware from uptime outcomes is shifting specification authority from OEM chassis divisions to fleet management platforms. This concentration is most visible in European urban bus electrification programs where municipal transport authorities now dictate motor efficiency bands in tender documents.
Global Automotive Motor Market Segmentation
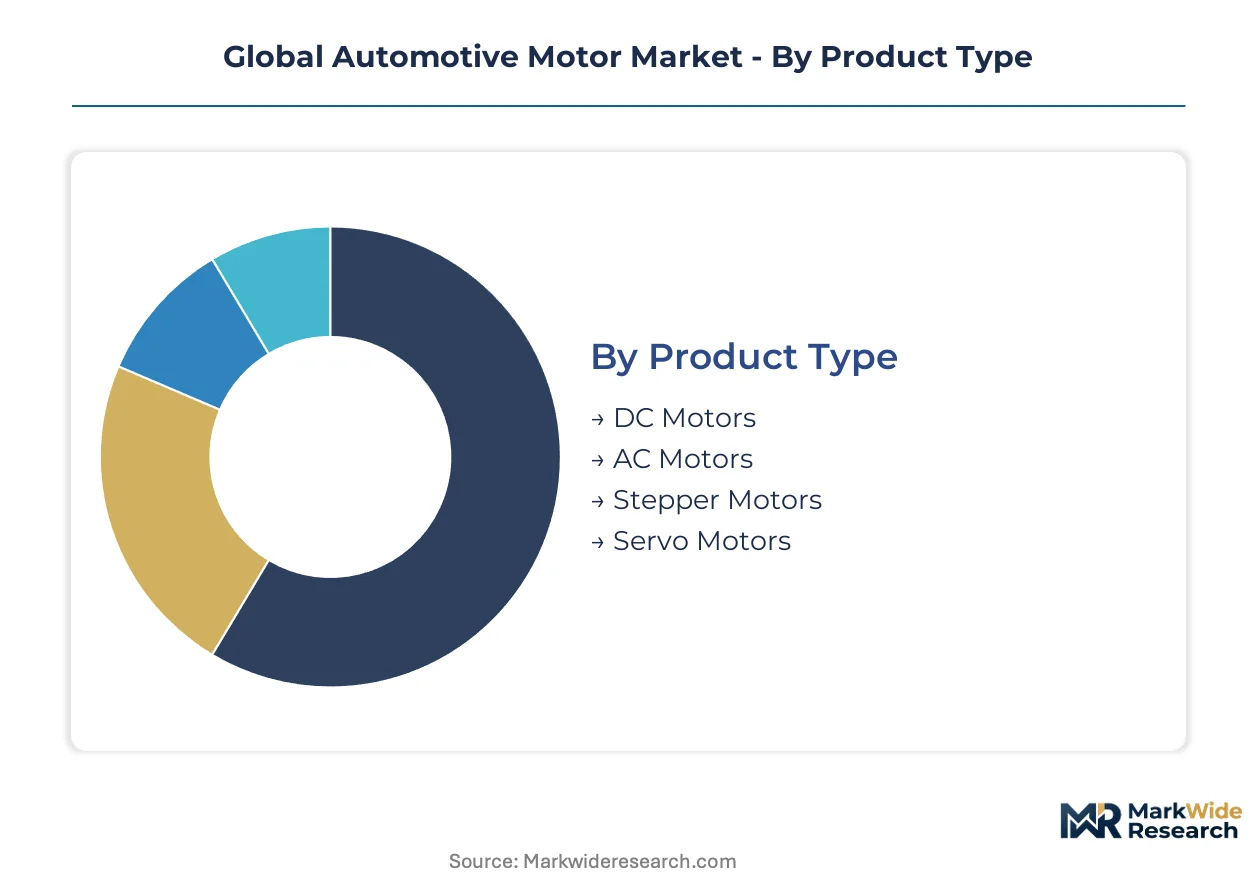
Automotive motor segmentation reveals divergent margin architectures across electrification tiers. Voltage class and magnet composition determine supplier profitability more than unit volume. Procurement authority is fragmenting between OEM powertrain divisions and fleet operator service contracts.
Product Type:
AC motor architectures command premium pricing in high-voltage traction applications where efficiency thresholds justify conductor and lamination costs.
- DC Motors:These architectures rely on commutator and brush assemblies for current reversal, limiting operational lifespan to 5,000-10,000 hours in auxiliary roles. Demand persists in 12V aftermarket retrofits and legacy climate control blower applications across India's commercial vehicle parc.
- AC Motors:Induction and synchronous designs dominate 400V-800V traction platforms through superior thermal endurance and reduced maintenance. German OEM procurement contracts for premium passenger EVs specify AC traction motors with hairpin windings and silicon carbide inverter pairing.
- Stepper Motors:Incremental rotation control suits precision positioning in headlamp leveling and HVAC damper actuation.
- Servo Motors:Closed-loop feedback enables torque and speed control for electric power steering and active suspension systems.
AC motors hold installed capacity. DC motors are rotating up the share rankings in cost-sensitive auxiliary retrofits.
Application:
Commercial vehicle electrification is compressing duty cycle specifications as last-mile delivery fleets impose uptime guarantees on motor suppliers.
- Electric Vehicles:Battery-electric platforms require traction motors rated for continuous operation at peak torque, driving demand for liquid-cooled permanent magnet designs with rare earth reduction. China MIIT procurement quotas concentrate volume in Jiangsu and Zhejiang foundries.
- Hybrid Vehicles:Dual-voltage architectures integrate 48V belt-integrated starter-generators with 400V traction motors, forcing suppliers to maintain dual production qualifications. Japan METI hydrogen corridor specifications are converging with hybrid thermal management standards.
- Conventional Vehicles:12V starter and alternator motors face efficiency mandates under EPA Tier 4 and Euro 7 auxiliary load requirements.
- Commercial Vehicles:Heavy-duty electrification prioritizes magnet-free switched reluctance designs to eliminate supply chain exposure.
Electric vehicles anchor current procurement volume. Commercial vehicles are expanding most quickly as fleet operators consolidate motor specifications in vehicle-as-a-service contracts.
Technology:
Brushless designs capture margin through reduced warranty exposure, while magnet-free topologies address supply security premiums.
- Brushless:Electronic commutation eliminates brush wear, extending service intervals beyond 100,000 kilometers. Bosch and Nidec production lines in Germany and Vietnam prioritize brushless traction motors for OEM supply agreements with efficiency guarantees.
- Permanent Magnet:Neodymium-iron-boron rotors deliver superior power density but concentrate supply risk in Chinese state-owned rare earth refineries. REACH substance restrictions on cobalt compounds are forcing magnet reformulation cycles that extend qualification timelines.
- Brushed:Mechanical commutation persists in cost-optimized auxiliary applications with limited duty cycles.
- Switched Reluctance:Magnet-free operation eliminates rare earth dependency at efficiency penalties acceptable in commercial vehicle thermal management.
Permanent magnet designs hold installed capacity. Switched reluctance is climbing the fastest as supply security overrides pure efficiency optimization.
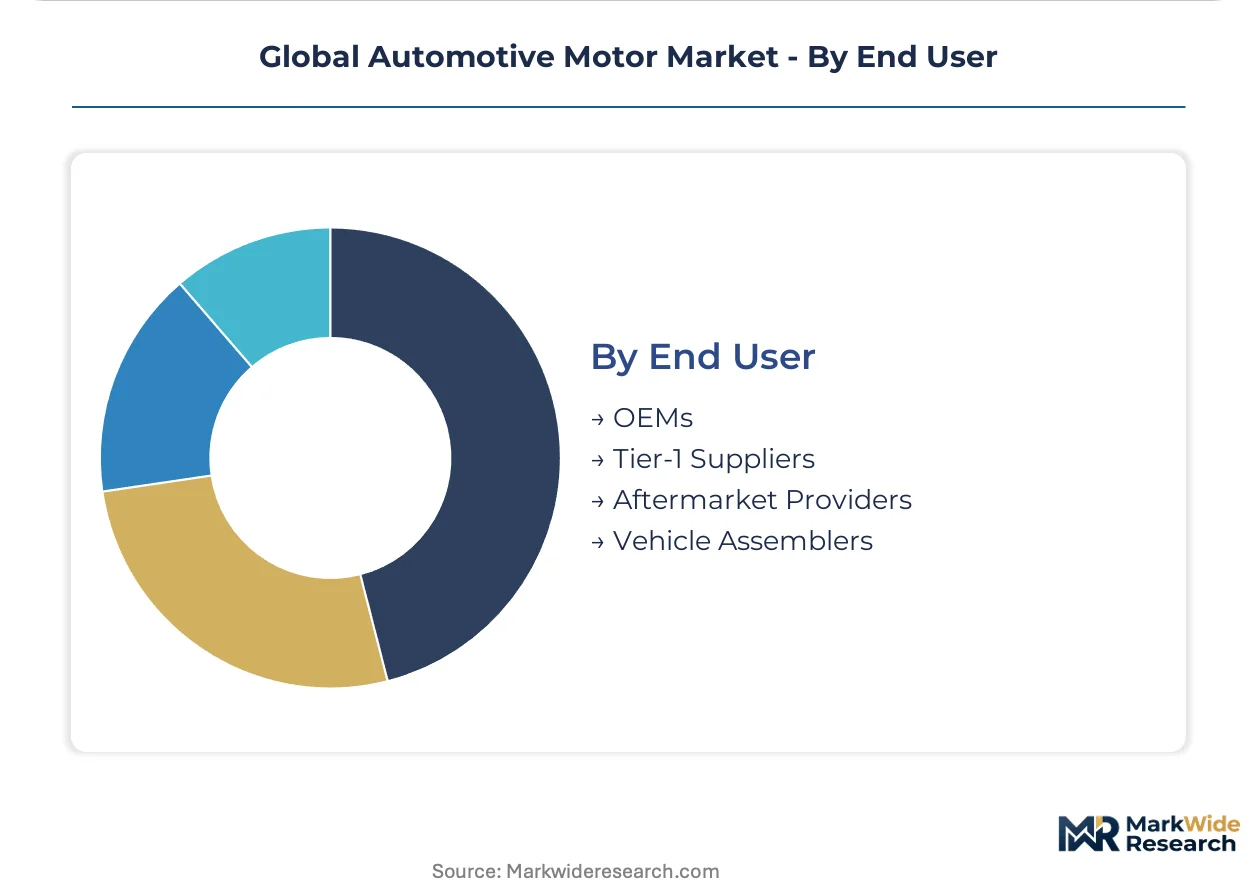
End User:
Tier-1 suppliers capture value through integrated motor-inverter subsystems that reduce OEM assembly complexity.
- OEMs:In-house motor design teams at Volkswagen, BYD, and Tesla specify proprietary winding configurations and thermal interfaces. Direct procurement of stator laminations and rotor assemblies from foundries in China and Germany bypasses traditional Tier-1 markup.
- Tier-1 Suppliers:Continental and Denso compete on modular platform designs spanning hybrid and full-electric applications. These suppliers integrate hairpin winding automation with machine vision quality inspection to meet OEM volume commitments.
- Aftermarket Providers:Remanufactured starter and alternator motors serve legacy vehicle parc maintenance in North American and European independent repair channels.
- Vehicle Assemblers:Contract manufacturers in India and Mexico source motors through consolidated procurement agreements with performance guarantees.
Tier-1 suppliers hold installed capacity. OEMs are rotating up the share rankings through backward integration into motor design and foundry partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China maintains a structural trade surplus in rare earth processed materials essential for permanent magnet motors, while Germany and the United States remain net importers of dysprosium and terbium concentrates. This imbalance concentrates motor foundry capacity in Chinese industrial clusters and forces Western OEMs to absorb supply chain volatility through strategic stockpiling.
China
Domestic EV procurement quotas under MIIT dual carbon mandates accelerate Jiangsu and Zhejiang foundry expansion. GB standards for motor efficiency tighten qualification thresholds for export-bound production. Nidec operates dedicated EV motor facilities in Dalian and Suzhou to anchor Asia-Pacific supply scale.
Germany
Premium passenger EV contracts specify hairpin winding AC traction motors with silicon carbide inverter pairing. KBA enforces electromagnetic compatibility certification that strains mid-tier supplier capex budgets. Bavarian engineering consultancies concentrate scarce multiphysics simulation talent for coupled thermal-electromagnetic modeling.
United States
EPA Tier 4 and NHTSA safety frameworks determine motor efficiency thresholds and thermal runaway protocols for domestic OEMs. Last-mile delivery fleets in California and Texas convert diesel auxiliary power units to electric thermal management motors. Detroit-area Tier-1 suppliers retool for dual-voltage production lines spanning 48V to 800V platforms.
Japan
METI hydrogen corridor specifications converge fuel cell air compressor motor standards with traction thermal management requirements. Kansai-based suppliers exploit platform reuse opportunities across hybrid and fuel cell architectures. JIS standards for brushless motor durability extend service interval guarantees beyond 100,000 kilometers.
India
PLI scheme localization incentives attract dedicated EV motor assembly investment in Tamil Nadu and Gujarat. BIS efficiency labeling mandates compress margin structures for cost-optimized auxiliary motor designs. Chennai and Ahmedabad industrial corridors concentrate Tier-1 supplier partnerships with domestic OEMs.
Global Automotive Motor Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and technology integration dimensions. The vendor base fragments across three tiers: integrated powertrain conglomerates with semiconductor capabilities, dedicated motor specialists with hairpin automation scale, and regional fabricators serving aftermarket channels. Two strategic archetypes dominate competitive positioning: magnet supply chain controllers and modular platform designers. Capacity expansion in Vietnamese and Mexican production zones and strategic partnerships for silicon carbide inverter pairing represent the dominant competitive moves.
Within the integrated conglomerate tier, Bosch and Continental exemplify archetypes that combine in-house semiconductor integration with modular platform architectures spanning hybrid and full-electric applications. Denso anchors Japanese-scale production with METI-aligned fuel cell and hybrid motor specifications. These three entities occupy positions where backward integration into magnet supply chains and upstream control over rare earth processing relationships determine procurement resilience.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| Bosch |
| Denso |
| Magna International |
| Continental |
| Aisin |
| Johnson Electric |
| Nidec |
| ABB |
| Others |
Supply Flow & Price Mechanics
Silicon carbide inverter pairing with permanent magnet motors is displacing conventional IGBT architectures and simultaneously concentrating procurement authority in German and Chinese foundries while compressing margin structures for suppliers lacking wide-bandgap semiconductor integration. This substitution dynamic reshapes pricing economics by tethering motor premiums to inverter compatibility tiers rather than standalone efficiency metrics.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels based on hairpin winding automation grade and silicon carbide pairing certification. Price differentiation hinges on thermal endurance guarantees and MIIT efficiency quota compliance, with premium tiers commanding substantial markups for liquid-cooled rare-earth-reduced designs. Cost compression in economy auxiliary motors is intensifying because copper LME price volatility erodes slot-fill margins. Fleet operators exhibit lowest price sensitivity due to vehicle-as-a-service uptime guarantees, while aftermarket retrofit channels face acute margin pressure.
Supply Chain Analysis
China and Vietnam anchor motor foundry capacity expansion, with Jiangsu and Zhejiang provinces concentrating rare earth processing and hairpin winding automation respectively. Raw material dependencies draw from dysprosium-terbium concentrates, high-grade electrical steel laminations, and copper rod stock. Single-source vulnerability in Chinese state-owned rare earth refineries exposes non-domestic manufacturers to export quota volatility. Distribution runs through Tier-1 integrated subsystems to OEM powertrain divisions, with direct foundry procurement bypassing traditional markup layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment, where EPA Tier 4 and Euro 7 efficiency mandates create certification barriers that extend qualification timelines and protect incumbent positions.
For Market Incumbents: Shield market position by deepening backward integration into rare earth processing relationships and expanding dedicated EV motor capacity in Vietnamese production zones. Magnet-free switched reluctance R&D investment addresses supply security threats from Chinese export quota volatility. Certification maintenance for 800V electromagnetic compatibility under CISPR 25 preserves OEM supply agreement eligibility. For New Entrants and Emerging Players: Fast-tracked BIS efficiency labeling under India's PLI scheme offers a white-space entry point in Tamil Nadu and Gujarat assembly corridors. Target commercial vehicle thermal management segments where magnet-free architectures eliminate incumbent rare earth advantages. Pursue fleet operator vehicle-as-a-service contracts that bypass OEM chassis division procurement gatekeepers. For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors semiconductor-integrated powertrain conglomerates over pure-play motor specialists. Long-term viability centers on silicon carbide inverter pairing capabilities and hairpin winding automation scale. Acquisition targets should demonstrate multiphysics simulation talent concentration or established OEM platform engineering relationships. Watch for MIIT dual carbon mandate acceleration as inflection signal for Chinese domestic content requirement tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Modular motor-inverter designs spanning 48V to 800V reduce OEM qualification cycles and tooling redundancy. |
| Battery Supply Agreement | Cell manufacturer partnerships secure thermal management motor placement in integrated pack architectures. |
| Software-Defined Vehicle Investment | Parameter-tunable motor control platforms collapse hardware variant counts and enable over-the-air efficiency updates. |
| Geographic Manufacturing Footprint | Dedicated EV motor facilities in Vietnam and Mexico diversify tariff exposure and anchor regional OEM supply. |
| Charging Infrastructure Partnership | High-power charging network alignment ensures 800V traction motor thermal specifications meet duty cycle demands. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distribution managers, and fleet operator maintenance heads and refined through secondary validation. Primary fieldwork drew from IHS Markit vehicle production databases, EPA and NHTSA regulatory filings, MIIT procurement quota disclosures, and customs trade records for rare earth concentrate flows. Bottom-up segmentation modeling triangulated with top-down macroeconomic scenario analysis across the analysis window.
Variance decomposition separated volume growth from pricing trajectory and mix shift effects throughout the forecast period. Segmentation dimensions modeled included propulsion architecture, voltage class, magnet composition, vehicle platform tier, and regional production cluster. CAGRs derived from logistic adoption curves fitted to electrification penetration rates, with motor content-per-vehicle assumptions calibrated to OEM powertrain roadmaps and silicon carbide inverter deployment schedules.
Underlying assumptions cover EPA Tier 4 and Euro 7 regulatory enforcement timelines, with deviation risk concentrated in rare earth export quota volatility and copper price swing magnitude. Forecasts reflect these documented assumptions with sensitivity bands for alternative electrification pace scenarios. Recalibration cycles align with material shifts in MIIT mandate stringency and wide-bandgap semiconductor cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Air Motor Market
Electric Motor
Electric Drives Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
Global Motor Management Market
Electric Motor
Motors for Robot Body and Robot Wheels Market
Electric Motor
Automotive Induction Motors Market
Electric Motor
Intelligent Motor Control Center Market
Electric Motor
Electric AC Motors Market
Electric Motor
Large Synchronous Motor Market
Electric Motor
Motorcycle Battery Market
Electric Motor
GCC Electric Motor Market
Electric Motor
Automotive in-Wheel Motors Market
Electric Motor
Automotive Heater Fan Motor Market
Electric Motor
Industrial Smart Motor Market
Electric Motor
Automotive Seat Motor Market
Electric Motor
France Alternating Current (AC) Motor Market