
 Traction Motor Core Market | 2026-2036
Traction Motor Core Market Size, Share, and Industry Trends Forecast 2026-2036
Traction Motor Core Market Insights
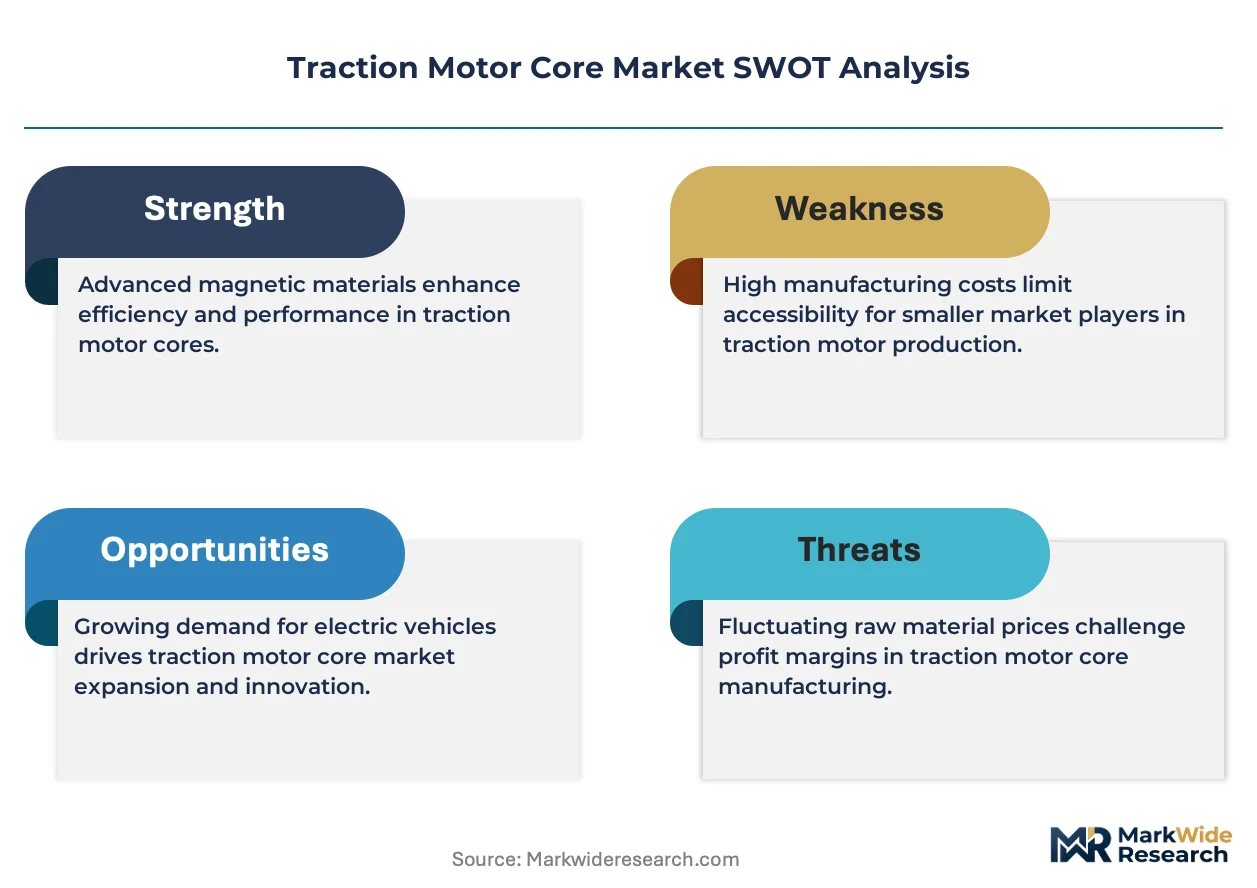
The EU's F-Gas Regulation is consolidating the cost-of-entry calculus for European traction motor core suppliers, forcing laminate stack producers to certify low-carbon silicon steel sourcing or forfeit OEM contracts. POSCO sustains backward integration into grain-oriented electrical steel, insulating its Korean manufacturing base from raw material volatility. Mitsui High-tec dominates precision stamping for hybrid vehicle stator cores, leveraging multi-layer lamination patents accumulated across three decades of Japanese automotive supply relationships.
A traction motor core comprises laminated electrical steel sheets stacked and bonded to form the magnetic path within an electric motor, typically using silicon steel with 0.2–0.5 mm thickness and insulating coatings to minimize eddy current losses; its primary purpose is to channel magnetic flux efficiently while maintaining mechanical integrity under rotational torque loads. Permanent magnet cores anchor the highest margin pools due to rare-earth magnet integration complexity, while induction configurations occupy the volume-heavy industrial machinery segment where copper rotor cage durability outweighs peak efficiency demands. Synchronous variants lead rail transport applications where precise speed-torque control determines operational safety margins.
The EPA's vehicle efficiency standards and China's MIIT dual carbon goals collectively mandate higher motor efficiency tiers, compelling core manufacturers to document lamination loss coefficients and recycling content percentages for market access. Japan's METI subsidizes domestic silicon steel refining capacity to reduce import dependence on Chinese and Korean sheet suppliers. Stakeholders must monitor whether regional carbon border adjustments will bifurcate core sourcing strategies between low-cost Asian laminate stampers and premium European integrated producers.
Market Dynamics
The EU's F-Gas Regulation and China's MIIT dual carbon goals are compressing the supplier qualification window, forcing laminate stack producers to certify low-carbon silicon steel sourcing or forfeit OEM contracts before the next platform cycle.
Growth Catalysts
- CO2 fleet targets:Europe's tightening automotive emissions standards mandate higher motor efficiency tiers, compelling core manufacturers to document lamination loss coefficients for market access.
- NEV credit system:China's new energy vehicle incentive structure accelerates procurement of laminated steel cores as domestic manufacturers expand production capacity.
- Silicon steel refinement:Government subsidies for domestic electrical steel production reduce import dependence and stabilize raw material supply chains for core stampers.
Market Restraints
- Rare-earth magnet volatility:Permanent magnet core production faces input cost instability due to concentrated rare-earth oxide processing in Chinese refineries.
- Grain-oriented steel supply concentration:Korean and Japanese integrated steel producers control premium silicon steel sheet capacity, limiting second-tier stator core manufacturers.
- Lamination thickness floor:Mechanical integrity requirements prevent sub-0.2 mm sheet adoption despite eddy current loss reduction benefits.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for domestic EV manufacturing create localized demand for precision-stamped stator and rotor cores.
- Rail transport electrification:Synchronous motor core specifications for high-speed train traction systems open specialized high-reliability segments.
- Recycling content mandates:EU battery and motor regulations incentivize closed-loop silicon steel recovery systems for qualifying core suppliers.
Industry Challenges
- Multi-layer lamination expertise:Precision stamping for hybrid vehicle stator cores requires tooling competencies concentrated among veteran Japanese automotive suppliers.
- Carbon border adjustment readiness:European importers must document embodied emissions across Chinese and Korean steel supply chains to maintain contract eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traction Motor Core Market |
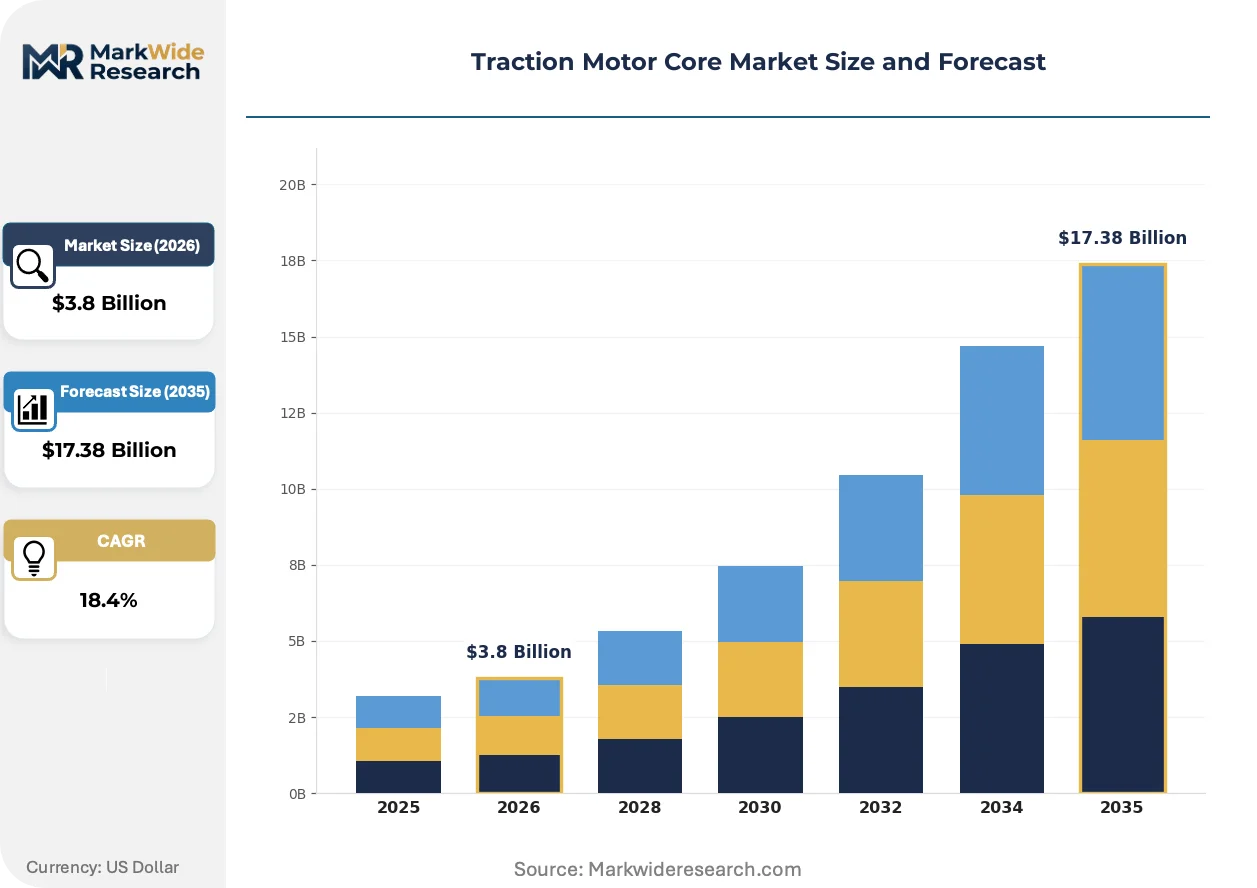
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Magnet, Induction, Switched Reluctance, Synchronous End User: Railways, Electric Vehicles, Industrial Machinery, Marine Application: Propulsion Systems, Auxiliary Drives, Rail Transport, Heavy Equipment Installation: On-board, Off-board, Integrated, Standalone |
| Companies Covered | Mitsui High-tec, POSCO, Suzhou Fine-stamping, Yutaka Giken, Toyota Boshoku Corporation, Tempel Steel, Kienle Spiess, EUROTRANCIATURA, Hidria, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traction Motor Core Market Trends and Innovations
Magnetic material processing and regulatory compliance frameworks are reshaping competitive positioning in traction motor core supply, with efficiency mandates and raw material traceability requirements driving capital allocation decisions.
High-grade non-oriented electrical steel with optimized silicon content is consolidating as the baseline specification for passenger EV traction motors. Tier-1 automotive suppliers are phasing out legacy motor grades within two platform generations. This material shift is consolidating procurement volumes among steel mills capable of consistent magnetic property certification.
REACH substance restrictions and the EU's F-Gas Regulation are eliminating certain insulating coating chemistries from laminate stack production. Core manufacturers must reformulate bonding agents and validate alternative thermal class ratings. European OEMs are responding by qualifying Asian stampers with pre-certified low-carbon steel supply chains.
Long-term lamination supply agreements are displacing spot purchasing for high-volume EV programs. Tier-1 motor suppliers are locking multi-year silicon steel allocations to secure capacity amid refining capacity constraints. This contracting pattern is most visible in Germany's industrial corridor and China's Yangtze River Delta manufacturing cluster.
Traction Motor Core Market Segmentation
Traction motor core procurement decisions pivot on magnetic efficiency requirements, thermal operating envelopes, and integration complexity with power electronics. Segment boundaries increasingly blur as hybrid architectures combine permanent magnet and induction elements within single motor assemblies.
Product Type:
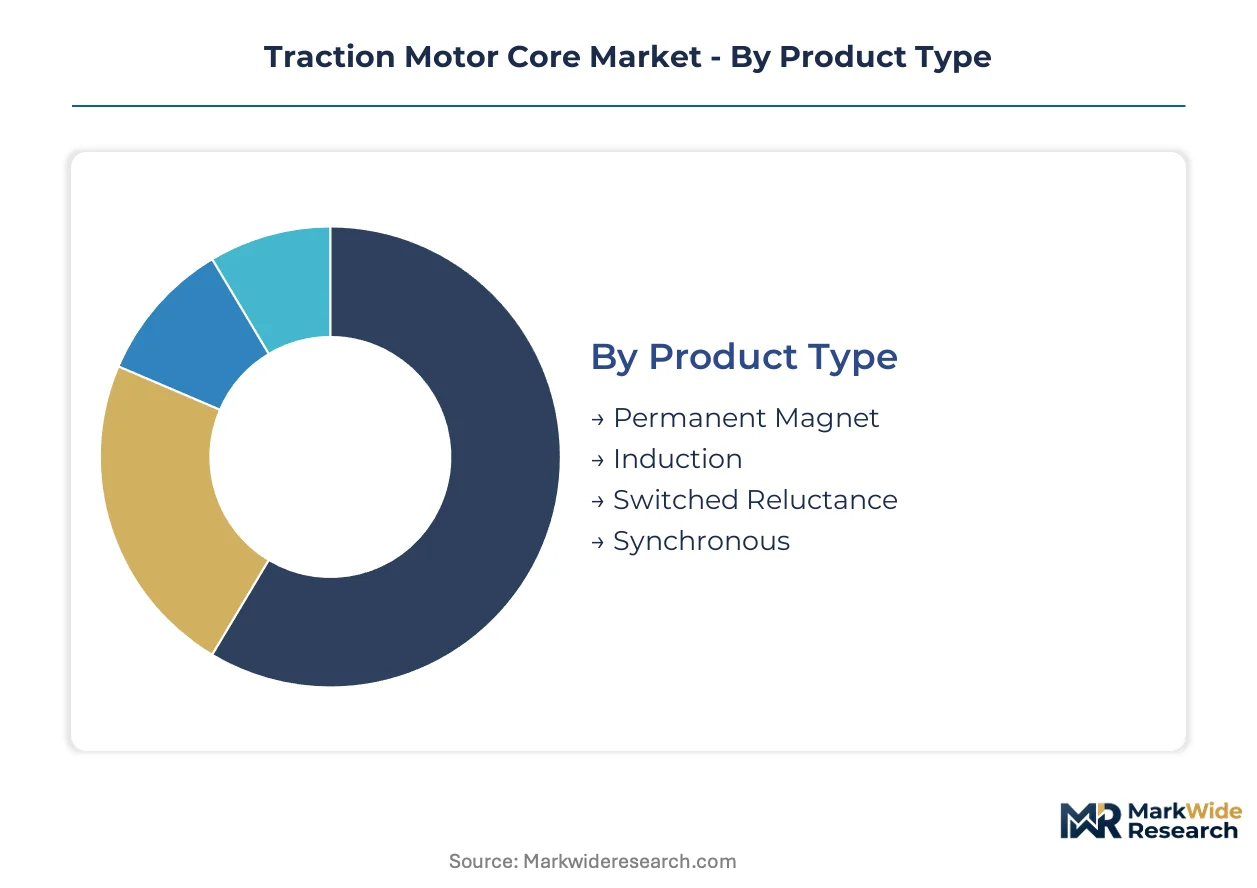
Buyers select magnetic core architectures based on torque density requirements, rare-earth supply security, and controller sophistication thresholds.
- Permanent Magnet:Neodymium-iron-boron or ferrite magnets embedded in laminated steel rotors deliver peak torque density for passenger EV propulsion. China's MIIT dual carbon goals and Europe's CO2 fleet targets concentrate demand in Germany's industrial corridor and China's Yangtze River Delta manufacturing cluster, where OEMs prioritize efficiency over magnet cost volatility.
- Induction:Copper or aluminum squirrel-cage rotors eliminate rare-earth dependencies through electromagnetic induction alone. Industrial machinery manufacturers across Japan's automotive belt favor this architecture for continuous-duty applications where rotor durability outweighs peak efficiency demands.
- Switched Reluctance:Salient-pole rotors without windings or magnets operate through variable reluctance torque generation. Mining equipment OEMs specify these cores for high-temperature environments where magnet demagnetization risks exclude permanent magnet alternatives.
- Synchronous:Field-excited or permanent magnet rotors maintain precise speed synchronization with grid frequency. Rail transport electrification programs specify synchronous cores for high-speed train traction systems requiring exact speed-torque control margins.
Volume sits with Induction configurations in industrial machinery; growth tilts toward Permanent Magnet cores as EV efficiency mandates tighten.
End User:
Application-specific duty cycles and certification requirements fragment procurement specifications across mobility and stationary power segments.
- Railways:Traction motor cores for locomotive and multiple-unit propulsion must survive million-kilometer service intervals with minimal maintenance. European rail operators specify synchronous laminated stacks with vacuum-pressure-impregnated windings for high-speed corridor electrification projects.
- Electric Vehicles:Passenger and commercial vehicle manufacturers demand compact stator-rotor assemblies with hairpin winding compatibility. China's NEV credit system accelerates procurement of thin-gauge silicon steel cores as domestic manufacturers expand production capacity.
- Industrial Machinery:Compressors, pumps, and conveyor systems utilize induction cores optimized for constant-speed operation. Japanese machine tool builders source laminated stacks through METI-subsidized domestic silicon steel channels to reduce import exposure.
- Marine:Propulsion and thruster motors for electric and hybrid vessels require corrosion-resistant lamination coatings and sealed bearing arrangements. Shipyards along Korea's southeastern coast specify high-grade non-oriented electrical steel for offshore supply vessel electrification retrofits.
Procurement volume clusters in Electric Vehicles; Railways represents the steepest expansion trajectory as intercity electrification accelerates.
Application:
Integration depth with vehicle or machinery architecture determines lamination stack geometry and thermal management specifications.
- Propulsion Systems:Main drive motors for traction applications demand highest-grade magnetic steel with sub-0.3 mm thickness and optimized silicon content. Tier-1 automotive suppliers lock multi-year silicon steel allocations to secure capacity for high-volume EV programs.
- Auxiliary Drives:Steering, braking, and HVAC compressor motors utilize smaller-diameter laminated cores with simplified stamping tooling. Secondary system suppliers compete on piece-cost reduction through high-speed progressive die automation.
- Rail Transport:Traction motor cores for metro, mainline, and high-speed applications require specialized insulation systems for 25 kV overhead electrification. European OEMs qualify Asian stampers with pre-certified low-carbon steel supply chains to meet F-Gas Regulation compliance deadlines.
- Heavy Equipment:Mining trucks, excavators, and port cranes specify robust laminated stacks with enhanced mechanical retention of windings under shock and vibration loads. Equipment builders prioritize field-serviceability over peak efficiency metrics.
Shipments concentrate in Propulsion Systems; Rail Transport gains share fastest as fleet electrification mandates proliferate.
Installation:
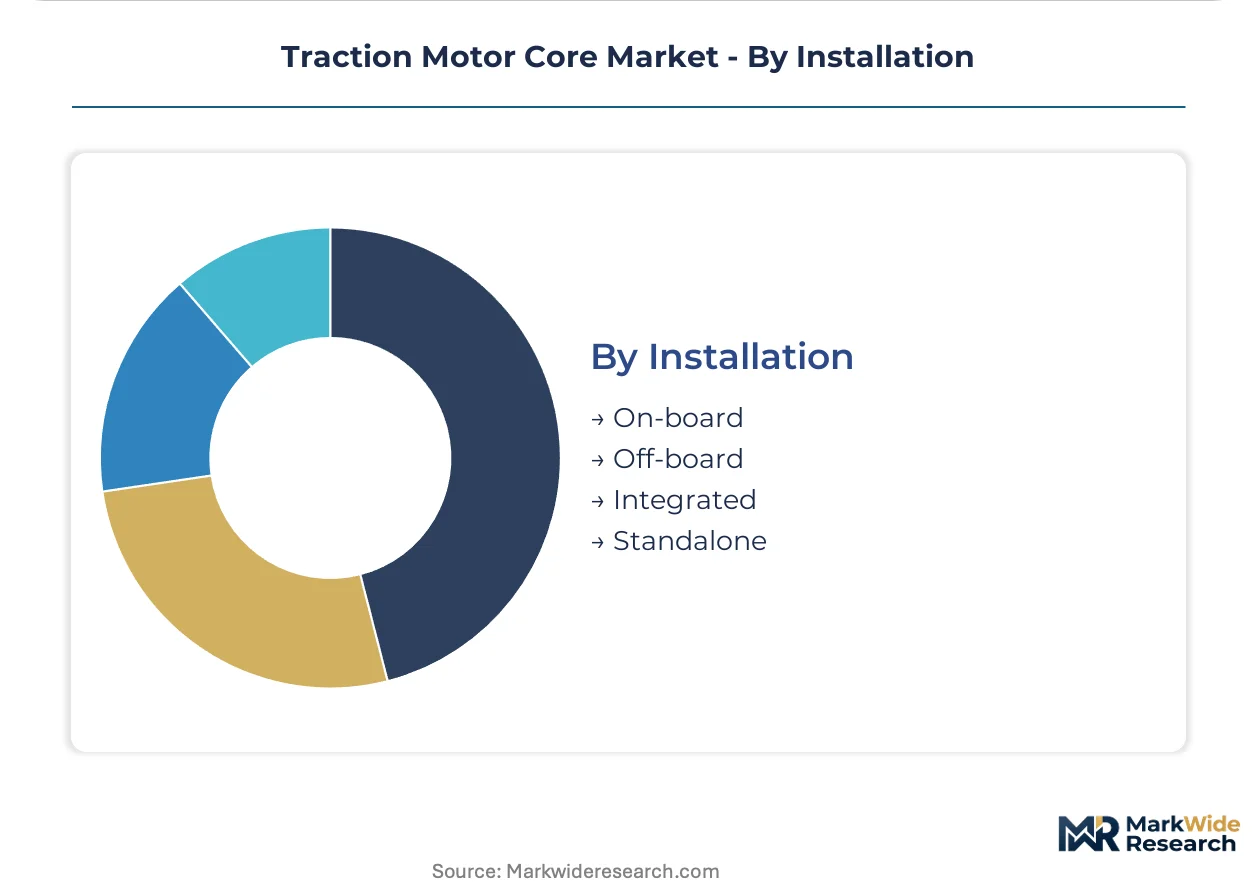
Packaging constraints and service accessibility requirements differentiate core specifications across mounting configurations.
- On-board:Motor cores integrated within vehicle chassis or machinery frames require compact axial-length minimization and liquid cooling jacket compatibility. Passenger EV platforms specify on-board permanent magnet cores with direct oil-spray rotor cooling.
- Off-board:Stationary charging infrastructure and wayside power equipment house laminated stacks in weather-protected enclosures. Pantograph and third-rail pickup systems utilize off-board transformer cores with grain-oriented electrical steel for efficiency.
- Integrated:Motor cores combined with transmissions, inverters, or axles into single housings demand precision-machined lamination outer diameters for bearing and seal interfaces. German powertrain suppliers lead integrated e-axle core development for premium EV platforms.
- Standalone:Separate motor assemblies for retrofit applications and service replacement require standardized mounting interfaces and terminal box configurations. Aftermarket distributors stock standalone induction cores for industrial machinery maintenance.
Integrated configurations capture expanding share; Standalone maintains residual volume in retrofit and service channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones and Germany's industrial corridor anchor laminated steel procurement concentration for electric vehicle powertrains.
China
Domestic NEV manufacturers expand stamping capacity for thin-gauge silicon steel cores. MIIT dual carbon goals mandate documented lamination loss coefficients for supplier qualification. Shanghai-Suzhou manufacturing clusters host precision stamping facilities serving BYD and Tesla Gigafactory Shanghai.
Germany
BMW and Volkswagen accelerate e-axle platform launches requiring high-grade non-oriented electrical steel. EU F-Gas Regulation eliminates legacy insulating coating chemistries from laminate stack production. Bavaria's Munich-Stuttgart corridor concentrates Tier-1 motor supplier engineering centers.
Japan
Hybrid vehicle stator core demand sustains multi-layer lamination tooling utilization. METI subsidizes domestic silicon steel refining capacity to reduce Korean and Chinese import exposure. Toyota City-Nagoya automotive belt hosts veteran stamping specialists with three-decade OEM relationships.
South Korea
Hyundai-Kia electrification roadmap drives permanent magnet core procurement volumes. POSCO's backward integration into grain-oriented electrical steel insulates domestic manufacturing from raw material volatility. Busan-Ulsan industrial complex houses integrated steel-to-motor supply chains.
India
PLI scheme incentives attract EV manufacturing investments requiring localized stator and rotor core supply. Central Electricity Authority efficiency standards tighten motor performance tiers for industrial applications. Tamil Nadu and Gujarat automotive corridors emerge as precision stamping investment destinations.
Traction Motor Core Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the traction motor core supply base. Japanese and Korean integrated steel producers control premium silicon steel sheet capacity, limiting second-tier stator core manufacturers. Three archetypes dominate: steel mill-integrated stampers, independent precision lamination specialists, and captive automotive supplier divisions. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEMs lock multi-year silicon steel allocations.
Within the steel-integrated stamper tier, POSCO exemplifies upstream control over electrical steel supply chains. Among precision-focused specialists, Mitsui High-tec occupies a position representing multi-layer lamination expertise accumulated across automotive supply relationships. Yutaka Giken anchors the Tier-1 automotive supplier archetype with integrated motor component portfolios.
| Leading Market Players |
|---|
| Mitsui High-tec |
| POSCO |
| Suzhou Fine-stamping |
| Yutaka Giken |
| Toyota Boshoku Corporation |
| Tempel Steel |
| Kienle Spiess |
| EUROTRANCIATURA |
| Hidria |
| Others |
Pricing and Supply Chain Analysis
Silicon steel coil spot indices cascade through laminated core supply chains into three distinct pricing tiers, with premium non-oriented electrical steel commanding substantial markups over standard grades as OEMs lock multi-year allocations ahead of platform cycles. China's Yangtze River Delta stampers and Germany's industrial corridor producers diverge on cost pass-through mechanisms, with Asian suppliers absorbing more freight volatility to secure European qualification under F-Gas Regulation deadlines.
Pricing Analysis
Lead-time premiums dominate transactional pricing, with spot inventory commanding discounts against six-month forward contracts as Tier-1 automotive suppliers pre-position silicon steel allocations. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-pressure-impregnated railway cores from mass-market EV stator stacks and aftermarket induction motor replacements. Cost compression in standard-grade laminations is intensifying because Chinese NEV manufacturers expand captive stamping capacity. Industrial machinery buyers exhibit highest price sensitivity, while rail operators prioritize million-kilometer reliability over unit cost.
Supply Chain Analysis
Containerized freight rates from Busan to Hamburg directly influence landed cost competitiveness for Korean and Japanese electrical steel exports. Supply concentrates in China, South Korea, and Japan for silicon steel refining, with Germany and India emerging as secondary precision stamping hubs. Raw material flows draw from Australian iron ore, Chinese rare-earth oxide processing, and Korean grain-oriented electrical steel capacity. Single-source vulnerability concentrates in Chinese neodymium-iron-boron magnet supply chains. Distribution runs through Tier-1 motor supplier engineering centers directly to OEM platform integration teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with electrical steel refining capacity and precision stamping tooling representing the decisive upstream levers players are pursuing to secure OEM contract eligibility.
For Market Incumbents: Acquire thin-gauge silicon steel rolling capacity to insulate margin structures from Korean and Chinese raw material volatility. Lock multi-year lamination supply agreements with European OEMs before F-Gas Regulation compliance deadlines disqualify non-certified stampers. Defensive consolidation must address emerging Chinese NEV manufacturers expanding captive core production. For New Entrants and Emerging Players: Tier-2 automotive supplier procurement teams represent the most accessible channel partner type for qualification without legacy platform incumbency. India's PLI scheme incentives and Tamil Nadu automotive corridor infrastructure offer the most penetrable geography for greenfield precision stamping investment. Target aftermarket standalone induction core replacement demand as a volume-building entry path before propulsion system Tier-1 qualification. For Investors and Strategic Acquirers: The window for entry favors steel-integrated stampers with demonstrated magnetic property certification capabilities over pure-play lamination specialists. Long-term viability hinges on securing OEM platform engineering relationships that span multiple vehicle generations. Watch for EU carbon border adjustment implementation timing as the critical inflection signal for European contract eligibility restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrical Steel Refining | POSCO's grain-oriented capacity insulates Korean manufacturing from Chinese silicon steel export volatility. |
| Multi-Year Silicon Steel Allocation Lock | BMW and Volkswagen pre-position high-grade non-oriented electrical steel ahead of e-axle platform launches. |
| Low-Carbon Steel Supply Chain Certification | European stampers document embodied emissions to maintain OEM contract eligibility under F-Gas Regulation. |
| Precision Stamping Capacity Expansion | Mitsui High-tec leverages three-decade hybrid stator core relationships for EV platform qualification. |
| Rail Transport Electrification Partnership | Synchronous motor core specifications for high-speed corridors open specialized high-reliability procurement channels. |
Research Methodology
Independent corroboration across OEM platform engineers, Tier-1 motor supplier procurement leads, electrical steel mill technical directors, and railway operator maintenance chiefs underwrites the qualitative findings in this analysis. Primary fieldwork combined structured interviews with secondary validation through MIIT dual carbon policy documentation, EU F-Gas Regulation compliance filings, METI subsidy program disclosures, and customs trade data for silicon steel coil movements. Bottom-up segmentation modeling and top-down macroeconomic anchoring triangulate volume estimates across the projection horizon.
Comparable-period anchoring referenced historical EV platform launch cycles and industrial motor replacement patterns to calibrate adoption curve assumptions. The analytical framework segmented by magnetic core architecture, end-use application, installation configuration, and regional production cluster throughout the forecast period. CAGRs derived from installed base growth rates, content-per-vehicle trajectories, and efficiency mandate compliance deadlines. Key inputs included NEV credit system incentive structures, rail electrification capital expenditure pipelines, and silicon steel refining capacity expansion announcements.
Several conditions sit outside the modeled scope, including abrupt rare-earth export restrictions, unanticipated F-Gas Regulation enforcement delays, and disruptive solid-state motor technology commercialization. Forecasts reflect documented assumptions about OEM platform cycle timing and regulatory compliance phase-in schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
Electric Trolling Motors Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Global Motor Soft Starter Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
US Solar E-Bike Market
Electric Motor
Electronically Commutated Motors Market
Electric Motor
Starter Motor Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
Global Hub Motors Market
Electric Motor
APAC Electric Drives Market
Electric Motor
Australia Solar E-Bike Market
Electric Motor
Electric Vehicle Motor (EVM) Controller Market
Electric Motor
Canada Electric Motor for Electric Vehicle Market
Electric Motor
Industrial Smart Motor Market
Electric Motor
Automotive ABS Motor Market