
 Automotive Power Steering Motor Market | 2026-2036
Automotive Power Steering Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Power Steering Motor Market Analysis
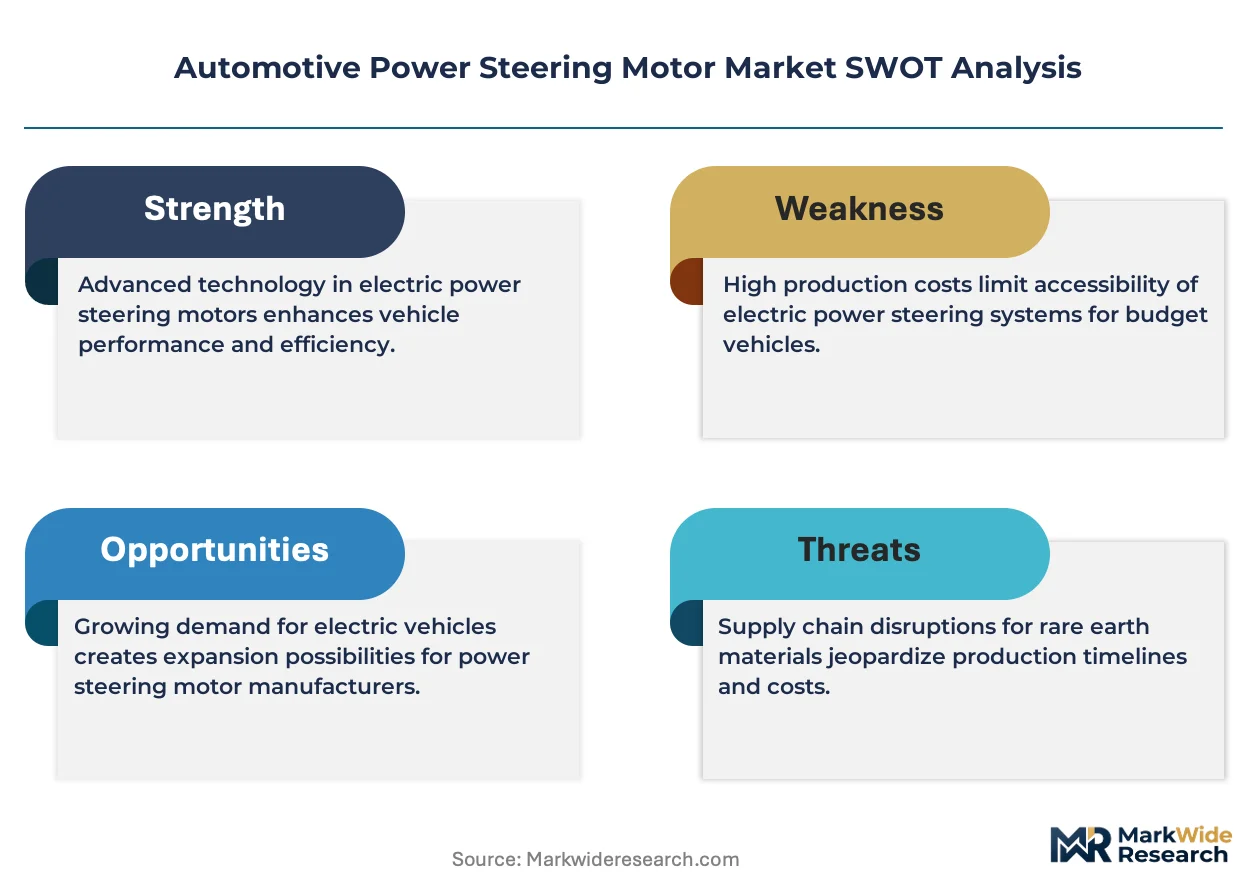
EPA tailpipe standards are restructuring the cost-of-entry calculus for steering motor suppliers, forcing redesigns toward higher-efficiency architectures. Robert Bosch GmbH leverages its integrated electronics-manufacturing footprint to capture premium brushless DC motor contracts. Nidec Corp. anchors high-volume production through dedicated facilities serving Japanese and Chinese OEM platforms.
An automotive power steering motor is an electromechanical actuator, typically a brushless DC or permanent-magnet synchronous design rated between 200W and 800W, that generates torque assistance for rack-and-pinion or recirculating-ball steering mechanisms to reduce driver effort. The device converts electrical energy from the vehicle powernet into mechanical rotational force via pulse-width modulation control, with rotor position feedback from Hall-effect or resolver sensors ensuring precise torque vectoring. Brushless DC motors dominate current production volumes due to their superior power density and maintenance-free operation, while synchronous motor architectures are gaining share in electric vehicle platforms where energy recuperation and thermal efficiency carry premium value. Passenger vehicles remain the largest addressable pool, though autonomous steering applications command the highest per-unit pricing as redundancy requirements and functional safety certification to ISO 26262 ASIL-D escalate bill-of-materials complexity.
The US EPA, EU REACH, and China's MIIT collectively shape material selection, recyclability mandates, and energy efficiency benchmarks that penetrate supplier specifications. NHTSA FMVSS 126 stability control requirements and the EU AI Act's risk classification for automated driving systems further tighten validation protocols for steering actuators in higher-autonomy vehicles. Stakeholders must monitor the divergence between regional software-defined vehicle architectures and their implications for motor control firmware standardization.
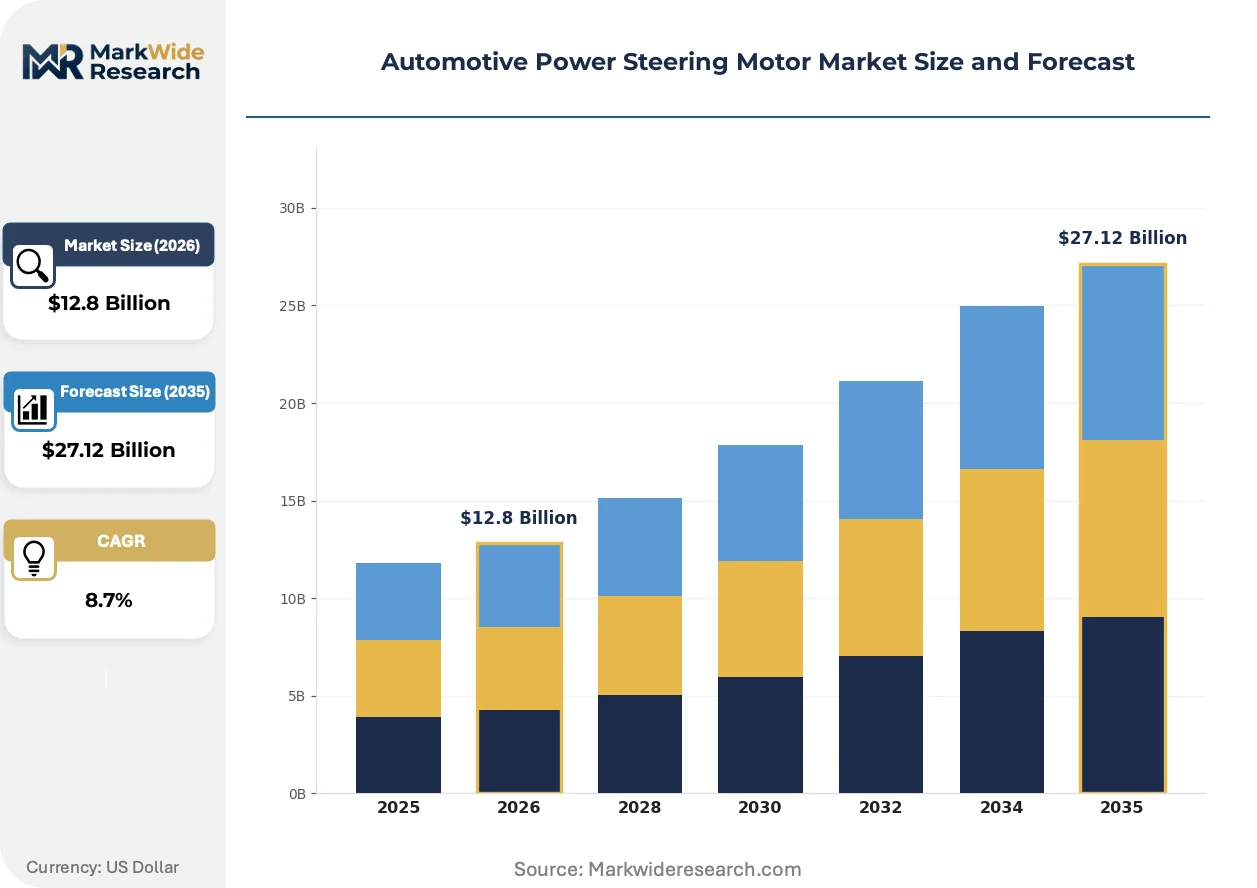
Market Dynamics
Electrification mandates and autonomous driving architectures are compressing the design cycle for steering motor suppliers, forcing simultaneous optimization for energy efficiency, functional safety, and software-defined control integration.
Growth Catalysts
- EU F-Gas Regulation:Tightened refrigerant rules cascade into thermal management demands that favor brushless DC motor architectures with superior heat dissipation profiles.
- Commercial vehicle fleet electrification:Heavy-duty platforms in North America and Europe are retrofitting hydraulic steering with electromechanical actuators to meet corporate fuel efficiency targets.
- Autonomous steering redundancy:ISO 26262 ASIL-D certification requirements for self-driving systems mandate dual-motor configurations that double per-vehicle motor content.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium processing capacity concentrates in China, exposing non-Chinese motor suppliers to input cost volatility and geopolitical supply risk.
- Copper price volatility:Winding wire represents 15-25% of bill-of-materials cost, and London Metal Exchange copper fluctuations compress margin predictability for tier-2 suppliers.
- Functional safety certification timeline:ASIL-D validation cycles extend 18-24 months, freezing design iterations and delaying platform approvals for new market entrants.
Strategic Opportunities
- India automotive production:PLI scheme incentives for electric vehicle manufacturing create localized demand for steering motor suppliers establishing captive facilities in Tamil Nadu and Gujarat.
- Software-defined vehicle convergence:Integration of steer-by-wire with centralized compute architectures enables motor suppliers to capture firmware and calibration service revenue streams.
- Aftermarket remanufacturing:Extended vehicle lifespans in Latin America and Southeast Asia create secondary demand for refurbished electronic power steering units with warranty-backed performance.
Industry Challenges
- Embedded software talent scarcity:Motor control algorithm development requires expertise in field-oriented control and functional safety standards that outpaces available engineering graduates in traditional manufacturing regions.
- Legacy platform integration friction:Retrofitting electromechanical steering into existing internal combustion architectures requires mechanical packaging compromises that degrade performance specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Power Steering Motor Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Brushless DC Motor, Synchronous Motor, Asynchronous Motor, Stepper Motor Vehicle Type: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, SUVs Power Rating: Low Power, Medium Power, High Power, Ultra High Power Application: Light Steering, Heavy Steering, Performance Steering, Autonomous Steering |
| Companies Covered | Robert Bosch GmbH, JTEKT Corporation, Nexteer Automotive Corp., ZF Friedrichshafen AG, DENSO Corp., Nidec Corp., NSK Ltd., Mitsubishi Electric Corp., Hyundai Mobis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Power Steering Motor Market Emerging Trajectories
Steering motor architectures are pivoting from standalone electromechanical components to software-integrated actuators, with thermal efficiency and cybersecurity hardening emerging as the primary vectors of supplier differentiation.
Permanent-magnet synchronous motors are overtaking conventional brushless DC designs in premium electric vehicle platforms. Nidec and Bosch have shifted R&D allocation toward synchronous architectures that enable energy recuperation during steering return-to-center maneuvers. This technology is overtaking incumbent solutions in the 400W+ segment where thermal efficiency directly impacts vehicle range certification.
EPA tailpipe standards and the EU AI Act are jointly tightening validation protocols for steering actuators in higher-autonomy vehicles. The EPA's fleet-wide emissions benchmarks indirectly mandate steering motor efficiency gains, while the EU AI Act's risk classification for automated driving systems imposes documentary burdens on functional safety evidence. Tier-1 suppliers serving both markets are consolidating certification workflows to reduce redundant testing cycles.
Fleet procurement departments are consolidating supplier relationships around vertically integrated motor-controller subsystem providers. Direct OEM purchasing of standalone motors is contracting as vehicle manufacturers outsource complete steering column assemblies to tier-1 integrators with in-house electronics manufacturing. This concentration is most visible in German and Japanese OEM supply chains, where platform sharing agreements accelerate standardization around preferred subsystem suppliers.
Automotive Power Steering Motor Market Segmentation
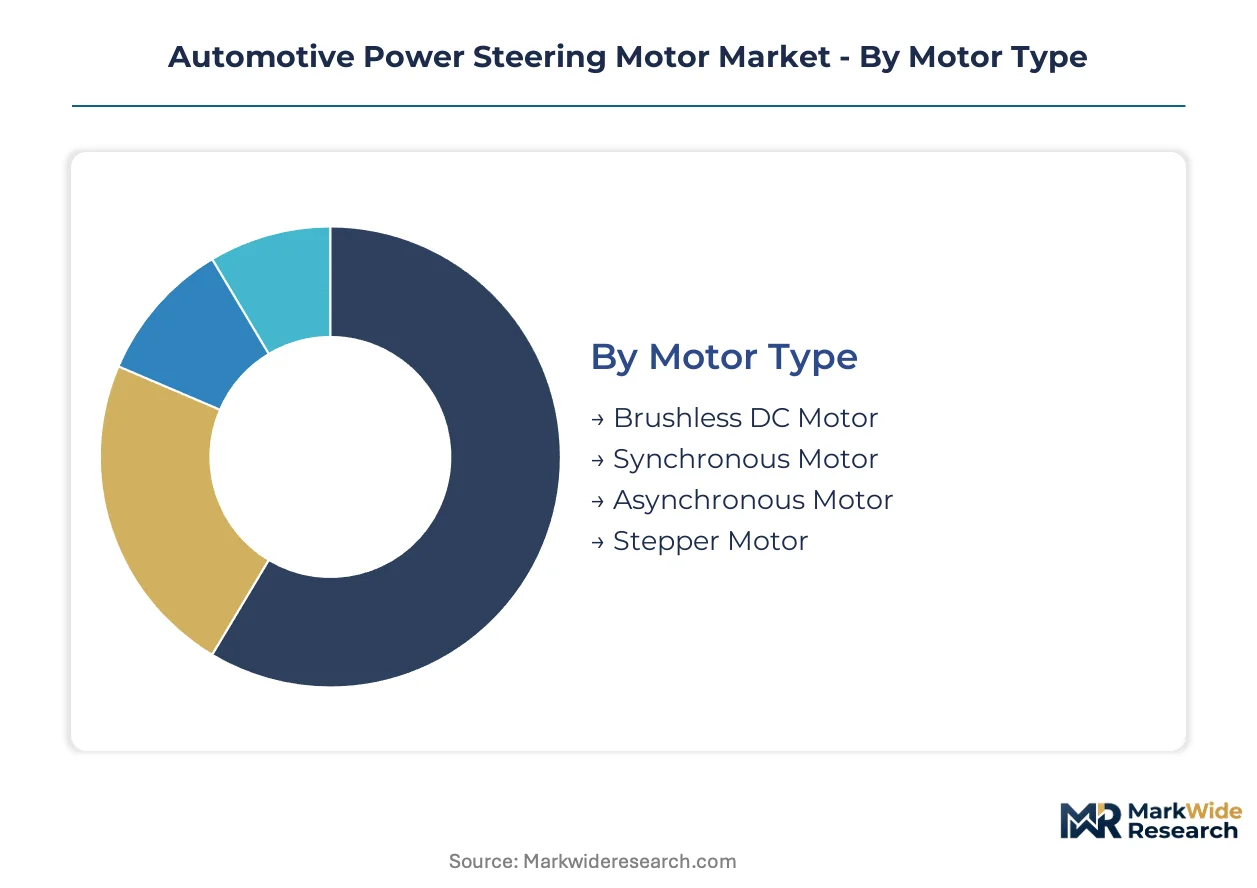
Steering motor suppliers configure product portfolios across four intersecting dimensions: electromagnetic architecture, vehicle platform characteristics, thermal-load specifications, and functional-safety requirements. Each axis carries distinct margin profiles and certification burdens that reshape competitive positioning.
Motor Type:
Electromagnetic design determines power density, thermal efficiency, and controller complexity.
- Brushless DC Motor:Permanent-magnet rotor with Hall-effect position sensing delivers 85-92% efficiency in 200-600W applications. Demand concentrates in mass-market passenger vehicles from Chinese and Japanese OEMs where cost-per-watt optimization dominates procurement. The architecture dominates current production volumes due to mature controller ecosystems and maintenance-free operation.
- Synchronous Motor:Field-oriented control enables energy recuperation during steering return-to-center maneuvers. Premium electric vehicle platforms specify synchronous designs for 400W+ segments where thermal efficiency directly impacts range certification under EPA fleet emissions benchmarks.
- Asynchronous Motor:Induction rotor eliminates rare-earth magnet dependency, reducing supply chain exposure to Chinese neodymium processing concentration.
- Stepper Motor:Open-loop control suits low-torque auxiliary steering applications in compact urban delivery vehicles with constrained packaging envelopes.
Brushless DC leads on scale; synchronous leads on momentum.
Vehicle Type:
Platform characteristics dictate motor sizing, environmental sealing, and duty-cycle specifications.
- Passenger Vehicles:Highest unit volumes with standardized 350-450W ratings for rack-and-pinion steering. European and Chinese OEMs drive specification convergence around modular column-integrated designs.
- Commercial Vehicles:Heavy-duty platforms require 600-800W actuators with IP6K9K sealing for underhood thermal exposure. North American fleet electrification mandates are retrofitting hydraulic systems with electromechanical units to meet corporate fuel efficiency targets.
- Electric Vehicles:Dedicated 48V or 400V architectures enable higher-efficiency synchronous motor integration with centralized thermal management.
- SUVs:Higher curb weights demand elevated torque output with reinforced bearing assemblies for off-road duty cycles.
Passenger vehicles anchor volume; commercial vehicles are climbing the fastest.
Power Rating:
Thermal-load segmentation aligns with vehicle mass, tire contact patch, and steering gear ratio requirements.
- Low Power:Sub-250W ratings serve A-segment city cars and light commercial vehicles in European urban mobility programs.
- Medium Power:250-450W range captures C-segment and D-segment passenger cars with electric power steering as standard fitment.
- High Power:450-650W segment addresses full-size SUVs and light commercial vehicles with higher steering rack loads.
- Ultra High Power:650W+ specifications serve heavy-duty trucks and autonomous platforms requiring redundant dual-motor configurations for ASIL-D compliance.
Medium power dominates unit economics; ultra high power shows steepest expansion trajectory.
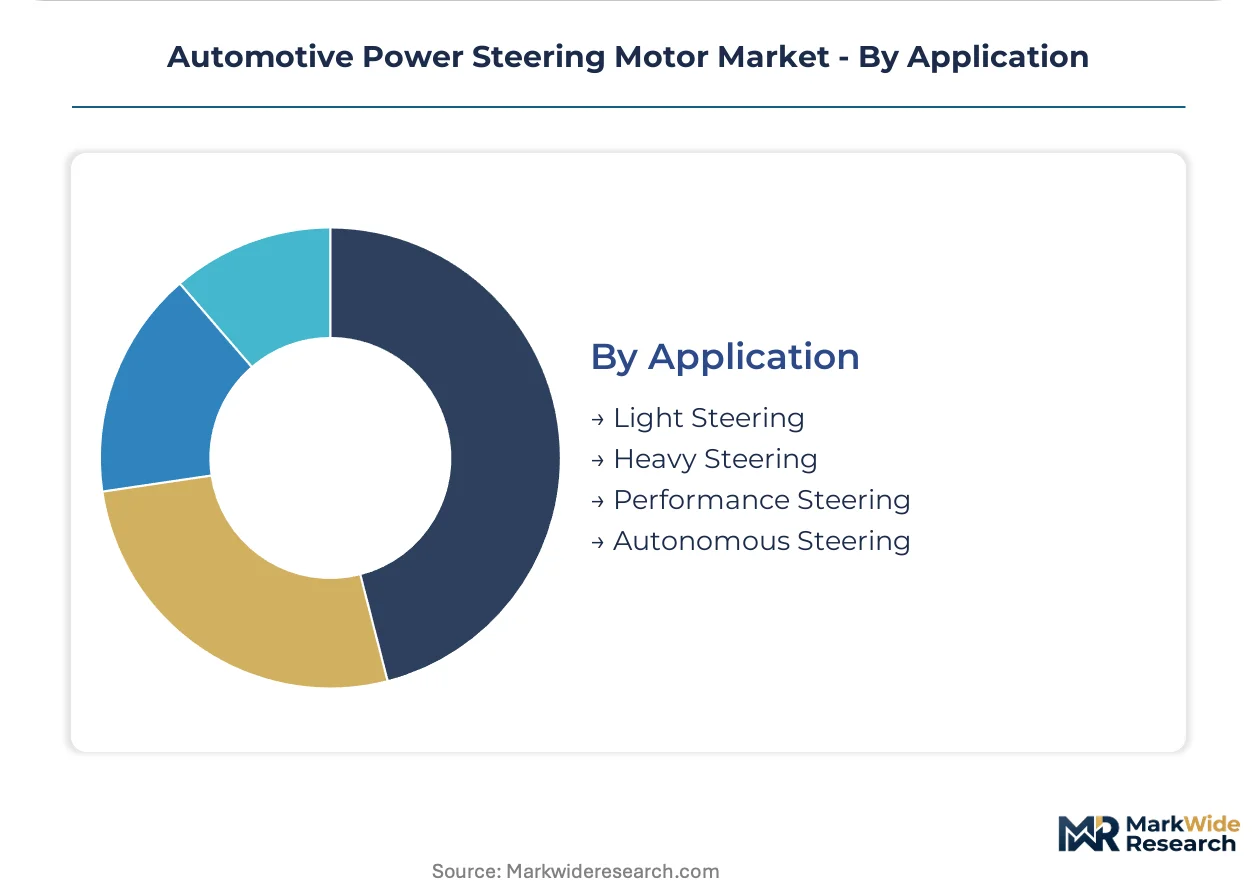
Application:
Functional-use cases determine control-loop complexity, sensor redundancy, and certification standards.
- Light Steering:Baseline electric power assistance for urban commuting with minimal highway-speed torque demand.
- Heavy Steering:Sustained high-load operation for towing and commercial hauling with enhanced thermal dissipation.
- Performance Steering:Variable ratio mapping and torque-vectoring integration for sport platforms requiring sub-50ms response latency.
- Autonomous Steering:ISO 26262 ASIL-D certification mandates dual-channel motor control with independent position sensing for SAE Level 4+ architectures.
Light steering sustains baseline revenue; autonomous steering commands premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Stuttgart, Shanghai, and Detroit anchor steering motor development. Supplier technical centers concentrate near OEM headquarters. Regional regulatory divergence shapes local product specifications.
United States
Commercial fleet electrification and autonomous vehicle testing drive demand for high-power steering actuators. EPA tailpipe standards tighten efficiency benchmarks that cascade into motor thermal specifications. Michigan's automotive corridor hosts supplier R&D facilities serving Detroit Three platform development.
Germany
Premium OEM platform sharing and steer-by-wire integration requirements elevate synchronous motor specifications. EU AI Act risk classifications impose documentary burdens on functional safety evidence for automated driving systems. Baden-Württemberg's supplier ecosystem concentrates electronics-integrated actuator manufacturing.
China
NEV production scale and domestic brand electrification create volume demand across all power ratings. MIIT energy efficiency benchmarks and dual carbon goals accelerate brushless DC motor adoption. Shanghai and Shenzhen production clusters concentrate tier-1 supplier manufacturing capacity.
Japan
Keiretsu supply relationships and compact vehicle packaging constraints favor high power-density motor designs. METI industrial standards and JIS certification requirements structure quality protocols. Nagoya and Tokyo metropolitan areas host integrated motor-controller subsystem development.
India
PLI scheme incentives for electric vehicle manufacturing attract steering motor suppliers establishing captive production. BIS automotive component standards and DGFT import substitution policies shape local sourcing requirements. Tamil Nadu and Gujarat automotive corridors concentrate emerging supplier assembly operations.
Automotive Power Steering Motor Market Vendor Landscape
The competitive structure tilts toward vertically integrated tier-1 subsystem providers with in-house electronics manufacturing. Three archetypes dominate: diversified industrial conglomerates with automotive divisions, specialized motor manufacturers with dedicated automotive facilities, and diversified tier-1 chassis suppliers extending into electromechanical actuation. Consolidation pressure intensifies as OEMs reduce supplier panels and demand complete steering column assemblies rather than standalone motors.
Among diversified industrial conglomerates, Robert Bosch GmbH and Mitsubishi Electric Corp. occupy positions spanning motor manufacturing through integrated controller production. Nidec Corp. exemplifies the specialized motor manufacturer archetype with dedicated automotive facilities. These three anchors represent distinct strategic postures: full-system integration, component specialization, and scale-driven manufacturing respectively.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| JTEKT Corporation |
| Nexteer Automotive Corp. |
| ZF Friedrichshafen AG |
| DENSO Corp. |
| Nidec Corp. |
| NSK Ltd. |
| Mitsubishi Electric Corp. |
| Hyundai Mobis |
| Others |
Supply Flow & Price Mechanics
ASIL-D certification bifurcation separates premium autonomous-grade motors from commodity passenger vehicle units, concentrating procurement power among tier-1 integrators who bundle electronics manufacturing with mechanical supply. This divergence concentrates margin capture in Germany and Japan where Bosch and Nidec maintain captive controller production, while Chinese suppliers compete on brushless DC unit cost without firmware differentiation.
Pricing Analysis
Bundled motor-controller subsystems command 40-60% premiums over standalone motor procurement as OEMs outsource complete steering column assemblies to tier-1 integrators. Three-tier pricing structure across premium synchronous, standard brushless DC, and economy brushed motor tiers reflects ISO 26262 certification grade and volume scale. Cost compression in the sub-400W passenger vehicle segment is intensifying because Chinese NEV platforms standardize around domestic supplier specifications. Fleet procurement departments at North American commercial vehicle operators show highest price sensitivity, while German premium OEMs prioritize thermal efficiency over unit cost.
Supply Chain Analysis
Warehouse-distribution layers concentrate in Stuttgart, Shanghai, and Detroit metropolitan zones where tier-1 technical centers co-locate with OEM headquarters. Rare earth magnet processing capacity centers on China, exposing non-Chinese motor suppliers to neodymium and dysprosium supply volatility. Copper winding wire and silicon steel laminations represent 25-35% of bill-of-materials cost, with London Metal Exchange fluctuations compressing margin predictability. Single-source vulnerability concentrates in Chinese rare earth processing. Distribution runs through just-in-time sequenced delivery direct to OEM assembly plants rather than aftermarket warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on synchronous motor premiumization and firmware service revenue capture, with thermal efficiency gains enabling pricing power against commodity brushless DC alternatives.
For Market Incumbents: Lock in platform standardization agreements with German and Japanese OEMs before steer-by-wire architectures consolidate supplier panels. Deepen backward integration into Hall-effect sensor and resolver manufacturing to defend against emerging Chinese electronics suppliers. Prioritize ASIL-D certification investment for autonomous steering contracts where dual-motor configurations double per-vehicle content. For New Entrants and Emerging Players: Induction motor architectures eliminating rare-earth magnet dependency offer a technology-first wedge into European commercial vehicle retrofit markets exposed to Chinese supply concentration. Target India's Tamil Nadu and Gujarat automotive corridors where PLI scheme incentives attract captive production facilities ahead of domestic NEV scale-up. Lead with aftermarket remanufacturing capabilities in Latin America where extended vehicle lifespans create warranty-backed refurbishment demand. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized motor manufacturers possessing dedicated automotive facilities and existing OEM qualification relationships. Five-to-ten year viability favors suppliers with synchronous motor R&D pipelines and software-defined vehicle firmware integration capabilities. Watch for tier-1 integrator consolidation announcements as OEMs reduce supplier panels around complete steering subsystem providers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | German OEM sharing agreements accelerate convergence around preferred synchronous motor specifications. |
| Software-Defined Vehicle Investment | Firmware and calibration service revenue streams capture recurring value beyond hardware supply. |
| Geographic Manufacturing Footprint | Captive facilities in Shanghai and Shenzhen production clusters secure NEV platform access. |
| Backward Integration into Electronics | In-house controller production defends margin against standalone motor commoditization. |
| Battery Supply Agreement | 48V and 400V architecture alignment with electric vehicle thermal management systems. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads with secondary validation. Vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed automotive suppliers, and MIIT energy efficiency disclosures provided foundational inputs. Bottom-up motor shipment estimates triangulated against top-down vehicle production forecasts across the analysis window.
Segment-weighting approaches applied differential growth assumptions by motor type, vehicle platform, power rating tier, and functional safety certification level. The analytical framework modeled brushless DC versus synchronous motor substitution curves, commercial vehicle electrification retrofit penetration, and autonomous steering redundancy requirements throughout the forecast period. CAGRs derived from regression analysis of historical shipment data against EPA fleet efficiency benchmarks and EU F-Gas Regulation compliance timelines.
The model holds under stable rare earth supply conditions and continued OEM platform sharing agreements; deviation in Chinese export restrictions or accelerated steer-by-wire standardization would shift trajectory. Forecasts reflect documented assumptions regarding NEV adoption curves and functional safety certification timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Electric Vehicle Motor (EVM) Controller Market
Electric Motor
Europe Electric Motor Market
Electric Motor
Electric Trolling Motors Market
Electric Motor
North America Electric Motor Market
Electric Motor
Traction Motor Core Market
Electric Motor
Intelligent Motor Control Market
Electric Motor
Starter Motor Market
Electric Motor
Global EV Motor Controller Market
Electric Motor
Australia Solar E-Bike Market
Electric Motor
Automotive Hub Motors Market
Electric Motor
Intelligent Motor Control Center Market
Electric Motor
Brazil Electrically Powered Hydraulic Steering Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Europe Alternating Current (AC) Motor Market
Electric Motor
Two Wheeler Electric Starter Magnet Market
Electric Motor
Traction Motors Market