
 Starter Motor Market | 2026-2036
Starter Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Starter Motor Market Outlook
Fleet consolidation among commercial vehicle operators is expanding the addressable market for high-durability starter systems. Denso Corporation leverages its integrated powertrain division to supply Japanese and North American OEMs with compact gear reduction units. Robert Bosch GmbH anchors European aftermarket channels through remanufactured starter programs and diagnostic-linked replacement services. Valeo Group competes on brushless technology leadership, positioning its synchronous motor designs for 48V mild-hybrid architectures.
A starter motor is an electromechanical device that converts electrical energy from a battery into mechanical torque to crank an internal combustion engine, typically operating at 12V or 24V with power outputs ranging from 0.8 kW to 7.5 kW depending on engine displacement. Gear reduction starters now dominate original equipment fitment due to their superior torque density and lighter packaging compared with conventional direct-drive units. Permanent magnet technology captures the fastest growth trajectory as automakers seek weight reduction for fuel efficiency compliance. The 48V power rating segment holds concentrated margin pools, though volume remains concentrated in 12V systems for passenger vehicles and light trucks.
EPA tailpipe regulations and NHTSA fuel economy standards in the United States compel OEMs to specify lighter, more efficient starter motors that reduce parasitic losses. The EU Green Deal and F-Gas Regulation indirectly shape demand by accelerating powertrain electrification, which alters starter motor duty cycles and thermal requirements. China's MIIT mandates domestic content ratios that push foreign suppliers to localize brushless motor production. Stakeholders must monitor how 48V electrical architecture proliferation redefines starter motor integration with belt-driven starter-generator systems.
Market Dynamics
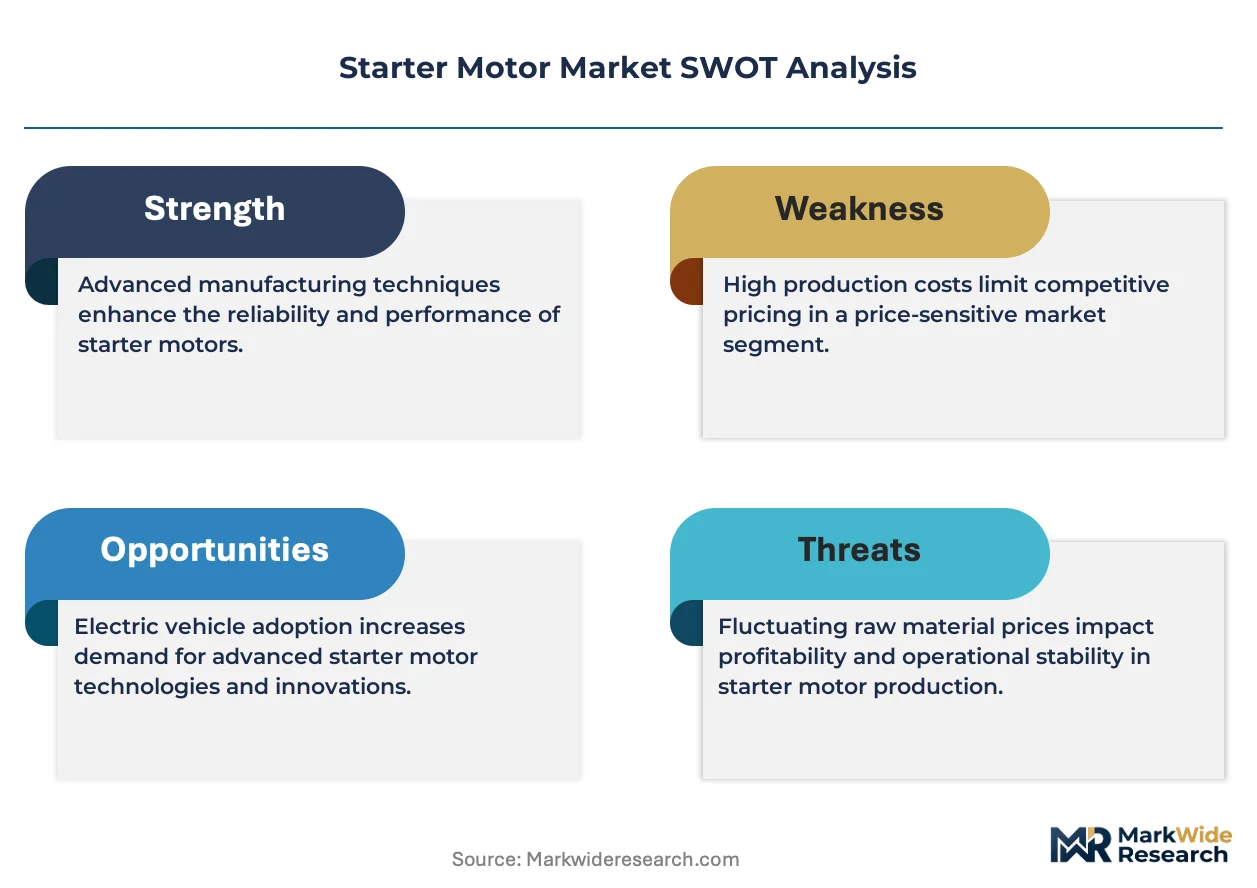
Brushless motor architectures are compressing product lifecycles across the starter motor value chain, forcing suppliers to retool manufacturing lines and rewrite thermal management specifications. The transition from wound-field to permanent magnet designs is redistributing margin pools toward magnet suppliers and specialized controller vendors.
Growth Catalysts
- EPA Phase 2 greenhouse gas standards:Commercial vehicle fleets in the United States face mandatory efficiency upgrades, expanding procurement of gear reduction starters with lower parasitic drag.
- China's MIIT domestic content mandates:Localization requirements push foreign suppliers to establish brushless motor production within Chinese industrial clusters, stimulating capital deployment.
- Permanent magnet technology:Neodymium-iron-boron magnet adoption enables weight reductions that directly improve fuel economy test cycles for passenger vehicle OEMs.
Market Restraints
- Neodymium supply concentration:Rare earth processing capacity clusters in China's Inner Mongolia region, exposing motor manufacturers to export quota volatility and price spikes.
- Copper winding cost inflation:Conventional brushed starter production remains exposed to London Metal Exchange copper price swings that compress assembler margins.
- 48V system substitution:Belt-driven starter-generator integration in mild-hybrid architectures threatens discrete starter motor volumes in European premium segments.
Strategic Opportunities
- India's commercial vehicle electrification gap:Medium-duty truck fleets lag in starter system refresh cycles, creating aftermarket penetration potential for brushless retrofit kits.
- Brazil's ANVISA automotive emission enforcement:Tighter tailpipe testing protocols force local OEMs toward precision-engineered starters with reduced voltage drop.
- Remanufactured channel expansion:Diagnostic-linked replacement services unlock recurring revenue streams independent of new vehicle production cycles.
Industry Challenges
- Brushless controller firmware certification:Functional safety validation under ISO 26262 stretches development timelines and requires specialized embedded systems talent.
- Legacy 12V system integration:Electromagnetic compatibility testing for synchronous motor designs against existing vehicle electrical architectures consumes engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Starter Motor Market |
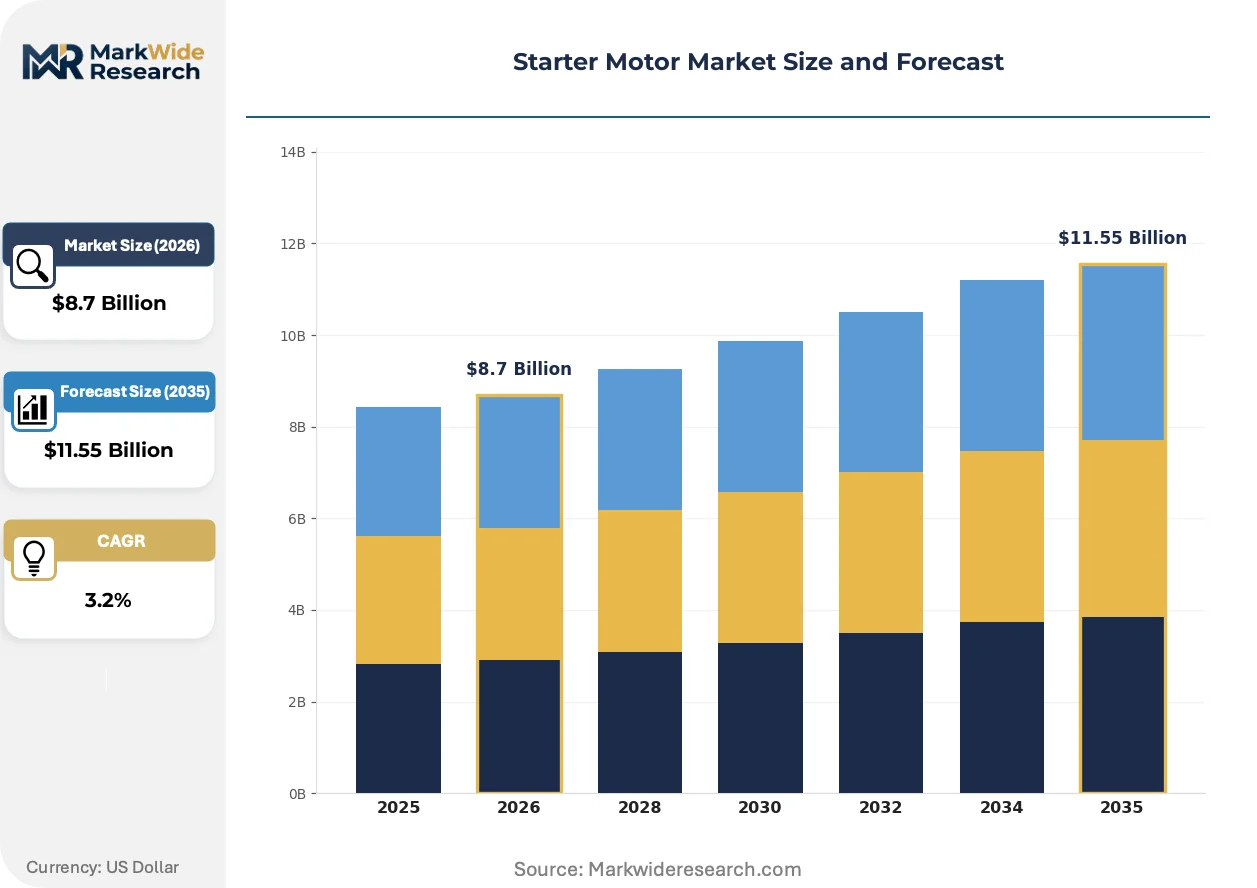
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.55 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gear Reduction, Permanent Magnet, Conventional, Adjustable Speed End User: Automobile Manufacturers, Aftermarket Providers, OEMs, Industrial Equipment Power Rating: 12V, 24V, 36V, 48V Technology: Electromechanical, Brushless, Synchronous, DC Motor |
| Companies Covered | Denso Corporation, Robert Bosch GmbH, Valeo Group, Mitsubishi Electric Corporation, Hitachi Astemo Ltd., Cummins Inc., Mitsuba Corporation, BorgWarner Inc., MAHLE Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Starter Motor Market Strategic Shifts
Starter motor architectures are fragmenting across voltage classes and thermal envelopes, with 48V mild-hybrid integration forcing redesigns of mechanical packaging and electronic control strategies. Suppliers must now engineer for dual-mode operation spanning cold-crank torque delivery and sustained generation duty.
Permanent magnet synchronous motor technology is modularizing starter system supply chains by separating magnet rotor fabrication from final assembly. Tier-1 suppliers in Japan and Germany are adopting sub-assembly outsourcing for magnet-containing rotors while retaining controller integration in-house. This architecture enables faster platform variants without full production line retooling.
The EU F-Gas Regulation is accelerating thermal management redesigns by restricting refrigerants used in vehicle climate systems that share mounting envelopes with starter motors. European OEMs now specify expanded operating temperature ranges that push suppliers toward enhanced encapsulation resins and improved heat sink geometries. Aftermarket channels face inventory complexity as regional thermal specifications diverge.
Fleet operators are consolidating procurement through telematics-linked predictive maintenance platforms that unbundle starter replacement from scheduled service intervals. North American commercial vehicle lessors now source starters through usage-based contracts tied to actual crank cycle counts rather than calendar-based replacement. This compresses supplier cash conversion cycles while rewarding durability performance with contract renewals.
Starter Motor Market Segmentation
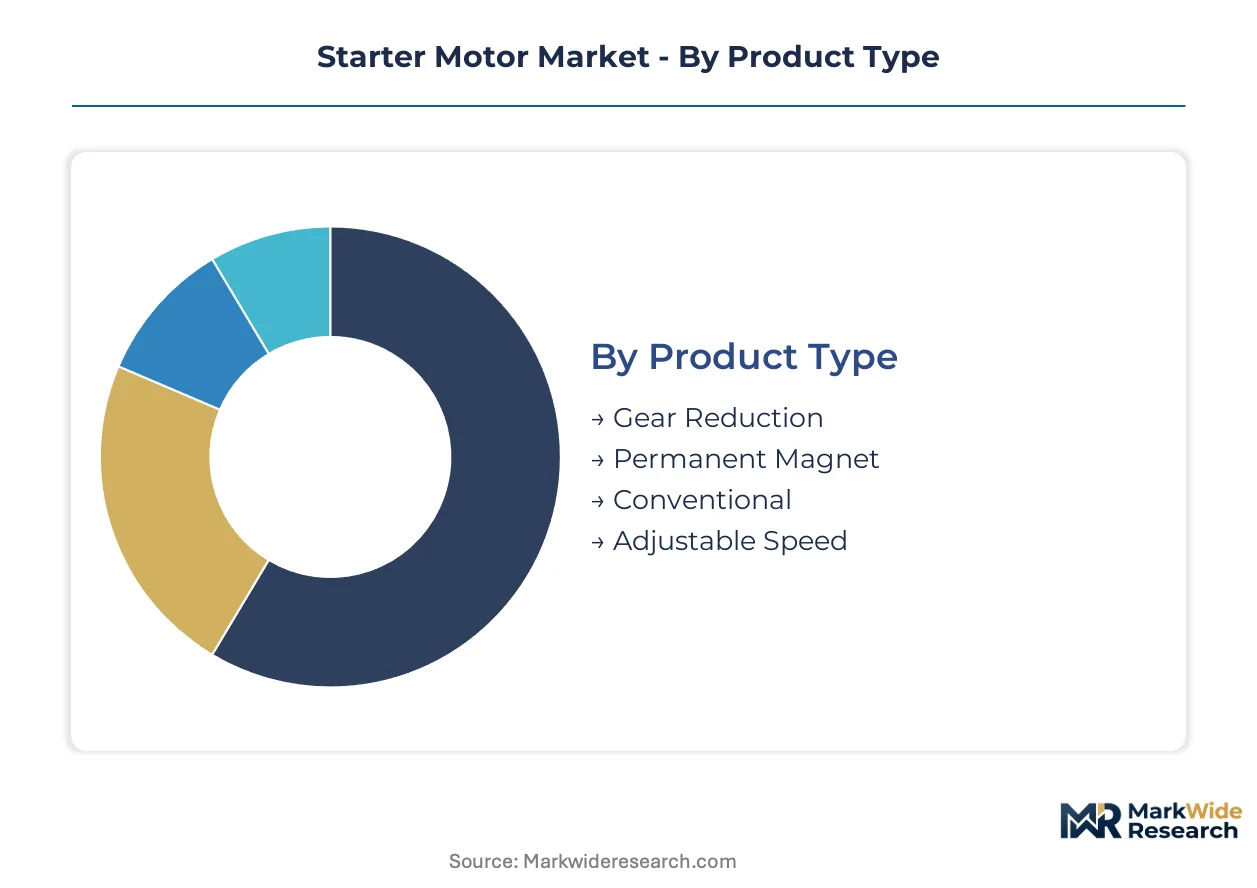
Starter motor procurement patterns diverge sharply across voltage classes and thermal envelopes, with each segment carrying distinct certification burdens and integration complexity. Understanding these fault lines enables suppliers to allocate engineering resources toward the highest-margin configuration clusters.
Product Type:
ISO 26262 functional safety validation applies differentially across this category, with brushless architectures requiring ASIL-D certification for 48V systems while conventional brushed units face lower electromagnetic compatibility thresholds.
- Gear Reduction:Planetary gearsets multiply torque output through 4:1 to 5:1 ratios, enabling smaller motor packages for commercial vehicle applications. Fleet operators in the United States specify these units to meet EPA Phase 2 greenhouse gas standards through reduced parasitic drag during non-cranking operation.
- Permanent Magnet:Neodymium-iron-boron rotors deliver superior power density, though magnet supply concentration in China's Inner Mongolia region exposes assemblers to export quota volatility. Passenger vehicle OEMs specify these for weight reduction credits in fuel economy test cycles.
- Conventional:Wound-field designs persist in price-sensitive aftermarket channels and legacy vehicle parc maintenance.
- Adjustable Speed:Variable frequency control enables soft-start torque profiles that reduce mechanical stress on engine components during cold weather operation.
Gear Reduction sits at the top of the volume ranking, with Permanent Magnet climbing the fastest.
End User:
Procurement scale and technical specification authority vary dramatically across this dimension, with automobile manufacturers dictating thermal envelopes while aftermarket providers prioritize inventory velocity over performance margins.
- Automobile Manufacturers:Tier-1 suppliers integrate starter systems at powertrain assembly plants, with contract terms tied to platform lifecycle volumes spanning eight to twelve years.
- Aftermarket Providers:Remanufactured starter programs generate recurring revenue through diagnostic-linked replacement services independent of new vehicle production cycles.
- OEMs:Original equipment specifications for commercial vehicle fleets emphasize crank cycle durability over weight minimization.
- Industrial Equipment:Stationary engine applications in construction and agriculture demand 24V systems with extended duty cycles for high-displacement diesel architectures.
Automobile Manufacturers command the largest procurement volumes, with Aftermarket Providers expanding most quickly through predictive maintenance platform integration.
Power Rating:
Voltage class selection determines electromagnetic compatibility testing scope and controller firmware complexity, with 48V systems requiring dual-mode engineering for both cranking and generation duty.
- 12V:Passenger vehicles and light trucks retain this standard, with ISO 16750-2 electrical load testing governing transient voltage immunity.
- 24V:Commercial vehicle fleets specify this rating for medium-duty and heavy-duty diesel engines, particularly in North American and European long-haul applications.
- 36V:Transitional architectures in mild-hybrid development programs face uncertain standardization.
- 48V:Belt-driven starter-generator integration demands synchronous motor designs with expanded operating temperature ranges under EU F-Gas Regulation thermal management constraints.
12V dominates absolute unit shipments, with 48V gaining share fastest through mild-hybrid architecture proliferation.
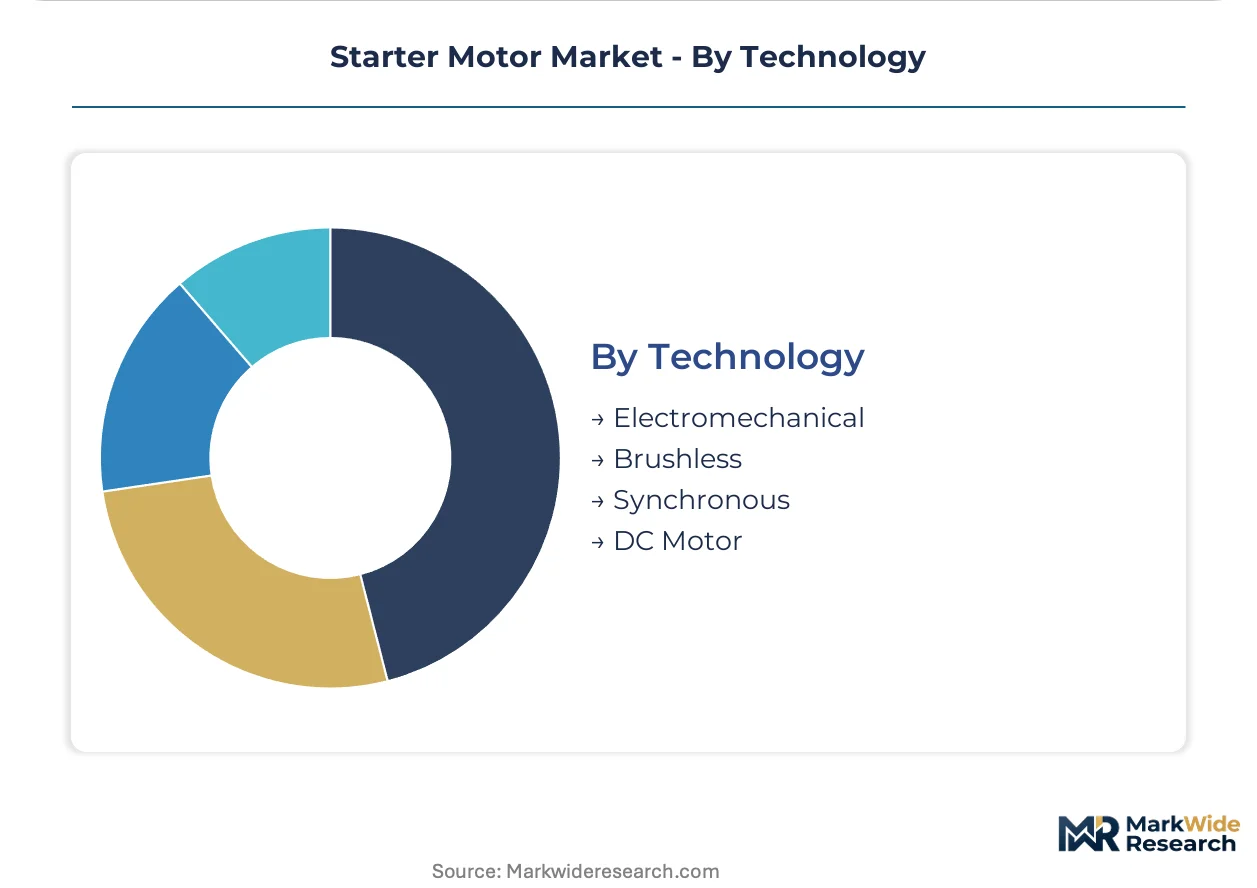
Technology:
Controller firmware certification timelines stretch development schedules disproportionately for brushless and synchronous variants, while electromechanical legacy designs face compressed margins from copper winding cost inflation.
- Electromechanical:Brushed commutator systems persist in cost-optimized applications where controller complexity must be minimized.
- Brushless:Electronic commutation eliminates mechanical wear, extending service intervals for commercial vehicle fleet operators monitoring total cost of ownership.
- Synchronous:Rotor position sensing enables precise torque control for 48V mild-hybrid systems with belt-driven starter-generator packaging.
- DC Motor:Series-wound architectures retain niche applications in industrial equipment with extreme cold-crank requirements.
Electromechanical retains volume leadership, with Brushless expanding most quickly as OEMs specify longer service intervals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands starter motor production volume through domestic OEM localization mandates, while Germany anchors European engineering specifications for brushless architectures. Japan and the United States split innovation leadership across permanent magnet and gear reduction technologies respectively.
China
Domestic OEMs localize brushless motor production to reduce import dependency under MIIT domestic content mandates. The country's dual carbon goals accelerate powertrain electrification, altering starter motor duty cycles for hybrid platforms. Shanghai and Chongqing industrial clusters host foreign supplier joint ventures producing neodymium-iron-boron rotor sub-assemblies.
Germany
European OEMs specify expanded operating temperature ranges under EU F-Gas Regulation thermal management constraints. KBA enforces stringent electromagnetic compatibility testing for 48V belt-driven starter-generator integration. Stuttgart and Munich engineering centers develop synchronous motor designs for mild-hybrid premium vehicle architectures.
United States
Commercial vehicle fleets upgrade starter systems to meet EPA Phase 2 greenhouse gas standards through reduced parasitic drag. NHTSA fuel economy standards compel lighter, more efficient starter motor specifications. Detroit and Chicago industrial corridors concentrate remanufactured starter program capacity for aftermarket predictive maintenance platforms.
Japan
METI supports permanent magnet technology development for weight reduction credits in fuel economy compliance. JIS standards govern ISO 26262 functional safety validation for brushless controller firmware. Nagoya and Osaka manufacturing bases supply compact gear reduction units to North American and domestic OEM powertrain divisions.
India
Medium-duty truck fleets lag in starter system refresh cycles, creating aftermarket penetration potential for brushless retrofit kits. BIS certification requirements for automotive electrical components tighten quality thresholds. Pune and Chennai industrial clusters attract foreign suppliers establishing localized assembly for domestic commercial vehicle OEMs.
Starter Motor Market Competitive Environment
Japanese producers anchor one tier; European specialists hold engineering-intensive positions; North American fabricators dominate remanufactured aftermarket channels. The vendor base splits between integrated powertrain divisions and standalone motor specialists. Three archetypes emerge: magnet-integrated rotor fabricators, diagnostic-linked service providers, and compact packaging engineers. Capacity expansion and strategic partnerships constitute the dominant competitive moves across all tiers.
Within the integrated powertrain tier, Denso Corporation and Robert Bosch GmbH exemplify geographic anchoring strategies, with the former representing Japanese OEM supply relationships and the latter occupying European aftermarket channel positions. Valeo Group sits within the brushless technology leadership archetype, reflecting synchronous motor specialization for voltage architecture transitions. These three entities collectively illustrate how regional regulatory exposure—MIIT mandates, EU F-Gas Regulation, EPA Phase 2 standards—shapes competitive positioning without converging on identical capability portfolios.
| Leading Market Players |
|---|
| Denso Corporation |
| Robert Bosch GmbH |
| Valeo Group |
| Mitsubishi Electric Corporation |
| Hitachi Astemo Ltd. |
| Cummins Inc. |
| Mitsuba Corporation |
| BorgWarner Inc. |
| MAHLE Group |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Japan and Germany anchor tier-2 supply positions, translating generational balance-sheet discipline into stable contract pricing for neodymium-iron-boron rotors. Their refusal to absorb copper winding cost spikes forces pricing adjustments downstream to aftermarket distributors and fleet procurement officers.
Pricing Analysis
Capacity additions in China are reshaping price floors for brushless motor controllers as MIIT-mandated localization spawns competing domestic rotor fabricators. Contract-based long-term offtake dominates OEM procurement, while spot-market transactions persist for aftermarket emergency replacement. Price differentiation rests on ISO 26262 certification tier and crank-cycle durability guarantees. Cost compression in conventional brushed units is intensifying because London Metal Exchange copper volatility squeezes assembler margins. Fleet operators exhibit highest price sensitivity; premium passenger vehicle OEMs prioritize weight-reduction credits over unit cost.
Supply Chain Analysis
Remanufacturing flows from North American commercial vehicle depots now feed diagnostic-linked replacement programs, compressing supplier cash conversion cycles. Magnet rotor fabrication concentrates in China, Japan, and Germany, with controller assembly tethered to customer proximity. Supply chains draw from neodymium-iron-boron magnets, copper windings, and silicon steel laminations. Single-source vulnerability in China's Inner Mongolia rare earth processing exposes assemblers to export quota volatility. Distribution runs through Tier-1 powertrain divisions and specialized aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EPA Phase 2 greenhouse gas standards mandating efficiency upgrades that expand procurement of gear reduction starters across commercial vehicle fleets.
For Market Incumbents: Extend service-interval guarantees through brushless controller firmware upgrades to defend against 48V belt-driven starter-generator substitution. Secure captive magnet supply through joint ventures in Shanghai and Chongqing industrial clusters. Denso Corporation and Robert Bosch GmbH illustrate how integrated powertrain divisions leverage platform lifecycle contracts spanning eight to twelve years. For New Entrants and Emerging Players: Aftermarket telematics platforms offer the most penetrable entry vector, particularly for brushless retrofit kits targeting India's medium-duty truck fleets. Brazil's ANVISA emission enforcement creates demand for precision-engineered starters with reduced voltage drop. Partner with predictive maintenance software vendors to bypass entrenched Tier-1 supply relationships. For Investors and Strategic Acquirers: Integrated powertrain divisions are the most active acquirer in this space, seeking brushless controller firmware capabilities and magnet-integrated rotor fabrication. The five-to-ten-year viability window favors suppliers with ASIL-D certification infrastructure and dual-mode 48V engineering capacity. Monitor 48V mild-hybrid architecture proliferation as the inflection indicator for discrete starter motor volume displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless Controller Firmware Certification | ASIL-D validation under ISO 26262 opens 48V mild-hybrid procurement channels at European premium OEMs. |
| Magnet Rotor Joint Venture | Localized neodymium-iron-boron fabrication satisfies China's MIIT domestic content mandates for foreign suppliers. |
| Remanufactured Channel Expansion | Diagnostic-linked replacement services generate recurring revenue independent of new vehicle production cycles. |
| Predictive Maintenance Platform Integration | Telematics-linked procurement unbundles starter replacement from calendar-based service intervals for fleet operators. |
| Dual-Mode 48V System Engineering | Synchronous motor designs with expanded thermal ranges meet EU F-Gas Regulation constraints for belt-driven starter-generators. |
Study Parameters
Direct dialogue with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet maintenance directors grounded this analysis in operational reality. Secondary validation drew from EPA regulatory filings, NHTSA fuel economy standard documentation, vehicle production databases, and customs trade records for neodymium and copper inputs. Bottom-up segment sizing triangulated against top-down powertrain production forecasts.
Segmented outputs across voltage class, motor architecture, end-user procurement authority, and regional regulatory cluster informed the analytical framework over the projection horizon. CAGRs were derived from platform lifecycle volume assumptions and technology substitution curves. Forecast inputs included MIIT localization mandate compliance timelines and EPA Phase 2 fleet turnover rates.
Revisions become necessary when rare earth export quotas tighten, 48V mild-hybrid adoption accelerates beyond base-case assumptions, or copper price volatility triggers contract renegotiation waves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Brazil Electrically Powered Hydraulic Steering Market
Electric Motor
China E-Bike (Pedelec Bikes) Hub Motor Market
Electric Motor
United States AC Motor Market
Electric Motor
US Solar E-Bike Market
Electric Motor
Traction Motors Market
Electric Motor
Electric Vehicle Flat Wire Motor Market
Electric Motor
Intelligent Motor Control Market
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Torque Motor Market
Electric Motor
Automotive in-Wheel Motors Market
Electric Motor
Electric Vehicle Motor (EVM) Controller Market
Electric Motor
Global Automotive Motor Market
Electric Motor
Global in-Wheel Motors Market
Electric Motor
Traction Motor Core Market
Electric Motor
Garden Tool Lithium Battery Market