
 APAC Electric Drives Market | 2026-2036
APAC Electric Drives Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Electric Drives Market Outlook
The gap between silicon-based inverters and silicon carbide power modules is narrowing as foundries across Asia-Pacific expand wide-bandgap capacity. ABB Ltd. leverages its robotics-automation integration to anchor premium servo drive contracts with automotive OEMs in Japan and South Korea. Siemens AG sustains engineering depth across induction and brushless platforms, competing on firmware-defined motor control architectures.
Electric drives are electromechanical systems that convert electrical energy into controlled mechanical motion through variable frequency operation, typically spanning 0.1 kW to multi-megawatt ratings with efficiency thresholds now governed by IE4 and IE5 class standards. AC Motors dominate installed base volumes across HVAC Systems and Industrial Automation applications where retrofit cycles extend replacement demand. Servo Motors occupy the fastest-expanding margin pool in Robotics and Electric Vehicles, where closed-loop precision and regenerative braking integration command price premiums over standard induction units.
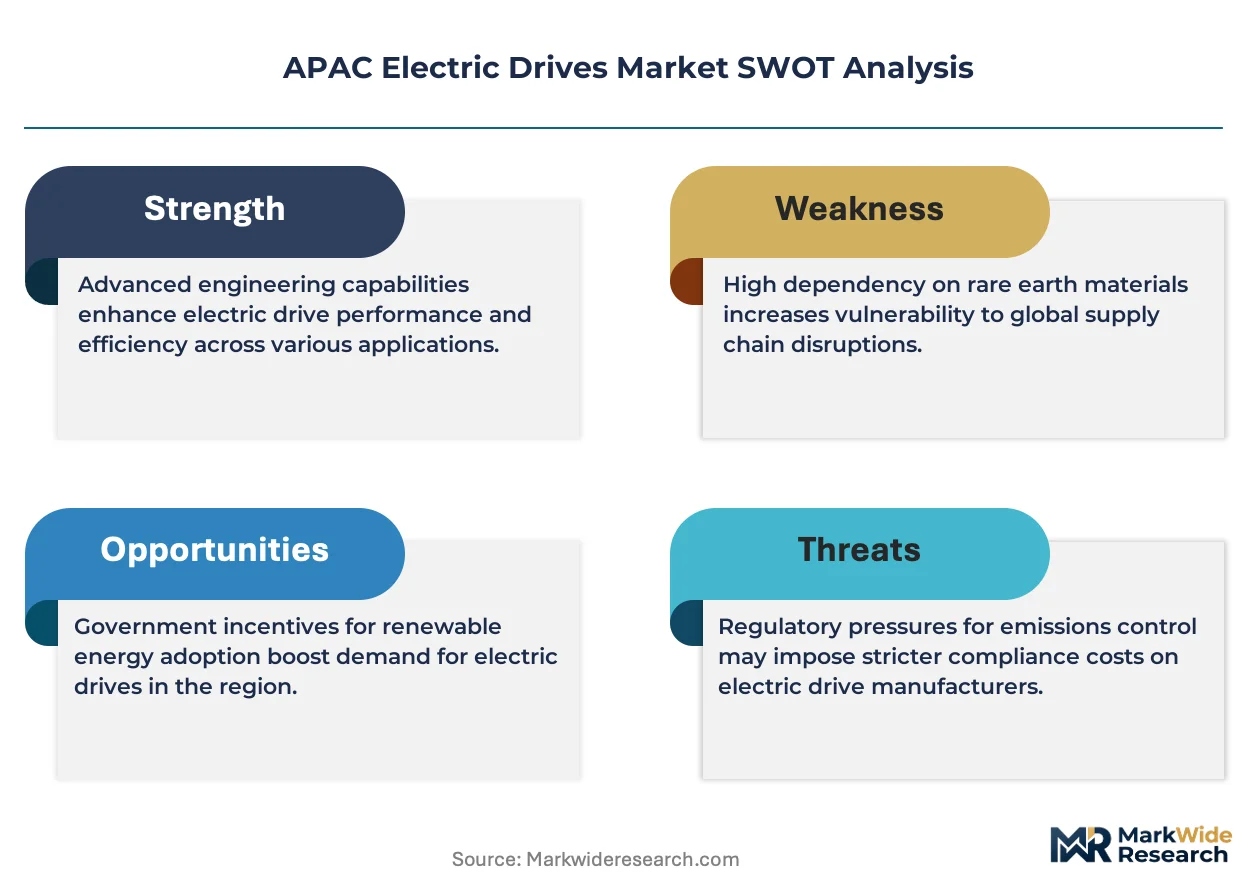
China's MIIT enforces GB motor efficiency standards that phase out IE2-class products from industrial procurement, while India's BIS aligns with IS 12615 efficiency norms under Bureau of Energy Efficiency directives. Japan's METI subsidizes SiC inverter adoption through green innovation funds, tightening product entry requirements for non-domestic suppliers. Stakeholders must weigh localized certification paths against platform standardization strategies as regulatory divergence across China, India, and Japan deepens compliance complexity.
Market Dynamics
The transition from silicon IGBTs to silicon carbide MOSFETs is compressing inverter footprints and switching losses, forcing incumbent suppliers to retool foundry partnerships across the Yangtze River Delta and Korea's Pangyo semiconductor cluster.
Growth Catalysts
- MIIT GB Efficiency Standards:China's phase-out of IE2-class motors from state procurement is accelerating replacement cycles in steel mills and chemical plants.
- EV Powertrain Integration:Brushless permanent magnet motors are capturing design wins in passenger vehicle traction systems across Japan, South Korea, and China's NEV manufacturers.
- India's PLI Scheme for Manufacturing:Production-linked incentives for advanced automotive components are drawing servo drive assembly into Gujarat and Tamil Nadu.
Market Restraints
- Rare Earth Magnet Dependency:Neodymium and dysprosium supply concentration in China's Inner Mongolia mining belt creates price volatility and geopolitical sourcing risk for permanent magnet motors.
- Wide-Bandgap Wafer Shortage:SiC substrate capacity constraints at Asian foundries are extending lead times for high-efficiency inverter modules beyond 26 weeks.
- Cross-Border Certification Friction:Divergent BIS, JIS, and GB testing protocols force manufacturers to maintain three parallel validation streams for regional product releases.
Strategic Opportunities
- Indonesia's Nickel Processing Expansion:Downstream battery and motor material refining is creating localized demand for medium-voltage drives in smelter automation.
- Regenerative Braking Integration:Bi-directional power flow capability in servo systems opens aftermarket retrofit potential for material handling equipment in Vietnam's port logistics sector.
- Edge Computing Convergence:Embedded motor control algorithms running on ARM-based SoCs are enabling predictive maintenance subscriptions as a recurring revenue layer.
Industry Challenges
- Firmware Talent Scarcity:Field-oriented control algorithm expertise and SiC gate driver design skills are concentrated among a small pool of engineers in Tokyo, Seoul, and Shanghai.
- Legacy System Integration:Retrofitting IE4 motors into decades-old induction motor infrastructures requires mechanical redesign and harmonic filtering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Electric Drives Market |
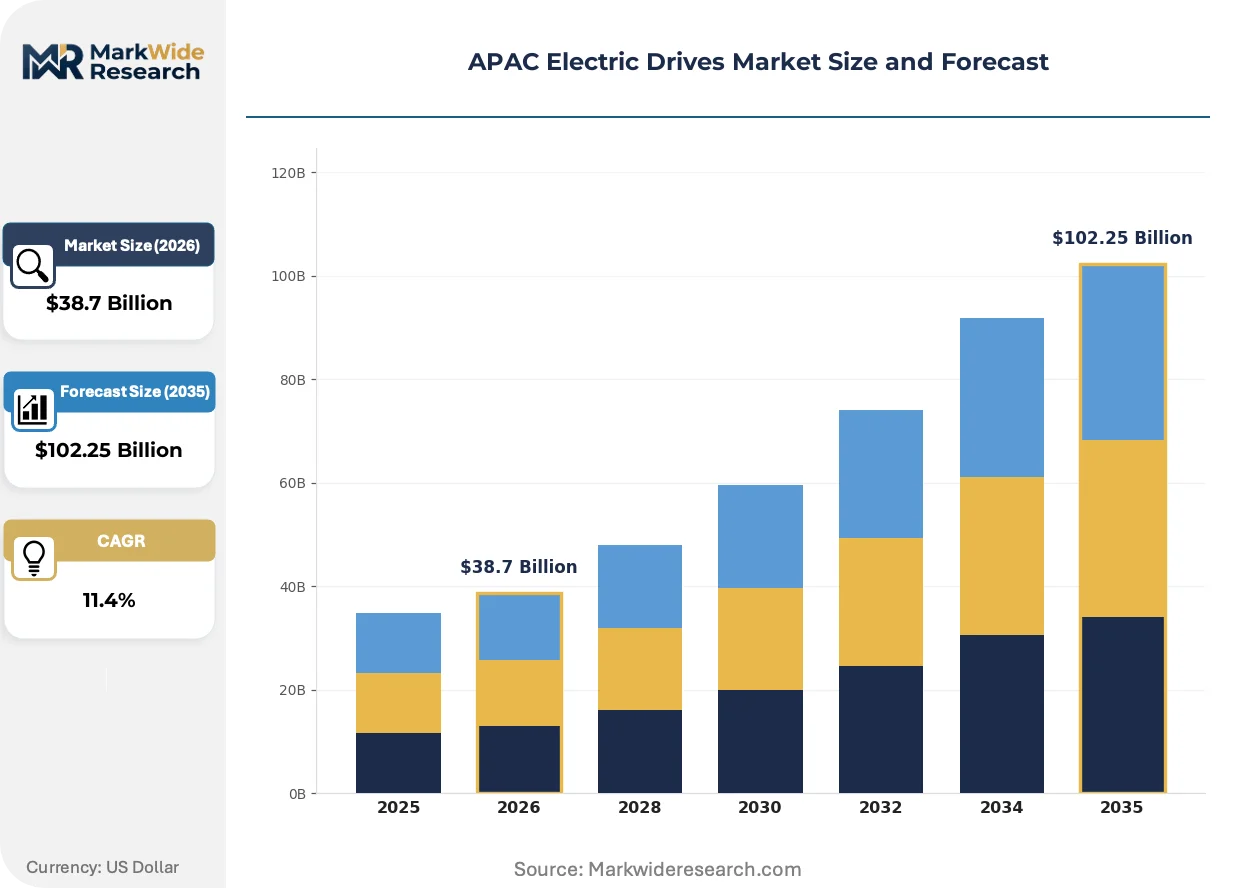
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Servo Motors, Stepper Motors End User: Automotive, Manufacturing, Renewable Energy, Robotics Technology: Brushless, Induction, Linear, Switched Reluctance Application: Electric Vehicles, Industrial Automation, HVAC Systems, Conveyors |
| Companies Covered | ABB Ltd., Siemens AG, Schneider Electric SE, Nidec Corporation, Danfoss A/S, Rockwell Automation Inc., Mitsubishi Electric Corporation, TMEIC Corporation, Yaskawa Electric Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Electric Drives Market Strategic Shifts
Digital twin architectures and physics-based motor modeling are compressing development cycles and enabling remote diagnostics that reduce field service dispatch frequency across distributed industrial assets.
Silicon carbide power modules are digitizing thermal management and switching dynamics in multi-kilowatt inverters. Japanese automotive Tier-1 suppliers are adopting 800V SiC traction inverters for next-generation EV platforms. This transition is digitizing the boundary between power electronics and real-time control software, collapsing traditional hardware-software procurement silos.
METI's green innovation fund subsidies for SiC inverter adoption are tightening product entry requirements for non-domestic suppliers seeking Japanese industrial certification. Domestic OEMs are accelerating local content quotas in response. The machine tool and robotics segments bear the highest compliance burden as efficiency mandates tighten through 2027.
Asset-as-a-service contracting is displacing capital purchase models for high-precision servo systems in South Korean electronics manufacturing. System integrators are bundling predictive maintenance algorithms with hardware leases, transferring operational risk from end-users to OEM balance sheets. This shift is most visible in Seoul-Incheon semiconductor fabrication and flat-panel display assembly lines.
APAC Electric Drives Market Segmentation
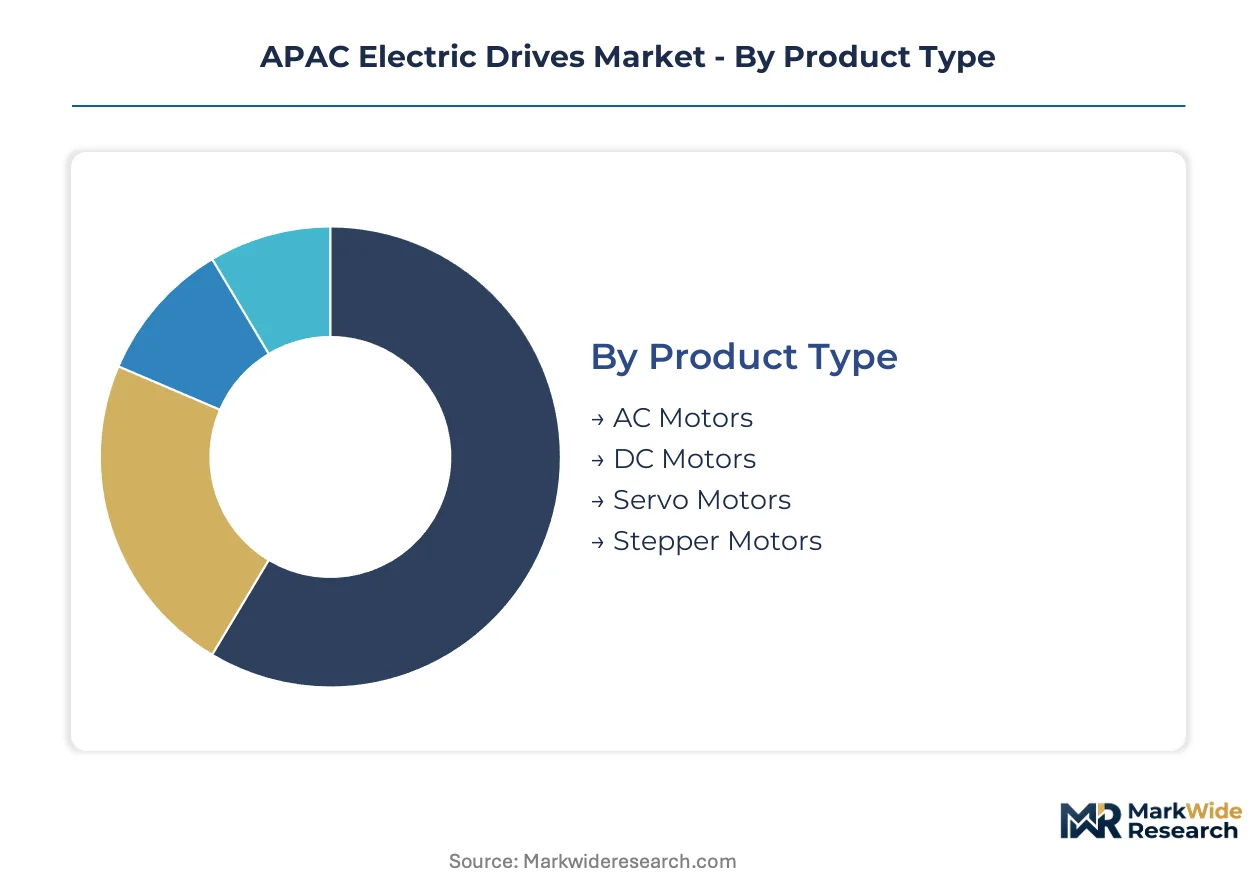
Electric drives span a wide performance and cost spectrum across Asia-Pacific, from commodity induction units in bulk manufacturing to precision servo systems in semiconductor fabrication. Understanding how product architectures, end-use requirements, and technology choices intersect reveals where procurement budgets concentrate and where supplier margins diverge.
Product Type:
The use-case spectrum ranges from continuous-duty industrial pumps to high-dynamic robotics axes, with motor topology determining efficiency ceiling and control complexity.
- AC Motors:Induction-based designs dominate HVAC Systems and pump applications across China's Yangtze River Delta manufacturing belt. Replacement cycles in aging industrial infrastructure sustain volume demand despite lower unit margins.
- Servo Motors:Closed-loop permanent magnet systems capture design wins in South Korean electronics assembly and Japanese machine tool sectors. MIIT efficiency mandates and METI green innovation subsidies accelerate displacement of open-loop alternatives in precision automation.
- DC Motors:Brushed architectures persist in cost-sensitive material handling equipment where maintenance access permits periodic brush replacement.
- Stepper Motors:Open-loop positioning systems retain niche adoption in laboratory automation and small-format 3D printing equipment.
Established volume favors AC Motors; emerging adoption favors Servo Motors.
End User:
Customer procurement patterns split between capital-intensive automotive programs and efficiency-driven industrial retrofit cycles.
- Automotive:NEV manufacturers in China, Japan, and South Korea specify brushless permanent magnet traction motors with integrated SiC inverters. India's PLI scheme for advanced automotive components draws servo drive assembly into Gujarat and Tamil Nadu supplier parks.
- Manufacturing:Steel mills and chemical plants across China's industrial corridor face MIIT-mandated IE2 phase-outs, triggering replacement demand for IE4-class induction systems.
- Renewable Energy:Wind turbine pitch control and solar tracking systems deploy medium-voltage drives in coastal provinces.
- Robotics:Collaborative robot joints and semiconductor wafer handling require harmonic-free torque control with regenerative braking integration.
Manufacturing commands the largest installed base; Automotive climbs the fastest.
Technology:
Power electronics architecture determines thermal performance, switching frequency, and firmware control complexity.
- Brushless:Permanent magnet synchronous designs with field-oriented control algorithms dominate EV traction and robotics applications. Neodymium supply concentration in China's Inner Mongolia mining belt creates sourcing volatility for magnet-dependent architectures.
- Induction:Squirrel-cage rotor designs persist in pumps, compressors, and fans where cost minimization outweighs efficiency premiums.
- Linear:Direct-drive electromagnetic propulsion systems serve precision positioning stages in flat-panel display manufacturing.
- Switched Reluctance:Magnet-free topologies attract interest for rare-earth-independent traction motor designs, though torque ripple limits adoption in passenger vehicle applications.
Induction retains cost leadership; Brushless gains share fastest.
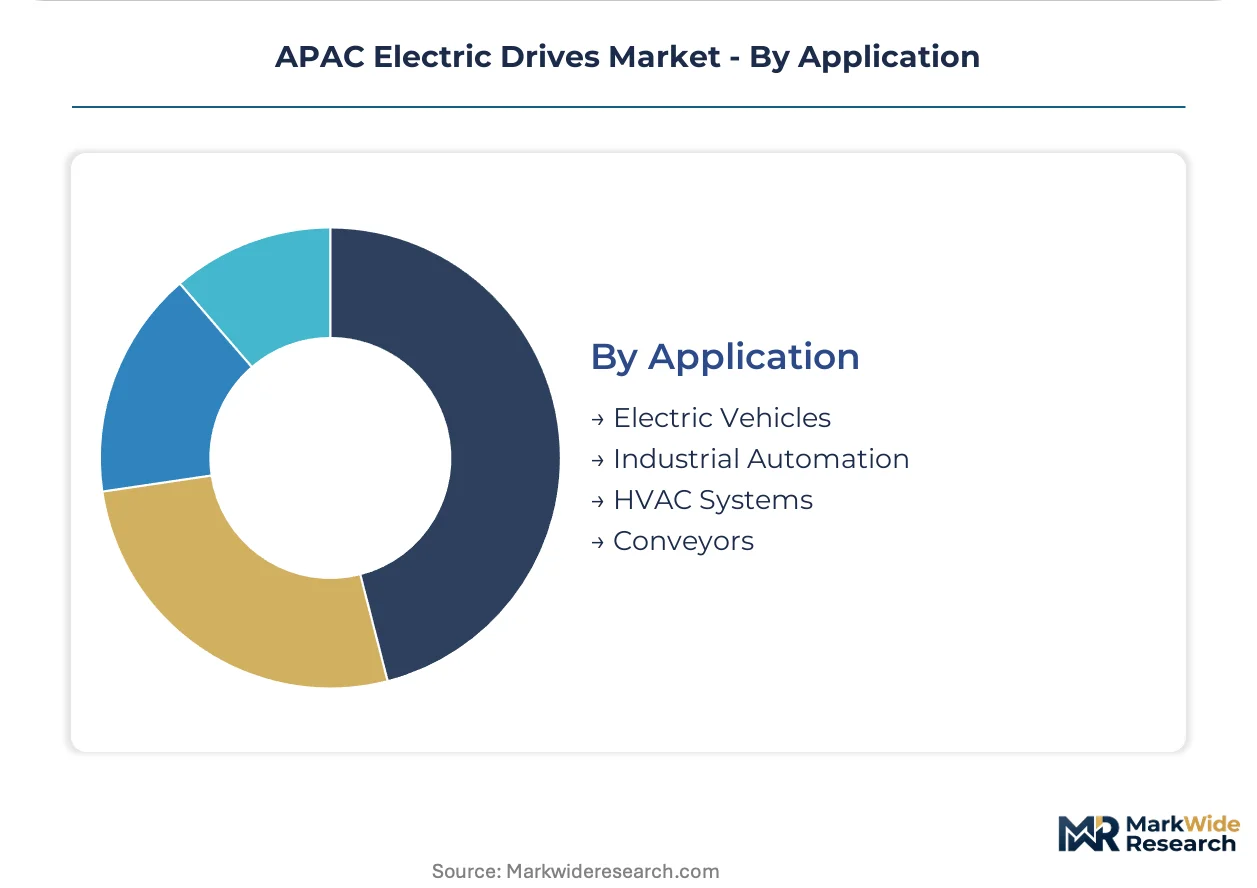
Application:
Deployment context dictates voltage class, enclosure rating, and communication protocol requirements.
- Electric Vehicles:800V SiC traction inverters from Japanese Tier-1 suppliers are digitizing thermal management boundaries in next-generation NEV platforms. Bi-directional power flow capability enables regenerative braking integration.
- Industrial Automation:Servo systems with embedded ARM-based SoCs are enabling predictive maintenance subscriptions in Seoul-Incheon semiconductor fabrication lines.
- HVAC Systems:Variable frequency drives for commercial building climate control face Bureau of Energy Efficiency efficiency norms in India and GB standards enforcement in China.
- Conveyors:Medium-voltage drives power bulk material handling in Indonesia's nickel processing smelters and Vietnam's port logistics infrastructure.
HVAC Systems anchor replacement volume; Electric Vehicles show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in China, Japan, and India dominate procurement volumes, with automotive OEMs and steel conglomerates driving specification intensity for high-efficiency drive systems.
China
NEV manufacturers in the Yangtze River Delta and Pearl River Delta are scaling brushless motor procurement for 800V traction platforms. MIIT's GB motor efficiency standards mandate IE4-class minimums for state-procured industrial equipment, eliminating IE2 units from steel mills and chemical plants. Shenzhen and Suzhou host the densest clusters of servo drive assembly operations serving robotics and semiconductor fabrication equipment.
Japan
Automotive Tier-1 suppliers in Nagoya and Tokyo are qualifying SiC traction inverters for next-generation EV platforms. METI's green innovation fund subsidizes wide-bandgap power electronics adoption, tightening certification requirements for non-domestic suppliers. The Kansai machine tool corridor around Osaka concentrates demand for harmonic-free servo systems with regenerative braking integration.
India
Steel producers in Odisha and Jharkhand face BIS IS 12615 efficiency mandates under Bureau of Energy Efficiency directives, triggering replacement cycles for aging induction motor infrastructure. The PLI scheme for advanced automotive components draws servo drive assembly into Gujarat and Tamil Nadu supplier parks. Pune and Chennai host expanding automation system integrator ecosystems.
South Korea
Electronics manufacturers in the Seoul-Incheon corridor are adopting asset-as-a-service contracting for precision servo systems in semiconductor fabrication. Domestic OEMs accelerate local content quotas in response to METI-aligned efficiency pressures from Japanese customers. Busan-Ulsan shipbuilders specify medium-voltage drives for propulsion system retrofits.
Indonesia
Nickel processing smelters in Sulawesi and Halmahera are creating localized demand for medium-voltage drives in hydrometallurgical refining operations. Downstream battery material investments from Chinese and Korean conglomerates are pulling automation equipment procurement into the Morowali Industrial Park. Jakarta-based system integrators are expanding service capabilities for mining sector deployments.
APAC Electric Drives Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement hierarchies, with consolidated Japanese and European conglomerates holding automotive OEM direct relationships while mid-scale regional fabricators capture industrial retrofit volume. The vendor base organizes around three strategic archetypes: integrated automation conglomerates with robotics-to-drives portfolios, power electronics specialists with foundry partnerships, and application-focused servo system builders. Competitive moves concentrate on SiC inverter platform partnerships and predictive maintenance software bundling.
Among Swiss-Swedish and German industrial conglomerates, ABB Ltd. and Siemens AG exemplify the integrated automation archetype with cross-selling leverage across robotics and motion control. Japanese specialists including Nidec Corporation and Yaskawa Electric Corporation occupy positions anchored in precision motor manufacturing heritage and automotive Tier-1 supply relationships. These named entities represent the premium-tier competitive vector where firmware-defined control architectures and SiC power module integration determine specification wins.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Schneider Electric SE |
| Nidec Corporation |
| Danfoss A/S |
| Rockwell Automation Inc. |
| Mitsubishi Electric Corporation |
| TMEIC Corporation |
| Yaskawa Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta foundry capacity expansion is compressing SiC inverter module costs and redistributing pricing power toward buyers of high-efficiency drive systems. This supply-side shift interacts with MIIT efficiency mandates to accelerate IE4-class motor replacement cycles across China's industrial belt.
Pricing Analysis
Cost-plus contracts indexed to neodymium and silicon carbide wafer spot prices dominate long-term procurement agreements between automotive OEMs and Tier-1 suppliers. Pricing stratifies across IE5 premium certification tiers, IE4 standard compliance levels, and non-certified economy units for retrofit applications. Cost compression in the servo motor segment is intensifying as Chinese foundries expand wide-bandgap capacity, eroding Japanese suppliers' historical margin premiums. Steel mills and chemical plants exhibit the highest price sensitivity due to capital budget constraints, while NEV manufacturers prioritize performance specifications over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Japanese trading houses anchor working capital structures for Southeast Asian system integrators. Component sourcing concentrates in China, Japan, and South Korea, with rare earth magnet processing tethered to Inner Mongolia mining operations and SiC substrate production anchored in Korea's Pangyo semiconductor cluster. Single-source vulnerability around neodymium-dysprosium separation creates geopolitical exposure for permanent magnet motor architectures. Distribution runs through authorized distributor networks in industrial corridors, with direct OEM relationships reserved for high-volume automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase driven by China's MIIT-mandated IE2 phase-out, which triggers replacement demand across aging industrial motor infrastructure.
For Market Incumbents:Entrench field-oriented control algorithm expertise through targeted hiring in Tokyo, Seoul, and Shanghai engineering clusters. Acquire SiC foundry partnerships in the Yangtze River Delta to secure substrate allocation ahead of capacity constraints. Lock in multi-year rare earth magnet offtake agreements with Inner Mongolia processors to neutralize price volatility exposure from neodymium supply concentration.
For New Entrants and Emerging Players:Indonesia's nickel processing smelter automation presents the most penetrable white-space opportunity, with medium-voltage drive demand outpacing local supplier capability. Vietnam's port logistics sector offers secondary entry potential through regenerative braking retrofit programs for material handling equipment. Partner with Jakarta-based system integrators to bypass established distributor networks and capture mining sector procurement relationships.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors power electronics specialists with captive SiC inverter platforms and firmware-defined motor control architectures. Five-to-ten year viability hinges on backward integration into wide-bandgap semiconductor sourcing. Monitor BIS, JIS, and GB certification divergence as the inflection signal—regulatory fragmentation that exceeds current compliance burden thresholds would favor acquisition targets with parallel validation infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| SiC Inverter Platform Partnership | Secures substrate allocation from Yangtze River Delta foundries for 800V traction applications. |
| Predictive Maintenance Software Bundling | Enables recurring revenue streams through ARM-based SoC embedded analytics in Seoul-Incheon corridors. |
| Backward Integration into Magnet Processing | Captures neodymium supply chain margin and reduces Inner Mongolia sourcing volatility exposure. |
| Localized Certification Infrastructure | Accelerates BIS, JIS, and GB parallel validation to compress regional product launch timelines. |
| Asset-as-a-Service Contracting | Transfers operational risk from South Korean electronics manufacturers to OEM balance sheets. |
Study Parameters
Initial hypotheses were tested against primary input from plant engineers at steel mills and chemical plants, procurement leads at NEV manufacturers, aftermarket service heads at distributor networks, and technical R&D directors at servo drive assemblers, then refined through secondary validation. Trade data from China's General Administration of Customs, MIIT equipment procurement disclosures, Bureau of Energy Efficiency compliance filings, and SEC 10-K filings from listed automation conglomerates anchored quantitative baselines. Bottom-up unit shipment estimates from foundry capacity announcements were triangulated against top-down industrial motor replacement cycle models.
Demand-supply balance framing structured the analytical approach across the analysis window, with segmentation modeled across motor topology, end-use industry, power electronics architecture, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and efficiency mandate compliance deadlines, incorporating SiC inverter adoption curves and rare earth magnet price elasticity assumptions specific to permanent magnet synchronous motor demand.
Practitioners should monitor wide-bandgap wafer capacity expansion announcements, METI subsidy program modifications, and BIS efficiency norm enforcement intensity for early signals of forecast deviation. Macroeconomic industrial capital expenditure cycles, regulatory certification divergence acceleration, or breakthroughs in switched reluctance motor torque ripple suppression would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Global Motor Management Market
Electric Motor
E-Bike Motor Market
Electric Motor
Automotive Torque Actuator Motor Market
Electric Motor
Motorcycle Lead Acid Battery Market
Electric Motor
Motorcycle Battery Market
Electric Motor
United States AC Motor Market
Electric Motor
Brazil Electrically Powered Hydraulic Steering Market
Electric Motor
Electric Vehicle Motor (EVM) Controller Market
Electric Motor
Implant Motors Market
Electric Motor
Traction Motors Market
Electric Motor
Positive Displacement Motor Market
Electric Motor
GCC Electric Motor Market
Electric Motor
Separately Excited Motor Market
Electric Motor
Industrial Smart Motor Market
Electric Motor
Australia Solar E-Bike Market
Electric Motor
Vibrator Motor Market