
 Europe Alternating Current (AC) Motor Market | 2026-2036
Europe Alternating Current (AC) Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Alternating Current (AC) Motor Market Foresight
European automotive electrification is pivoting toward integrated motor-drive systems for electric vehicle powertrains and thermal management. Siemens AG leverages its industrial automation portfolio to anchor high-efficiency motor production for German OEM supply chains. ABB Ltd. competes through its IEC premium efficiency motor range, while Nidec Corporation extends its position in compact traction motors for European EV platforms.
An alternating current motor converts electrical energy into mechanical rotation through electromagnetic induction, with synchronous types operating at fixed speeds tied to grid frequency and asynchronous induction motors dominating variable-load industrial applications. Three-phase asynchronous motors occupy the largest installed base across European process industries due to their rugged construction and direct-on-line starting capability. Synchronous motor demand is accelerating in precision-controlled applications where power factor correction and constant-speed operation justify higher capital outlay.
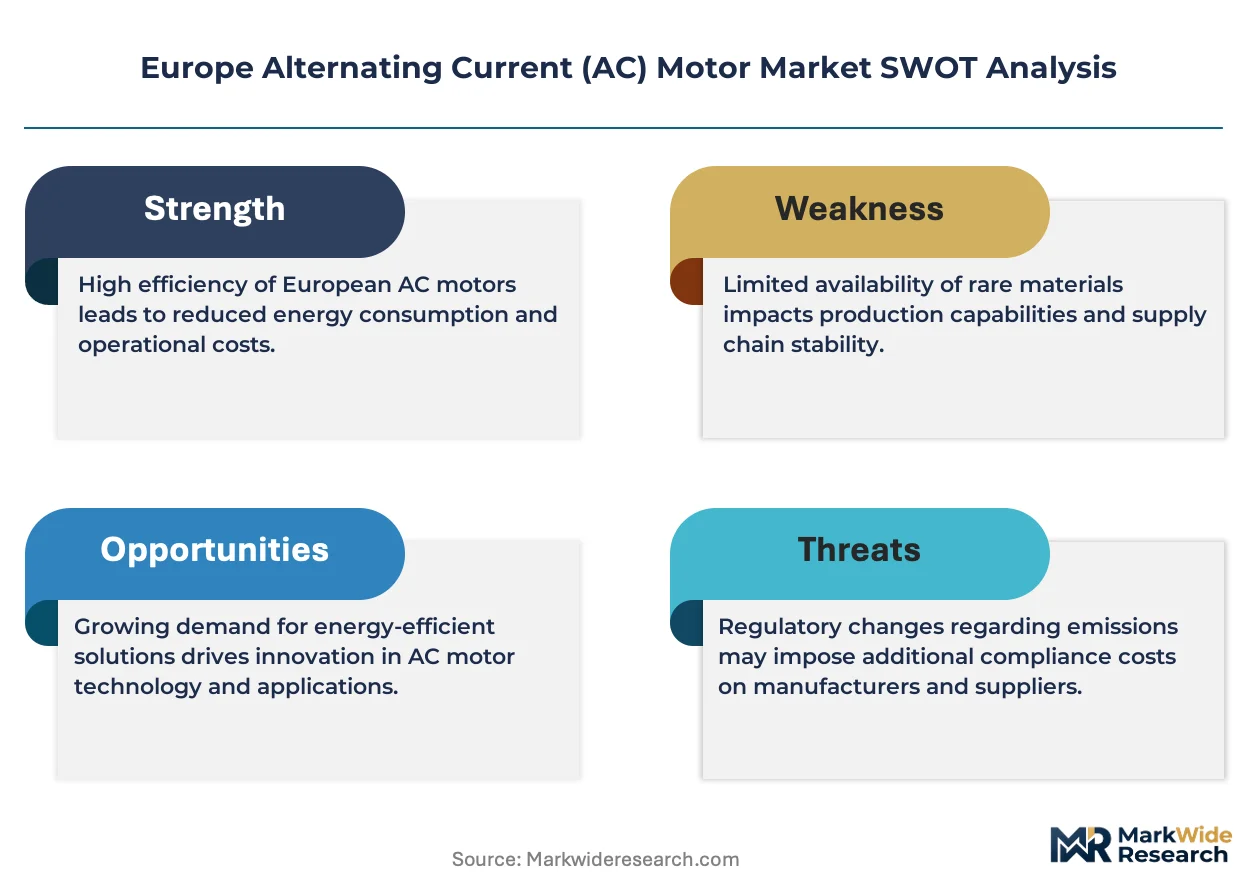
The EU Ecodesign Directive and ErP regulations mandate minimum IE3 efficiency classes for most industrial motors, while CE marking requirements govern electromagnetic compatibility and mechanical safety for market access. ECHA REACH compliance shapes material selection for insulation systems and bearing lubricants. Stakeholders must monitor the pending IE4 premium efficiency mandate trajectory and assess retrofit versus replacement economics across aging motor populations.
Market Dynamics
The EU Ecodesign Directive's tightening efficiency tiers are forcing wholesale motor fleet replacement across German, Italian, and French manufacturing bases, compressing payback periods for premium IE4 systems.
Growth Catalysts
- IE4 Premium Efficiency Mandates:The EU Ecodesign Directive's pending efficiency escalations are accelerating replacement cycles across aging motor populations in German process industries.
- Automotive Electrification:Integrated motor-drive systems for electric vehicle powertrains are pulling demand from Stuttgart, Munich, and Wolfsburg OEM supply chains.
- Industrial Automation Density:German manufacturing plants are retrofitting conveyor, pump, and compressor systems with variable-frequency drives paired to high-efficiency asynchronous motors.
Market Restraints
- Copper and Rare-Earth Price Volatility:Neodymium and dysprosium supply concentration in Chinese processing facilities creates input cost instability for permanent-magnet synchronous motor production.
- Capital Intensity of IE4 Migration:Premium efficiency motor procurement requires 30-50% higher upfront outlay versus IE3 equivalents, stretching SME maintenance budgets.
- Technical Limitation of Retrofit Compatibility:Legacy mechanical couplings and shaft dimensions constrain direct drop-in replacement of older motor generations without full system redesign.
Strategic Opportunities
- Polish and Czech Industrial Expansion:Central European manufacturing migration from Western European cost centers is creating greenfield motor specification opportunities in Wrocław and Ostrava automotive clusters.
- EU Green Deal Funding Windows:Recovery and Resilience Facility disbursements are subsidizing energy-efficiency upgrades across Italian textile and ceramics processing facilities.
- Digital Twin Convergence:Integration of motor condition monitoring with predictive maintenance platforms is enabling servitization models for Milanese and Turin-based system integrators.
Industry Challenges
- Electromagnetic Compatibility Certification:CE marking timelines for variable-speed drive combinations are extending 8-12 weeks due to notified body backlogs, delaying project commissioning.
- Legacy Control System Integration:Proprietary fieldbus protocols in 1990s-era German automation infrastructure obstruct seamless connectivity with modern IE4 motor-drive packages.
- Skilled Commissioning Engineer Scarcity:Vibration analysis and thermal modeling expertise for high-efficiency motor installation is concentrating among aging specialist workforces in Northern Italy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Alternating Current (AC) Motor Market |
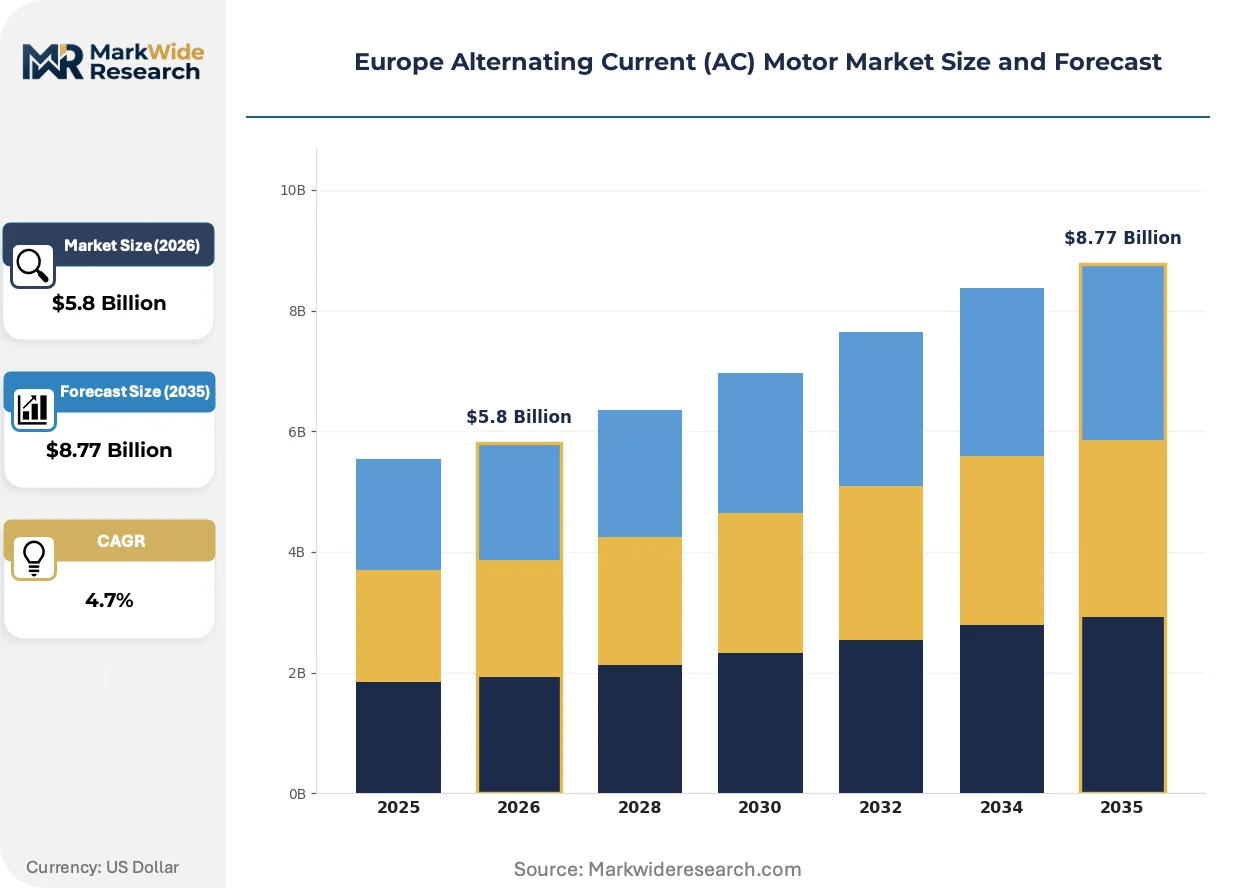
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Synchronous, Asynchronous, Single-phase, Three-phase End User: Industrial, Commercial, Residential, Automotive Power Rating: Low, Medium, High, Ultra High Distribution Channel: Direct Sales, Online Retail, Distributors, Dealers |
| Companies Covered | ABB Ltd., Siemens AG, Nidec Corporation, Regal Rexnord Corporation, Toshiba Mitsubishi-Electric Industrial Systems Corporation, Baldor Electric, Brook Crompton, Johnson Electric Holdings Limited, Fuji Electric Co., Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Alternating Current (AC) Motor Market Shifts & Advancements
Permanent-magnet synchronous motor technology is penetrating precision-controlled applications previously dominated by asynchronous designs, while digitalization layers create new value-capture mechanisms for system suppliers.
Integrated motor-drive packages combining power electronics with compact synchronous machines are decentralizing machine-level control architectures. Packaging machinery OEMs in Bologna and pharmaceutical equipment builders in Basel are specifying these integrated units for reduced cabinet footprint. This topology is decentralizing traditional centralized drive rooms into distributed motor-mounted intelligence.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon refrigerants is tightening thermal management requirements for motor cooling systems. Hermetic compressor motor designs must now accommodate lower-GWP refrigerants with altered thermodynamic properties. Cold chain equipment manufacturers in Denmark and the Netherlands are redesigning stator insulation systems to withstand modified lubricant chemistries.
Italian and Spanish industrial buyers are consolidating supplier relationships around full-lifecycle service agreements rather than transactional motor procurement. MRO distributors in Barcelona and Madrid are unbundling installation and commissioning from hardware supply. This behavioral shift is most visible in water and wastewater treatment utilities where total cost of ownership models now dominate specification criteria.
Europe Alternating Current (AC) Motor Market Segmentation
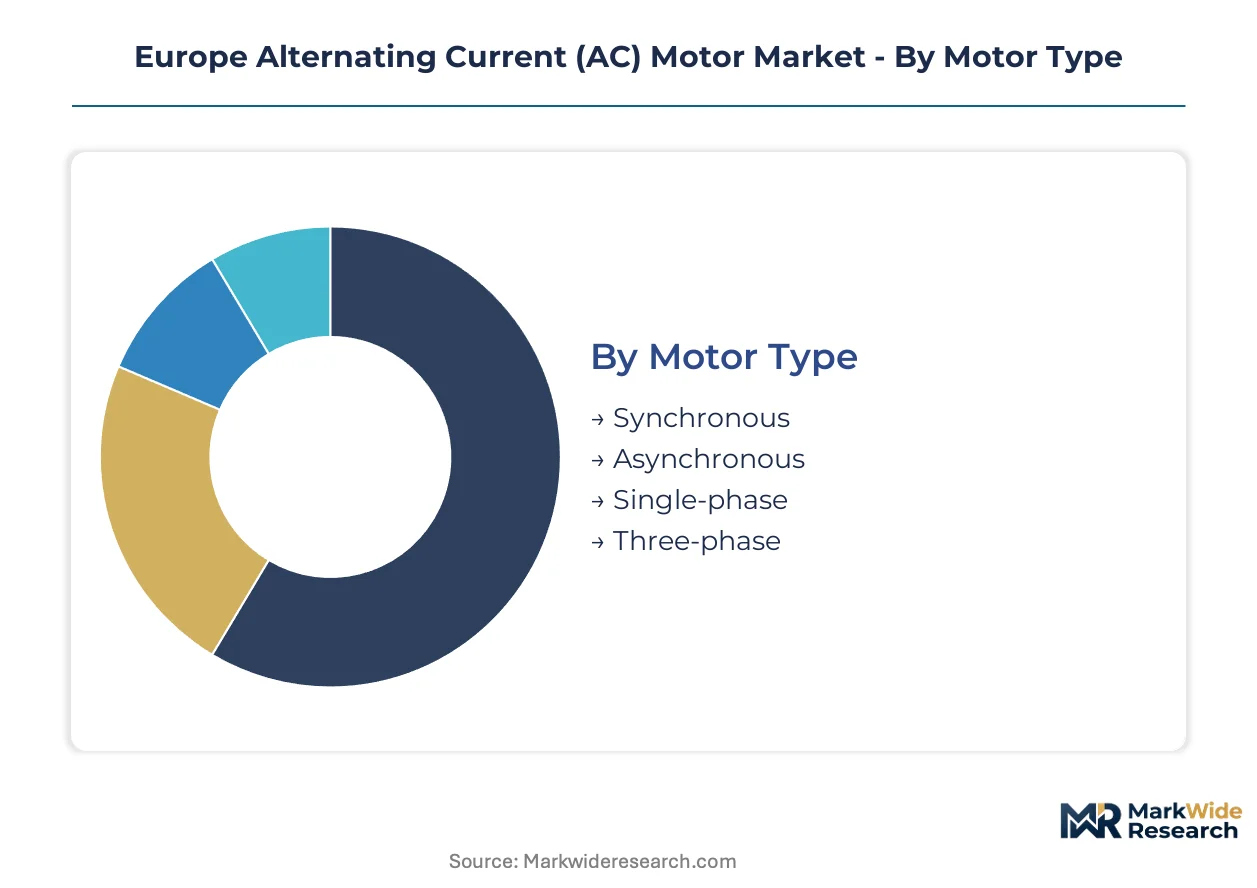
Segmentation in the Europe AC Motor Market reveals divergent capital requirements and technical specifications across motor architectures and power classes. Procurement patterns vary sharply between German automotive OEMs specifying integrated traction systems and Italian textile processors retrofitting legacy pump infrastructure.
Motor Type:
Capital intensity escalates dramatically from basic single-phase units to precision-engineered synchronous systems requiring rare-earth magnet assemblies and advanced thermal management.
- Synchronous:Permanent-magnet designs deliver fixed-speed operation with power factor correction capability. German automotive electrification programs in Stuttgart and Wolfsburg are pulling demand for compact traction-grade synchronous machines.
- Asynchronous:Rugged induction construction dominates variable-load industrial applications through direct-on-line starting. Three-phase asynchronous motors occupy the largest installed base across French and Italian process industries due to maintenance simplicity.
- Single-phase:Fractional-horsepower units serve residential HVAC and small appliance applications.
- Three-phase:Industrial workhorse configuration powers conveyor, compressor, and pump systems across manufacturing plants.
Asynchronous motors absorb the bulk of installed capacity; synchronous designs are expanding most quickly.
End User:
Application requirements fragment procurement specifications across torque density, duty cycle, and environmental sealing demands.
- Industrial:Continuous-duty motors face 24/7 operational stress in chemical processing and materials handling. German manufacturing plants are retrofitting conveyor and compressor systems with IE4-rated asynchronous motors paired to variable-frequency drives.
- Automotive:Traction motor specifications demand extreme power density and thermal endurance. Integrated motor-drive systems for electric vehicle powertrains concentrate specification authority with Stuttgart, Munich, and Wolfsburg OEM engineering centers.
- Commercial:HVAC and refrigeration applications require hermetic compressor motor designs.
- Residential:Appliance and climate control motors prioritize cost minimization over efficiency premiums.
Industrial end users command the largest procurement volumes; automotive applications are climbing the fastest.
Power Rating:
Unit economics and efficiency regulatory thresholds shift discretely across power bands, with IE3 mandates applying differentially by kilowatt class.
- Low:Fractional to small integral horsepower motors serve auxiliary equipment and light machinery. Italian textile machinery OEMs in Bologna specify low-power IE4 motors for precision spindle drives.
- Medium:General-purpose industrial motors from 1-75 kW face the strictest Ecodesign Directive efficiency enforcement. French food processing facilities are replacing aging medium-power fleets ahead of pending IE4 escalations.
- High:Heavy-duty process motors exceed 75 kW for compressor and pump duty.
- Ultra High:Specialized large synchronous machines serve steel mill and mining applications.
Medium power ratings dominate replacement cycles; low-power segments are gaining share fastest.
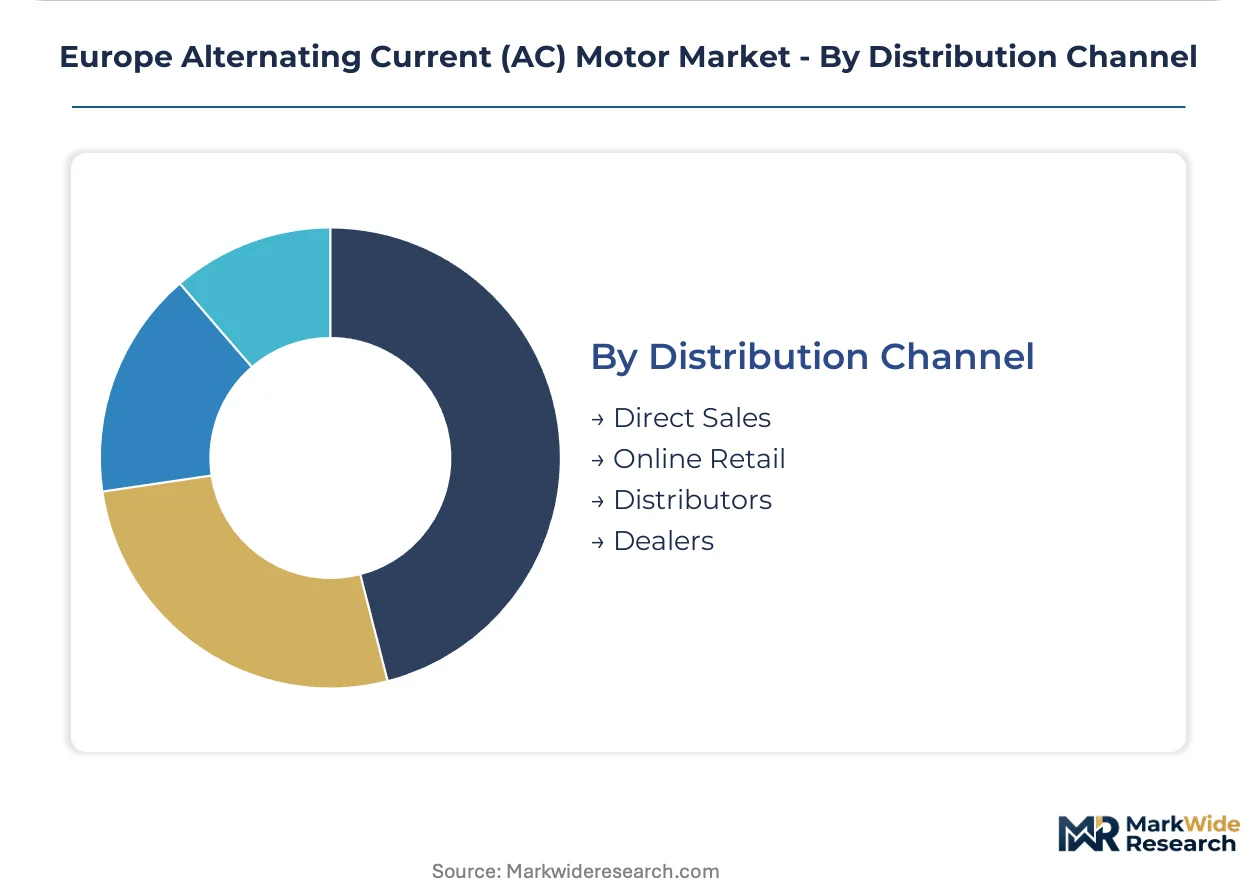
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and the complexity of drive system integration.
- Direct Sales:Large OEM contracts and system integration projects bypass intermediaries. Siemens AG and ABB Ltd. maintain direct technical liaison with German automotive and industrial automation customers.
- Distributors:MRO supply chains serve maintenance replacement demand across fragmented industrial bases. Spanish and Italian distributors are unbundling installation services from hardware supply.
- Online Retail:Standardized small motors move through digital procurement platforms.
- Dealers:Regional representatives provide localized commissioning support.
Direct sales capture the largest project values; distributor channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Central Europe are drawing motor manufacturing investment through tax holidays and infrastructure subsidies. The EU Recovery and Resilience Facility channels capital toward energy-efficiency retrofits across industrial corridors. National efficiency mandates and automotive electrification programs fragment demand concentration across Western and Central European manufacturing belts.
Germany
Stuttgart and Wolfsburg automotive engineering centers specify integrated traction motors for electric vehicle platforms. The EU Ecodesign Directive's IE3 minimums and pending IE4 escalations compress replacement cycles across Ruhr Valley process industries. Bavarian industrial automation clusters in Munich and Nuremberg retrofit conveyor systems with variable-frequency drive pairings.
Italy
Textile machinery OEMs in Bologna and pharmaceutical equipment builders in Milan drive demand for precision spindle motors and hermetic compressor designs. Recovery and Resilience Facility disbursements subsidize ceramic processing upgrades in Emilia-Romagna. Turin-based system integrators pioneer predictive maintenance servitization models.
France
Food processing facilities in Lyon and chemical plants in Dunkirk face accelerated medium-power motor replacement ahead of efficiency tier escalations. CE marking requirements govern electromagnetic compatibility for variable-speed drive combinations. Île-de-France water utilities adopt total cost of ownership procurement frameworks.
Poland
Wrocław automotive clusters attract greenfield motor specification from Western European cost migration. Special economic zone incentives support supplier park development for German OEM supply chains. Katowice mining equipment manufacturers test ultra-high-power synchronous machines for heavy-duty extraction.
Spain
Barcelona and Madrid MRO distributors unbundle installation services from hardware supply. Textile processing in Catalonia and food packaging in Valencia consolidate supplier relationships around lifecycle service agreements. Spanish industrial buyers prioritize total cost of ownership over transactional procurement.
Europe Alternating Current (AC) Motor Market Competitive Landscape
Top-tier vendors anchor premium efficiency segments, while mid-tier specialists compete on retrofit compatibility and regional service density. The vendor base stratifies across integrated industrial conglomerates, dedicated motor manufacturers, and automotive-focused traction specialists. Siemens AG and ABB Ltd. exemplify full-system integrators; Nidec Corporation represents compact traction specialization. Competitive moves concentrate on backward integration into rare-earth magnet supply and predictive maintenance platform development.
Within the diversified industrial tier, Siemens AG and ABB Ltd. occupy positions exemplifying full-portfolio automation suppliers. Nidec Corporation anchors the compact traction motor specialization vector. These three entities represent distinct strategic archetypes: German-headquartered system integration, Swiss-Swedish premium efficiency leadership, and Japanese compact powertrain focus.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Nidec Corporation |
| Regal Rexnord Corporation |
| Toshiba Mitsubishi-Electric Industrial Systems Corporation |
| Baldor Electric |
| Brook Crompton |
| Johnson Electric Holdings Limited |
| Fuji Electric Co., Ltd. |
| Others |
Supply & Pricing Matrix
Backward integration into rare-earth magnet processing anchors pricing power for synchronous motor producers serving German automotive electrification programs. Captive supply of neodymium and dysprosium separates premium IE4 traction motor suppliers from distributors competing on spot copper winding inventories.
Pricing Analysis
Short lead-time premiums of 15-25% apply to IE4-rated synchronous motors serving Stuttgart OEM emergency replacement schedules, while spot inventory discounts move aging IE3 asynchronous stock through Italian MRO channels. Three-tier pricing structure across premium IE4, standard IE3, and economy IE2 certification levels reflects the EU Ecodesign Directive's tiered compliance deadlines. Pricing pressure stems from copper volatility and rare-earth processing concentration in Chinese facilities. SME maintenance teams in Spanish textile plants exhibit highest price sensitivity; German automotive platform engineers prioritize torque density over unit cost.
Supply Chain Analysis
Dual-sourcing qualification requirements from Wolfsburg and Munich OEM engineering centers force traction motor suppliers to maintain qualified winding facilities in both Germany and Poland. Geographic supply concentration centers on China for rare-earth magnet feedstock, Germany for precision stator lamination, and Italy for aluminum die-cast rotor housings. Raw material dependencies include copper magnet wire, silicon electrical steel, and rare-earth permanent magnets. Single-source vulnerability concentrates in Chinese dysprosium refining capacity. Distribution runs through authorized system integrators for large OEM contracts and fragmented MRO distributors for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around suppliers with captive rare-earth processing and certified IE4 production lines, as pending efficiency mandates force sub-scale motor rebuilders into exit.
For Market Incumbents: Anticipate margin compression from Chinese rare-earth traders entering European winding services through Polish special economic zones. Prioritize backward integration into magnet alloy processing and expand direct technical liaison with Stuttgart OEM platform teams to lock in multi-year traction motor offtake agreements. For New Entrants and Emerging Players: Polish automotive tier suppliers in Wrocław and Ostrava represent the most penetrable buyer archetype for greenfield IE4 motor specification. Target predictive maintenance service bundling for Italian ceramic processing utilities and Czech conveyor system integrators seeking lifecycle cost models over transactional procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to industrial conglomerates seeking European motor manufacturing footprints. Long-term viability favors targets with ECHA REACH-certified insulation systems and established CE marking test records. Watch rare-earth price volatility as the inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Processing | Captive neodymium supply insulates German traction motor producers from Chinese export quota volatility. |
| IE4 Premium Efficiency Certification Investment | Early CE marking for IE4-rated asynchronous motors captures replacement cycles ahead of EU Ecodesign Directive escalations. |
| Predictive Maintenance Platform Development | Digital twin integration enables Milanese system integrators to capture recurring service revenue from water utility clients. |
| Polish Manufacturing Footprint Expansion | Wrocław special economic zone proximity reduces logistics costs for supplying Stuttgart OEM supply chains. |
| Long-Term Copper Supply Agreement | Fixed-price magnet wire contracts stabilize input costs for French food processing motor replacement programs. |
Research Methodology
Independent corroboration across plant engineers at German automotive OEMs, procurement leads at Italian textile machinery builders, maintenance directors at French food processing facilities, and MRO distributors in Spain underwrites the qualitative findings. Primary interviews with OEM platform engineers, Tier 1 supplier sourcing managers, and aftermarket service heads were cross-referenced against secondary sources including EU Ecodesign Directive implementation reports, ECHA REACH substance restriction updates, and customs trade data for copper and rare-earth magnet flows. Bottom-up motor shipment estimates triangulate with top-down industrial automation capex analysis.
Rate-of-change decomposition separates volume growth from price realization across motor type, power rating, and end-user segments throughout the forecast period. The analytical framework models synchronous versus asynchronous technology splits, IE3 versus IE4 efficiency class penetration, and direct sales versus distributor channel mix. CAGRs derive from regression against industrial production indices and automotive electrification program timelines. Forecast inputs include EU Green Deal disbursement schedules and F-Gas Regulation phase-down impacts on hermetic compressor motor demand.
Revisions become necessary when rare-earth export restrictions materialize, IE4 mandate timelines accelerate, or automotive platform standardization shifts toward integrated wheel-hub architectures. Deviation in Chinese magnet processing capacity utilization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Electric Vehicle Flat Wire Motor Market
Electric Motor
Electric Vehicle Permanent Magnet Synchronous Motors Market
Electric Motor
Global Automotive Motor Market
Electric Motor
Automotive ABS Motor Market
Electric Motor
Global EV Motor Controller Market
Electric Motor
UAE Electric Motor Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Intelligent Motor Controller Market
Electric Motor
Power Tool Lithium Battery Market
Electric Motor
Automotive Torque Actuator Motor Market
Electric Motor
Electric AC Motors Market
Electric Motor
Implant Motors Market
Electric Motor
Automotive Wiper Motor Market
Electric Motor
Positive Displacement Motor Market
Electric Motor
Global Automotive Starter Motor Market
Electric Motor
Brazil Electrically Powered Hydraulic Steering Market