
 Fluid Conveyance Products Motors Market | 2026-2036
Fluid Conveyance Products Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Conveyance Products Motors Market Foresight
Skilled fluid power technician availability is bifurcating the competitive landscape between premium and commodity motor suppliers. Parker Hannifin Corp leverages its captive distribution network to sustain margin capture in high-specification hydraulic power units. Eaton Corporation anchors its position through backward integration into motor winding and sealing technologies. Sabo Group competes on dedicated servo motor lines for precision pumping applications.
Fluid conveyance products motors are electromechanical devices engineered to convert electrical energy into mechanical torque for driving pumps, compressors, and fluid transfer equipment, typically operating at IP55 or higher enclosure ratings to withstand moisture, dust, and chemical exposure in industrial environments. AC motors dominate pumping systems deployments due to simpler maintenance profiles and compatibility with variable frequency drives, while brushless DC architectures displace brushed units in marine and food processing settings where spark minimization and washdown compatibility prove critical. Servo motors command premium positioning in material handling for closed-loop flow control, whereas induction technology sustains volume leadership across water treatment and agricultural machinery through proven durability in continuous-duty cycles.
FCC electromagnetic compatibility standards constrain motor drive integration for North American OEMs, while EU Ecodesign regulations and REACH material restrictions compel European manufacturers to reformulate insulation systems and bearing lubricants. India's BIS certification requirements for rotating electrical machinery create compliance thresholds for import-dependent water treatment infrastructure projects. Stakeholders must monitor evolving efficiency tier migrations and regional certification divergence to align product portfolios with procurement gatekeeping.
Market Dynamics
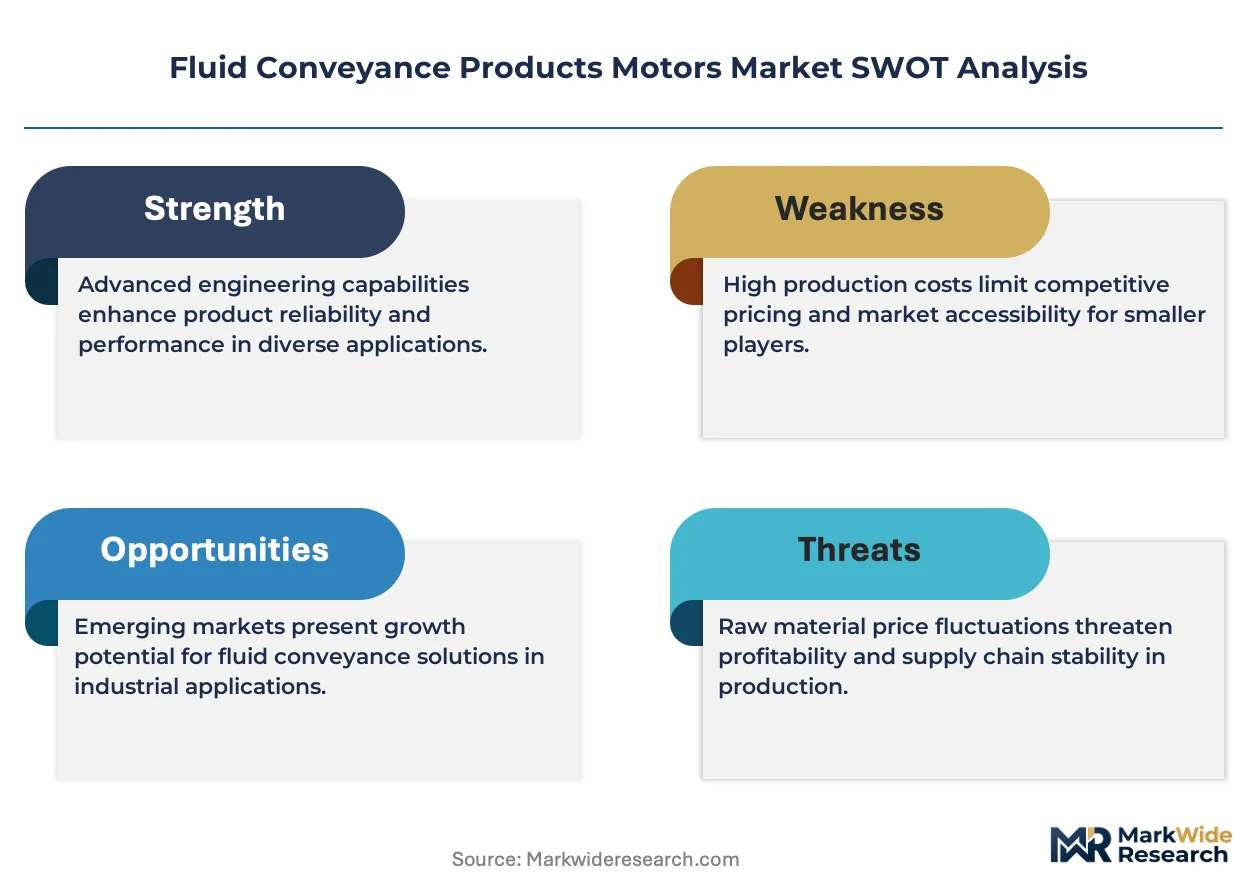
IECEX and ATEX certification requirements for hazardous zone motors are bifurcating supplier capabilities, forcing mid-tier manufacturers to exit oil and gas applications while premium specialists capture margin in chemical processing infrastructure.
Growth Catalysts
- Water treatment infrastructure:North American municipalities are retrofitting aging pumping stations with NEMA Premium efficiency motors to meet EPA energy consumption targets for public utilities.
- REACH material compliance:European Ecodesign regulations are accelerating replacement cycles for motors with non-compliant insulation systems in Germany's industrial corridor.
- Servo motor architectures:Closed-loop flow control requirements in precision chemical dosing are pulling brushless DC technology into pharmaceutical manufacturing equipment.
Market Restraints
- Rare earth magnet supply:Permanent magnet motor production faces input cost volatility as neodymium processing concentrates in China's Inner Mongolia refining complexes.
- IEC efficiency tier migration:IE4 and IE5 motor redesigns require winding copper grades that strain European wire drawing capacity, extending lead times for high-efficiency units.
- Mechanical seal compatibility:Advanced motor bearing systems face technical limitations in high-pressure hydraulic circuits above 350 bar, constraining adoption in deep-sea oil extraction.
Strategic Opportunities
- India water infrastructure:BIS certification requirements for rotating electrical machinery create procurement thresholds that favor established suppliers in municipal treatment plant tenders.
- Marine electrification:IMO 2023 emission standards are pulling permanent magnet motors into auxiliary pump systems for harbor craft and coastal vessels.
- Digital twin integration:Predictive maintenance platforms combining vibration sensors with cloud analytics are opening aftermarket service revenue streams for motor OEMs.
Industry Challenges
- Fluid power technician scarcity:Specialized skills for hydraulic-electric system integration are concentrating in Germany, the United States, and Japan, leaving other regions dependent on expatriate labor.
- Multi-certification timelines:Simultaneous UL, CSA, and CE marking requirements for export motors extend product validation cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Conveyance Products Motors Market |
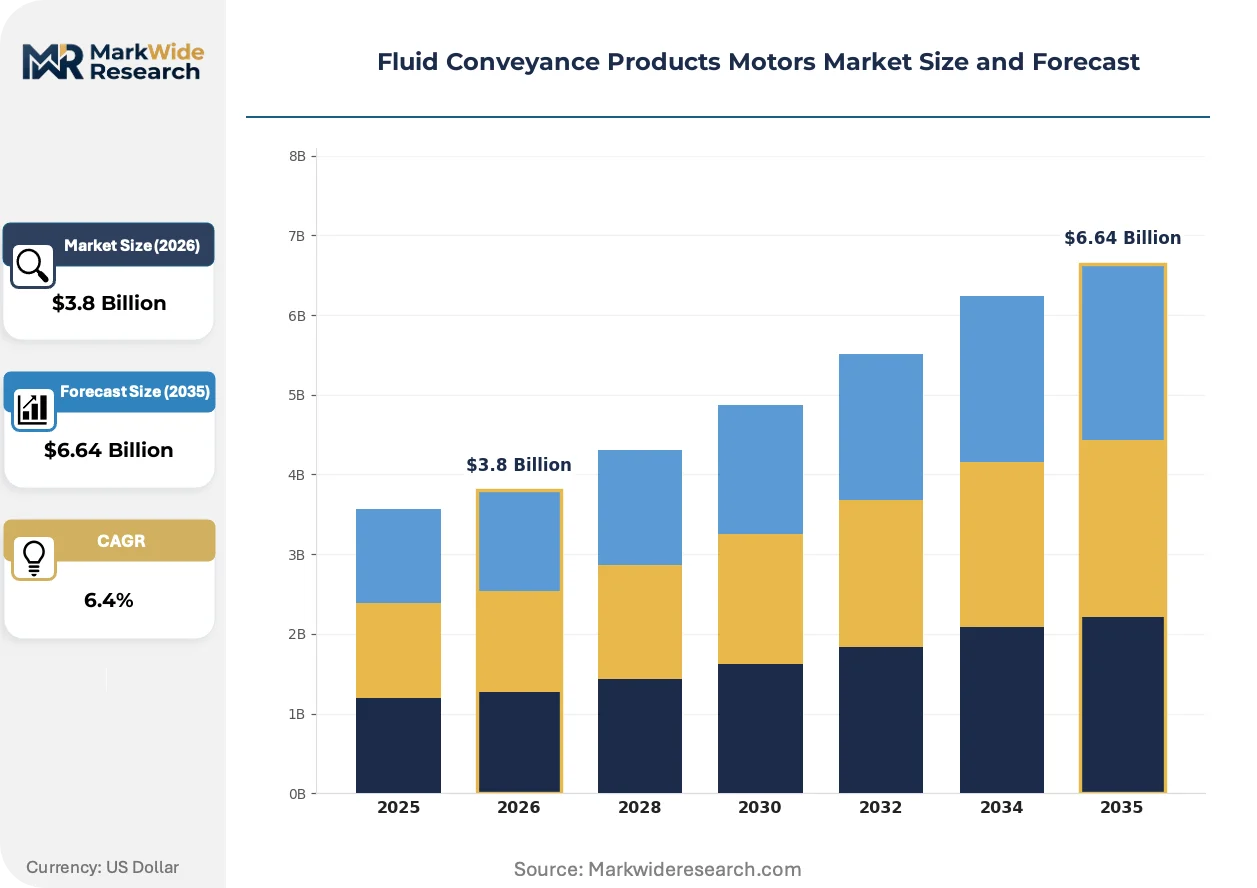
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Servo Motors, Stepper Motors, Brushless Motors Technology: Induction, Synchronous, Universal, Reluctance, Hysteresis Application: Pumping Systems, HVAC Equipment, Material Handling, Agricultural Machinery, Marine Vessels End User: Manufacturing Plants, Water Treatment Facilities, Construction Companies, Food Processing Units, Mining Operations |
| Companies Covered | Senior Plc, Sabo Group, Eaton Corporation, GHX Industrial, LLC, Leading Edge Hydraulics, Parker Hannifin Corp, Ideal Plm, Metline Industries, Unison, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Conveyance Products Motors Market Shifts & Advancements
Synchronous reluctance motor designs are eroding induction motor dominance in pumping applications, while digitalization of maintenance workflows restructures aftermarket value capture. Regulatory efficiency mandates and supply chain regionalization are accelerating technology substitution cycles.
Permanent magnet-assisted synchronous reluctance motors are displacing conventional induction technology in continuous-duty pumping systems. Water treatment operators in the Netherlands and Denmark are adopting these architectures for variable-load applications. The technology is displacing premium-efficiency induction units in the 7.5-75 kW range, compressing margin pools for legacy winding suppliers.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon refrigerants in motor cooling systems for compressors. European OEMs are reformulating thermal management designs to accommodate CO2 and ammonia-based alternatives. Food processing and cold chain logistics sectors in Germany and France are absorbing the highest compliance costs, accelerating local motor redesign cycles.
Condition-based maintenance contracts are unbundling traditional motor sales from service revenue. Industrial buyers in Scandinavia are purchasing uptime guarantees rather than equipment, shifting risk to manufacturers. Food and beverage processing facilities in Sweden and Norway are piloting this model most aggressively, pressuring distributors to develop diagnostic capabilities.
Fluid Conveyance Products Motors Market Segmentation
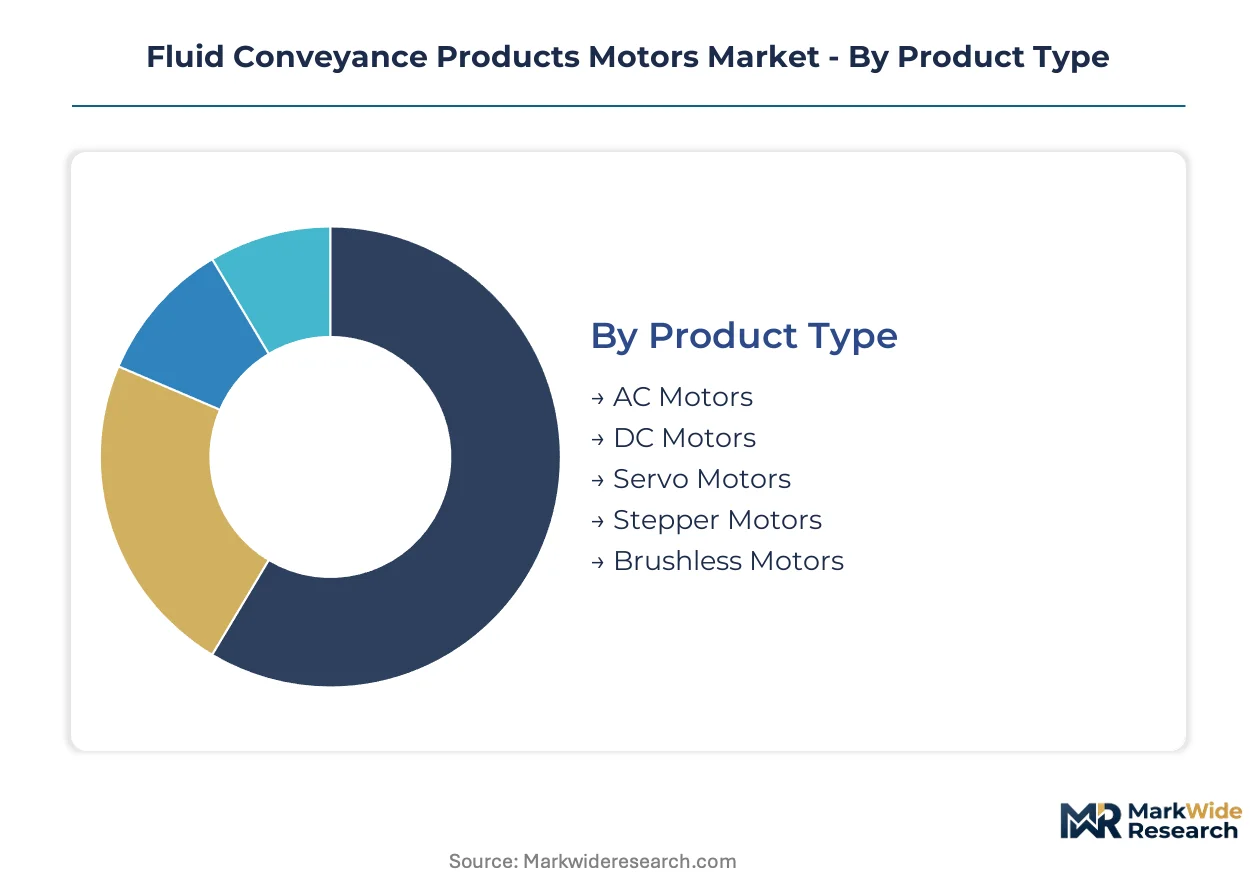
Segmentation in fluid conveyance motors reveals how procurement priorities diverge across technical specifications and operational environments. Buyers optimize for efficiency tiers, enclosure ratings, and duty cycles based on whether motors face continuous pumping loads or intermittent material handling cycles.
Product Type:
AC motors dominate domestic procurement in Germany and the United States, while DC architectures concentrate in export-oriented marine equipment from Japan and South Korea.
- AC Motors:These units operate at fixed or variable frequencies through standard three-phase power, typically achieving IP55 enclosure ratings for dust and moisture protection. Demand clusters in North American water treatment facilities where municipalities prioritize NEMA Premium efficiency compliance for EPA energy reduction mandates.
- DC Motors:Brushed and brushless configurations deliver high starting torque for hydraulic power units and winch drives. Marine equipment builders in Japan and South Korea specify these for auxiliary pump systems on harbor craft subject to IMO emission standards.
- Servo Motors:Closed-loop positioning systems with encoder feedback enable precise flow control in chemical dosing equipment.
- Stepper Motors:Open-loop digital control suits low-speed metering pumps in laboratory and pilot-scale processing.
- Brushless Motors:Eliminated commutator maintenance and spark-free operation serve food processing washdown environments.
AC motors hold the largest share; momentum sits with brushless DC architectures in marine and food safety applications.
Technology:
Cost stratification separates induction technology for volume pumping from synchronous reluctance designs commanding premium positioning in variable-load systems.
- Induction:Squirrel-cage rotors with copper or aluminum bars deliver proven durability in continuous-duty cycles. Agricultural machinery OEMs in the United States and Brazil specify these for irrigation pumps where maintenance access is limited and capital constraints favor proven technology.
- Synchronous:Permanent magnet rotors lock to supply frequency for precise speed control in multi-pump synchronized systems. Water treatment operators in the Netherlands and Denmark are adopting these architectures for variable-load applications, displacing premium-efficiency induction units.
- Universal:Series-wound commutator motors operate on AC or DC supply for portable pumping equipment.
- Reluctance:Rotor saliency without permanent magnets reduces rare earth dependency for mid-efficiency applications.
- Hysteresis:Constant torque characteristics suit precision metering pumps in pharmaceutical manufacturing.
Induction technology anchors volume procurement; synchronous designs are climbing the fastest in European water infrastructure retrofits.
Application:
Application selection tracks regional industrial structure, with pumping systems concentrated in municipal utilities and marine vessels driven by coastal economies.
- Pumping Systems:Centrifugal and positive displacement pumps for water transfer, pressure boosting, and process circulation. North American municipalities retrofit aging stations with efficiency-rated motors to meet EPA consumption targets for public utilities.
- HVAC Equipment:Chillers, cooling towers, and air handling units require continuous-duty motors with thermal protection. Demand concentrates in Germany's industrial corridor where Ecodesign regulations accelerate replacement cycles for non-compliant insulation systems.
- Material Handling:Conveyor drives and lifting equipment need high starting torque and dynamic braking capability.
- Agricultural Machinery:Irrigation pumps and spraying equipment operate in outdoor exposure conditions.
- Marine Vessels:Bilge, ballast, and fire pumps face saltwater corrosion and vibration exposure.
Pumping systems command the largest application share; marine vessels are gaining share fastest under IMO 2023 emission compliance deadlines.
End User:
End user procurement patterns separate specification-driven buyers with in-house engineering from price-sensitive contractors relying on distributor recommendations.
- Manufacturing Plants:Integrated production facilities specify motors for process cooling, compressed air, and hydraulic power units. Food and beverage processors in Sweden and Norway pilot condition-based maintenance contracts purchasing uptime guarantees rather than equipment.
- Water Treatment Facilities:Municipal and industrial plants prioritize energy efficiency certifications and corrosion resistance. India's BIS certification requirements for rotating electrical machinery create procurement thresholds favoring established suppliers in municipal tenders.
- Construction Companies:Mobile equipment and temporary pumping installations favor ruggedized, easily serviced units.
- Food Processing Units:Washdown-compatible enclosures and food-safe lubricants meet sanitary design standards.
- Mining Operations:Explosion-proof ratings and heavy-duty bearings survive abrasive dust and vibration.
Water treatment facilities hold the largest end user share; manufacturing plants show the steepest expansion trajectory through predictive maintenance platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA energy consumption targets for public utilities anchor procurement patterns in the United States, while Ecodesign regulations and BIS certification requirements reshape competitive access across Europe and India respectively.
United States
Municipal water treatment retrofits drive NEMA Premium efficiency motor procurement across the Great Lakes and Ohio River basins. EPA mandates for public utility energy reduction compress replacement cycles for aging pumping station infrastructure. Chicago and Cleveland anchor the largest concentration of retrofit activity, with municipal engineering departments prioritizing corrosion-resistant enclosures for continuous-duty applications.
Germany
REACH material compliance and F-Gas Regulation phase-down schedules force insulation system reformulation across the industrial corridor. Ecodesign efficiency tier migrations accelerate replacement demand for non-compliant motor windings in process cooling equipment. The Ruhr region and Baden-Württemberg manufacturing clusters absorb the highest compliance costs, driving local redesign cycles for thermal management systems.
India
BIS certification requirements for rotating electrical machinery create procurement thresholds in municipal water infrastructure tenders. Central Electricity Authority efficiency guidelines pull premium motor architectures into treatment plant expansions. Gujarat and Maharashtra industrial zones concentrate demand for import-compliant units, with established suppliers capturing share in government-backed sanitation projects.
Japan
METI efficiency standards and JIS certification protocols constrain motor drive integration for domestic OEMs serving export markets. Brushless DC architectures displace conventional units in food processing equipment bound for marine applications. Osaka and Nagoya manufacturing bases specialize in compact motor designs for precision pumping systems, leveraging captive winding capabilities.
Netherlands
Variable-load water treatment applications pull synchronous reluctance motor designs into municipal retrofit programs. EU F-Gas restrictions on hydrofluorocarbon refrigerants reshape thermal management specifications for compressor motors. Rotterdam and Amsterdam port infrastructure drives marine electrification demand, with harbor craft auxiliary systems adopting permanent magnet architectures under IMO compliance deadlines.
Fluid Conveyance Products Motors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive distribution networks separating premium positioning from commodity supply. Three archetypes dominate: diversified fluid power conglomerates with backward integration into winding and sealing technologies; dedicated servo motor specialists capturing precision dosing applications; and regional fabricators competing on lead time and certification agility. Competitive moves concentrate on portfolio diversification into predictive maintenance platforms and geographic expansion through local certification partnerships.
Among diversified conglomerates, Parker Hannifin Corp and Eaton Corporation exemplify integrated positioning through captive distribution and in-house production of critical components. Sabo Group occupies a specialist tier position, representing the dedicated servo motor archetype for precision pumping applications. These three anchors illustrate how competitive advantage separates between scale-driven efficiency compliance and niche technical specification capture.
| Leading Market Players |
|---|
| Senior Plc |
| Sabo Group |
| Eaton Corporation |
| GHX Industrial, LLC |
| Leading Edge Hydraulics |
| Parker Hannifin Corp |
| Ideal Plm |
| Metline Industries |
| Unison, LLC |
| Others |
Supply & Pricing Matrix
European wire drawing capacity utilization at IE4 and IE5 copper grade specifications compresses lead times for high-efficiency units while simultaneously elevating price floors for premium motor architectures. This scale-driven bottleneck concentrates procurement power among established suppliers with captive winding capabilities, forcing mid-tier manufacturers toward commodity induction technology or exit.
Pricing Analysis
German industrial corridor pricing for REACH-compliant insulation systems runs 15-25 percent above North American NEMA Premium equivalents, reflecting material reformulation costs and Ecodesign compliance investments. Three-tier pricing structure across premium IE5 synchronous reluctance, standard IE3 induction, and economy IE2 replacement units separates specification-driven buyers from price-sensitive contractors. Cost compression in economy tiers intensifies because Chinese neodymium processing concentration feeds permanent magnet motor input volatility. Municipal water treatment facilities exhibit lowest price sensitivity due to EPA energy reduction mandates, while agricultural machinery OEMs in Brazil and the United States face acute capital constraints.
Supply Chain Analysis
Strategic stockpiling of rare earth magnets and copper winding materials dominates inventory strategy among premium motor specialists, contrasting with just-in-time component flows at commodity assemblers. Neodymium refining concentrates in China's Inner Mongolia complexes, copper rod drawing anchors in Germany and the United States, and precision bearing manufacturing clusters in Japan and South Korea. Permanent magnet motor production draws from concentrated rare earth supply, high-grade electrical steel, and specialized bearing lubricants. Single-source vulnerability in neodymium processing creates structural exposure to export restriction shocks. Distribution runs through captive OEM-direct channels for high-specification hydraulic power units and independent electrical distributors for replacement induction motors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet-assisted synchronous reluctance motor displacement of induction technology constitutes a high-growth disruption, with EU Ecodesign tier migrations and rare earth cost volatility compressing legacy margin pools.
For Market Incumbents: Fortify backward integration into motor winding and sealing technologies to defend against servo motor specialists capturing precision dosing applications. Parker Hannifin Corp's captive distribution network model offers template for margin capture retention. Capacity addition in India's BIS-certified production corridors addresses municipal tender thresholds. Certification investment in IECEX and ATEX hazardous zone ratings preserves oil and gas positioning against mid-tier exits. For New Entrants and Emerging Players: Lead with brushless DC architectures targeting marine auxiliary pump systems under IMO 2023 emission compliance deadlines, where incumbent induction motor portfolios face technical obsolescence. India's water infrastructure expansion presents most penetrable geography given BIS certification barriers favoring established suppliers with local partnerships. Digital twin predictive maintenance platforms offer differentiated go-to-market angle unbundling equipment sales from uptime guarantee contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors servo motor specialists with precision dosing capabilities and synchronous reluctance design houses with rare earth reduction IP. Long-term viability rests on regulatory efficiency tier acceleration and marine electrification adoption curves. Acquisition target archetype: mid-cap motor winding specialists with captive distribution in Germany or North American water treatment corridors. Signal to watch: BIS certification timeline compression in Indian municipal tenders as indicator of localization premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Winding | Eaton Corporation's in-house motor winding production insulates margin capture from copper grade supply shocks. |
| IECEX/ATEX Certification Investment | Hazardous zone motor specialists capture margin pools as mid-tier manufacturers exit chemical processing applications. |
| Digital Twin Platform Development | Predictive maintenance contracts shift risk to manufacturers while opening recurring revenue streams in Scandinavia. |
| India BIS Certification Partnership | Local certification agility unlocks municipal water treatment tenders in Gujarat and Maharashtra industrial zones. |
| Synchronous Reluctance R&D Scale-Up | Permanent magnet-assisted designs reduce rare earth dependency while meeting EU Ecodesign IE4/IE5 efficiency tiers. |
Research Methodology
Cross-validation between primary interviews with fluid power system integrators and secondary trade data anchors the qualitative findings. Plant engineers at North American water treatment facilities, procurement leads at German HVAC OEMs, aftermarket service heads at hydraulic power unit distributors, and technical R&D directors at motor winding specialists provided operational context. SEC 10-K filings, customs records for copper and rare earth magnet flows, IEC efficiency standard documentation, and EPA energy consumption databases furnished quantitative grounding. Bottom-up unit economics triangulate against top-down addressable market sizing across the projection horizon.
Sensitivity analysis around neodymium price volatility and Ecodesign tier migration timelines frames the forecast uncertainty. Segmentation dimensions include motor architecture type, efficiency certification tier, enclosure rating specification, duty cycle classification, and regional regulatory cluster. CAGRs derive from installed base replacement velocity modeling and new infrastructure capital expenditure patterns. Industry-specific inputs capture IMO marine electrification deadlines and India's BIS certification penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained rare earth supply concentration or accelerated EU efficiency tier enforcement would require recalibration. Forecasts reflect assumptions around technician labor availability for hydraulic-electric integration and municipal budget continuity for water treatment retrofits. Revision becomes warranted when neodymium processing capacity expansion crosses thresholds that materially alter permanent magnet motor cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Global Two Wheeler Hub Motor Market
Electric Motor
Two Wheeler Electric Starter Magnet Market
Electric Motor
Europe Electric Commercial Vehicle Battery Pack Market
Electric Motor
Electric Vehicle (EV) Traction Motor Market
Electric Motor
Global Automotive Onboard Charger Market
Electric Motor
Air Motor Market
Electric Motor
Automotive Traction Motor Market
Electric Motor
Automotive Hub Motors Market
Electric Motor
Electric Motor Sales Market
Electric Motor
France Alternating Current (AC) Motor Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
United States AC Motor Market
Electric Motor
Garden Tool Lithium Battery Market
Electric Motor
Torque Motor Market
Electric Motor
Global Automotive Starter Motor Market
Electric Motor
Global Hub Motors Market