
 Automotive Sunroof Motor Market | 2026-2036
Automotive Sunroof Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Sunroof Motor Market Analytics
Automotive OEM purchasing is pivoting toward consolidated global platform strategies that bundle sunroof motor sourcing with full roof system contracts. Robert Bosch GmbH leverages its integrated mechatronics portfolio to capture multi-year supply agreements with European and Asian vehicle assemblers. Denso Corporation anchors its position through captive production lines co-located with Toyota Motor manufacturing clusters. Johnson Electric competes aggressively on compact motor torque density for sliding and pop-up configurations.
An automotive sunroof motor is a fractional horsepower DC or brushless DC electromechanical actuator, typically rated between 15 and 40 watts, that converts electrical energy into controlled rotary or linear motion to open, close, tilt, or ventilate vehicle roof panels. These motors integrate Hall-effect position sensors, thermal overload protection, and CAN bus communication modules to synchronize with vehicle body control modules and anti-pinch safety algorithms. Panoramic and solar product types command the widest motor torque range and highest unit value due to extended rail lengths and photovoltaic load management requirements. Electric technology dominates new platform designs while pneumatic and hydraulic variants retreat to legacy aftermarket replacement channels. Medium and large size categories align with the shift toward full-length glass roof architectures in crossover and SUV body styles.
NHTSA Federal Motor Vehicle Safety Standard 118 governs power-operated window, partition, and roof panel systems, mandating precise motor force limitation and reversal response thresholds. EPA corporate average fuel economy rules indirectly shape motor specification by rewarding overall vehicle mass reduction, pushing suppliers toward aluminum rotor housings and magnesium gearboxes. The EU General Safety Regulation introduces expanded intelligent speed assistance and pedestrian protection requirements that extend to protruding roof components. Stakeholders must monitor how cybersecurity standards for vehicle actuator networks reshape motor controller firmware validation protocols.
Market Dynamics
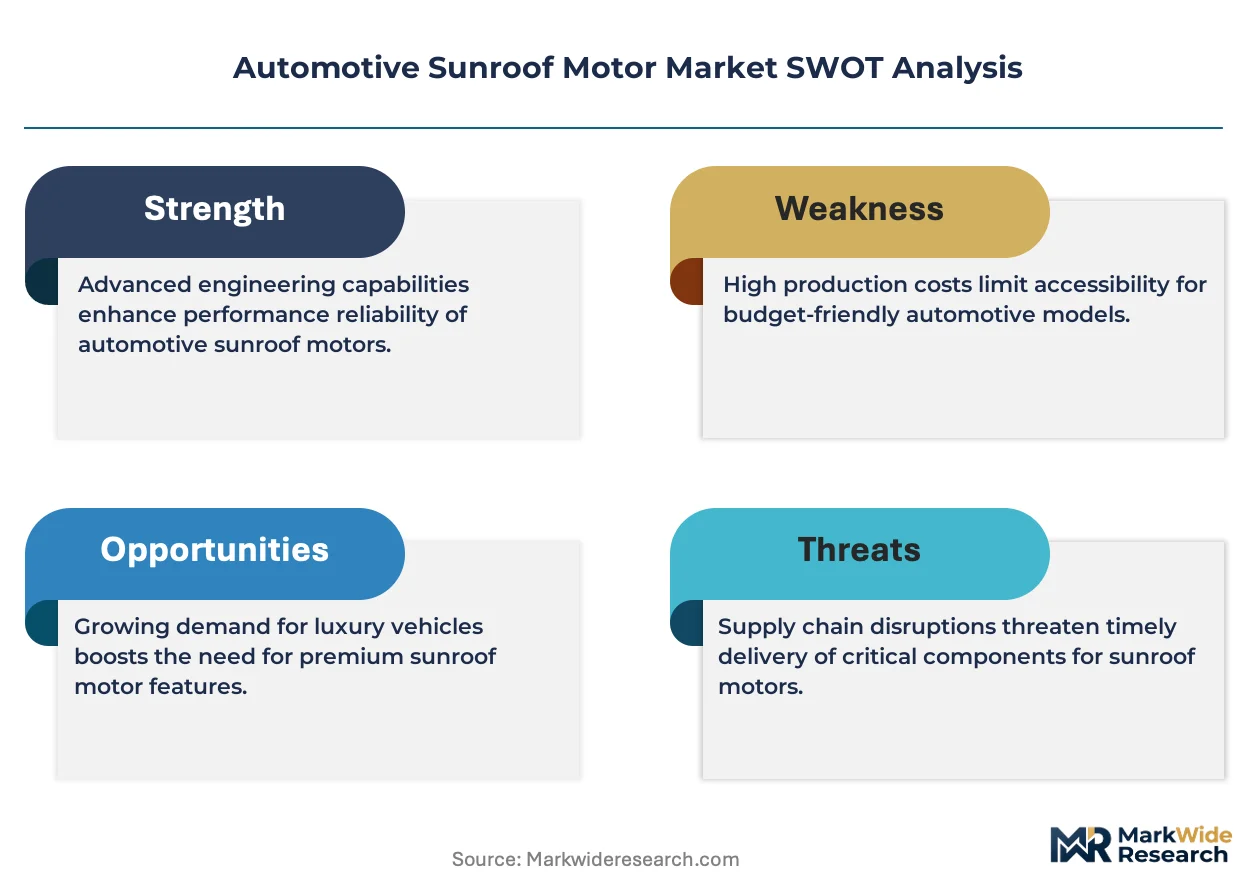
Platform consolidation among vehicle assemblers is compressing supplier tiers, forcing motor manufacturers to bundle electromechanical actuators with full roof system contracts rather than supplying standalone components.
Growth Catalysts
- Panoramic glass adoption:Crossover and SUV body styles in China are integrating full-length roof architectures that demand extended rail motors with higher torque density.
- EPA fuel-efficiency benchmarks:Corporate average fuel economy rules reward vehicle mass reduction, pulling demand toward aluminum rotor housings and magnesium gearboxes.
- Anti-pinch safety mandates:NHTSA Federal Motor Vehicle Safety Standard 118 requires precise force limitation and reversal response, expanding sensor-integrated motor deployments.
Market Restraints
- Neodymium price volatility:Rare-earth magnet cost swings constrain brushless DC motor margins and complicate long-term contract pricing.
- Single-source gear train concentration:Precision planetary gearbox production clusters in Germany and Japan create vulnerability to regional supply disruptions.
- Pneumatic legacy entrenchment:Aftermarket replacement channels for older European and North American vehicle fleets delay full electrification of installed base.
Strategic Opportunities
- Photovoltaic load management:Solar roof integration creates white space for motors with integrated power electronics managing dual energy flows.
- India's PLI scheme for auto components:Production-linked incentives for advanced automotive electronics attract motor controller manufacturing investments.
- Cybersecurity firmware validation:EU General Safety Regulation and emerging ISO/SAE 21434 standards open specialized engineering services for actuator network protection.
Industry Challenges
- Mechatronics talent scarcity:Embedded software engineers capable of Hall-effect sensor calibration and CAN bus protocol integration command premium compensation.
- Dual certification timelines:Simultaneous NHTSA and EU type-approval processes for new anti-pinch algorithms extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Sunroof Motor Market |
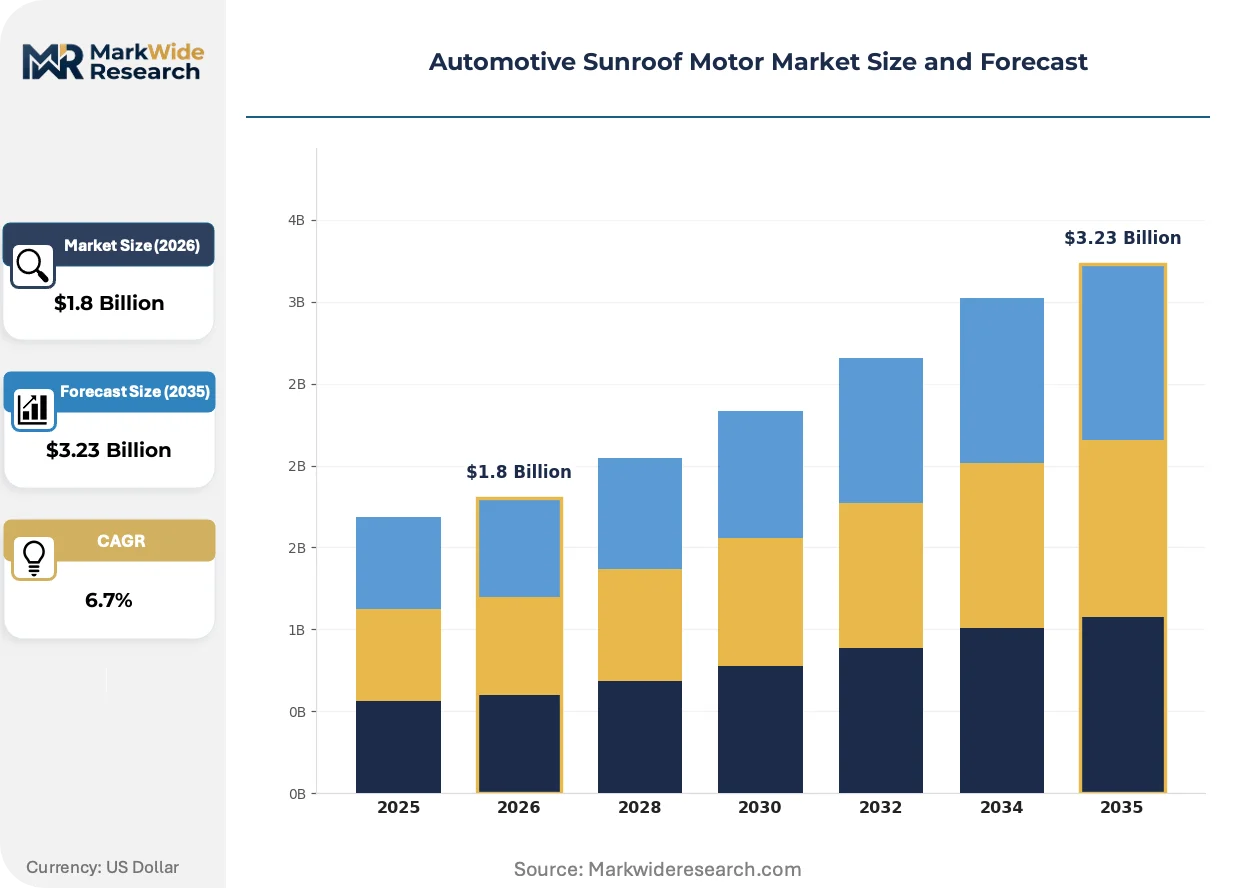
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding, Pop-up, Panoramic, Solar End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Electric, Pneumatic, Hydraulic, Mechanical Size: Small, Medium, Large, Custom |
| Companies Covered | Denso Corporation, Robert Bosch GmbH, Magna International, Continental AG, Johnson Electric, Mitsubishi Electric Corporation, Aisin Seiki, Webasto SE, Gentex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Sunroof Motor Market Evolving Landscape
Electrification of roof systems is converging with vehicle-wide domain architecture shifts, compressing the traditional separation between body control modules and distributed motor controllers.
Brushless DC motor technology with integrated position sensing is decentralizing control logic away from centralized body modules toward edge computing at the actuator level. Tier-1 suppliers are adopting these smart motors for sliding and pop-up configurations to reduce wiring harness complexity. This architecture is decentralizing fault diagnosis and enabling over-the-air calibration updates without dealer intervention.
EU General Safety Regulation mandates for intelligent speed assistance and pedestrian protection are extending to protruding roof components, forcing motor designers to embed force-feedback algorithms that detect obstructions before panel contact. The regulation compresses development timelines for new roof architectures. European luxury OEMs are responding by pre-certifying motor-gearbox assemblies as complete subsystems rather than validating components separately.
Fleet procurement of standardized motor platforms across multiple vehicle nameplates is displacing bespoke engineering for each model year. Tier-1 roof system integrators are consolidating motor specifications to capture volume pricing on Hall-effect sensors and thermal protection modules. This concentration is most visible in China, where domestic brands are adopting shared motor platforms across crossover, sedan, and MPV body styles to accelerate development cycles.
Automotive Sunroof Motor Market Segmentation
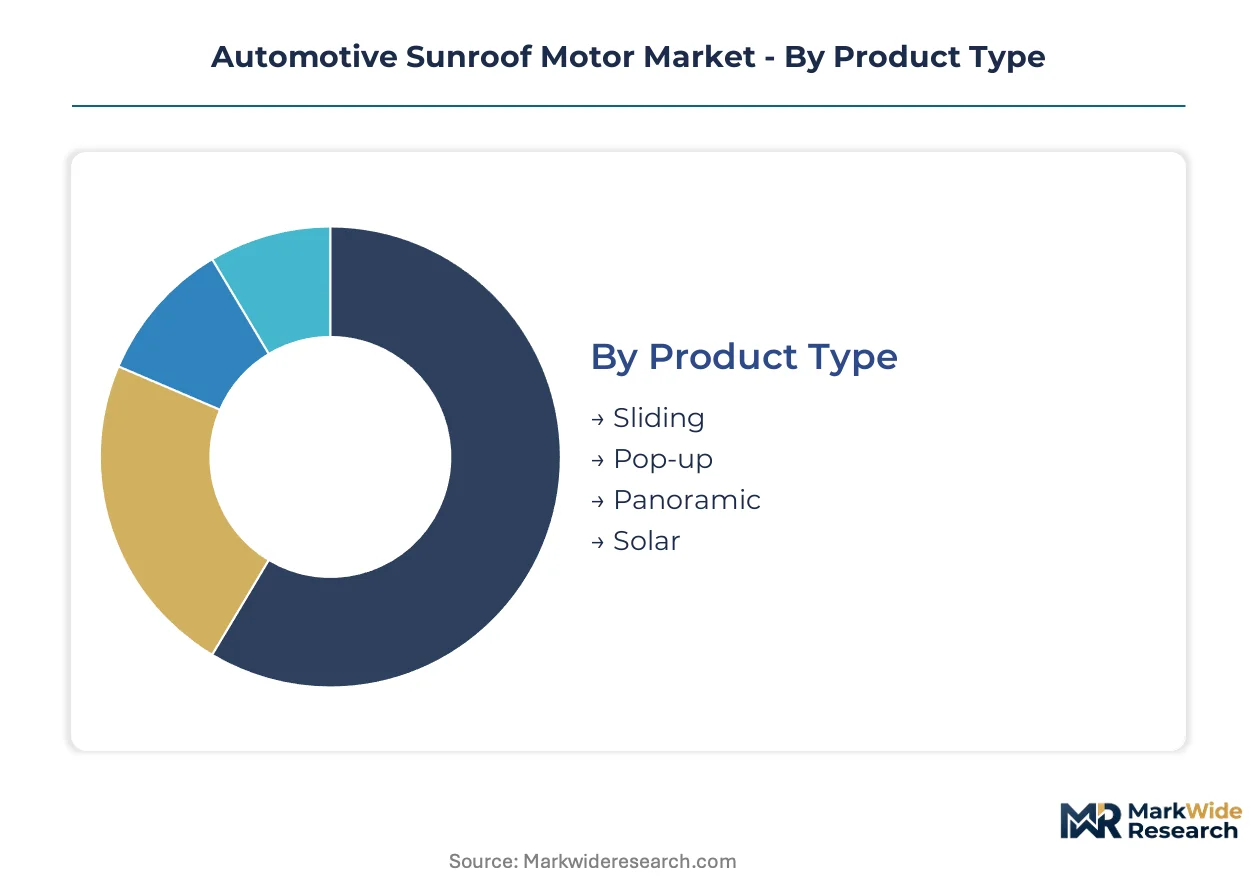
Automotive sunroof motor segmentation reveals how technical specifications, procurement channels, and vehicle integration requirements fragment supply strategies. Motor manufacturers must calibrate torque density, control architecture, and certification pathways differently across each dimension to capture platform contracts.
Product Type:
Customization intensity varies sharply across roof architectures, with fixed-panel designs demanding standardized motors while movable glass systems require bespoke actuator engineering.
- Panoramic:Extended rail lengths up to 1.5 meters demand brushless DC motors with 35-40 watt ratings and dual Hall-effect sensor arrays for synchronized panel movement. Crossover and SUV platforms in China concentrate procurement for full-length glass roofs, where NHTSA anti-pinch compliance adds firmware validation costs.
- Sliding:Single-panel horizontal actuation employs compact 15-25 watt motors with integrated thermal overload protection and CAN bus modules for body control synchronization. OEM platform consolidation favors this configuration for mid-tier sedan and hatchback nameplates.
- Pop-up:Tilt-and-vent mechanisms utilize lower-torque motors with simplified gear trains for angular displacement rather than linear travel.
- Solar:Photovoltaic roof integration requires motors with embedded power electronics managing dual energy flows between panel actuation and battery charging circuits.
Leading the category by volume: Sliding. Growing fastest: Panoramic.
End User:
Procurement authority concentrates at distinct supply chain tiers, with platform-level contracts displacing component-level sourcing for new vehicle programs.
- OEMs:Vehicle assemblers with captive roof system divisions specify motor torque curves, connector pinouts, and cybersecurity protocols for multi-nameplate platforms. EPA fuel-efficiency benchmarks reward their direct engagement in mass-reduction engineering.
- Tier-1 Suppliers:Full roof system integrators bundle motor procurement with rail mechanisms, drainage channels, and sealing systems, compressing supplier tiers and demanding mechatronics partnerships.
- Aftermarket Providers:Replacement channel distributors stock legacy pneumatic and hydraulic motor variants for aging European and North American vehicle fleets.
- Vehicle Assemblers:Contract manufacturers and emerging EV specialists source pre-certified motor-gearbox subassemblies to accelerate homologation timelines.
Contract concentration: Tier-1 Suppliers. Margin pressure point: Aftermarket Providers.
Technology:
Electrification maturity separates growth platforms from declining maintenance revenue streams across motor architectures.
- Electric:Brushless DC designs with integrated position sensing decentralize control logic toward edge computing at the actuator level, reducing wiring harness complexity for sliding and pop-up configurations. NHTSA Federal Motor Vehicle Safety Standard 118 mandates precise force limitation and reversal response thresholds.
- Pneumatic:Compressed-air actuation persists in aftermarket replacement channels for legacy European vehicle populations, though new platform development has ceased.
- Hydraulic:Fluid-power systems retreat to specialized heavy-duty applications and vintage model support, displaced by electromechanical efficiency gains.
- Mechanical:Manual crank mechanisms survive in entry-market segments and regulatory-compliant emergency override functions.
Dominant share: Electric. Steepest decline trajectory: Hydraulic.
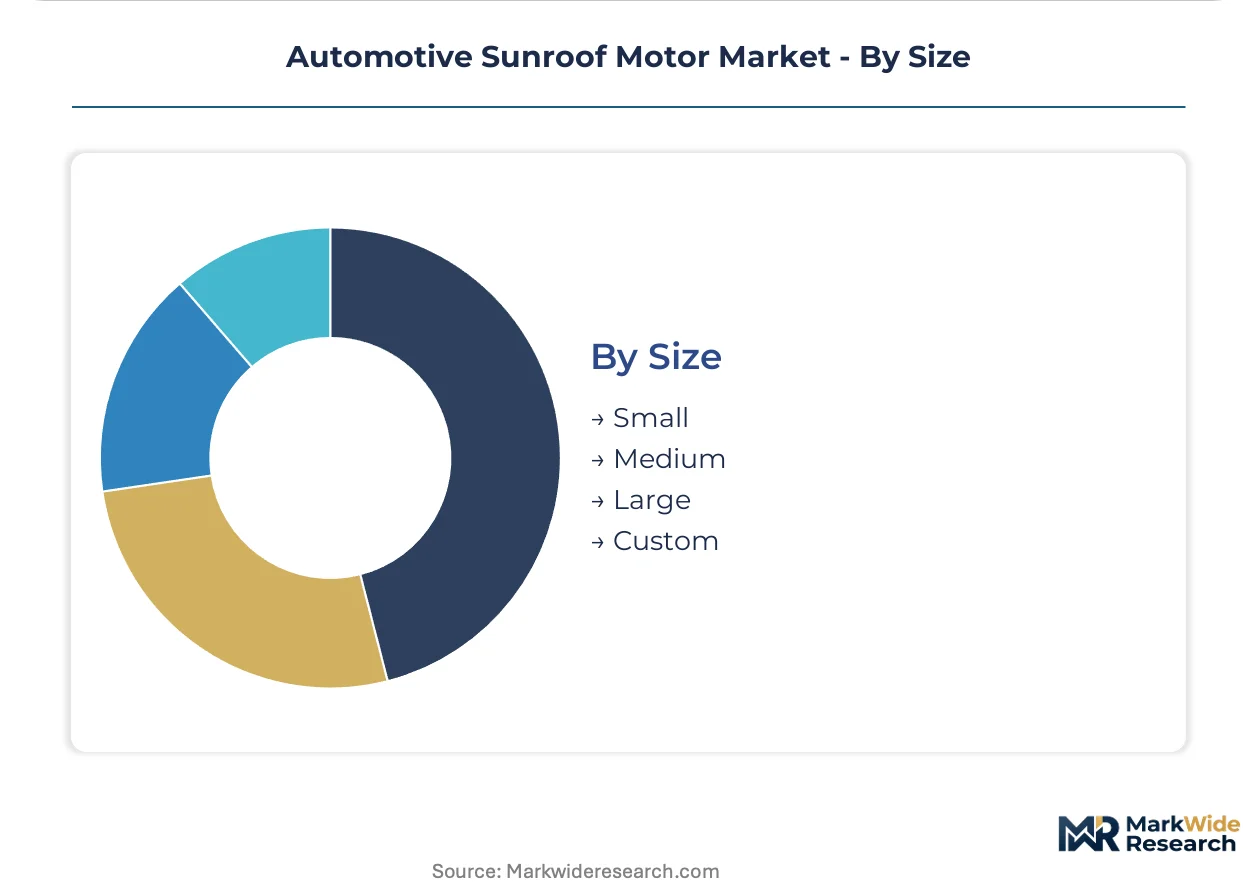
Size:
Physical envelope constraints correlate directly with vehicle body style trends and glass roof expansion ratios.
- Large:Full-length panoramic applications in crossover and SUV architectures require extended motor housings with magnesium gearboxes and aluminum rotors to satisfy EPA corporate average fuel economy mass targets.
- Medium:Mid-size sliding panels for sedans and compact SUVs balance torque density against packaging constraints in roof header assemblies.
- Small:Pop-up vent mechanisms and luxury coupe applications utilize compact 15-watt motors with minimal rail integration complexity.
- Custom:Bespoke coachbuilt and ultra-luxury vehicles demand application-specific motor engineering with extended development cycles.
Highest unit volume: Medium. Fastest specification expansion: Large.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the largest share of sunroof motor procurement as domestic vehicle brands expand panoramic glass fitment across crossover and SUV lineups. Germany and the United States anchor precision manufacturing clusters for brushless DC motor assemblies. Japan and South Korea maintain captive supply relationships with domestic vehicle assemblers.
China
Domestic brands including BYD and Geely are integrating full-length glass roofs across mid-tier crossover nameplates, requiring extended rail motors with 35-40 watt ratings. MIIT fuel-consumption standards push suppliers toward aluminum rotor housings to reduce vehicle mass. The Yangtze River Delta hosts concentrated production of Hall-effect sensor arrays and motor controller modules serving both local OEMs and export programs.
Germany
Luxury vehicle assemblers headquartered in Stuttgart and Munich specify pre-certified motor-gearbox subassemblies to compress EU General Safety Regulation homologation timelines. KBA type-approval processes mandate embedded force-feedback algorithms for pedestrian protection compliance. The Baden-Württemberg industrial corridor houses precision planetary gearbox manufacturing clusters supplying European and Asian roof system integrators.
United States
Detroit-based OEMs are consolidating sunroof motor sourcing with full roof system contracts under platform standardization strategies. NHTSA Federal Motor Vehicle Safety Standard 118 requires precise motor force limitation and reversal response thresholds. The Southeast manufacturing belt spanning Tennessee and South Carolina attracts motor controller assembly investments serving regional vehicle assembly plants.
Japan
Toyota Motor and Honda Motor maintain captive production lines co-located with domestic motor suppliers to synchronize just-in-time delivery with vehicle assembly schedules. METI carbon-neutrality roadmaps incentivize brushless DC motor adoption over legacy hydraulic systems. The Aichi prefecture cluster around Nagoya concentrates mechatronics engineering talent for Hall-effect sensor calibration and CAN bus protocol integration.
South Korea
Hyundai Motor and Kia Corporation are expanding panoramic roof fitment rates across electric SUV platforms, pulling demand for high-torque density motors. MFDS automotive safety standards align with NHTSA anti-pinch mandates for export vehicle programs. The Busan-Ulsan industrial complex hosts motor winding and rotor assembly operations supplying both domestic OEMs and North American vehicle plants.
Automotive Sunroof Motor Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue photovoltaic load management and cybersecurity firmware validation services. The supplier base compresses into three tiers: integrated mechatronics conglomerates with captive automotive divisions, specialized fractional horsepower motor fabricators, and roof system integrators bundling electromechanical actuators with sealing and drainage components. Competitive positioning depends on multi-year supply agreement tenure, torque density specifications, and synchronized development cycle alignment with vehicle platform launches. M&A activity concentrates on sensor-integrated motor portfolios, while capacity expansion targets co-location with high-volume vehicle assembly clusters.
Within the integrated tier, Denso Corporation and Robert Bosch GmbH exemplify archetypes of conglomerates leveraging captive production networks and cross-divisional technology portfolios. Johnson Electric occupies a position among specialized motor fabricators competing on compact torque density for sliding and pop-up configurations. These three anchors demonstrate how geographic proximity to vehicle assembly clusters and firmware integration capabilities separate contract winners from component suppliers.
| Leading Market Players |
|---|
| Denso Corporation |
| Robert Bosch GmbH |
| Magna International |
| Continental AG |
| Johnson Electric |
| Mitsubishi Electric Corporation |
| Aisin Seiki |
| Webasto SE |
| Gentex Corporation |
| Others |
Value Network & Pricing Analysis
Tier-1 roof system integrators concentrate procurement authority, locking motor suppliers into long-term contract structures that bundle electromechanical actuators with full roof assemblies. This buyer concentration compresses component-level pricing power while rewarding synchronized development cycle alignment with vehicle platform launches.
Pricing Analysis
High-volume sliding motor programs sacrifice margin for platform tenure, while low-volume panoramic and solar configurations capture premium positioning through torque density differentiation and embedded power electronics. Price stratification across premium, standard, and economy tiers reflects certification grade, volume scale, and Hall-effect sensor integration depth. Pricing pressure stems from neodymium magnet cost volatility constraining brushless DC motor margins. Aftermarket providers face acute price sensitivity due to legacy pneumatic replacement demand, whereas OEM captive sourcing demonstrates lower sensitivity to unit cost fluctuations.
Supply Chain Analysis
Refurbishment flows for legacy hydraulic and pneumatic motors sustain aftermarket channels, while forward logistics prioritize brushless DC assemblies for new platform deployment. Manufacturing gravity centers on Germany, China, and Japan, with precision planetary gearbox production clustering in Baden-Württemberg and Aichi prefecture. Rare-earth magnet supply draws from concentrated extraction regions, creating vulnerability to commodity price swings. Single-source gear train concentration in Germany and Japan presents regional disruption risk. Distribution runs through Tier-1 roof system integrators bundling motors with rail mechanisms and sealing systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless DC motor controller fabrication capacity constitutes the binding constraint propping pricing for qualified suppliers, as mechatronics talent scarcity limits rapid scale-up of Hall-effect sensor calibration and CAN bus firmware validation capabilities.
For Market Incumbents: Anchor multi-year supply agreements through co-location investments near high-volume vehicle assembly clusters in China and the Southeast United States. Deepen captive production of Hall-effect sensor arrays to defend against emerging cybersecurity firmware validation specialists. Prioritize NHTSA and EU dual certification pipelines to compress launch cycles for new anti-pinch algorithms. For New Entrants and Emerging Players: India's production-linked incentive scheme for advanced automotive electronics offers the most penetrable entry point for motor controller manufacturing investments. Photovoltaic load management integration for solar roof systems presents white-space opportunity with limited incumbent specialization. Pursue direct partnerships with domestic Chinese brands adopting shared motor platforms across crossover and MPV body styles. For Investors and Strategic Acquirers: The window for entry favors sensor-integrated motor portfolios with embedded position sensing and edge computing capabilities. Acquisition targets should demonstrate synchronized development cycle alignment with vehicle platform launches and multi-year supply agreement tenure. Monitor EU General Safety Regulation enforcement timelines as inflection indicators for force-feedback algorithm certification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidates motor specifications across crossover, sedan, and MPV body styles to capture volume pricing. |
| Backward Integration into Sensor Arrays | Captures Hall-effect calibration capabilities and reduces dependency on single-source German suppliers. |
| Cybersecurity Firmware Validation | Addresses emerging ISO/SAE 21434 standards for actuator network protection in EU and North American markets. |
| Geographic Manufacturing Footprint | Co-locates controller assembly with Yangtze River Delta and Southeast US vehicle production clusters. |
| Photovoltaic Load Management Integration | Enables dual energy flow management for solar roof systems in premium electric SUV platforms. |
Research Methodology
Multi-period observation of vehicle production databases, sunroof fitment rates, and rare-earth magnet price indices anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and mechatronics firmware specialists. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standard 118 filings, EPA corporate average fuel economy documentation, EU General Safety Regulation implementation notices, and MIIT fuel-consumption standard updates. Bottom-up motor shipment estimates triangulated against top-down vehicle production forecasts.
The input-output matrix mapped torque density specifications, control architecture requirements, and certification pathways across product type, end user, technology, size, and regional production cluster dimensions. CAGRs were derived from regression analysis of historical fitment rate trajectories and platform consolidation patterns. Industry-specific forecast inputs incorporated Hall-effect sensor cost curves and brushless DC motor adoption rates by vehicle class.
Revisions become necessary when neodymium price volatility exceeds historical bands, when cybersecurity standards reshape firmware validation protocols, or when platform consolidation accelerates beyond modeled timelines. Practitioners should monitor EU type-approval process durations and MIIT policy adjustments for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Car Charger Market
Electric Motor
Europe Alternating Current (AC) Motor Market
Electric Motor
Kayak Trolling Motor Market
Electric Motor
UK Solar E-Bike Market
Electric Motor
Brush Motor Control Unit Market
Electric Motor
Starter Motor Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
Automotive in-Wheel Motors Market
Electric Motor
Two Wheeler Electric Starter Magnet Market
Electric Motor
Electric Trolling Motors Market
Electric Motor
Separately Excited Motor Market
Electric Motor
Intelligent Motor Control Center Market
Electric Motor
Automotive Induction Motors Market
Electric Motor
Intelligent Motor Controller Market
Electric Motor
Europe Automotive Torque Actuator Motor Market
Electric Motor
Traction Motor Core Market