
 EV Traction Motor Control Unit Market | 2026-2036
EV Traction Motor Control Unit Market Size, Share, and Industry Trends Forecast 2026-2036
EV Traction Motor Control Unit Market Insights
The acute shortage of power electronics engineers is unwinding as universities in Bavaria, Michigan, and Shanghai expand specialized semiconductor curricula. Bosch leverages in-house wafer fabrication to sustain margin control across inverter module production. Nidec Corporation anchors its competitive stance through dedicated motor-inverter integration expertise for Japanese and Chinese OEM platforms.
An EV traction motor control unit governs power conversion between the battery pack and the electric motor, typically managing DC-to-AC inversion at switching frequencies between 10 and 20 kHz to optimize torque response and thermal efficiency. Its primary purpose is to modulate voltage, current, and frequency in real time to match driver demand while protecting semiconductor junctions from thermal runaway. Inverter components command the dominant share of value within the component type dimension, reflecting their direct impact on drivetrain efficiency and their exposure to SiC and GaN material upgrades. Passenger vehicles absorb the bulk of volume within the application dimension, though heavy-duty vehicles represent a concentrated margin pool where high-voltage architectures and ruggedized thermal management justify premium pricing.
The EPA tailpipe emission standards and the EU Green Deal's 2035 ICE phase-out mandate are compressing development timelines and forcing OEMs to source control units from qualified suppliers with proven automotive-grade reliability records. China's MIIT new-energy vehicle credit system and GB/T standards for electromagnetic compatibility shape product specifications for any supplier accessing domestic production lines. Stakeholders must monitor how battery voltage platform migration toward 800V architectures reshapes inverter semiconductor specifications and supplier qualification requirements.
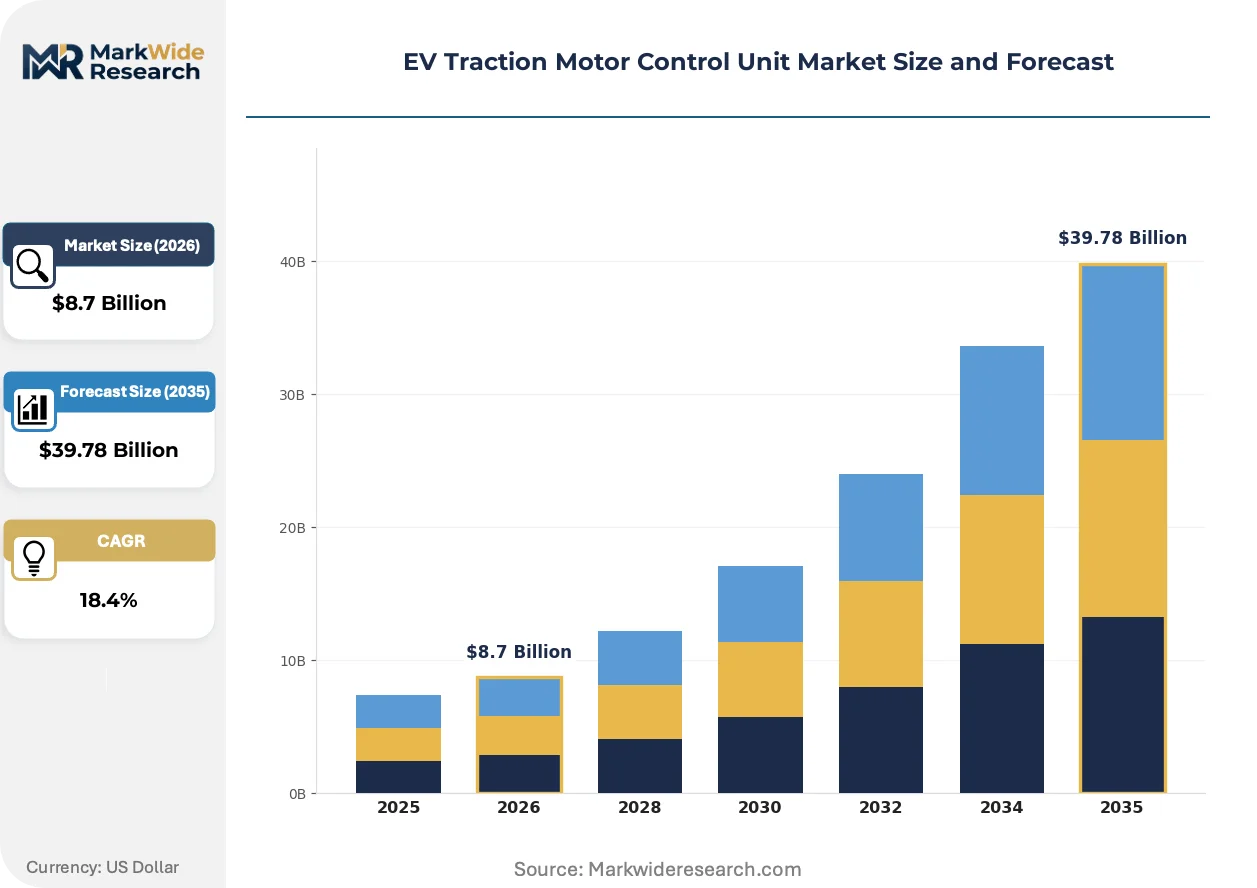
Market Dynamics
The migration toward 800V battery architectures is compressing inverter semiconductor specifications and forcing wholesale redesigns of thermal management systems across passenger and commercial vehicle platforms.
Growth Catalysts
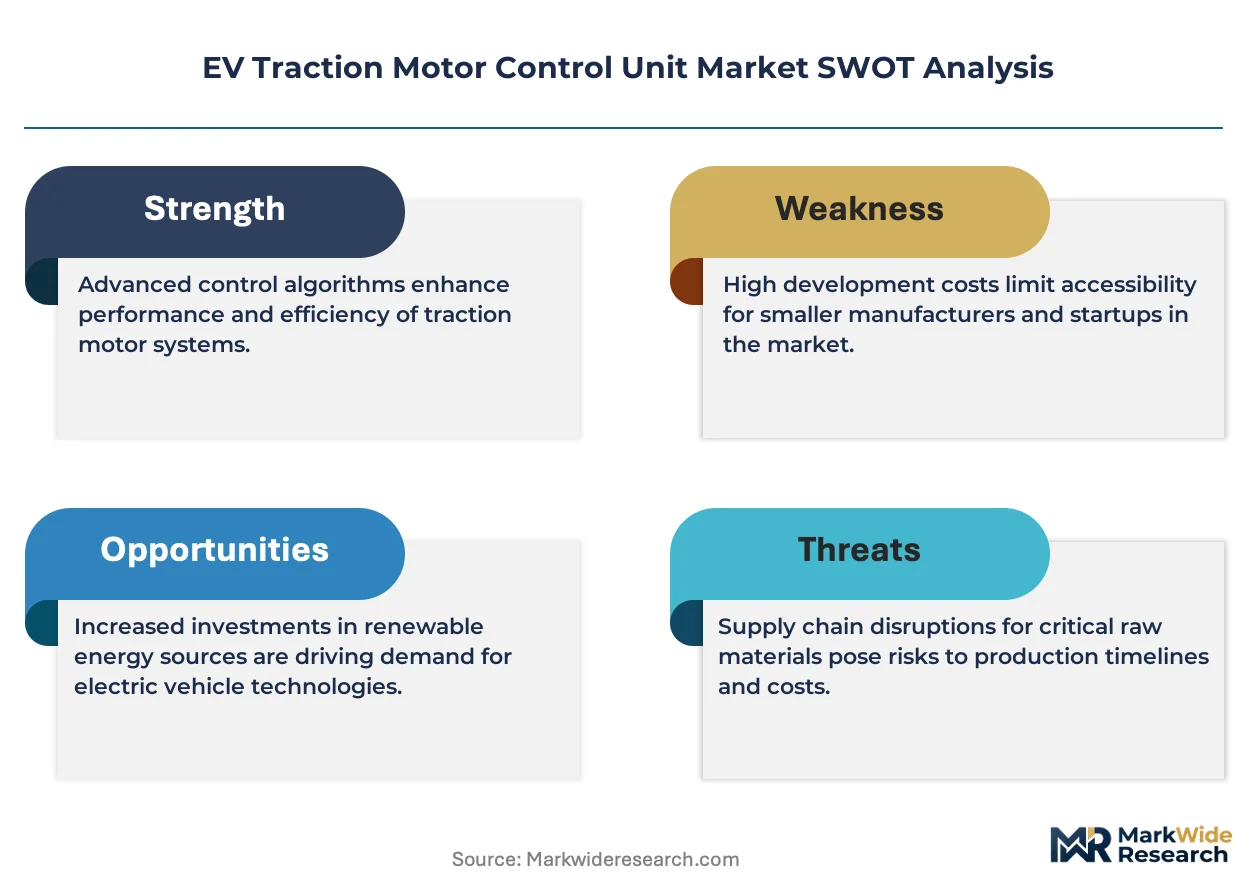
- EU Green Deal ICE Phase-Out:The 2035 ban on internal combustion engines mandates EV-only sales, forcing OEMs to lock in multi-year control unit supply agreements with qualified vendors.
- Silicon Carbide Wafer Scaling:SiC substrate manufacturing expansion in China and Germany is lowering unit costs for power modules while enabling switching frequencies above 20 kHz.
- Heavy-Duty Electrification:Battery-electric trucks and buses require ruggedized inverters with liquid cooling, opening premium-margin procurement pools distinct from passenger vehicle commoditization.
Market Restraints
- Neodymium and Dysprosium Volatility:Rare earth magnet price swings embedded in motor-inverter integrated units create margin unpredictability for suppliers without long-term offtake contracts.
- Wafer Fabrication Concentration:SiC epitaxy capacity clusters in Bavaria and Hokkaido expose the supply base to single-point disruption from seismic or energy grid events.
- Automotive-Grade Qualification Timelines:AEC-Q101 and AQG-324 testing protocols stretch 18-24 months, freezing out new entrants regardless of technical merit.
Strategic Opportunities
- India PLI Scheme for Auto:Production-linked incentives for advanced automotive technology are drawing inverter assembly investments toward Tamil Nadu and Gujarat manufacturing clusters.
- Motor-Inverter Integration:Co-design of power electronics and e-axle systems eliminates interconnect losses and reduces packaging volume for platform-native EV architectures.
- Direct-to-OEM Digital Procurement:Cloud-based supplier portals are displacing tiered distribution, enabling real-time specification updates and volume commitment adjustments.
Industry Challenges
- Power Electronics Engineering Scarcity:Specialized talent in wide-bandgap semiconductor design remains concentrated in Munich, Detroit, and Shanghai, forcing wage inflation elsewhere.
- Multi-Voltage Platform Complexity:Simultaneous engineering for 400V legacy and 800V next-generation vehicles doubles validation overhead without commensurate volume splits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Traction Motor Control Unit Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Inverter, Converter, Microcontroller, Sensor End User: OEMs, Aftermarket Suppliers, Ride-Hailing Services, Fleet Operators Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Vehicles Installation Type: Integrated, Standalone, Semi-Integrated, Modular |
| Companies Covered | Bosch, Continental, Nidec Corporation, ZF Friedrichshafen, Magna International, Denso Corporation, Hitachi, Siemens, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Traction Motor Control Unit Market Trends and Innovations
Wide-bandgap semiconductors and embedded thermal management are redrawing the technical boundaries between inverter hardware and motor design, collapsing traditional supplier silos.
Gallium nitride power devices are fragmenting the high-frequency inverter segment previously dominated by silicon IGBTs. GaN transistors enable switching above 100 kHz, permitting smaller magnetics and passive components. Tier 1 suppliers in Japan and South Korea are sampling GaN modules for 400V passenger vehicle platforms, though 800V architectures retain SiC preference due to breakdown voltage requirements. The technology is fragmenting procurement patterns as OEMs dual-source SiC and GaN for different voltage tiers.
China's MIIT new-energy vehicle credit system is tightening electromagnetic compatibility thresholds under revised GB/T standards. Domestic OEMs must demonstrate compliance with conducted and radiated emission limits that exceed prior baselines by 6 dB. Suppliers without in-country testing laboratories face exclusion from platform nominations, accelerating localization of validation capacity in Suzhou and Shenzhen.
Fleet operators are consolidating procurement decisions at the holding-company level, displacing brand-by-brand sourcing that historically fragmented inverter specifications. Rental and logistics fleets in Germany and California now mandate common control unit architectures across multi-brand vehicle portfolios. This concentration is compressing supplier diversity and rewarding vendors with cross-platform software configurability.
EV Traction Motor Control Unit Market Segmentation
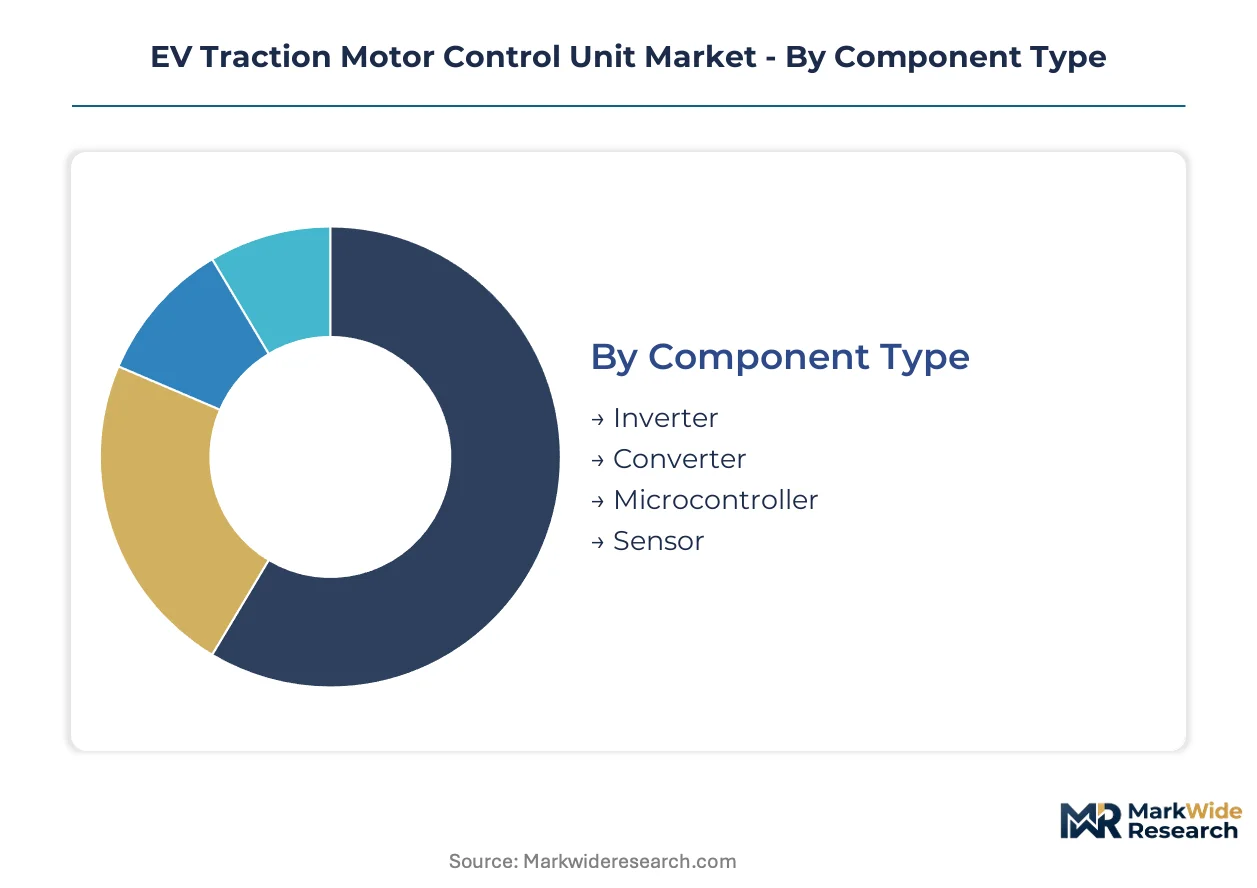
Segmentation in the EV traction motor control unit market reveals how value concentrates differently across hardware layers, customer procurement models, and vehicle integration philosophies. Understanding these divisions exposes where suppliers can defend pricing power versus where commoditization pressures dominate.
Component Type:
Margin pools concentrate in power semiconductor modules and their thermal management subsystems, with differentiation fading rapidly in commodity sensing and basic control logic.
- Inverter:Power modules execute DC-to-AC conversion at switching frequencies between 10 and 20 kHz, with silicon carbide substrates enabling higher power density than silicon IGBT predecessors. Demand clusters in battery-electric passenger vehicle platforms from Chinese and German OEMs where drivetrain efficiency ratings directly influence consumer purchase decisions.
- Converter:DC-to-DC stages step voltage between battery pack and auxiliary systems, requiring ruggedized designs for 800V architectures rolling out across premium European and Korean vehicle lines. Procurement volumes are accelerating as dual-voltage platforms become standard in next-generation EV architectures.
- Microcontroller:Embedded processors execute torque vectoring algorithms and thermal protection routines, with automotive-grade qualification requirements limiting supplier pools to established semiconductor vendors.
- Sensor:Current and temperature sensing elements provide real-time feedback loops for motor protection, facing price compression from multi-sensor integration trends.
Inverter holds installed capacity. Converter is rotating up the share rankings.
End User:
Procurement concentration varies sharply between direct OEM relationships and fragmented aftermarket channels, with fleet operators emerging as disciplined price negotiators.
- OEMs:Original equipment manufacturers specify control units at the platform architecture stage, locking in multi-year supply agreements with qualified vendors. German and Chinese automakers dominate procurement volumes as domestic production scales accelerate.
- Fleet Operators:Rental and logistics holding companies now mandate common control unit architectures across multi-brand portfolios, compressing supplier diversity and rewarding cross-platform software configurability.
- Aftermarket Suppliers:Replacement and retrofit channels serve aging EV populations, with demand concentrated in California and Norway where early adoption created installed bases requiring component refresh.
- Ride-Hailing Services:High-utilization vehicle operators prioritize durability and service interval predictability over upfront cost, sourcing through fleet management intermediaries rather than direct manufacturer relationships.
OEMs hold installed capacity. Fleet operators are rotating up the share rankings.
Application:
Vehicle class determines thermal management requirements and voltage platform selection, with heavy-duty applications commanding premium pricing for ruggedized designs.
- Passenger Vehicles:Battery-electric cars and crossovers absorb the dominant share of control unit volume, with 400V and 800V architectures splitting procurement specifications across mass-market and premium segments. Chinese domestic brands and Tesla drive the steepest expansion trajectory in absolute unit terms.
- Heavy-Duty Vehicles:Battery-electric trucks and buses require liquid-cooled inverters with extended duty cycles, opening concentrated margin pools distinct from passenger vehicle commoditization pressures.
- Commercial Vehicles:Delivery vans and light trucks balance payload constraints with range requirements, favoring integrated motor-inverter packages that reduce packaging volume.
- Two-Wheelers:Electric scooters and motorcycles operate at lower voltage tiers with simplified thermal management, representing high-volume, low-margin procurement concentrated in Indian and Southeast Asian markets.
Passenger vehicles hold installed capacity. Heavy-duty vehicles are rotating up the share rankings.
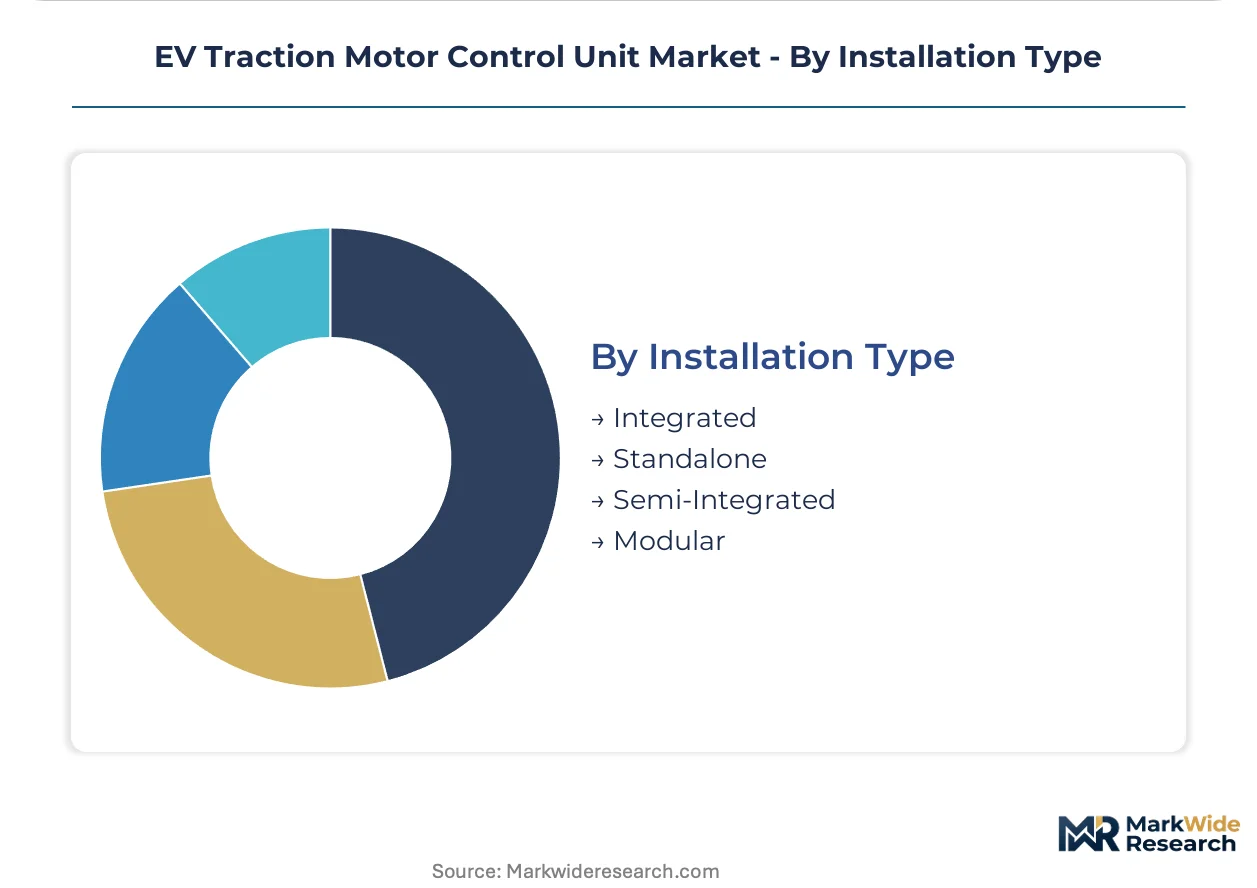
Installation Type:
Integration philosophy directly impacts bill-of-materials complexity and service accessibility, with platform-native designs displacing retrofit configurations.
- Integrated:Motor-inverter co-design eliminates interconnect losses and reduces packaging volume, becoming standard for dedicated EV architectures from Korean and Chinese OEMs.
- Modular:Swappable sub-assemblies enable field serviceability and platform flexibility, appealing to commercial fleet operators with diverse vehicle configurations.
- Standalone:Separately housed inverters persist in conversion applications and legacy platform adaptations, losing share to integrated alternatives.
- Semi-Integrated:Partial integration splits power stage from control electronics, occupying a narrowing middle ground as thermal management requirements tighten.
Integrated holds installed capacity. Modular is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's Bavaria corridor while Chinese suppliers compete on volume throughput. The United States captures premium margins through domestic content incentives. Japan and South Korea defend technology premiums through integrated motor-inverter architectures.
China
Domestic OEM procurement volumes exceed any other single country, driven by BYD and CATL platform expansion. MIIT's new-energy vehicle credit system tightens electromagnetic compatibility thresholds under revised GB/T standards. Suzhou and Shenzhen host concentrated validation laboratories serving both local and foreign suppliers seeking market access.
Germany
Bavarian wafer fabrication clusters anchor European SiC supply security for premium vehicle platforms. The EU Green Deal's 2035 ICE phase-out compresses supplier qualification timelines. Stuttgart and Munich engineering centers concentrate power electronics talent pools for next-generation 800V inverter development.
United States
IRA domestic content requirements reshape procurement toward North American assembly capacity. EPA tailpipe emission standards accelerate heavy-duty electrification timelines. Michigan's engineering corridor sustains inverter design expertise while Tennessee and Texas attract battery plant co-location investments.
Japan
Integrated motor-inverter co-design expertise commands persistent technology premiums from Toyota and Honda platforms. METI funding programs support wide-bandgap semiconductor manufacturing scale-up. Nagoya and Tokyo metropolitan areas concentrate specialized power electronics engineering talent.
South Korea
Hyundai-Kia platform architectures drive concentrated demand for compact, high-power-density inverter modules. Government battery technology initiatives extend into power electronics supply chain localization. Seoul Capital Area and Busan-Ulsan manufacturing belts host tiered supplier ecosystems for export-oriented production.
EV Traction Motor Control Unit Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. The vendor base clusters around three strategic positions: integrated system suppliers with captive semiconductor capacity, specialized motor-inverter co-designers, and modular component vendors serving aftermarket channels. Capacity expansion and strategic partnerships dominate competitive moves as qualification timelines freeze out new entrants.
Within the integrated system tier, Bosch exemplifies backward integration into wafer fabrication. Nidec Corporation occupies a position as a dedicated motor-inverter integration specialist. Continental represents the diversified automotive supplier archetype with broad platform coverage across voltage tiers.
| Leading Market Players |
|---|
| Bosch |
| Continental |
| Nidec Corporation |
| ZF Friedrichshafen |
| Magna International |
| Denso Corporation |
| Hitachi |
| Siemens |
| ABB |
| Others |
Pricing and Supply Chain Analysis
Wafer fabrication scale economies in Bavaria and Hokkaido concentrate SiC substrate supply, compressing unit costs for qualified suppliers while erecting price floors for entrants lacking captive epitaxy capacity or long-term OEM supply agreements.
Pricing Analysis
Configured-to-order pricing for 800V SiC inverter modules commands substantial premiums over standard 400V silicon IGBT configurations, with price differentiation resting on AEC-Q101 certification tier and volume commitment scale. Three-tier pricing structure across premium, standard, and economy levels separates automotive-grade qualified modules from industrial-grade alternatives and unvalidated prototypes. Cost compression in silicon-based legacy tiers is intensifying because Chinese suppliers are flooding 400V passenger vehicle procurement pools. Fleet operators exhibit highest price sensitivity through consolidated holding-company negotiations, while premium German OEMs remain least sensitive due to platform performance requirements.
Supply Chain Analysis
Strategic stockpiling of SiC wafers and rare earth magnets dominates inventory strategy among Japanese and German Tier 1 suppliers, contrasting with just-in-time preferences for commodity sensing components and standard microcontrollers. Supply concentrates in China for rare earth processing and magnet fabrication, Germany for SiC epitaxy and automotive qualification, and Japan for integrated motor-inverter system assembly. Raw material dependencies include neodymium-dysprosium magnet alloys, high-purity SiC substrates, and copper busbar stock. Single-source vulnerability around SiC epitaxy equipment exposes the supply base to extended lead time disruptions. Distribution runs through direct OEM platform engineering channels with limited aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as 800V platform proliferation and heavy-duty electrification create specialist niches beyond the reach of integrated system giants. Dual-voltage engineering requirements and divergent thermal management specifications reward focused co-design expertise.
For Market Incumbents: Secure captive SiC wafer supply through backward integration into epitaxy capacity or binding offtake contracts with emerging Chinese substrate vendors. Lock in multi-year platform nominations with German and Korean OEMs before AEC-Q101 qualification timelines freeze out alternatives. Prioritize motor-inverter integration R&D to defend against modular suppliers encroaching on e-axle content share.
For New Entrants and Emerging Players: Lead with GaN-based 400V inverter modules for cost-sensitive Chinese domestic OEM platforms where SiC premiums face procurement resistance. Target India's Tamil Nadu and Gujarat manufacturing clusters leveraging PLI scheme incentives before incumbent assembly footprint solidifies. Pursue fleet operator direct procurement relationships bypassing tiered distribution channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among motor-inverter integration specialists with multi-platform software configurability and long-term service contracts. Long-term viability favors suppliers with demonstrated 800V qualification records and in-country validation laboratories in China. Acquisition target archetype: mid-cap SiC module designers with automotive-grade certification progress but constrained by working capital. Watch for inflection when MIIT credit system revisions force GB/T electromagnetic compliance upgrades.
| Strategic Initiative | Industry Significance |
|---|---|
| Motor-Inverter Co-Design Investment | Eliminates interconnect losses for Hyundai-Kia and BYD platform architectures. |
| Domestic Wafer Fabrication Expansion | Bosch's in-house SiC epitaxy insulates margin control from substrate volatility. |
| 800V Thermal Management Redesign | Liquid-cooled architectures unlock premium procurement pools in heavy-duty segments. |
| Cloud-Based Direct Procurement Portal | Enables real-time specification updates for fleet operator volume commitments. |
| In-Country Validation Laboratory Buildout | Suzhou and Shenzhen facilities secure MIIT GB/T compliance access. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, power electronics engineering directors, and fleet operator holding-company executives; and secondary validation against SEC filings, MIIT new-energy vehicle credit system documentation, vehicle production databases, and customs/trade flow records. Bottom-up unit demand modeling triangulated against top-down market sizing from semiconductor vendor revenue disclosures.
Across the projection horizon, analytical frameworks segmented volume and value by component type, end user procurement model, vehicle application class, and installation integration philosophy. CAGRs derived from regression analysis of historical SiC adoption curves, battery platform voltage migration timelines, and OEM production capacity announcements. Industry-specific forecast inputs included AEC-Q101 qualification pipeline status and MIIT credit system threshold revisions.
The analysis sits within stated boundaries; outcomes outside sustained 800V platform rollout, stable rare earth magnet supply, and continued IRA domestic content enforcement would require recalibration. Forecasts reflect assumptions regarding OEM dual-sourcing preferences and fleet operator consolidation trajectories. Revision becomes warranted when SiC epitaxy capacity expansion crosses thresholds that eliminate current supply constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Electric Vehicle Motor (EVM) Controller Market
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
Europe Electric Motor Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Automotive Sunroof Motor Market
Electric Motor
Starter Motor Market
Electric Motor
Intelligent Motor Control Center Market
Electric Motor
Europe Alternating Current (AC) Motor Market
Electric Motor
North America Alternating Current (AC) Motor Market
Electric Motor
Electric Motors for IC Engine Vehicle Market
Electric Motor
Automotive Seat Motor Market
Electric Motor
UAE Electric Motor Market
Electric Motor
Europe Electric Motors for Electric Vehicle Market
Electric Motor
Electric Vehicle Traction Motor Core Market
Electric Motor
GCC Electric Motor Market
Electric Motor
Electric Propulsion Systems Market