
 Infectious Enteritis Treatment Market | 2026-2036
Infectious Enteritis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Infectious Enteritis Treatment Market Outlook
REACH compliance is restructuring manufacturing requirements for active pharmaceutical ingredients destined for European markets. GlaxoSmithKline leverages captive vaccine production networks across multiple continents. Pfizer sustains dominance in oral antibiotic formulations through dedicated fermentation capacity. Merck anchors its position with intravenous antiparasitic portfolios that serve tertiary care systems.
Infectious enteritis treatment encompasses pharmacological and biological interventions targeting acute or chronic intestinal mucosal inflammation caused by pathogenic microorganisms, typically administered via oral, intravenous, rectal, or topical routes depending on severity and pathogen type. These therapies function by eradicating causative agents, modulating host immune response, or restoring commensal microbiota balance to halt diarrheal fluid loss and prevent systemic sepsis. Antibiotics command the largest revenue pool among product types due to entrenched bacterial enteritis prevalence, while probiotics represent the fastest-expanding category as clinicians integrate microbiome restoration into standard protocols. The hospital end-user segment captures premium pricing for intravenous formulations, though homecare channels are extending reach for oral maintenance regimens post-discharge.
The FDA, EMA, and WHO collectively shape antimicrobial development pathways through resistance surveillance mandates and pre-approval efficacy benchmarks. EMA's evolving environmental risk assessment requirements for antibiotic manufacturing discharge now influence site selection and capital allocation decisions. Stakeholders must monitor regulatory divergence between jurisdictions on combination therapy approvals and adapt portfolio strategies accordingly.
Market Dynamics
Antimicrobial stewardship programs are compressing broad-spectrum antibiotic utilization across hospital systems, forcing manufacturers to reconfigure clinical trial endpoints and formulary access strategies around narrow-spectrum alternatives.
Growth Catalysts
- Hospital antimicrobial stewardship mandates:US integrated delivery networks now require pathogen-directed therapy protocols, accelerating demand for rapid diagnostic-guided treatment selection.
- REACH environmental discharge standards:EMA's evolving manufacturing requirements for antibiotic active pharmaceutical ingredients are filtering out subscale producers and consolidating supply among compliant facilities.
- Microbiome restoration protocols:Clinicians in tertiary care systems are integrating live biotherapeutic products into standard-of-care regimens for recurrent Clostridioides difficile enteritis.
Market Restraints
- Fermentation capacity concentration:Oral antibiotic active ingredient production clusters in China and India, creating geographic supply vulnerability and quality audit backlogs.
- Narrow-spectrum development economics:FDA's evolving guidance on pathogen-specific endpoints extends trial timelines and patient recruitment costs versus legacy broad-spectrum comparators.
- Faecal microbiota transplantation substitution:Regulatory-cleared stool-derived therapies for recurrent C. difficile are displacing pharmaceutical maintenance regimens in select hospital formularies.
Strategic Opportunities
- Homecare oral maintenance channels:Post-discharge administration of oral antibiotics and probiotics is extending therapy adherence monitoring and recurring revenue capture.
- WHO prequalification pathway:Antidiarrheal combination therapies targeting childhood enteritis in low-income settings unlock pooled procurement contracts through UNICEF and national immunization programs.
- Phage-bacteriophage convergence:Engineered lytic phage cocktails paired with narrow-spectrum antibiotics are opening salvage therapy positioning for multidrug-resistant Enterobacteriaceae infections.
Industry Challenges
- Specialized fermentation workforce scarcity:Commercial-scale antibiotic active pharmaceutical ingredient production requires rare expertise in aseptic bioprocessing and regulatory-compliant strain banking.
- Legacy intravenous line integration:Hospital pharmacy information systems require costly middleware upgrades to accommodate real-time microbiome test result feeds for therapy selection algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infectious Enteritis Treatment Market |
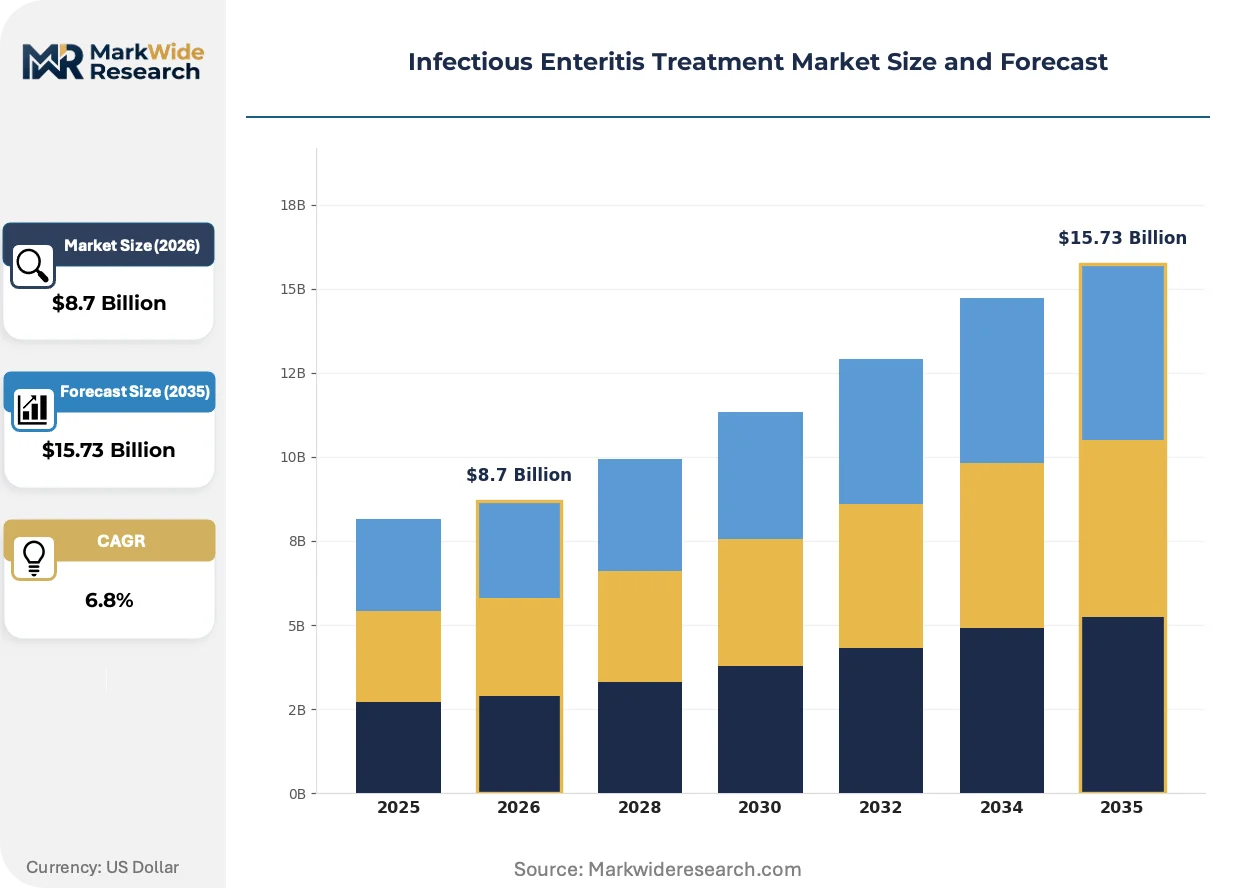
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antivirals, Probiotics, Vaccines Administration Route: Oral, Intravenous, Rectal, Topical Indication: Bacterial Infections, Viral Infections, Parasitic Infections, Fungal Infections End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | GlaxoSmithKline, Bristol-Myers Squibb, Johnson & Johnson, AbbVie, Teva Pharmaceutical Industries, Pfizer, Merck, Takeda Pharmaceuticals, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infectious Enteritis Treatment Market Strategic Shifts
Live biotherapeutic products are displacing conventional probiotic supplements in hospital formularies, while rapid molecular diagnostics compress the window between specimen collection and pathogen-directed therapy initiation.
Next-generation sequencing-based pathogen identification is electrifying clinical decision-making in emergency departments and intensive care units. Academic medical centers in the United States and Germany are adopting metagenomic platforms capable of detecting polymicrobial enteric infections within hours. This compression of diagnostic latency is enabling same-day narrow-spectrum antibiotic selection that stewardship committees previously blocked.
EMA's environmental risk assessment requirements for antibiotic manufacturing discharge are reshaping capital allocation across European production networks. Facility upgrades to contain active pharmaceutical ingredient effluent now precede regulatory approval for new molecular entities. Manufacturers with existing zero-liquid-discharge infrastructure in the Netherlands and Switzerland are capturing accelerated review timelines.
Integrated delivery networks are unbundling therapy selection from pharmacy dispensing through centralized antimicrobial stewardship telemedicine hubs. Remote infectious disease specialists now override local prescribing decisions in community hospitals lacking on-site expertise. This concentration of clinical authority is most visible in the United States, where rural critical access hospitals contract with urban academic centers for 24-hour consultation coverage.
Infectious Enteritis Treatment Market Segmentation
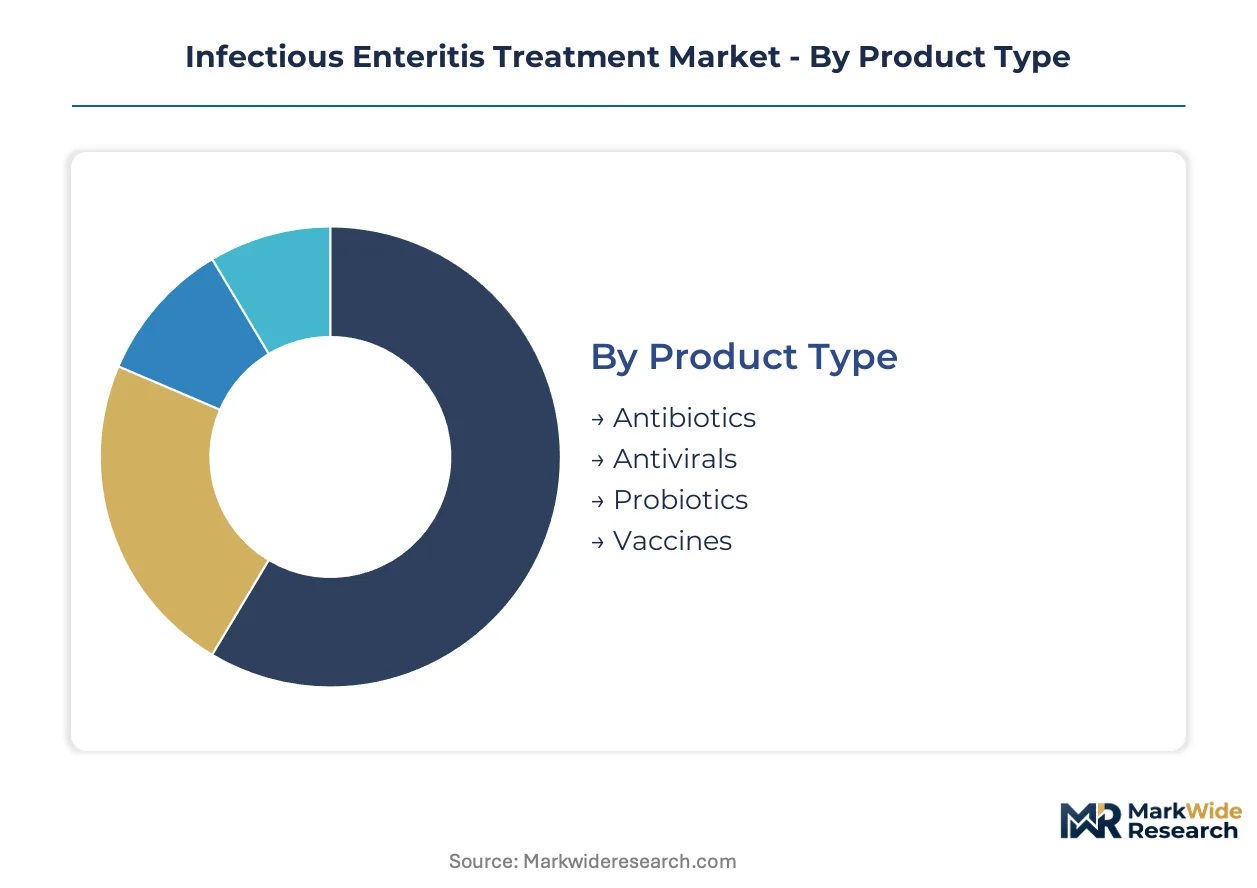
Segmentation in infectious enteritis treatment reveals how clinical severity, pathogen identification speed, and care setting economics fragment demand across distinct product configurations. Manufacturers must align formulation development with the precision medicine trajectory reshaping hospital procurement and post-acute care channels.
Product Type:
Standardized mass-market formulations dominate volume, while precision biotherapeutics command premium positioning through microbiome-specific efficacy claims.
- Antibiotics:Beta-lactam, fluoroquinolone, and macrolide formulations target confirmed bacterial pathogens through bactericidal or bacteriostatic mechanisms. Demand concentrates in US hospital systems where antimicrobial stewardship committees mandate pathogen-directed therapy selection. Stewardship program compliance requirements are compressing broad-spectrum utilization and elevating narrow-spectrum alternatives.
- Probiotics:Live bacterial cultures and yeast preparations restore commensal gut microbiota disrupted by antibiotic exposure or primary infection. Clinicians in German and Dutch tertiary care centers are integrating these into recurrent Clostridioides difficile protocols. Microbiome restoration protocols are displacing conventional supplements with regulatory-cleared live biotherapeutic products.
- Antivirals:Nucleoside analogues and polymerase inhibitors target rotavirus, norovirus, and cytomegalovirus enteritis in immunocompromised populations.
- Vaccines:Attenuated and recombinant formulations prevent rotavirus and typhoid enteritis through mucosal immunity induction.
Leading the category by volume: Antibiotics. Expanding most quickly: Probiotics.
Administration Route:
Route selection tracks patient acuity, with acute care settings demanding rapid systemic exposure and ambulatory channels favoring self-administered maintenance.
- Oral:Tablets, capsules, and suspensions deliver antibiotics and probiotics through gastrointestinal absorption for mild-to-moderate infections. US integrated delivery networks are extending post-discharge oral regimens through homecare pharmacy partnerships. Homecare channel expansion is capturing recurring revenue from adherence monitoring programs.
- Intravenous:Infusion and bolus delivery achieves immediate therapeutic concentrations for severe dehydration or sepsis risk. Tertiary care systems in Switzerland and the Netherlands prioritize IV-to-oral step-down protocols to reduce length of stay. Hospital pharmacy information systems require middleware upgrades to accommodate real-time therapy selection algorithms.
- Rectal:Suppository and enema formulations provide localized delivery for distal colonic inflammation or vomiting intolerance.
- Topical:Cream and ointment applications address perianal complications of enteric infection in limited clinical scenarios.
Dominant by revenue: Intravenous. Fastest channel growth: Oral homecare maintenance.
Indication:
Pathogen-specific targeting determines reimbursement eligibility and formulary placement, with bacterial diagnostics enabling the most precise therapy matching.
- Bacterial Infections:Salmonella, Shigella, Campylobacter, and Escherichia coli pathovars drive antibiotic prescription volume through toxin-mediated or invasive mechanisms. Academic medical centers in the United States and Germany deploy metagenomic platforms for same-day species identification. Rapid molecular diagnostics are compressing the window between specimen collection and pathogen-directed initiation.
- Parasitic Infections:Giardia lamblia, Entamoeba histolytica, and Cryptosporidium species require antiprotozoal or antihelminthic intervention in travel-related and immunocompromised presentations. Merck's intravenous antiparasitic portfolios anchor positioning in tertiary care systems managing severe amebiasis.
- Viral Infections:Rotavirus, norovirus, and adenovirus predominate in pediatric populations with limited targeted pharmacotherapy options.
- Fungal Infections:Candida and rare mold enteritis occur primarily in neutropenic or prolonged antibiotic exposure contexts.
Highest prescription volume: Bacterial Infections. Steepest diagnostic investment: Parasitic Infections.
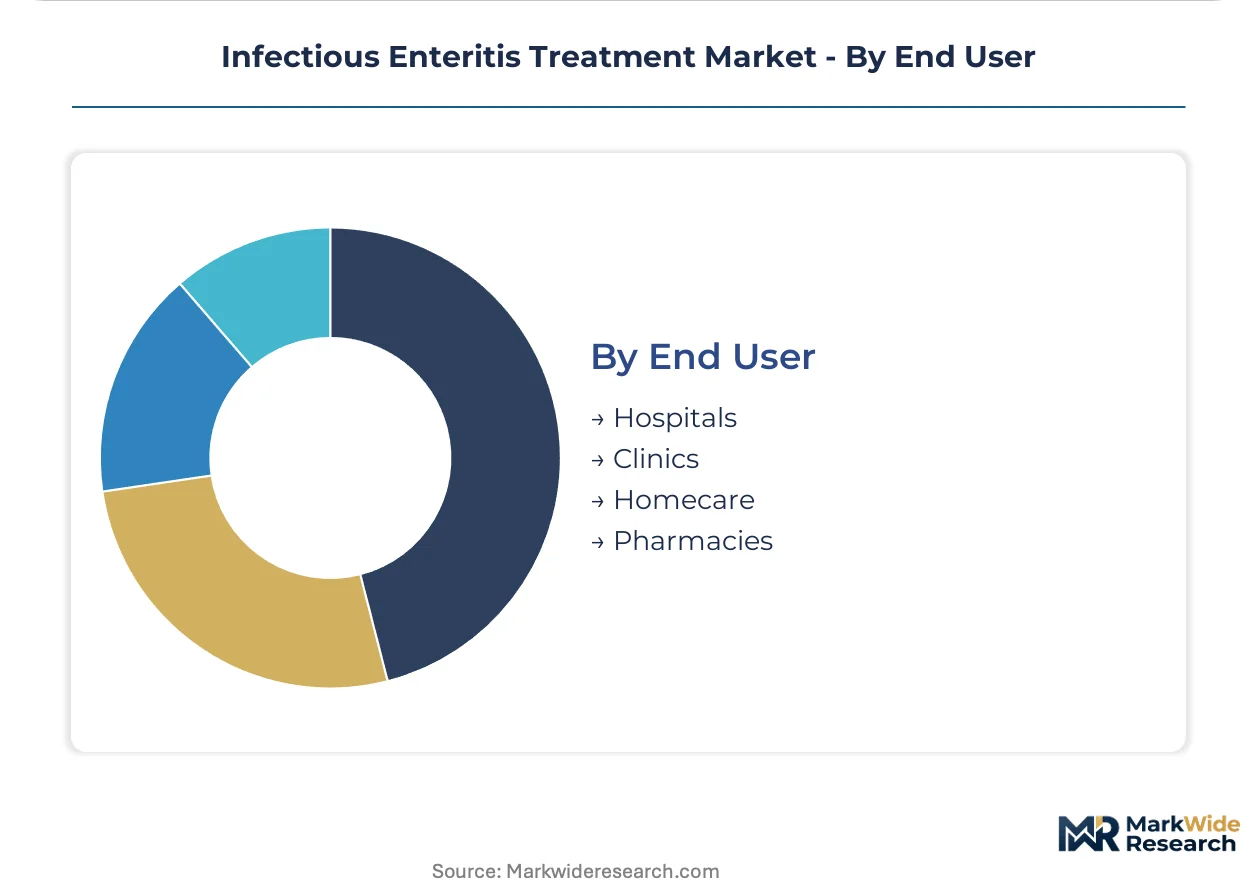
End User:
Procurement authority concentrates in consolidated health systems, while retail and homecare channels fragment purchasing across pharmacy benefit managers and direct-to-consumer platforms.
- Hospitals:Inpatient and emergency departments capture premium pricing for IV formulations and rapid diagnostic bundles. US rural critical access hospitals contract with urban academic centers for 24-hour infectious disease telemedicine consultation. Centralized antimicrobial stewardship hubs are unbundling therapy selection from pharmacy dispensing.
- Homecare:Post-acute and long-term care settings administer oral maintenance regimens with remote monitoring support. Homecare channels extend therapy adherence capture for probiotics and oral antibiotics following hospital discharge.
- Clinics:Outpatient and urgent care facilities manage uncomplicated infections with rapid strep and stool antigen testing.
- Pharmacies:Community and specialty dispensaries fulfill prescriptions with over-the-counter probiotic adjacents.
Revenue concentration: Hospitals. Fastest channel expansion: Homecare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for pharmaceutical manufacturing in India and tax-advantaged research corridors in Switzerland concentrate active ingredient production and clinical trial operations. FDA's evolving narrow-spectrum guidance and EMA's REACH discharge standards reshape facility investment patterns across jurisdictions.
United States
Integrated delivery networks in Texas and Florida drive hospital formulary consolidation for intravenous antibiotic step-down protocols. FDA antimicrobial stewardship mandates require pathogen-directed therapy selection algorithms in Medicare-participating facilities. Boston's academic medical cluster deploys metagenomic diagnostic platforms that compress specimen-to-treatment windows.
Germany
Tertiary care systems in Bavaria and North Rhine-Westphalia integrate live biotherapeutic products into recurrent Clostridioides difficile protocols. EMA environmental risk assessments for antibiotic manufacturing discharge filter subscale producers from European supply chains. Frankfurt's pharmaceutical corridor concentrates zero-liquid-discharge fermentation infrastructure.
India
CDSCO accelerated approval pathways for combination antidiarrheal therapies target childhood enteritis in low-income settings. Pharmaceutical special economic zones in Telangana and Gujarat consolidate oral antibiotic active ingredient production. Hyderabad's fermentation cluster faces quality audit backlogs from US FDA inspections.
Switzerland
Swissmedic's streamlined review timelines attract manufacturers with existing environmental compliance infrastructure. Basel's pharmaceutical corridor anchors intravenous antiparasitic formulation capacity for tertiary care export markets. Geneva's health technology cluster prototypes rapid molecular diagnostic platforms for emergency department deployment.
Japan
PMDA's resistance surveillance mandates align with WHO prequalification standards for pediatric combination therapies. Osaka's fermentation infrastructure supports narrow-spectrum antibiotic development for hospital stewardship compliance. Tokyo's academic medical centers validate next-generation sequencing platforms for polymicrobial enteric detection.
Infectious Enteritis Treatment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation development and microbiome restoration vectors. Market structure consolidates around fermentation-capable manufacturers with captive active ingredient supply and regulatory-cleared live biotherapeutic developers. Three archetypes dominate: integrated pharmaceutical conglomerates with vaccine networks, antibiotic specialists with dedicated fermentation assets, and emerging biotherapeutic platforms. Competitive intensity centers on M&A for diagnostic-therapy bundling and capacity expansion for zero-liquid-discharge compliance.
Within the integrated conglomerate tier, GlaxoSmithKline and Pfizer occupy positions shaped by captive production networks and dedicated fermentation infrastructure. Merck exemplifies the antiparasitic specialist archetype with intravenous portfolio concentration. Among pure-play biotherapeutic developers, Takeda Pharmaceuticals represents the microbiome restoration vector.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Bristol-Myers Squibb |
| Johnson & Johnson |
| AbbVie |
| Teva Pharmaceutical Industries |
| Pfizer |
| Merck |
| Takeda Pharmaceuticals |
| Novartis |
| Others |
Value Chain & Pricing Dynamics
Specialized fermentation workforce concentration in the Hyderabad-Telangana corridor and Basel pharmaceutical belt compresses labor-cost differentials into narrow-spectrum antibiotic pricing spreads. REACH-compliant zero-liquid-discharge facilities command 15-20% premia over standard fermentation capacity, segmenting the market into environmental-compliance tiers that reshape procurement negotiations.
Pricing Analysis
Lead-time-driven pricing stratifies across emergency stockpile, scheduled offtake, and spot procurement tiers. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification grade and FDA establishment inspection history. Cost compression in economy-tier oral generics is intensifying because Indian API producers face quality audit backlogs. Hospital procurement committees demonstrate lowest price sensitivity for IV antiparasitic emergency reserves, while retail pharmacy channels drive hardest oral probiotic substitution bargaining.
Supply Chain Analysis
Warehouse-distribution layer consolidation centers on regional cold-chain hubs in Rotterdam, Singapore, and Memphis that feed hospital pharmacy networks. Active pharmaceutical ingredient production draws from India, China, and Switzerland, with fermentation capacity tethered to telithromycin and macrolide precursor availability. Single-source vulnerability concentrates in Chinese xanthone derivative supply for antiprotozoal synthesis. Distribution runs through integrated delivery network central purchasing with homecare pharmacy last-mile extension.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around environmental compliance infrastructure as EMA discharge standards force subscale fermentation operators into exit or acquisition. REACH audit failures and quality citation backlogs are accelerating distressed asset availability.
For Market Incumbents: Acquire zero-liquid-discharge fermentation assets in the Netherlands and Switzerland to preempt regulatory capacity constraints. Anchor narrow-spectrum antibiotic portfolios with captive API supply through backward integration into Indian special economic zones. Faecal microbiota transplantation regulatory clearance threatens pharmaceutical maintenance regimen pricing power.
For New Entrants and Emerging Players: Launch via homecare oral maintenance channels with remote adherence monitoring platforms that bypass hospital formulary gatekeeping. Target US rural critical access hospital telemedicine stewardship contracts underserved by urban academic center coverage. Phage-bacteriophage salvage therapy for multidrug-resistant Enterobacteriaceae offers the most penetrable white-space positioning.
For Investors and Strategic Acquirers: Re-rating potential sits with live biotherapeutic product developers given FDA breakthrough therapy designation acceleration for recurrent C. difficile indications. Five-to-ten-year viability hinges on microbiome restoration protocol integration into standard-of-care guidelines. Watch for metagenomic diagnostic platform FDA 510(k) clearance velocity as inflection signal for narrow-spectrum therapy demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Liquid-Discharge Fermentation Capacity Expansion | EMA REACH compliance accelerates review timelines for Dutch and Swiss manufacturing sites. |
| Live Biotherapeutic Product Regulatory Submission | FDA breakthrough therapy pathway compresses development timelines for recurrent C. difficile candidates. |
| Metagenomic Diagnostic Platform Integration | Hospital pharmacy information system middleware upgrades enable real-time pathogen-directed therapy selection. |
| Homecare Pharmacy Partnership Network | Post-discharge oral maintenance adherence monitoring captures recurring revenue from step-down protocols. |
| Phage-Bacteriophage Cocktail Development | Engineered lytic phage salvage therapy addresses multidrug-resistant Enterobacteriaceae in tertiary care systems. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this infectious enteritis treatment market assessment. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors combined with FDA 510(k) filings, EMA marketing authorization applications, ClinicalTrials.gov protocols, and GPO contract databases. Bottom-up patient-flow modeling and top-down pharmaceutical spending allocation triangulated volume estimates.
Granularity-level modeling tracked product type, administration route, indication pathology, and end-user channel across the projection horizon. Treatment line positioning, dosage form complexity, and regional regulatory cluster maturity shaped segment-level CAGRs. Antimicrobial stewardship program penetration rates and live biotherapeutic product formulary adoption curves informed therapy-mix assumptions.
Regulatory approval delays, API quality audit failures, and microbiome restoration protocol substitution are the dominant revision risks to base-case projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Italy Infectious Disease in-Vitro Diagnostics Market
Infectious Disease
Direct-Acting Antiviral Medicines Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Global Veterinary Infectious Disease Diagnostics Market
Infectious Disease
Tuberculous Meningitis Treatment Market
Infectious Disease
Meningococcal Disease Treatment Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Acute Vulvovaginal Candidiasis Treatment Market
Infectious Disease
Human Immunodeficiency Virus Type 1 (HIV 1) Market
Infectious Disease
Efavirenz Market
Infectious Disease
Global Infectious Disease Therapeutics Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Gram Positive Bacterial Infections Market
Infectious Disease
Infectious Disease Molecular Diagnostics Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
IVD Infectious Disease Market