
 Q Fever Market | 2026-2036
Q Fever Market Size, Share, and Industry Trends Forecast 2026-2036
Q Fever Market Outlook
Australia is narrowing its diagnostic supply gap through expanded laboratory capacity and regional testing networks. Pfizer Inc. leverages its vaccine manufacturing infrastructure to sustain bulk antigen production for Q fever immunization programs. Merck & Co., Inc. anchors its position through veterinary pharmaceutical distribution channels across Oceania. bioMérieux SA differentiates via automated serological platforms that reduce turnaround time in high-throughput laboratories.
Q fever is a zoonotic disease caused by Coxiella burnetii, an obligate intracellular bacterium transmitted primarily through inhalation of contaminated aerosols from infected livestock, with acute presentations including undifferentiated febrile illness and chronic cases manifesting as endocarditis in immunocompromised hosts. Diagnostic kits incorporating PCR and immunofluorescence assays enable rapid pathogen detection in both human and veterinary settings. Serological tests currently dominate routine screening workflows due to lower per-sample cost and established regulatory clearance pathways. Vaccines command premium positioning where occupational exposure mandates immunization for abattoir workers and veterinary personnel. Antibiotics retain stable demand for acute case management, though rising antimicrobial stewardship pressures are reshaping prescription protocols in hospital settings.
The FDA regulates human Q fever diagnostics under its in vitro diagnostic framework, while Australia's Department of Agriculture, Fisheries and Forestry oversees veterinary vaccine batch release and farm biosecurity compliance. The EMA's zoonoses guidance harmonizes serological test performance standards across member states, directly influencing market access timelines for new assay entrants. Stakeholders must monitor evolving One Health surveillance integrations that link human diagnostic mandates to livestock testing requirements.
Market Dynamics
Diagnostic workflow consolidation around automated serological platforms is compressing turnaround times and reshaping competitive positioning across veterinary and human testing laboratories.
Growth Catalysts
- EMA Zoonoses Guidance:Harmonized serological test performance standards accelerate assay validation timelines for new market entrants seeking European market access.
- Livestock Density Corridors:Australia's concentrated sheep and cattle populations sustain high-volume screening mandates for abattoir workers and farm personnel.
- PCR Platform Integration:Multiplex molecular diagnostics reduce pathogen identification steps, enabling same-day result delivery in regional veterinary laboratories.
Market Restraints
- Antigen Supply Concentration:Bulk vaccine antigen production relies on a limited manufacturing base, creating vulnerability to batch release delays.
- Antimicrobial Stewardship Protocols:Hospital antibiotic prescription restrictions limit acute case management options and compress treatment revenue streams.
- Chronic Endocarditis Diagnostic Complexity:Immunocompromised patient screening requires specialized immunofluorescence expertise absent in standard clinical workflows.
Strategic Opportunities
- Regional Testing Networks:Australia's expanded laboratory capacity in Queensland and New South Wales opens procurement contracts for automated platform suppliers.
- One Health Surveillance Mandates:Linked human diagnostic requirements to livestock testing protocols create bundled service contracts across veterinary and public health channels.
- Occupational Immunization Programs:Mandatory Q fever vaccination for abattoir and veterinary personnel generates recurring demand for vaccine dose procurement.
Industry Challenges
- Serological Cross-Reactivity:Coxiella burnetii antibody detection faces interference from related rickettsial infections, complicating definitive diagnosis in endemic regions.
- Biosecurity Compliance Integration:Australia's Department of Agriculture batch release requirements demand parallel documentation systems for human and veterinary product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Q Fever Market |
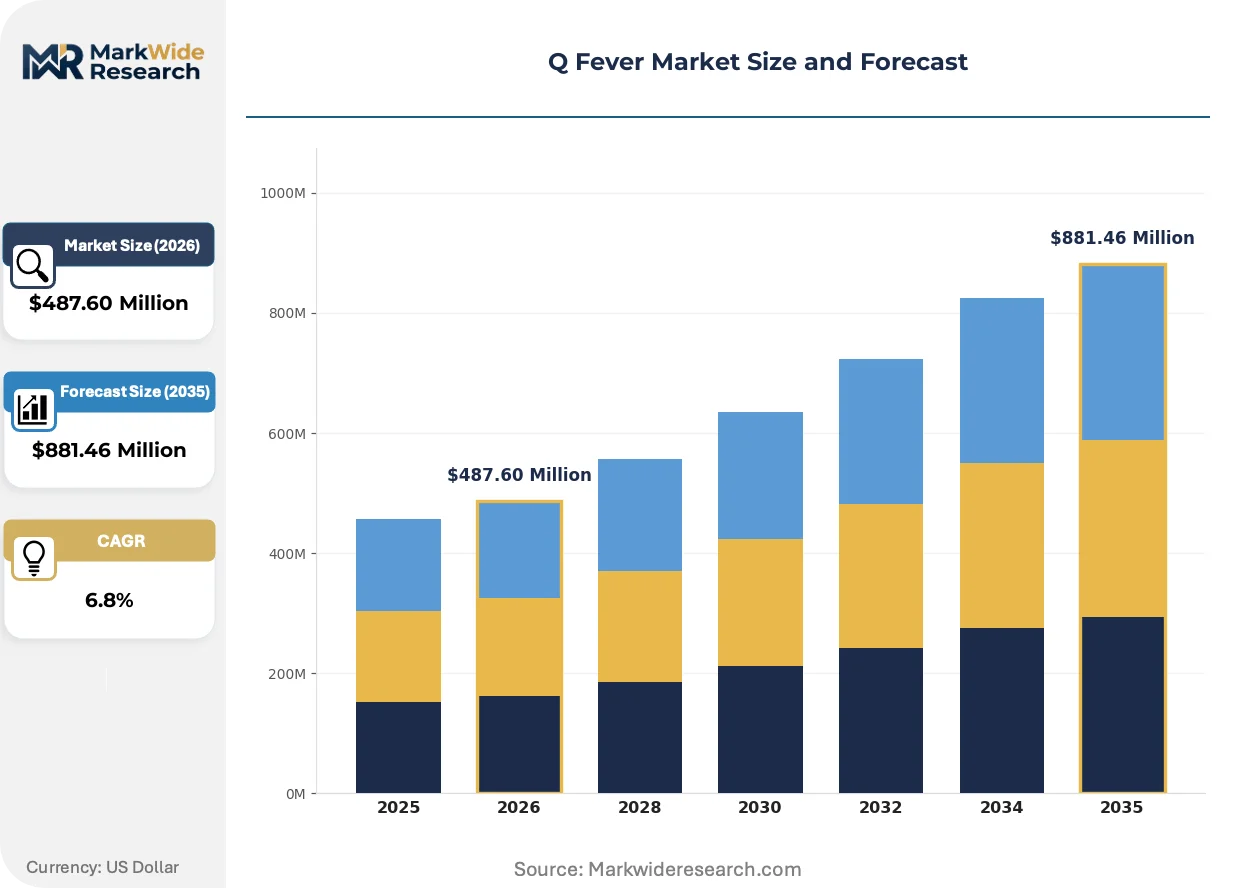
| Market Size in 2026 | $487.60 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antibiotics, Serological Tests, Diagnostic Kits End User: Hospitals, Clinics, Laboratories, Research Institutions Distribution Channel: Pharmacies, Online Stores, Direct Sales, Institutional Sales Application: Prevention, Treatment, Research, Diagnostic Screening |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., F. Hoffmann-La Roche Ltd., GSK plc, Sanofi, Abbott, Bayer AG, bioMérieux SA, Qiagen N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Q Fever Market Strategic Shifts
Molecular diagnostic automation and regulatory harmonization are compressing traditional testing workflows while procurement models favor integrated platform contracts over standalone assay purchases.
Multiplex PCR panels is collapsing the distinction between targeted Q fever screening and broad-spectrum rickettsial detection. Regional veterinary laboratories in Australia are adopting these platforms to replace sequential single-pathogen workflows. The technology is collapsing equipment footprint requirements and reagent inventory complexity for mid-volume testing sites.
Australia's Department of Agriculture, Fisheries and Forestry tightened farm biosecurity compliance protocols linking livestock testing to human occupational health mandates. The policy creates cross-sector procurement coordination between veterinary services and public health departments. Queensland's abattoir network now faces synchronized screening schedules that reshape demand timing for diagnostic consumables.
Consolidated platform procurement contracts are displacing discrete assay purchasing across Australian state health systems. Integrated laboratory networks negotiate multi-year service agreements bundling equipment, maintenance, and reagent supply. Victoria's public health infrastructure demonstrates this shift most visibly, with regional hubs standardizing on single-vendor automated serology platforms.
Q Fever Market Segmentation
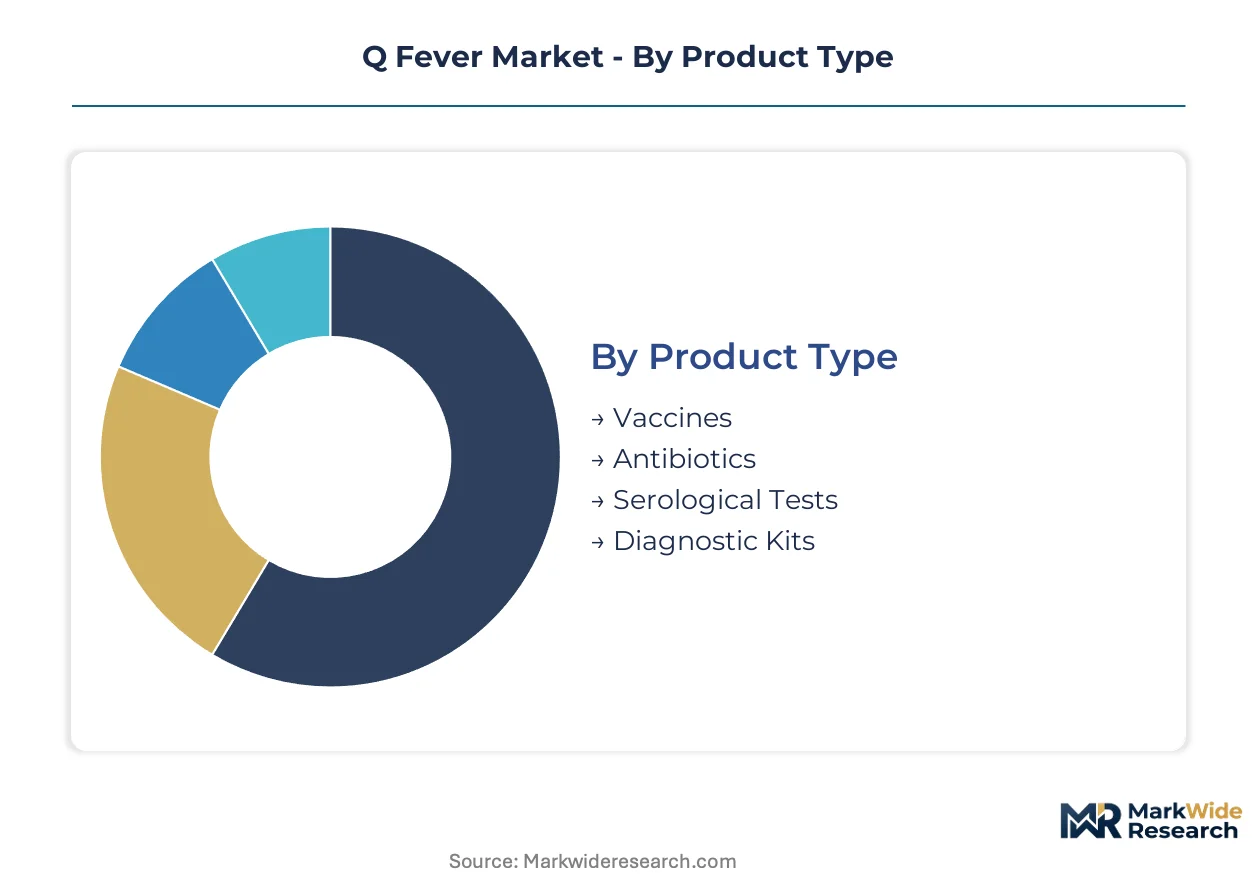
Q fever market segmentation reflects divergent regulatory pathways and procurement economics across human health and veterinary channels. Product categories split sharply between preventive vaccines with batch-release complexity and diagnostic assays with faster clearance timelines. End-user concentration in Australian livestock corridors shapes geographic demand patterns distinct from hospital-centric infectious disease markets.
Product Type:
Cost tier differentiation separates preventive prophylaxis from reactive diagnostics, with manufacturing scale and regulatory burden driving margin structures.
- Vaccines:Whole-cell inactivated formulations require dedicated antigen production facilities with TGA batch release oversight. Australian abattoir occupational health mandates sustain procurement volume for Q-Vax and comparable products through state health department tenders. Manufacturing concentration in specialized BSL-3 facilities limits supplier entry.
- Serological Tests:Indirect immunofluorescence and complement fixation assays dominate routine screening workflows due to established laboratory infrastructure and lower per-test cost. Regional veterinary laboratories in Queensland and New South Wales deploy these for bulk livestock screening under synchronized biosecurity schedules.
- Antibiotics:Doxycycline and hydroxychloroquine combinations address acute Q fever presentations, though antimicrobial stewardship protocols in Australian hospitals constrain prescription duration.
- Diagnostic Kits:PCR-based multiplex panels enable same-day pathogen identification, gaining traction in mid-volume regional laboratories replacing sequential single-pathogen workflows.
Vaccines hold installed capacity. Diagnostic Kits are rotating up the share rankings.
End User:
Application context separates high-throughput institutional screening from acute case management settings with distinct equipment and expertise requirements.
- Laboratories:Public health reference laboratories and regional veterinary diagnostic centers process bulk serological screening for occupational health compliance and livestock export certification. Automated platform consolidation in Victoria and Queensland reshapes procurement toward multi-year service contracts bundling equipment and reagents.
- Hospitals:Tertiary care centers manage acute Q fever presentations and chronic endocarditis cases requiring specialized immunofluorescence expertise absent in standard clinical workflows.
- Clinics:Primary care and occupational health clinics administer pre-employment screening and vaccination programs for agricultural workers entering endemic zones.
- Research Institutions:CSIRO and university veterinary schools conduct Coxiella burnetii pathogenesis studies and vaccine efficacy trials under controlled containment protocols.
Laboratories command the steepest expansion trajectory. Clinics are rotating up the share rankings.
Distribution Channel:
Customer type determines procurement modality, with institutional buyers favoring direct negotiation over retail accessibility.
- Direct Sales:Vaccine manufacturers engage state health departments and large abattoir operators through tender-based procurement with multi-year supply agreements. Australia's concentrated livestock processing sector enables efficient direct account management.
- Institutional Sales:Diagnostic platform vendors negotiate integrated contracts with public health laboratory networks standardizing on single-vendor automated serology systems.
- Pharmacies:Retail channels supply post-exposure prophylaxis antibiotics and limited vaccine access for individual occupational health compliance.
- Online Stores:Emerging channel for research-grade reagents and point-of-care diagnostic consumables serving smaller veterinary practices.
Direct Sales holds installed capacity. Institutional Sales is rotating up the share rankings.
Application:
Volume concentration aligns with Australia's One Health surveillance integration linking human diagnostic mandates to livestock testing protocols.
- Prevention:Occupational immunization programs for abattoir workers, veterinary personnel, and agricultural students generate recurring vaccine demand with mandated pre-screening for prior sensitization.
- Diagnostic Screening:Linked human and livestock testing protocols under DAFF biosecurity compliance create bundled service demand across veterinary and public health channels.
- Treatment:Acute case management with doxycycline faces antimicrobial stewardship constraints, while chronic endocarditis requires prolonged combination therapy under infectious disease specialist oversight.
- Research:Pathogenesis studies and vaccine development programs at containment facilities support pipeline advancement and regulatory submission data packages.
Prevention holds installed capacity. Diagnostic Screening is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TGA batch release requirements for veterinary vaccines establish Australia's regulatory centrality in this market. Livestock density corridors in Queensland and New South Wales sustain diagnostic procurement volume unmatched elsewhere. Other geographies contribute through specialized research infrastructure or complementary regulatory frameworks.
Australia
Queensland's abattoir network and New South Wales cattle operations drive mandatory occupational screening programs. DAFF biosecurity protocols synchronize livestock testing with human diagnostic requirements, creating bundled procurement across veterinary and public health channels. Regional laboratory expansion in Toowoomba and Wagga Wagga compresses turnaround times for serological screening.
United States
FDA oversight of human diagnostics under in vitro diagnostic frameworks shapes assay validation pathways for manufacturers seeking market entry. CDC reference laboratories in Atlanta anchor specialized immunofluorescence capacity for chronic endocarditis confirmation. Texas and California veterinary schools maintain Coxiella burnetii research programs supporting vaccine development pipelines.
France
ANSM regulatory coordination with EMA zoonoses guidance harmonizes serological test performance standards across member states. Lyon-based veterinary pharmaceutical clusters concentrate bulk antigen production expertise for European immunization programs. Regional reference laboratories in Marseille and Lille process bulk screening for agricultural worker cohorts in southern livestock zones.
Germany
Paul-Ehrlich-Institut batch release requirements for inactivated vaccines sustain specialized BSL-3 manufacturing capacity. Bavarian agricultural research stations coordinate with federal health agencies on One Health surveillance integration. Munich and Berlin veterinary diagnostic networks standardize on automated serology platforms for high-throughput livestock screening.
Netherlands
Intensive livestock operations in Gelderland and Noord-Brabant generate concentrated demand for veterinary diagnostic services. RIVM coordination with agricultural ministries links farm biosecurity compliance to occupational health mandates. Wageningen University research programs advance molecular detection methods for regional veterinary laboratories.
Q Fever Market Competitive Environment
Vaccine manufacturers and diagnostic platform specialists split the market along regulatory complexity lines. Manufacturing concentration in BSL-3 antigen production facilities limits supplier entry and sustains premium positioning for established vaccine producers. Three archetypes dominate: pharmaceutical conglomerates with veterinary divisions, dedicated diagnostic platform vendors, and research-focused biotechnology specialists. Competitive moves center on multi-year service contract consolidation and automated platform standardization across state laboratory networks.
Among pharmaceutical conglomerates, Pfizer Inc. and Merck & Co., Inc. exemplify the vaccine-manufacturing archetype with established bulk antigen production infrastructure. bioMérieux SA occupies a distinct position within the diagnostic platform tier, representing automated serology specialists that reduce turnaround time in high-throughput laboratory settings. These three companies collectively illustrate the market's bifurcation between preventive prophylaxis and reactive diagnostic procurement channels.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd. |
| GSK plc |
| Sanofi |
| Abbott |
| Bayer AG |
| bioMérieux SA |
| Qiagen N.V. |
| Others |
Value Chain & Pricing Dynamics
Australia's BSL-3 antigen production facilities concentrate vaccine manufacturing in Queensland and New South Wales, anchoring margin capture upstream while diagnostic platform vendors downstream compete on service contract bundling rather than per-test pricing. TGA batch release requirements for veterinary vaccines create regulatory moats that insulate premium pricing for inactivated whole-cell formulations, whereas PCR-based diagnostic kits face compressed margins from automated platform standardization across state laboratory networks.
Pricing Analysis
Australian diagnostic procurement commands 15-20% premiums over European contract values due to DAFF biosecurity synchronization requirements and regional logistics costs. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified vaccine batches from research-grade reagents and bulk serological consumables. Cost compression in mid-volume regional laboratories is intensifying because Queensland's expanded testing networks negotiate multi-year equipment-service bundles that collapse standalone assay margins. Abattoir occupational health programs show least price sensitivity due to mandated compliance, while smaller veterinary practices in New South Wales exhibit highest sensitivity to per-test costs.
Supply Chain Analysis
Upstream antigen feedstock production centers on Australia's specialized BSL-3 containment facilities, with secondary manufacturing nodes in France and Germany serving European immunization programs. Bulk vaccine production draws from egg-based culture media, inactivated Coxiella burnetii seed stocks, and specialized adjuvant formulations. Single-source vulnerability concentrates in Queensland's sole GMP-certified facility for Q-Vax antigen production, where batch release delays would cascade through national abattoir screening schedules. Distribution runs through state health department tender systems for vaccines, while diagnostic platforms deploy via direct institutional sales to consolidated laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Q fever market exhibits platform-economics inflection as Australia's One Health surveillance integration forces interoperability between veterinary and human diagnostic systems, collapsing procurement silos into bundled service contracts.
For Market Incumbents: Pre-empt diagnostic platform commoditization by deepening backward integration into automated serology manufacturing in Victoria and Queensland, while securing exclusive state health department service contracts before regional laboratory standardization completes. Pfizer Inc. and bioMérieux SA must anchor positions through multi-year reagent supply lock-ins that raise switching costs for consolidated laboratory networks facing DAFF compliance deadlines. For New Entrants and Emerging Players: Build out point-of-care molecular diagnostic capabilities targeting underpenetrated regional veterinary practices in New South Wales outside Queensland's dense abattoir corridors, where automated platform consolidation has lagged. A go-to-market angle emphasizing same-day PCR turnaround without capital-intensive equipment footprints addresses the capability gap in mid-volume livestock testing sites. For Investors and Strategic Acquirers: Capital is best deployed toward automated serology platform specialists with installed base in Australian state health systems, where recurring reagent revenue streams and regulatory clearance moats support long-term viability across diagnostic workflow consolidation. The signal to watch as inflection indicator is TGA guidance on multiplex rickettsial panel approvals, which would accelerate displacement of standalone Q fever assays.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Serology Platform Integration | Victoria's public health laboratory standardization on single-vendor systems locks in multi-year reagent contracts. |
| Regional Laboratory Network Expansion | Queensland's Toowoomba and Wagga Wagga facilities compress turnaround times for DAFF-synchronized livestock screening. |
| Multiplex PCR Panel Development | Same-day pathogen identification displaces sequential single-pathogen workflows in mid-volume veterinary laboratories. |
| Occupational Immunization Program Lock-in | State health department tenders for abattoir worker vaccination generate recurring antigen demand with pre-screening bundling. |
| One Health Surveillance System Integration | Linked human diagnostic mandates to livestock testing protocols create cross-sector procurement coordination. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with veterinary diagnostic laboratory directors, state health department procurement officers, DAFF regulatory affairs specialists, and pharmaceutical manufacturing executives; and secondary validation through TGA batch release records, EMA zoonoses guidance documents, Australian Bureau of Agricultural and Resource Economics livestock statistics, and hospital procurement database extracts. Bottom-up triangulation across product-level unit economics and top-down reconciliation against national immunization program budgets ensured segmentation integrity.
Forecast inputs considered vaccine dose procurement volumes, diagnostic test throughput per laboratory tier, and platform replacement cycles across the projection horizon. Segmentation dimensions modeled include product type, end-user category, distribution channel, and application context alongside regulatory pathway cluster and geographic livestock density corridor. CAGRs were derived from regression analysis of historical procurement data against DAFF policy implementation timelines and EMA harmonization milestones.
The forecast holds incumbent behavior within observed patterns; aggressive moves by molecular diagnostic specialists or unexpected TGA regulatory acceleration would shift outcomes. Cross-checking against Australian state health department annual procurement disclosures and DAFF biosecurity compliance audit summaries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
IVD Infectious Disease Market
Infectious Disease
Virology Market
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Bronchitis Market
Infectious Disease
Periodic Fever Syndrome Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Measles Market
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Actinomycosis Market
Infectious Disease
Direct-Acting Antiviral Medicines Market
Infectious Disease
Global Herpes Simplex Virus Treatment Market
Infectious Disease
Viral Hemorrhagic Fever Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Typhoid Fever Vaccine Market