
 Virology Market | 2026-2036
Virology Market Size, Share, and Industry Trends Forecast 2026-2036
Virology Market Outlook
Antiviral drug licensing revenue is fragmenting across multiple monetization models as originator compounds face patent cliffs and biosimilar pressure. Gilead Sciences Inc. sustains premium positioning through proprietary nucleotide analog platforms. Merck & Co. Inc. competes via diversified infectious disease portfolios spanning HIV and hepatitis C. Thermo Fisher Scientific Inc. anchors its position through integrated diagnostic-to-therapeutic workflow solutions.
Virology encompasses the study of viral structure, replication mechanisms, pathogenesis, and host interaction, employing techniques such as plaque assays, quantitative PCR with detection thresholds below ten copies per milliliter, and viral culture in biosafety level laboratories. Vaccines command the largest revenue pool among product types due to recurring national immunization schedules and outbreak response stockpiling. Molecular diagnostics leads technology-based growth as laboratories replace legacy immunoassays with multiplexed nucleic acid platforms that detect respiratory and bloodstream pathogens simultaneously. CRISPR-Cas-based antiviral screening represents the fastest-emerging segment, attracting research funding from pharmaceutical companies seeking accelerated target validation.
The FDA governs antiviral approval pathways through accelerated and breakthrough designations, while the EMA enforces centralized marketing authorization for vaccines distributed across EU member states. ISO 15189 accreditation shapes diagnostic laboratory quality standards that determine market access for testing kit manufacturers. Stakeholders must monitor how pandemic preparedness agencies rebalance stockpile commitments between broad-spectrum antivirals and pathogen-specific vaccines as threat assessments evolve.
Market Dynamics
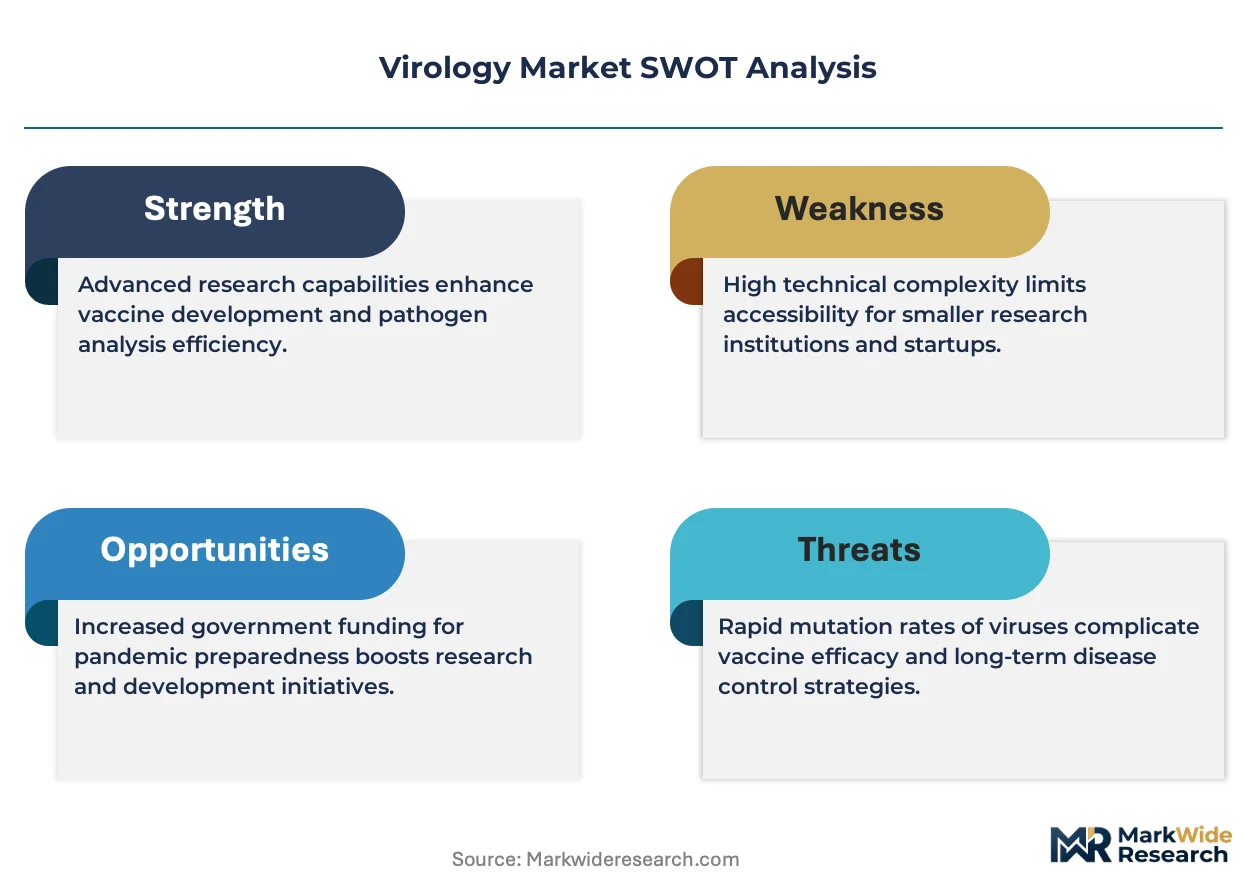
The virology market restructures around multiplexed nucleic acid platforms that compress diagnostic timelines from days to hours, forcing laboratories to retire legacy immunoassay infrastructure and consolidate vendor relationships around integrated workflow providers.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses development timelines for novel antiviral classes, enabling sponsors to reach commercialization before patent cliffs erode originator revenue streams.
- Respiratory pathogen surveillance networks:Hospital laboratories deploy syndromic panels that detect multiple viruses simultaneously, driving replacement demand for single-target testing kits.
- CRISPR-Cas screening platforms:Pharmaceutical research divisions adopt gene-editing tools for rapid target validation, redirecting R&D budgets toward antiviral discovery programs.
Market Restraints
- Biosafety level containment costs:Viral culture and live-pathogen research requires BSL-3 and BSL-4 laboratory infrastructure, concentrating capability among federally funded institutions and limiting private-sector participation.
- Nucleotide analog raw material concentration:Active pharmaceutical ingredient supply for antiviral manufacturing clusters in Chinese and Indian chemical synthesis hubs, exposing formulation sponsors to geopolitical supply disruption.
- EMA centralized authorization delays:Vaccine marketing authorization procedures across EU member states extend regulatory review timelines compared with national pathways, compressing commercial windows for seasonal influenza candidates.
Strategic Opportunities
- Next-generation mRNA manufacturing:Platform technology developed for COVID-19 vaccines now applies to cytomegalovirus and respiratory syncytial virus candidates, opening therapeutic categories previously dominated by protein subunit approaches.
- Point-of-care molecular diagnostics:Miniaturized PCR and isothermal amplification devices penetrate ambulatory settings and resource-limited clinics, expanding addressable volume beyond centralized laboratory networks.
- Pandemic Preparedness and Response Act funding:US federal stockpile commitments sustain advance purchase agreements for broad-spectrum antivirals, de-risking manufacturing capacity investments for suppliers.
Industry Challenges
- Bioinformatics talent scarcity:Viral genomic surveillance and variant analysis requires computational biology expertise that outpaces university training pipeline output, forcing diagnostic manufacturers to compete with technology firms for qualified hires.
- ISO 15189 accreditation timelines:Diagnostic kit manufacturers face extended quality system validation periods to achieve laboratory accreditation, delaying market entry in regulated European jurisdictions.
- Legacy immunoassay integration friction:Hospital systems with sunk capital in enzyme-linked immunosorbent assay infrastructure resist full platform conversion, slowing nucleic acid test adoption curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virology Market |
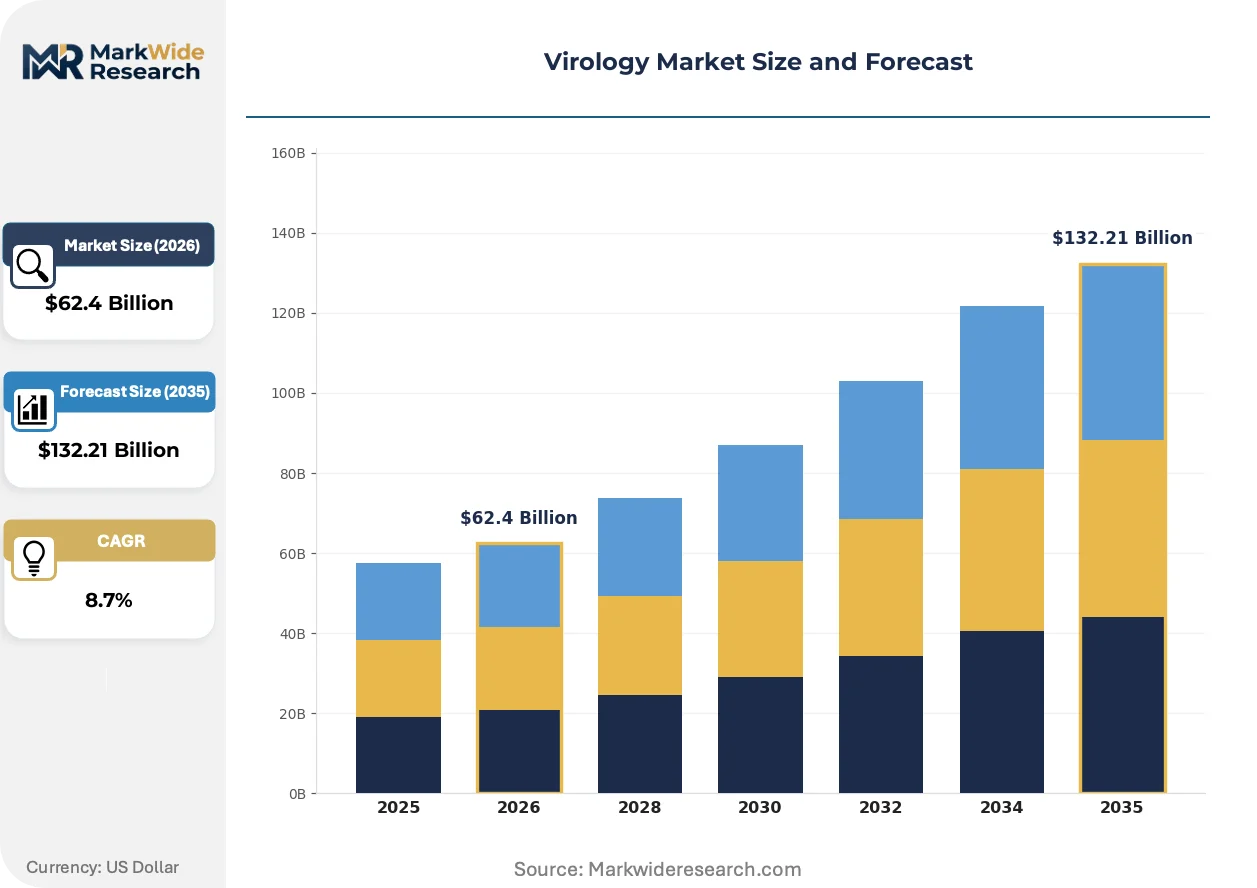
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $132.21 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antiviral Drugs, Testing Kits, Diagnostic Devices Application: Infectious Disease Control, Research, Blood Screening, Vaccine Development End User: Hospitals, Research Laboratories, Blood Banks, Pharmaceutical Companies Technology: Molecular Diagnostics, Immunoassays, Next-Generation Sequencing, CRISPR-Cas |
| Companies Covered | GlaxoSmithKline plc, Abbott Laboratories, Merck & Co. Inc., Johnson & Johnson, F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific Inc., Gilead Sciences Inc., Novartis International AG, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virology Market Strategic Shifts
Digital PCR and nanopore sequencing platforms compress viral load quantification from batch workflows to real-time monitoring, enabling therapeutic decision-making at the point of care rather than centralized reference laboratories.
Digital PCR systems partition samples into thousands of micro-reactions, achieving absolute quantification without standard curves. Oncology and transplant centers adopt these platforms for cytomegalovirus and Epstein-Barr virus monitoring. Single-molecule sensitivity is rendering obsolete quantitative PCR methods that require extrapolation from calibration curves.
The FDA's Emergency Use Authorization pathway, expanded during recent public health emergencies, now accommodates template-based submissions for novel respiratory pathogens. Sponsors pre-position master file components to compress review timelines. Vaccine developers targeting emerging variants leverage this framework to accelerate seasonal strain updates.
Hospital procurement departments consolidate diagnostic vendor relationships around comprehensive workflow contracts that bundle instruments, reagents, and informatics. Independent reference laboratories lose share to integrated device manufacturers. This concentration is most visible in US health system networks where centralized purchasing authority has expanded.
Virology Market Segmentation
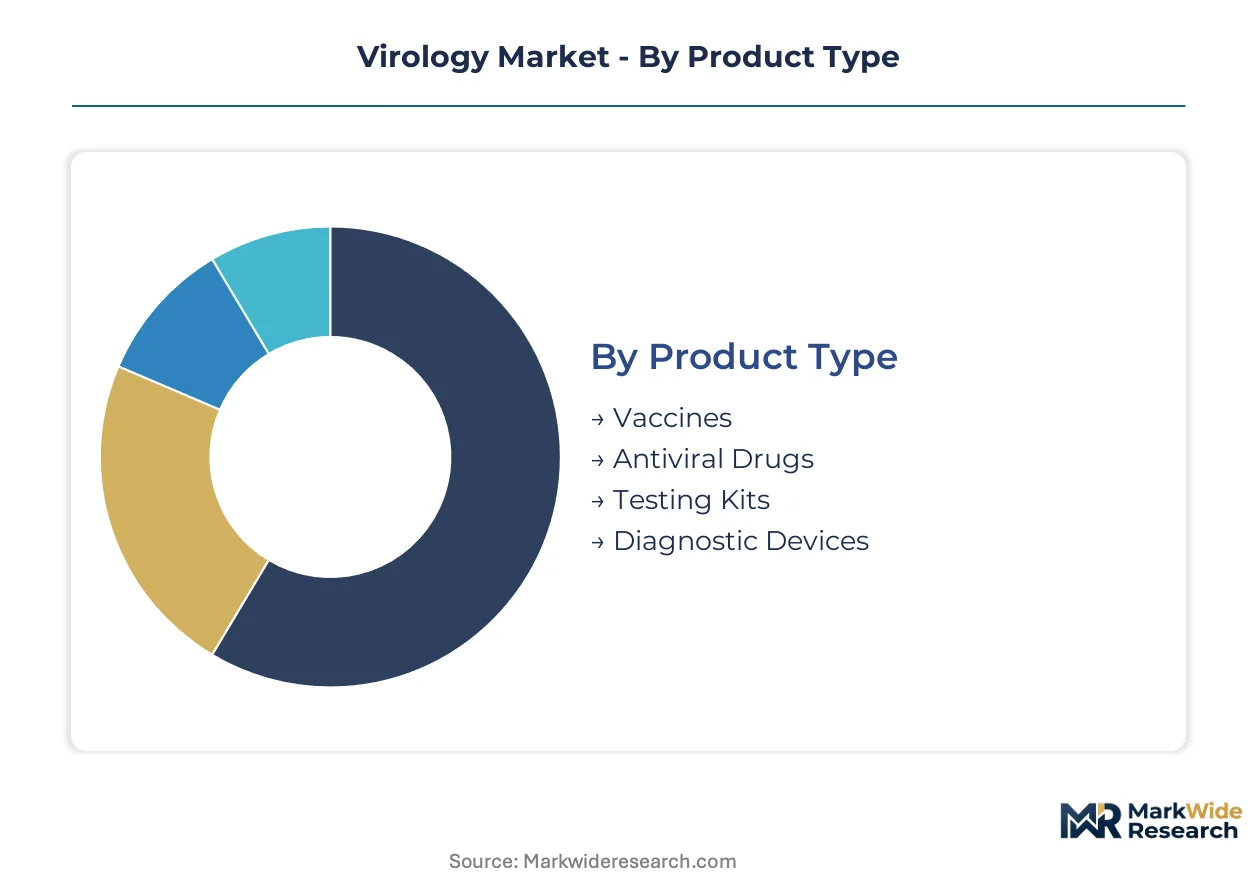
Virology market segmentation reveals divergent service intensity profiles across product categories. Vaccines and diagnostic devices demand extensive cold chain logistics and field technical support, while antiviral compounds and testing kits operate through conventional pharmaceutical distribution with lighter aftermarket requirements.
Product Type:
After-sales-service intensity varies dramatically across this category, with biological products requiring temperature-controlled distribution networks and real-time stability monitoring that chemical antivirals do not.
- Vaccines:Thermolabile formulations require validated cold chain infrastructure from manufacturing through administration. Federal stockpile procurement in the United States sustains the largest revenue concentration, with national immunization programs generating recurring demand cycles independent of outbreak conditions.
- Antiviral Drugs:Small-molecule and biologic therapeutics targeting HIV, hepatitis C, and respiratory viruses. Patent cliff pressures are fragmenting revenue across originator, generic, and biosimilar tiers, with nucleotide analog platforms commanding premium positioning.
- Testing Kits:Lyophilized reagent formats with extended ambient stability reduce field service burden compared to liquid diagnostics. Hospital laboratories drive volume through syndromic respiratory panels.
- Diagnostic Devices:Integrated platforms combining sample preparation, amplification, and detection modules. ISO 15189 accreditation requirements in Europe extend installation and validation timelines.
By volume, Testing Kits leads. By growth pace, CRISPR-Cas-based screening applications within Antiviral Drugs discovery pipelines are expanding most quickly.
Application:
Cost tier stratification separates federally funded preparedness programs from discretionary research budgets, with capital-intensive vaccine development occupying the highest investment threshold.
- Infectious Disease Control:Surveillance, outbreak response, and population-level intervention programs. The FDA's Emergency Use Authorization pathway accelerates deployment timelines for novel respiratory threats.
- Research:Academic and commercial investigation of viral pathogenesis, host interaction, and therapeutic targets. CRISPR-Cas screening platforms are redirecting pharmaceutical R&D budgets toward accelerated target validation.
- Blood Screening:Donor testing for HIV, hepatitis B, hepatitis C, and emerging pathogens. Regulatory mandates in the United States and Europe sustain mandatory screening volumes.
- Vaccine Development:Preclinical through Phase III trials for prophylactic candidates. mRNA platform technology developed for COVID-19 now applies to cytomegalovirus and respiratory syncytial virus candidates.
By institutional spending, Infectious Disease Control dominates. By investment momentum, Vaccine Development is gaining share fastest as platform technologies reduce time-to-clinic.
End User:
Customer type determines procurement authority structure, with consolidated hospital networks exercising centralized purchasing that fragments vendor relationships among independent research laboratories.
- Hospitals:Clinical diagnostic laboratories and inpatient antiviral administration. US health system networks are consolidating vendor relationships around comprehensive workflow contracts bundling instruments, reagents, and informatics.
- Research Laboratories:Academic, government, and commercial facilities conducting basic and applied virology. BSL-3 and BSL-4 containment requirements concentrate high-pathogen capability among federally funded institutions.
- Blood Banks:Collection and processing facilities performing mandatory donor screening. Regulatory compliance sustains testing volumes regardless of economic cycles.
- Pharmaceutical Companies:Internal R&D divisions and contracted research organizations. Antiviral discovery programs compete for bioinformatics talent with technology firms.
By facility count, Research Laboratories leads. By revenue concentration, Pharmaceutical Companies show the steepest expansion trajectory as pipeline investments recover.
Technology:
Supply concentration in reagent manufacturing and instrument platforms creates vendor lock-in effects that shape long-term customer relationships across installation bases.
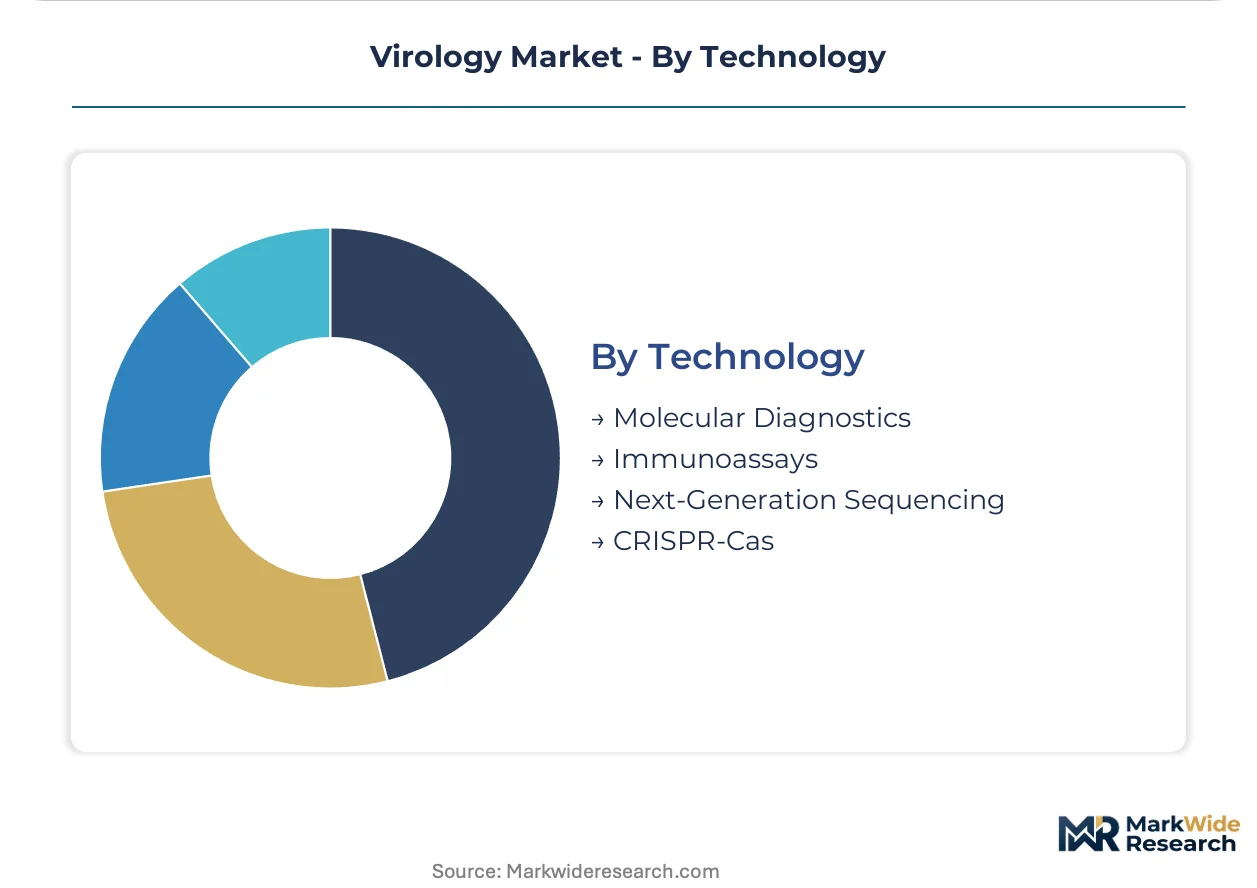
- Molecular Diagnostics:Nucleic acid amplification and detection methods including PCR and isothermal techniques. Laboratories are replacing legacy immunoassays with multiplexed platforms detecting respiratory and bloodstream pathogens simultaneously.
- Immunoassays:Antigen and antibody detection via enzyme-linked and chemiluminescent formats. Sunk capital in ELISA infrastructure slows full platform conversion in hospital systems.
- Next-Generation Sequencing:Viral genomic surveillance and variant analysis. Nanopore platforms enable real-time monitoring at point of care rather than centralized reference laboratories.
- CRISPR-Cas:Gene-editing tools adapted for antiviral target validation and diagnostic applications. Pharmaceutical research divisions are adopting these platforms for accelerated screening programs.
By installed base, Molecular Diagnostics leads. By funding inflow, CRISPR-Cas is climbing the fastest as discovery applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antiviral active pharmaceutical ingredient synthesis clusters in Chinese and Indian chemical hubs, while vaccine formulation and diagnostic platform manufacturing concentrate in North American and European metropolitan clusters with established biotechnology infrastructure.
United States
Federal pandemic preparedness funding sustains advance purchase agreements for broad-spectrum antivirals and seasonal influenza vaccines. The FDA accelerates emergency use authorization pathways for novel respiratory pathogens through template-based submission frameworks. Boston-Cambridge and Research Triangle Park anchor nucleic acid diagnostic platform development, with hospital networks consolidating vendor relationships around integrated workflow contracts.
Germany
EMA centralized marketing authorization procedures govern vaccine distribution across EU member states, extending regulatory review timelines for seasonal candidates. The country's national pharmaceutical regulator enforces ISO 15189 accreditation standards for diagnostic laboratory quality systems. Rhine-Main and Munich metropolitan regions concentrate CRISPR-Cas screening platform R&D, attracting pharmaceutical research divisions seeking accelerated antiviral target validation.
China
Nucleotide analog raw material supply for antiviral manufacturing concentrates in coastal chemical synthesis hubs, exposing formulation sponsors to geopolitical supply disruption risk. The country's national pharmaceutical regulator governs domestic vaccine approval pathways through centralized review procedures. Shanghai and Suzhou industrial parks host expanding mRNA manufacturing capacity, applying platform technology developed during COVID-19 to cytomegalovirus and respiratory syncytial virus candidates.
India
Generic antiviral production capacity scales to serve export markets as originator compounds face patent cliff pressures. The country's national pharmaceutical regulator accelerates abbreviated approval pathways for biosimilar therapeutics. Hyderabad and Ahmedabad pharmaceutical clusters specialize in active pharmaceutical ingredient synthesis and formulation, supplying global antiviral distribution networks.
Switzerland
Swissmedic maintains stringent marketing authorization standards for vaccines distributed through European procurement networks. Basel and Zurich metropolitan areas anchor integrated diagnostic-to-therapeutic workflow providers, bundling instruments, reagents, and informatics for hospital laboratory networks. Federal research funding sustains biosafety level containment infrastructure for high-pathogen viral culture capabilities.
Virology Market Competitive Environment
Integrated platform providers and specialized therapeutic developers split the market between comprehensive workflow bundling and focused antiviral discovery. The vendor structure concentrates around three strategic archetypes: nucleic acid diagnostic platform manufacturers, nucleotide analog drug originators, and multiplexed testing kit suppliers. Competitive positioning depends on securing ISO 15189 accreditation for European market access and achieving FDA breakthrough therapy designation to compress development timelines. Consolidation pressure intensifies as hospital procurement departments favor comprehensive vendor contracts over fragmented point solutions.
Within the integrated platform tier, Thermo Fisher Scientific Inc. and Abbott Laboratories exemplify workflow consolidation strategies, while Gilead Sciences Inc. occupies a position representing nucleotide analog platform specialization. These entities anchor distinct competitive vectors: diagnostic instrumentation bundling versus proprietary antiviral compound development, with each archetype competing for bioinformatics talent against technology sector employers.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Abbott Laboratories |
| Merck & Co. Inc. |
| Johnson & Johnson |
| F. Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific Inc. |
| Gilead Sciences Inc. |
| Novartis International AG |
| Siemens Healthineers |
| Others |
Value Chain & Pricing Dynamics
Hyderabad and Ahmedabad pharmaceutical clusters concentrate generic antiviral active pharmaceutical ingredient synthesis, concentrating upstream supply power among Indian and Chinese chemical manufacturers and compressing formulation margins for originator sponsors facing patent cliff pressures.
Pricing Analysis
FDA Breakthrough Therapy Designation dictates the pricing tier structure for novel antiviral classes, creating premium positioning for nucleotide analog platforms while generic and biosimilar tiers erode originator revenue. Pricing stratifies across premium proprietary compounds, standard licensed generics, and economy biosimilars. Cost compression in the standard tier is intensifying because Indian and Chinese API manufacturers scale export capacity. Hospital procurement departments show least price sensitivity for bundled workflow contracts, while independent reference laboratories face greatest budget pressure.
Supply Chain Analysis
Contract manufacturing organizations in Shanghai, Suzhou, and coastal Chinese chemical hubs hold expanding mRNA vaccine production capacity. Nucleotide analog raw materials draw from Chinese and Indian synthesis clusters, while diagnostic device assembly rests on German and Swiss precision manufacturing. Single-source vulnerability concentrates in API supply for antiviral formulation. Distribution runs through federally funded stockpile procurement channels in the United States and centralized EMA-coordinated networks across EU member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Virology market fragmentation creates entry niches as hospital procurement departments consolidate vendor relationships around integrated workflow providers, displacing independent reference laboratories and fragmenting point-solution suppliers.
For Market Incumbents: Pre-empt biosimilar pressure by deepening proprietary nucleotide analog platform specialization and securing FDA breakthrough therapy designation for pipeline candidates. Incumbents should anchor hospital network contracts through comprehensive diagnostic-to-therapeutic workflow bundling that raises switching costs for competing point solutions.
For New Entrants and Emerging Players: Resource-limited clinics in Southeast Asia and sub-Saharan Africa represent underpenetrated demand for point-of-care molecular diagnostics. New entrants should target miniaturized PCR and isothermal amplification devices with ambient-stable reagent formats, leveraging distributor partnerships with international health procurement organizations to bypass established laboratory networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors CRISPR-Cas screening platform specialists with validated pharmaceutical research division relationships. Long-term viability hinges on bioinformatics talent retention and recurring R&D budget capture from antiviral discovery programs. Watch for inflection when pandemic preparedness agencies rebalance stockpile commitments toward broad-spectrum antivirals.
| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR-Cas Platform Expansion | Accelerated target validation redirects pharmaceutical R&D budgets toward antiviral discovery pipelines. |
| mRNA Manufacturing Scale-Up | Platform technology transfer from COVID-19 opens cytomegalovirus and respiratory syncytial virus therapeutic categories. |
| ISO 15189 Accreditation Investment | European diagnostic laboratory quality standards determine market access for testing kit manufacturers. |
| Point-of-Care Device Miniaturization | Ambulatory and resource-limited clinic penetration expands addressable volume beyond centralized laboratories. |
| Broad-Spectrum Antiviral Stockpiling | US federal advance purchase agreements de-risk manufacturing capacity investments for suppliers. |
Study Parameters
Initial hypotheses were tested against primary input from diagnostic laboratory directors, pharmaceutical R&D executives, regulatory affairs specialists, and hospital procurement managers and refined through secondary validation against FDA Emergency Use Authorization filings, EMA centralized marketing authorization records, ClinicalTrials.gov antiviral study registries, and ISO 15189 accreditation databases. Bottom-up testing kit volume estimates and top-down vaccine procurement value projections were triangulated to constrain forecast variance.
Demand-supply-balance modeling across the analysis window incorporated patient population segmentation by infectious disease indication, technology platform type, and regional regulatory cluster. CAGRs were derived from patent cliff erosion curves for originator compounds and platform adoption S-cycles for nucleic acid diagnostics. Forecast inputs included federal pandemic preparedness funding trajectories and CRISPR-Cas research funding inflows from pharmaceutical discovery programs.
Practitioners should monitor EMA centralized authorization timeline extensions and API supply disruption events for early signals of forecast revision. Cross-checking against WHO viral genomic surveillance priority pathogen lists is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
IVD Infectious Disease Market
Infectious Disease
Viral Gastroenteritis Market
Infectious Disease
Human Immunodeficiency Virus Type 1 (HIV 1) Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Acute Viral Rhinosinusitis Treatment Market
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Mosquito-Borne Diseases Treatment Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Toxoplasmosis Infection Treatment Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Arthropod Borne Viral Infections Market
Infectious Disease
Norovirus Infection Treatment Market
Infectious Disease
Efavirenz Market
Infectious Disease
Acute Vulvovaginal Candidiasis Treatment Market
Infectious Disease
Vaginal Fungi Infections Treatment Market