
 Norovirus Infection Treatment Market | 2026-2036
Norovirus Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Norovirus Infection Treatment Market Analytics
FDA guidance on antiviral development for gastrointestinal pathogens is pivoting the cost-of-entry calculus for norovirus drug developers. Vaxart leverages its oral vaccine platform to differentiate from injectable alternatives in the clinical pipeline. HilleVax sustains R&D intensity through its virus-like particle approach, while Pfizer anchors its position via broad infectious disease infrastructure and hospital channel control.
Norovirus infection treatment encompasses pharmacological and supportive interventions targeting acute gastroenteritis caused by norovirus, a non-enveloped RNA virus transmitted via fecal-oral routes; oral rehydration solutions with precise electrolyte composition (sodium 75 mmol/L, glucose 75 mmol/L) remain the foundation of therapy to prevent dehydration. Symptomatic treatment and hydration solutions occupy the largest volume share due to universal protocol application across all severity grades, while antiviral drugs represent the fastest-growing margin pool as developers target the immunocompromised and institutional populations. Hospitals dominate end-user demand through outbreak management requirements, though homecare settings are expanding as oral therapies reduce admission duration.
FDA, EMA, and WHO prequalification standards collectively shape product registration, manufacturing compliance, and procurement eligibility for norovirus therapeutics across regulated markets. The FDA's orphan drug incentives and EMA's pediatric investigation plans create divergent but complementary pathways that developers must navigate for multi-jurisdiction approval. Stakeholders should monitor antiviral pipeline readouts and regulatory designations to anticipate which therapeutic modalities will secure priority review and formulary placement.
Market Dynamics
FDA's evolving antiviral development guidance is compressing clinical trial timelines for norovirus therapeutics while hospital procurement centralization reshapes formulary access for rehydration and antiemetic protocols.
Growth Catalysts
- Orphan drug incentives:The FDA's orphan designation pathway accelerates regulatory review for norovirus antivirals targeting immunocompromised populations, reducing sponsor development risk.
- Outpatient protocol expansion:Homecare settings are adopting oral rehydration solutions with precise electrolyte composition, extending treatment access beyond acute care facilities.
- Institutional outbreak mandates:Long-term care facilities face state-level reporting requirements that standardize antiemetic stockpiling and drive recurring procurement cycles.
Market Restraints
- Antiviral development costs:Norovirus cannot be cultured in standard cell lines, forcing reliance on human challenge studies that inflate Phase II trial expenditure.
- Single-source API concentration:Glucose and sodium chloride for oral rehydration solutions concentrate among three domestic suppliers, creating input vulnerability.
- Diagnostic substitution:Multiplex gastrointestinal panels displace standalone norovirus testing, reducing confirmed case attribution and targeted treatment initiation.
Strategic Opportunities
- Pediatric investigation plans:EMA's PIP requirements create a regulatory tailwind for sponsors developing weight-based dosing formulations for children under five.
- Telehealth integration:Remote consultation platforms are integrating rehydration protocol guidance, opening direct-to-patient distribution channels previously locked to hospital discharge.
- WHO prequalification:Prequalification standards for oral rehydration solutions unlock procurement eligibility across Gavi-eligible countries with high diarrheal disease burden.
Industry Challenges
- Bioanalytical talent scarcity:Human challenge study design requires specialized virologists and biostatisticians that contract research organizations struggle to retain.
- Cold chain reconfiguration:Virus-like particle vaccine candidates require -70°C storage infrastructure that conflicts with existing 2-8°C distribution networks for oral rehydration solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norovirus Infection Treatment Market |
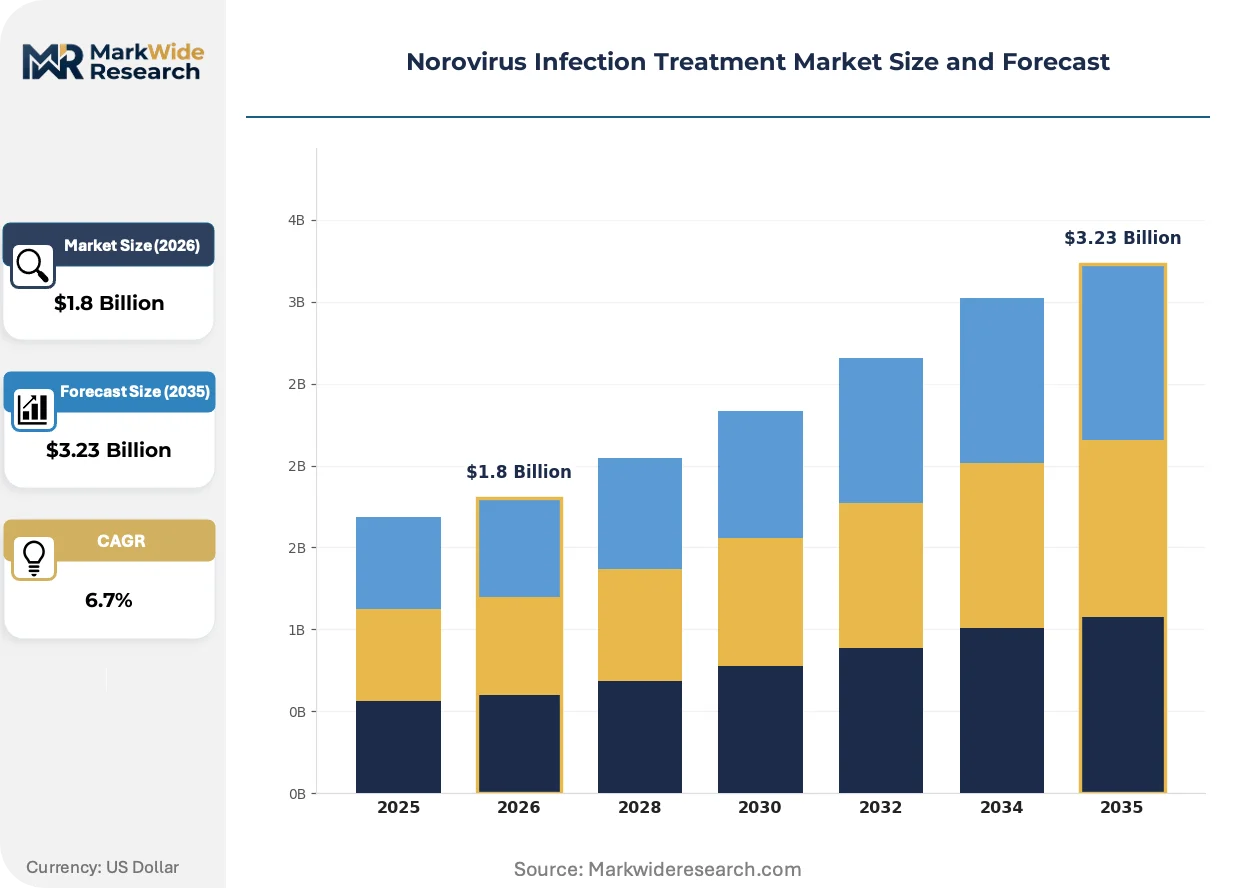
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Symptomatic Treatment, Antiemetics, Antiviral Drugs, Hydration Solutions End User: Hospitals, Clinics, Long-term Care Facilities, Homecare Settings Route of Administration: Oral, Intravenous, Subcutaneous, Rectal Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Direct Sales |
| Companies Covered | Vaxart, HilleVax, Cocrystal Pharma Inc, Prosit Sole Biotechnology, iosBio, OstriGen, Pfizer Inc., Merck & Co., Inc., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norovirus Infection Treatment Market Evolving Landscape
Antiviral pipeline advancement is converging with diagnostic multiplexing and procurement centralization to reshape how norovirus therapeutics reach patients across care settings.
RNA polymerase inhibitors are integrating into Phase II trials as the dominant antiviral modality, with sponsors targeting viral replication suppression rather than symptomatic relief alone. Hospital infectious disease departments are screening immunocompromised transplant recipients for early enrollment, compressing the traditional gap between diagnostic confirmation and therapeutic intervention. This mechanism is integrating clinical trial infrastructure with existing transplant center networks, reducing per-patient recruitment cost.
EMA's pediatric investigation plan mandates are forcing sponsors to develop age-appropriate formulations before adult indication approval, reversing the traditional sequential development pathway. The industrial consequence is parallel formulation workstreams that extend preclinical timelines but secure broader label claims. Vaccine developers targeting norovirus are responding by advancing oral tablet platforms alongside injectable candidates to satisfy PIP administration route diversity requirements.
Hospital procurement consortia are consolidating antiemetic and rehydration solution purchasing through single-source contracts that bundle gastrointestinal protocol supplies. Group purchasing organizations are displacing individual hospital formulary committees as the primary decision node for norovirus outbreak stockpiles. This concentration is most visible in United States acute care networks, where seasonal demand spikes force just-in-time inventory models that prioritize supplier reliability over unit cost minimization.
Norovirus Infection Treatment Market Segmentation
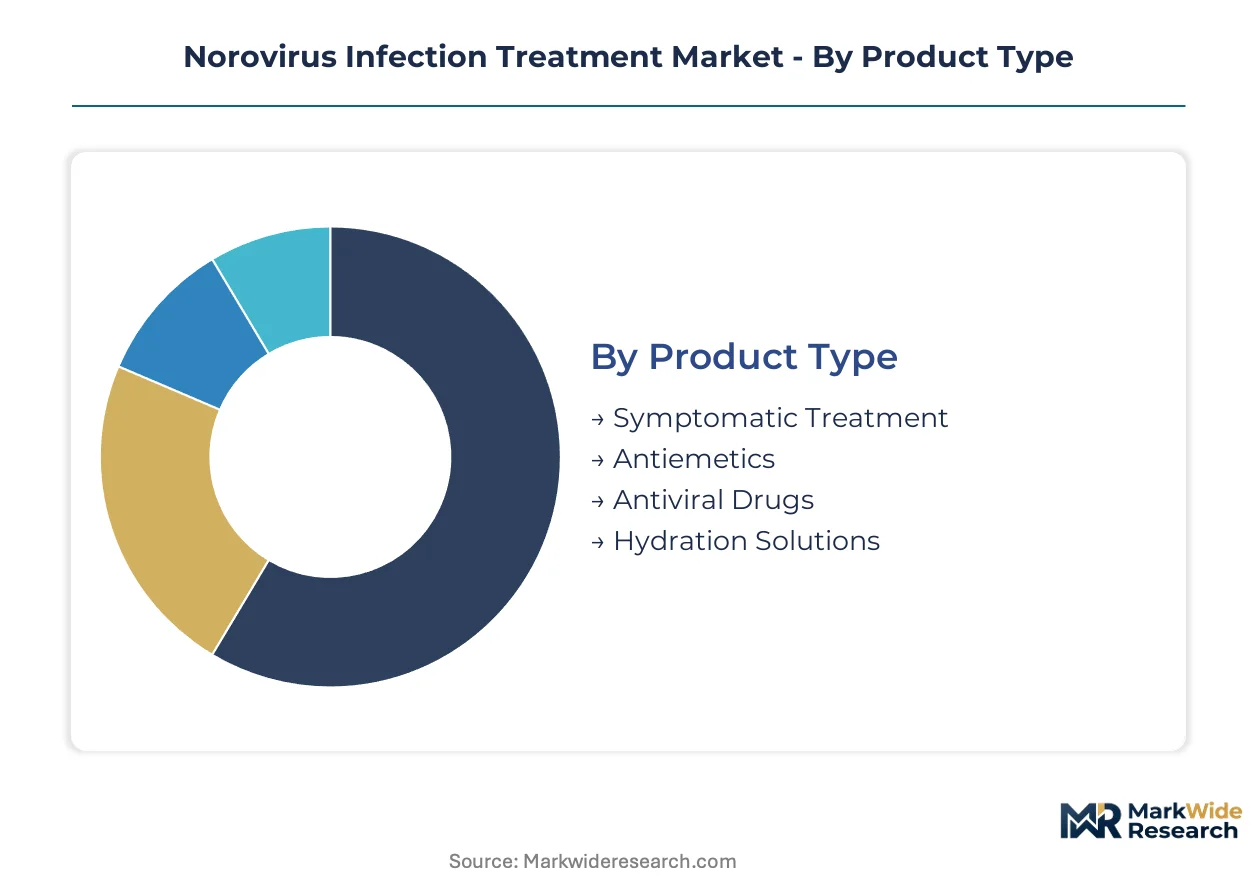
Norovirus therapeutics fragment across four distinct category axes, each governing how products reach patients and who controls procurement decisions. Treatment modality, care setting, delivery mechanism, and distribution pathway together determine margin capture and formulary access for developers and suppliers.
Product Type:
Standalone symptomatic interventions dominate outpatient protocols, while embedded antiviral regimens require hospital infrastructure for administration and monitoring.
- Hydration Solutions:Oral rehydration solutions with sodium 75 mmol/L and glucose 75 mmol/L composition form the foundational therapy across all severity grades. Demand concentrates in United States acute care networks where seasonal outbreak mandates drive just-in-time inventory procurement.
- Antiviral Drugs:RNA polymerase inhibitors target viral replication suppression in immunocompromised populations. Faster expansion belongs to this segment as FDA orphan drug incentives compress clinical trial timelines for sponsors.
- Symptomatic Treatment:Broad-spectrum anti-diarrheal agents address acute gastroenteritis symptoms without pathogen specificity.
- Antiemetics:5-HT3 receptor antagonists and dopamine antagonists manage nausea and vomiting in institutional outbreak settings.
Volume placements concentrate in Hydration Solutions; the faster expansion belongs to Antiviral Drugs.
End User:
Cost tier stratification separates capital-intensive hospital systems from decentralized homecare channels with divergent reimbursement mechanisms.
- Hospitals:Infectious disease departments and emergency departments manage acute dehydration and outbreak containment. Demand concentrates in United States transplant centers where immunocompromised screening protocols accelerate therapeutic intervention.
- Long-term Care Facilities:State-level reporting requirements standardize antiemetic stockpiling for institutional outbreak response. Faster expansion belongs to this segment as regulatory mandates force recurring procurement cycles.
- Clinics:Urgent care and primary care settings handle mild-to-moderate cases with oral rehydration protocols.
- Homecare Settings:Telehealth-integrated remote consultation platforms extend treatment access beyond acute care discharge.
Procurement authority concentrates in Hospitals; the steepest expansion trajectory belongs to Long-term Care Facilities.
Route of Administration:
Application context distinguishes self-administered oral regimens from clinician-dependent parenteral delivery systems.
- Oral:Rehydration solutions and antiemetic tablets enable outpatient management without clinical supervision. Demand concentrates in United States homecare channels where telehealth integration opens direct-to-patient distribution.
- Intravenous:Fluid resuscitation and antiemetic infusion require hospital infrastructure for severe dehydration cases.
- Subcutaneous:Limited application for antiemetic delivery in patients with compromised gastrointestinal absorption.
- Rectal:Alternative administration for patients with persistent vomiting precluding oral intake.
Patient volume concentrates in Oral delivery; the fastest clinical adoption belongs to Intravenous routes in transplant center networks.
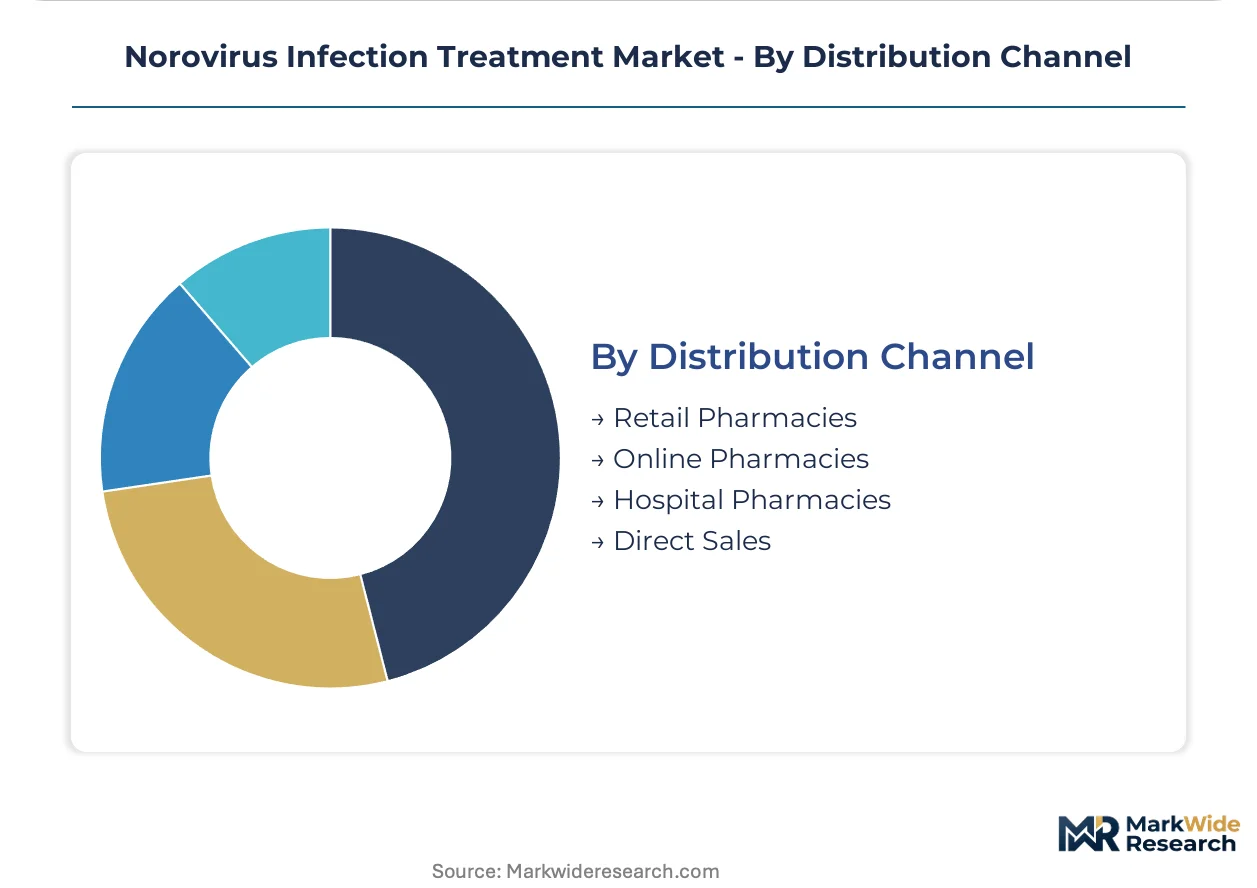
Distribution Channel:
Supply concentration shapes how group purchasing organizations displace individual formulary committees as primary decision nodes.
- Hospital Pharmacies:Centralized procurement consortia bundle gastrointestinal protocol supplies through single-source contracts. Demand concentrates in United States acute care networks where seasonal spikes force supplier reliability prioritization.
- Retail Pharmacies:Community-based access points for oral rehydration and over-the-counter antiemetics in outpatient markets.
- Online Pharmacies:Direct-to-patient channels emerging through telehealth platform integration for homecare protocols.
- Direct Sales:Manufacturer-to-institution contracts for outbreak stockpiles in long-term care and hospital systems.
Contract value concentrates in Hospital Pharmacies; the fastest channel expansion belongs to Online Pharmacies through telehealth integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives and EMA pediatric investigation plans are concentrating norovirus therapeutic development in jurisdictions with specialized regulatory pathways. Hospital procurement centralization and outbreak reporting mandates further shape geographic demand patterns.
United States
Seasonal outbreak spikes drive formulary investment across acute care networks, with transplant centers screening immunocompromised patients for early therapeutic intervention. FDA orphan drug designation accelerates antiviral development timelines for sponsors targeting vulnerable populations. Boston's biotech corridor hosts multiple RNA polymerase inhibitor programs advancing through Phase II trials.
Germany
EMA pediatric investigation plans force parallel formulation development for children under five, extending preclinical timelines but securing broader label claims. Federal outbreak reporting standards standardize antiemetic stockpiling in long-term care facilities. The Rhine-Main biopharma cluster concentrates contract research organizations specializing in human challenge study design.
United Kingdom
NHS procurement consortia bundle gastrointestinal protocol supplies through single-source contracts that prioritize supplier reliability. NICE guidance shapes cost-effectiveness thresholds for novel antiviral reimbursement. London's infectious disease research centers coordinate multicenter transplant recipient screening protocols.
Japan
PMDA streamlined review pathways for infectious disease therapeutics compress regulatory timelines for norovirus antivirals. Aging demographics expand long-term care facility networks subject to institutional outbreak mandates. The Kansai region's vaccine development infrastructure supports oral tablet platform advancement alongside injectable candidates.
India
CDSCO manufacturing compliance requirements and WHO prequalification standards unlock procurement eligibility for oral rehydration solutions across Gavi-eligible countries. Domestic API production for glucose and sodium chloride inputs reduces import dependency. Hyderabad's pharmaceutical formulation cluster scales electrolyte solution manufacturing for regional distribution.
Norovirus Infection Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the norovirus therapeutic landscape, creating a tiered competitive structure. Large pharmaceutical incumbents leverage hospital channel control and broad infectious disease infrastructure to anchor formulary positions. Mid-cap biotech specialists concentrate R&D intensity on single-modality platforms. The dominant competitive moves include strategic partnerships for human challenge study infrastructure and geographic expansion through WHO prequalification pathways.
Within the platform-technology tier, Vaxart occupies a position exemplifying oral vaccine differentiation from injectable alternatives, while HilleVax represents the virus-like particle approach to immunogen design. Among diversified pharmaceutical incumbents, Pfizer sits within the hospital channel control archetype. These three entities collectively illustrate the strategic divergence between modality-focused specialists and infrastructure-anchored conglomerates competing for outbreak response and immunocompromised patient segments.
| Leading Market Players |
|---|
| Vaxart |
| HilleVax |
| Cocrystal Pharma Inc |
| Prosit Sole Biotechnology |
| iosBio |
| OstriGen |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Sanofi |
| Others |
Value Network & Pricing Analysis
WHO prequalification standards for oral rehydration solutions gate both qualified supply and premium-tier pricing access, forcing manufacturers to invest in electrolyte precision and cold-chain documentation before securing procurement eligibility across Gavi-eligible countries. Hospital procurement consortia in the United States leverage this certification hierarchy to tier suppliers by reliability rather than unit cost alone.
Pricing Analysis
Short lead-time premiums dominate contract negotiations for outbreak stockpiles, with hospital group purchasing organizations paying reliability premiums for just-in-time antiemetic delivery during seasonal spikes. Three-tier pricing structure across premium, standard, and economy levels separates WHO-prequalified electrolyte solutions from domestic-grade alternatives and spot-market generics. Price differentiation hinges on FDA registration status and cold-chain documentation depth. Cost compression in economy-tier glucose-sodium inputs is intensifying because single-source API concentration limits supplier switching.
Supply Chain Analysis
Workforce availability constraints in Hyderabad's pharmaceutical formulation cluster and the Rhine-Main biopharma corridor are extending lead times for electrolyte solution batch release. Supply concentrates in India for glucose and sodium chloride API production, the United States for finished oral rehydration formulation, and Germany for virus-like particle vaccine fill-finish. Raw material dependencies rest on pharmaceutical-grade glucose, sodium chloride, and purified water systems. Single-source vulnerability pervades the three-domestic-supplier concentration for critical electrolyte inputs. Distribution runs through hospital pharmacy consortia bundling gastrointestinal protocol supplies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
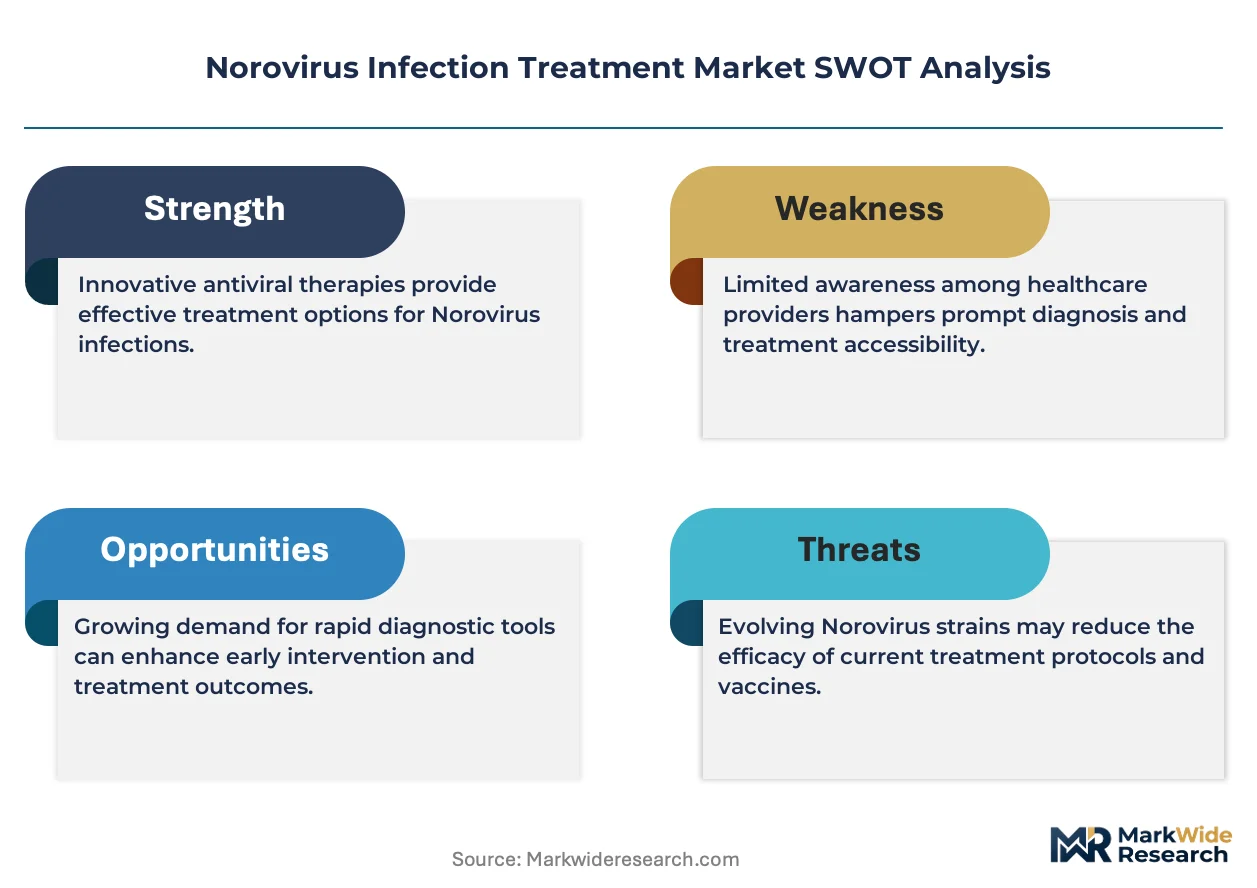
RNA polymerase inhibitors are displacing legacy symptomatic-only protocols, creating a technology-transition phase where mechanism-based antiviral developers capture margin from hydration-therapy incumbents.
For Market Incumbents: Anticipate formulary displacement by RNA polymerase inhibitors through preemptive integration of antiviral screening protocols into existing transplant center networks. Consolidation moves should prioritize backward integration into pharmaceutical-grade electrolyte API production to secure supply against single-source concentration risks. Certification investment in WHO prequalification pathways defends procurement access across Gavi-eligible countries. For New Entrants and Emerging Players: Begin with telehealth-integrated direct-to-patient distribution for oral rehydration solutions, the most penetrable channel expansion opportunity as homecare settings displace hospital discharge protocols. White-space targets include weight-based pediatric formulations under EMA pediatric investigation plan mandates and institutional outbreak stockpiles in long-term care facilities facing state-level reporting requirements. Go-to-market positioning should anchor on supplier reliability guarantees rather than unit cost minimization. For Investors and Strategic Acquirers: FDA orphan drug designation for norovirus antivirals is the leading indicator that clinical trial infrastructure will compress per-patient recruitment costs and accelerate path to formulary placement. Long-term viability favors platform-technology specialists with human challenge study capabilities over diversified infectious disease conglomerates dependent on hospital channel control alone. Target acquisition archetypes include oral vaccine platform developers and contract research organizations specializing in virologist-retention for bioanalytical talent-scarce study design.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Investigation Plan Advancement | EMA mandates force parallel formulation workstreams securing broader label claims before adult approval. |
| Human Challenge Study Infrastructure Partnership | Specialized CRO access reduces Phase II trial expenditure for norovirus antiviral developers. |
| WHO Prequalification Pathway Investment | Unlocks procurement eligibility across Gavi-eligible countries with high diarrheal disease burden. |
| Telehealth Platform Integration | Direct-to-patient distribution channels bypass hospital discharge bottlenecks for oral rehydration protocols. |
| Oral Vaccine Platform Differentiation | Vaxart's tablet approach separates from injectable alternatives in cold-chain-constrained distribution networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with drug development executives, formulary directors, hospital procurement managers, and regulatory affairs leads across United States, German, and Indian markets. FDA orphan drug designation databases, EMA pediatric investigation plan submissions, ClinicalTrials.gov entries, and WHO prequalification rosters supplied validation benchmarks. Bottom-up patient-volume modeling and top-down pharmaceutical expenditure triangulation converged on segment-level estimates.
Granularity-level modeling tracked treatment modality, care setting, administration route, and distribution channel dimensions across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by reimbursement pathway maturity and regulatory designation timelines. Forecast inputs incorporated institutional outbreak mandate expansion rates, telehealth integration penetration curves, and human challenge study completion velocities without year-specific anchoring.
Regulatory pathway delays, antiviral pipeline failure rates, and electrolyte API supply disruptions are the dominant revision risks warranting forecast reassessment. Material deviation in FDA orphan drug review timelines, EMA pediatric investigation plan enforcement intensity, or WHO prequalification queue processing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Direct-Acting Antiviral Medicines Market
Infectious Disease
Viral Gastroenteritis Market
Infectious Disease
Coxsackievirus Infections Treatment Market
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Global Veterinary Infectious Disease Diagnostics Market
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Measles Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Global Pelvic Inflammatory Disease Therapeutics Market
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Italy Infectious Disease in-Vitro Diagnostics Market
Infectious Disease
Acute Viral Rhinosinusitis Treatment Market
Infectious Disease
Viral Hemorrhagic Fever Market