
 Global Gastroesophageal Reflux Disease Market | 2026-2036
Global Gastroesophageal Reflux Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gastroesophageal Reflux Disease Market Foresight
Patient care settings is shifting from inpatient hospital wards toward ambulatory care centers and home healthcare channels. Takeda Pharmaceutical Company leverages its proton pump inhibitor portfolio to sustain leadership across Asia-Pacific markets. AstraZeneca competes through differentiated delivery science in oral suspensions and modified-release tablets. Sanofi anchors its position via over-the-counter antacid distribution networks spanning retail pharmacy and direct-to-consumer platforms.
Gastroesophageal reflux disease encompasses chronic retrograde flow of gastric contents into the esophagus causing mucosal injury, with diagnosis relying on pH monitoring, impedance testing, and endoscopic grading systems such as the Los Angeles classification. Proton pump inhibitors command the largest product type segment due to irreversible H+/K+ ATPase blockade and superior healing rates in erosive esophagitis. Home healthcare represents the fastest-growing end user channel as remote pH capsule monitoring and telemedicine consultations reduce facility dependency.
The FDA maintains strict labeling requirements for long-term PPI safety signals including fracture risk and Clostridioides difficile infection, while the EMA's Pharmacovigilance Risk Assessment Committee periodically reviews acid suppression therapy benefit-risk profiles. Japan's PMDA imposes additional post-market surveillance obligations on novel potassium-competitive acid blockers. Stakeholders must monitor evolving reimbursement policies for ambulatory reflux testing and position for potential biosimilar entry in the H2 receptor antagonist category.
Market Dynamics
The GERD therapeutic landscape pivots on ambulatory pH monitoring technology displacing inpatient diagnostic protocols, forcing reimbursement recalibration and capital redeployment across hospital systems and outpatient networks.
Growth Catalysts
- Japan's PMDA surveillance framework:Post-market obligations on potassium-competitive acid blockers accelerate clinical evidence generation, expanding prescriber confidence in novel mechanisms beyond PPIs.
- Home healthcare channel expansion:Remote pH capsule monitoring and telemedicine consultations reduce facility dependency, capturing patients previously lost to diagnosis abandonment.
- Minimally invasive intervention programs:United States, Germany, and Japan invest in transoral incisionless fundoplication training, creating procedural capacity that pharmaceutical maintenance therapy cannot match.
Market Restraints
- Long-term acid suppression safety signals:FDA fracture risk and Clostridioides difficile infection labeling requirements constrain chronic PPI prescribing patterns.
- Biosimilar entry preparation:H2 receptor antagonist category faces margin compression as manufacturers pre-position for generic substitution dynamics.
- Reimbursement fragmentation:Ambulatory reflux testing coverage varies across United States commercial payers and Medicare Advantage plans, creating access inequities.
Strategic Opportunities
- Telemedicine-integrated diagnosis:Remote interpretation of pH-impedance data by specialized gastroenterology networks opens rural and underserved urban precincts.
- Modified-release formulation development:Differentiated delivery science in oral suspensions addresses nighttime breakthrough symptoms uncontrolled by standard PPI regimens.
- Over-the-counter channel elevation:Direct-to-consumer platforms and retail pharmacy networks capture self-diagnosed patients prior to formal healthcare system entry.
Industry Challenges
- Interventional gastroenterology training pipelines:Transoral incisionless fundoplication and magnetic sphincter augmentation require specialized procedural skills with limited fellowship exposure.
- Legacy EMR integration:Ambulatory pH monitoring data streams face interoperability friction with hospital system electronic medical record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gastroesophageal Reflux Disease Market |
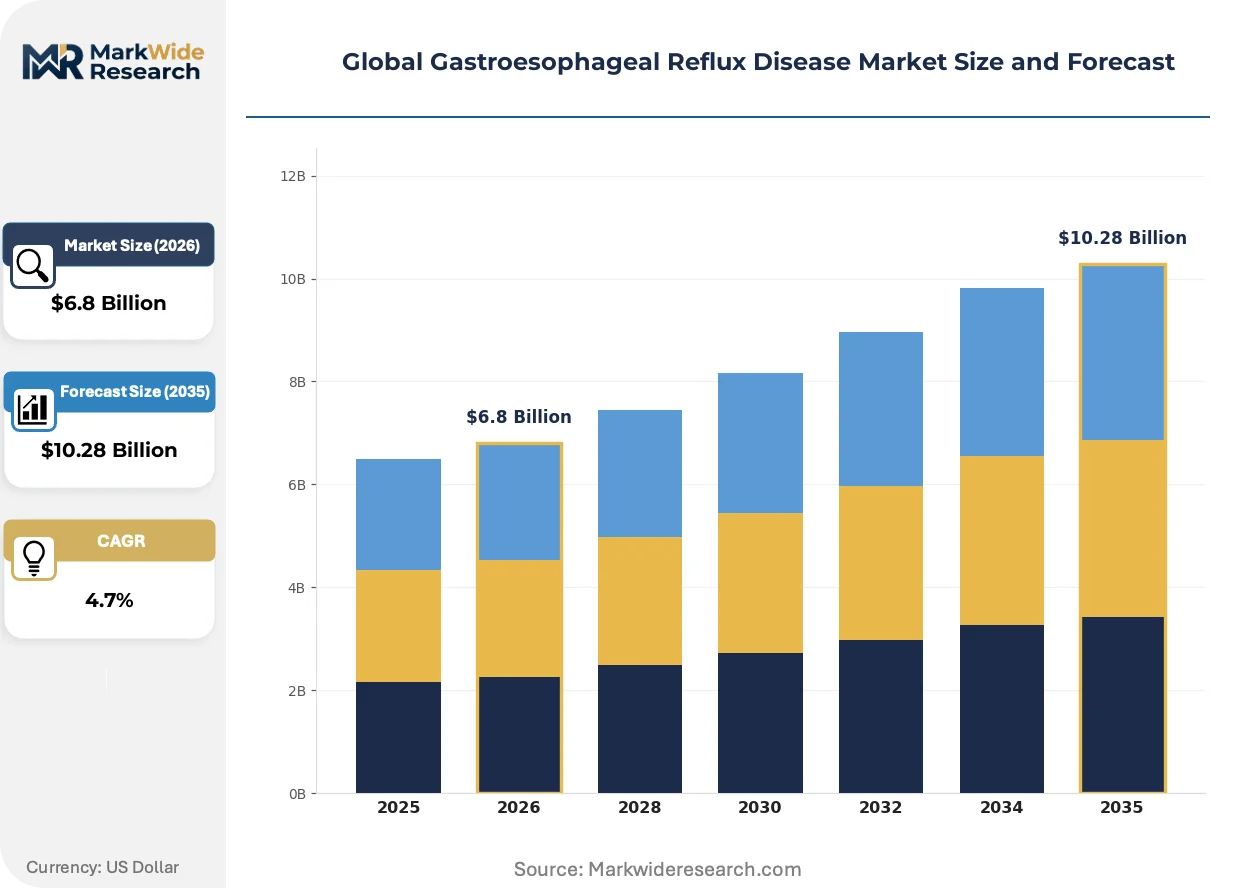
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Pump Inhibitors, H2 Receptor Antagonists, Antacids, Prokinetics, Alginates Therapy Area: Reflux Esophagitis, Erosive Esophagitis, Non-Erosive Reflux Disease, Barrett’s Esophagus, Extra-Esophageal Symptoms End User: Ambulatory Care Centers, Specialty Clinics, Home Healthcare, Outpatient Surgery Centers, Diagnostic Laboratories Delivery Mode: Oral Tablets, Oral Suspensions, Injectable Formulations, Transdermal Patches, Inhalation Solutions |
| Companies Covered | Takeda Pharmaceutical Company, GlaxoSmithKline plc, AstraZeneca, Phathom Pharmaceuticals, Merck & Co., Inc., Johnson & Johnson, Eisai Co., Ltd., Sanofi, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gastroesophageal Reflux Disease Market Shifts & Advancements
Wireless pH monitoring systems and potassium-competitive acid blockers are compressing the diagnostic-to-treatment interval, while regulatory pharmacovigilance tightens long-term safety documentation requirements across all acid suppression categories.
Wireless capsule pH monitoring is rewriting referral patterns between primary care and gastroenterology specialists. Community physicians in United States ambulatory settings deploy Bravo and OMOM systems for 48-96 hour esophageal acid exposure quantification without specialist consultation. This capability is compressing time-to-diagnosis from months to weeks, redirecting endoscopy volume toward therapeutic rather than confirmatory procedures.
REACH-style chemical safety protocols in European pharmaceutical manufacturing impose extended impurity profiling on excipient sourcing for oral suspensions. EMA's Pharmacovigilance Risk Assessment Committee periodic reviews now demand real-world evidence generation beyond randomized trial endpoints. Modified-release tablet manufacturers respond by embedding patient registries into post-launch surveillance obligations.
Self-directed diagnostic behavior among reflux sufferers is fragmenting traditional physician-referral pathways. United States consumers initiate therapy via direct-to-consumer platforms and retail pharmacy antacid aisles before presenting to medical professionals. This pattern concentrates revenue in over-the-counter channels while delaying prescription-grade intervention, challenging pharmaceutical manufacturer patient acquisition economics.
Global Gastroesophageal Reflux Disease Market Segmentation
GERD therapeutic selection hinges on mucosal injury severity, symptom chronicity, and patient adherence profiles. Segmentation reveals where irreversible acid blockade outperforms symptomatic relief, and which delivery innovations capture non-responders to standard-of-care.
Product Type:
Irreversible H+/K+ ATPase inhibitors displaced histamine blockade through superior healing rates in erosive esophagitis, yet potassium-competitive acid blockers now challenge this dominance with faster onset kinetics.
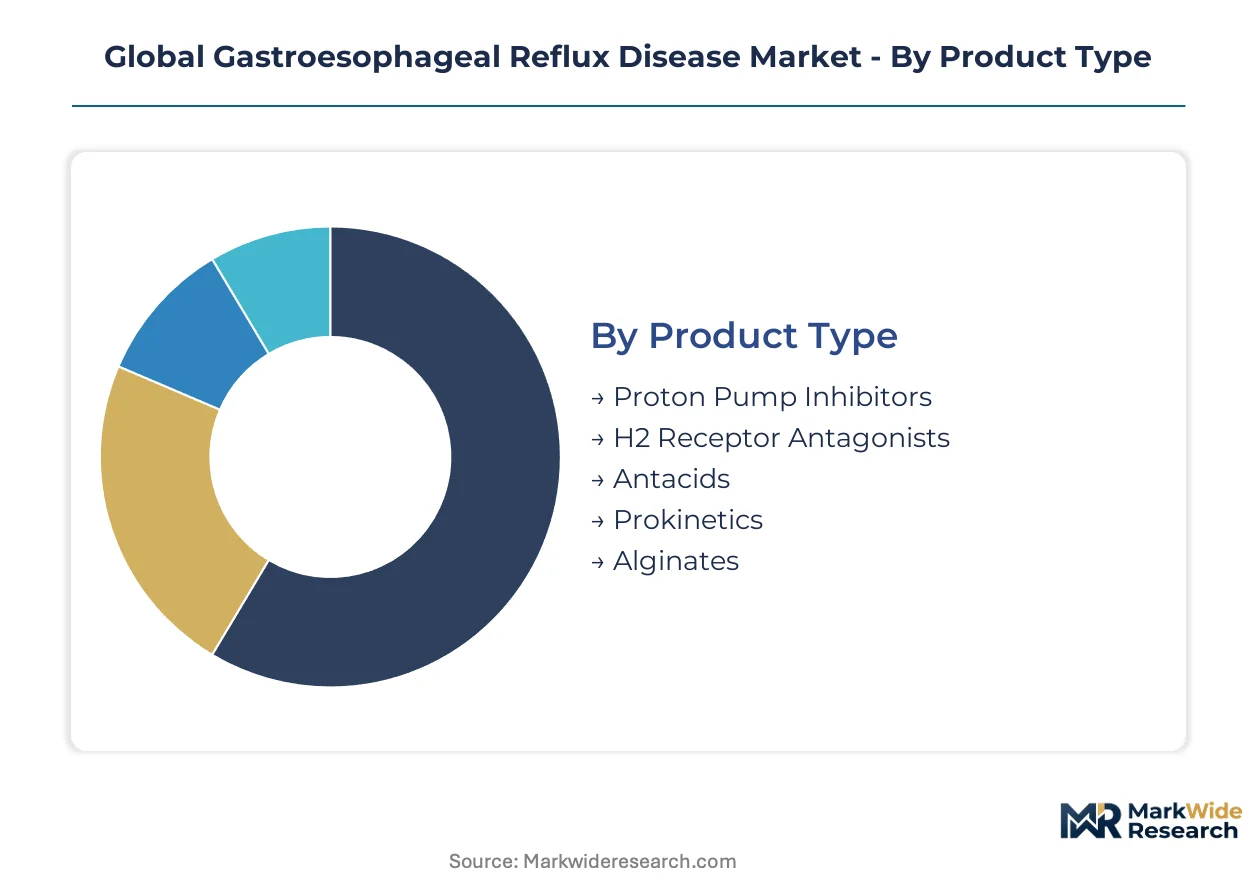
- Proton Pump Inhibitors:Irreversible parietal cell proton pump blockade delivers the highest mucosal healing rates in Los Angeles grade C-D esophagitis. Demand concentrates in United States and Japan where chronic maintenance prescribing dominates ambulatory gastroenterology practice, though FDA fracture risk labeling now constrains indefinite therapy duration.
- H2 Receptor Antagonists:Competitive histamine-2 receptor antagonism provides rapid nocturnal acid breakthrough control at lower cost tiers. Volume placements cluster in European markets where EMA pharmacovigilance reviews have accelerated generic substitution, compressing originator margins ahead of anticipated biosimilar entry.
- Antacids:Rapid chemical acid neutralization serves self-directed symptom management through retail pharmacy and direct-to-consumer channels.
- Prokinetics:Dopamine D2 receptor antagonism and 5-HT4 agonism accelerate gastric emptying in delayed transit phenotypes.
- Alginates:Raft-forming polysaccharide barriers provide postprandial reflux suppression with minimal systemic exposure.
Volume placements concentrate in Proton Pump Inhibitors; the steepest expansion trajectory belongs to Alginates as post-meal symptom control gains prescriber acceptance.
Therapy Area:
Diagnostic stratification by mucosal integrity separates patients requiring mucosal healing from those needing symptom control alone, reshaping endoscopy referral thresholds and pharmaceutical positioning.
- Reflux Esophagitis:Inflammatory mucosal changes visible on endoscopy mandate acid suppression therapy with documented healing endpoints. Demand concentrates in Germany and Japan where systematic screening programs capture patients prior to stricture formation, driven by national digestive disease registry mandates.
- Erosive Esophagitis:Breaks in esophageal mucosa classified Los Angeles grade A through D require highest-intensity acid blockade. Japan's PMDA imposes extended post-market surveillance on novel agents seeking approval in this category, elevating evidence requirements beyond standard PPI comparators.
- Non-Erosive Reflux Disease:Typical reflux symptoms without endoscopic damage dominate patient volume but challenge reimbursement authorization.
- Barrett's Esophagus:Intestinal metaplasia surveillance protocols drive specialist referral and high-dose maintenance therapy.
- Extra-Esophageal Symptoms:Laryngeal and respiratory manifestations require multidisciplinary diagnosis with poor correlation to esophageal acid exposure.
Patient volume concentrates in Non-Erosive Reflux Disease; the fastest clinical evidence generation targets Barrett's Esophagus given malignant transformation surveillance obligations.
End User:
Site-of-care migration from inpatient wards to ambulatory settings reconfigures capital equipment deployment and pharmaceutical distribution economics across health systems.
- Ambulatory Care Centers:Same-day diagnostic and therapeutic procedures reduce hospital admission costs for refractory GERD phenotypes. United States health systems concentrate wireless pH monitoring and transoral incisionless fundoplication capacity in these settings, capturing patients previously routed to academic medical centers.
- Home Healthcare:Remote pH capsule monitoring and telemedicine consultation eliminate facility dependency for diagnosis and maintenance therapy. Germany's ambulatory care reimbursement reforms explicitly cover home-based reflux testing, accelerating channel expansion faster than clinic-based alternatives.
- Specialty Clinics:Gastroenterology-focused practices concentrate advanced endoscopic therapy and surgical referral decisions.
- Outpatient Surgery Centers:Minimally invasive fundoplication and magnetic sphincter augmentation procedures shift from hospital operating rooms.
- Diagnostic Laboratories:Centralized pH-impedance interpretation services support community physician diagnostic capability.
Service volume concentrates in Specialty Clinics; Home Healthcare gains share fastest as remote monitoring technology matures and reimbursement parity expands.
Delivery Mode:
Pharmaceutical formulation science now targets nighttime breakthrough symptoms and dysphagia populations underserved by immediate-release tablet standards.
- Oral Tablets:Modified-release coatings and multiparticulate systems extend acid suppression duration through nocturnal dosing intervals. AstraZeneca's differentiated delivery science in this modality targets United States patients with persistent symptoms on standard PPI regimens.
- Oral Suspensions:Liquid formulations address pediatric populations and adults with swallowing dysfunction. REACH chemical safety protocols in European manufacturing impose extended excipient impurity profiling on suspension products, elevating compliance costs for market entry.
- Injectable Formulations:Intravenous proton pump inhibitors serve perioperative stress ulcer prophylaxis in hospitalized patients.
- Transdermal Patches:Non-oral delivery remains investigational for acid suppression with limited commercial penetration.
- Inhalation Solutions:Aerosolized delivery targets extra-esophageal respiratory manifestations with unproven efficacy in standard GERD.
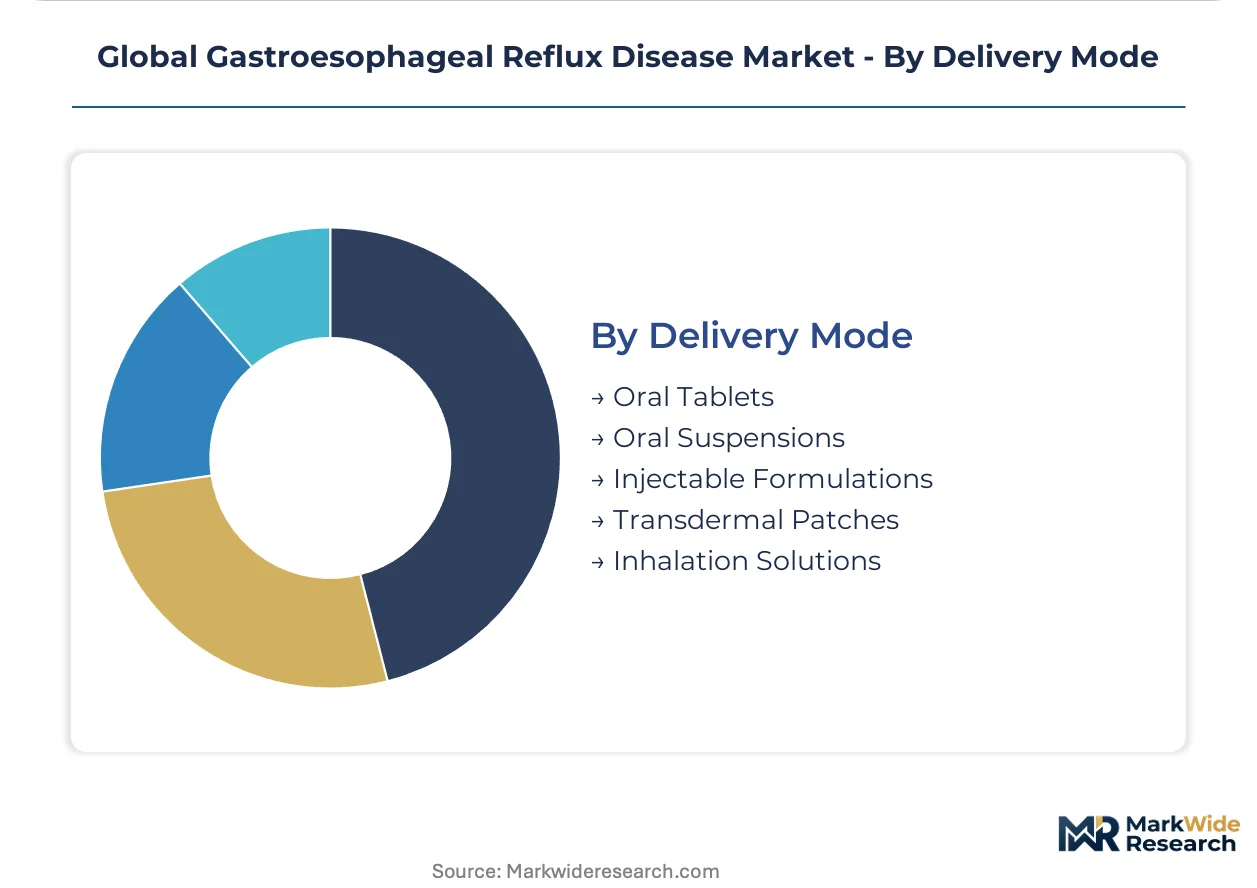
Unit volume concentrates in Oral Tablets; Oral Suspensions expand most quickly as pediatric labeling extensions and geriatric dysphagia populations drive formulation diversity requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for pharmaceutical manufacturing in Singapore and Ireland concentrate active pharmaceutical ingredient synthesis and formulation science for acid suppression therapies. These jurisdictions offer accelerated regulatory pathways and intellectual property protections that attract proton pump inhibitor and potassium-competitive acid blocker developers. Tax incentives in Singapore's Biopolis and Ireland's Shannon Free Zone anchor European and Asia-Pacific supply chains.
United States
FDA fracture risk labeling requirements for long-term proton pump inhibitor therapy constrain chronic prescribing patterns in ambulatory gastroenterology practices. The Centers for Medicare & Medicaid Services reimbursement reforms for wireless pH monitoring expand home healthcare channel access. Minnesota's Mayo Clinic Rochester campus trains interventional gastroenterologists in transoral incisionless fundoplication, building procedural capacity that competes with pharmaceutical maintenance approaches.
Germany
EMA Pharmacovigilance Risk Assessment Committee periodic reviews of acid suppression benefit-risk profiles elevate post-market surveillance obligations for manufacturers. Ambulatory care reimbursement reforms explicitly cover home-based reflux testing, accelerating channel migration faster than clinic-based alternatives. Heidelberg's university hospital system operates Europe's largest pH-impedance diagnostic laboratory, centralizing interpretation services for community physicians across Baden-Württemberg and Bavaria.
Japan
PMDA post-market surveillance obligations on novel potassium-competitive acid blockers accelerate clinical evidence generation beyond standard proton pump inhibitor comparators. National digestive disease registry mandates drive systematic screening programs that capture reflux esophagitis patients prior to stricture formation. Tokyo's Keio University Hospital anchors the Asia-Pacific training network for magnetic sphincter augmentation procedures.
United Kingdom
NICE technology appraisal guidelines for ambulatory reflux monitoring create standardized access criteria across National Health Service trusts. MHRA vigilance requirements for long-term acid suppression align with EMA frameworks while maintaining independent Yellow Card reporting systems. London's Guy's and St Thomas' NHS Foundation Trust operates the country's largest Barrett's esophagus surveillance program, concentrating high-dose maintenance therapy demand.
Global Gastroesophageal Reflux Disease Market Competitive Landscape
Top-tier vendors anchor prescription-grade proton pump inhibitor and potassium-competitive acid blocker development, while mid-tier specialists concentrate on generic histamine antagonist manufacturing and over-the-counter antacid formulations. The vendor base stratifies across three archetypes: integrated pharmaceutical conglomerates with global distribution infrastructure, regional specialists in modified-release delivery science, and consumer health divisions leveraging retail pharmacy networks. Dominant competitive moves include strategic partnerships for biosimilar pre-positioning in the H2 receptor antagonist category and technology licensing agreements for wireless pH monitoring integration.
Among Japanese pharmaceutical conglomerates, Takeda Pharmaceutical Company and Eisai Co., Ltd. occupy positions reflecting deep heritage in gastrointestinal therapeutic development. AstraZeneca represents the Anglo-Swedish integrated model with differentiated delivery science capabilities in oral suspensions and modified-release tablets. These three entities exemplify how geographic origin and corporate structure shape competitive positioning within prescription acid suppression markets.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company |
| GlaxoSmithKline plc |
| AstraZeneca |
| Phathom Pharmaceuticals |
| Merck & Co., Inc. |
| Johnson & Johnson |
| Eisai Co., Ltd. |
| Sanofi |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
Proton pump inhibitor pricing stratifies across originator, authorized generic, and commodity generic tiers, with each tier commanding distinct supply chain configurations from active pharmaceutical ingredient sourcing through finished dose distribution. Originators anchor supply in Ireland's Shannon Free Zone and Singapore's Biopolis, while commodity manufacturers draw from Indian and Chinese API clusters with fragmented secondary packaging networks.
Pricing Analysis
Short lead-time premiums attach to modified-release tablet formulations serving nighttime breakthrough symptom populations, while spot inventory discounts characterize standard immediate-release PPIs facing H2 receptor antagonist substitution pressure. Three-tier pricing structure across premium, standard, and economy levels reflects FDA certification status, volume commitment scale, and vertical integration depth in API manufacturing. Pricing pressure stems from biosimilar pre-positioning in the histamine antagonist category, compressing margins across European markets. Hospital procurement committees exhibit highest price sensitivity via tender aggregation, while specialty gastroenterology practices retain brand loyalty for documented mucosal healing endpoints.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Memphis anchor hub-and-spoke patterns for temperature-sensitive oral suspensions and pH monitoring capsules. Active pharmaceutical ingredient synthesis concentrates in India, China, and Ireland, with potassium-competitive acid blocker intermediates sourcing exclusively from Japanese and South Korean specialty chemical manufacturers. Single-source vulnerability attaches to wireless pH capsule sensor components fabricated in Taiwanese semiconductor foundries. Distribution runs through hospital system central pharmacies, retail pharmacy networks, and direct-to-consumer platforms with divergent cold-chain requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GERD therapeutic landscape sits in a technology-transition phase as potassium-competitive acid blockers displace proton pump inhibitor dominance in Japan and advance through FDA review pathways.
For Market Incumbents: Anticipate reimbursement compression in European ambulatory care channels as EMA pharmacovigilance reviews accelerate generic substitution timelines. Defensive consolidation should concentrate on backward integration into API manufacturing for potassium-competitive acid blocker intermediates, securing supply continuity against Japanese and South Korean specialty chemical bottlenecks. Channel control investments in telemedicine-integrated diagnostic platforms will retain patient capture against direct-to-consumer antacid erosion. For New Entrants and Emerging Players: Launch via direct-to-consumer platforms targeting self-diagnosed non-erosive reflux disease populations in the United States prior to formal healthcare system entry. Home healthcare channel penetration offers the most penetrable white-space, particularly in Germany where ambulatory reimbursement reforms explicitly cover remote pH monitoring. Modified-release formulation development for pediatric and geriatric dysphagia populations provides differentiated positioning against immediate-release tablet incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists in wireless pH monitoring technology given CMS reimbursement expansion and telemedicine integration catalysts. Long-term viability across the analysis window favors acquisition targets with embedded patient registries satisfying EMA post-market surveillance obligations. The signal to watch as inflection indicator is FDA approval pathway progression for novel acid suppression mechanisms beyond irreversible proton pump blockade.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | PMDA post-market surveillance frameworks for potassium-competitive acid blockers elevate evidence requirements beyond standard PPI comparators. |
| Manufacturing Scale-Up | REACH chemical safety protocols in European oral suspension production impose extended excipient impurity profiling compliance costs. |
| Licensing Agreement | Technology licensing for wireless pH monitoring integration opens rural and underserved urban precincts through remote interpretation networks. |
| Pipeline Diversification | Modified-release formulation development targets nighttime breakthrough symptoms uncontrolled by standard proton pump inhibitor regimens. |
| Strategic Partnership | Hospital system partnerships for transoral incisionless fundoplication training build procedural capacity competing with pharmaceutical maintenance approaches. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with formulary directors, regulatory affairs leads, hospital procurement managers, and payer access specialists across the United States, Germany, and Japan. FDA submission databases, EMA periodic safety update reports, PMDA post-market surveillance records, and ClinicalTrials.gov registries provided pharmaceutical pipeline visibility. Bottom-up patient volume modeling and top-down therapeutic category expenditure analysis were reconciled through iterative triangulation.
Data-stream reconciliation across prescription audit databases, ambulatory procedure registries, and reimbursement claim extracts informed segmentation-specific growth trajectories. The analytical framework modeled therapy area, product type, end user channel, and delivery mode dimensions across the projection horizon, with regional regulatory clusters treated as distinct forecast strata. CAGRs were derived from fitted trend extrapolation moderated by patent expiry schedules and biosimilar entry probability assessments. Wireless pH monitoring technology diffusion curves and telemedicine reimbursement parity timelines served as category-specific demand drivers.
Regulatory approval delays, ambulatory reimbursement fragmentation, and interventional gastroenterology training pipeline constraints are the dominant revision risks to forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Herpangina Treatment Market
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Wilms Tumor Treatment Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Allergic Conjunctivitis Market
Specialty Medicine
Iron Deficiency Anemia Therapy Market
Specialty Medicine
Severe Combined Immunodeficiency Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market
Specialty Medicine
Paediatric Sports Medicine Market
Specialty Medicine
Pseudobulbar Treatment Market
Specialty Medicine
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market
Specialty Medicine
Asia-Pacific Primary Angle-Closure Glaucoma Market
Specialty Medicine
Meningitis Treatment Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Global Pancreatic Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Musculoskeletal System Disorders Market