
 India Heavy Construction Equipment Rental Market | 2026-2036
India Heavy Construction Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
India Heavy Construction Equipment Rental Market Insights
Skilled crane operators and certified rigging specialists is rotating from traditional ownership models toward rental platforms as fleet complexity outpaces in-house maintenance capabilities. L&T Rentals anchors western and southern India through its captive equipment pool and project-integrated service contracts. Sanghvi Movers Limited dominates heavy-lift crane logistics with one of Asia's largest crawler crane fleets. ABC Infra Equipment Pvt Ltd specializes in earthmoving fleets for dam and irrigation contractors across central India.
India heavy construction equipment rental encompasses the short-to-medium-term provision of mechanized earthmoving, lifting, and material-handling machinery rated above 75 horsepower, typically deployed through operator-inclusive contracts with maintenance obligations borne by the lessor. The segment serves capital-intensive projects requiring intermittent or project-specific mechanization without balance-sheet asset ownership. Excavators and cranes lead equipment type demand, with hydraulic crawler units above 20-ton capacity commanding premium rental rates in mining and metro applications. Monthly and long-term rental service models capture the deepest margin pools by locking contractors into fleet-management agreements that bundle fuel, operators, and preventive maintenance.
BIS certification requirements for construction machinery safety and CEA electrical standards for powered equipment shape product eligibility and cross-state deployment permissions. The PLI scheme for specialty steel and domestic component manufacturing is nudging rental fleet operators toward India-assembled chassis and boom assemblies. State-level RERA enforcement and NHAI contractor pre-qualification norms are tightening equipment-age and emission thresholds that rental providers must monitor to retain project eligibility.
Market Dynamics
Rental fleet operators face mounting pressure from Bharat Stage V emission pre-compliance deadlines and the Ministry of Road Transport and Highways' contractor pre-qualification norms, which now mandate equipment-age thresholds that accelerate fleet turnover cycles.
Growth Catalysts
- Bharatmala Pariyojana corridor development:Dedicated highway projects generate sustained demand for earthmoving and paving equipment rentals across Maharashtra, Gujarat, and Rajasthan.
- CEA electrical standards for powered machinery:Uniform certification requirements enable cross-state fleet deployment, reducing idle-time penalties for rental operators holding multi-region contracts.
- Metro rail construction acceleration:Urban infrastructure authorities in Delhi, Mumbai, and Bangalore specify hydraulic crawler cranes above 20-ton capacity, locking rental providers into long-term fleet-management agreements.
Market Restraints
- Specialty steel import dependency:Domestic boom assembly manufacturing remains constrained by raw material availability, compressing margins on crane fleet expansions.
- BIS certification timeline bottlenecks:Safety testing backlogs for new equipment models delay commercial deployment by 4-6 months, stranding capital in pre-certified inventory.
- Skilled operator scarcity:Certified rigging specialists and crane operators command wage premiums that erode the cost advantage of rental versus ownership for long-duration projects.
Strategic Opportunities
- PLI scheme for domestic chassis assembly:Incentives for India-assembled equipment components reduce import duty exposure and align fleet operators with local content preferences in government tenders.
- Dam and irrigation contractor penetration:Central India earthmoving demand remains underserved by organized rental platforms, offering first-mover positioning for fleet operators with excavator-heavy configurations.
- Telematics-integrated preventive maintenance:IoT-enabled fleet monitoring converges with operator-inclusive contracts to create performance-guaranteed rental products that differentiate against asset-only competitors.
Industry Challenges
- Emission threshold compliance velocity:State-level RERA enforcement and NHAI contractor norms require real-time fleet age monitoring, complicating asset lifecycle planning across dispersed project sites.
- Cross-state permit fragmentation:Motor vehicle taxation and interstate movement clearances for heavy equipment create administrative overhead that delays emergency fleet reallocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Heavy Construction Equipment Rental Market |
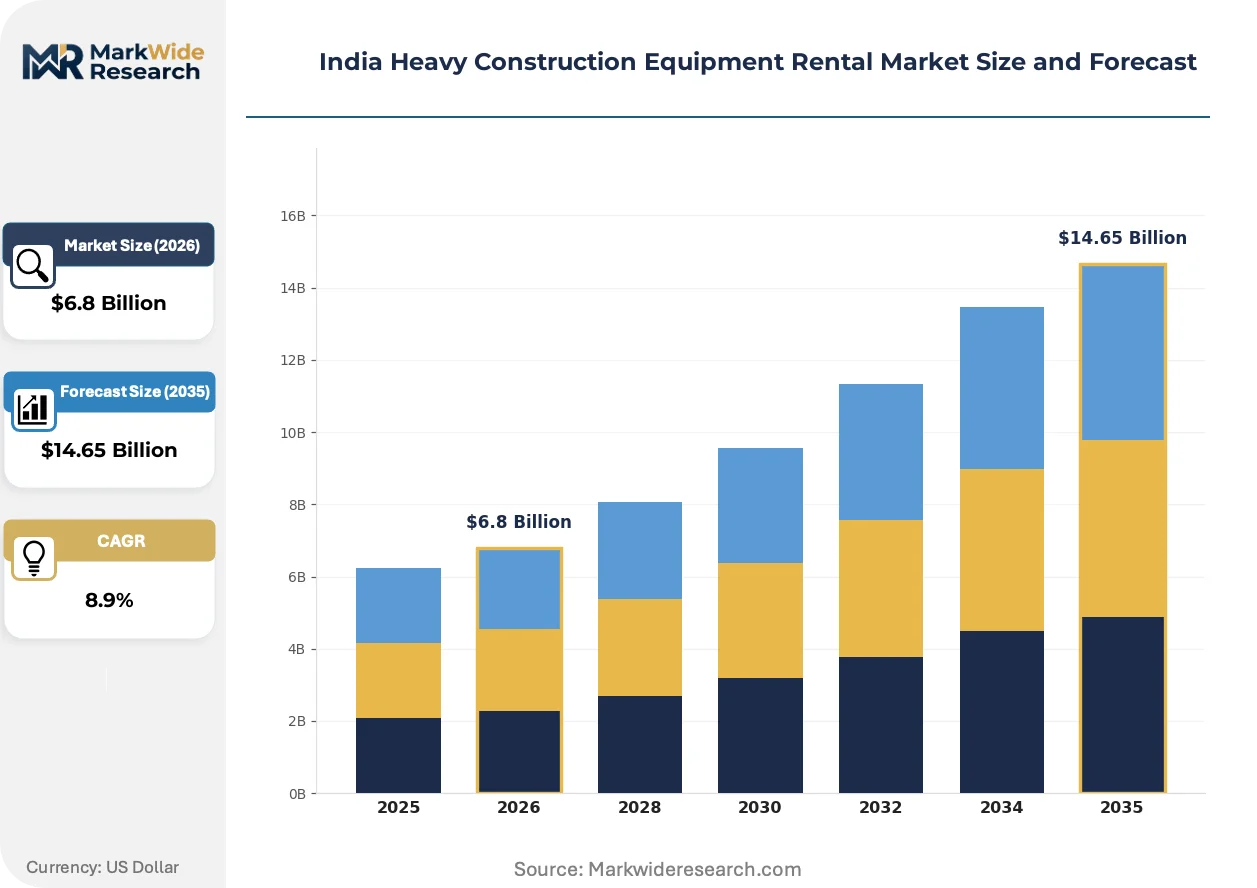
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.65 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Bulldozers, Cranes, Loaders Application: Infrastructure, Mining, Residential, Commercial End User: Contractors, Government, Builders, Developers Service Model: Hourly Rental, Daily Rental, Monthly Rental, Long-term Rental |
| Companies Covered | ABC Infra Equipment Pvt Ltd, L&T Rentals, Sanghvi Movers Limited, Quippo Construction Equipment Ltd., Gmmco, Volvo Construction Equipment, All India Crane Hiring Co., Jainex Group, IQUIPPO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Heavy Construction Equipment Rental Market Trends and Innovations
Telematics-enabled fleet management and emission-compliant powertrains are compressing the traditional ownership-rental decision boundary, while contractor procurement patterns favor bundled service contracts over bare equipment leases.
Hybrid-electric auxiliary systems for crawler cranes are supplanting conventional diesel idling practices in metro construction zones. Delhi Metro Rail Corporation contractors now specify low-emission crane configurations for urban airshed compliance. This shift is compressing residual values of pure-diesel fleet assets and accelerating rental operator capital redeployment toward electrified platforms.
BIS certification requirements for construction machinery safety are tightening documentation standards for cross-state equipment deployment. The Central Electricity Authority's electrical standards for powered equipment now mandate third-party inspection protocols that extend pre-rental preparation timelines. Mining and dam contractors in Maharashtra and Gujarat are responding by consolidating rental relationships with providers holding pre-certified fleet pools.
Fixed monthly rental agreements with bundled fuel, operators, and maintenance are displacing traditional hourly-rate bare leases in highway and industrial corridor projects. NHAI contractors facing Bharatmala Pariyojana milestone penalties now prioritize fleet availability guarantees over per-hour cost minimization. This preference shift concentrates contract awards with rental operators holding captive technician pools and preventive maintenance infrastructure.
India Heavy Construction Equipment Rental Market Segmentation
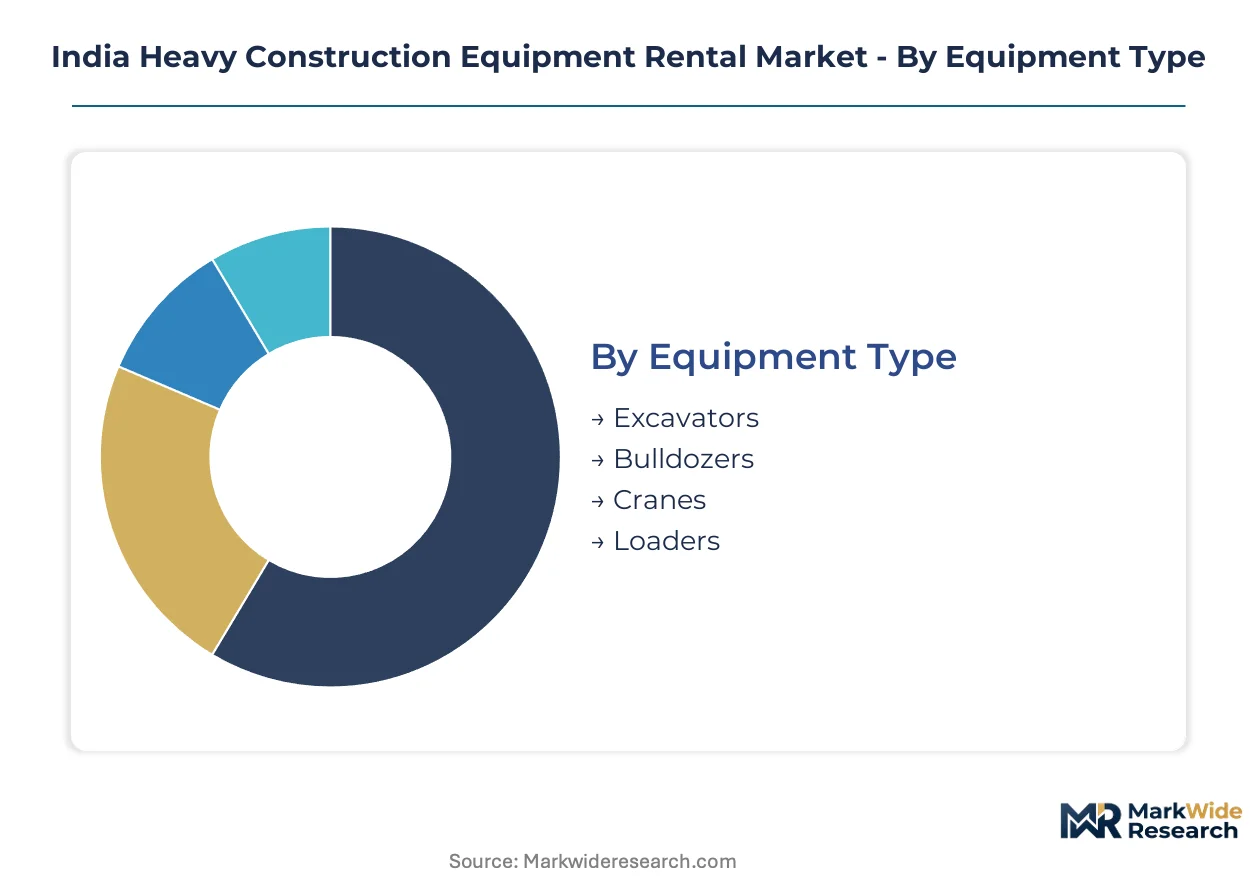
Equipment rental in India fragments across four dimensions that determine fleet configuration, contract structure, and geographic deployment. Each segmentation axis carries distinct margin profiles and regulatory exposure that rental operators must calibrate against project pipelines.
Equipment Type:
Domestic demand concentrates on earthmoving and lifting machinery serving corridor infrastructure, while specialized mining-grade units retain import dependency for core components.
- Excavators:Hydraulic crawler units above 20-ton capacity dominate metro rail and mining applications. Maharashtra and Gujarat contractors specify these for Bharatmala Pariyojana earthworks, with CEA electrical standards mandating third-party inspection protocols that extend pre-rental preparation timelines.
- Cranes:Crawler and all-terrain configurations above 75 horsepower command premium rates in urban airshed zones. Delhi Metro Rail Corporation contractors now specify low-emission crane configurations, compressing residual values of pure-diesel fleet assets and accelerating capital redeployment toward electrified platforms.
- Bulldozers:Tracked dozers serve dam and irrigation contractors across central India where organized rental penetration remains limited.
- Loaders:Wheel loaders support highway paving fleets in Rajasthan and Karnataka corridor projects.
Excavators command the established base. The steepest expansion runs through cranes as metro construction accelerates across Delhi, Mumbai, and Bangalore.
Application:
Cost tier separation distinguishes capital-intensive long-cycle projects from intermittent residential deployment, with infrastructure commanding bundled service premiums.
- Infrastructure:Highway, rail, and port projects generate sustained demand for fleet-availability guarantees. NHAI contractors facing Bharatmala Pariyojana milestone penalties prioritize uptime over per-hour cost minimization, locking rental providers into long-term fleet-management agreements with bundled fuel, operators, and preventive maintenance.
- Mining:Open-cast operations in Odisha and Jharkhand specify high-horsepower excavators with BIS-certified safety documentation for cross-state deployment permissions.
- Residential:Mid-rise construction in tier-2 cities drives short-cycle loader and mini-excavator rentals.
- Commercial:IT park and logistics hub development in Hyderabad and Chennai sustains crane-heavy rental portfolios.
Infrastructure anchors revenue concentration. Mining exhibits the steepest margin compression from specialty steel import dependency.
End User:
Customer type determines contract duration, payment security, and compliance burden, with government pre-qualification norms filtering fleet eligibility.
- Contractors:Road and highway specialists seek fleet flexibility without capital lock-in, rotating from ownership models toward rental platforms as Bharat Stage V emission pre-compliance deadlines accelerate fleet turnover cycles.
- Government:NHAI and state irrigation departments mandate equipment-age thresholds and emission certifications that rental providers must monitor through real-time fleet tracking.
- Builders:Commercial real estate developers in Mumbai and Bangalore consolidate rental relationships with providers holding pre-certified fleet pools.
- Developers:Industrial corridor participants in Gujarat specify operator-inclusive contracts with performance guarantees.
Contractors represent the volume base. Government contracts deliver the steepest expansion in long-term fleet-management penetration.
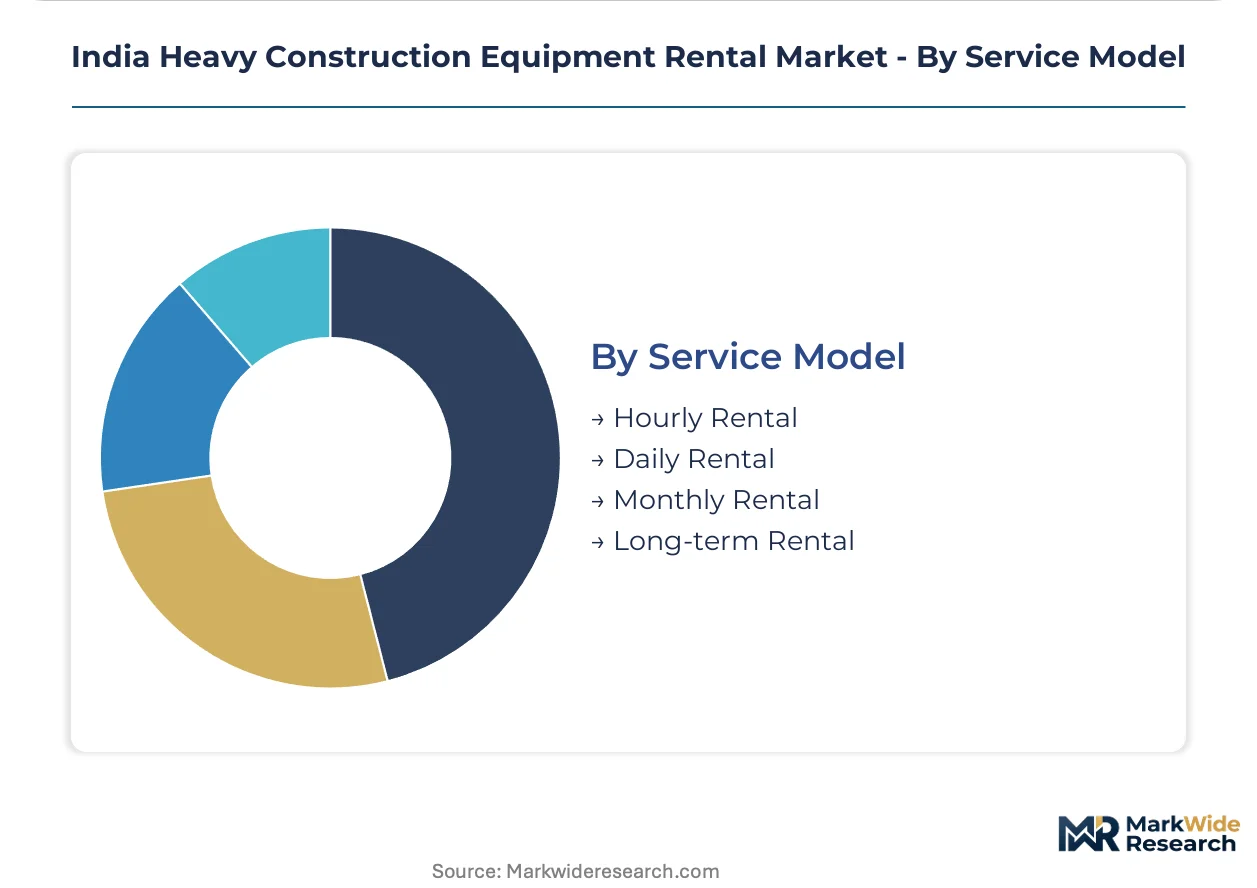
Service Model:
Duration-based pricing stratifies across premium bundled offerings and economy bare leases, with monthly structures capturing deepest margin pools.
- Monthly Rental:Fixed agreements bundling fuel, operators, and preventive maintenance displace traditional hourly-rate structures in highway and industrial corridor projects. This model captures the deepest margin pools by locking contractors into comprehensive fleet-management relationships.
- Long-term Rental:Multi-year agreements align rental operators with Bharatmala Pariyojana project timelines, incorporating telematics-integrated preventive maintenance as a differentiation layer against asset-only competitors.
- Hourly Rental:Bare equipment leases persist in intermittent residential applications with limited operator scarcity exposure.
- Daily Rental:Emergency fleet reallocation for breakdown coverage faces administrative overhead from cross-state permit fragmentation.
Monthly rental commands the established base. Long-term rental exhibits the steepest expansion as NHAI contractors prioritize availability guarantees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra commands rental rate premiums 15-20% above Gujarat for equivalent crawler crane configurations, reflecting Mumbai metro construction intensity versus Surat corridor standardization.
Maharashtra
Mumbai Metro Rail Corporation contractors specify hydraulic crawler cranes above 20-ton capacity for urban airshed compliance, while Bharatmala Pariyojana earthworks sustain excavator deployment across the Mumbai-Pune Expressway corridor. BIS certification requirements for construction machinery safety filter equipment eligibility for cross-state movement. Nagpur's industrial zone anchors heavy-lift crane logistics serving mining operations in adjoining districts.
Gujarat
Dedicated freight corridor development and port modernization at Mundra and Hazira generate continuous demand for earthmoving and material-handling fleets. CEA electrical standards for powered equipment enable seamless cross-border deployment into Rajasthan. The Delhi-Mumbai Industrial Corridor segment through Ahmedabad-Dholera sustains long-term rental agreements with bundled maintenance obligations.
Karnataka
Bangalore metro construction Phase 3 specifications lock rental providers into low-emission crane configurations, compressing residual values of pure-diesel assets. State-level RERA enforcement tightens equipment-age thresholds for commercial real estate contractors. The Bangalore-Chennai Industrial Corridor drives wheel loader demand for logistics hub development.
Tamil Nadu
Chennai port modernization and Ennore container terminal expansion sustain crane-heavy rental portfolios with performance-guaranteed contracts. NHAI contractor pre-qualification norms mandate real-time fleet age monitoring for highway projects linking Tamil Nadu with Kerala. Coimbatore's manufacturing cluster generates intermittent demand for short-cycle excavator rentals.
Delhi-NCR
Delhi Metro Rail Corporation's low-emission mandates for urban construction zones accelerate rental operator capital redeployment toward hybrid-electric auxiliary systems. Bharat Stage V emission pre-compliance deadlines compress fleet turnover cycles for contractors serving the Eastern Peripheral Expressway. Gurugram's commercial real estate developers consolidate rental relationships with providers holding pre-certified fleet pools.
India Heavy Construction Equipment Rental Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated project-service bundlers commanding premium positioning against asset-only hourly lessors. The vendor base organizes around three strategic tiers: captive equipment pools with maintenance infrastructure, specialized heavy-lift logistics operators, and regional earthmoving fleet aggregators. Consolidation pressure is intensifying as Bharat Stage V compliance costs favor scaled operators with capital redeployment capacity. Dominant competitive moves center on long-term fleet-management contract capture and telematics-integrated preventive maintenance differentiation.
Within the integrated service tier, L&T Rentals anchors western and southern India through project-integrated contracts that bundle fuel, operators, and maintenance. Sanghvi Movers Limited exemplifies the specialized heavy-lift archetype with crawler crane logistics capabilities. ABC Infra Equipment Pvt Ltd occupies a position among regional earthmoving specialists serving dam and irrigation contractors across central India.
| Leading Market Players |
|---|
| ABC Infra Equipment Pvt Ltd |
| L&T Rentals |
| Sanghvi Movers Limited |
| Quippo Construction Equipment Ltd. |
| Gmmco |
| Volvo Construction Equipment |
| All India Crane Hiring Co. |
| Jainex Group |
| IQUIPPO |
| Others |
Pricing and Supply Chain Analysis
Captive fleet scale at tier-one rental operators compresses per-unit maintenance overhead and establishes price floors that regional aggregators struggle to match. This scale concentration rewards integrated service bundlers with margin headroom while forcing asset-only competitors toward commodity hourly-rate positioning.
Pricing Analysis
Configured-to-order crane specifications command 25-35% premiums over standard crawler configurations in metro airshed zones. Project-based long-term contracts dominate highway and industrial corridor deployment, with price differentiation hinging on Bharat Stage V pre-compliance certification and bundled operator availability. Cost compression in bare equipment leasing intensifies as diesel-idling restrictions in Delhi and Mumbai erode residual values of non-hybrid fleet assets. Government contractors exhibit lowest price sensitivity due to milestone penalty exposure, while residential developers in tier-2 cities drive aggressive rate negotiation.
Supply Chain Analysis
Strategic stockpiling of specialty steel boom assemblies characterizes fleet operators seeking to buffer BIS certification timeline volatility. Manufacturing concentration in China, South Korea, and Japan supplies hydraulic systems and precision-engineered components that Indian assembly plants integrate into CEA-compliant finished equipment. Single-source vulnerability in high-horsepower engine supply creates exposure to DGFT import licensing shifts. Distribution runs through project-integrated service contracts that bypass traditional equipment dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bharat Stage V emission deadlines and CEA electrical standard enforcement constitute a dual regulatory inflection compressing fleet turnover cycles and rewarding pre-certified fleet pools.
For Market Incumbents: Fortify captive maintenance infrastructure through technician training pipelines and preventive maintenance technology deployment. Consolidate position in long-term fleet-management agreements before emission thresholds harden. Bharat Stage V compliance costs favor scaled operators with capital redeployment capacity over regional aggregators. For New Entrants and Emerging Players: Differentiate on telematics-integrated performance guarantees in dam and irrigation corridors where organized rental penetration remains limited. Target central India earthmoving demand with excavator-heavy configurations. Pursue operator-inclusive contracts as the primary go-to-market angle against asset-only incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated service bundlers with captive technician pools over pure-play fleet owners. Five-to-ten year viability hinges on electrified platform transition velocity. Acquisition targets should demonstrate pre-certified fleet scale and Bharatmala Pariyojana contract visibility. Monitor BIS certification backlog duration as the critical inflection signal for fleet deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Integrated Preventive Maintenance | IoT-enabled fleet monitoring creates performance-guaranteed rental products that differentiate against bare equipment competitors. |
| Domestic Chassis Assembly Expansion | PLI scheme alignment reduces import duty exposure and secures eligibility for government tender local content preferences. |
| Hybrid-Electric Fleet Transition | Delhi Metro Rail Corporation low-emission mandates compress diesel asset residual values and accelerate capital redeployment. |
| Central India Earthmoving Penetration | Dam and irrigation contractor demand remains underserved by organized rental platforms offering first-mover positioning. |
| Cross-State Certification Pre-Positioning | BIS documentation standards and CEA inspection protocols enable seamless fleet reallocation across Maharashtra, Gujarat, and Rajasthan. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations directors, NHAI contractor procurement leads, crane maintenance supervisors, and state irrigation department engineers and refined through secondary validation against Ministry of Road Transport and Highways project disclosures, BIS certification registries, CEA electrical standard filings, and PLI scheme participant announcements. Bottom-up equipment deployment estimates triangulated with top-down infrastructure investment flow analysis.
Variance decomposition across equipment type, application intensity, service model duration, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segmented fleet expansion trajectories and project pipeline visibility. Forecast inputs incorporated Bharat Stage V pre-compliance capital cycle timing and specialty steel import dependency ratios.
Material uncertainties — BIS certification timeline extensions, DGFT import licensing shifts, and state-level RERA enforcement variance — sit outside the modeled envelope. Forecasts reflect assumptions regarding Bharatmala Pariyojana milestone adherence and CEA standard harmonization across state electricity boards. Revision becomes warranted when hybrid-electric crane specification adoption crosses 40% of metro authority tender volume.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Vibratory Rammer Market
Construction Equipment
Global Vibratory Hammer Market
Construction Equipment
Collating Machinery Market
Construction Equipment
Brazil Metal Fabrication Equipment Market
Construction Equipment
Mobile Asphalt Plant Market
Construction Equipment
Aerial Work Platform (AWP) Market
Construction Equipment
Broaching Machine Market
Construction Equipment
Global Asphalt Crushers Market
Construction Equipment
Compact Power Equipment Rental Market
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
North America: Heavy Construction Equipment Market
Construction Equipment
Roadheaders Market
Construction Equipment
Log Splitters Rental Market
Construction Equipment
Induction Furnace Market
Construction Equipment
Cement and Mortar Testing Equipment Market
Construction Equipment
Hydraulic Shearing Machine Market