
 Baby Ear Thermometer Market | 2026-2036
Baby Ear Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Ear Thermometer Market Outlook
Bundle-and-accessory unbundling is decoupling thermometer sales from traditional kit configurations, letting parents purchase standalone ear probes, hygiene caps, and calibration tools separately. Braun leverages its brand strength across European pharmacy channels to sustain premium positioning. Omron Healthcare anchors its portfolio through R&D intensity in infrared sensor miniaturization. Kinsa competes by extending software integration into fever-tracking apps that sync with pediatric telehealth platforms.
A baby ear thermometer is a handheld diagnostic device that measures infrared energy emitted from the tympanic membrane to calculate core body temperature within one to three seconds, typically employing thermopile sensors and microchip processors housed in a plastic probe with disposable lens filters. Its primary commercial purpose is to provide non-invasive, rapid fever detection for infants and toddlers in home and clinical settings. Infrared sensor technology leads unit shipments due to speed and hygiene advantages, while smart-connected models represent the fastest-growing category as Bluetooth-enabled data logging attracts digitally engaged parents. The pediatrician end-user segment occupies stable margin pools through bulk procurement contracts and clinical validation requirements.
The FDA regulates baby ear thermometers as Class II medical devices under 510(k) premarket notification requirements, enforcing accuracy standards that shape design investments and testing timelines for manufacturers seeking US market access. ISO standards for clinical thermometers establish international performance benchmarks that influence procurement specifications across European and Asian hospital systems. Stakeholders must monitor evolving cybersecurity guidance for connected health devices as smart thermometer data flows into pediatric electronic health records and remote monitoring platforms.
Market Dynamics
Home health monitoring infrastructure is compressing diagnostic device procurement cycles as parents demand real-time fever tracking integrated with pediatric telehealth platforms, forcing manufacturers to reconfigure hardware-software value capture models.
Growth Catalysts
- ISO 80601-2-56 compliance:International clinical thermometer standards create procurement clarity across European and Asian hospital systems, accelerating bulk purchasing decisions by pediatric networks.
- Thermopile sensor miniaturization:Advances in infrared detection arrays enable probe size reduction without accuracy degradation, expanding infant usability windows.
- China's pediatric home-care infrastructure:Municipal health bureaus in tier-1 cities subsidize connected diagnostic devices, creating concentrated demand pools for Bluetooth-enabled models.
Market Restraints
- Disposable lens filter cost volatility:Polypropylene supply concentration in Middle East petrochemical complexes creates input price instability for hygiene cap manufacturers.
- FDA 510(k) pathway friction:Pre-market notification timelines for Class II medical devices extend product launch windows by 12-18 months for US market entrants.
- Temporal artery thermometer substitution:Non-contact forehead scanning devices capture parent preference in sleep-disrupted nighttime usage scenarios.
Strategic Opportunities
- Remote patient monitoring integration:Bluetooth Low Energy protocols are converging with pediatric EHR systems, enabling automated fever alert workflows for family practitioners.
- Germany's digital health application (DiGA) pathway:Fast-track reimbursement approval for prescription digital therapeutics creates precedent for connected thermometer software modules.
- Pharmacy channel unbundling:Standalone probe and hygiene cap sales through European apotheke networks decouple recurring revenue from initial device purchases.
Industry Challenges
- Cybersecurity compliance complexity:FDA guidance on connected device data integrity requires firmware architecture redesigns for cloud-syncing thermometer models.
- Calibration technician scarcity:Infrared sensor drift correction demands specialized metrology expertise that contract manufacturers struggle to staff at volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Ear Thermometer Market |
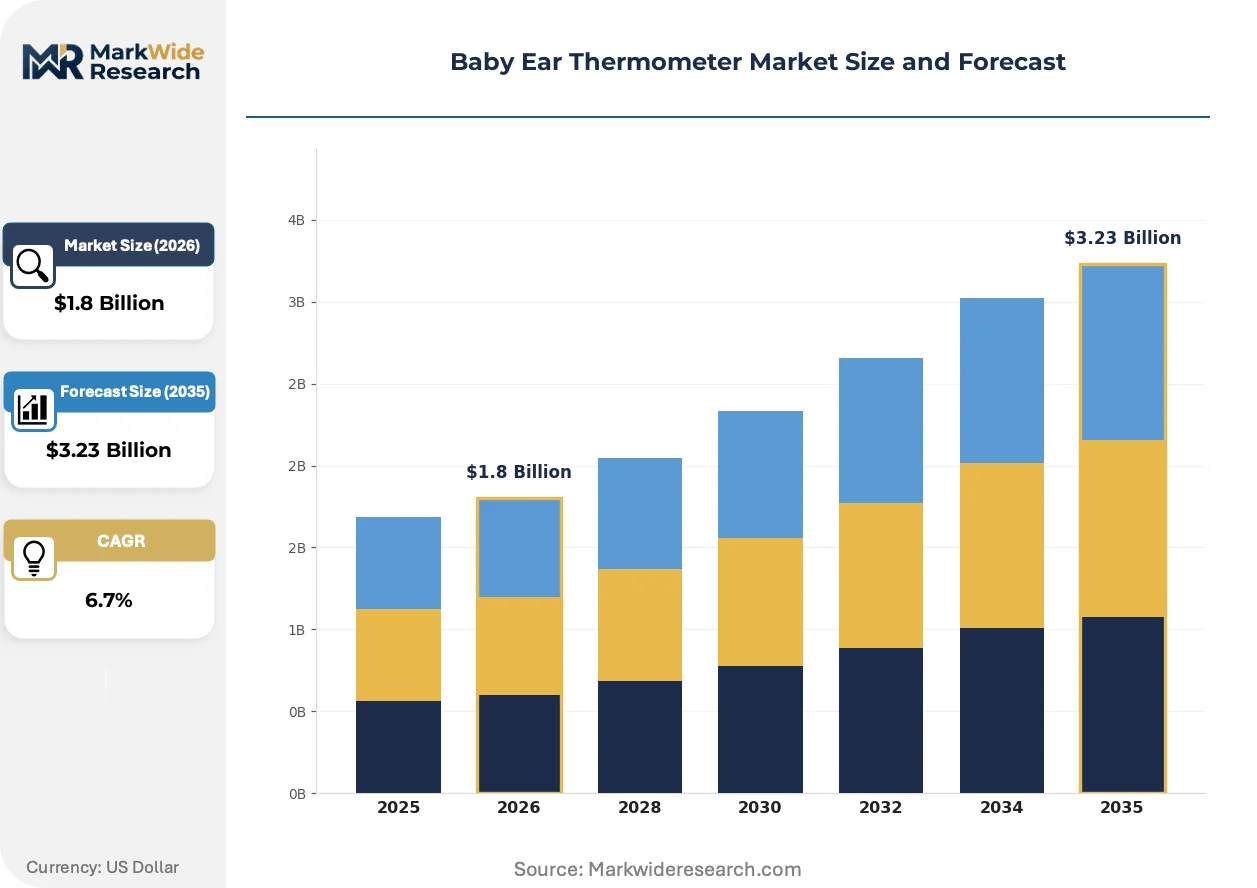
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Infrared, Analog, Smart Technology: Thermocouple, Thermistor, Infrared Sensor, Microchip End User: Parents, Pediatricians, Hospitals, Clinics Distribution Channel: Online Retail, Pharmacies, Supermarkets, Wholesale |
| Companies Covered | Omron Healthcare, Exergen Corporation, Kinsa, Braun, iProven, Vicks, iHealth, Goodbaby, Rossmax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Ear Thermometer Market Strategic Shifts
Diagnostic hardware is shedding its standalone identity as software layers capture disproportionate value, with sensor commoditization pushing manufacturers toward platform economics and recurring revenue architectures.
Multispectral infrared sensing is converging with machine learning classification algorithms to distinguish tympanic membrane signals from ear canal wall interference, reducing false readings in infant positioning scenarios. Pediatric urgent care networks in the United States are piloting these enhanced-accuracy probes for standardized intake protocols. This convergence is compressing the performance gap between clinical and consumer-grade devices, forcing premium positioning strategies to emphasize connectivity rather than raw sensor precision.
EU Medical Device Regulation (MDR) post-market surveillance requirements are mandating systematic vigilance reporting for Class IIa thermometers, compelling manufacturers to invest in European Authorized Representative infrastructure and clinical follow-up systems. German notified bodies are processing technical documentation reviews with extended timelines due to MDR transition backlogs. Smaller Asian exporters are responding by consolidating CE marking responsibilities through specialized regulatory consultancies rather than maintaining in-house compliance teams.
Subscription-based fever tracking services are displacing perpetual software licenses as the dominant monetization model for connected thermometer ecosystems, with parents paying monthly fees for pediatrician dashboard access and automated symptom logging. Direct-to-consumer channels in the United States are capturing this shift through app-store integrated billing systems that bypass traditional retail markup structures. This behavioral pivot concentrates lifetime value calculations in software cohort retention metrics rather than hardware replacement cycles.
Baby Ear Thermometer Market Segmentation
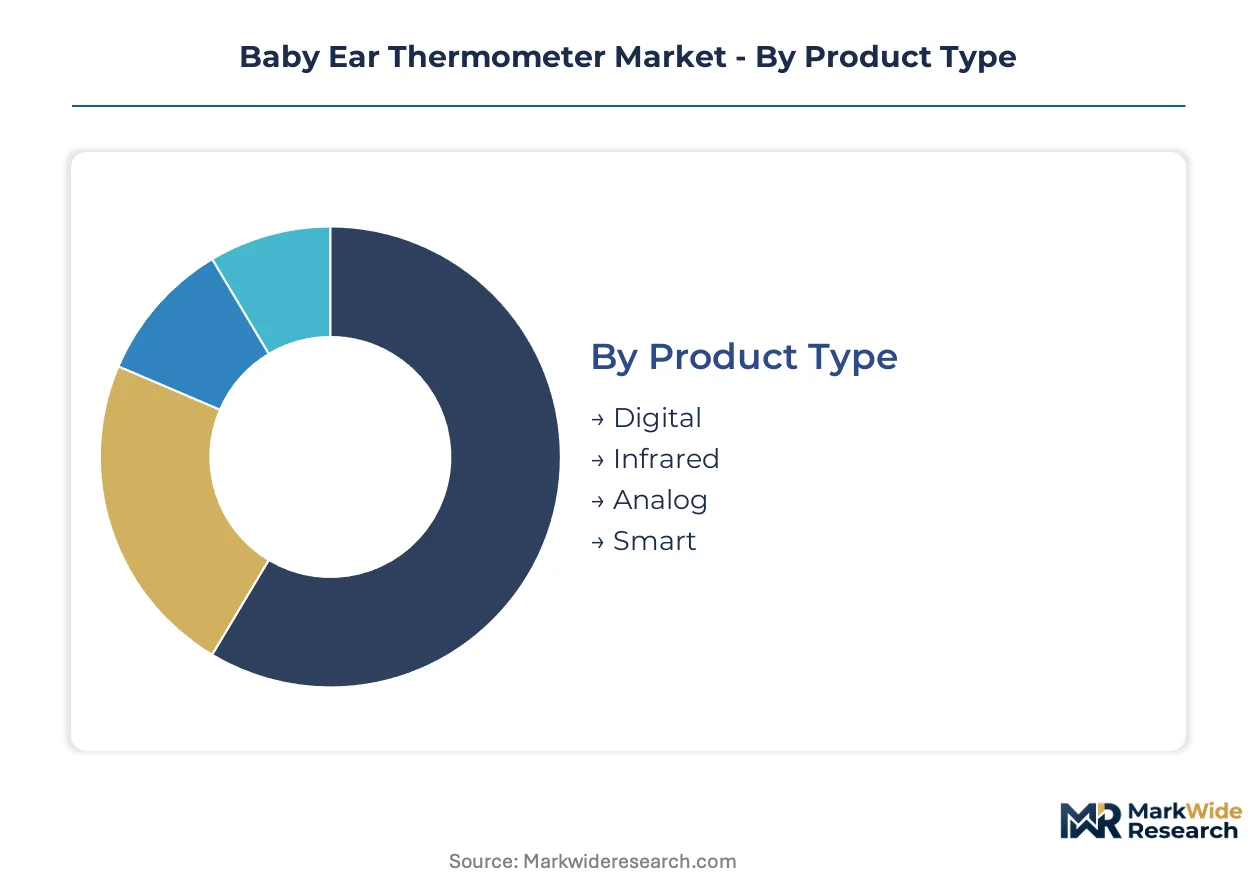
Segmentation in the baby ear thermometer market reveals how hardware specifications, user workflows, and procurement channels create distinct margin architectures. Manufacturers must align sensor technology choices with end-user technical sophistication and purchase context.
Product Type:
Volume concentration clusters in accessible price bands, while premium capture depends on connectivity and clinical validation tiers.
- Digital:Thermistor-based units with LCD displays dominate pharmacy and supermarket channels through price accessibility. Demand concentrates in Germany and the United States where parents prioritize immediate readability over connectivity. Disposable battery dependency creates recurring accessory purchases.
- Infrared:Thermopile sensor arrays enable one-second readings with disposable lens filter hygiene protocols. Pediatric networks in China bulk-procure these for standardized fever screening in municipal health stations. FDA 510(k) clearance requirements extend development timelines for US market variants.
- Analog:Mercury-free liquid crystal designs persist in price-sensitive wholesale segments across rural India and Southeast Asia. Minimal calibration requirements suit clinic deployments with limited technical infrastructure.
- Smart:Bluetooth-enabled models with app-synced fever tracking command premium positioning through software subscription potential. Kinsa and connected-device specialists target digitally engaged parent segments in tier-1 Chinese cities and US direct-to-consumer channels.
Mature deployment sits with Digital. Newer deployment is concentrated in Smart.
Technology:
Component selection determines accuracy certification tiers and regulatory pathway complexity.
- Thermocouple:Junction-based temperature measurement offers durability in high-frequency clinical use. Hospital procurement specifications in France and Italy favor these for ward-based infant monitoring stations.
- Thermistor:Ceramic semiconductor elements provide cost-optimized accuracy for consumer-grade digital models. Volume manufacturing concentrates in contract electronics facilities across Guangdong province.
- Infrared Sensor:Thermopile arrays detect tympanic membrane radiation with clinical-grade precision. ISO 80601-2-56 compliance requirements shape design investments for European market access. This segment is expanding most quickly as sensor miniaturization enables infant-optimized probe geometries.
- Microchip:Signal processing units integrate calibration algorithms and connectivity protocols. R&D intensity at Omron Healthcare and Braun centers on firmware architectures that reduce sensor drift over device lifetime.
Established production capacity clusters around Thermistor. Emerging specification demand flows toward Infrared Sensor.
End User:
Procurement authority and technical requirements fragment the customer base across retail and institutional channels.
- Parents:Home health monitoring adoption drives replacement cycles and accessory purchases. China's municipal subsidy programs for connected diagnostic devices accelerate Bluetooth-enabled model penetration in Beijing and Shanghai households.
- Pediatricians:Clinical validation requirements and bulk contracting create stable margin pools. German pediatric networks specify ISO-compliant devices with systematic calibration documentation.
- Hospitals:Infection control protocols mandate disposable lens filters and probe covers. Procurement departments prioritize total cost of ownership calculations over unit price.
- Clinics:Intermediate usage volumes favor mid-tier infrared models with simplified maintenance requirements. India's primary health centers under Ayushman Bharat infrastructure expansion represent emerging demand concentration.
Volume scale concentrates with Parents. Margin stability attaches to Pediatricians.
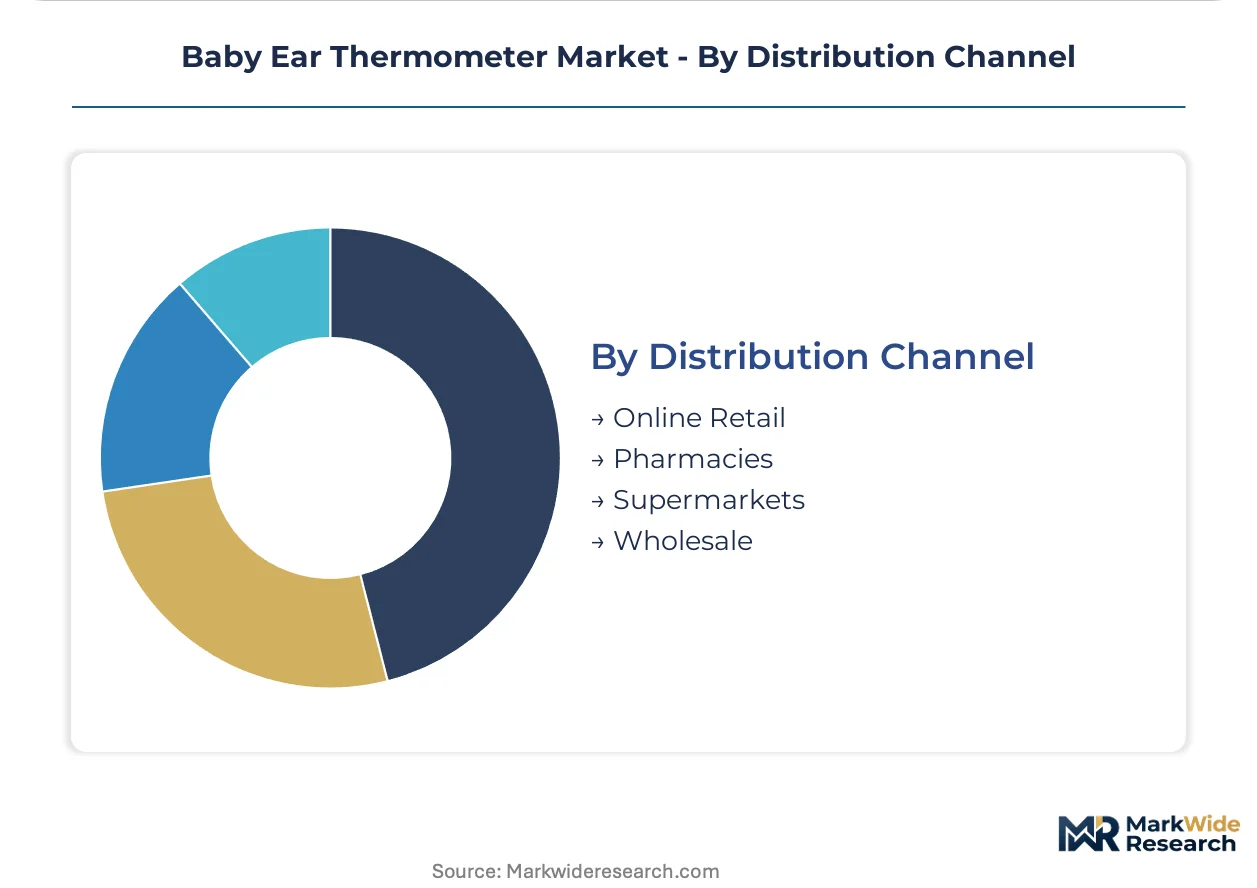
Distribution Channel:
Channel selection determines pricing architecture and customer education burden.
- Online Retail:Direct-to-consumer platforms enable subscription billing for connected thermometer software services. Amazon and Tmall capture parent segment research behavior through review aggregation and comparison tools.
- Pharmacies:European apotheke networks sustain premium positioning through pharmacist consultation and accessory unbundling. Braun leverages this channel for probe and hygiene cap standalone sales in Germany and France.
- Supermarkets:Mass retail placement drives impulse purchases and gift-giving occasions. Price compression limits feature differentiation to display readability and packaging design.
- Wholesale:Institutional procurement aggregators serve hospital and clinic networks with volume pricing and centralized calibration services. India's government medical supply corporations represent significant tender-based volume.
Traditional strength resides with Pharmacies. Channel expansion is accelerating fastest through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in China's Guangdong electronics clusters while consumption gravitates toward subsidized home-care programs in Beijing, Shanghai, and Shenzhen. The United States and Germany absorb premium-tier volumes through pharmacy networks and direct-to-consumer channels. Regulatory divergence across FDA, EU MDR, and NMPA jurisdictions fragments product development timelines.
United States
Pediatric telehealth platform adoption drives Bluetooth-enabled thermometer demand among digitally engaged parents. FDA 510(k) premarket notification requirements extend product launch windows by 12-18 months for Class II medical device entrants. Greater Boston hosts connected health startups integrating fever tracking data with pediatric electronic health records.
China
Municipal health bureaus in tier-1 cities subsidize connected diagnostic devices for household health monitoring infrastructure. NMPA medical device registration and GB standards compliance shape domestic market access requirements. Yangtze River Delta manufacturing clusters supply thermopile sensor arrays and probe assemblies to global OEMs.
Germany
Apotheke pharmacy networks sustain premium positioning through pharmacist consultation and accessory unbundling. EU Medical Device Regulation post-market surveillance requirements mandate systematic vigilance reporting for Class IIa thermometers. Bavaria's notified bodies process technical documentation reviews with extended timelines due to MDR transition backlogs.
India
Ayushman Bharat primary health center expansion generates tender-based procurement for mid-tier infrared models. CDSCO medical device registration requirements concentrate compliance investments among organized manufacturers. Gujarat contract electronics facilities produce thermistor-based units for price-sensitive wholesale segments.
Japan
Aging demographic shifts and pediatric home-care infrastructure investments sustain replacement demand cycles. PMDA quality management system requirements align with international ISO standards for clinical thermometer performance. Kanto region electronics manufacturers specialize in microchip signal processing units with integrated calibration algorithms.
Baby Ear Thermometer Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies into three strategic archetypes: multinational health technology conglomerates with broad diagnostic portfolios, connected-device specialists monetizing software subscriptions, and contract manufacturers serving private-label retail channels. Consolidation pressure operates through M&A activity targeting sensor technology assets and strategic partnerships linking hardware OEMs with pediatric telehealth platforms.
Within the multinational conglomerate tier, Omron Healthcare and Braun exemplify diversified health technology positioning spanning multiple diagnostic categories. Kinsa occupies a specialist position representing the connected-device archetype with software-integrated fever tracking ecosystems. These three anchors illustrate the competitive divergence between hardware-centric margin capture and platform economics built on recurring subscription revenue.
| Leading Market Players |
|---|
| Omron Healthcare |
| Exergen Corporation |
| Kinsa |
| Braun |
| iProven |
| Vicks |
| iHealth |
| Goodbaby |
| Rossmax |
| Others |
Value Chain & Pricing Dynamics
Polypropylene resin indices in Middle Eastern petrochemical complexes cascade through disposable lens filter manufacturing into three-tier pricing structures across premium, standard, and economy levels. This input cost volatility compresses margins for hygiene cap suppliers while forcing OEMs to rebalance hardware-software value capture toward subscription revenue.
Pricing Analysis
Cost-down pressure on standard-tier infrared units accelerates because thermopile sensor commoditization erodes hardware differentiation. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) certification grade and Bluetooth connectivity bundling. Parent buyers in mass retail channels exhibit acute price sensitivity, while pediatric networks prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Thermopile sensor arrays draw from Japanese micro-electromechanical systems foundries, Guangdong province contract assembly facilities, and German precision optics workshops. Critical dependencies include polypropylene hygiene caps, lithium coin cell batteries, and medical-grade ABS housings. Single-source vulnerability concentrates in Japanese signal processing chip supply, with distribution running through European apotheke networks and Asian direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized metrology technician scarcity props pricing for calibration-validated devices, creating durable margin pools for manufacturers with in-house technical service infrastructure.
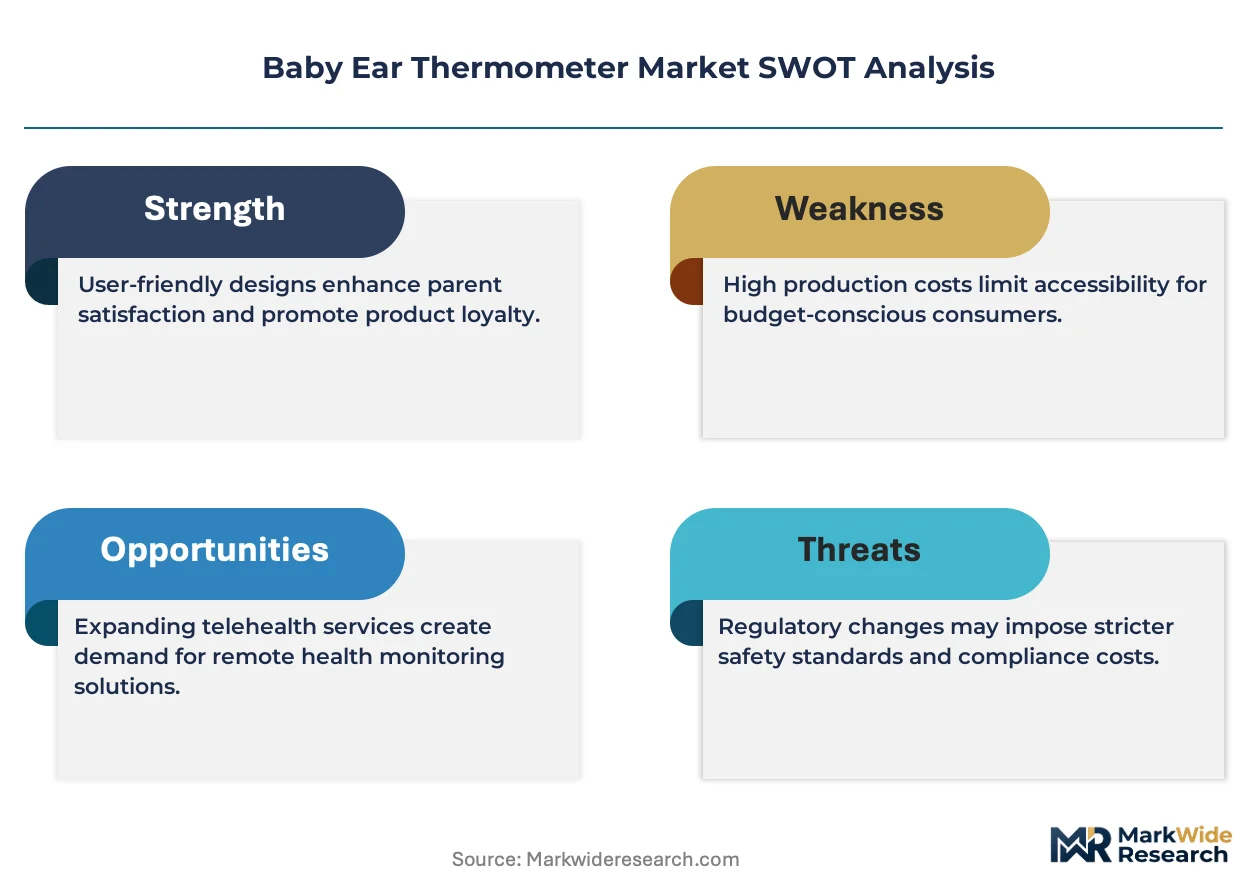
For Market Incumbents: Lock in sensor technology partnerships with Yangtze River Delta MEMS foundries to defend against temporal artery thermometer substitution. Prioritize firmware architecture investments that satisfy FDA cybersecurity guidance for connected devices, converting compliance burden into competitive moat against unvalidated entrants. For New Entrants and Emerging Players: Direct-to-consumer platforms offer the most penetrable channel for software-subscription monetization, particularly among digitally engaged parent segments in tier-1 Chinese cities. Target municipal health bureau subsidy programs with stripped-down Bluetooth-enabled hardware bundled with fever-tracking app services. For Investors and Strategic Acquirers: The window for entry favors connected-device specialists with proven pediatric telehealth platform integrations. Watch NMPA registration timeline compression as the inflection signal for Chinese market access arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Regulatory clearance enables US pharmacy channel placement and pediatric network procurement. |
| CE Marking Under EU MDR | Notified body certification unlocks German apotheke distribution and hospital system tenders. |
| Hospital System Partnership | Bulk contracting with pediatric networks stabilizes margin pools through calibration service attachments. |
| Software Companion Development | Bluetooth-enabled fever tracking apps convert hardware sales into recurring subscription revenue. |
| Reimbursement Strategy | Germany's DiGA pathway precedent creates potential for prescription digital therapeutic status. |
Study Parameters
FDA 510(k) premarket notification databases, EU MDR vigilance reporting systems, and NMPA medical device registration records formed the secondary backbone, cross-referenced with primary interviews involving pediatric procurement managers, biomedical engineers at children's hospitals, GPO contracts specialists, and regulatory affairs leads at infrared sensor manufacturers. Bottom-up unit shipment estimates triangulated against top-down value projections.
Historical trendline analysis across sensor technology cost curves and connected health adoption patterns informed the projection framework. Segmentation modeling incorporated product type, end-user procurement authority, distribution channel economics, and regional regulatory cluster variations. CAGRs derived from fitted growth curves adjusted for ISO standard implementation timelines and municipal subsidy program rollouts.
Caveats apply where FDA cybersecurity guidance evolution or EU MDR notified body capacity constraints could materially shift the outlook. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bioimpedance Analyzers Market
Medical Devices
Electrocardiograph (ECG) Market
Medical Devices
Australia Clear Aligner Market
Medical Devices
Russia Viscosupplementation Market
Medical Devices
Active Wheelchair Market
Medical Devices
Laparoscopic Devices Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Ventilation Devices Market
Medical Devices
Transcranial Magnetic Stimulator for Depression Requisition Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Soft Tissue Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
Non-Destructive Medical Technologies Market