
 Middle East and Africa Frozen Bread Market | 2026-2036
Middle East and Africa Frozen Bread Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Frozen Bread Market Foresight
Hypermarket and supermarket distribution across the Gulf Cooperation Council is fragmenting as local convenience store networks and quick-commerce platforms capture weekly bread purchasing. Almarai Company leverages its integrated dairy and bakery supply chain to dominate Saudi retail freezer space. Aryzta AG sustains production scale through centralized baking facilities serving foodservice accounts across the UAE and Qatar. Sunbulah Group anchors its position in Levant markets through long-standing relationships with hotel and catering operators.
Frozen bread comprises par-baked or fully baked loaves, rolls, and flatbreads quick-frozen at minus eighteen degrees Celsius to arrest staling and preserve crust texture for later finishing or direct sale. The category serves retail consumers seeking extended shelf life and foodservice operators requiring portion-controlled, consistent output without on-site fermentation labor. White bread and whole wheat bread together occupy the volume core, though gluten-free bread captures expanding margin pools as health-conscious households and hospitality menus diversify. Food services and restaurants represent the fastest-growing end user channel, driven by chain expansion and central kitchen models that demand reliable thaw-and-serve solutions.
Saudi Food and Drug Authority standards and UAE Ministry of Industry and Advanced Technology labeling requirements govern additive limits, nutritional declarations, and cold chain integrity documentation for frozen bakery imports and domestic production. Gulf Standardization Organization harmonization efforts reduce cross-border compliance friction for manufacturers operating across multiple member states. Egypt's food safety regulator enforces periodic facility inspections and ingredient traceability protocols that shape supplier qualification criteria. Stakeholders must monitor evolving halal certification requirements and energy subsidy reforms affecting cold storage economics as they evaluate capacity placement and partnership structures.
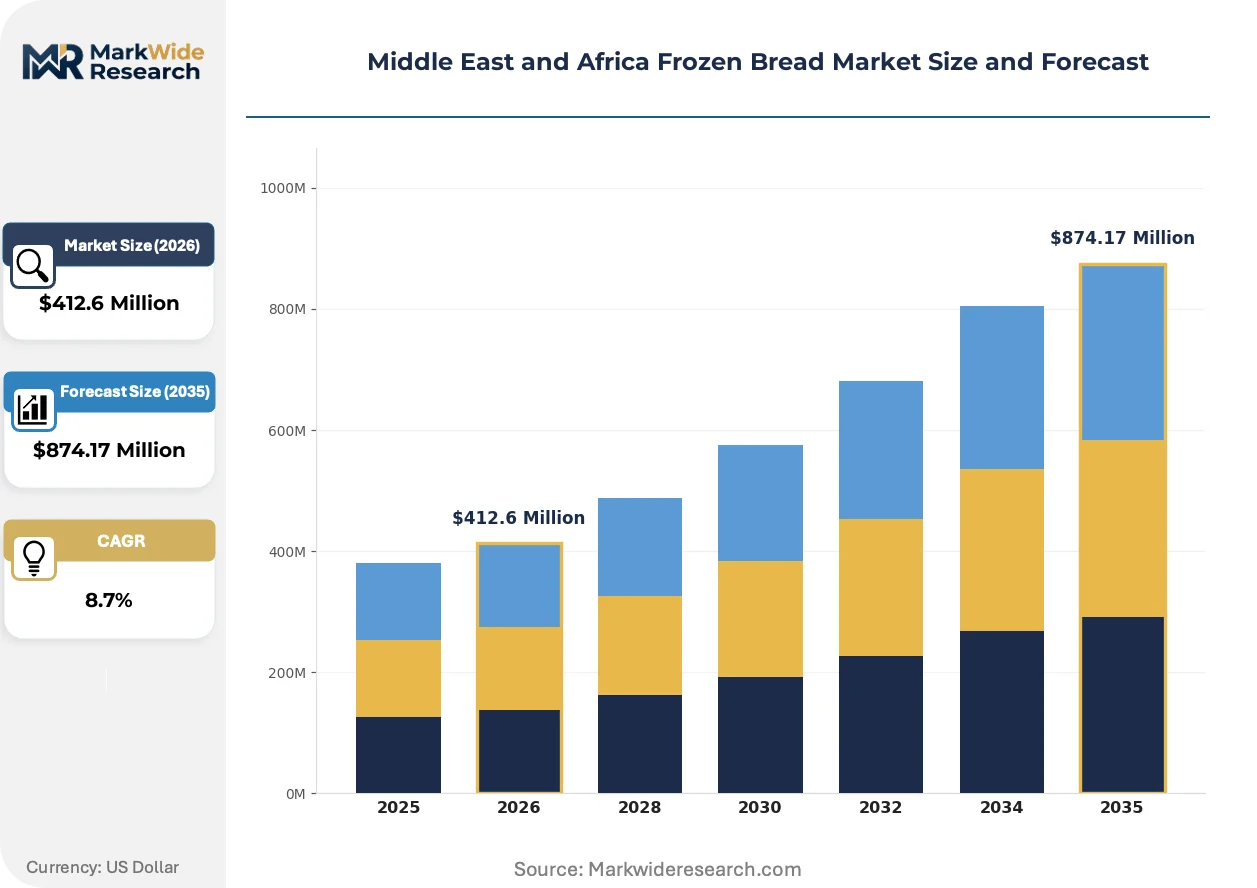
Market Dynamics
Quick-service restaurant chains across Saudi Arabia and the UAE are consolidating procurement under central kitchen models, compressing supplier relationships and rewarding scale baking operations that can guarantee par-baked consistency across dozens of franchise locations.
Growth Catalysts
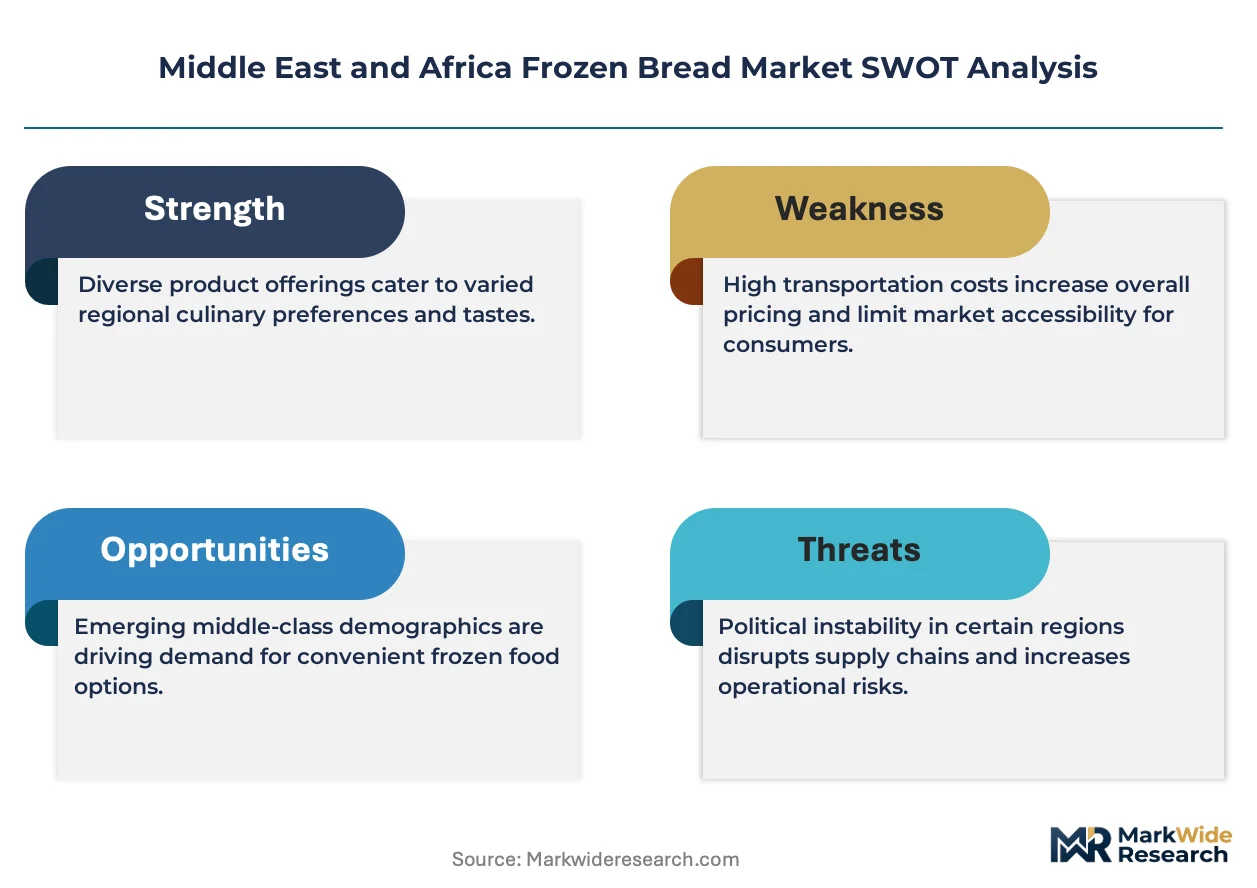
- SFDA cold chain documentation mandates:Saudi Food and Drug Authority requirements for temperature logging during transport and storage are professionalizing logistics networks and disqualifying informal suppliers, creating shelf space for compliant frozen bread brands.
- Hotel chain breakfast standardization:International hospitality groups operating across Dubai and Cairo are mandating identical bread specifications property-wide, driving procurement toward frozen par-baked products that eliminate fermentation variability.
- Blast freezing at minus eighteen degrees Celsius:This core process technology arrests staling enzymes and preserves crust texture, enabling Egyptian bakery suppliers to serve distant Red Sea resort markets without quality degradation.
Market Restraints
- Natural gas price volatility:Egyptian and Saudi baking facilities rely heavily on subsidized natural gas for oven operations; energy subsidy reforms in both countries are compressing margin structures for energy-intensive frozen bread production.
- Import dependency for specialty wheat:Black Sea and North American wheat supplies dominate high-protein varieties required for consistent frozen dough performance, exposing margins to currency fluctuation and shipping cost spikes.
- Halal certification fragmentation:Divergent standards between Gulf Standardization Organization member states and Egypt's Dar al-Ifta create redundant audit costs and shipment delays for cross-border suppliers.
Strategic Opportunities
- Quick-commerce platform penetration:InstaShop and Talabat Mart in Dubai and Riyadh are building dedicated frozen food dark stores, creating direct-to-consumer channels that bypass traditional retail freezer slotting fees.
- Whole wheat and multigrain line extensions:Health-conscious households in Cairo's Zamalek and Riyadh's Diplomatic Quarter are paying premiums for fiber-enriched frozen breads, expanding margin pools beyond commodity white bread.
- Gulf Standardization Organization harmonization:Pending unified labeling and additive standards across GCC member states would eliminate country-specific packaging runs and accelerate pan-Gulf distribution scale.
Industry Challenges
- Artisan baker skill scarcity:Central kitchen and commissary operations struggle to recruit technicians capable of managing par-baked finishing protocols, forcing reliance on equipment automation that raises capital requirements.
- Cold storage capex intensity:Establishing minus eighteen degrees Celsius distribution hubs in Nigeria and Kenya's emerging urban corridors demands refrigeration infrastructure investment that exceeds local bakery balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Frozen Bread Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Bread, Whole Wheat Bread, Multigrain Bread, Gluten-Free Bread End User: Households, Restaurants, Cafes, Food Services Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Local Markets Pack Size: 500g, 1kg, 2kg, Bulk Packaging |
| Companies Covered | Almarai Company, Aryzta AG, Sunbulah Group, Agthia Group, Rich Products Corporation, Lantmännen Unibake, Vandemoortele, Goosebumps, Wonder Bakery LLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Frozen Bread Market Shifts & Advancements
Digital traceability systems and automated finishing equipment are compressing the gap between frozen distribution and fresh-baked perception, while regulatory pressure on sodium and additive content is reformulating legacy recipes.
Blast freezing combined with modified atmosphere packaging is virtualizing the traditional bakery supply chain by displacing daily delivery routes with weekly frozen shipments. Quick-service restaurant chains across Jeddah and Abu Dhabi are adopting these systems fastest, consolidating dozens of daily bread supplier relationships into single frozen contracts that compress procurement overhead and enable kitchen labor reduction.
Gulf Standardization Organization harmonization efforts on nutritional labeling and additive limits are forcing reformulation across Saudi and UAE production facilities. Industrial bakers must now reconcile divergent national standards into unified product specifications, with whole wheat and gluten-free lines facing the most complex compliance timelines as they navigate multiple certification pathways simultaneously.
Foodservice buyers are consolidating weekly bread purchasing through integrated procurement platforms that aggregate frozen bakery with protein and produce categories. Hotel and catering operators in Cairo and Riyadh are abandoning direct supplier relationships in favor of these bundled purchasing systems, which demand volume commitments and standardized SKU ranges that favor large-scale frozen bread manufacturers over artisan alternatives.
Middle East and Africa Frozen Bread Market Segmentation
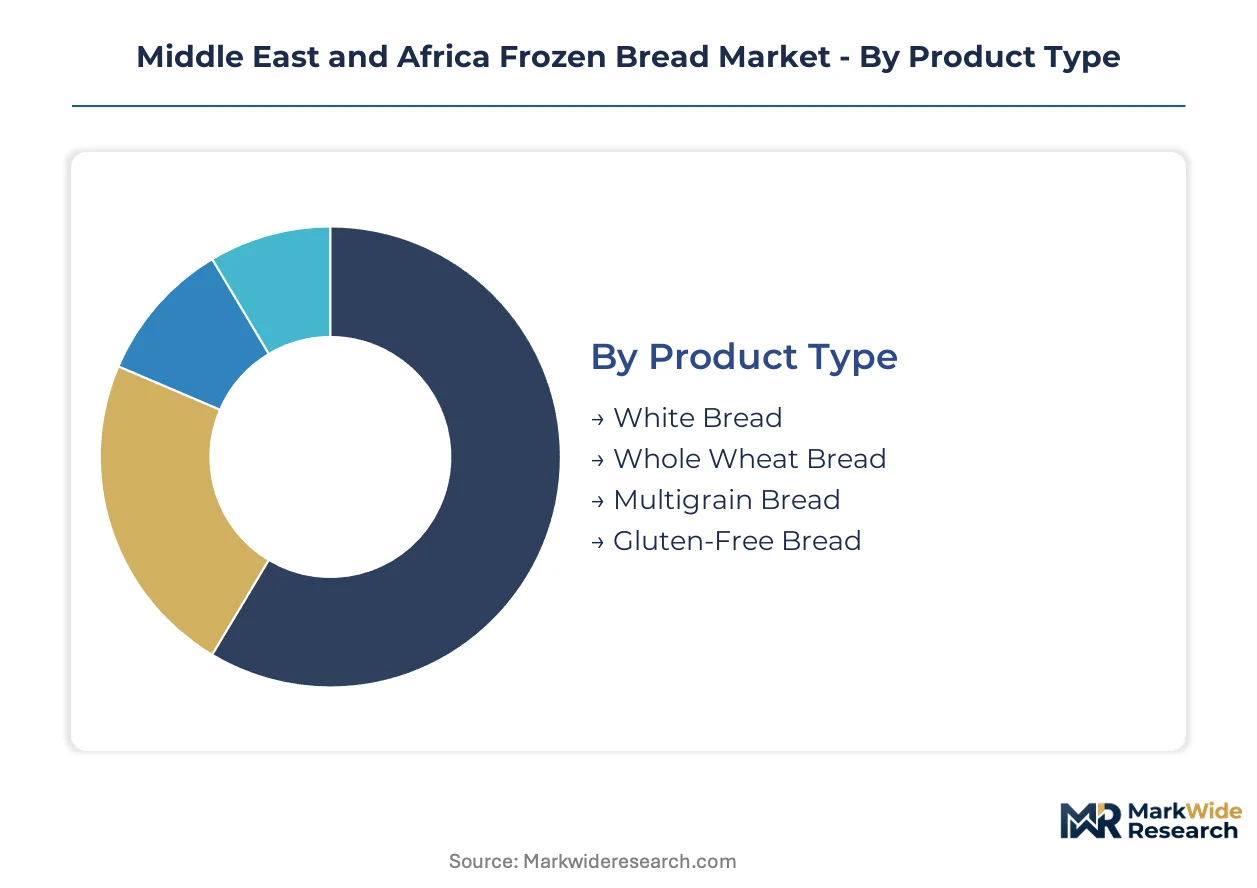
Frozen bread segmentation across the Middle East and Africa reflects divergent consumption contexts, from Egyptian household bulk purchasing to UAE foodservice portion control. Understanding these category boundaries clarifies where manufacturers must configure distinct product specifications, packaging formats, and distribution investments.
Product Type:
The use-case spectrum spans commodity daily consumption through specialized dietary accommodation, with functional attributes determining channel placement and margin capture.
- White Bread:Standard refined-flour loaves with soft crumb structure and extended freezer stability serve mass-market retail and QSR bun applications across Saudi Arabia and Egypt. Cairo's informal bakery sector and Riyadh's hypermarket freezer aisles both move substantial volumes, though health-conscious positioning is eroding share in premium urban districts.
- Whole Wheat Bread:Higher-fiber formulations using partially refined flour appeal to wellness-focused households in Dubai's Marina district and Nairobi's emerging middle-class suburbs. Egyptian millers are expanding whole wheat sourcing as SFDA nutritional labeling requirements expose actual fiber content versus marketing claims.
- Multigrain Bread:Seed and grain inclusions add texture complexity and price premiums for hospitality breakfast service in Abu Dhabi and Amman hotel properties.
- Gluten-Free Bread:Rice and tapioca-based formulations address celiac and lifestyle dietary restrictions, commanding shelf space in UAE pharmacy retail chains and South African specialty grocers.
The dominant share belongs to White Bread, while Gluten-Free Bread is closing the gap fastest.
End User:
Cost tier differentiation separates price-sensitive household stockpiling from operational efficiency investments by commercial operators.
- Households:Family-scale purchasers prioritize freezer longevity and thaw convenience, with Egyptian and Nigerian urban households buying 1-2kg packs for weekly consumption cycles.
- Restaurants:Chain operators across Jeddah and Dubai specify par-baked rolls and flatbreads that finish in under four minutes, compressing table-turn times and reducing kitchen labor.
- Cafes:Independent coffee shops in Cairo's Zamalek and Johannesburg's Rosebank favor artisan-positioned frozen sourdough and ciabatta for premium sandwich applications.
- Food Services:Institutional caterers, airline commissaries, and hospital feeding operations demand pallet-scale consistency with documented halal certification and batch traceability.
Food Services commands the largest procurement volumes, with Restaurants expanding most quickly as central kitchen models proliferate.
Distribution Channel:
Geography determines channel viability, with cold chain maturity dictating which formats can sustain minus eighteen degree integrity to point of sale.
- Supermarkets:Carrefour, Lulu, and Spinneys outlets across the GCC dedicate substantial freezer real estate to bread, using promotional pricing to drive traffic.
- Online Retailers:Talabat Mart and Noon Food are building dedicated frozen dark stores in Riyadh and Dubai, enabling sub-30-minute delivery without retail slotting fees.
- Convenience Stores:Circle K and local equivalents in Saudi Arabia's highway corridors stock limited SKUs for immediate consumption and travel provisioning.
- Local Markets:Traditional souks and open-air bazaars in Cairo, Lagos, and Karachi move frozen bread through independent cold storage intermediaries with variable temperature control.
Supermarkets retain the widest SKU access, though Online Retailers are gaining transaction frequency fastest among urban professionals.
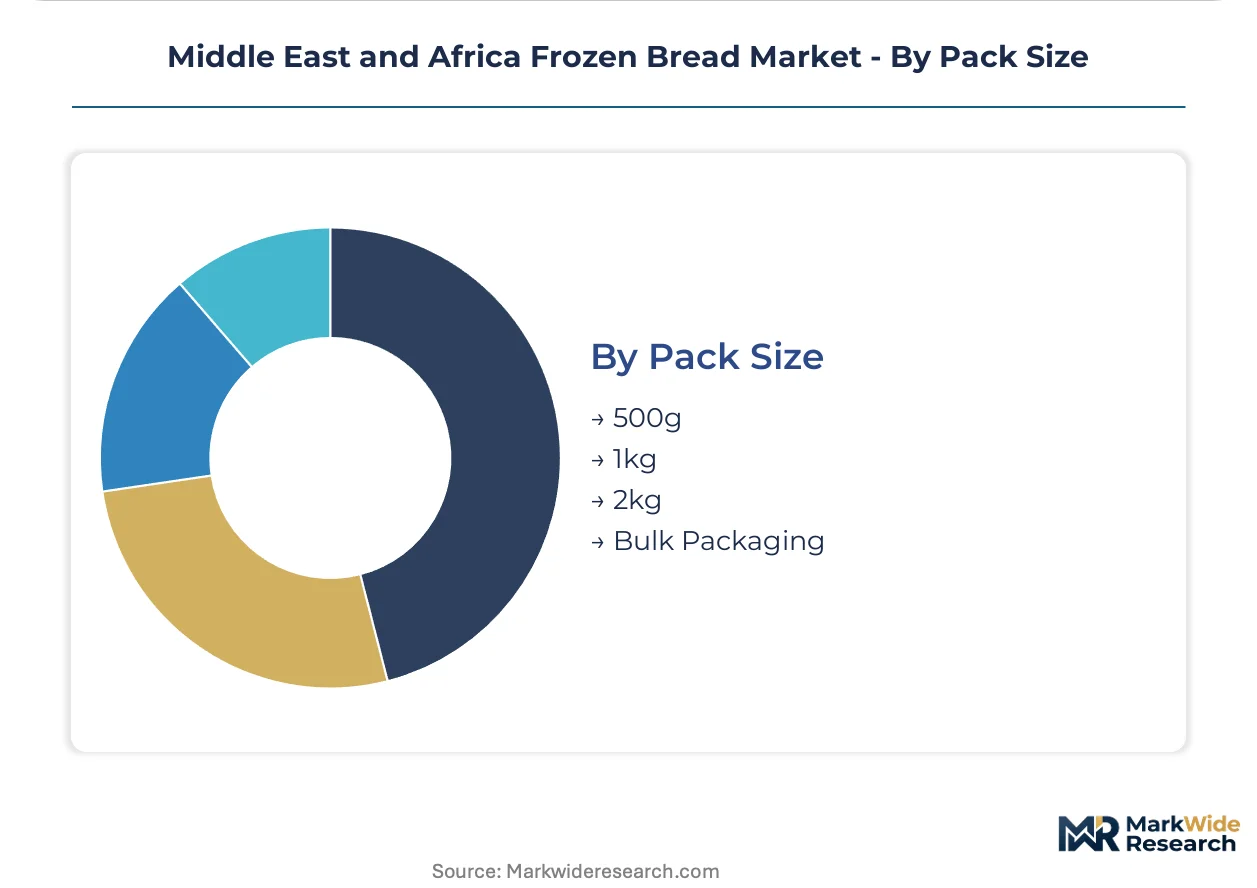
Pack Size:
Customer type and consumption velocity determine optimal pack configuration, with bulk formats rewarding supply chain efficiency and small packs capturing trial and convenience.
- 500g:Single or small-family units suit trial purchases and premium positioning in UAE convenience retail.
- 1kg:Standard household format balances freezer space economy with consumption freshness across Saudi and Egyptian retail.
- 2kg:Value-oriented families and small foodservice accounts in Nigeria and Kenya favor this intermediate bulk tier.
- Bulk Packaging:5kg and larger foodservice totes with inner poly-lining serve hotel chains, airline caterers, and central kitchen operations across the GCC.
The dominant share belongs to 1kg formats, while Bulk Packaging is climbing the fastest as foodservice centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jeddah Islamic Port's expanded cold chain terminals anchor Saudi Arabia's frozen bread distribution reach across Red Sea corridors. This maritime infrastructure underwrites the kingdom's procurement consolidation for quick-service restaurant chains.
Saudi Arabia
Central kitchen models at Al Baik and Herfy drive par-baked roll procurement at scale across Riyadh and Jeddah. SFDA cold chain documentation mandates now require temperature logging from production through retail freezer placement. The Eastern Province's Jubail industrial zone hosts expanding blast freezing capacity serving franchise networks.
United Arab Emirates
Dubai's hotel chain breakfast standardization programs demand identical bread specifications across Marriott and Hilton properties citywide. MOHAP labeling requirements govern additive limits and nutritional declarations for frozen bakery imports through Jebel Ali. Abu Dhabi's Khalifa Industrial Zone concentrates commissary operations feeding airline catering and hospital networks.
Egypt
Cairo's urban foodservice corridors serve dense populations of institutional buyers from Zamalek to Nasr City. The country's food safety regulator enforces periodic facility inspections and ingredient traceability protocols shaping supplier qualification. Alexandria's port infrastructure enables Red Sea resort market access for frozen flatbread producers.
South Africa
Johannesburg's Rosebank and Sandton precincts generate premium frozen sourdough demand from independent cafe operators. National halal certification harmonization efforts reduce cross-border compliance friction for suppliers entering neighboring SADC markets. Cape Town's Atlantic seaboard hotel cluster drives consistent par-baked procurement for hospitality breakfast service.
Nigeria
Lagos's emerging quick-commerce platforms build dedicated frozen food dark stores bypassing traditional retail slotting fees. Energy subsidy reforms compress margin structures for natural gas-dependent baking facilities in Ikeja industrial zones. Kano's northern corridor distribution hubs face cold storage capex intensity exceeding local bakery balance sheet capacity.
Middle East and Africa Frozen Bread Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient and equipment supply. The vendor base concentrates around three archetypes: integrated dairy-bakery conglomerates with captive distribution, centralized production specialists serving multi-country foodservice accounts, and Levant-rooted operators with long-standing hospitality relationships. Competitive moves center on backward integration into wheat sourcing and quick-commerce platform partnerships that disintermediate traditional retail freezer slotting.
Within the integrated conglomerate tier, Almarai Company anchors Saudi retail freezer space through its dairy-bakery supply chain integration. Aryzta AG occupies a position exemplifying centralized production scale serving UAE and Qatar foodservice accounts from consolidated baking facilities. Sunbulah Group represents the hospitality-relationship archetype, with its Levant market position built on enduring hotel and catering operator ties. These three entities collectively illustrate how geographic origin and structural configuration shape competitive positioning across the region's frozen bread procurement corridors.
| Leading Market Players |
|---|
| Almarai Company |
| Aryzta AG |
| Sunbulah Group |
| Agthia Group |
| Rich Products Corporation |
| Lantmännen Unibake |
| Vandemoortele |
| Goosebumps |
| Wonder Bakery LLC |
| Others |
Supply & Pricing Matrix
Blast freezing capacity underutilization across Egypt's Red Sea industrial zones is compressing contract baking margins and forcing suppliers toward volume-commitment pricing to cover fixed refrigeration infrastructure costs.
Pricing Analysis
Volume-discount tiering separates foodservice pallet contracts from retail unit pricing across Saudi and UAE procurement corridors. Three-tier pricing structure across premium, standard, and economy levels reflects halal certification grade and blast freezing protocol adherence. Cost compression in commodity white bread is intensifying because Egyptian energy subsidy reforms are lifting natural gas input costs. Quick-service restaurant chains demonstrate lowest price sensitivity due to central kitchen consolidation, while Nigerian urban households exhibit highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration rests with centralized baking facilities in Saudi Arabia's Jubail industrial zone, UAE's Khalifa Industrial Zone, and Egypt's Alexandria corridor. High-protein wheat sourcing draws from Black Sea and North American suppliers, while modified atmosphere packaging materials hinge on petrochemical feedstock availability. Single-source vulnerability runs through Ukrainian wheat corridor disruptions. Distribution runs through Jeddah Islamic Port cold terminals feeding GCC retail networks and Red Sea resort markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: SFDA cold chain documentation mandates and GSO harmonization protocols create compliance barriers that informal suppliers cannot scale.
For Market Incumbents: Insulate market position through backward integration into captive wheat milling operations in Saudi Arabia's Eastern Province and certification dual-tracking across SFDA and GSO audit pathways. Emerging quick-commerce platforms threaten traditional retail freezer slotting dominance. Cold storage capacity addition in Nigeria's Lagos corridor addresses supply gap exposure. For New Entrants and Emerging Players: Establish a beachhead in gluten-free bread formulations for UAE pharmacy retail chains and South African specialty grocers where incumbent presence remains thin. Quick-commerce dark store partnerships in Dubai and Riyadh offer the most penetrable channel. Direct-to-hotel procurement bypassing consolidated foodservice platforms provides viable go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across blast freezing infrastructure as minus eighteen degree Celsius compliance becomes non-negotiable. Long-term viability favors vertically integrated dairy-bakery conglomerates with captive distribution networks. Acquisition target archetype: Levant-rooted operators with enduring hospitality relationships and underutilized freezing capacity. Quarterly review of GSO harmonization implementation timelines and Egyptian energy subsidy reform schedules is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Blast Freezing Capacity Expansion | Jubail and Khalifa Industrial Zone investments anchor GCC supply security for franchise network procurement. |
| Quick-Commerce Platform Partnership | Talabat Mart and InstaShop dark store integration disintermediates traditional retail freezer slotting fees. |
| Halal Certification Dual-Tracking | Parallel SFDA and GSO audit pathways reduce cross-border shipment delays for multi-country suppliers. |
| Whole Wheat Line Extension | Fiber-enriched formulations capture premium positioning in Riyadh's Diplomatic Quarter and Cairo's Zamalek districts. |
| Wheat Sourcing Backward Integration | Captive milling operations in Saudi Arabia's Eastern Province buffer Black Sea supply volatility exposure. |
Research Methodology
The analysis maps frozen bread sub-sectors spanning par-baked loaves, fully baked rolls, and flatbread formats, each validated through plant managers at centralized baking facilities, procurement leads at quick-service restaurant chains, cold storage logistics operators, and hospitality foodservice directors. Primary interview intelligence combined with secondary validation from SFDA regulatory filings, GSO harmonization protocols, customs and trade data, and Gulf hypermarket retail audit records. Bottom-up production capacity assessment and top-down consumption demand modeling provided triangulation anchors.
Assumption sets held cold chain infrastructure investment schedules and energy subsidy reform trajectories fixed across baseline scenarios while varying wheat price volatility bands and quick-commerce penetration rates in sensitivity analysis. Segmentation dimensions modeled include product type, end-user channel, distribution format, and regional cold chain maturity tier. CAGRs were derived from production volume trajectories mapped against consumption demand curves, with blast freezing capacity utilization and halal certification compliance timelines serving as industry-specific forecast inputs.
Stress conditions across natural gas price spikes, Black Sea wheat corridor disruptions, and GSO harmonization delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding central kitchen adoption rates and quick-commerce platform buildout schedules. Quarterly review of SFDA enforcement intensity and Egyptian energy subsidy reform implementation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
North America Freeze Dried Products Market
Processed and Frozen Foods
Frozen Soup Market
Processed and Frozen Foods
Frozen Tortilla Market
Processed and Frozen Foods
Chocolate Ice Cream Market
Processed and Frozen Foods
Turkey Cold Storage Market
Processed and Frozen Foods
Chilled Soup Market
Processed and Frozen Foods
Asia Pacific Frozen Desserts Market
Processed and Frozen Foods
Frozen Meat and Fish Market
Processed and Frozen Foods
North America Frozen Pizza Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Refrigerated & Frozen Soup Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
United States Frozen Yogurt Market
Processed and Frozen Foods
Frozen Sardine Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
North America Frozen Food Market