
 Bread Slicer Market | 2026-2036
Bread Slicer Market Size, Share, and Industry Trends Forecast 2026-2036
Bread Slicer Market Analytics
Commercial bakeries is pivoting toward high-throughput slicing lines as in-store bakery counters expand across European retail chains. Empire Bakery Equipment leverages its North American manufacturing footprint to anchor supply contracts with regional bread cooperatives. Ferneto competes through blade-technology specialization for crusty artisan loaves. Oliver Packaging & Equipment Company sustains channel control via direct-service networks in mature bakery equipment markets.
A bread slicer mechanically portions loaves through reciprocating or rotary blade arrays, typically achieving slice thickness precision within millimeters for uniform retail presentation. Stainless steel construction and NSF-certified food contact surfaces define commercial-grade specifications, with automated models integrating conveyor feeds and safety interlocks for continuous production environments. Automatic slicers lead product-type demand as labor costs pressure manual operations, while integrated systems capture margin pools through line-efficiency guarantees. Blade technology dominates the technology dimension, though laser cutting attracts niche interest for delicate crumb structures in premium applications.
The EU Machinery Directive and CE marking govern equipment safety and electromagnetic compliance across European installations, while FDA food contact surface regulations shape material specifications for slicers deployed in US commercial kitchens. BIS certification requirements in India add compliance layers for exporters targeting institutional bakery modernization programs. Stakeholders must monitor how evolving hygiene standards and energy-efficiency mandates redistribute competitive advantage between European and Asian manufacturing bases.
Market Dynamics
Automated slicing lines are compressing manual operations across commercial bakeries, while CE marking and FDA food contact surface regulations are redrawing equipment qualification requirements and procurement criteria.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements are forcing equipment upgrades across European commercial bakeries, accelerating replacement cycles for legacy slicers.
- Artisan bread retail expansion:In-store bakery counters in German and French retail chains are scaling high-throughput slicing operations for crusty specialty loaves.
- Blade-technology advancement:Reciprocating blade arrays with millimeter-precision thickness control are enabling uniform retail presentation standards.
Market Restraints
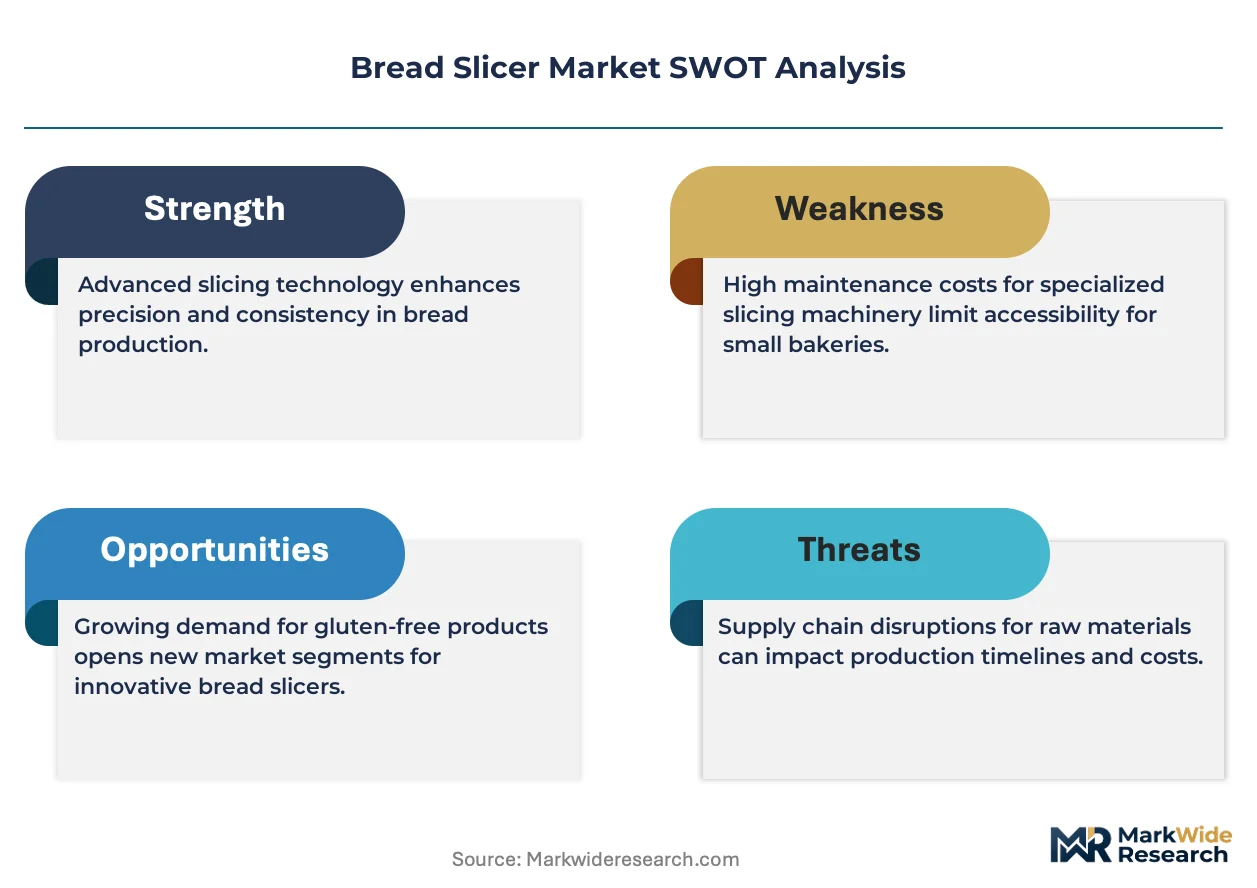
- Stainless steel input cost volatility:Nickel and chromium price fluctuations are compressing margins for NSF-certified food contact surface construction.
- Supply concentration in German industrial clusters:Munich and Stuttgart anchor premium slicer procurement, creating geographic dependency for specialized component sourcing.
- Manual slicing substitution persistence:Small-scale artisan bakeries continue deploying hand-operated equipment for low-volume specialty production.
Strategic Opportunities
- Indian institutional bakery modernization:BIS certification requirements are creating compliance-driven upgrade demand for automated slicer installations.
- Laser cutting technology convergence:Integration of laser systems with traditional blade arrays is opening premium applications for delicate crumb structures.
- Direct-service network expansion:Channel control through captive technician deployment is capturing margin pools in mature bakery equipment markets.
Industry Challenges
- NSF certification timeline compression:Third-party validation for food contact surfaces is extending equipment qualification periods and delaying revenue recognition.
- Legacy conveyor integration complexity:Retrofitting automated slicers into existing production lines requires custom engineering for safety interlock compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bread Slicer Market |
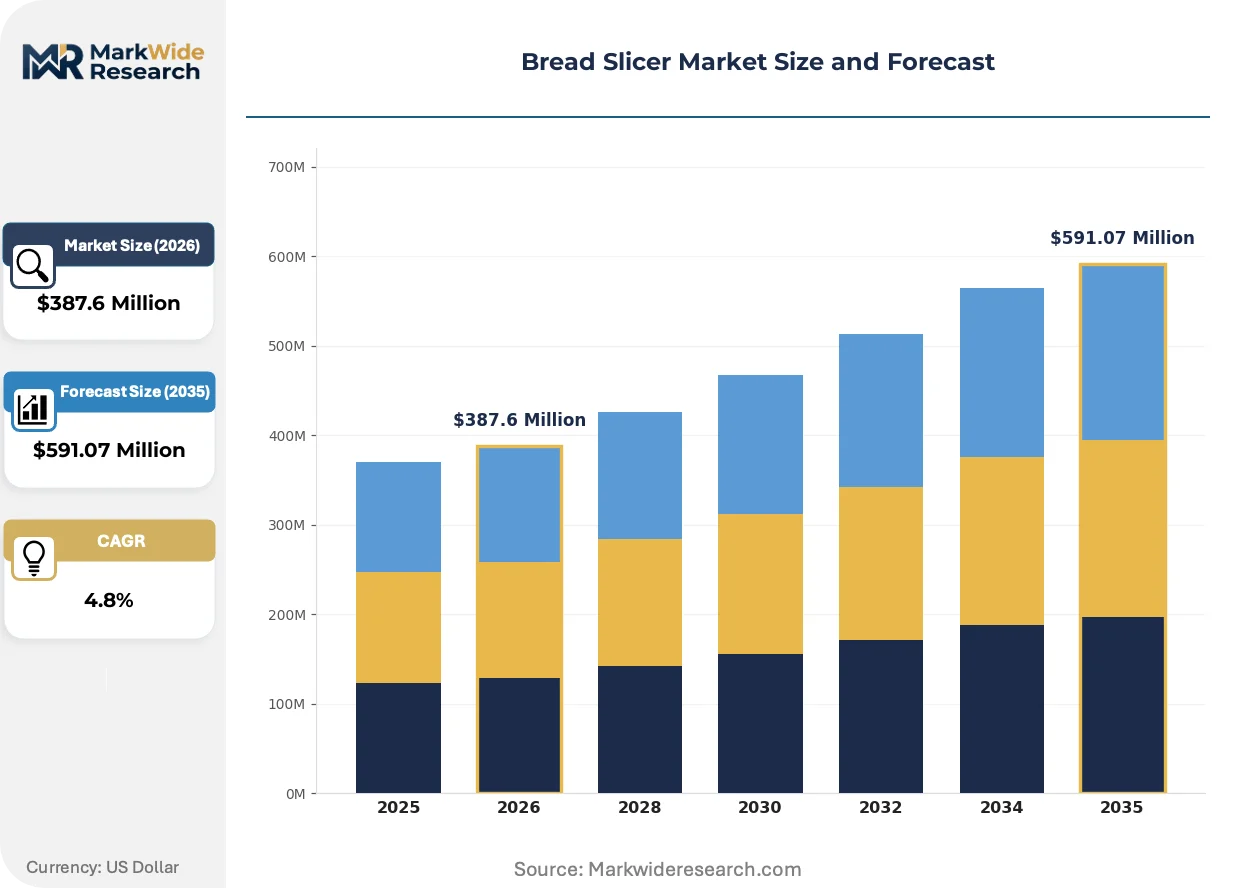
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Slicer, Automatic Slicer, Electric Slicer, Semi-Automatic Slicer End User: Commercial Bakeries, Supermarkets, Restaurants, Home Users Technology: Blade Technology, Laser Cutting, Horizontal Cutting, Vertical Cutting Solution: Stand-Alone Machines, Integrated Systems, High-Volume Production, Custom Solutions |
| Companies Covered | ABO Bread Slicers, Empire Bakery Equipment, Berkel, Oliver Packaging & Equipment Company, OMEGA, Doyon Baking Equipment, LOZAMET, Erika Record, Ferneto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bread Slicer Market Evolving Landscape
Equipment manufacturers are converging blade mechanics with digital controls and alternative cutting modalities, while regulatory frameworks on both sides of the Atlantic are tightening material and safety specifications.
Ultrasonic blade technology is automating clean-slice performance through high-frequency vibration that reduces crumb fracturing in dense artisan loaves. Mid-sized commercial bakeries in Germany are piloting these systems for round-the-clock production shifts. The technology is automating labor out of high-precision slicing tasks while compressing maintenance intervals through reduced blade wear.
REACH substance restrictions are prohibiting certain coating materials previously standard on commercial food processing equipment. European manufacturers are reformulating blade surface treatments to maintain NSF compliance while eliminating restricted chemical constituents. German and French bakery cooperatives are demanding documentation trails that satisfy both CE marking and emerging circular economy disclosure requirements.
Buying committees are consolidating vendor relationships around line-efficiency guarantee contracts rather than discrete equipment purchases. Regional bread cooperatives are unbundling after-sales service from capital acquisition to improve operational expenditure predictability. This pattern is most visible in North American markets where direct-service networks compete on uptime commitments rather than unit pricing.
Bread Slicer Market Segmentation
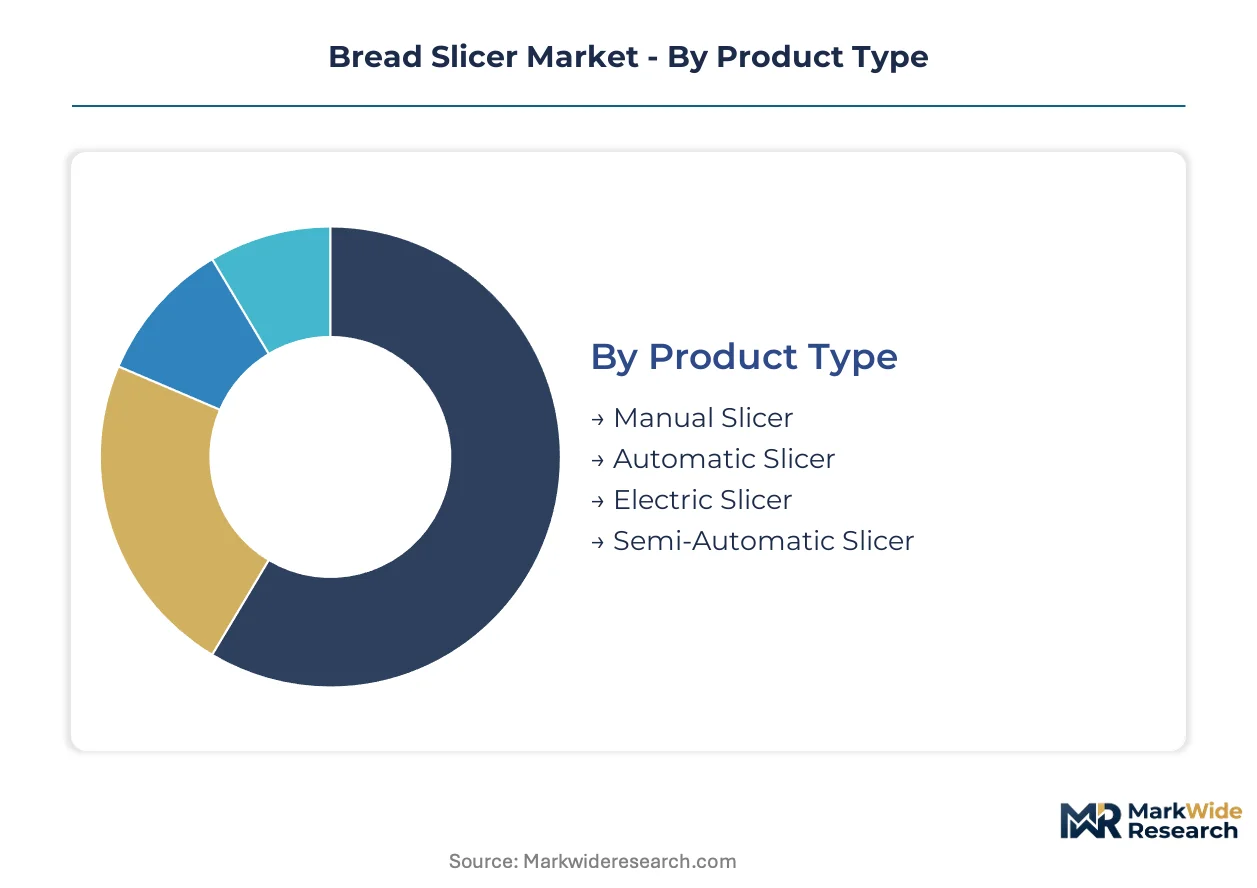
Equipment specification varies sharply across bakery scale and production intensity. Procurement committees evaluate slicer categories against throughput targets, labor substitution potential, and integration complexity with existing conveyor lines.
Product Type:
Volume tiers separate labor-dependent manual units from premium automated lines with safety interlocks and continuous feed mechanisms.
- Automatic Slicer:Conveyor-fed systems with reciprocating blade arrays achieve millimeter-precision thickness control for uniform retail presentation. Commercial bakeries in Germany and France are scaling these units for round-the-clock artisan production shifts.
- Manual Slicer:Hand-operated units with gravity-fed loaf cradles serve small-scale specialty bakeries where low volume and crust-handling flexibility outweigh labor costs. These systems persist in European artisan cooperatives producing limited-batch heritage loaves.
- Electric Slicer:Motorized blade drives with adjustable thickness settings bridge manual and fully automated workflows for mid-sized operations.
- Semi-Automatic Slicer:Hybrid designs combine powered cutting with manual loaf positioning, targeting bakeries transitioning from craft to scaled production.
Today's leader: Automatic Slicer. Tomorrow's challenger: Semi-Automatic Slicer.
End User:
Application intensity drives specification divergence, from NSF-certified stainless steel construction in commercial kitchens to compact countertop units for residential use.
- Commercial Bakeries:High-throughput slicing lines with automated feeding and blade-wear monitoring dominate procurement. Munich and Stuttgart industrial clusters anchor premium slicer demand as German bakery cooperatives expand retail distribution.
- Supermarkets:In-store bakery counters require compact footprint units with rapid changeover between loaf varieties. French retail chains are standardizing blade-technology platforms across regional bakery departments.
- Restaurants:Front-of-house presentation slicers emphasize low-noise operation and crumb containment for open-kitchen visibility.
- Home Users:Consumer-grade electric slicers with safety interlocks and easy-clean blade cartridges serve household bread enthusiasts.
Commercial Bakeries command the largest equipment budgets. Supermarkets are gaining share fastest through in-store bakery expansion.
Technology:
Cutting modality selection hinges on crumb structure preservation and maintenance interval requirements.
- Blade Technology:Reciprocating and rotary blade arrays remain the industry default, with ultrasonic vibration variants reducing fracturing in dense artisan loaves. German mid-sized bakeries are piloting these systems for delicate crumb structures.
- Laser Cutting:Non-contact thermal separation enables precision portioning of fragile specialty breads without mechanical compression. Premium applications in European artisan markets are testing integration with traditional blade lines.
- Horizontal Cutting:Parallel-to-crust slicing orientation suits sandwich bread production with uniform crumb density.
- Vertical Cutting:Perpendicular blade alignment handles round and oval loaves with irregular crown geometries.
Blade Technology retains installed base dominance. Laser Cutting holds the steepest expansion trajectory for premium niche applications.
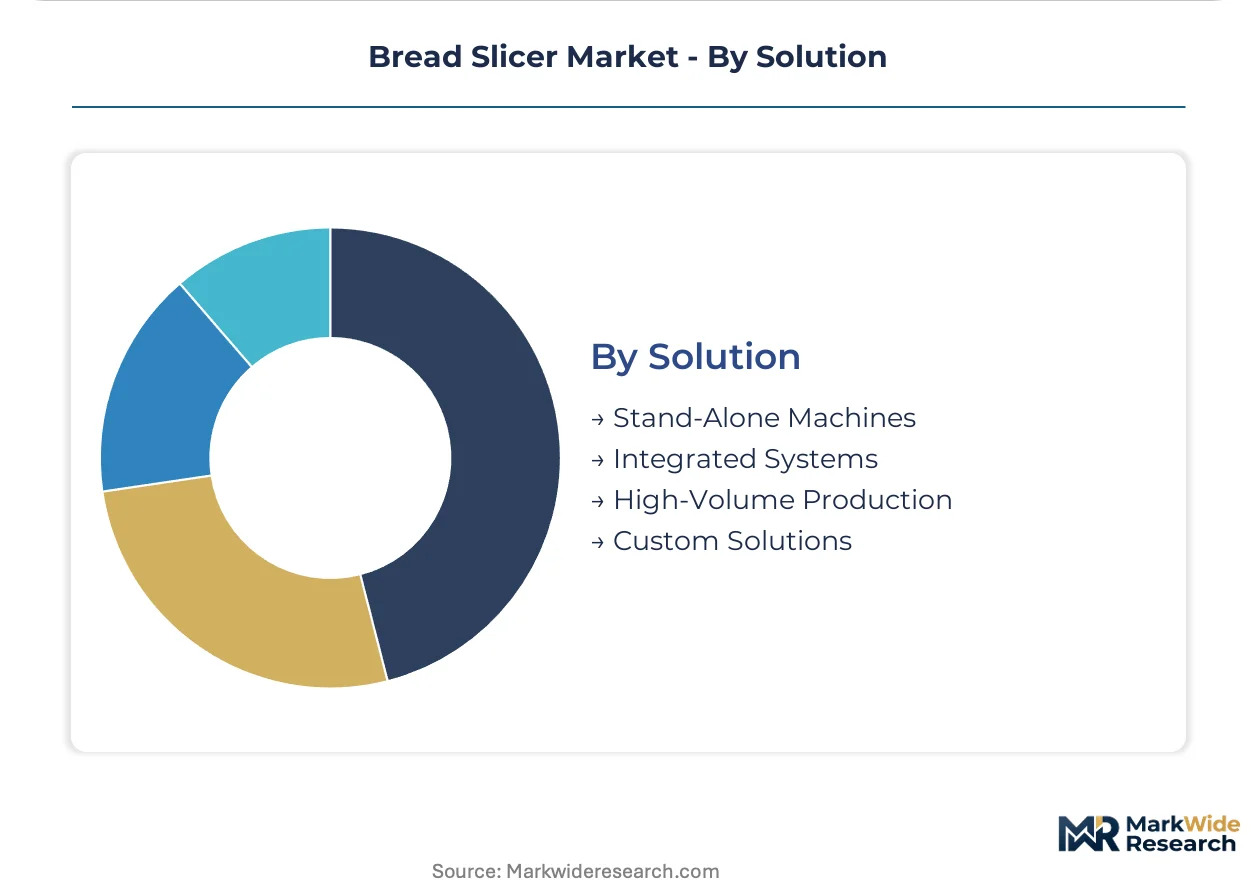
Solution:
System architecture choices reflect capital deployment strategy and operational expenditure predictability preferences.
- Integrated Systems:End-to-end slicing lines with upstream dough handling and downstream packaging capture margin pools through line-efficiency guarantees. North American bread cooperatives are unbundling after-sales service from capital acquisition to improve cost predictability.
- Stand-Alone Machines:Modular slicer units allow incremental capacity expansion and retrofit into existing production flows. These systems dominate replacement cycles in mature European bakery equipment markets.
- High-Volume Production:Continuous-duty architectures with automated blade sharpening and conveyor synchronization target industrial-scale facilities.
- Custom Solutions:Engineered-to-order slicing configurations address non-standard loaf dimensions or specialty crust treatments.
Integrated Systems anchor new facility investments. Stand-Alone Machines defend position in upgrade and replacement procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich and Stuttgart anchor industrial baking clusters where automated slicer procurement concentrates. German cooperatives drive CE-marked equipment upgrades. Regulatory pressure from Brussels reshapes cross-border equipment flows.
Germany
Artisan bread retail expansion and in-store bakery counter scaling drive slicer demand across Munich and Stuttgart industrial clusters. The EU Machinery Directive mandates CE marking for all new commercial installations. Bavarian bakery cooperatives are consolidating vendor relationships around line-efficiency guarantee contracts.
France
French retail chains standardize blade-technology platforms across regional bakery departments with rapid loaf variety changeover requirements. REACH substance restrictions prohibit legacy coating materials on food contact surfaces. Parisian and Lyon-based bakery cooperatives demand documentation trails satisfying both CE marking and circular economy disclosure mandates.
United States
Regional bread cooperatives unbundle after-sales service from capital acquisition to improve operational expenditure predictability. FDA food contact surface regulations govern NSF-certified stainless steel construction specifications. Midwest and Northeast bakery clusters prioritize direct-service network coverage in vendor selection criteria.
India
Institutional bakery modernization programs create compliance-driven upgrade demand for automated slicer installations. BIS certification requirements add regulatory layers for equipment exporters targeting commercial kitchen deployments. Maharashtra and Gujarat industrial zones anchor procurement committees evaluating integrated slicing lines.
Italy
Specialty crust-handling requirements for heritage loaves sustain demand for flexible slicing configurations. CE marking alignment with EU Machinery Directive safety interlock standards shapes equipment qualification. Emilia-Romagna and Lombardy baking clusters pilot ultrasonic blade systems for delicate crumb preservation.
Bread Slicer Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment fabricators align with regional service networks and technology licensors. The vendor base organizes around three tiers: multinational bakery equipment houses with captive manufacturing, mid-sized specialists in blade mechanics, and regional fabricators serving localized artisan markets. Two archetypes anchor competitive positioning: integrated system providers capturing margin pools through line-efficiency guarantees, and stand-alone machine specialists defending replacement cycle revenue. M&A activity and geographic expansion through distributor acquisitions represent the dominant competitive moves.
Among North American equipment houses, Empire Bakery Equipment and Oliver Packaging & Equipment Company exemplify the integrated-system archetype with manufacturing footprint advantages. Ferneto occupies a position within the European specialist tier, representing blade-technology specialization for crusty artisan applications. These three anchors illustrate how competitive positioning diverges between scale-driven system provision and precision-focused component engineering.
| Leading Market Players |
|---|
| ABO Bread Slicers |
| Empire Bakery Equipment |
| Berkel |
| Oliver Packaging & Equipment Company |
| OMEGA |
| Doyon Baking Equipment |
| LOZAMET |
| Erika Record |
| Ferneto |
| Others |
Value Network & Pricing Analysis
REACH substance restrictions on coating materials gate qualified supply and premium-tier pricing access for European bread slicer manufacturers. NSF-certified stainless steel construction with compliant blade surface treatments commands pricing premiums as German and French bakery cooperatives demand documentation trails satisfying both CE marking and circular economy disclosure mandates.
Pricing Analysis
Distributor margin layers compress as regional bread cooperatives unbundle after-sales service from capital acquisition. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and line-efficiency guarantee scope. Cost compression in mid-tier equipment is intensifying because nickel and chromium price fluctuations squeeze stainless steel input budgets. Small-scale artisan bakeries exhibit highest price sensitivity, while German industrial clusters anchor least sensitive procurement.
Supply Chain Analysis
Workforce availability constraints in German and Italian manufacturing geographies tether component fabrication to specialized technician pools. Germany, Italy, and China anchor supply concentration for precision blade arrays, conveyor mechanisms, and control systems. Raw material dependencies center on nickel-chromium stainless steel alloys, NSF-certified coating formulations, and electromagnetic safety components. Single-source vulnerability runs through Munich and Stuttgart industrial clusters for premium slicer subassemblies. Distribution runs through direct-service networks in mature markets and regional distributor partnerships in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bread slicer market functions as a regulatory compounder where EU Machinery Directive CE marking mandates and FDA food contact surface regulations continuously refresh equipment replacement cycles.
For Market Incumbents: To counter ultrasonic blade technology displacement from European specialists, deepen backward integration into blade alloy supply and expand captive technician deployment for direct-service network density. CE marking compliance investments and line-efficiency guarantee contracts defend margin pools against emerging Asian competitors targeting Indian institutional bakery modernization programs. For New Entrants and Emerging Players: Capture white-space in Indian BIS-certified automated slicer installations and Italian ultrasonic blade pilot programs for heritage loaf applications. Mid-sized commercial bakeries in Emilia-Romagna and Maharashtra represent the most penetrable buyer archetype. Go-to-market positioning through retrofit integration engineering for legacy conveyor compatibility unlocks replacement cycle access. For Investors and Strategic Acquirers: Roll-up economics work for blade-technology specialists because fragmented artisan equipment fabricators lack scale for REACH compliance investment and direct-service network buildout. Long-term viability centers on consolidation platforms capturing regulatory-driven upgrade demand. Watch laser cutting technology adoption rates in premium European artisan markets as inflection signal for next-generation slicing modality displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blade Alloy Supply | Captive nickel-chromium sourcing buffers NSF-certified construction against commodity volatility. |
| Direct-Service Network Expansion | Technician deployment density secures uptime commitments from German bakery cooperatives. |
| Ultrasonic Blade Technology Licensing | High-frequency vibration patents unlock premium positioning for dense artisan loaf applications. |
| BIS Certification Pathway Investment | Compliance infrastructure captures Indian institutional bakery modernization program demand. |
| Laser Cutting System Integration | Non-contact thermal separation addresses fragile specialty bread premium niche expansion. |
Research Methodology
Direct dialogue with plant engineers at commercial bakeries, OEM procurement teams, aftermarket service heads, and distribution channel partners grounded qualitative findings. Secondary validation drew from EU Machinery Directive implementation records, FDA food contact surface guidance documents, BIS certification registries, and customs trade data for bakery equipment flows. Bottom-up installation tracking and top-down industrial baking capacity estimates provided triangulation across the analysis window.
Segment-level outputs across product type, end user, technology, and solution dimensions were modeled throughout the forecast period. CAGRs were derived from equipment replacement cycle analysis, regulatory mandate implementation timelines, and artisan bread retail expansion trajectories. Input assumptions incorporated stainless steel price elasticity, CE marking compliance cost pass-through rates, and labor substitution automation thresholds.
Regulatory enforcement variance, nickel-chromium commodity volatility, and artisan bakery consolidation rates are the dominant revision risks to modeled trajectories. Forecasts reflect documented assumptions on mandate implementation pacing and technology adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Sandwich Preparation Refrigerators Market
Food Processing Equipment
Food Sterilization Equipment Market
Food Processing Equipment
Corn Puff Making Machine Market
Food Processing Equipment
Bread Maker Market
Food Processing Equipment
Food Processing and Handling Equipment Market
Food Processing Equipment
Nigeria Cocoa Processing Market
Food Processing Equipment
Double Stack Oven Market
Food Processing Equipment
High-Pressure Processing Equipment Market
Food Processing Equipment
Destemmer Market
Food Processing Equipment
North America Food and Beverage Filling and Capping Machines Market
Food Processing Equipment
Filleting Machines Market
Food Processing Equipment
Wine Bottling Machine Market
Food Processing Equipment
Sheet Metal Processing Equipment Market
Food Processing Equipment
Walk-In Refrigerators & Freezers Market
Food Processing Equipment
Global Starch Recovery Systems Market