
 Europe Tablet PC Market | 2026-2036
Europe Tablet PC Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tablet PC Market Insights
Premium OLED display tiering is collapsing the mid-range value proposition across the Europe Tablet PC Market. Samsung Electronics Co. Ltd. leverages its AMOLED supply chain to dominate high-resolution segments. Apple Inc. sustains margin leadership through proprietary silicon and ecosystem lock-in. Lenovo Group Ltd. competes aggressively on convertible form factors targeting enterprise procurement cycles.
A tablet PC is a portable computing device with a touchscreen interface, typically featuring processors between 2-4 GHz, RAM configurations from 4 GB to 16 GB, and battery capacities exceeding 8,000 mAh for full-shift operation. The Windows product type anchors enterprise deployments across European financial services and public administration, where legacy software compatibility determines procurement. The healthcare end user segment represents the fastest-growing demand pool, driven by clinical mobility mandates and HIPAA-aligned EU data protection requirements. Screen sizes of 11-12 inches capture the largest volume share, balancing portability against document readability for field technicians and nursing staff.
CE marking under the EU Radio Equipment Directive governs electromagnetic compatibility and spectrum use for all tablet imports. REACH and RoHS frameworks restrict hazardous substances in solder and display coatings, directly affecting component sourcing decisions. Ecodesign regulations from the European Commission mandate repairability scores and spare parts availability, compelling manufacturers to rethink chassis architecture and modular assembly. Stakeholders must monitor how the EU AI Act's risk classification rules will reshape tablet-integrated diagnostic and automation software across healthcare and industrial verticals.
Market Dynamics
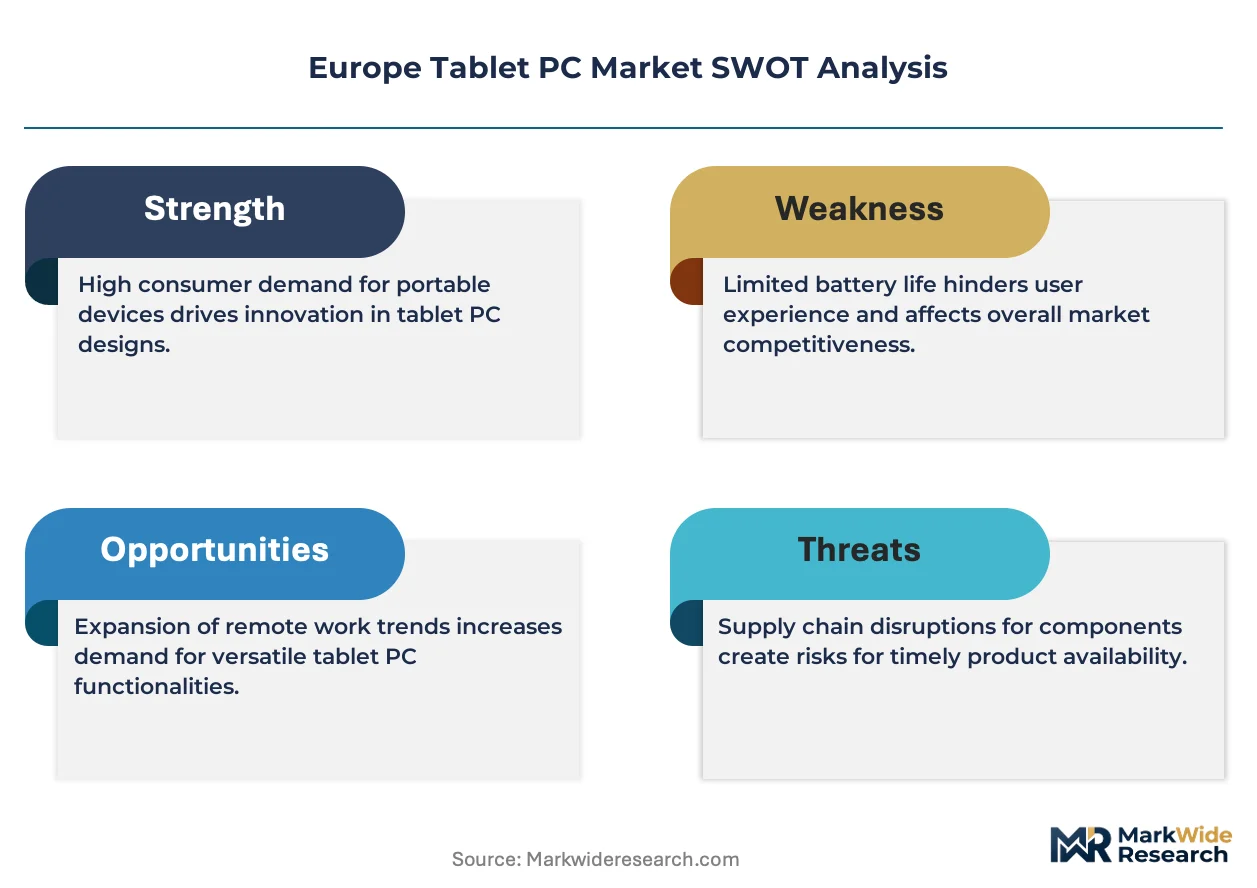
The EU Green Deal's circular electronics mandates are forcing tablet manufacturers to redesign chassis architecture around modularity and extended warranty obligations, compressing traditional hardware refresh cycles.
Growth Catalysts
- Clinical mobility mandates:Healthcare providers across Germany and France are deploying tablets for bedside patient monitoring and electronic health record access. The EU AI Act's risk classification rules are accelerating diagnostic software integration.
- REACH and RoHS compliance:Hazardous substance restrictions in solder and display coatings are pushing manufacturers toward cleaner supply chains. Component suppliers are retooling production lines to meet Ecodesign repairability scores.
- Industrial corridor concentration:Factory-floor automation in Germany's manufacturing belt is driving demand for ruggedized tablets with extended temperature tolerance and MIL-STD certification.
Market Restraints
- AMOLED supply concentration:Premium display panel production clusters in South Korean and Chinese fabs, exposing European OEMs to geopolitical supply disruptions and allocation constraints.
- Legacy software dependency:Windows tablet deployments in financial services and public administration face migration friction from decades-old proprietary applications lacking ARM compatibility.
- Lithium-ion cell volatility:Battery raw material costs fluctuate with cobalt and nickel spot markets, compressing margin structures for devices requiring 8,000 mAh+ capacities for full-shift operation.
Strategic Opportunities
- CE marking convergence:The EU Radio Equipment Directive's electromagnetic compatibility standards are creating a unified certification pathway for cross-border healthcare and industrial deployments.
- Convertible form factor expansion:Detachable keyboards and stylus integration are opening procurement cycles in education and field service sectors previously served by notebooks.
- Poland and Czech Republic manufacturing:Central European assembly capacity offers tariff-advantaged production for EU-distributed tablets, reducing logistics lead times versus Asian final assembly.
Industry Challenges
- Ecodesign repairability implementation:Mandated spare parts availability and modular assembly requirements demand retooling of surface-mount production lines and inventory management systems.
- Clinical workflow integration:HIPAA-aligned EU data protection requirements complicate tablet deployment in multi-hospital networks with fragmented electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tablet PC Market |
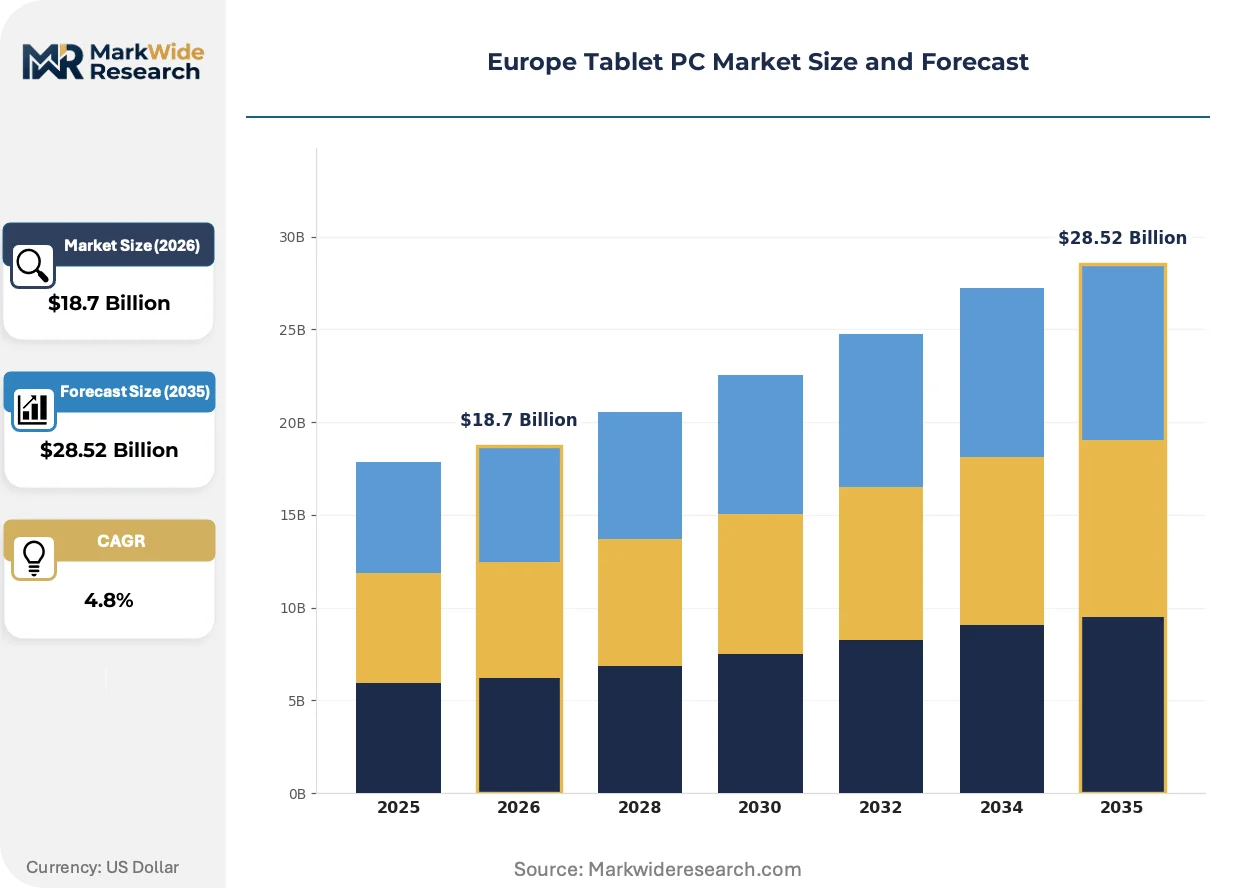
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Android, iOS, Windows, Others End User: Education, Business, Entertainment, Healthcare Distribution Channel: Online, Retail, Direct Sales, Wholesale Screen Size: 7-8 inches, 9-10 inches, 11-12 inches, 13 inches and above |
| Companies Covered | Microsoft Corporation, Acer Inc., Apple Inc., LG Corporation, Xiaomi Group, Samsung Electronics Co. Ltd., AsusTek Computer Inc., Hewlett Packard Enterprise Development LP, Lenovo Group Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tablet PC Market Trends and Innovations
Active matrix OLED technology is compressing display tier differentiation while regulatory pressure on circularity is reshaping hardware design priorities across European procurement channels.
Fanless thermal management systems using vapor chamber cooling are miniaturizing compute density in sealed industrial tablets. German automotive suppliers are adopting these designs for paint-shop and welding-floor deployments. The technology is miniaturizing chassis volumes while maintaining IP65 ingress protection ratings.
The EU AI Act's risk-based classification system is mandating conformity assessments for tablet-integrated diagnostic software in clinical settings. Device manufacturers must now embed audit trails and algorithmic transparency documentation. Healthcare OEMs are responding by segregating AI-enabled and standard configurations into distinct SKU lineups.
Enterprise buyers in France and the Netherlands are consolidating vendor relationships through framework agreements with single-source convertible tablet suppliers. Traditional reseller channels face margin compression as direct procurement teams negotiate multi-year fleet refresh schedules. Public administration verticals exhibit the most pronounced concentration, with national purchasing bodies centralizing device standardization.
Europe Tablet PC Market Segmentation
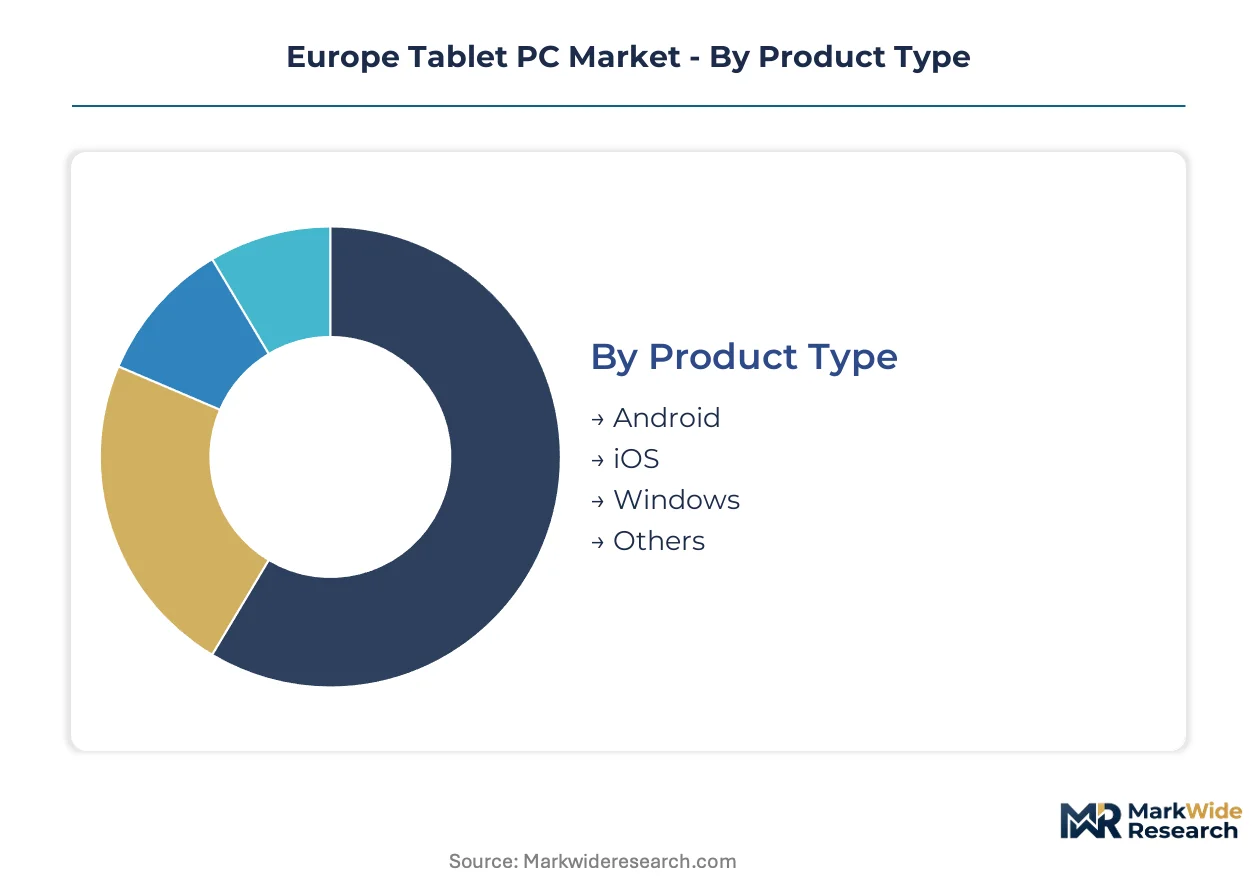
Tablet PC procurement across Europe fragments along software ecosystem lines, with enterprise buyers prioritizing legacy compatibility while healthcare and education sectors chase mobility-optimized form factors. Segmentation clarity exposes where CE marking convergence and Ecodesign repairability mandates reshape competitive positioning.
Product Type:
Domestic demand in Germany and France concentrates on Windows configurations for public administration, while Android and iOS volumes flow through retail channels into consumer hands across Southern Europe.
- Windows:Full x86 architecture maintains binary compatibility with legacy financial services software and SAP deployments across German industrial corridors. Procurement teams in Frankfurt and Munich banking clusters specify Windows tablets exclusively for regulatory audit trail requirements.
- iOS:Proprietary silicon delivers extended security update lifecycles that align with EU AI Act conformity assessment timelines for clinical diagnostic applications. French hospital networks in Paris and Lyon standardize on iOS for HIPAA-aligned data protection.
- Android:Open-source flexibility enables OEM customization for Polish and Czech factory-floor deployments with specialized sensor integration.
- Others:Chrome OS and Linux variants serve education sector procurement in Netherlands and Belgium seeking cloud-native management.
Windows holds the largest share; momentum sits with iOS as healthcare AI integration accelerates.
End User:
Cost tier stratification separates ruggedized industrial specifications from mass-market education deployments, with healthcare commanding premium positioning.
- Healthcare:Clinical mobility mandates in German Krankenhaus networks require MIL-STD-810G certification and antimicrobial chassis coatings. Bedside patient monitoring applications in Bavaria and North Rhine-Westphalia specify 8000 mAh+ batteries for full-shift operation.
- Business:Convertible form factors with detachable keyboards displace notebook procurement in French field service operations. Enterprise framework agreements in Île-de-France consolidate vendor relationships around single-source convertible suppliers.
- Education:Volume tenders from Spanish autonomous communities prioritize stylus integration and cloud management platforms for primary classroom deployment.
- Entertainment:OLED display tiering drives consumer replacement cycles in Italian retail channels, with Milan and Rome electronics districts commanding premium positioning.
Business captures the greatest volume concentration; healthcare is climbing the fastest as diagnostic software integration deepens.
Distribution Channel:
Supply concentration in direct sales channels reflects public administration centralization, while online fragmentation challenges traditional retail margins.
- Direct Sales:National purchasing bodies in France and Netherlands negotiate multi-year fleet refresh schedules, bypassing reseller markups. Government standardization programs concentrate procurement authority in Paris and The Hague.
- Online:Amazon and regional platforms capture consumer replacement demand across Spain and Italy, with logistics hubs in Poland reducing delivery lead times.
- Retail:Electronics specialists in German city centers maintain showroom presence for enterprise buyer evaluation, though transaction volume migrates online.
- Wholesale:System integrators in Czech Republic and Hungary bundle tablets with industrial automation deployments for manufacturing clients.
Direct sales dominates value capture; online channels are expanding most quickly as procurement digitization advances.
Screen Size:
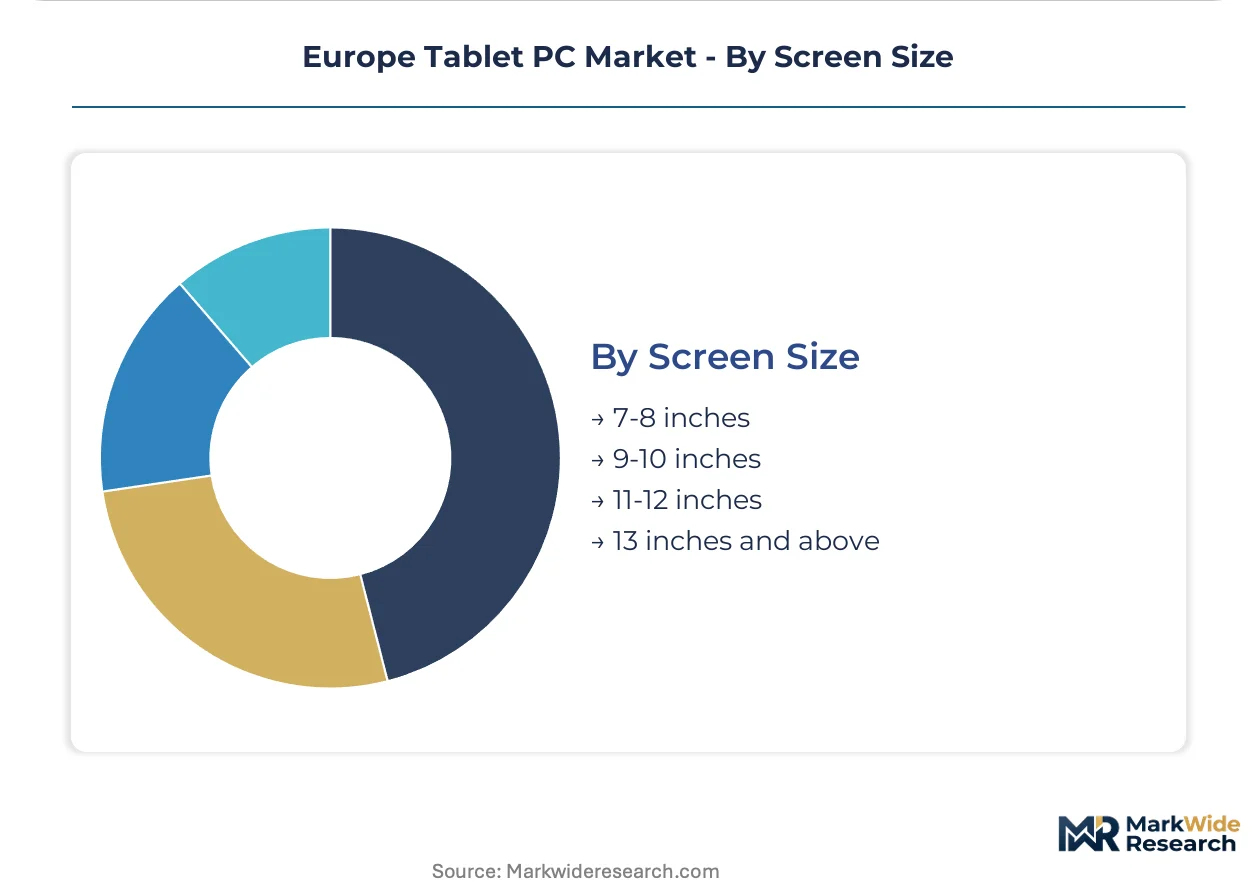
Volume clusters around portability-readability tradeoffs, with field technician and nursing staff specifications driving 11-12 inch dominance.
- 11-12 inches:Document readability for German automotive supplier quality inspectors balances against chassis weight for full-shift mobility. Paint-shop and welding-floor deployments in Stuttgart industrial belt specify this format exclusively.
- 9-10 inches:Education sector procurement in Belgian Flemish Community standardizes on this dimension for one-to-one student programs, optimizing backpack portability.
- 7-8 inches:Compact form factors serve Polish logistics warehouse picking operations where single-hand operation proves essential.
- 13 inches and above:Large-format displays address creative professional workflows in London and Berlin media clusters, though European volume remains limited.
11-12 inches leads absolute volume; 13 inches and above shows steepest expansion trajectory as creative workstation replacement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian and Spanish retail channels exhibit the highest price elasticity, where consumer replacement cycles stretch during economic pressure, while German industrial buyers absorb premium positioning for MIL-STD-certified factory-floor tablets without volume contraction.
Germany
Automotive suppliers in Stuttgart and Wolfsburg specify ruggedized tablets for paint-shop and welding-floor deployments. The EU Green Deal's Ecodesign regulations mandate modular chassis architecture and extended spare parts availability from manufacturers. Bavarian Krankenhaus networks drive clinical mobility procurement with 8000 mAh battery specifications for full-shift nursing operation.
France
Paris and Lyon hospital networks standardize procurement around HIPAA-aligned data protection configurations for patient monitoring applications. The EU AI Act's risk classification rules accelerate conformity assessments for tablet-integrated diagnostic software. Île-de-France public administration bodies consolidate vendor relationships through multi-year framework agreements for convertible tablet fleets.
United Kingdom
London media clusters generate limited but expanding demand for 13-inch and above creative workstation replacements. REACH compliance requirements restrict hazardous substances in display coatings and solder materials. Greater Manchester logistics operations deploy compact 7-8 inch tablets for warehouse picking workflows requiring single-hand operation.
Poland
Central European assembly capacity offers tariff-advantaged production for EU-distributed tablets, reducing logistics lead times versus Asian final assembly. CE marking under the EU Radio Equipment Directive governs electromagnetic compatibility for cross-border healthcare deployments. Warsaw and Kraków factory floors adopt Android-customized tablets with specialized sensor integration for process automation.
Netherlands
The Hague national purchasing bodies centralize public administration device standardization, bypassing traditional reseller channels. CSRD reporting requirements pressure procurement teams to document circular electronics compliance across tablet fleets. Randstad education authorities prioritize cloud-native management platforms for one-to-one student tablet programs.
Europe Tablet PC Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Europe Tablet PC Market. Premium display integration and proprietary silicon development concentrate among vertically integrated electronics conglomerates, while scale manufacturing and convertible form factor innovation distribute across diversified hardware groups. The competitive structure separates into three archetypes: ecosystem-locked premium vendors, supply-chain-differentiated display specialists, and enterprise-focused convertible manufacturers. Dominant competitive moves include backward integration into semiconductor design and geographic diversification of final assembly capacity.
Among ecosystem-locked premium vendors, Apple Inc. anchors the proprietary silicon tier with extended security update lifecycles aligned to EU AI Act timelines. Samsung Electronics Co. Ltd. occupies the display-integrated position, leveraging captive AMOLED supply for high-resolution clinical and industrial specifications. Lenovo Group Ltd. sits within the enterprise convertible tier, targeting framework agreement procurement cycles with detachable keyboard configurations. These three represent the archetype boundaries that reshape competitive positioning as Ecodesign repairability mandates force chassis architecture retooling.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Acer Inc. |
| Apple Inc. |
| LG Corporation |
| Xiaomi Group |
| Samsung Electronics Co. Ltd. |
| AsusTek Computer Inc. |
| Hewlett Packard Enterprise Development LP |
| Lenovo Group Ltd. |
| Others |
Pricing and Supply Chain Analysis
CE marking under the EU Radio Equipment Directive gates both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb certification costs upfront while capturing premium positioning through extended warranty and modular repairability bundling. German automotive suppliers and French hospital networks pay marked-up contract rates for compliant configurations, while uncertified gray-market imports compete on sticker price alone.
Pricing Analysis
Extended warranty and spare parts availability contracts drive lifetime value in the Europe Tablet PC Market. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-certified industrial units from education-sector volume tenders and consumer retail SKUs. Cost compression in mid-range OLED tiers intensifies because Samsung's captive AMOLED supply constrains competitor access to high-resolution panels. Education authorities in Spain exhibit highest price sensitivity; German factory-floor buyers absorb premium positioning without volume contraction.
Supply Chain Analysis
Inventory buffers for AMOLED display panels stretch lead times beyond standard component procurement cycles. Display fabrication concentrates in South Korea and China; final assembly draws from Poland and Czech Republic tariff-advantaged capacity. Cobalt and nickel spot volatility in lithium-ion cells feeds from battery raw material markets. Single-source vulnerability in premium OLED supply exposes European OEMs to geopolitical allocation constraints. Distribution runs through direct sales channels for public administration framework agreements and online platforms for consumer replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Tablet PC Market functions as a defensive-moat story anchored in regulatory entrenchment: Ecodesign repairability mandates and CE marking requirements create certification barriers that favor incumbents with established compliance infrastructure and long-standing regulator relationships.
For Market Incumbents: Shield market position by deepening backward integration into semiconductor design for proprietary silicon differentiation, and by locking multi-year framework agreements with Paris and The Hague national purchasing bodies before Ecodesign spare parts mandates fully phase in. Emerging Polish and Czech assembly capacity threatens margin compression if tariff advantages erode pricing power. For New Entrants and Emerging Players: CE marking fast-track partnerships with notified bodies in Germany and France unlock procurement access without the 12-18 month qualification delays that strand capital. Target Netherlands education authorities seeking cloud-native management platforms with Chrome OS and Linux variants, where incumbent ecosystem lock-in remains weakest. Bundle stylus integration and classroom management software to displace notebook procurement in Belgian and Dutch volume tenders. For Investors and Strategic Acquirers: EU AI Act risk classification implementation reshapes the acquisition landscape by mandating algorithmic transparency documentation and audit trail infrastructure that smaller clinical software integrators cannot self-fund. Long-term viability favors targets with established HIPAA-aligned data protection frameworks and existing hospital network deployments. Monitor CE marking backlog queues at German and French notified bodies as the inflection signal: clearance delays indicate tightening supply of qualified tablet configurations and pricing power concentration among certified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Chassis Architecture Redesign | Ecodesign repairability mandates in Germany force retooling of surface-mount production lines and inventory systems. |
| CE Marking Fast-Track Partnership | Notified body relationships in France compress qualification timelines for clinical diagnostic software integration. |
| Central European Assembly Expansion | Poland and Czech Republic capacity reduces logistics lead times versus Asian final assembly for EU distribution. |
| Proprietary Silicon Development | In-house ARM-based processor design extends security update lifecycles aligned to EU AI Act conformity timelines. |
| Framework Agreement Consolidation | Direct procurement with Île-de-France and Randstad national purchasing bodies bypasses reseller margin compression. |
Research Methodology
A standing panel of tablet OEM procurement directors, hospital biomedical engineers, automotive plant managers, and education authority IT directors provided ongoing calibration across the study period. Primary interviews combined with secondary validation from EU Ecodesign regulatory filings, CE marking databases, hospital procurement records, and customs trade data for tablet component flows. Bottom-up volume modeling and top-down value triangulation anchored segmentation outputs.
Consistency checks against external benchmarks validated projections across the analysis window. The analytical framework modeled product type, end user vertical, screen size tier, and distribution channel dimensions alongside repairability score compliance as an industry-specific segmentation layer. CAGRs derived from regression analysis of historical shipment data and elasticity-adjusted demand curves. Forecast inputs incorporated Ecodesign implementation timelines and EU AI Act risk classification phase-in schedules.
Decision-makers should treat outputs as directional under assumptions of stable REACH and RoHS hazardous substance restrictions; material deviation in cobalt-nickel battery chemistry regulations or AMOLED supply allocation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Gas Holders Market
Others
Europe Travel Retail Market
Others
Solar Animal Repellent Market
Others
North America Cashew Market
Others
Spinner Flask Market
Others
North America Medical Simulation Market
Others
Nuclear Power Cables Market
Others
Global Molded Plastics Market
Others
Billet Market
Others
Video Paas Market
Others
Nyerereite Market
Others
DNA Data Storage Market
Others
Global Webinar and Webcast Market
Others
Workstation Desktops Market
Others
Latin America Automotive HVAC Market
Others
Middle East and Africa Home Care Packaging Market