
 Digital Media Adaptor (DMA) Market | 2026-2036
Digital Media Adaptor (DMA) Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Media Adaptor (DMA) Market Intelligence
The expansion of DMA applications into corporate and educational settings is rebalancing the market away from a purely consumer-centric model. Roku, Inc. specializes in the streaming device category for home entertainment. In contrast, Cisco Systems, Inc. leverages its networking expertise to serve corporate presentation needs. Google LLC competes across both consumer and enterprise segments with its casting dongles and smart hub technologies, while Apple Inc. anchors its position through a tightly integrated hardware and content ecosystem.
A Digital Media Adaptor is a networking device that bridges digital content sources with display units lacking native streaming capabilities. These adaptors typically feature an HDMI output and process video codecs like H.265 to enable high-definition media playback from local or internet-based servers. Streaming devices and casting dongles show significant volume, while smart hubs integrate broader home automation functions. Although home entertainment remains the dominant application, digital signage and e-learning present new growth avenues for specialized media players.
Compliance with radio frequency emission rules, such as those from the FCC in the United States, is mandatory for wireless DMAs. In Europe, CE marking demonstrates adherence to safety and electromagnetic compatibility standards, while China's GB standards govern product specifications. Stakeholders must navigate evolving Wi-Fi protocols and the licensing landscape for next-generation video and audio codecs to maintain a competitive edge.
Market Dynamics
The market's primary dynamic is the performance gap between rapidly advancing content standards and the installed base of display hardware. The mainstreaming of 4K/8K media and immersive audio formats creates a replacement cycle, compelling users to upgrade adaptors to unlock the full potential of their subscriptions and displays.
Growth Catalysts
- Wi-Fi 6E Adoption:The rollout of the Wi-Fi 6E standard provides a dedicated 6 GHz band, reducing interference and latency for high-bitrate video streams, which in turn drives demand for compatible Digital Media Adaptors to leverage this improved network performance.
- Corporate and Education Expansion:Applications in corporate boardrooms for wireless presentations and in educational institutions for e-learning content delivery are creating new, high-margin revenue streams beyond the saturated home entertainment sector.
- 4K/8K Content Proliferation:Major streaming services are expanding their libraries of ultra-high-definition content, making older, non-4K compatible adaptors obsolete and compelling consumers to purchase new devices capable of processing advanced video codecs.
Market Restraints
- Smart TV Integration:The native integration of sophisticated operating systems and streaming applications directly into new television sets by manufacturers diminishes the total addressable market for standalone external adaptors.
- Codec Licensing Costs:High royalty fees associated with essential video codecs like HEVC (H.265) and emerging standards like VVC (H.266) increase the bill of materials for DMA manufacturers, pressuring margins or raising consumer prices.
- Semiconductor Volatility:The reliance on a concentrated number of foundries for specialized System-on-Chip (SoC) components exposes the market to supply chain disruptions, leading to potential production delays and price instability for core processors.
Strategic Opportunities
- Niche Vertical Applications:There is an opportunity to develop specialized, high-performance DMAs for markets such as medical imaging, industrial monitoring, and professional digital signage, which require enhanced security, reliability, and specific I/O configurations.
- Smart Hub Convergence:Integrating DMA functionality with broader smart home control capabilities, including support for protocols like Matter, allows devices to serve as central hubs for home automation, expanding their value proposition beyond media streaming.
- Emerging Market Broadband Growth:Rising fixed-line and mobile broadband penetration in regions like Southeast Asia and Latin America opens new markets for affordable, entry-level streaming dongles tailored to local content preferences and bandwidth constraints.
Industry Challenges
- Regulatory Compliance Fragmentation:Navigating the divergent and evolving requirements for radio frequency emissions and product safety, such as FCC rules in the US and CE marking in Europe, creates significant compliance overhead and extends time-to-market.
- Digital Rights Management Complexity:Implementing and maintaining multiple, complex Digital Rights Management (DRM) schemes required by content owners is a significant technical and operational challenge, with failures leading to blocked content and poor user experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Media Adaptor (DMA) Market |
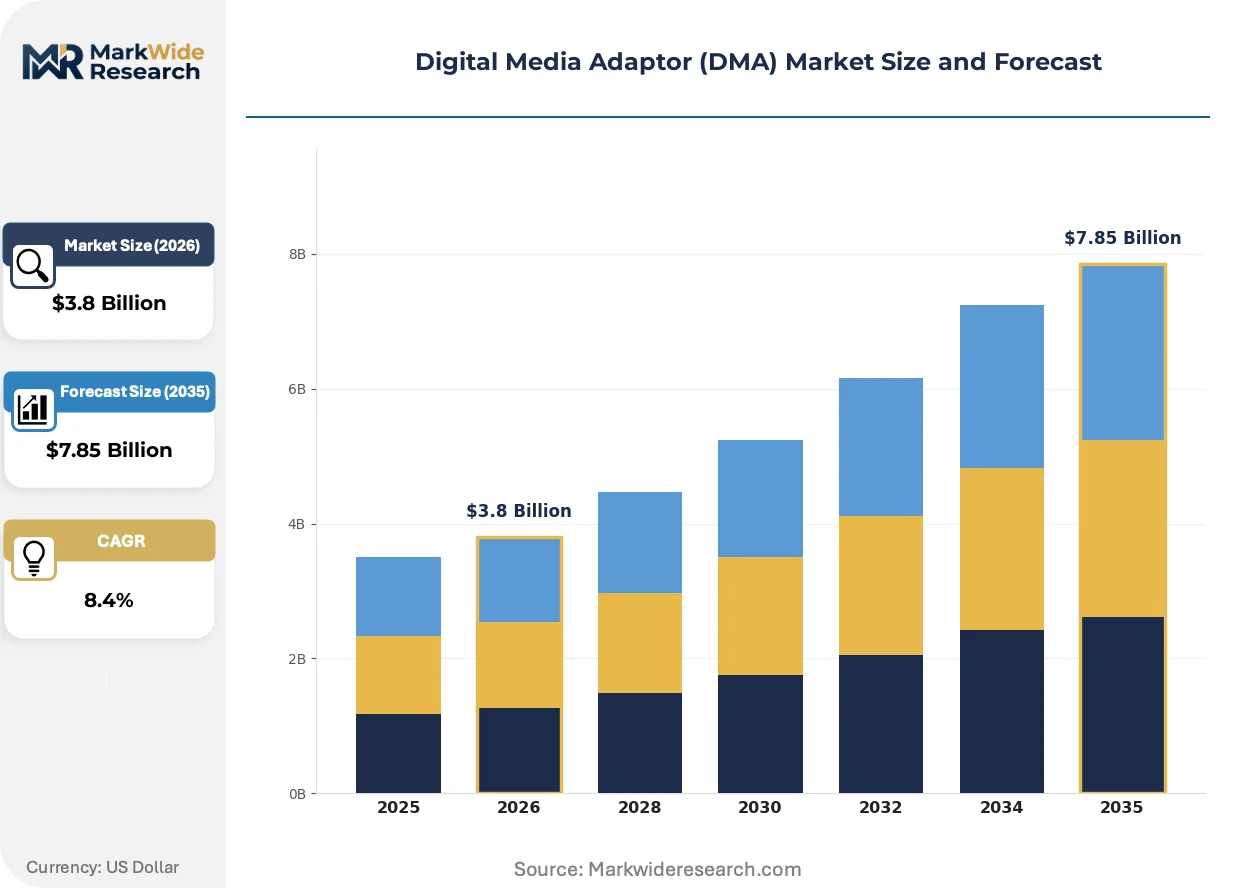
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Streaming Devices, Set-Top Boxes, Media Players, Smart Hubs, Casting Dongles Technology: HDMI, Wi-Fi, Bluetooth, USB, Ethernet, DLNA Application: Home Entertainment, Corporate Presentations, Digital Signage, E-Learning, Gaming End User: Consumers, Small Enterprises, Educational Institutions, Hospitality Providers, Event Organizers |
| Companies Covered | Apple Inc., Roku, Inc., Samsung Electronics Co., Ltd., Cisco Systems, Inc., Google LLC, NETGEAR Inc., Seagate Technology LLC, Western Digital Technologies, Inc., Zyxel Communications Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Media Adaptor (DMA) Market Strategic Shifts & Innovations
Ecosystem lock-in is intensifying as hardware becomes a conduit for recurring software and service revenue. The strategic focus is shifting from one-time device sales to capturing long-term user engagement through proprietary operating systems, content aggregation, and advertising platforms.
AI-powered upscaling is a key product evolution. This technology uses machine learning algorithms embedded in the device's SoC to enhance standard and high-definition content to 4K or 8K resolution in real time. Premium consumer segments are adopting these devices to improve the viewing experience on large-screen televisions. This on-device processing capability is converging with cloud-based content delivery to create a superior, bandwidth-efficient viewing experience.
European Union regulations on energy efficiency are influencing device design. The Ecodesign for Sustainable Products Regulation (ESPR) imposes strict limits on standby and networked standby power consumption for electronics. This is forcing manufacturers to innovate in power management hardware and optimize software to minimize idle power draw. The consumer DMA segment is most affected, leading to redesigns that prioritize low-power states to achieve compliance for market access.
A notable shift in purchasing behavior is the move toward hardware subsidized by content or advertising revenue. This model disrupts the traditional one-time purchase in retail channels by linking the device's cost to a subscription or user engagement with an ad-supported platform. This strategy is most visible in the competitive United States market, where streaming service providers leverage low-cost or free DMAs as a key tool for customer acquisition and retention.
Digital Media Adaptor (DMA) Market Segmentation
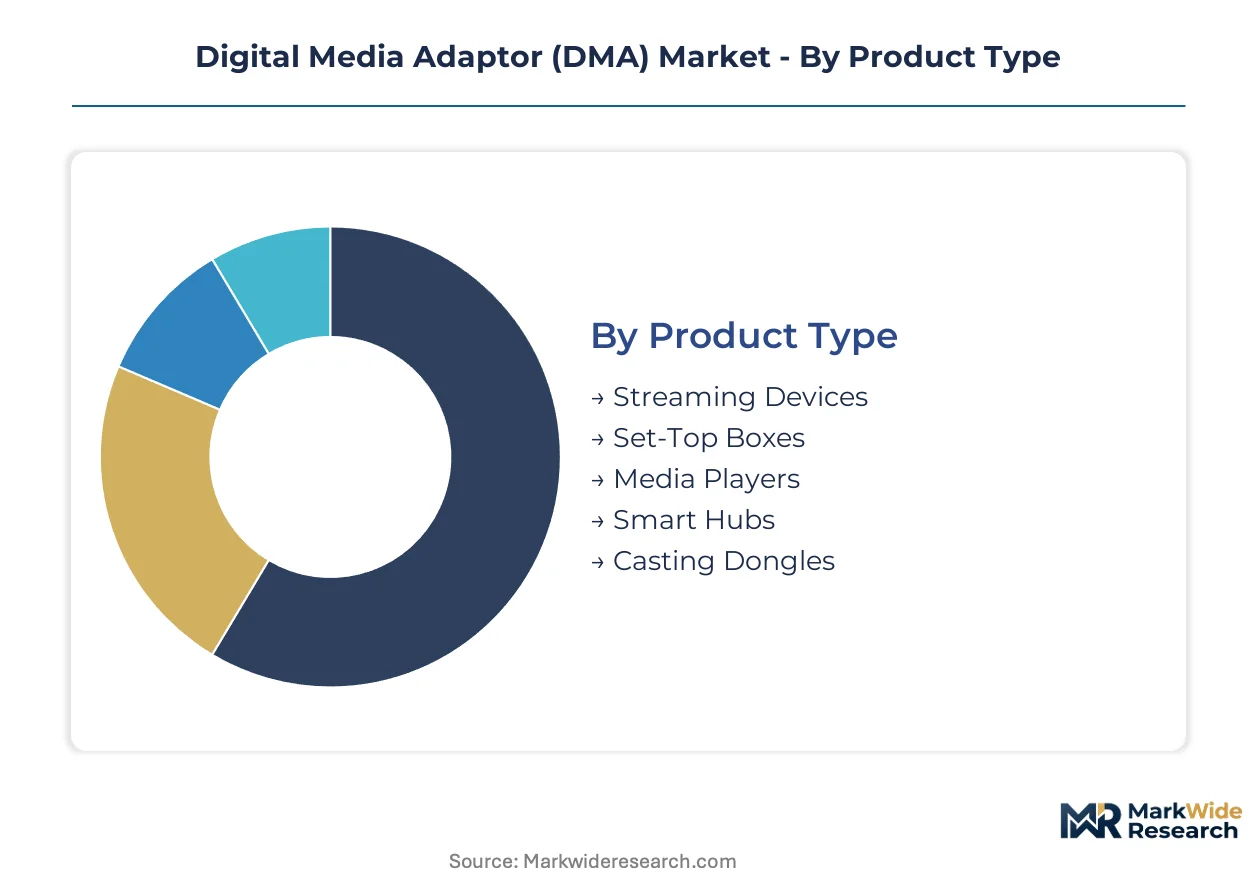
The Digital Media Adaptor market segmentation highlights distinct product functionalities and use cases driving industry growth. Understanding these segments is crucial for manufacturers to tailor offerings to specific consumer and enterprise demands. Strategic product development addresses the varying technical requirements across diverse applications.
Product Type:
The product type segmentation reflects the ongoing upgrade and replacement cycles driven by evolving content standards and user expectations. Consumers frequently replace older devices to access higher resolution media and improved streaming features.
- Streaming Devices:These dedicated hardware units connect to a display and access internet-based content services, often featuring proprietary operating systems and remote controls. Demand is concentrated in developed media markets like the United States, driven by the proliferation of 4K/8K content and subscription services.
- Set-Top Boxes:These devices typically decode digital television signals for display on a television set, often including DVR capabilities and basic internet connectivity. Demand for these legacy devices is declining as consumers transition to direct streaming and smart TV platforms.
- Media Players:Standalone units designed for local media playback from USB drives, network-attached storage, or optical discs. These cater to niche users with extensive personal media libraries.
- Smart Hubs:These integrated devices combine DMA functionality with broader smart home control capabilities, supporting various IoT protocols like Matter. Their expansion is driven by the desire for centralized home automation and media management.
- Casting Dongles:Compact devices that allow users to wirelessly cast content from mobile devices or computers to a larger display. These offer an affordable entry point into streaming for budget-conscious consumers.
Volume placements concentrate in Casting Dongles; the faster expansion belongs to Smart Hubs.
Technology:
Technology segmentation highlights the diverse connectivity options and protocols essential for bridging content sources with display units across various application environments. Each technology addresses specific requirements for bandwidth, range, and interoperability.
- HDMI:High-Definition Multimedia Interface is the primary digital interface for transmitting uncompressed video and audio data from the DMA to a display. The standard's evolution to HDMI 2.1 supports 4K and 8K resolutions, driving its continued adoption in premium devices.
- Wi-Fi:This wireless networking technology enables DMAs to connect to local networks and the internet for content streaming. The adoption of Wi-Fi 6E, utilizing the 6 GHz band, reduces interference and latency for high-bitrate video streams, particularly in dense network environments.
- Bluetooth:A short-range wireless technology primarily used for connecting peripherals like remote controls, keyboards, or audio devices to the DMA. Its low power consumption suits accessory integration.
- USB:Universal Serial Bus ports on DMAs facilitate local media playback from external storage devices or power delivery for compact dongles. USB-C offers enhanced power and data transfer capabilities.
- Ethernet:A wired networking standard providing stable, high-bandwidth connections for DMAs, favored in corporate and digital signage applications requiring reliability. Ethernet minimizes latency and interference for critical installations.
- DLNA:Digital Living Network Alliance provides guidelines for sharing digital media between devices over a home network. Its use is declining as proprietary streaming protocols gain prominence.
The segment's evolution is heavily influenced by advancements in wireless transmission and high-definition video standards.
Application:
The application segmentation reveals how different customer types leverage Digital Media Adaptors for specific use cases, extending beyond traditional consumer entertainment. This diversification reflects new market opportunities in professional and educational settings.
- Home Entertainment:This dominant application involves streaming movies, TV shows, and music to televisions and home theater systems. Consumers in Germany and South Korea increasingly demand 4K and 8K content, driving upgrades in this segment.
- Corporate Presentations:DMAs enable wireless screen sharing and content delivery in meeting rooms and boardrooms, replacing traditional wired connections. Cisco Systems, Inc. leverages its networking expertise to serve this high-margin enterprise segment.
- Digital Signage:Specialized media players power dynamic displays in retail, public spaces, and transportation hubs for advertising and information dissemination. These applications require robust, continuously operating devices.
- E-Learning:DMAs facilitate content delivery to display screens in classrooms and lecture halls, supporting remote learning and interactive educational experiences. This segment sees demand for reliable, easy-to-manage solutions.
- Gaming:Adaptors can stream games from cloud services or local PCs to a television, offering a console-like experience without dedicated gaming hardware. This niche application benefits from low-latency connections.
Growth across this category reflects diverse user needs, from casual media consumption to mission-critical professional deployments.
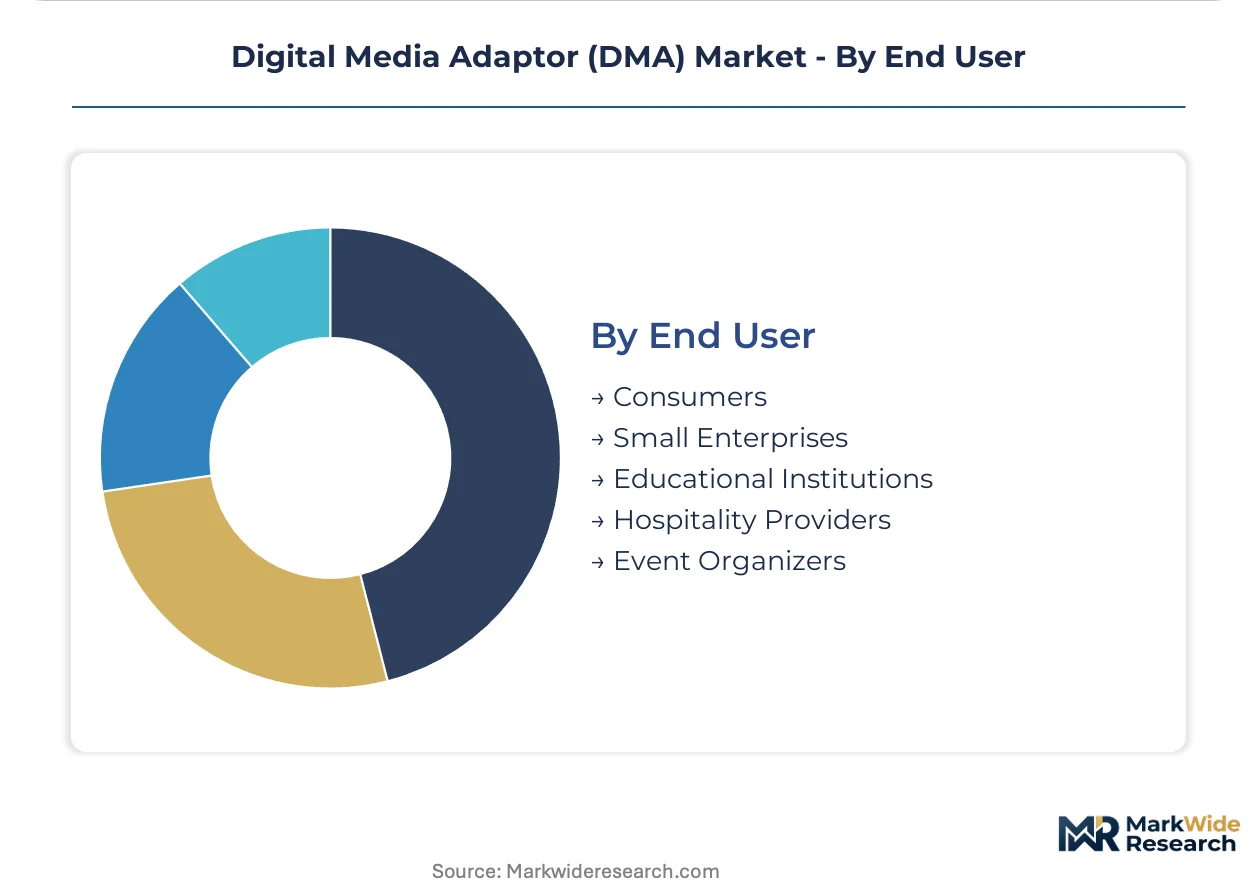
End User:
The end user segmentation delineates the distinct purchasing behaviors and value propositions that drive market dynamics across different customer groups. Profitability often varies significantly between high-volume consumer sales and specialized enterprise solutions.
- Consumers:Individual purchasers seeking devices for personal home entertainment, smart home integration, or casual content casting. This segment is characterized by price sensitivity and a focus on ease of use, with a strong replacement cycle for new content standards.
- Small Enterprises:Businesses utilizing DMAs for internal presentations, digital signage in offices, or basic collaboration tools. These users prioritize reliability, security, and cost-effectiveness for their operational needs.
- Educational Institutions:Schools and universities deploy DMAs for e-learning content delivery, interactive whiteboards, and campus-wide information displays. They require robust, manageable solutions for multiple users and diverse learning environments.
- Hospitality Providers:Hotels, resorts, and cruise lines use DMAs to offer in-room entertainment and digital information services to guests. This segment demands devices with strong content protection and easy integration with existing systems.
- Event Organizers:Professionals who utilize DMAs for temporary installations at conferences, concerts, and exhibitions for large-screen projections and live content streaming. Portability and quick setup are key requirements.
Demand shifts indicate a broadening base beyond traditional users, with significant opportunity in institutional and commercial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand for Digital Media Adaptors concentrates in developed media markets, driven by continuous content upgrades and consumer preferences. Emerging economies also present significant opportunities for entry-level devices. This geographic spread reflects varying consumer needs and infrastructure readiness.
United States
The United States market exhibits robust demand for advanced Digital Media Adaptors, fueled by widespread 4K/8K content availability and extensive streaming service subscriptions. Wireless DMAs must comply with stringent FCC rules regarding radio frequency emissions to gain market access. Technology hubs like Silicon Valley continue to innovate, pushing advancements in streaming platforms and smart home device integration.
Germany
Germany shows substantial demand for high-resolution Digital Media Adaptors within its mature home entertainment sector, with consumers frequently upgrading for 4K and 8K media. Products sold in Germany require CE marking, signifying compliance with European safety and electromagnetic compatibility standards. Cities such as Munich and Berlin foster media technology development, influencing regional product design and market trends.
South Korea
South Korea demonstrates significant demand for cutting-edge Digital Media Adaptors, propelled by its early adoption of advanced display technologies and a strong appetite for 4K/8K content. Manufacturers must adhere to the country's national product specifications and telecommunications regulations for market entry. Seoul's dynamic technology ecosystem fosters rapid innovation in smart home devices and integrated streaming solutions.
India
India represents a growing market for affordable Digital Media Adaptors, driven by increasing fixed-line and mobile broadband penetration in urban and semi-urban areas. Devices must meet BIS standards for product quality and safety, while TRAI oversees broadcasting compliance. Major tech hubs like Bengaluru and Hyderabad are developing localized content platforms, increasing demand for compatible streaming devices.
Brazil
Brazil offers substantial opportunities for entry-level Digital Media Adaptors, supported by expanding internet access and a preference for local content delivery. Telecommunication products require certification from ANATEL to ensure compliance with national standards. Urban centers such as São Paulo and Rio de Janeiro are driving digital infrastructure development, supporting wider streaming device adoption.
Digital Media Adaptor (DMA) Market Key Industry Players
United States producers often anchor one tier, emphasizing integrated ecosystem solutions and consumer streaming platforms. Asian manufacturers, conversely, frequently focus on high-volume, cost-effective devices or specialized components for a broader market. The market structure exhibits a blend of highly diversified technology conglomerates and focused niche players. Key strategic archetypes include consumer entertainment specialists, enterprise networking providers, and integrated smart home ecosystem developers. Competitive moves center on technology licensing for advanced codecs, strategic partnerships with content providers, and portfolio diversification into broader smart home functionality.
Within the integrated ecosystem and specialized streaming segments, Apple Inc. represents a player focused on a tightly controlled hardware and content environment. Roku, Inc. exemplifies a dedicated streaming device provider, primarily serving the home entertainment sector with its proprietary operating system. Cisco Systems, Inc. occupies a position as a networking expert, leveraging its capabilities for robust corporate presentation solutions. These companies anchor distinct market approaches, from broad consumer platforms to specialized enterprise applications, highlighting the diverse strategic orientations defining the Digital Media Adaptor market.
| Leading Market Players |
|---|
| Apple Inc. |
| Roku, Inc. |
| Samsung Electronics Co., Ltd. |
| Cisco Systems, Inc. |
| Google LLC |
| NETGEAR Inc. |
| Seagate Technology LLC |
| Western Digital Technologies, Inc. |
| Zyxel Communications Corporation |
| Others |
Cost & Logistics Intelligence
Semiconductor component costs, originating from concentrated foundries, significantly influence the final pricing tiers of Digital Media Adaptors downstream. These core processor expenses are then passed through to consumers, impacting device affordability.
Pricing Analysis
Volume-driven segments like casting dongles operate on thin margins, while smart hubs command higher profitability. Pricing stratifies across premium, standard, and economy tiers, differentiating by brand premium and advanced feature sets like Wi-Fi 6E support. Pricing pressure stems from the increasing native integration of streaming capabilities into smart televisions. Consumers seeking entry-level casting dongles exhibit the highest price sensitivity, unlike enterprise buyers for corporate presentation solutions.
Supply Chain Analysis
Dual-sourcing requirements are emerging for critical components to mitigate supply disruptions for Digital Media Adaptors. Supply concentrates heavily in East Asia, drawing specialized System-on-Chip (SoC) components from Taiwan and manufacturing capabilities primarily from China. Semiconductor volatility presents a structural risk, impacting production stability and component costs. Downstream distribution primarily occurs through consumer electronics retail channels and specialized AV integrators for corporate applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Media Adaptor market is navigating a technology-transition phase, as Wi-Fi 6E and 4K/8K content standards replace older connectivity and resolution capabilities. This shift compels stakeholders to adapt product strategies and market approaches.
For Market Incumbents:Deepen ecosystem integration by leveraging proprietary operating systems and content partnerships to counter native smart TV integration. Invest heavily in R&D for AI-powered upscaling technology to maintain a premium offering. This strategy reinforces brand loyalty and mitigates margin erosion from commoditized streaming solutions. Prioritize compliance with evolving energy efficiency regulations like the EU's ESPR to ensure market access.
For New Entrants and Emerging Players:Price-point gaps exist within emerging markets and specialized vertical applications, offering entry opportunities. Target underpenetrated regions like Southeast Asia with affordable, entry-level casting dongles tailored to local content preferences. Focus on niche professional segments, such as digital signage, by offering enhanced security and specific I/O configurations. A localized content partnership strategy can accelerate market penetration.
For Investors and Strategic Acquirers:Widespread adoption of the Matter protocol in smart hubs is the leading indicator that convergence in home automation and media streaming is accelerating. The market offers long-term viability, driven by continuous home entertainment upgrades and new enterprise applications over the next decade. Identify acquisition targets among specialized media player manufacturers or vertically integrated smart hub developers with strong IP in AI upscaling. Monitor regulatory shifts in energy efficiency and DRM compliance for market stability.
| Strategic Initiative | Industry Significance |
|---|---|
| Ecosystem Integration | Strengthens user retention against smart TV competition through proprietary content and services. |
| AI Upscaling R&D | Enhances viewing experience on high-resolution displays, creating a premium product differentiator. |
| Enterprise Niche Expansion | Diversifies revenue streams beyond consumer markets into high-margin corporate and educational applications. |
| Wi-Fi 6E Compatibility | Ensures optimal performance for high-bitrate 4K/8K content, meeting evolving network standards. |
| Matter Protocol Integration | Positions devices as central smart home hubs, expanding value proposition and market reach. |
Research Approach
Multi-period observation of content consumption patterns and network infrastructure advancements anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with product managers, network architects, content strategists, and consumer electronics retail buyers. Secondary validation drew from FCC filings, CE marking databases, streaming service subscriber reports, and technology patent databases. This approach utilized both bottom-up market sizing and top-down validation.
Segment-weighting approaches were applied to project market trajectories across the analysis window, integrating various growth catalysts and restraints. The analytical framework modeled dimensions such as product type, technology, application, end user, and regional regulatory compliance. Compound Annual Growth Rates were derived through a combination of regression analysis and expert consensus. Key forecast inputs included global broadband penetration rates and 4K/8K display adoption metrics.
Underlying measurement precision varies by segment; home entertainment and corporate applications carry tighter precision than emerging niche verticals. Forecasts reflect assumptions regarding technological evolution and regulatory stability. Deviation in geopolitical disruptions or rapid shifts in codec licensing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Durian Market
Others
Video Conferencing Hardware Market
Others
High-Performance Films Market
Others
Android STB and TV Market
Others
Latin America Domestic CEP Market
Others
Latin America Automotive HVAC Market
Others
Canada Feed Additives Market
Others
Wingboards Market
Others
Plastic Films and Sheets Market
Others
UK Real Estate Hospitality Market
Others
Kuwait Retail Market
Others
Global Cryogenic Tanks Market
Others
North America Wiring Duct Market
Others
Server Market
Others
Belt Loader Market
Others
Japan 3D Printing Construction Market