
 Coconut Activated Carbon Market | 2026-2036
Coconut Activated Carbon Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Activated Carbon Market Analysis
Market Context
Municipal water utilities are bifurcating from industrial buyers as the fastest-growing procurement archetype for coconut activated carbon. Jacobi Carbons leverages its vertically integrated Sri Lankan operations to dominate supply to European municipal contracts. Haycarb sustains its position through specialized gold recovery grades that command premium positioning in African mining corridors. Donau Carbon competes on technical service intensity, embedding engineering teams directly into German industrial filtration installations.
Technical Definition and Segment Structure
Coconut activated carbon is a microporous adsorbent material derived from the pyrolysis and steam activation of coconut shells, typically exhibiting iodine numbers exceeding 1,000 mg/g and surface areas above 1,000 m²/g, engineered primarily for contaminant removal in liquid and gas phase industrial processes. Granular activated carbon anchors the value pool in municipal water treatment infrastructure, where long bed-life and low pressure-drop requirements favor larger particle sizes over powdered alternatives. Powdered activated carbon is displacing historical alum coagulation in seasonal taste-and-odor events at North American surface water plants, creating episodic but high-margin demand spikes.
Regulatory Framework and Outlook
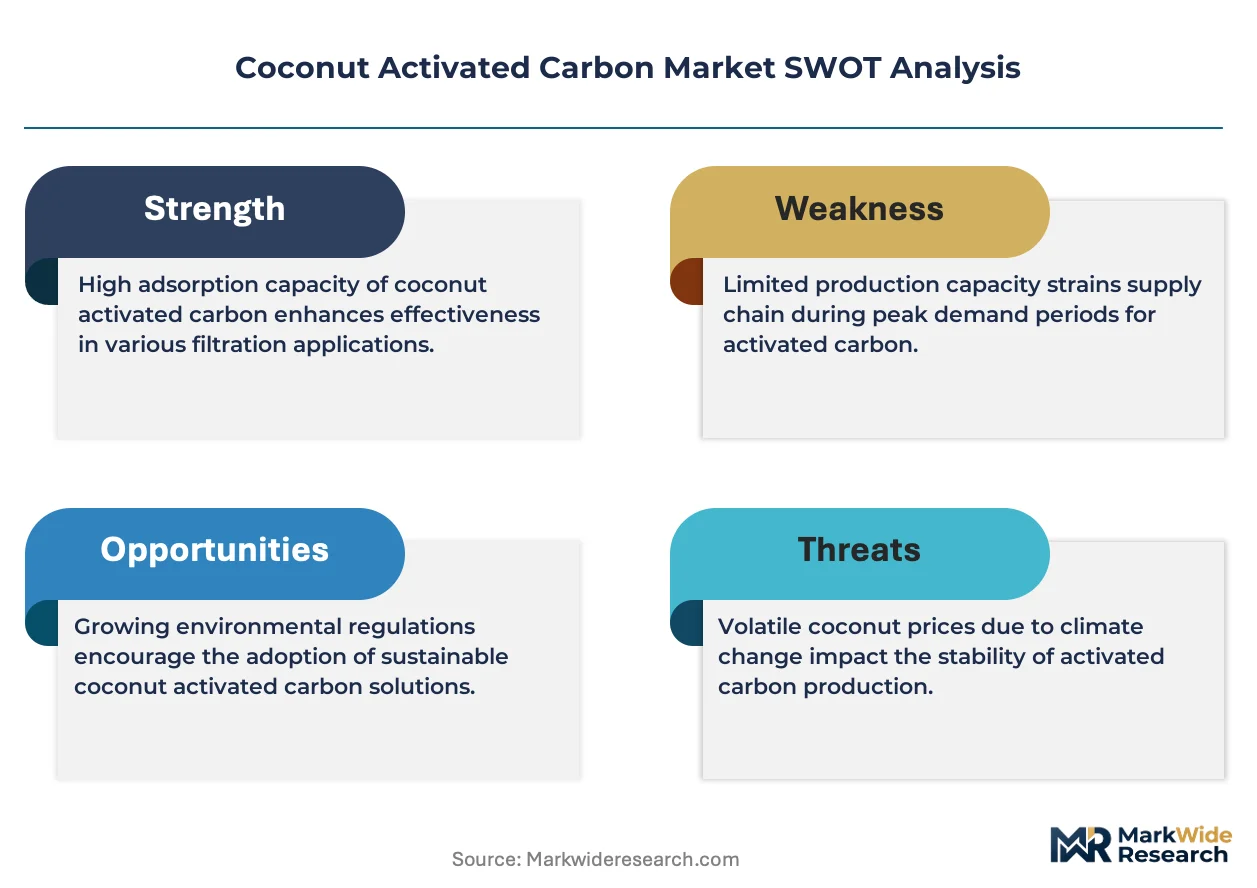
The EPA's Stage 2 DBP Rule and the EU Drinking Water Directive, enforced by national regulators under ECHA guidance, are mandating lower total organic carbon thresholds that directly expand activated carbon loading rates at treatment facilities. ISO 9001 and NSF/ANSI 61 certification requirements are narrowing market access for uncertified producers, particularly in North American municipal procurement. Stakeholders must monitor feedstock cost volatility in Philippine coconut regions, where climatic disruption and competing copra demand are tightening shell availability ahead of capacity expansions.
Market Dynamics
Municipal water utilities are diverging from industrial procurement patterns as EPA Stage 2 DBP Rule compliance deadlines compress activated carbon loading cycles at treatment facilities. This regulatory compression is forcing infrastructure retrofit decisions that favor granular bed configurations over powdered episodic dosing.
Growth Catalysts
- EPA Stage 2 Disinfectants and Disinfection Byproducts Rule:The rule mandates lower total organic carbon thresholds, compelling US municipal utilities to expand activated carbon capacity in surface water treatment plants.
- Gold recovery sector:African mining corridors sustain premium-grade demand for specialized coconut carbon with superior attrition resistance and gold adsorption kinetics.
- Southeast Asian feedstock clusters:Philippine and Indonesian coconut shell supply chains provide cost-advantaged pyrolysis feedstock that anchors regional production economics.
Market Restraints
- Copra demand competition:Edible oil processors in Mindanao and Sulawesi divert coconut shell availability, tightening pyrolysis feedstock access for carbon producers during peak harvest volatility.
- NSF/ANSI 61 certification barriers:North American municipal procurement specifications exclude uncertified producers, constraining market entry for Southeast Asian manufacturers lacking testing infrastructure.
- Coal-based activated carbon substitution:Bituminous coal carbons retain cost advantage in large-volume industrial gas-phase applications where micropore specificity matters less.
Strategic Opportunities
- Per- and polyfluoroalkyl substances remediation:Emerging PFAS treatment mandates at US Department of Defense sites and municipal wells create demand for reactivated carbon services with specialized handling protocols.
- EU Drinking Water Directive revisions:The directive's tightened contaminant thresholds expand activated carbon deployment in Eastern European municipal systems previously reliant on conventional filtration.
- On-site reactivation infrastructure:Mobile thermal reactivation units enable industrial users to reduce virgin carbon consumption and waste disposal costs in remote mining and food processing locations.
Industry Challenges
- Activation furnace engineering expertise:The specialized knowledge required for steam activation temperature profiling and residence time optimization constrains capacity expansion timelines for new market entrants.
- Legacy alum coagulation system integration:Surface water plants retrofitting seasonal powdered carbon dosing must reconcile incompatible chemical handling infrastructure and operator training protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Activated Carbon Market |
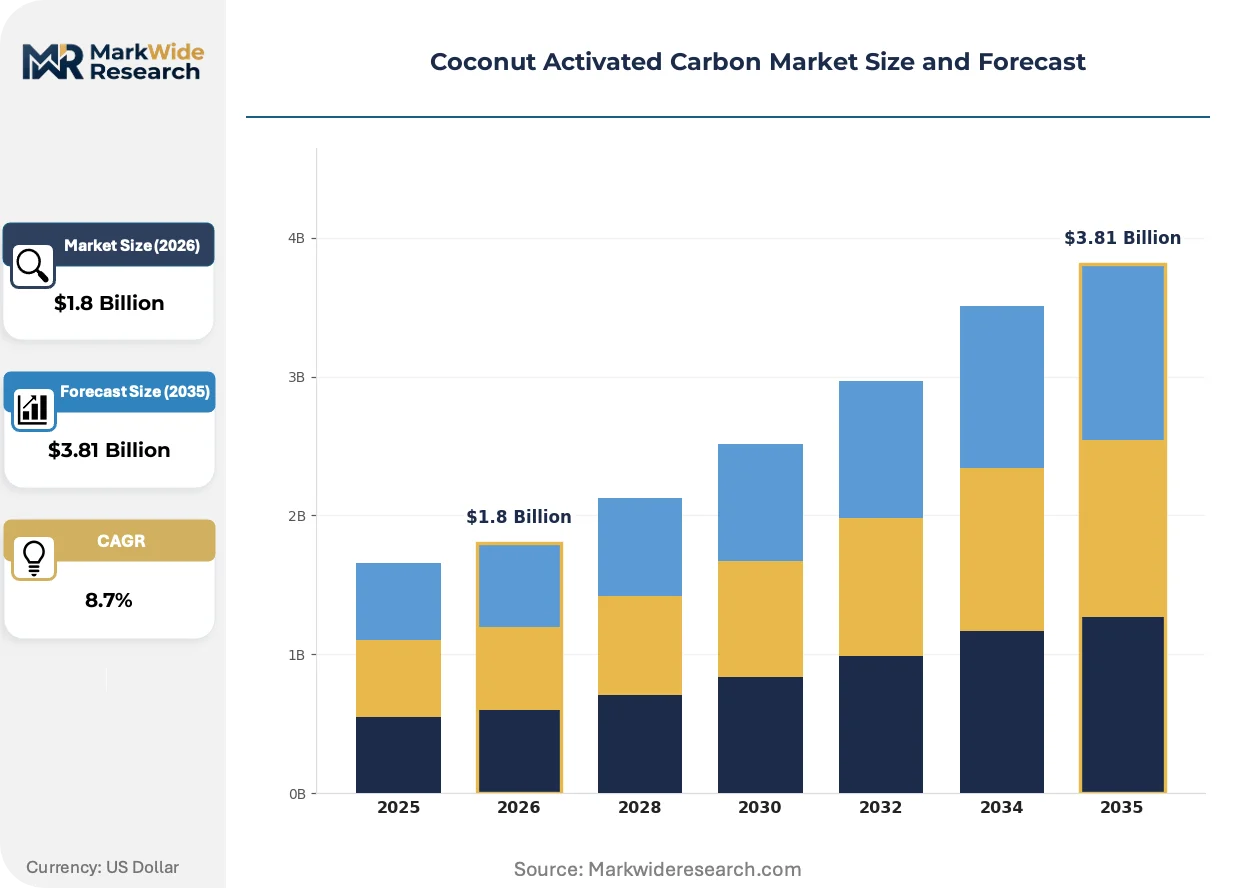
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Activated Carbon, Granular Activated Carbon, Extruded Activated Carbon, Coconut Shell Charcoal Application: Air Purification, Water Treatment, Food & Beverage Processing, Gold Recovery End User: Industrial Manufacturers, Environmental Services, Food Production Facilities, Healthcare Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Premium A.C. Corporation, Donau Carbon, Jacobi Carbons, Active Char Products, Philippine-Japan Active Carbon Corp, Haycarb, Boyce Carbon, Kalimati Carbon, Core Carbons, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Activated Carbon Market Emerging Trajectories
Steam activation process optimization and reactivation service models are compressing the total cost of ownership for high-volume industrial users. These shifts are altering how carbon is procured, consumed, and replenished across municipal and mining verticals.
Continuous rotary kiln steam activation is displacing batch processing in new Southeast Asian capacity installations. Indonesian producers adopting this technology achieve tighter iodine number consistency and reduced energy intensity per metric ton. Municipal procurement specifications in Germany and the Netherlands now favor suppliers with continuous kiln certification, marginalizing batch-processed inventory.
REACH registration requirements for activated carbon importers are tightening substance documentation obligations for European industrial users. The regulation forces supply chain visibility into pyrolysis feedstock origin and activation chemical inputs. German automotive coating operations and Belgian pharmaceutical manufacturers are consolidating supplier bases to reduce compliance audit burden.
Reactivation service contracts are displacing virgin carbon spot purchasing at North American industrial filtration accounts. Chemical processors in Texas and Ohio are outsourcing spent carbon thermal regeneration to specialized service providers with RCRA-permitted facilities. This model transfers capital burden from carbon inventory to treatment-as-a-service fees, compressing working capital requirements for mid-scale users.
Coconut Activated Carbon Market Segmentation
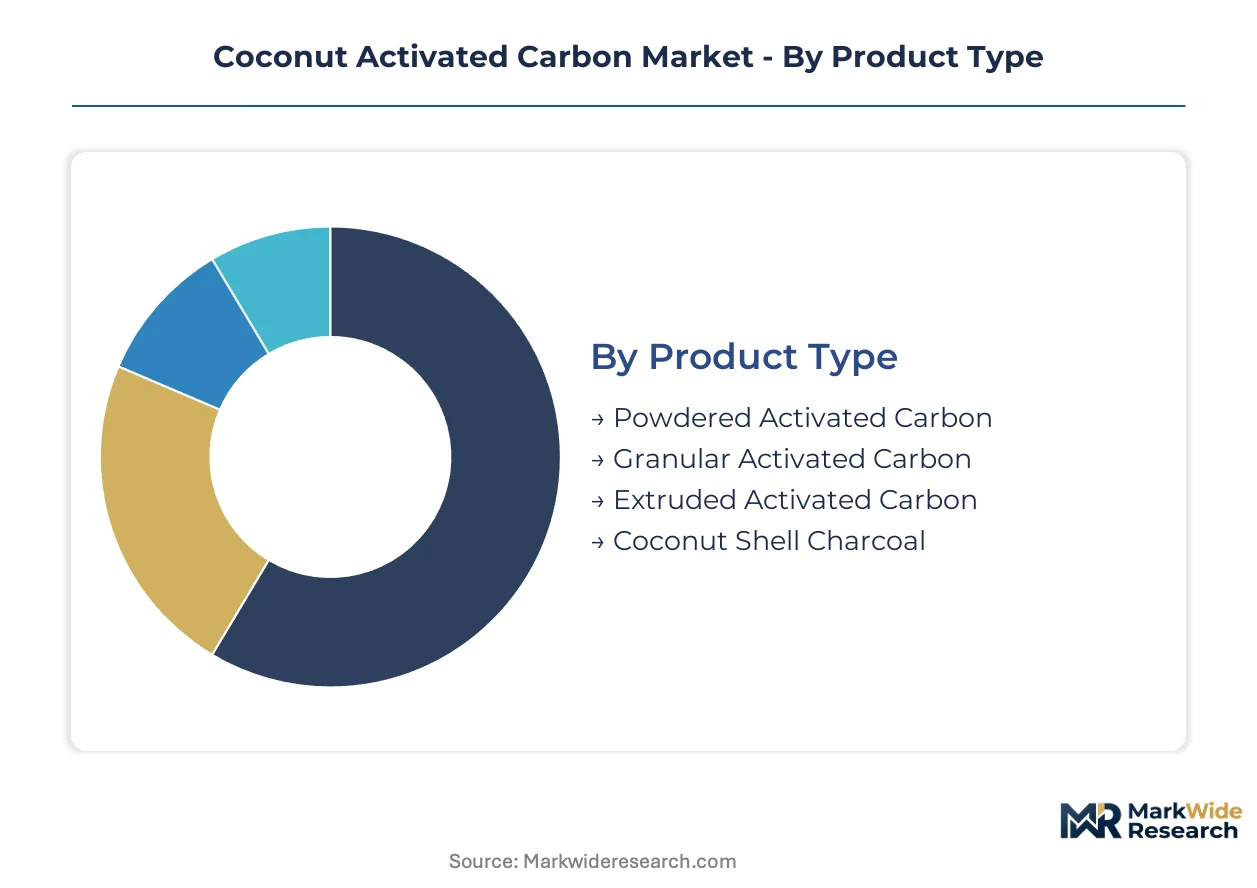
Segmentation in coconut activated carbon reveals divergent procurement economics between capital-intensive municipal infrastructure and episodic industrial demand. Product form and application specificity dictate channel selection, certification requirements, and reactivation service attachment rates.
Product Type:
Channel mix varies sharply by physical form: granular grades flow predominantly through direct sales to engineering contractors, while powdered variants reach seasonal users via distributor networks with spot purchasing flexibility.
- Granular Activated Carbon:Hard, irregular particles sized 0.2-5mm with iodine numbers exceeding 1,000 mg/g, engineered for fixed-bed adsorption systems. Demand concentrates in German and Dutch municipal water treatment infrastructure where continuous kiln certification is now mandatory. EPA Stage 2 DBP Rule compliance is forcing US surface water plants to expand granular bed capacity ahead of powdered dosing retrofits.
- Powdered Activated Carbon:Fine particles below 0.18mm optimized for rapid adsorption kinetics and seasonal taste-and-odor events. North American surface water utilities in Ohio and Texas are displacing historical alum coagulation with powdered carbon during cyanobacterial bloom periods, creating high-margin episodic demand spikes.
- Extruded Activated Carbon:Cylindrical pellets manufactured for low-pressure-drop gas-phase applications in industrial air streams.
- Coconut Shell Charcoal:Unactivated pyrolysis product serving metallurgical and traditional fuel markets in Southeast Asian domestic supply chains.
Granular Activated Carbon dominates installed base. Powdered Activated Carbon is where expansion concentrates for seasonal compliance flexibility.
Application:
Application mix determines margin structure: water treatment commands long-term service contracts while gold recovery sustains premium pricing through specialized attrition-resistant grades.
- Water Treatment:Potable and process water contaminant removal leveraging coconut carbon's micropore dominance for organic molecule capture. US municipal utilities face compressed loading cycles under EPA Stage 2 DBP Rule thresholds. Eastern European municipal systems are expanding activated carbon deployment under revised EU Drinking Water Directive mandates.
- Gold Recovery:Carbon-in-pulp and carbon-in-leach circuits requiring superior hardness and gold adsorption kinetics. African mining corridors in Ghana and Tanzania sustain premium-grade demand despite volatile commodity pricing.
- Air Purification:Industrial emission control and indoor air quality management, increasingly substituting coal-based carbon where micropore specificity matters less.
- Food & Beverage Processing:Decolorization and odor removal in sugar refining, edible oil purification, and alcoholic beverage production.
Water Treatment anchors volume. Gold Recovery commands the steepest expansion trajectory in value terms.
End User:
End user type shapes procurement sophistication: environmental services firms bundle reactivation capabilities while food producers prioritize NSF/ANSI 61 certification for ingredient contact approval.
- Industrial Manufacturers:Chemical processors and automotive coating operations with continuous filtration demand and RCRA-permitted spent carbon disposal requirements.
- Environmental Services:Specialized contractors providing mobile thermal reactivation and PFAS remediation at US Department of Defense sites.
- Food Production Facilities:Sugar refiners and edible oil processors requiring batch decolorization with strict food-grade certification.
- Healthcare Institutions:Pharmaceutical manufacturers and medical air purification systems with validated supply chain documentation under REACH.
Industrial Manufacturers represent the largest volume commitment. Environmental Services is gaining share fastest through treatment-as-a-service models.
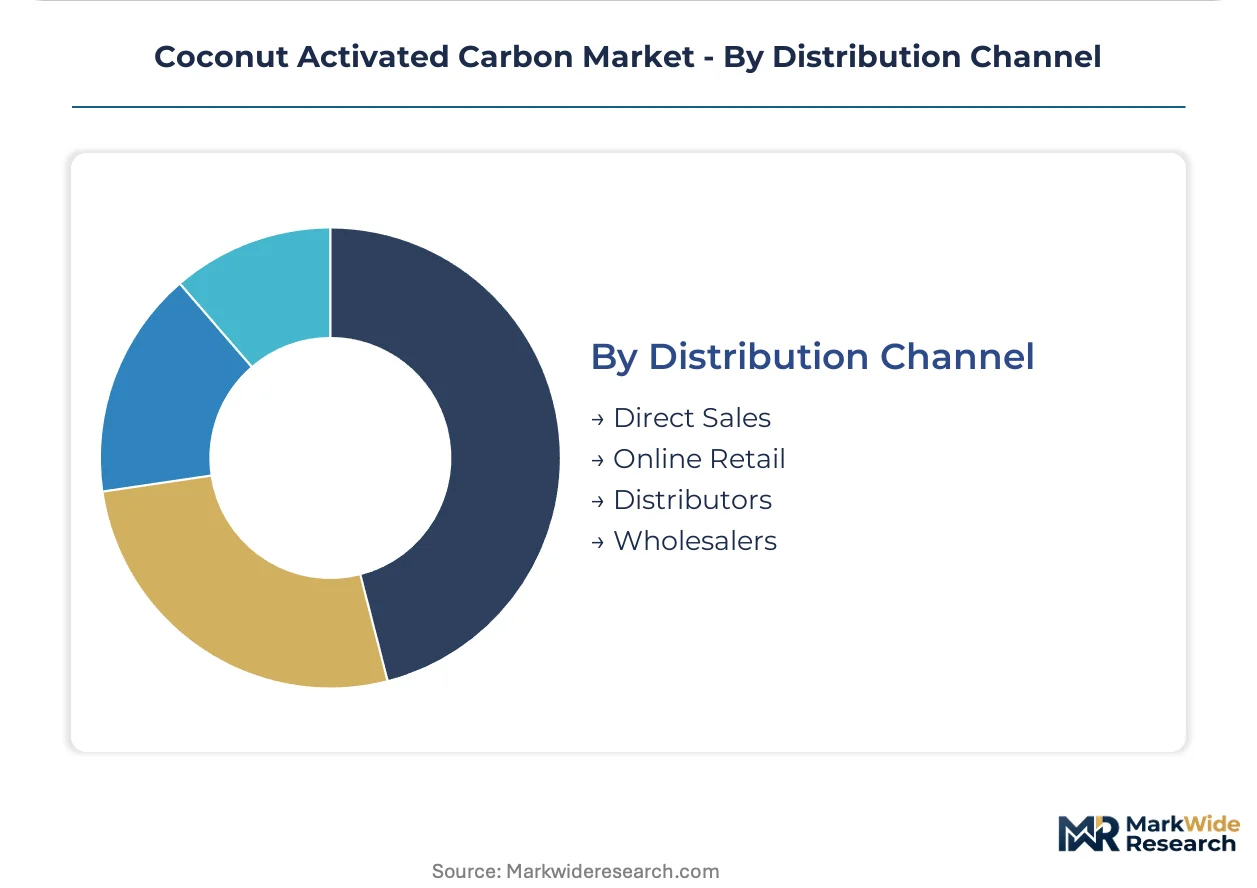
Distribution Channel:
Channel configuration reflects order scale and technical service intensity: direct sales capture engineered system contracts while distributors serve fragmented seasonal demand.
- Direct Sales:Manufacturer-to-end-user relationships for municipal water treatment infrastructure and large industrial filtration systems requiring embedded engineering support.
- Distributors:Regional inventory stocking for powdered carbon spot purchases and mid-scale industrial accounts without specialized handling capabilities.
- Wholesalers:Bulk volume aggregation for re-export and secondary processing in non-producing regions.
- Online Retail:Emerging channel for laboratory-scale quantities and replacement filter cartridges in consumer air purification devices.
Direct Sales commands the highest value per transaction. Distributors capture the broadest geographic reach for fragmented demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure anchors European activated carbon distribution, while the Trans-Siberian rail corridor links Southeast Asian feedstock to Russian industrial filtration demand.
United States
Municipal utilities in Ohio and Texas face compressed granular carbon loading cycles under EPA Stage 2 DBP Rule deadlines. The EPA mandates lower total organic carbon thresholds at surface water treatment plants. Houston's petrochemical corridor sustains industrial reactivation service demand through RCRA-permitted thermal regeneration facilities.
Germany
Ruhr Valley municipal water authorities specify continuous rotary kiln certification in procurement tenders. The EU Drinking Water Directive, enforced by ECHA guidance, tightens contaminant removal standards. Bavarian automotive coating operations consolidate supplier bases to reduce REACH registration audit burdens.
Philippines
Mindanao's integrated coconut processing clusters supply pyrolysis feedstock to carbon activation furnaces. Climatic disruption and competing copra demand tighten shell availability during peak harvest periods. Davao City's port infrastructure exports granular grades to European municipal contracts.
Indonesia
Sulawesi and Java-based producers adopt continuous rotary kiln technology for iodine number consistency. The country's national environmental regulator enforces industrial emission standards at activation facilities. Surabaya's manufacturing zone hosts expanding capacity installations serving Asian mining filtration demand.
Ghana
Gold mining corridors in Ashanti and Western regions sustain premium-grade carbon demand for carbon-in-pulp circuits. The country's minerals commission regulates cyanide handling protocols in extraction operations. Tarkwa's mining district anchors West African demand for attrition-resistant coconut carbon grades.
Coconut Activated Carbon Market Vendor Landscape
Concentration sits with vertically integrated feedstock-to-carbon producers commanding Southeast Asian supply chains. The vendor base spans three strategic tiers: plantation-integrated pyrolysis operators, specialized reactivation service providers, and regional distributor-assemblers. Capacity expansion and certification infrastructure investments represent the dominant competitive moves as NSF/ANSI 61 and continuous kiln standards narrow market access.
Among European-based technical service providers, Donau Carbon exemplifies the engineering-embedded sales model. Jacobi Carbons occupies a position within the plantation-integrated tier through its Sri Lankan operations. Haycarb represents the specialized premium-grade archetype serving African mining corridors with attrition-resistant formulations.
| Leading Market Players |
|---|
| Premium A.C. Corporation |
| Donau Carbon |
| Jacobi Carbons |
| Active Char Products |
| Philippine-Japan Active Carbon Corp |
| Haycarb |
| Boyce Carbon |
| Kalimati Carbon |
| Core Carbons |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Southeast Asian producers and European municipal utilities lock in both coconut shell feedstock access and granular carbon price visibility across multi-year procurement cycles. These arrangements insulate buyers from Philippine harvest volatility while securing activation furnace throughput for suppliers.
Pricing Analysis
Volume-discount tiering separates municipal utilities purchasing granular grades in bulk from industrial spot buyers of powdered carbon. Three-tier pricing structure across premium, standard, and economy levels tracks iodine number consistency and NSF/ANSI 61 certification status. Cost compression in standard grades is intensifying because Indonesian continuous kiln capacity is expanding faster than Mindanao shell supply. Municipal water authorities exhibit the lowest price sensitivity due to regulatory compliance mandates, while seasonal taste-and-odor users in North American surface water plants negotiate aggressively on spot powdered carbon.
Supply Chain Analysis
Inventory buffers at Rotterdam and Houston ports extend to twelve weeks, reflecting trans-Pacific shipping unreliability and seasonal Philippine harvest patterns. Production gravity centers on the Philippines, Indonesia, and Sri Lanka, where coconut shell pyrolysis feeds steam activation furnaces. The chain draws from copra processors, shipping lines, and reactivation service providers as critical inputs. Single-source vulnerability concentrates in Mindanao shell supply during El Niño drought cycles. Distribution runs through direct sales for municipal infrastructure and regional distributors for industrial spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and reactivation service models creates niche entry points as EPA and EU Drinking Water Directive mandates proliferate buyer archetypes with divergent technical requirements.
For Market Incumbents: Consolidate backward integration into Philippine coconut shell pyrolysis to defend against copra demand competition tightening feedstock access. Expand continuous rotary kiln certification coverage to capture German and Dutch municipal tenders that now exclude batch-processed inventory. Secure long-term offtake with North American reactivation service providers to lock in spent carbon volume before mobile thermal units achieve scale. For New Entrants and Emerging Players: Lead with PFAS remediation capabilities at US Department of Defense sites, where specialized handling protocols and RCRA permitting create barriers to incumbent carbon suppliers without hazardous waste infrastructure. Target Eastern European municipal systems under revised EU Drinking Water Directive mandates, where incumbent relationships remain less entrenched than in Western European markets. Deploy treatment-as-a-service contracting to bypass capital-intensive virgin carbon manufacturing. For Investors and Strategic Acquirers: Capital is best deployed toward reactivation service providers with RCRA-permitted facilities and mobile thermal unit fleets, given the model's working capital efficiency and recurring revenue profile. The five-to-ten year viability window favors asset-light service archetypes over capital-heavy virgin carbon expansion. Watch for EPA enforcement acceleration on PFAS maximum contaminant levels as the inflection signal for reactivation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive shell supply from Mindanao insulates Jacobi Carbons against copra competition and harvest volatility. |
| Continuous Kiln Certification | Rotary kiln validation opens German municipal tenders that exclude batch-processed Philippine inventory. |
| Reactivation Service Expansion | Mobile thermal units enable Donau Carbon to capture Texas chemical processor accounts from virgin carbon suppliers. |
| PFAS Handling Protocol Development | RCRA-permitted infrastructure positions Haycarb for US Department of Defense remediation contracts. |
| NSF/ANSI 61 Certification Investment | Testing infrastructure unlocks North American municipal procurement previously closed to uncertified Indonesian producers. |
Methodological Framework
Operator-level perspectives from municipal water treatment engineers, coconut shell pyrolysis plant managers, gold mining metallurgists, and reactivation service technicians anchored the qualitative base. Primary interviews triangulated against customs data from Philippine and Indonesian export authorities, EPA enforcement action databases, and EU Drinking Water Directive implementation reports. Bottom-up activation furnace capacity estimates and top-down municipal procurement budget analysis cross-validated volume assumptions.
Sensitivity analysis tested forecast outputs against Philippine copra price volatility, continuous kiln adoption rates, and PFAS regulatory enforcement scenarios across the analysis window. Segmentation modeling tracked product form, application vertical, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from installed base expansion rates, replacement cycle compression under tightened organic carbon thresholds, and reactivation service penetration curves. Gold recovery demand and municipal infrastructure retrofit timelines served as industry-specific demand drivers.
The analysis sits within stated boundaries; outcomes outside sustained EPA Stage 2 DBP Rule enforcement or accelerated EU Drinking Water Directive implementation would require recalibration. Forecasts reflect documented assumptions about shell feedstock availability, activation energy costs, and certification infrastructure investment. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Military Lighting Market
Others
Asia-Pacific Camping and Caravanning Market
Others
Android STB and TV Market
Others
Global Hardware Acceleration Market
Others
Lined Tank Market
Others
US Automotive LED Lighting Market
Others
Turbo Mills Market
Others
Gesture Recognition for Smart TV Market
Others
Pet Care Packaging Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
Programmatic Display Market
Others
DNA Data Storage Market
Others
US Cat Food Market
Others
Global Animal Feed Protein Ingredients Market
Others
Tanned Fish Skin Leather Market
Others
Europe Electric Forklift Market