
 Technical Films Market | 2026-2036
Technical Films Market Size, Share, and Industry Trends Forecast 2026-2036
Technical Films Market Outlook
Software-defined coating specifications is restructuring how technical films are specified and procured, shifting value from commodity resin supply to tunable surface functionality. DuPont leverages its fluoropolymer expertise to sustain premium positioning in semiconductor-grade films. Toray Industries anchors Japanese supply chains for optical-grade PET substrates used in display stacks. 3M competes through adhesive-film integration that reduces downstream assembly steps for electronics OEMs.
Technical films are engineered polymer substrates typically ranging from 1 to 500 micrometers in thickness, manufactured through cast extrusion, biaxial orientation, or solution coating processes to deliver controlled barrier, optical, electrical, or mechanical properties for industrial applications. Polyethylene films dominate volume in agricultural and general packaging applications where cost efficiency and moisture resistance matter most. PET films command margin pools in electronics and automotive sectors due to dimensional stability and optical clarity requirements. Polypropylene grades are gaining ground in food packaging as retort and microwaveable formats expand.
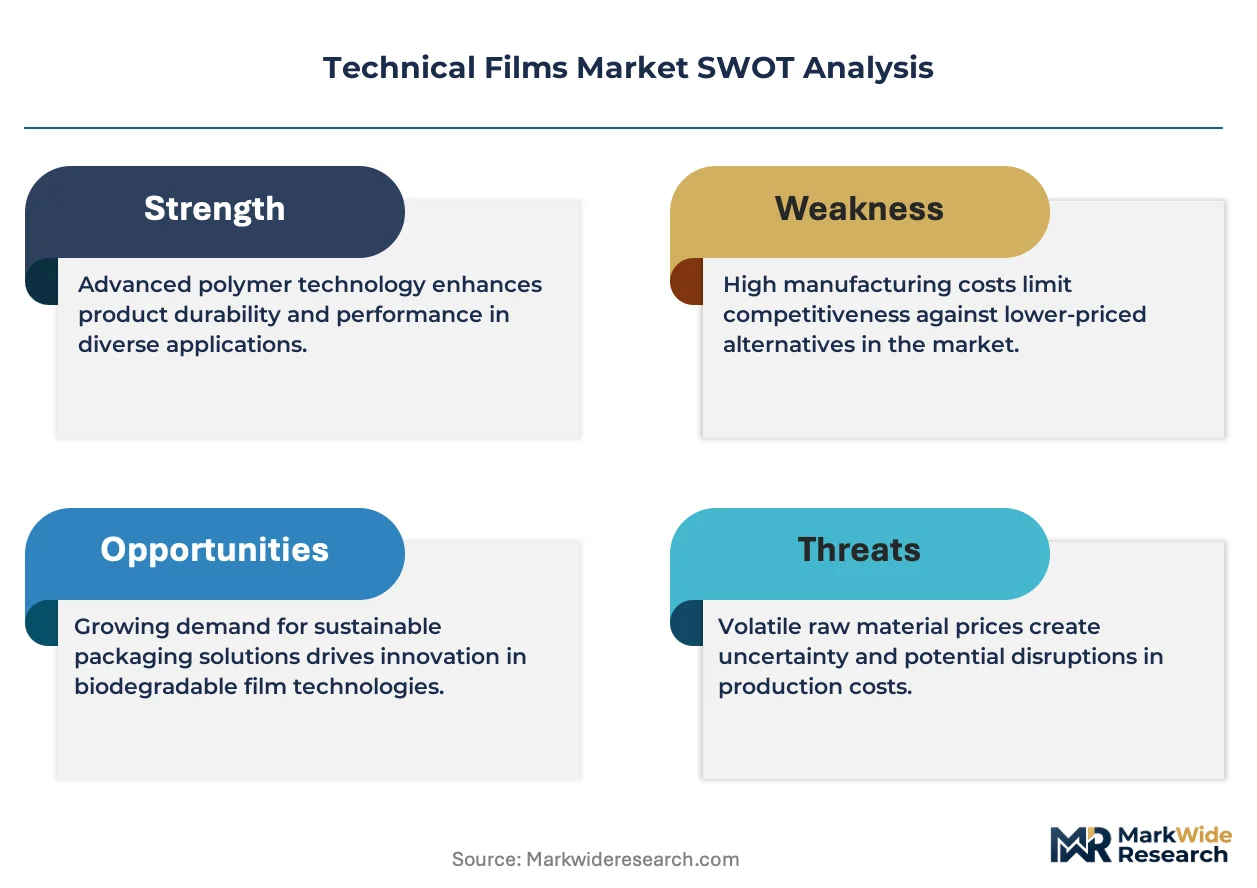
REACH restrictions on phthalate plasticizers and perfluorinated compounds are forcing PVC and fluoropolymer film producers to reformulate additive packages, while FDA compliance for food-contact layers shapes resin selection and migration testing protocols for packaging films. EU Green Deal packaging waste directives and emerging state-level extended producer responsibility frameworks in the US are redirecting R&D toward mono-material and chemically recyclable constructions. Stakeholders must monitor how regulatory timelines for recycled content mandates intersect with available mechanical and advanced recycling feedstock quality.
Market Dynamics
Flexible OLED panel manufacturing is concentrating technical film demand into China while REACH and FDA compliance costs are fragmenting supplier bases across Europe and North America.
Growth Catalysts
- Barrier Film Performance:Water vapor transmission rate specifications below 10^-6 g/m²/day enable foldable display commercialization. Electronics OEMs in South Korea and China are qualifying new substrate grades.
- EU Green Deal Packaging Directives:Recycled content mandates for 2030 are accelerating mono-material film R&D. Packaging converters are redesigning multilayer constructions to meet EPR frameworks.
- China:Domestic OLED fab capacity expansion is pulling optical-grade PET and polyimide substrate volume. NMPA medical device registrations are opening diagnostic film applications.
Market Restraints
- Specialty Resin Concentration:Semiconductor-grade fluoropolymer feedstock relies on Japanese and US chemical producers. Geopolitical friction threatens supply continuity for 5G and EV battery films.
- REACH Reformulation Costs:Phthalate and PFAS restrictions force PVC and fluoropolymer producers to validate alternative plasticizers. Migration testing timelines extend 18-24 months.
- Technical Limitation:Transparent conductive oxide sputtering onto polymer substrates suffers from cracking at sub-50 micrometer thicknesses. Flexible electronics yields remain depressed.
Strategic Opportunities
- India:PLI scheme subsidies for electronics manufacturing are attracting display module assembly. Technical film distributors are establishing local slitting and converting operations.
- Solid-State Battery Interfaces:Ceramic-polymer composite films for lithium-metal anode stabilization represent uncontracted demand. Material suppliers with dry-room processing capability hold first-mover advantage.
- ISO 13485 Certification:Medical device film qualification opens recurring revenue streams. Diagnostic test strip and wearable sensor applications require biocompatible substrate validation.
Industry Challenges
- Coating Process Engineering Talent:Solution casting and atomic layer deposition expertise concentrates in Japan and Germany. Emerging market producers face 3-5 year skill development cycles.
- Cleanroom Capex Intensity:Class 1000 environments for semiconductor-grade film production require $50-100 million per production line. Financing constraints limit mid-cap expansion.
- Dual Certification Timelines:Concurrent FDA 510(k) and EU MDR submissions for medical films extend approval windows. Regulatory strategy misalignment delays market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Technical Films Market |
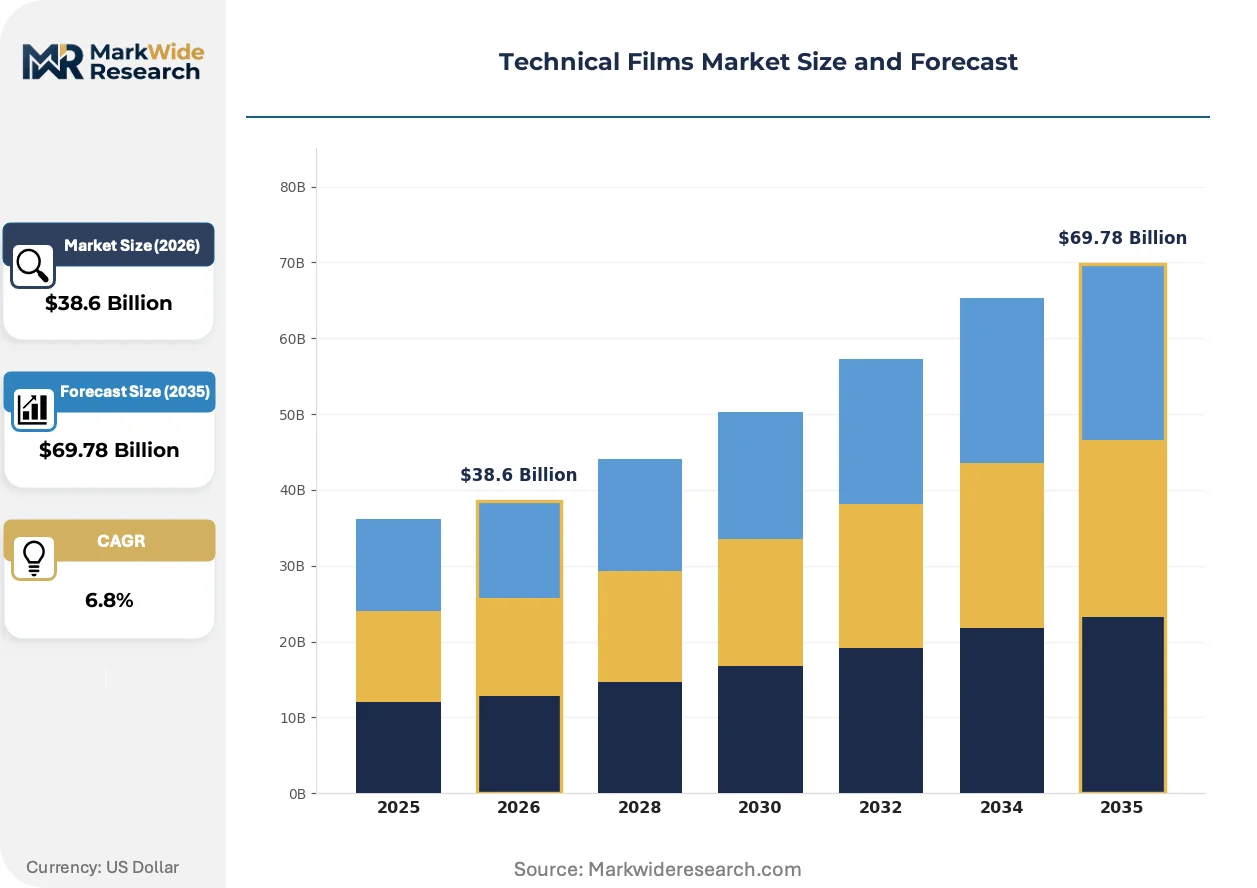
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, PVC, PET, Polypropylene Application: Packaging, Automotive, Electronics, Agriculture End User: Manufacturers, Retailers, OEMs, Distributors Distribution Channel: Online, Direct Sales, Wholesalers, Brokers |
| Companies Covered | DuPont, Toray Industries, 3M, Mitsubishi Chemical, Saint-Gobain, Berry Global, Nitto Denko, SABIC, Cosmo Films, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Technical Films Market Strategic Shifts
Technical film specification is migrating from commodity resin catalogs to tunable surface functionality platforms, compressing traditional material selection cycles and elevating coating chemistry expertise.
Atomic layer deposition barrier coatings are decentralizing vacuum metallization's dominance in high-performance packaging. Food and pharmaceutical converters are adopting ALD-equipped roll-to-roll lines at pilot scale. The technology is decentralizing barrier performance from aluminum foil and metallized PET toward transparent, microwaveable, and chemically recyclable alternatives.
REACH restrictions on per- and polyfluoroalkyl substances are forcing fluoropolymer film producers to eliminate C6 and C8 chemistries from process aids and surface treatments. ECHA substance evaluation timelines are compressing reformulation windows to 24-36 months. Medical and semiconductor packaging segments are accelerating qualification of fluorine-free barrier alternatives.
Electronics OEMs are consolidating technical film procurement under direct material qualification programs, bypassing traditional distributor inventory positions. Tier-1 display and battery manufacturers are requiring substrate suppliers to co-locate technical service engineers at fabrication sites. The shift is most visible in China's Yangtze River Delta, where panel producers operate vendor-managed inventory hubs.
Technical Films Market Segmentation
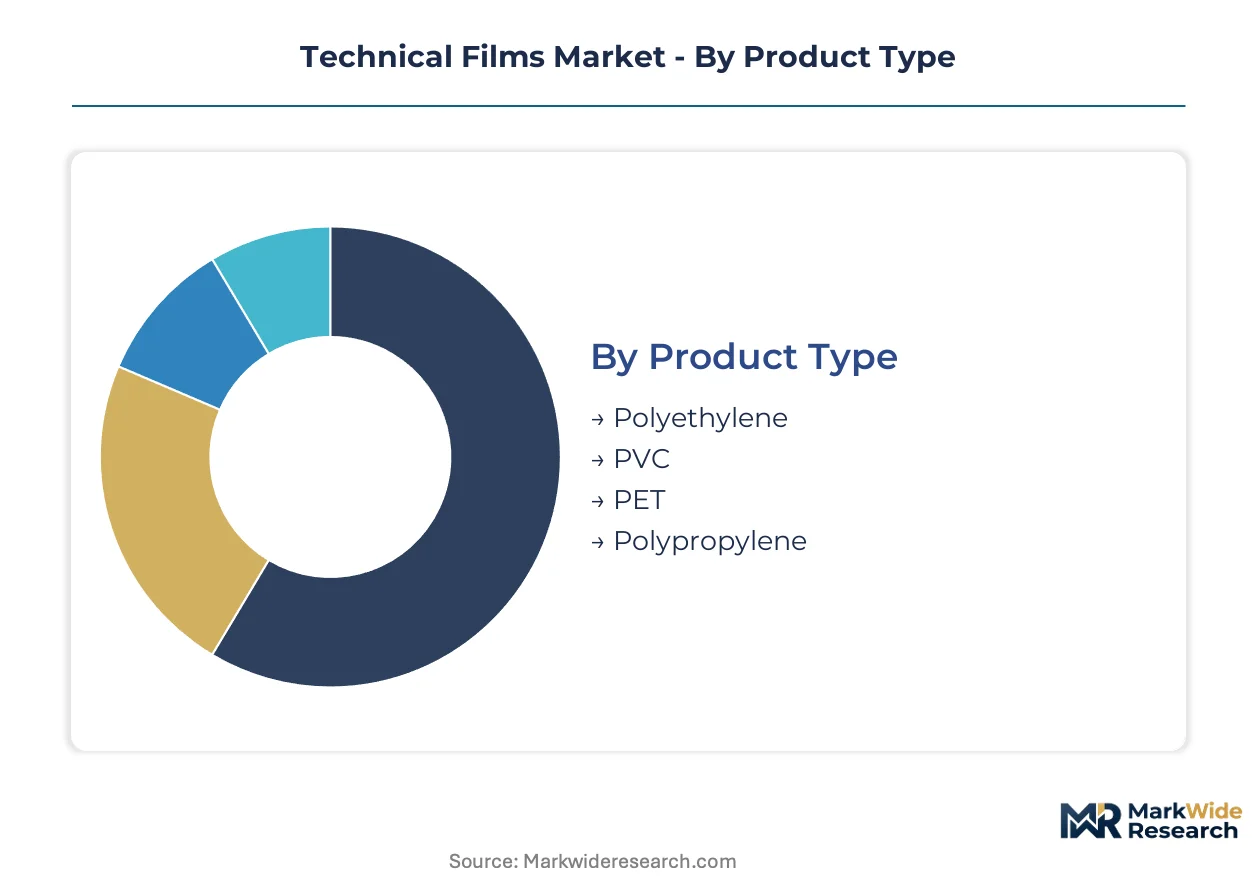
Technical film procurement patterns diverge sharply across resin chemistry, end-use performance requirements, and channel relationships. Buyers in electronics and automotive sectors prioritize dimensional stability and cleanroom certification over unit cost, while packaging converters optimize for throughput compatibility and regulatory compliance.
Product Type:
Buyers differentiate primarily by thermal tolerance, optical clarity, and barrier performance specifications rather than commodity resin pricing.
- Polyethylene:Low-density and linear-low-density grades dominate agricultural mulch and general packaging through moisture resistance and processability. Cost-sensitive food packaging converters in India and Southeast Asia are expanding blown film capacity for flexible pouch formats.
- PET:Biaxially oriented polyester films deliver dimensional stability and optical clarity critical for display substrates and automotive interiors. Electronics manufacturers in South Korea and China are qualifying thicker gauge grades for foldable OLED encapsulation.
- Polypropylene:Cast and oriented PP grades offer heat resistance for retort and microwaveable food packaging. European converters are redesigning multilayer structures to meet EU Green Deal mono-material recyclability mandates.
- PVC:Calendered and extruded vinyl films serve medical device packaging and industrial tape backings. REACH phthalate restrictions are forcing reformulation of plasticizer packages with 18-24 month migration testing timelines.
Polyethylene leads volumes today; PET is gaining share fastest in value terms.
Application:
End-use performance thresholds create distinct procurement behaviors, with semiconductor-grade specifications commanding 10-20x premiums over commodity packaging grades.
- Packaging:Food, pharmaceutical, and consumer goods films range from commodity LDPE to high-barrier metallized and ALD-coated constructions. Extended producer responsibility frameworks in Germany and France are accelerating mono-material design adoption.
- Electronics:Optical-grade PET and polyimide substrates for displays, batteries, and flexible circuits require Class 1000 cleanroom production. Domestic OLED fab expansion in China is pulling substrate volume from Japanese and Korean suppliers.
- Automotive:Interior trim films, battery separator substrates, and HUD optical stacks demand UV stability and flame retardancy. German and US automakers are qualifying thinner gauge grades to reduce vehicle weight.
- Agriculture:Greenhouse and mulch films prioritize UV stabilization and mechanical durability over optical precision. Indian and Brazilian growers are adopting longer-life formulations to reduce seasonal replacement labor.
Packaging commands the largest volume position; electronics applications are expanding most quickly.
End User:
Procurement sophistication varies by technical qualification capability and direct supplier relationship depth.
- OEMs:Tier-1 electronics and automotive manufacturers operate direct material qualification programs with co-located technical service engineers. Panel producers in China's Yangtze River Delta are consolidating procurement under vendor-managed inventory hubs.
- Manufacturers:Mid-cap converters and component fabricators rely on distributor technical support for grade selection and slitting optimization. Indian electronics assembly operations under PLI scheme subsidies are establishing local converting partnerships.
- Distributors:Specialized film distributors add value through precision slitting, inventory positioning, and regulatory documentation. Medical device distributors in the US and EU are building ISO 13485-certified warehousing capacity.
- Retailers:Private-label packaging film procurement concentrates volume for standard gauge polyethylene and polypropylene grades. Large European retail chains are imposing recycled content requirements on flexible packaging suppliers.
OEMs drive premium segment development; manufacturers represent the broadest addressable base.
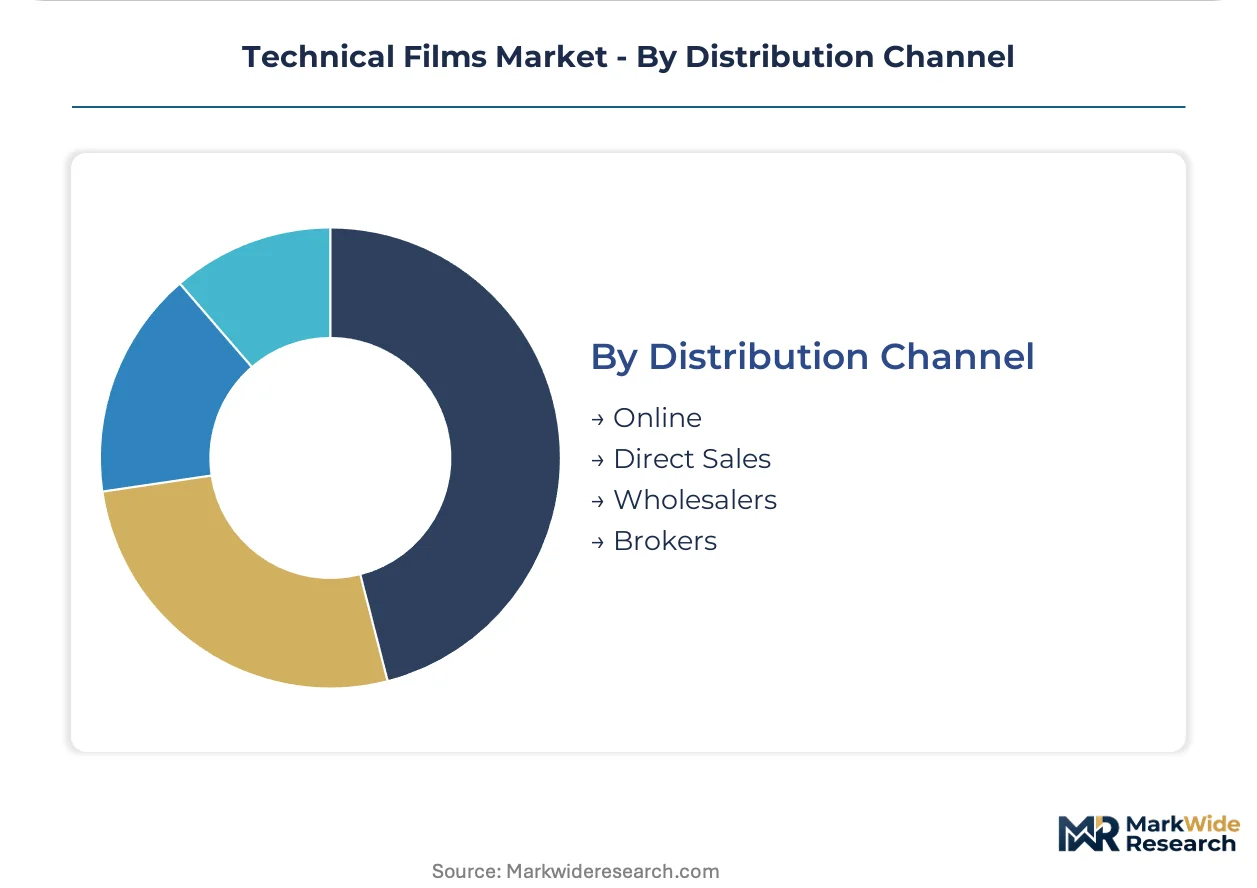
Distribution Channel:
Channel selection reflects order fragmentation, technical service intensity, and geographic proximity to converting operations.
- Direct Sales:Large-volume electronics and automotive OEMs contract directly with resin producers and major film manufacturers for annual volume commitments. Korean display panel makers are negotiating multi-year substrate supply agreements with Japanese PET producers.
- Wholesalers:Regional distributors serve mid-volume converters with stocked slit rolls and technical application support. German and Italian packaging converters rely on wholesaler networks for just-in-time PE and PP supply.
- Online:E-procurement platforms are penetrating standard gauge commodity grades for small-batch and prototype orders. Indian and Southeast Asian converters are adopting digital channels for price discovery and spot purchasing.
- Brokers:Surplus and secondary market channels liquidate off-spec and obsolete inventory from converter operations. Brokers concentrate in regions with dense flexible packaging production clusters.
Direct sales capture the highest value contracts; online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's OLED fab expansion pulls substrate volume faster than Germany's automotive electrification reshapes film specifications, yet both geographies tighten purity standards under divergent regulatory timelines.
China
Domestic display panel manufacturing concentrates demand for optical-grade PET and polyimide substrates in the Yangtze River Delta. NMPA medical device registrations accelerate diagnostic film applications beyond traditional electronics. BOE and TCL CSOT operate vendor-managed inventory hubs in Suzhou and Hefei, compressing supplier response times.
United States
Semiconductor packaging and EV battery separator films drive fluoropolymer and ceramic-polymer composite demand. FDA material safety standards for food-contact layers shape migration testing protocols for packaging converters. Cleanroom production clusters in Arizona and Texas attract Japanese substrate suppliers establishing technical service operations.
Germany
Automotive interior trim and HUD optical stacks require UV-stable, flame-retardant PET grades as OEMs qualify thinner gauges. EU Green Deal packaging waste directives and EPR frameworks accelerate mono-material film R&D. Stuttgart and Munich host converter networks redesigning multilayer constructions for chemical recyclability.
Japan
Semiconductor-grade fluoropolymer feedstock and optical-grade PET substrate production anchor global supply chains. METI industrial policy supports atomic layer deposition barrier coating commercialization. Chubu and Kansai regions concentrate solution casting expertise that emerging market producers struggle to replicate.
South Korea
Flexible OLED panel manufacturers qualify new barrier film grades with water vapor transmission rates below 10^-6 g/m²/day. MFDS pharmaceutical packaging regulations align with FDA timelines for export-oriented converters. Gyeonggi Province hosts Samsung Display and LG Display procurement consolidation under direct material qualification programs.
Technical Films Market Competitive Environment
Top-tier vendors anchor premium semiconductor and display-grade substrate supply, while mid-cap regional converters compete on slitting precision and regulatory documentation speed. The vendor base stratifies across resin producers with captive film extrusion, independent film manufacturers with coating specialization, and distributors adding value through inventory positioning and technical service. Strategic moves concentrate on backward integration into specialty resin supply and geographic co-location with tier-1 OEM fabrication sites.
Among diversified chemical conglomerates with film divisions, DuPont and Toray Industries occupy positions exemplifying fluoropolymer expertise and optical-grade PET substrate leadership respectively. 3M sits within the adhesive-film integration archetype that reduces downstream assembly steps for electronics OEMs. These three anchors represent distinct competitive vectors: materials science depth, display supply chain anchoring, and adhesive-system integration.
| Leading Market Players |
|---|
| DuPont |
| Toray Industries |
| 3M |
| Mitsubishi Chemical |
| Saint-Gobain |
| Berry Global |
| Nitto Denko |
| SABIC |
| Cosmo Films |
| Others |
Value Chain & Pricing Dynamics
Solution casting and atomic layer deposition expertise concentrated in Japan and Germany feeds labor-cost differentials that widen pricing-tier spreads between semiconductor-grade substrates and commodity packaging films.
Pricing Analysis
Capacity additions in China are reshaping price floors for optical-grade PET substrates as domestic OLED fab expansion pulls volume from established Japanese suppliers. Three-tier pricing structure across semiconductor-grade, industrial-performance, and commodity packaging levels separates buyers by cleanroom certification requirements and barrier performance specifications. Cost compression in standard gauge polyethylene runs through Indian and Southeast Asian blown film capacity expansion. Packaging converters represent the most price-sensitive segment, while electronics OEMs absorb premiums for dimensional stability and optical clarity.
Supply Chain Analysis
Dual-sourcing requirements from tier-1 display manufacturers mandate multi-supplier qualification for fluoropolymer feedstock and optical-grade PET substrates across Japan, South Korea, and the United States. Specialty resin production draws from Japanese and US chemical producers, with ceramic-polymer composite precursors sourced from German and Japanese suppliers. Single-source vulnerability concentrates in semiconductor-grade fluoropolymer feedstock threatened by geopolitical friction. Distribution runs through vendor-managed inventory hubs co-located with panel producers in China's Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as flexible OLED commercialization shifts procurement toward water vapor transmission rate specifications below 10^-6 g/m²/day.
For Market Incumbents: Deploy backward integration into specialty resin supply to secure fluoropolymer feedstock continuity threatened by REACH reformulation timelines. Anchor premium positioning through ISO 13485 certification for medical device film applications. Co-locate technical service engineers at tier-1 OEM fabrication sites in South Korea and China to defend against distributor disintermediation. For New Entrants and Emerging Players: Enter via solid-state battery interface films for lithium-metal anode stabilization, where uncontracted demand and dry-room processing capability gaps create first-mover windows. Target India's PLI scheme-subsidized electronics assembly operations for local slitting and converting partnerships. Qualify fluorine-free barrier alternatives ahead of ECHA substance evaluation timelines to bypass incumbent reformulation cycles. For Investors and Strategic Acquirers: Chemical conglomerates with captive film extrusion capability are the most active acquirer in this space, seeking coating chemistry expertise to compress material selection cycles. Five-to-ten-year viability hinges on atomic layer deposition barrier coating commercialization. Monitor NMPA medical device registration acceleration in China as inflection indicator for diagnostic film application expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resin Supply | DuPont leverages fluoropolymer expertise to secure semiconductor-grade feedstock continuity against REACH restrictions. |
| Atomic Layer Deposition Commercialization | Toray Industries anchors Japanese supply chains as food and pharmaceutical converters adopt ALD-equipped roll-to-roll lines. |
| ISO 13485 Certification Investment | Medical device distributors build certified warehousing capacity to capture recurring revenue from diagnostic test strip applications. |
| Geographic Co-location with OEM Fabrication Sites | BOE and TCL CSOT operate vendor-managed inventory hubs in Suzhou and Hefei, compressing supplier response times. |
| Fluorine-Free Barrier Qualification | ECHA substance evaluation timelines compress reformulation windows to 24-36 months for medical and semiconductor packaging segments. |
Study Parameters
Coverage spans Asia-Pacific, North America, and Europe, with primary inputs from each region combining interviews with plant managers at film extrusion facilities, procurement leads at electronics OEMs, distribution channel partners, and technical R&D directors with secondary validation from customs and trade data, SEC filings, and industry association reports. Bottom-up and top-down triangulation reconciles capacity announcements with end-use demand modeling.
Rate-of-change decomposition across the analysis window segments volume and value by resin chemistry, end-use performance tier, cleanroom certification level, and regional production hub. CAGRs derive from regression against OLED panel shipment forecasts, battery separator substrate adoption curves, and EU Green Deal packaging waste directive compliance timelines. Modeled inputs include barrier film water vapor transmission rate qualification cycles and migration testing duration for phthalate-free plasticizer alternatives.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-time OLED fab yield data and solid-state battery commercialization timelines introduce uncertainty bands around high-performance substrate demand projections. Deviation in ECHA substance evaluation acceleration or NMPA medical device registration pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Nutricosmetics Market
Others
Roasted Wheat Market
Others
Space Cables Market
Others
Industrial Computers Market
Others
Military Wearable Market
Others
TWS Micro-Battery Market
Others
Latin America Automotive HVAC Market
Others
Solar Animal Repellent Market
Others
Trusted Platform Module (TPM) Market
Others
Global Molded Plastics Market
Others
AI in Home Automation Market
Others
Printing Machines Market
Others
Binoculars and Mounting Solutions Market
Others
Global Pregnancy Tracker Apps Market
Others
Calcined Petroleum Coke Market
Others
Global Personal Care Packaging Market