
 Silicone Molding Machinery Market | 2026-2036
Silicone Molding Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Molding Machinery Market Insights
The performance gap between precision electric presses and standard hydraulic units is broadening. Engel Austria GmbH leverages all-electric architecture for medical-grade cleanroom applications, while Haitian International Holdings anchors volume production through cost-optimized hydraulic platforms in Asia. KraussMaffei competes with hybrid systems that bridge energy efficiency and clamping force for automotive suppliers.
Silicone molding machinery encompasses injection, compression, transfer, and blow molding systems engineered to process liquid silicone rubber and high-consistency rubber at temperatures between 150°C and 200°C with precise cavity pressure control, serving industries that require biocompatible, thermally stable, or electrically insulating components. Injection molding equipment captures the dominant share of capital expenditure as medical device and automotive electronics manufacturers prioritize repeatability and flash reduction. Electric technology installations are expanding fastest in regulated environments where energy consumption reporting and cleanroom compatibility constrain hydraulic alternatives.
FDA device regulations, EU MDR conformity requirements, and ISO 13485 quality management standards collectively mandate process validation documentation and equipment qualification protocols that elevate total cost of ownership for machinery purchasers. REACH restrictions on platinum catalyst handling and volatile silicone emissions further shape regional equipment specifications and supplier certification burdens. Stakeholders must weigh electrification investments against retrofit flexibility as regulatory timelines compress for medical and automotive qualification cycles.
Market Dynamics
Medical device OEMs are consolidating supplier relationships around machinery vendors capable of delivering validated cleanroom-compatible systems with full FDA 21 CFR Part 11 documentation packages, compressing qualification timelines from 18 months to under 12 months for implantable silicone components.
Growth Catalysts
- EU MDR conformity mandates:European medical device manufacturers must replace legacy hydraulic presses with electric systems capable of process parameter traceability, accelerating capital expenditure cycles for Class III implantable device production lines.
- Automotive electronics sealing demand:Electric vehicle battery pack manufacturers require liquid silicone rubber gaskets with thermal runaway containment properties, driving injection molding machinery orders for high-cavitation tooling.
- Platinum catalyst recovery systems:Advanced vacuum degassing and closed-loop material handling technologies reduce volatile methyl siloxane emissions while capturing precious metal catalyst residue, aligning with ECHA REACH enforcement priorities in Germany and Switzerland.
Market Restraints
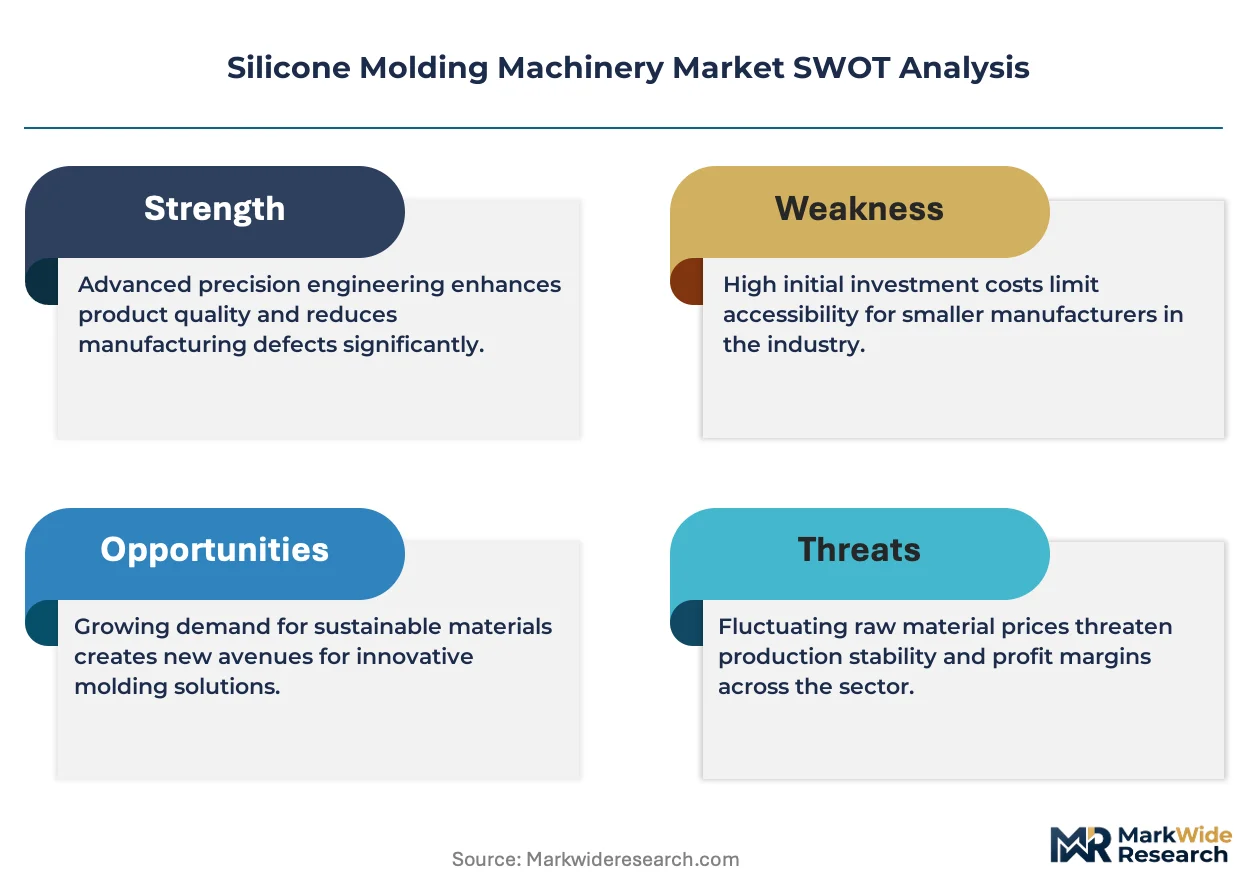
- Platinum group metal price volatility:Liquid silicone rubber formulations depend on platinum catalysts priced on London Metal Exchange benchmarks, creating 15-20% raw material cost swings that machinery purchasers cannot pass through in fixed-price equipment contracts.
- Precision component supply concentration:Servo motor drives and linear motion systems for all-electric presses source primarily from Japanese and German component specialists, exposing OEMs to 26-week lead times during semiconductor foundry allocation constraints.
- Technical limitation in multi-material processing:Existing clamping unit architectures struggle to maintain cavity pressure stability below 0.5% variance when alternating between liquid silicone rubber and thermoplastic substrates in two-shot medical device applications.
Strategic Opportunities
- Saudi Arabia healthcare localization:SFDA medical device manufacturing incentives under Vision 2030 create first-mover advantage for machinery vendors establishing regional technical centers with Arabic-language validation documentation capabilities.
- Wearable biosensor integration:Convergence of microfluidic channel molding with stretchable silicone substrates enables continuous glucose monitoring patch production, opening equipment specifications previously served by semiconductor packaging tools.
- US IRA clean manufacturing credits:Domestic content bonuses for medical device production equipment incentivize reshoring of silicone molding capacity from Asian contract manufacturers to FDA-registered US facilities.
Industry Challenges
- Process validation engineer scarcity:ISO 13485-qualified personnel capable of executing installation qualification, operational qualification, and performance qualification protocols command 40% salary premiums, constraining machinery vendor field service expansion.
- Legacy SCADA integration complexity:Brownfield pharmaceutical manufacturing sites operate 1990s-era distributed control systems with proprietary communication protocols, requiring custom middleware development for electric press data acquisition.
- Patent thickets in cold runner technology:Cross-licensing disputes between European and North American mold component suppliers delay introduction of valve-gate systems with independent temperature control zones for multi-cavity medical molding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Molding Machinery Market |
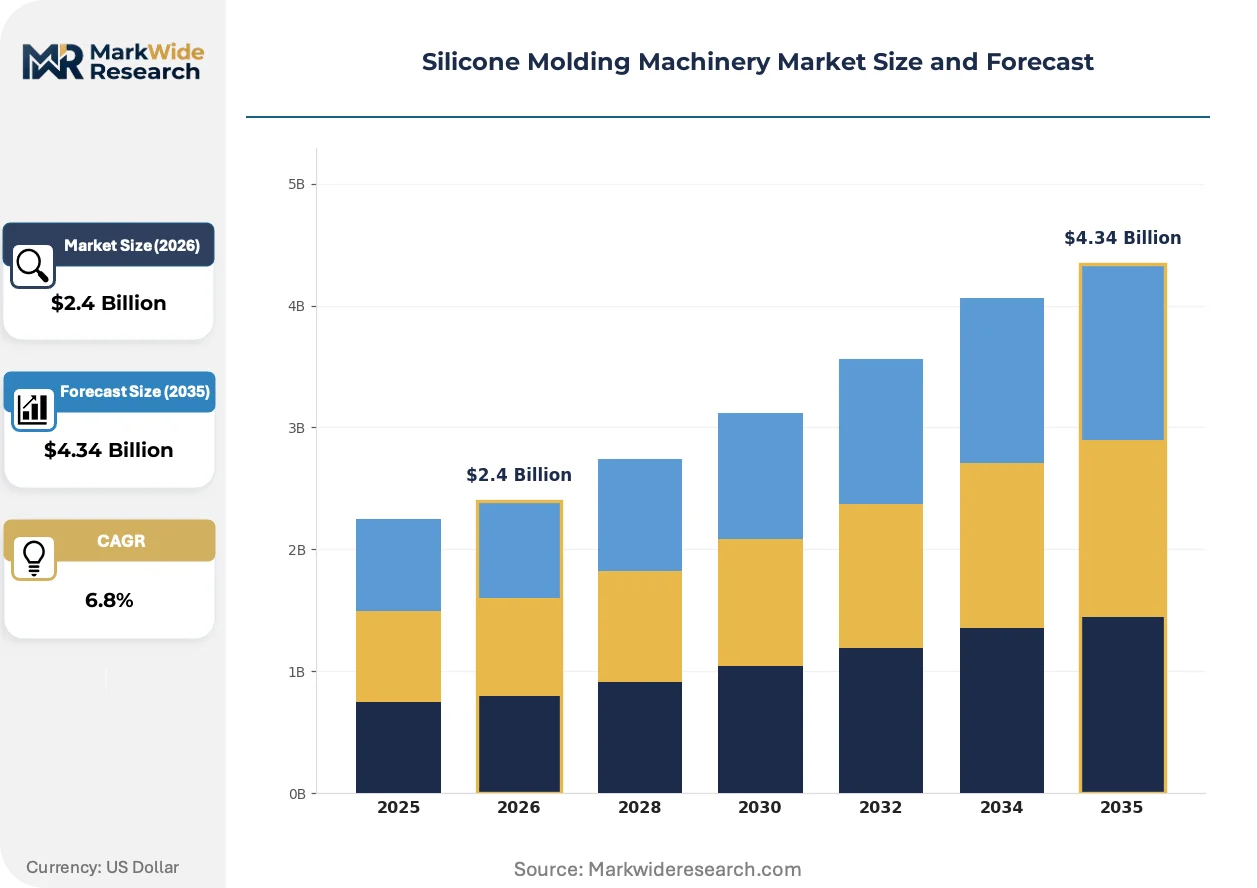
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
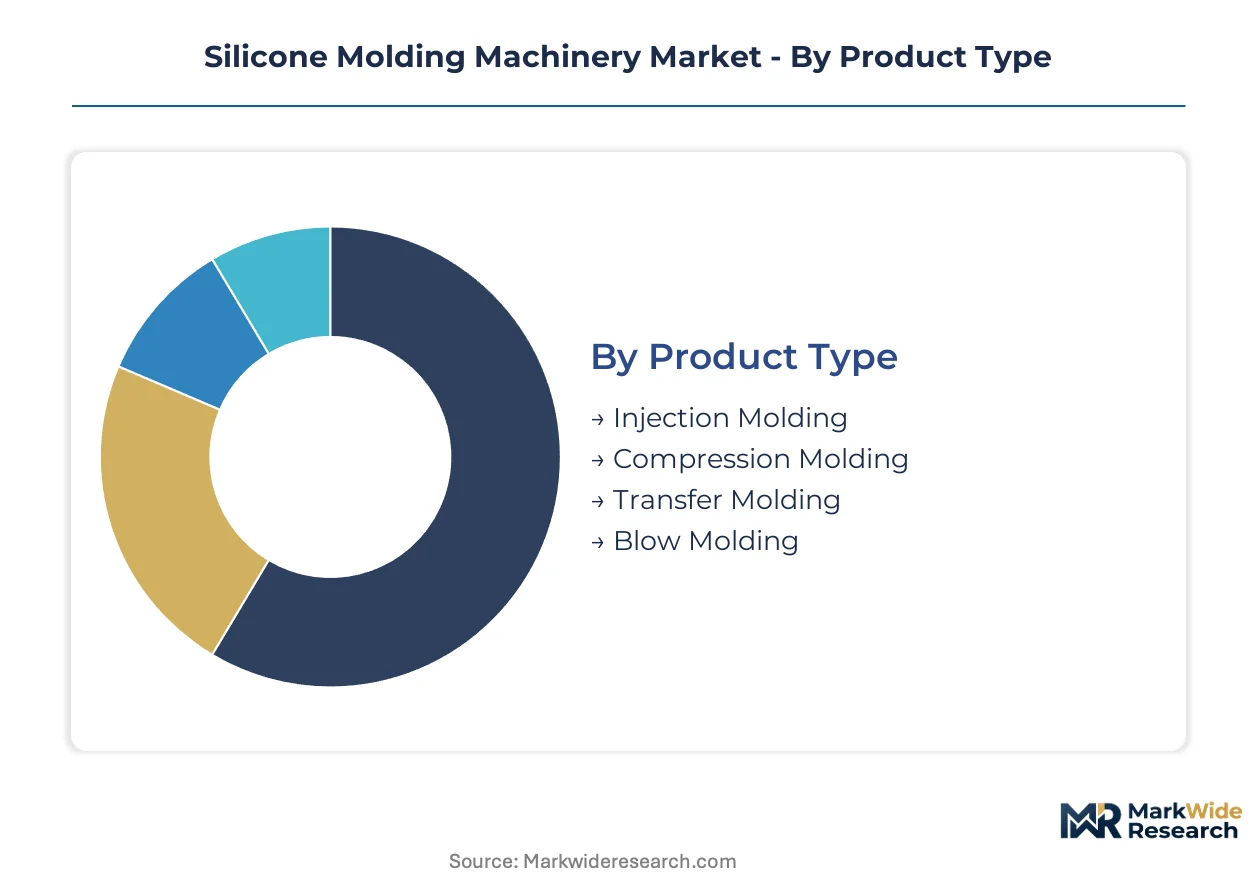
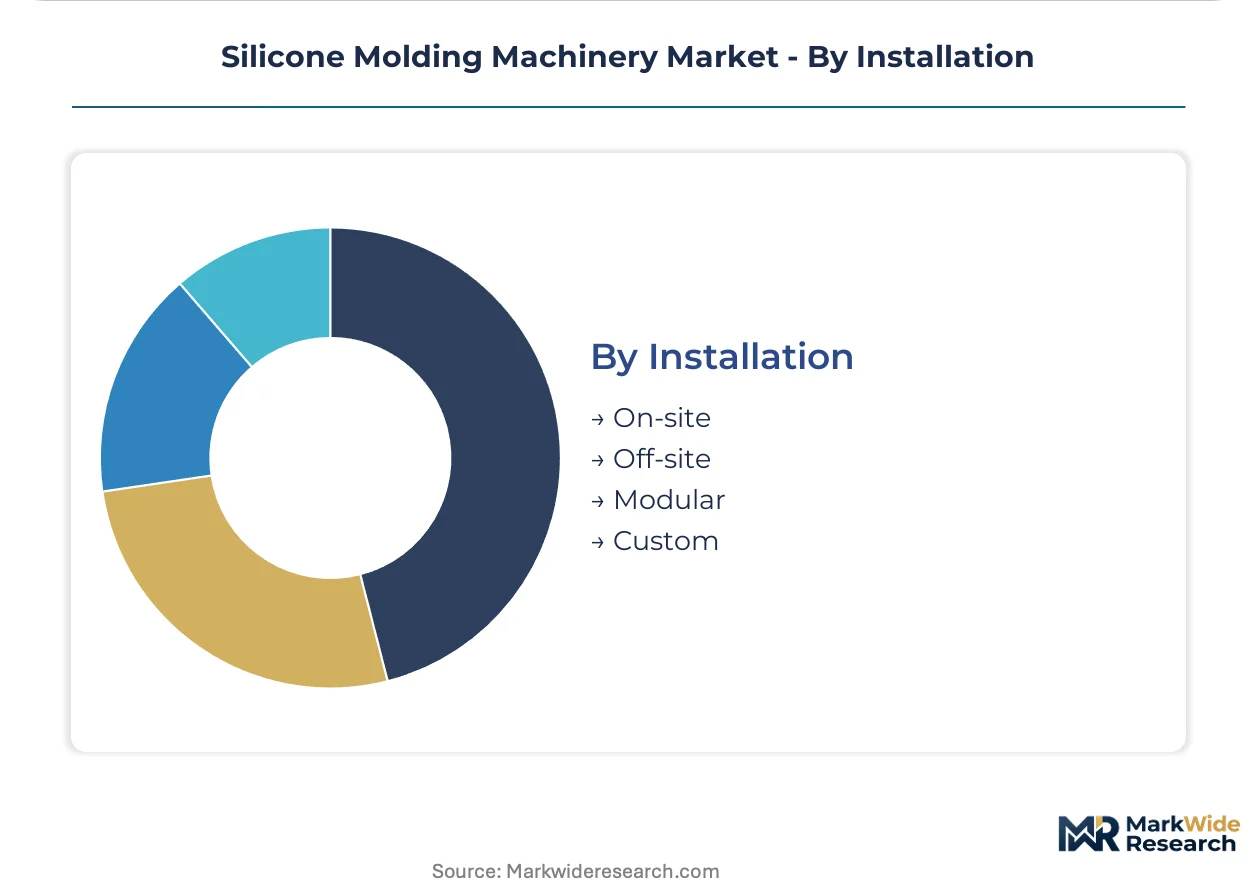
| Segmentation | Product Type: Injection Molding, Compression Molding, Transfer Molding, Blow Molding Industry Vertical: Automotive, Consumer Goods, Electronics, Medical Devices Technology: Hydraulic, Mechanical, Pneumatic, Electric Installation: On-site, Off-site, Modular, Custom |
| Companies Covered | Sumitomo Heavy Industries, Toshiba Machine Corporation, Haitian International Holdings, Nissei Plastic Industrial, Engel Austria GmbH, Arburg, KraussMaffei, Sodick Co., Ltd., Milacron Holdings Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Molding Machinery Market Trends and Innovations
Equipment architecture is bifurcating between all-electric precision platforms for regulated medical applications and servo-hydraulic hybrid systems serving automotive volume production, with control software becoming the primary differentiation vector.
Artificial vision systems with machine learning defect classification are integrating directly into press control architectures, enabling real-time flash detection and automatic parameter adjustment without operator intervention. Medical device contract manufacturers in Germany and Switzerland are adopting these systems at 18-month replacement cycles for quality-critical implantable components. This convergence is integrating quality assurance functions previously performed offline, compressing total cycle time and reducing work-in-process inventory buffers.
REACH Annex XVII restrictions on octamethylcyclotetrasiloxane (D4) content in silicone formulations are forcing machinery OEMs to redesign metering systems for higher-viscosity, lower-volatility LSR grades with extended mixing requirements. Compounders in the Netherlands and Belgium are reformulating catalyst packages to maintain cure rates under modified processing windows. Automotive sealing applications face the steepest compliance penalties, driving specification changes for European supplier qualification programs.
Hospital procurement consortiums are consolidating silicone component purchasing through outcome-based total cost-per-part contracts rather than capital equipment acquisition models. Original equipment manufacturers in the US Midwest and Bavaria now lease press capacity with guaranteed uptime clauses and predictive maintenance inclusion. This restructuring is most visible in cardiovascular device supply chains, where OEMs transfer mold ownership to machinery vendors while retaining exclusive production rights.
Silicone Molding Machinery Market Segmentation
Silicone molding machinery segmentation reveals divergent compliance burdens across product architectures. FDA 21 CFR Part 11 traceability requirements and EU MDR process validation protocols create tiered certification costs that reshape procurement patterns among medical device manufacturers versus automotive suppliers.
Product Type:
Injection molding systems carry the heaviest regulatory load for implantable device production, while compression and transfer variants face lighter documentation requirements for industrial sealing applications.
- Injection Molding:Liquid silicone rubber processing with closed-loop cavity pressure monitoring and vacuum degassing achieves flash-free medical components. German cardiovascular device manufacturers specify these systems for pacemaker lead insulators under EU MDR Class III conformity mandates. FDA-qualified validation packages compress supplier qualification timelines.
- Compression Molding:High-consistency rubber forming with heated platen configurations suits automotive gaskets and industrial seals. Bavarian automotive suppliers deploy these systems for thermal management components where energy consumption reporting carries less regulatory weight than medical traceability requirements.
- Transfer Molding:Intermediate precision for electrical connector housings and consumer appliance seals.
- Blow Molding:Specialized for hollow silicone respiratory device components and bellows formations.
Injection Molding sits at the top of the volume ranking, with Electric technology climbing the fastest among technology categories.
Industry Vertical:
Medical device procurement concentrates around machinery vendors with ISO 13485-certified service networks, while automotive buyers prioritize throughput metrics over documentation depth.
- Medical Devices:Implantable silicone components demand cleanroom-compatible electric presses with full IQ/OQ/PQ protocol support. Swiss and German contract manufacturers consolidate supplier relationships around vendors delivering validated systems with guaranteed uptime clauses.
- Automotive:Electric vehicle battery pack sealing drives high-cavitation tooling orders for thermal runaway containment gaskets. Stuttgart and Munich OEMs specify hybrid electric-hydraulic systems balancing energy efficiency with clamping force for volume production.
- Electronics:Microfluidic channel molding for wearable biosensors and semiconductor packaging substrates.
- Consumer Goods:Kitchenware and personal care applicators with lower regulatory documentation thresholds.
Medical Devices commands the steepest pricing premiums, with Electronics expanding most quickly through wearable biosensor convergence.
Technology:
Capital expenditure patterns split between precision electric architectures for regulated environments and cost-optimized hydraulic platforms for volume production in Asia.
- Electric:All-electric servo drives with linear motion systems deliver sub-0.5% cavity pressure variance for multi-cavity medical tooling. Japanese and German component specialists supply servo motors facing 26-week lead times during semiconductor allocation constraints.
- Hydraulic:Cost-optimized platforms anchor volume production for automotive and consumer goods applications. Asian contract manufacturers favor these systems where energy consumption reporting lacks regulatory enforcement.
- Hybrid:Bridging configurations combining electric precision with hydraulic clamping force for automotive suppliers.
- Pneumatic:Limited deployment for low-force compression applications in consumer goods.
Hydraulic retains the largest installed base, with Electric gaining share fastest through medical device electrification mandates.
Installation:
Deployment models diverge between brownfield pharmaceutical sites requiring legacy SCADA integration and greenfield facilities adopting modular architectures.
- Modular:Pre-validated skid-mounted configurations accelerate commissioning for medical device contract manufacturers. These systems reduce field service dependency amid ISO 13485-qualified engineer scarcity commanding salary premiums.
- Custom:Tailored cleanroom integrations for implantable device production lines with specific airflow and vibration isolation requirements.
- On-site:Conventional installation with full vendor field service support for complex validation protocols.
- Off-site:Remote technical center configuration with subsequent site transfer for standardized equipment.
Modular installations lead capital expenditure growth, with Custom specifications holding the highest margin profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision machinery demand for medical-grade applications, while China anchors volume production through cost-optimized platforms serving automotive and consumer goods sectors.
Germany
Cardiovascular device manufacturers in Bavaria and Baden-Württemberg specify electric presses for pacemaker lead insulators under EU MDR Class III mandates. ECHA REACH enforcement on platinum catalyst handling drives equipment specification changes. Stuttgart machinery clusters supply validated cleanroom-compatible systems with full IQ/OQ/PQ documentation packages.
United States
Midwest medical device OEMs consolidate supplier relationships around vendors delivering FDA 21 CFR Part 11 traceability systems. IRA clean manufacturing credits incentivize reshoring of silicone molding capacity from Asian contract manufacturers. Minnesota and Massachusetts cardiovascular device corridors compress qualification timelines for implantable components.
China
Automotive electronics sealing demand from electric vehicle battery pack manufacturers drives high-cavitation tooling orders. MIIT energy efficiency standards shape equipment procurement for domestic OEMs. Yangtze River Delta machinery clusters serve cost-sensitive volume production for consumer goods and industrial sealing applications.
Switzerland
Swissmedic oversight of implantable device manufacturing elevates process validation requirements for contract manufacturers in the Zurich and Basel regions. ISO 13485-certified service networks command premium positioning. Precision machinery specialists supply multi-cavity medical tooling with sub-0.5% cavity pressure variance specifications.
Saudi Arabia
SFDA medical device manufacturing incentives under Vision 2030 create first-mover opportunities for machinery vendors establishing regional technical centers. Healthcare localization policies drive demand for Arabic-language validation documentation capabilities. Riyadh and Jeddah industrial zones attract equipment suppliers targeting Middle East medical device production.
Silicone Molding Machinery Market Competitive Landscape
Top-tier vendors anchor premium electrified architectures for regulated medical applications, while mid-tier fabricators compete on cost-optimized hydraulic platforms for volume automotive production. The vendor base stratifies across three archetypes: precision electric specialists, hybrid system integrators, and scale-driven hydraulic manufacturers. M&A activity concentrates on control software capabilities and regional service network expansion. Technology licensing agreements for servo motor drives and linear motion systems proliferate amid semiconductor supply constraints.
Within the precision electric tier, Engel Austria GmbH and Sodick Co., Ltd. exemplify cleanroom-compatible architecture development for medical-grade applications. Haitian International Holdings occupies a position among scale-driven hydraulic platform suppliers serving cost-sensitive volume markets. KraussMaffei represents hybrid system integration, bridging energy efficiency and clamping force specifications for automotive supplier qualification programs.
| Leading Market Players |
|---|
| Sumitomo Heavy Industries |
| Toshiba Machine Corporation |
| Haitian International Holdings |
| Nissei Plastic Industrial |
| Engel Austria GmbH |
| Arburg |
| KraussMaffei |
| Sodick Co., Ltd. |
| Milacron Holdings Corp. |
| Others |
Pricing and Supply Chain Analysis
Class III implantable device manufacturers concentrate procurement decisions around validated electric press vendors, locking in long-term service contracts that embed predictive maintenance and guaranteed uptime clauses within capital expenditure frameworks.
Pricing Analysis
Bundled validation documentation packages with IQ/OQ/PQ protocols command 25-35% premiums over unbundled equipment-only transactions. Three-tier pricing structure across premium electric, standard hybrid, and economy hydraulic levels differentiates on FDA 21 CFR Part 11 certification depth and cleanroom compatibility grades. Cost compression in hydraulic tiers intensifies as Asian contract manufacturers prioritize throughput metrics over traceability features. Automotive sealing buyers exhibit highest price sensitivity, while Swiss and German cardiovascular OEMs absorb premium electric press pricing without volume negotiation.
Supply Chain Analysis
US IRA domestic content bonuses and Saudi Vision 2030 localization mandates are reshaping sourcing patterns for North American and Middle Eastern machinery deployments. Precision servo motors and linear motion systems draw from Japanese and German component specialists, while hydraulic power units source primarily from Chinese and Taiwanese fabricators. Single-source vulnerability in semiconductor-grade servo drives creates allocation risk during foundry capacity constraints. Distribution runs through authorized regional technical centers with ISO 13485-certified field engineering capabilities rather than direct OEM-to-end-user shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric press architectures enable margin expansion through platinum catalyst recovery system integration and outcome-based leasing models that capture recurring service revenue from implantable device manufacturers.
For Market Incumbents: Anchor premium positioning through backward integration into servo motor and cold runner valve-gate manufacturing, eliminating 26-week lead time exposure to Japanese component specialists. Deepen captive supply of vacuum degassing systems to defend against emerging Asian hybrid platform vendors. Prioritize Arabic-language validation documentation capabilities to capture Saudi SFDA healthcare localization incentives before regional technical center saturation. For New Entrants and Emerging Players: Machine-vision defect classification with real-time parameter adjustment offers a technology-first wedge into German and Swiss contract manufacturer quality-critical implantable component lines. Target wearable biosensor microfluidic channel molding as the most penetrable application, where semiconductor packaging tool vendors lack silicone substrate processing expertise. Pursue hospital procurement consortium outcome-based contracts as the primary go-to-market angle, transferring mold ownership while retaining exclusive production rights. For Investors and Strategic Acquirers: Medical device OEMs with captive molding operations are the most active acquirers in this space, seeking control software capabilities and ISO 13485-certified service network expansion. Five-to-ten-year viability hinges on electrification mandate acceleration across EU MDR and FDA regulatory frameworks. Monitor ECHA REACH enforcement intensity on platinum catalyst handling as the key inflection signal for equipment specification change velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Manufacturing | Eliminates 26-week lead time exposure to Japanese component specialists during semiconductor allocation constraints. |
| Arabic-Language Validation Documentation Development | Captures Saudi SFDA healthcare localization incentives under Vision 2030 before regional technical center saturation. |
| Machine Vision Integration with Real-Time Parameter Adjustment | Compresses total cycle time for German cardiovascular device manufacturers under EU MDR Class III mandates. |
| Outcome-Based Leasing with Predictive Maintenance Inclusion | Aligns with hospital procurement consortium purchasing consolidation through guaranteed uptime clauses. |
| Platinum Catalyst Recovery System Proliferation | Addresses ECHA REACH enforcement priorities while reducing volatile methyl siloxane emissions in German manufacturing clusters. |
Research Methodology
Bottom-up medical device and automotive OEM procurement modeling reconciled against top-down machinery vendor order book tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital GPO contracts managers, FDA regulatory affairs specialists, and Tier 1 automotive supplier procurement directors combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, ECHA REACH enforcement records, and SEC equipment manufacturer 10-K disclosures. Triangulation across stakeholder perspectives and documentary sources ensures cross-verified demand and supply-side estimates.
Historical trendline analysis of electric versus hydraulic technology adoption rates, cleanroom-compatible system deployment patterns, and validation documentation package penetration informs projection framework construction across the analysis window. Segmentation modeling incorporates product architecture, technology type, industry vertical, and regional regulatory cluster dimensions. CAGRs derive from equipment replacement cycle compression analysis and capital expenditure elasticity to EU MDR and FDA device regulation timeline shifts.
The model holds under continued regulatory enforcement intensity for liquid silicone rubber process validation; deviation in platinum group metal price volatility or semiconductor foundry allocation constraints would shift equipment procurement timing and technology mix assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Industrial Wearable Devices Market
Others
Social Media Engagement Applications Market
Others
Middle East and Africa Medium Voltage Switchgear Market
Others
Global Application Testing Services Market
Others
Server Market
Others
Couscous Market
Others
Gas Radiators Market
Others
Global Recruitment and Staffing Market
Others
Global Active Speaker Market
Others
Deflectometer Market
Others
Gesture Recognition for Smart TV Market
Others
Air Separation Unit Market
Others
Latin America Fire Sprinklers Market
Others
Global Optical Comparator Market
Others
Canada Feed Additives Market
Others
Toy Packaging Market