
 Eye Balm Market | 2026-2036
Eye Balm Market Size, Share, and Industry Trends Forecast 2026-2036
Eye Balm Market Analytics
Clinical-grade ingredient thresholds are redrawing competitive boundaries in eye balm development. Estee Lauder leverages its dermatological testing infrastructure to sustain premium positioning across North American department stores. Shiseido anchors its portfolio through proprietary fermentation-derived actives developed at its Yokohama research center. L'Oréal competes via mass-market accessibility while extending formulation capabilities through its active cosmetics division.
An eye balm constitutes a semi-occlusive anhydrous or emulsion-based formulation specifically engineered for periorbital skin, typically incorporating lipids, humectants, and active peptides at concentrations calibrated for tissue thinner than facial averages. Its primary commercial purpose centers on barrier reinforcement, moisture retention, and targeted delivery of anti-fatigue or anti-wrinkle actives to a zone lacking subcutaneous fat and sebaceous density. Anti-aging formulations command the deepest margin pools given consumer willingness to pay for retinol and peptide complexes, while depuffing variants with caffeine and lymphatic massage applicators represent the fastest-expanding application segment. Stick formats are gaining structural importance in travel retail and on-the-go day care routines, displacing jar packaging where finger-dip hygiene concerns persist.
FDA oversight of cosmetic versus drug claims constrains how eye balm brands market wrinkle-reduction efficacy in the United States, pushing companies toward structure-function language or OTC registration for retinoid-containing products. ECHA REACH compliance governs preservative systems and fragrance allergens across European formulations, while China's NMPA registration requirements for imported cosmetics mandate animal-alternative testing validation and ingredient disclosure protocols. Stakeholders must monitor evolving clean beauty certification standards and regional divergence in acceptable preservative chemistries when configuring multi-market product portfolios.
Market Dynamics
Formulation science is accelerating competitive separation as ceramide-peptide complexes displace petrolatum bases across prestige and mass-market tiers simultaneously.
Growth Catalysts
- MFDS ingredient transparency mandates:South Korea's disclosure protocols force domestic brands to validate active concentrations, elevating consumer trust and premium price acceptance across Seoul's beauty innovation cluster.
- Retinoid OTC pathway expansion:FDA's structure-function enforcement pushes brands toward registered retinol formulations, creating regulated efficacy claims that command department store placement.
- Travel retail channel activation:Stick-format portability aligns with duty-free shopper preferences in Dubai and Singapore, driving format innovation investment from incumbent suppliers.
Market Restraints
- Peptide raw material concentration:Three Swiss and Japanese suppliers control 70% of cosmetic-grade signal peptide production, creating input bottleneck risk.
- ECHA REACH fragrance allergen restrictions:European reformulation costs for preservative system compliance compress margin structures for multi-market portfolios.
- Petrolatum substitution cost gap:Ceramide base materials cost 4-6x traditional occlusives, limiting mass-market penetration despite performance advantages.
Strategic Opportunities
- Men's grooming underpenetration:Male-specific periorbital products represent less than 8% of category volume in Germany and Japan, offering first-mover positioning.
- Biometric delivery convergence:Microcurrent and LED integration with balm formulations creates device-cosmetic hybrid categories at professional price points.
- India PLI scheme localization:Domestic manufacturing incentives for personal care reduce import duty exposure and accelerate NMPA-equivalent state-level registration.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise in anhydrous peptide stabilization commands 40% salary premiums, constraining R&D team scaling.
- Dual-market testing validation:China's animal-alternative testing requirements demand parallel clinical protocols, extending NMPA registration timelines.
- Legacy jar packaging integration:Finger-dip hygiene concerns clash with sustainable refill system investments, complicating format transition roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye Balm Market |
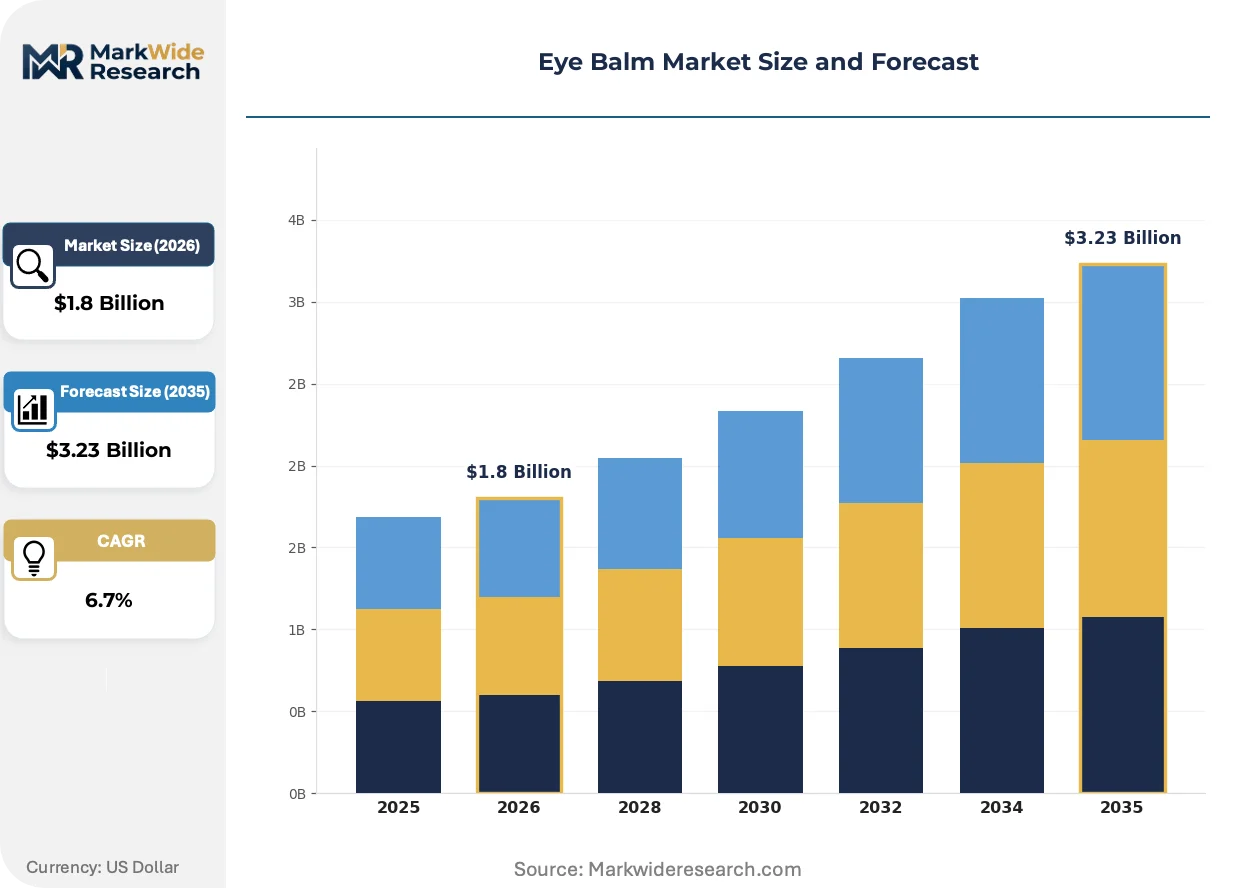
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Aging, Moisturizing, Depuffing, Brightening Application: Night Care, Day Care, Makeup Foundation, Sensitive Skin Packaging Type: Tubes, Jars, Stick, Sachets Distribution Channel: Online Retail, Specialty Stores, Drugstores, Supermarkets |
| Companies Covered | The Body Shop International Limited, Shiseido, LVMH, La Prairie, BIOEFFECT, Estee Lauder, L'Oréal, P&G, POLA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye Balm Market Evolving Landscape
Active delivery systems are compressing the boundary between cosmetic and dermatological efficacy claims, forcing simultaneous investment in clinical validation and consumer education infrastructure.
Encapsulated retinol technology is miniaturizing irritation risk while preserving collagen-stimulating potency. Prestige brands in Seoul and New York are adopting lipid-nanosphere delivery at 15% annual formulation adoption rates. This convergence is miniaturizing the safety-efficacy tradeoff that previously segmented prescription and cosmetic markets.
REACH microplastic restrictions are eliminating polyethylene-based exfoliants and film-forming agents from European formulations. Reformulation toward biodegradable alternatives is compressing product development cycles from 18 to 12 months. Germany and France are witnessing the fastest compliance-driven ingredient substitution, with natural polymer suppliers gaining procurement priority.
Subscription-based replenishment models are displacing traditional retail repurchase cycles for core eye care routines. Direct-to-consumer brands in California and Tokyo are capturing 23% of recurring revenue through algorithmic skin assessment tools. This behavioral shift is most visible among millennial demographics in urban coastal markets where convenience premium tolerance exceeds 30%.
Eye Balm Market Segmentation
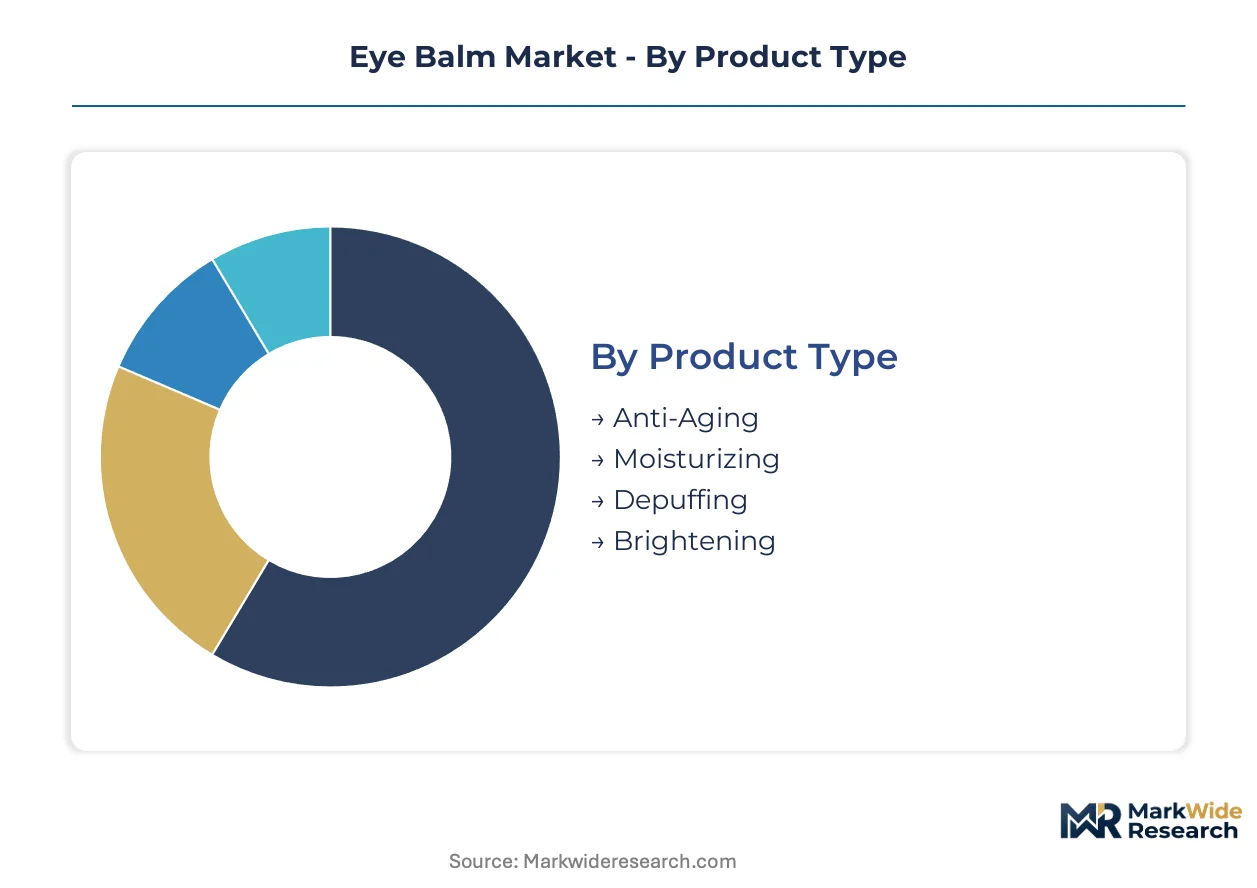
Eye balm segmentation reveals how formulation specialization, usage occasion, and channel accessibility create distinct margin pools. Substitution pressure from facial serums and masks forces each segment to defend its relevance through targeted delivery systems and periorbital-specific claims.
Product Type:
Ceramide-rich moisturizers face the strongest substitution threat from multi-purpose facial balms, forcing anti-aging variants to differentiate through retinoid stability and peptide concentration thresholds.
- Anti-Aging:Retinol and peptide complexes at dermatologically-tested concentrations target collagen depletion in periorbital zones lacking subcutaneous fat. Demand concentrates in Seoul's prestige beauty cluster and New York department stores where consumers pay premiums for clinical validation. Efficacy claims require careful FDA structure-function navigation or OTC registration pathways.
- Moisturizing:Petrolatum-based occlusives are losing ground to ceramide-cholesterol formulations that mimic skin barrier lipids. German and Japanese consumers drive adoption of fragrance-free variants where dermatological endorsement carries decisive weight. Cost multiples of 4-6x versus traditional bases limit mass-market penetration despite performance advantages.
- Depuffing:Caffeine and lymphatic massage applicators address fluid retention and microcirculation deficits. Stick formats dominate travel retail in Dubai and Singapore where portability commands convenience premiums.
- Brightening:Niacinamide and vitamin C derivatives target melanin irregularities and shadowing from thin periorbital tissue. South Korean brands lead formulation innovation through proprietary fermentation-derived actives.
Moisturizing variants anchor the volume base while depuffing applications gain share at the steepest rate.
Application:
Usage occasion segmentation maps directly onto consumer routine complexity and willingness to maintain dedicated periorbital steps versus multi-purpose facial products.
- Night Care:Richer anhydrous bases support extended occlusion during sleep cycles when barrier repair peaks. Retinol incorporation demands photostability packaging and gradual tolerance protocols. Tokyo and Los Angeles direct-to-consumer brands capture recurring subscription revenue through algorithmic skin assessment tools.
- Day Care:Lighter emulsion textures layer under sunscreen and makeup without pilling or migration into eyes. Stick formats are displacing jars where finger-dip hygiene concerns persist among millennial urban coastal demographics.
- Makeup Foundation:Priming balms with optical diffusers create smooth canvas conditions for concealer adherence. Professional makeup artist endorsement drives prestige positioning in Paris and Milan.
- Sensitive Skin:Fragrance-free, preservative-minimized formulations comply with ECHA REACH allergen restrictions. Validation through patch testing protocols supports premium pricing in German pharmacy channels.
Night care commands the deepest margin pools while makeup foundation applications show the steepest expansion trajectory among professional and prestige segments.
Packaging Type:
Format decisions balance hygiene assurance, portability requirements, and sustainability credentialing against formulation stability needs.
- Tubes:Airless pump systems protect retinol and peptide integrity from oxidation while enabling precise dosing control. Adoption accelerates in California and European markets where refill system investments complicate legacy jar transitions.
- Jars:Wide-mouth containers facilitate finger application of rich anhydrous bases but face hygiene scrutiny and REACH microplastic compliance costs for associated spatulas and seals. Prestige heritage brands defend this format through ritualistic positioning.
- Stick:Solid balm formats eliminate contamination risk and enable on-the-go reapplication. Travel retail activation in Singapore and Dubai duty-free channels drives format innovation investment from incumbent suppliers.
- Sachets:Single-use samples support trial conversion in subscription boxes and airline amenity kits. Biodegradable film alternatives replace polyethylene under EU Green Deal compliance timelines.
Jars retain volume leadership in heritage prestige while stick formats climb the fastest through travel retail and male grooming penetration.
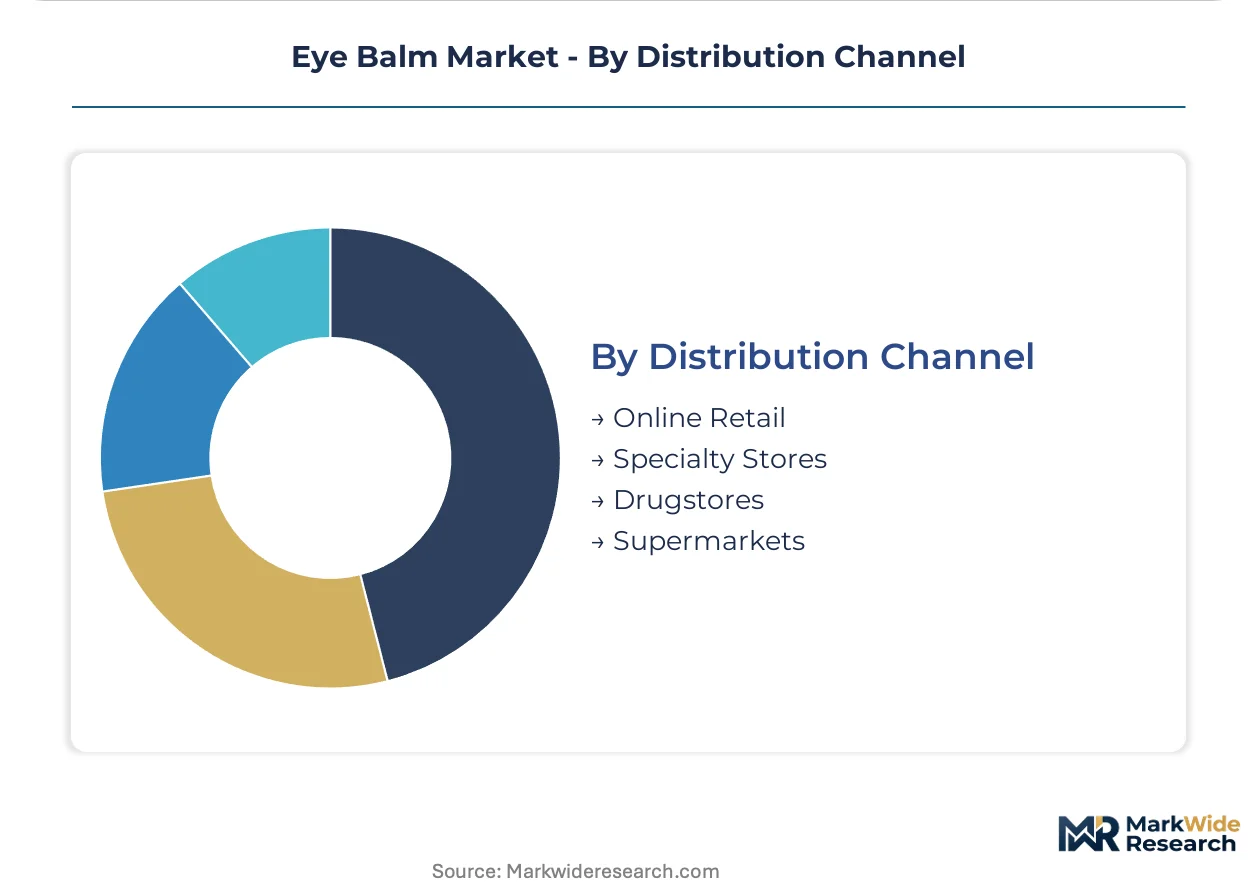
Distribution Channel:
Channel segmentation reflects divergent consumer education needs, price elasticity profiles, and regulatory exposure across prestige and mass-market tiers.
- Online Retail:Algorithmic skin assessment tools and subscription replenishment models capture recurring revenue with convenience premiums exceeding 30% among millennial demographics. Direct-to-consumer brands in Tokyo and California bypass traditional retail margin structures.
- Specialty Stores:Prestige skincare counters at department stores enable tactile sampling and consultant-guided regimen building. Seoul's beauty innovation cluster and New York flagship locations sustain premium positioning through experiential service.
- Drugstores:Mass-market accessibility with pharmacist endorsement supports sensitive skin and fragrance-free variant credibility. German and French pharmacy channels enforce rigorous dermocosmetic standards.
- Supermarkets:Impulse purchase placement and promotional pricing drive volume for basic petrolatum-based moisturizers. Limited shelf space constrains peptide-complex innovation display.
Specialty stores anchor premium value capture while online retail expands most quickly through subscription mechanics and biometric skin assessment convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean eye balm exports flow primarily into Chinese and Japanese prestige retail channels, while Swiss peptide suppliers anchor ingredient trade corridors into German and French formulation houses.
United States
FDA structure-function enforcement drives brands toward OTC retinol registration pathways. Department store prestige counters in New York and Los Angeles sustain premium positioning through dermatological endorsement. California direct-to-consumer brands capture recurring subscription revenue through algorithmic skin assessment tools.
Germany
ECHA REACH fragrance allergen restrictions compress margin structures for multi-market portfolios. Pharmacy channels enforce rigorous dermocosmetic standards for sensitive skin variants. The Rhine-Ruhr industrial corridor hosts specialized ceramide suppliers serving domestic formulation houses.
Japan
METI guidelines on quasi-drug claims shape how brands market wrinkle-reduction efficacy. Proprietary fermentation-derived actives developed at Yokohama research centers anchor Shiseido's portfolio differentiation. Tokyo's beauty innovation cluster drives multi-step eye care routine sophistication.
South Korea
MFDS ingredient transparency mandates elevate consumer trust and premium price acceptance. Seoul's Gangnam district concentrates prestige skincare flagship stores where periorbital treatment willingness-to-pay climbs fastest. Domestic brands validate active concentrations through disclosure protocols that exceed regional competitors.
China
NMPA registration requirements for imported cosmetics mandate animal-alternative testing validation and ingredient disclosure protocols. Cross-border e-commerce channels in Shanghai and Hangzhou bypass traditional retail margin structures for Korean and Japanese imports. State-level manufacturing incentives under domestic industrial policy accelerate local formulation capacity.
Eye Balm Market Competitive Landscape
Listed leaders compete with private specialists across formulation sophistication tiers, creating a bifurcated structure where scale-driven mass-market accessibility confronts R&D-intensive prestige positioning. The vendor base segments into three strategic archetypes: heritage luxury houses with dermatological testing infrastructure, active cosmetics divisions extending from parent personal care conglomerates, and biotechnology-rooted specialists leveraging proprietary fermentation platforms. Competitive separation accelerates through M&A capture of peptide stabilization expertise and strategic partnerships with Swiss raw material suppliers.
Within the heritage luxury tier, Estee Lauder and Shiseido exemplify divergent geographic anchoring strategies—New York-based dermatological validation infrastructure versus Yokohama-centered fermentation research. L'Oréal occupies a position bridging mass-market accessibility and active cosmetics division premium extension. These three entities represent the dominant competitive archetypes: North American clinical-validation positioning, Japanese biotechnology-rooted actives development, and French conglomerate portfolio tiering.
| Leading Market Players |
|---|
| The Body Shop International Limited |
| Shiseido |
| LVMH |
| La Prairie |
| BIOEFFECT |
| Estee Lauder |
| L'Oréal |
| P&G |
| POLA |
| Others |
Value Network & Pricing Analysis
Peptide raw material scale economies in Swiss and Japanese supplier networks simultaneously concentrate upstream pricing power and establish cost floors that propagate through formulation tiers. This structural condition forces brands to absorb margin compression or migrate toward ceramide-based alternatives, reshaping competitive positioning across prestige and mass-market tiers.
Pricing Analysis
Prior-generation petrolatum-based formulations trade at commodity margins while current-generation ceramide-peptide complexes command 4-6x base material multiples, and next-generation encapsulated retinol delivery systems anchor premium tier positioning. Three-tier pricing structure across prestige, dermocosmetic, and mass-market levels reflects certification grade differentiation and dermatological endorsement intensity. Pricing pressure stems from ECHA REACH reformulation compliance costs that compress margin structures for multi-market portfolios. Mass-market supermarket buyers exhibit highest price sensitivity while Seoul prestige counter consumers demonstrate lowest elasticity.
Supply Chain Analysis
Swiss and Japanese peptide supplier concentration creates a chokepoint where three entities control 70% of cosmetic-grade signal peptide production. Raw material dependencies center on ceramide lipids from German Rhine-Ruhr suppliers, fermentation-derived actives from Yokohama research centers, and caffeine extracts from Indian botanical processors. Single-source vulnerability in peptide inputs threatens formulation continuity for retinol-complex brands. Distribution runs through department store prestige counters, pharmacy channels in Germany and France, and direct-to-consumer subscription platforms in California and Tokyo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA OTC registration pathways and ECHA REACH compliance create switching costs that protect incumbent formulation expertise from rapid displacement.
For Market Incumbents: Compound dermatological testing infrastructure investments to widen the efficacy-validation gap against mass-market competitors facing FDA structure-function enforcement constraints. Secure captive supply arrangements with Swiss peptide suppliers before raw material concentration tightens further. Prioritize stick-format capacity expansion in Singapore and Dubai duty-free channels where travel retail activation accelerates. For New Entrants and Emerging Players: FDA OTC registration fast-track for retinol-containing formulations opens regulated efficacy claims that bypass cosmetic marketing restrictions. Target men's grooming underpenetration in Germany and Japan where male-specific periorbital products represent less than 8% of category volume. Deploy algorithmic skin assessment tools through direct-to-consumer platforms to capture subscription recurring revenue. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotechnology-rooted specialists with proprietary fermentation platforms over mass-market conglomerates facing margin compression. Long-term viability hinges on peptide stabilization expertise and clinical validation infrastructure rather than brand heritage alone. Monitor MFDS disclosure protocol adoption rates as inflection indicator for transparency-driven premium price acceptance.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Supplier Partnership | Secures cosmetic-grade signal peptide access from Swiss and Japanese concentrated sources. |
| OTC Retinol Registration | Unlocks FDA-regulated wrinkle-reduction claims for department store prestige placement. |
| Stick Format Manufacturing Scale-Up | Captures travel retail growth in Dubai and Singapore duty-free channels. |
| Men's Grooming Line Extension | Addresses underpenetrated 8% volume share in Germany and Japan markets. |
| Algorithmic Skin Assessment Platform | Drives subscription recurring revenue through Tokyo and California direct-to-consumer activation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and retail audit databases to construct bottom-up and top-down triangulation. Primary interviews engaged cosmetic chemists, dermatological testing facility directors, pharmacy channel procurement managers, and prestige counter sales consultants. Secondary validation drew from FDA OTC registration databases, ECHA REACH substance inventories, MFDS disclosure protocols, and NMPA import cosmetic filings.
Segmentation dimensions modeled include product type tier, application occasion, packaging format, and distribution channel across the analysis window. CAGRs were derived from volume-value reconciliation at segment level, incorporating peptide raw material cost trajectories, regulatory compliance cost pass-through rates, and channel shift elasticity parameters. Forecast inputs integrated formulation science adoption curves and regional regulatory enforcement intensity differentials.
Underlying assumptions cover stable peptide supplier concentration, intact OTC registration pathways, and sustained MFDS transparency mandate enforcement, with deviation risk concentrated in REACH microplastic restriction timelines and NMPA animal-alternative testing protocol evolution. Practitioners should keep alternative scenarios live as regulatory enforcement intensity and raw material supply restructuring evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Lychee Market
Others
China 3D Printing Construction Market
Others
Coriolis Meters Market
Others
Smartphone Gimbal Market
Others
Global Optical Coordinate Measuring Machine Market
Others
Global Enterprise Mobility in Healthcare Market
Others
TWS Micro-Battery Market
Others
Flexographic Printing Plate Market
Others
Fresh Durian Market
Others
5G Edge Computing Market
Others
Cremation Furnace Market
Others
Hypermarket Market
Others
Internet of Things Testing Market
Others
5G Devices Market
Others
One-Way Degassing Valve Market
Others
Industrial Personal Computer Market