
 Europe Laundry Appliances Market | 2026-2036
Europe Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Laundry Appliances Market Foresight
Appliance technician shortages across Central Europe is bifurcating the market into premium service-network brands and low-touch disposable-unit suppliers. BSH Hausgeräte GmbH leverages its captive service infrastructure across Germany and Austria to sustain above-average attach rates for extended warranties. Miele & Cie. KG anchors its positioning in commercial-grade durability, while Hisense Europe competes aggressively on landed cost through direct retail partnerships in Eastern Europe.
Europe laundry appliances encompass electrically powered machines for washing, rinsing, spinning, or drying textiles, typically operating at drum speeds between 1,000 and 1,600 RPM with rated capacities from five to twelve kilograms. These units serve residential households, commercial laundries, and institutional facilities where throughput reliability and water-energy efficiency determine total cost of ownership. Washing machines occupy the largest value share given replacement frequency and regulatory nudges toward cold-wash cycles, while smart technology segments expand fastest as connected diagnostics reduce service dispatch costs for fleet operators. Compact units command outsized margins in urban Benelux and Nordic markets where floor space constraints override capacity preferences.
EU Ecodesign for Sustainable Products Regulation and REACH compliance reshape material choices and repairability mandates, forcing redesign of sealed drum assemblies and control board accessibility. CE marking under the EU Green Deal framework now embeds digital product passports that trace component origin and end-of-life recyclability. Stakeholders must monitor how upcoming F-Gas Regulation amendments affect heat-pump dryer refrigerant specifications and supplier qualification timelines.
Market Dynamics
EU Ecodesign for Sustainable Products Regulation is forcing appliance manufacturers to redesign drum assemblies for repairability while heat-pump refrigerant rules under pending F-Gas amendments compress supplier qualification timelines.
Growth Catalysts
- Hospitality CAPEX Recovery:Hotel renovation pipelines in Poland and Portugal are replacing legacy linen-processing equipment with energy-certified units ahead of 2027 efficiency benchmarks.
- REACH Material Compliance:Restrictions on hazardous substances in electronics are accelerating substitution of brominated flame retardants in control boards, opening qualification windows for compliant component suppliers.
- Cold-Wash Cycle Adoption:Residential detergent formulations optimized for sub-30°C operation reduce energy draw and extend drum-bearing life, tightening replacement intervals for aging machines.
Market Restraints
- Copper-Wiring Cost Volatility:Motor stator materials face commodity price swings that compress OEM margin buffers on mid-range units.
- Compressor Supply Concentration:Heat-pump dryer refrigeration circuits rely on a narrow base of qualified European suppliers, creating single-source vulnerability for capacity expansion.
- Sealed-Drum Technical Limitation:Integrated bearing designs that improve water sealing complicate field repair, conflicting with EU repairability mandates and raising warranty reserve requirements.
Strategic Opportunities
- Eastern Europe Rental Housing:Multi-family operators in Romania and Bulgaria are consolidating procurement for standardized appliance fleets, creating volume aggregation points for direct-ship manufacturers.
- Digital Product Passport Mandate:CE marking under EU Green Deal traceability requirements creates first-mover advantage for component serialization and blockchain verification services.
- Connected Diagnostics Convergence:Integration of vibration sensors with predictive maintenance algorithms reduces service dispatch costs for commercial laundry fleet operators.
Industry Challenges
- Appliance Technician Scarcity:Vocational training pipelines across Germany and Austria fail to replenish retiring field-service workforces, forcing brands to internalize training costs or accept longer repair lead times.
- Dual Certification Complexity:Simultaneous compliance with Ecodesign energy labeling and REACH substance restrictions extends product development cycles and strains regulatory affairs staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Laundry Appliances Market |
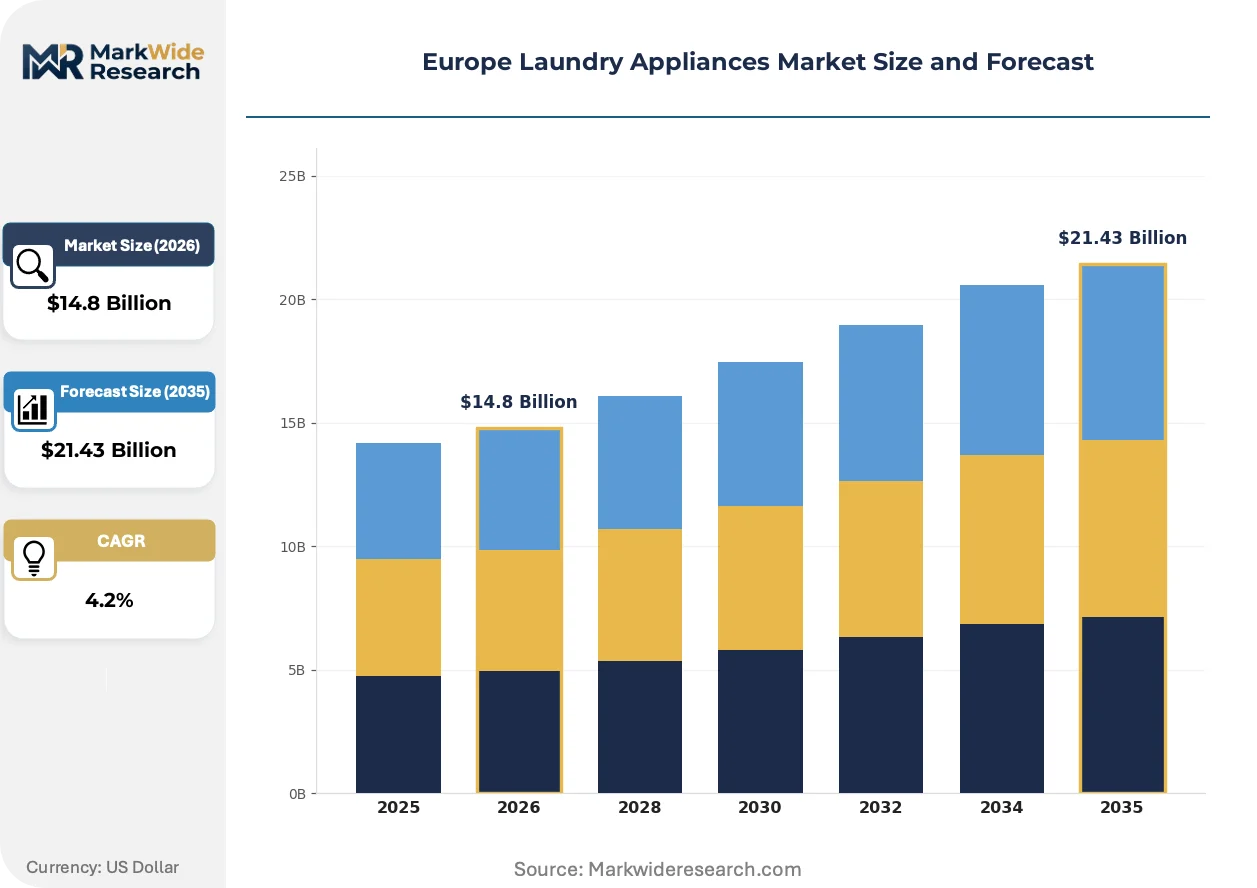
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $21.43 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Washer-Dryers, Compact Units Technology: Smart Technology, Steam Cleaning, Energy Efficient, Conventional Capacity: Small, Medium, Large, Extra Large End User: Households, Commercial, Hotels, Laundromats |
| Companies Covered | Arçelik A.Ş., Samsung Electronics Co., Ltd., BSH Hausgeräte GmbH, Haier Smart Home Co., Ltd., Miele & Cie. KG, Electrolux AB, LG Electronics Inc., Hisense Europe, Whirlpool Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Laundry Appliances Market Shifts & Advancements
Heat-pump drying technology and connected service architectures are compressing total cost of ownership calculations while regulatory traceability mandates reshape supplier qualification protocols across the value chain.
Inverter-driven motor controllers are miniaturizing power electronics into drum-mounted packages that eliminate external drive units. Commercial laundromat operators in Benelux urban cores are adopting these integrated systems to reclaim floor space for additional revenue-generating equipment. The technology is miniaturizing mechanical footprints while maintaining 1,600 RPM spin profiles, enabling retrofit installations in heritage buildings with constrained utility access.
F-Gas Regulation amendments targeting hydrofluorocarbon phase-down are restricting refrigerant choices for heat-pump dryers to lower-GWP alternatives with modified thermodynamic properties. OEM engineering teams must revalidate compressor maps and evaporator geometries under accelerated timelines. Southern European markets with higher ambient temperatures face disproportionate performance verification burdens as operating envelopes tighten.
Subscription-based equipment access is displacing outright purchase in German multi-family housing cooperatives, transferring capital risk to fleet operators while bundling maintenance and energy costs into per-cycle fees. Property managers in Berlin and Munich are consolidating vendor relationships around outcome-guarantee contracts. This procurement model concentrates buying power among fewer decision-makers and compresses sales cycles for standardized unit specifications.
Europe Laundry Appliances Market Segmentation
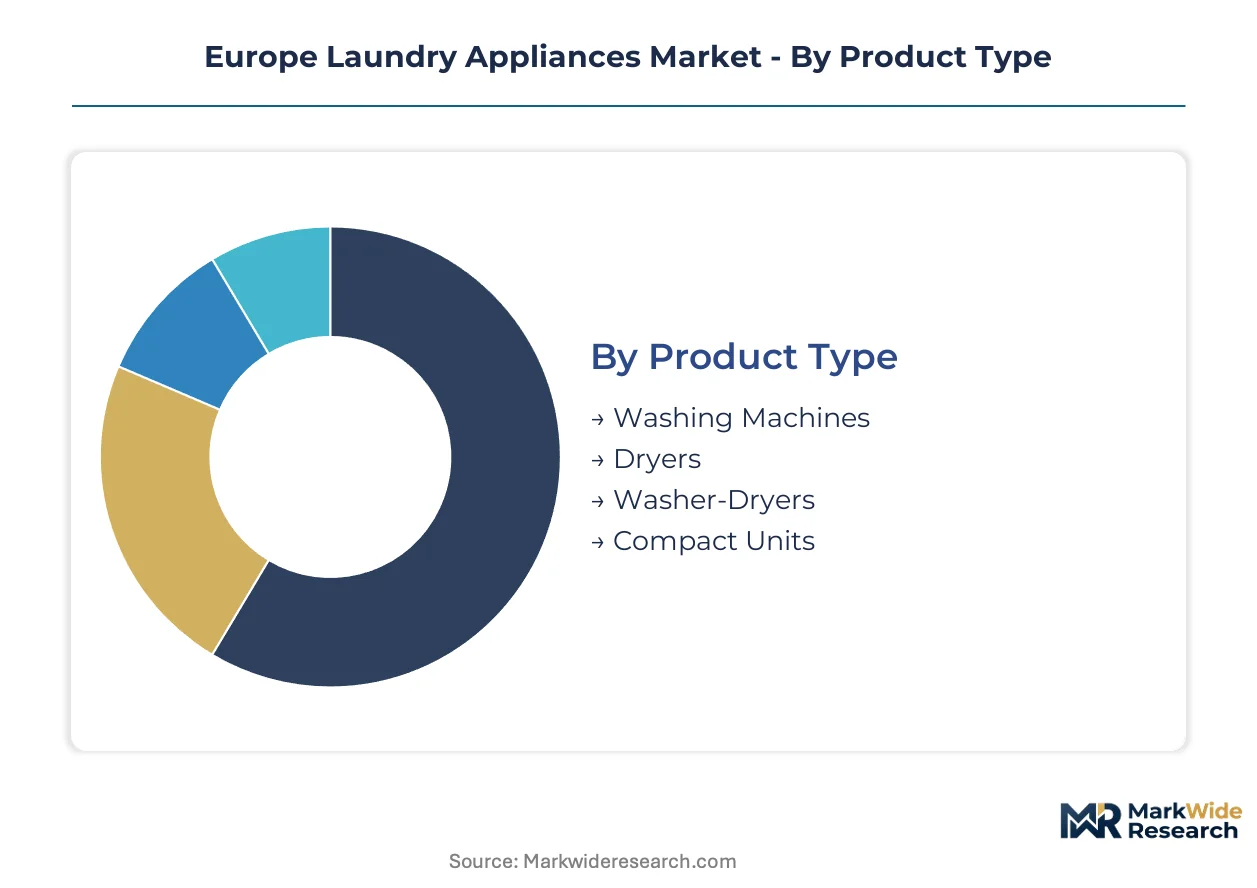
Segmentation in Europe laundry appliances reveals how regulatory pressure and housing stock conditions split demand across technical specifications. Manufacturers must align product portfolios with distinct replacement cycles and efficiency mandates that vary by end-use environment.
Product Type:
Domestic consumption concentrates in Germany, Italy, and Poland where housing renewal drives replacement demand, while export-oriented production in Turkey and Romania supplies broader regional distribution networks.
- Washing Machines:Drum speeds of 1,000–1,600 RPM with rated capacities from five to twelve kilograms dominate residential replacement cycles. German and Polish households prioritize cold-wash cycle compatibility as EU Ecodesign energy labeling tightens efficiency benchmarks.
- Dryers:Heat-pump refrigeration circuits with lower-GWP refrigerants are displacing vented units as F-Gas Regulation amendments compress supplier qualification timelines. Southern European markets with higher ambient temperatures face disproportionate performance verification burdens.
- Washer-Dryers:Combined functionality appeals to urban Benelux and Nordic markets where floor space constraints override capacity preferences.
- Compact Units:Outsized margins in heritage buildings with constrained utility access across Paris, Amsterdam, and Vienna rental stock.
Washing machines command the established base. The steepest expansion runs through dryers as heat-pump technology matures.
Technology:
Cost tiering separates premium connected diagnostics from baseline mechanical systems, with mid-range inverter-driven motor controllers capturing commercial laundromat investment in space-constrained urban cores.
- Smart Technology:Vibration sensors with predictive maintenance algorithms reduce service dispatch costs for fleet operators. Connected diagnostics expand fastest as commercial laundry operators in Berlin and Munich consolidate around outcome-guarantee contracts.
- Steam Cleaning:High-temperature sanitization cycles meet hospitality linen-processing standards in Portuguese and Polish hotel renovation pipelines ahead of 2027 efficiency benchmarks.
- Energy Efficient:Cold-wash detergent formulations optimized for sub-30°C operation reduce energy draw and extend drum-bearing life.
- Conventional:Mechanical controls persist in Eastern European rental housing procurement where capital constraints favor standardized, repairable units.
Energy efficient systems anchor current installed base volumes. Smart technology is climbing the fastest as fleet digitization accelerates.
Capacity:
Application context determines sizing: multi-family housing cooperatives in German cities aggregate demand around standardized medium units, while commercial laundromats scale toward extra-large throughput configurations.
- Medium:Five to eight kilogram drums align with replacement cycles in German and French rental housing where appliance refresh programs are expanding. REACH material compliance for control board flame retardants affects reliability expectations at this volume tier.
- Large:Eight to ten kilogram units serve family households in Italian and Polish markets where housing stock renewal intersects with hospitality investment.
- Small:Sub-five kilogram compact drums for single-occupancy urban apartments in Copenhagen and Stockholm.
- Extra Large:Twelve kilogram-plus commercial specifications for institutional facilities and high-throughput laundromats.
Medium capacity holds the dominant position. Large capacity is gaining share fastest as household formation patterns shift toward multi-generational living.
End User:
Customer type stratification shows households driving volume through replacement cycles, while commercial operators concentrate buying power through fleet standardization and vendor consolidation.
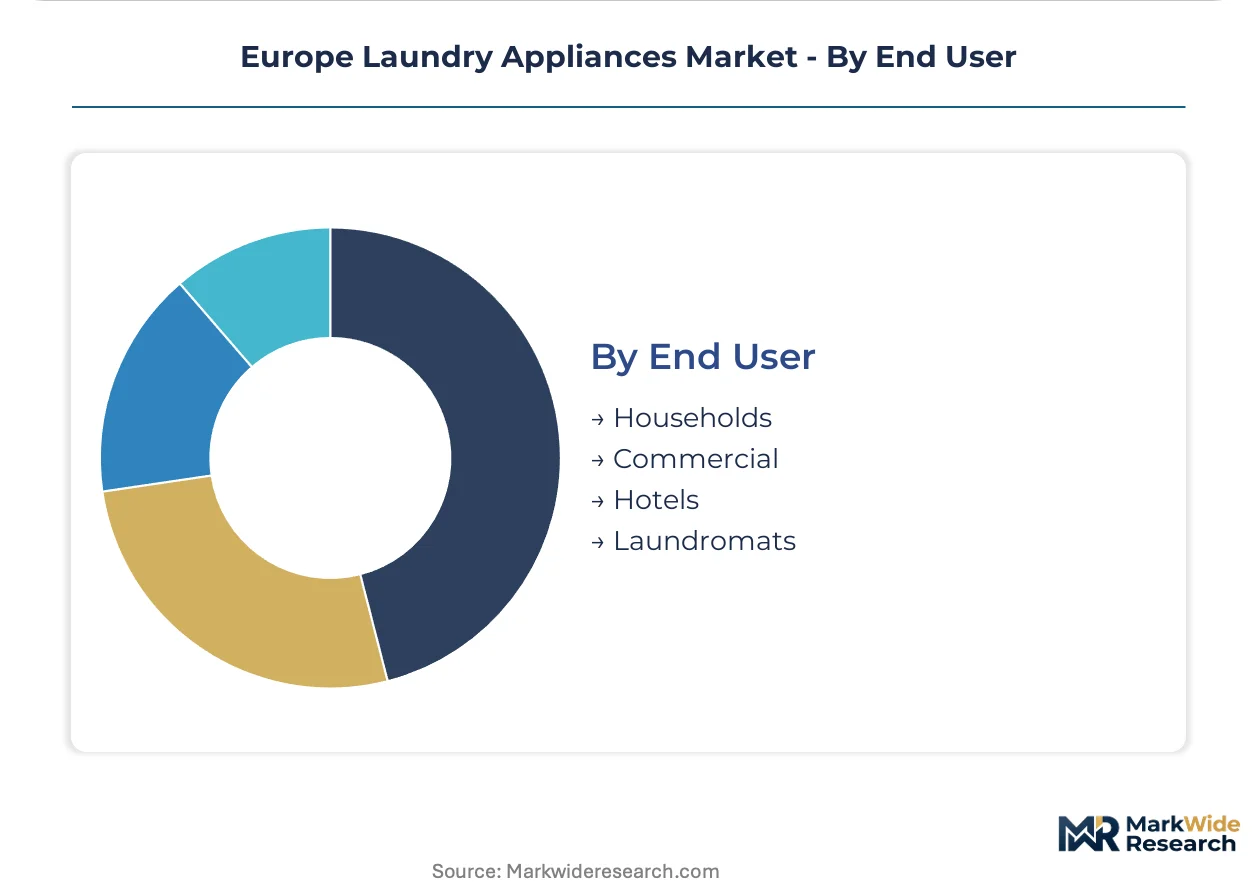
- Households:Residential replacement intervals tighten as cold-wash detergent formulations extend drum-bearing life. German and Austrian consumers attach extended warranties at above-average rates where captive service networks exist.
- Commercial:Fleet operators in Romanian and Bulgarian multi-family housing are consolidating procurement for standardized appliance fleets, creating volume aggregation points for direct-ship manufacturers.
- Hotels:Polish and Portuguese renovation pipelines are replacing legacy linen-processing equipment with energy-certified units.
- Laundromats:Benelux urban core operators adopt inverter-driven motor controllers to reclaim floor space for additional revenue-generating equipment.
Households represent the core revenue base. Commercial end-use is expanding most quickly as subscription-based equipment access displaces outright purchase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Ecodesign for Sustainable Products Regulation anchors demand patterns across the continent, with national implementations creating differentiated compliance timelines and procurement incentives.
Germany
Rental housing cooperatives in Berlin and Munich are consolidating vendor relationships around subscription-based equipment access. The Federal Ministry for Economic Affairs enforces strict repairability mandates under national transposition of EU directives. BSH Hausgeräte GmbH leverages captive service infrastructure across Bavaria and North Rhine-Westphalia to sustain above-average warranty attach rates.
France
Multi-family operators in Paris and Lyon are expanding appliance refresh cycles ahead of 2027 efficiency benchmarks. ANSM and environmental regulators coordinate enforcement of REACH substance restrictions in control board manufacturing. Île-de-France rental stock drives outsized demand for compact units where heritage building constraints limit utility access.
Poland
Hotel renovation pipelines in Warsaw and Kraków are replacing legacy linen-processing equipment with energy-certified units. The national energy regulator aligns building code updates with EU Green Deal efficiency targets. Silesian manufacturing clusters supply export-oriented production serving broader regional distribution networks.
Italy
Family household formation patterns in Lombardy and Emilia-Romagna are shifting toward multi-generational living, expanding large-capacity unit demand. The Ministry of Economic Development administers CE marking compliance for digital product passport traceability requirements. Milan-based hospitality investors intersect with housing stock renewal in driving replacement cycles.
Netherlands
Urban Benelux floor space constraints in Amsterdam and Rotterdam override capacity preferences for compact drum specifications. The Dutch Environment Agency enforces F-Gas Regulation amendments affecting heat-pump dryer refrigerant qualifications. Randstad rental markets concentrate demand for washer-dryer combinations in single-occupancy apartments.
Europe Laundry Appliances Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with mid-range volume players filling procurement channels for standardized fleet specifications. German and Austrian service-network brands defend position through captive technician training pipelines, while Asian-headquartered electronics groups compete on landed cost through direct retail partnerships. Two strategic archetypes dominate: premium durability specialists anchoring commercial-grade positioning, and scale-driven manufacturers optimizing for Eastern European rental housing aggregation points. Competitive moves concentrate on M&A for service infrastructure and geographic expansion through distribution partnerships.
Within the integrated leader tier, BSH Hausgeräte GmbH and Miele & Cie. KG exemplify divergent positioning strategies rooted in German engineering heritage. BSH occupies a position anchored by captive service networks across German-speaking markets, while Miele represents the durability-focused archetype targeting commercial and institutional end-use. Hisense Europe sits within the cost-competitive vector, competing through direct retail partnerships in Eastern European markets where procurement consolidation creates volume aggregation opportunities.
| Leading Market Players |
|---|
| Arçelik A.Ş. |
| Samsung Electronics Co., Ltd. |
| BSH Hausgeräte GmbH |
| Haier Smart Home Co., Ltd. |
| Miele & Cie. KG |
| Electrolux AB |
| LG Electronics Inc. |
| Hisense Europe |
| Whirlpool Corporation |
| Others |
Supply & Pricing Matrix
EU Ecodesign for Sustainable Products Regulation gates both supplier qualification timelines and price differentiation across the Europe laundry appliances market, compressing development cycles for repairable drum assemblies while elevating compliance costs that manufacturers recover through tiered product positioning.
Pricing Analysis
Western European markets command substantial premiums over Eastern European procurement channels due to bundled service infrastructure and extended warranty attach rates. Pricing stratifies across premium, standard, and economy tiers where certification grade and captive technician networks drive differentiation. Cost compression in mid-range units is intensifying because copper-wiring volatility erodes OEM margin buffers. Eastern European rental housing operators exhibit highest price sensitivity, while German multi-family cooperatives prioritize outcome-guarantee contracts over unit economics.
Supply Chain Analysis
Inventory buffers for heat-pump compressor modules have compressed to twelve-week horizons as F-Gas Regulation amendments accelerate refrigerant requalification timelines. Manufacturing concentrates in Germany, Poland, and Turkey where Silesian clusters feed broader regional distribution networks. Motor stator copper, electronic control boards, and sealed drum bearings constitute critical input dependencies. Single-source vulnerability pervades heat-pump refrigeration circuits where a narrow qualified supplier base creates capacity expansion risk. Distribution runs through direct retail partnerships in Eastern Europe and captive service networks in German-speaking markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe laundry appliances market tracks a cyclical recovery pattern as hospitality CAPEX pipelines in Poland and Portugal replenish equipment fleets ahead of regulatory efficiency benchmarks.
For Market Incumbents: Compound service infrastructure advantages by expanding captive technician training pipelines across Austria and Bavaria to offset field-service workforce attrition. Deepen backward integration into inverter-driven motor controller production to defend margin position against Asian cost competitors. Prioritize CE marking compliance investments for digital product passport traceability ahead of competitor qualification windows. For New Entrants and Emerging Players: REACH-compliant component fast-tracks open qualification windows for control board suppliers substituting brominated flame retardants. White-space concentrates in Romanian and Bulgarian multi-family rental procurement where volume aggregation points favor direct-ship manufacturers lacking legacy service networks. Penetrate through standardized fleet specifications bundled with predictive maintenance algorithms rather than competing on landed cost alone. For Investors and Strategic Acquirers: Pending F-Gas Regulation amendments reshape the acquisition landscape by elevating heat-pump engineering capabilities above commodity manufacturing scale. Long-term viability over a multi-year horizon favors targets with verified lower-GWP refrigerant compressor maps and accelerated performance verification protocols. Monitor technician certification pipeline throughput as an inflection indicator for incumbent service-network defensibility.| Strategic Initiative | Industry Significance |
|---|---|
| Service Network Expansion | BSH Hausgeräte GmbH leverages captive infrastructure across Germany to sustain above-average warranty attach rates. |
| Heat-Pump Technology Licensing | Lower-GWP refrigerant validation compresses supplier qualification timelines for Southern European ambient temperature performance. |
| Digital Product Passport Integration | Component serialization creates first-mover advantage for blockchain verification services under EU Green Deal traceability mandates. |
| Eastern European Distribution Partnership | Direct retail partnerships in Romania and Bulgaria aggregate procurement volumes for standardized appliance fleets. |
| Predictive Maintenance Platform Development | Vibration sensor integration reduces service dispatch costs for commercial laundry fleet operators in Berlin and Munich. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and hospitality procurement databases. Appliance manufacturer product managers, rental housing procurement directors, and commercial laundry fleet operators provided operational perspective on replacement cycle dynamics. Secondary validation drew from ECHA substance restriction updates, EU Ecodesign implementing measures, and national energy regulator efficiency benchmark announcements. Bottom-up unit shipment analysis triangulates against top-down market value reconstruction across the projection horizon.
Segmentation dimensions modeled include product type, technology tier, capacity specification, and end-use application across the analysis window. CAGRs derive from regression analysis of historical replacement intervals correlated with housing stock renewal rates and hospitality investment cycles. Cold-wash detergent formulation adoption curves and F-Gas Regulation amendment implementation timelines constitute industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained hospitality CAPEX recovery or accelerated Ecodesign enforcement would require recalibration. Forecasts reflect documented assumptions regarding technician workforce replenishment and refrigerant supplier qualification throughput. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
Bahrain Major Home Appliances Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
China Laundry Appliances Market
Home Appliances
Latin America Home Appliances Market
Home Appliances
Oman Small Home Appliances Market
Home Appliances
Germany Washing Machine Market
Home Appliances
Residential Cooker Hoods Market
Home Appliances
Household Fridge Market
Home Appliances
North America Luxury Appliance Market
Home Appliances
Global Electric Motors Household Appliances Market
Home Appliances
Middle East and Africa Laundry Appliances Market
Home Appliances
Smart Small Home Appliances Market
Home Appliances
Europe Small Home Appliances Market
Home Appliances
UAE Small Home Appliances Market